
 Europe Point of Care Diagnostics Market | 2026-2036
Europe Point of Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Point of Care Diagnostics Market Analytics
Hospital procurement consolidation across Western Europe is repositioning vendor relationships toward integrated platform suppliers. Abbott Laboratories leverages its broad assay menu to anchor multi-year hospital contracts across France and Italy. Siemens Healthineers competes through its installed base of connected instruments that sustain recurring consumable revenue. bioMérieux specializes in syndromic infectious disease panels that differentiate its portfolio in emergency department workflows.
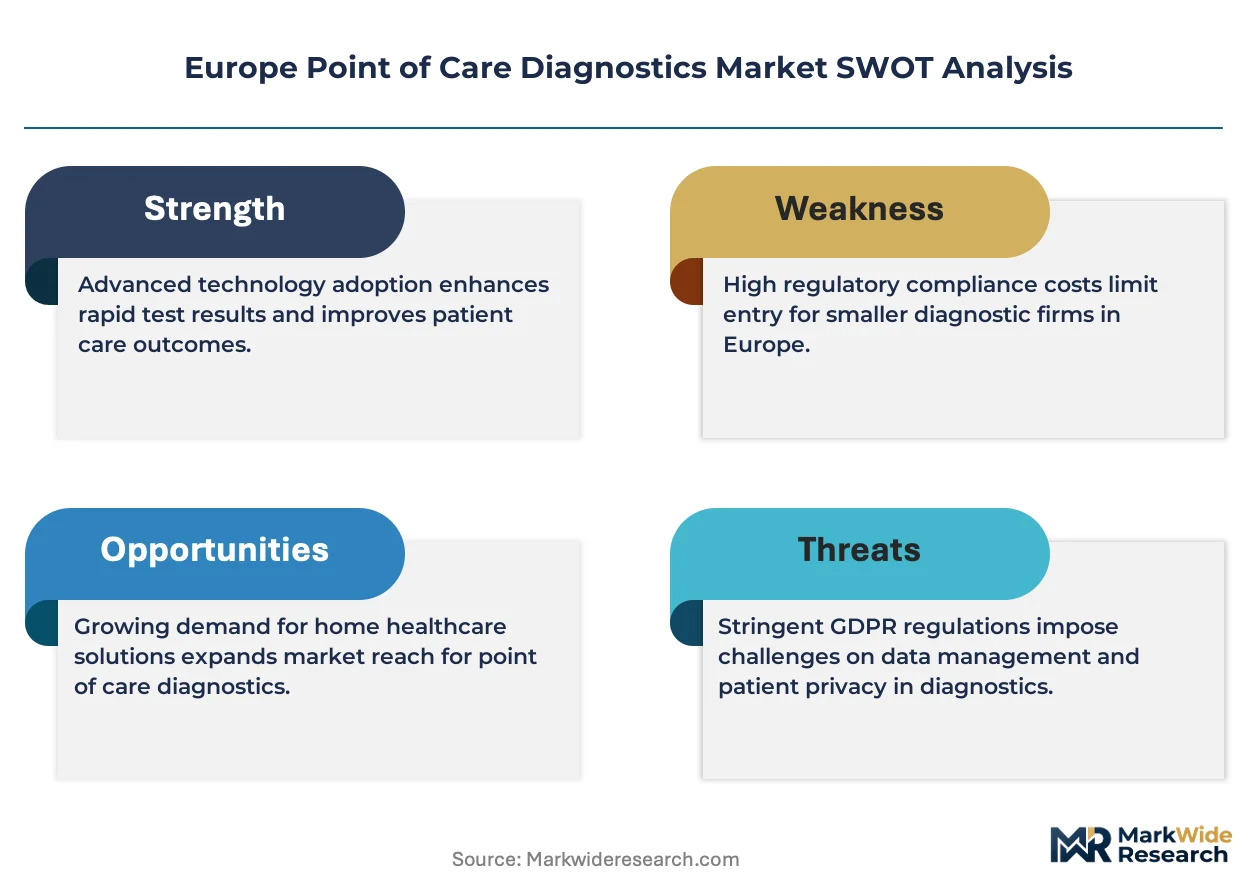
Point of care diagnostics encompass portable analytical devices and consumables designed to deliver clinical results at or near the patient site, typically requiring sample volumes below 500 microliters and turnaround times under 30 minutes. These systems serve the primary purpose of accelerating clinical decision-making while reducing laboratory infrastructure dependency. Glucose meters occupy a mature, high-volume position with compressed margins, whereas microfluidics-enabled platforms represent the fastest-expanding technology segment due to multiplexing capabilities. Lateral flow assays retain dominant share in infectious disease testing, particularly in clinics and homecare settings where simplicity governs purchasing criteria.
The European Medicines Agency coordinates scientific advice for novel diagnostic biomarkers, while the IVDR framework mandates notified body oversight for the majority of point of care devices entering the European market. REACH compliance additionally constrains material selection for disposable test cartridges, particularly affecting manufacturers sourcing complex polymer formulations. Stakeholders must monitor the evolving relationship between IVDR implementation pace and national reimbursement decisions for decentralized testing modalities.
Market Dynamics
Procurement consolidation across Western European hospital networks is compressing vendor margins while elevating platform-scale suppliers who can anchor multi-year integrated contracts. This concentration dynamic favors manufacturers with broad assay menus and connected instrument ecosystems over point-product specialists.
Growth Catalysts
- IVDR compliance timelines:Extended transition periods under the EU In Vitro Diagnostic Regulation are allowing manufacturers to maintain market presence while completing notified body certifications.
- Germany's ambulatory infrastructure:Decentralized healthcare delivery models in German primary care networks are accelerating deployment of rapid diagnostic platforms outside hospital settings.
- Microfluidics multiplexing:Lab-on-a-chip architectures enabling simultaneous biomarker detection are reducing per-test costs and expanding test menus at the point of care.
Market Restraints
- REACH polymer constraints:Complex disposable cartridge formulations face material substitution costs and supply qualification delays under EU chemical safety mandates.
- Notified body capacity:Limited EU-authorized certification bodies are creating bottlenecks for IVDR technical documentation review and quality management audits.
- Glucose meter commoditization:Mature blood glucose monitoring segments face margin compression from low-cost Asian manufacturers and reimbursement rate pressures.
Strategic Opportunities
- Eastern European expansion:Underpenetrated outpatient clinic networks in Poland and Romania present first-mover advantages for syndromic infectious disease panel suppliers.
- Homecare channel development:Direct-to-patient distribution models for chronic disease monitoring are bypassing traditional hospital procurement gatekeepers.
- EU Green Deal alignment:Sustainable manufacturing certifications and recyclable cartridge designs are becoming differentiated selection criteria in public tender evaluations.
Industry Challenges
- IVDR technical documentation:Expanded clinical evidence requirements and post-market surveillance obligations are extending product registration timelines and consuming regulatory affairs capacity.
- Legacy LIS integration:Hospital information system interoperability with new point of care devices requires customized middleware development and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Point of Care Diagnostics Market |
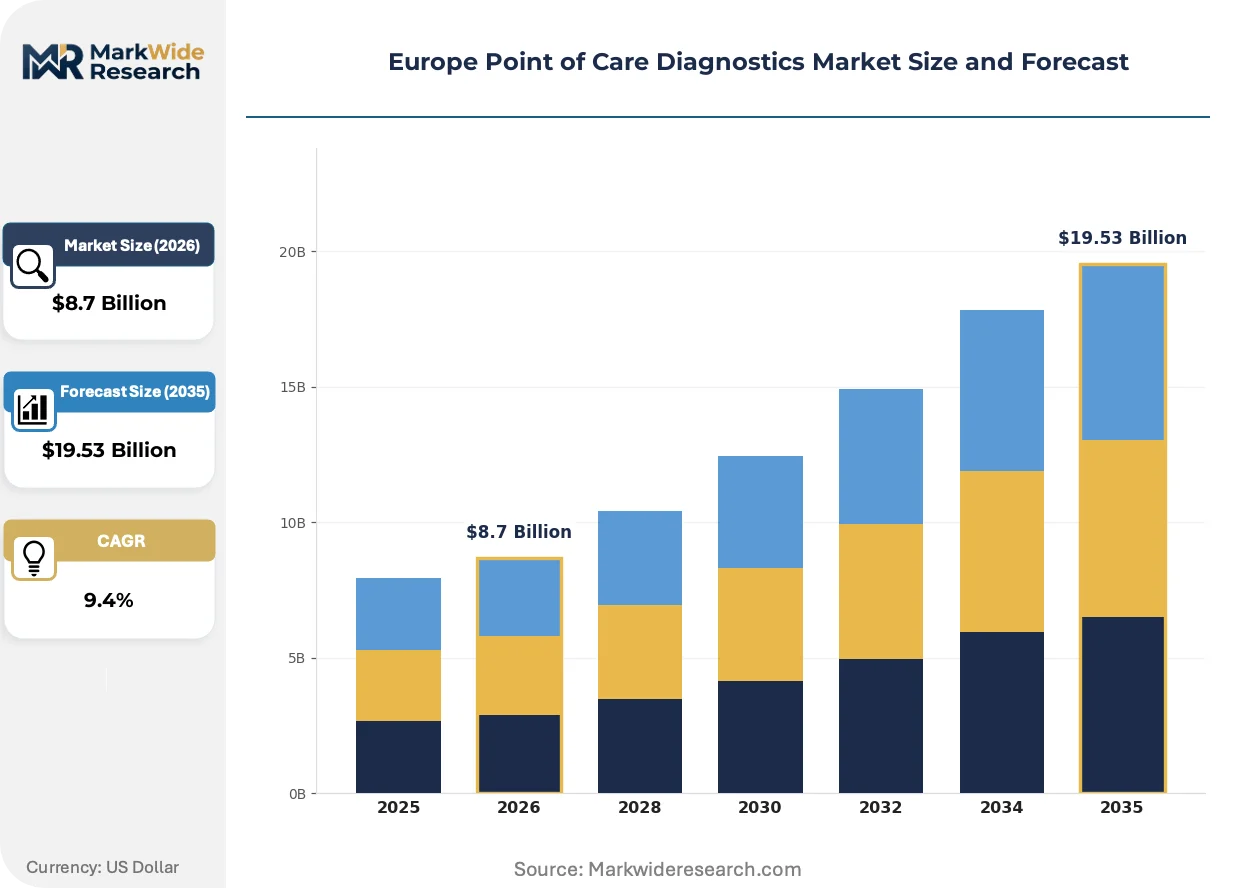
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Infectious Disease Tests, Cardiac Markers, Coagulation Testing Delivery Mode: Self-Test, Laboratory Testing, Remote Monitoring, Point of Care Testing End User: Hospitals, Clinics, Homecare, Emergency Services Technology: Microfluidics, Lateral Flow Assays, Automation, Nucleic Acid Amplification |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Danaher Corporation, bioMérieux, QIAGEN, Bayer AG, Bio-Rad Laboratories, Agilent Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Point of Care Diagnostics Market Evolving Landscape
Connected diagnostics and algorithm-enabled interpretation are transforming point of care workflows from isolated testing events into integrated clinical decision nodes. Three developments are actively reshaping competitive positioning and R&D priorities across European markets.
Microfluidics-enabled multiplex platforms are expanding into emergency department and primary care settings where rapid differential diagnosis of respiratory and bloodstream infections drives purchasing decisions. French and Italian hospital groups are prioritizing these systems for antibiotic stewardship programs. The technology is expanding into applications previously requiring centralized laboratory infrastructure, compressing the addressable market for conventional benchtop analyzers.
EMA scientific advice pathways for novel biomarkers are creating structured entry routes for companion diagnostic developers seeking parallel drug-device approvals. This coordination mechanism reduces regulatory uncertainty for oncology and infectious disease test developers. Syndromic panel manufacturers targeting sepsis and antimicrobial resistance markers are most affected, with several firms restructuring clinical trial designs to align with EMA feedback timelines.
Hospital procurement committees are consolidating supplier relationships around integrated platform vendors who bundle instruments, consumables, and service contracts into multi-year agreements. Independent distributors and regional equipment specialists are losing access to major account decision-making in France and Germany. This concentration is most visible in university hospital networks where standardization across campus sites overrides local department preferences.
Europe Point of Care Diagnostics Market Segmentation
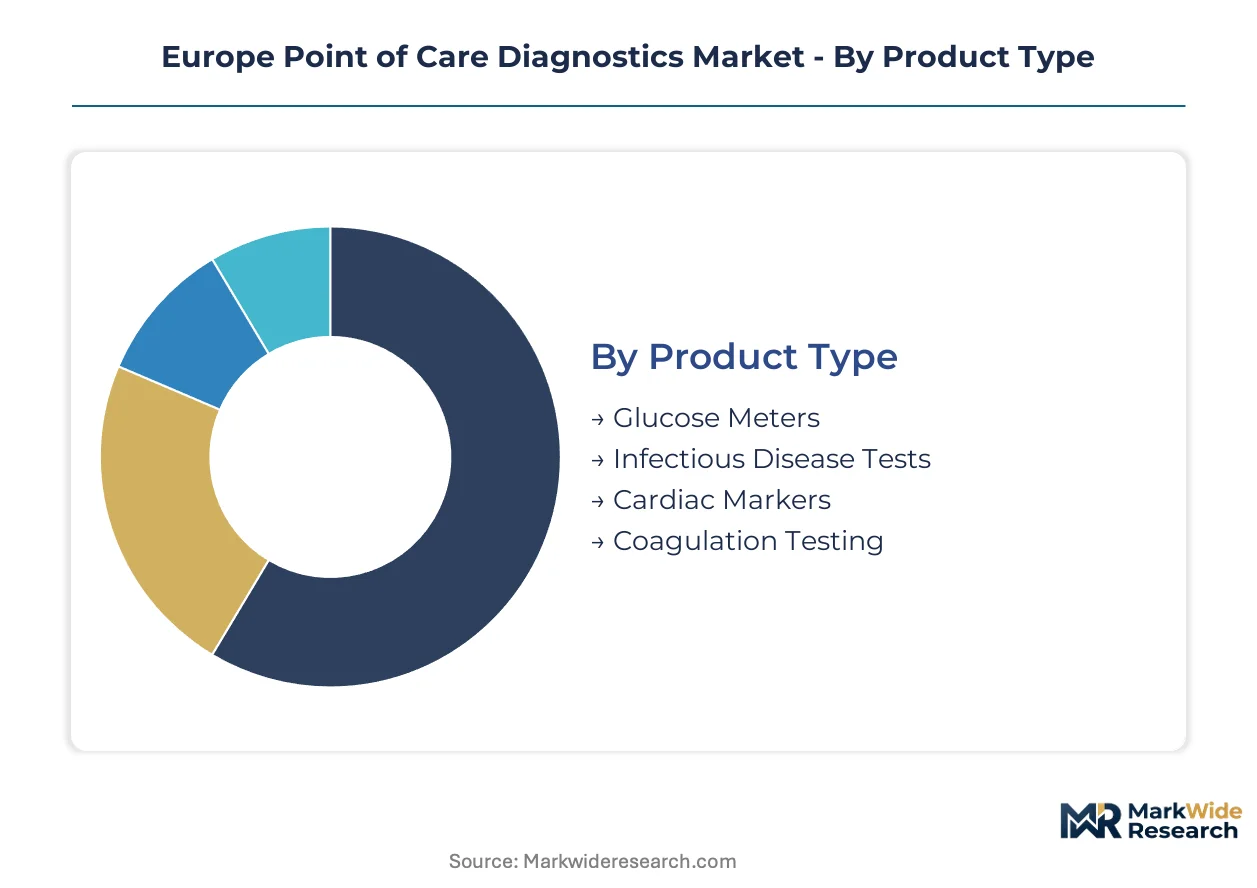
Segmentation in Europe's point of care diagnostics market reveals divergent margin profiles and regulatory pathways. Product type and technology choices determine IVDR certification complexity, while end-user concentration shapes procurement access and pricing power.
Product Type:
Volume leaders dominate procurement tenders, while premium segments command superior margins through clinical differentiation.
- Glucose Meters:Capillary blood sampling devices with sub-5-second readout capabilities. German homecare networks and Dutch pharmacy chains drive replenishment demand amid reimbursement compression and Asian manufacturer price pressure.
- Infectious Disease Tests:Syndromic panels detecting respiratory, gastrointestinal, and sexually transmitted pathogens through multiplexed antigen or nucleic acid detection. French emergency departments and Italian hospital networks prioritize these for antibiotic stewardship compliance.
- Cardiac Markers:Troponin and BNP quantification systems for acute coronary syndrome triage. Spanish and Portuguese cardiology wards deploy these to reduce central lab turnaround.
- Coagulation Testing:INR and aPTT monitoring for anticoagulant therapy management. Belgian and Austrian anticoagulation clinics sustain demand through warfarin patient monitoring protocols.
Today's leader: Glucose Meters. Tomorrow's challenger: Infectious Disease Tests.
Delivery Mode:
Channel selection determines regulatory burden, with professional-use pathways demanding stricter IVDR clinical evidence than self-test frameworks.
- Self-Test:Over-the-counter devices for glucose, pregnancy, and infectious disease screening. UK pharmacy retail and German drugstore chains represent primary distribution, with CE-IVD self-test classification streamlining market entry.
- Laboratory Testing:Near-patient analyzers operated by trained personnel within hospital satellite labs. Scandinavian hospital networks favor these for hub-and-spoke laboratory consolidation.
- Remote Monitoring:Cloud-connected devices transmitting results to centralized care teams. Dutch and Danish telehealth programs deploy these for chronic disease management outside traditional facilities.
- Point of Care Testing:Bedside and ambulatory instruments integrated into clinical workflows. German primary care networks and French hospital emergency departments anchor procurement volume.
Professional channels capture current volume. Remote Monitoring shows steepest expansion trajectory through telehealth reimbursement expansion.
End User:
Procurement authority concentrates in consolidated hospital networks, while homecare channels offer margin protection through direct-to-patient models.
- Hospitals:Integrated delivery networks in France, Germany, and Italy negotiating multi-year platform contracts. Emergency departments and intensive care units drive syndromic panel adoption.
- Clinics:Primary care and specialty outpatient facilities in decentralized German and Spanish healthcare systems. These sites favor portable instruments with minimal maintenance requirements.
- Homecare:Direct-to-patient distribution for chronic disease monitoring. UK and Nordic reimbursement frameworks increasingly cover glucose and coagulation self-testing.
- Emergency Services:Pre-hospital deployment by paramedic and ambulance services. French SAMU and German EMS networks evaluate cardiac marker and infectious disease platforms for field triage.
Hospitals dominate contract value. Homecare offers fastest margin expansion through bypassing procurement gatekeepers.
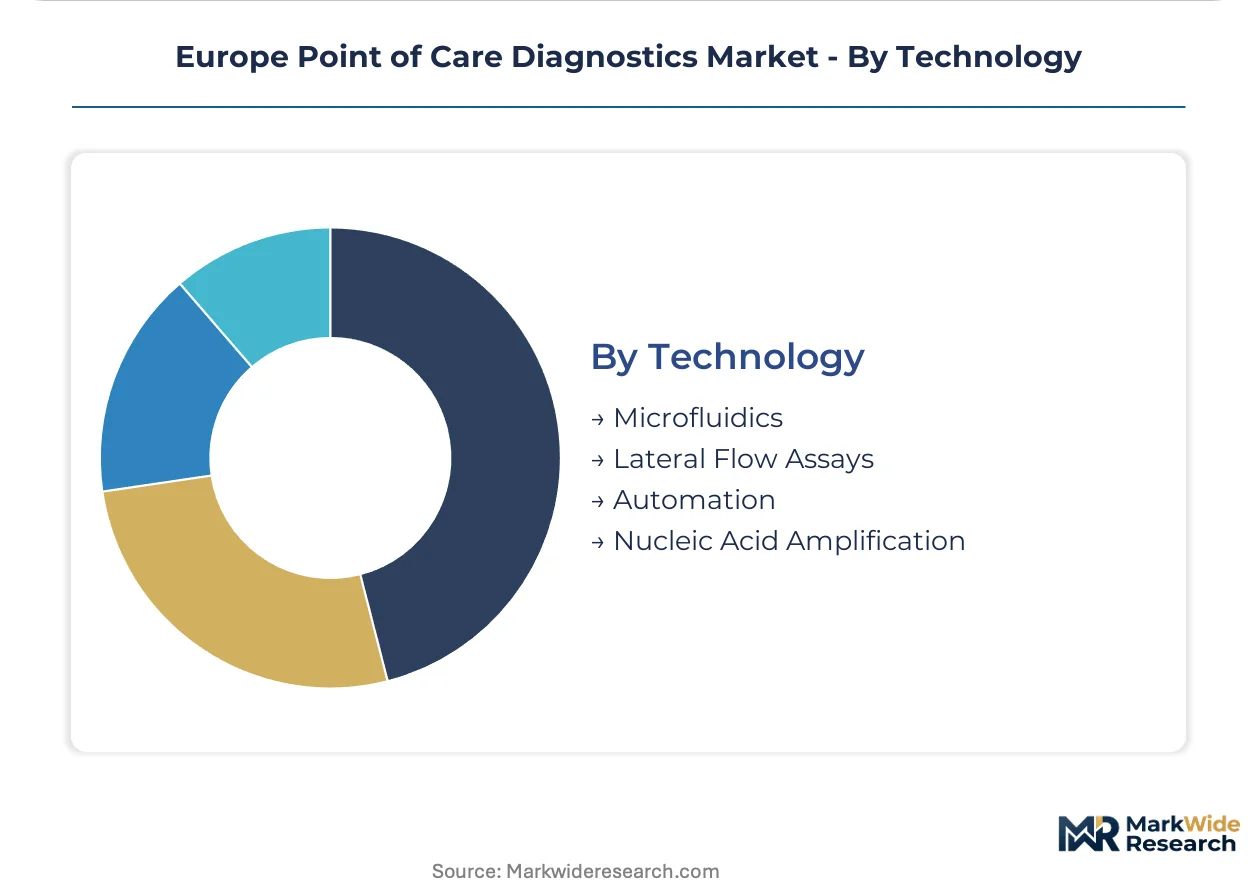
Technology:
Platform architecture determines multiplexing capability, manufacturing complexity, and REACH compliance exposure for disposable components.
- Microfluidics:Lab-on-a-chip architectures enabling simultaneous multi-analyte detection from sub-100-microliter samples. French and Italian hospital groups prioritize these for respiratory and bloodstream infection differential diagnosis.
- Lateral Flow Assays:Immunochromatographic strips for single or limited multiplex detection. These dominate infectious disease screening in clinics and homecare settings where simplicity and cost govern selection.
- Automation:Sample-to-answer systems minimizing operator intervention. German and Swiss hospital laboratories deploy these to reduce training burden and result variability.
- Nucleic Acid Amplification:Isothermal and PCR-based platforms for pathogen detection at point of care. EMA-coordinated scientific advice pathways support oncology and infectious disease developers seeking companion diagnostic alignment.
Lateral Flow Assays retain installed base dominance. Microfluidics platforms gain share fastest through antibiotic stewardship program alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's decentralized ambulatory infrastructure contrasts sharply with France's consolidated hospital procurement networks, creating divergent deployment patterns for point of care platforms across Western Europe.
Germany
Primary care networks and anticoagulation clinics drive demand for portable coagulation and glucose monitoring systems. The BfArM oversees IVDR implementation timelines, extending transition periods for legacy device registrations. Bavaria's medical technology corridor around Munich anchors manufacturing clusters for microfluidics-enabled diagnostic cartridges.
France
Emergency departments and university hospital networks prioritize syndromic infectious disease panels for antibiotic stewardship compliance. ANSM coordinates with EMA on novel biomarker scientific advice pathways for companion diagnostics. The Paris-Saclay cluster concentrates R&D activity for nucleic acid amplification platforms targeting sepsis markers.
United Kingdom
Pharmacy retail chains and NHS primary care networks sustain demand for self-test glucose and infectious disease screening devices. The MHRA operates parallel recognition routes for CE-IVD and UKCA-marked devices post-Brexit. The Cambridge-Oxford-London golden triangle hosts development activity for algorithm-enabled diagnostic interpretation software.
Italy
Hospital emergency departments and regional health authorities drive procurement of cardiac marker and respiratory pathogen detection systems. The Ministry of Health administers regional tender processes that favor multi-year platform contracts with integrated service provisions. Lombardy's medical device manufacturing base around Milan supplies automation components for sample-to-answer systems.
Netherlands
Telehealth programs and decentralized chronic disease management initiatives accelerate deployment of remote monitoring devices transmitting results to centralized care teams. The Dutch Healthcare Authority structures reimbursement frameworks for home-based diagnostic testing outside traditional facilities. The Eindhoven Brainport region concentrates microfluidics engineering expertise for lab-on-a-chip architectures.
Europe Point of Care Diagnostics Market Competitive Landscape
Swiss and German producers anchor the premium instrumentation tier; American specialists hold strong positions in consumables and assay development. Market structure concentrates around integrated platform vendors capable of bundling instruments, reagents, and multi-year service contracts. Three archetypes dominate: diversified conglomerates with broad assay menus, mid-cap specialists in syndromic infectious disease panels, and emerging microfluidics technology developers. Competitive dynamics center on M&A activity targeting complementary assay portfolios and strategic partnerships securing distribution access through consolidated procurement channels.
Among diversified conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers occupy positions exemplifying the integrated platform archetype, anchoring multi-year hospital contracts through connected instrument ecosystems. Abbott Laboratories represents the consumables-heavy model, leveraging broad assay menus to sustain recurring revenue streams. These three entities illustrate how geographic origin and corporate structure shape competitive positioning within procurement consolidation environments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher Corporation |
| bioMérieux |
| QIAGEN |
| Bayer AG |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Others |
Value Network & Pricing Analysis
Microfluidics engineering talent concentrated in the Eindhoven Brainport region and Bavaria's Munich corridor feeds labor-cost differentials that widen pricing-tier spreads between premium multiplex platforms and commodified glucose meters. REACH compliance burdens for complex polymer formulations further stratify cost structures across European manufacturing zones.
Pricing Analysis
Capacity additions in German and Swiss automation hubs are reshaping price floors for sample-to-answer systems while Asian contract manufacturers compress glucose meter economics. Three-tier pricing structure across premium, standard, and economy levels separates IVDR-certified multiplex platforms from CE-IVD self-tests and unconnected legacy devices. Cost compression in the glucose segment is intensifying because of low-cost Asian entrants and pharmacy chain tender aggregation. Hospital procurement committees show lowest price sensitivity for integrated platform contracts bundling instruments and multi-year consumable commitments.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale procurement demand from consolidated French and German network buyers, while specialty distributors serve fragmented clinic segments. Manufacturing concentration centers on Germany, Switzerland, and the Netherlands for precision instrumentation, with disposable cartridge production drawing from polymer formulation expertise in Belgium and Austria. Supply chains hinge on fluoropolymer and cyclic olefin copolymer inputs for microfluidic layer fabrication. Single-source vulnerability in notified body certification capacity creates qualification bottlenecks for new product introductions. Distribution runs through GPO-negotiated framework agreements in university hospital networks and direct manufacturer relationships in ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European point of care diagnostics rests on microfluidics-enabled test menu expansion commanding premium pricing and REACH-compliant material substitution reducing long-term compliance costs.
For Market Incumbents: Lock in multi-year platform contracts with German hospital networks before IVDR transition deadlines consolidate supplier relationships further. Deepen backward integration into microfluidic cartridge manufacturing to offset REACH polymer cost volatility and defend consumable margins against Asian contract manufacturers. Prioritize EMA scientific advice pathways for companion diagnostic alignment to sustain oncology panel pricing power. For New Entrants and Emerging Players: Polish and Romanian outpatient clinic networks represent the most penetrable buyer archetype for syndromic infectious disease panels, with procurement decentralization bypassing incumbent-locked Western European hospital systems. Homecare channels for chronic disease monitoring offer direct-to-patient margin protection outside GPO gatekeeper control. Lead with telehealth-integrated remote monitoring platforms to capture Dutch and Danish reimbursement expansion. For Investors and Strategic Acquirers: Diversified diagnostic conglomerates seeking assay portfolio breadth are the most active acquirer in this space, targeting mid-cap specialists with IVDR-ready infectious disease panels. Long-term viability favors platforms with installed instrument bases generating recurring consumable revenue over point-product developers facing procurement exclusion. Watch IVDR notified body capacity expansion as the signal indicating whether registration timelines compress or extend competitive windows for emerging players.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Notified body pre-submission meetings with BfArM and ANSM reduce registration timeline uncertainty for multiplex platforms. |
| Microfluidics Cartridge Manufacturing Scale-Up | In-house polymer formulation capabilities in Bavaria insulate against REACH supply disruption and qualify for EU Green Deal tenders. |
| Hospital System Partnership Agreements | Multi-year integrated contracts with French university hospital networks lock out competing platform vendors through standardization mandates. |
| EMA Scientific Advice Coordination | Parallel drug-device development pathways for sepsis biomarkers reduce regulatory risk and accelerate companion diagnostic commercialization. |
| Telehealth Platform Integration | Cloud-connected result transmission aligns with Dutch Healthcare Authority reimbursement frameworks for home-based chronic monitoring. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at notified bodies grounded qualitative findings, cross-validated against EMA scientific advice records, IVDR technical documentation filings, hospital tender databases, and REACH compliance disclosures. Bottom-up instrument shipment and consumable revenue estimates triangulated with top-down healthcare expenditure allocation models across the analysis window.
Bottom-up modeling segmented the market by product type, technology platform, delivery mode, and end-user concentration, with value outputs derived from pricing intelligence across German, French, and UK procurement channels. CAGRs were computed from annual growth rate progression across the projection horizon, incorporating IVDR implementation pace assumptions and telehealth reimbursement expansion trajectories as key forecast inputs.
Inputs from hospital procurement databases and GPO contract registries were available through the study window; gaps in real-time IVDR certification queue data introduce uncertainty bands around product launch timing assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Europe Breath Analyzer Market