
 Recombinant Factor C Assay Market | 2026-2036
Recombinant Factor C Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Factor C Assay Market Analysis
Endotoxin detection service revenue is reshaping margin distribution across the recombinant Factor C assay value chain. Lonza Group AG leverages its bioscience manufacturing footprint to sustain captive demand for in-house assay kits. Thermo Fisher Scientific Inc. anchors the chromogenic and fluorometric reagent segments through extensive distribution networks in North America and Europe. Charles River Laboratories International, Inc. competes by integrating endotoxin testing within its broader pharmaceutical services portfolio.
The recombinant Factor C assay is a synthetic, recombinant protein-based endotoxin detection system derived from the horseshoe crab coagulation cascade, utilizing a genetically engineered Factor C enzyme that initiates a measurable enzymatic reaction in the presence of lipopolysaccharide with sensitivity thresholds reaching 0.001 EU/mL. Its primary commercial purpose is to replace animal-derived Limulus Amebocyte Lysate methods for bacterial endotoxin testing in sterile pharmaceutical manufacturing, water quality monitoring, and medical device validation. Chromogenic assays dominate current procurement volumes due to established laboratory familiarity and straightforward photometric readout protocols, while automated assays represent the fastest-expanding segment as contract manufacturing organizations seek throughput gains for high-volume parenteral batch release. Fluorometric assays occupy a specialized niche where enhanced sensitivity is required for complex biologics matrices, though manual assays retain persistent demand in academic and small-scale research settings.
The European Medicines Agency and the United States Food and Drug Administration both recognize recombinant Factor C under pharmacopeial standards, with EMA guidance explicitly endorsing the method for pharmaceutical quality control and FDA's Center for Drug Evaluation and Research accepting validated rFC data in New Drug Applications. REACH compliance requirements and the European Pharmacopoeia's Chapter 2.6.32 are reshaping supplier qualification criteria, effectively filtering market access toward manufacturers with documented sustainable production practices. Stakeholders must monitor evolving compendial harmonization between USP, EP, and JP standards to anticipate which assay formats will achieve broad regulatory equivalence.
Market Dynamics
The recombinant Factor C assay market is restructuring around regulatory substitution mandates that deauthorize horseshoe crab blood harvesting for endotoxin testing, forcing pharmaceutical manufacturers to validate synthetic alternatives ahead of compendial deadlines.
Growth Catalysts
- EMA Chapter 2.6.32:The European Pharmacopoeia's formal recognition of recombinant Factor C as a reference method creates immediate procurement pull across German and Swiss sterile manufacturing facilities.
- Biologics manufacturing expansion:Cell and gene therapy production lines in Massachusetts and North Carolina require endotoxin detection formats compatible with complex protein matrices.
- Horseshoe crab conservation statutes:Delaware Bay harvesting restrictions and Atlantic coast state-level protections are constraining Limulus Amebocyte Lysate supply availability.
Market Restraints
- Validation cost burden:Full method transfer studies for recombinant Factor C qualification require 18-24 month timelines and substantial analytical development expenditure.
- Japanese Pharmacopoeia lag:Japan's continued preference for Limulus-based methods creates regulatory fragmentation for multinational batch release protocols.
- Enzyme stability limitations:Recombinant Factor C reagents exhibit narrower temperature tolerance ranges than traditional lysate preparations, complicating cold chain logistics.
Strategic Opportunities
- Water quality monitoring:Municipal utilities and dialysis centers present underpenetrated demand for rapid endotoxin detection in ultrapure water systems.
- Automated platform integration:Robotics-compatible assay formats enable high-throughput screening for contract manufacturing organizations running continuous bioprocessing lines.
- REACH sustainable chemistry incentives:European manufacturers sourcing animal-free testing methods qualify for streamlined substance registration pathways and ESG scoring advantages.
Industry Challenges
- Compendial harmonization delays:Misalignment between USP, EP, and JP acceptance criteria forces duplicate validation studies for global product registrations.
- Analyst retraining requirements:Laboratory technicians familiar with gel-clot and turbidimetric Limulus methods require structured competency programs for fluorometric and chromogenic recombinant protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Factor C Assay Market |
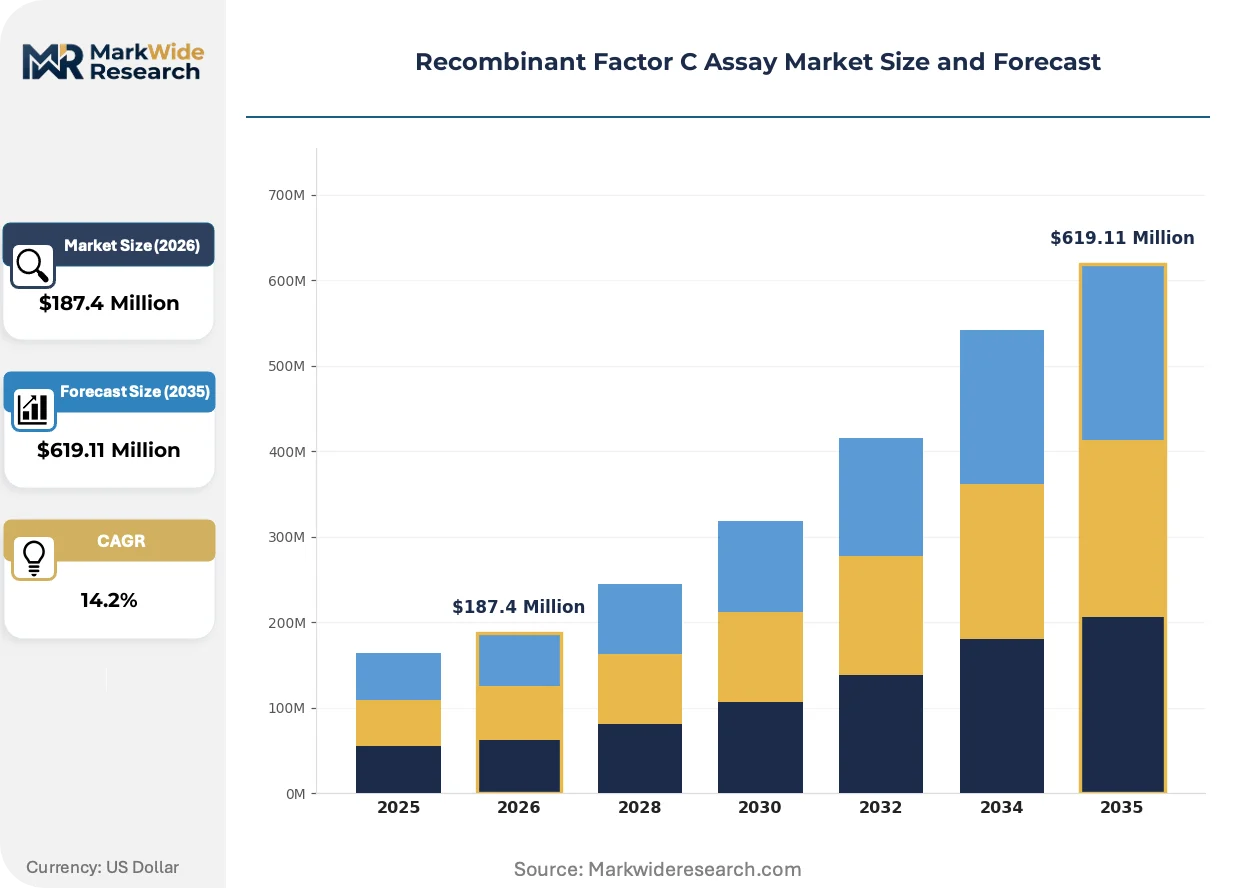
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromogenic Assays, Fluorometric Assays, Automated Assays, Manual Assays Application: Quality Control, Research Laboratory, Clinical Diagnostics, Blood Banking End User: Hospitals, Contract Research Organizations, Academic Institutes, Diagnostic Laboratories Technology: Microplate Readers, PCR Systems, Flow Cytometry, Enzymatic Detection |
| Companies Covered | Thermo Fisher Scientific Inc., Hyglos GmbH, Lonza Group AG, Xiamen Bioendo Technology Co., Ltd., GenScript Biotech Corporation, Charles River Laboratories International, Inc., Associates of Cape Cod, Inc., bioMérieux SA, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Factor C Assay Market Emerging Trajectories
Endotoxin detection architecture is pivoting from animal-derived reagents toward engineered biochemistry, with automation and regulatory alignment determining which assay formats achieve dominant design status.
Fluorometric detection chemistry is migrating from niche high-sensitivity applications toward standard biologics release testing. Contract manufacturing organizations in Germany and Switzerland are validating these formats for monoclonal antibody batches where matrix interference complicates chromogenic readouts. The shift is compressing demand for manual photometric systems while expanding the addressable market for plate-reader integrated platforms.
REACH compliance deadlines are reshaping supplier qualification protocols across European pharmaceutical manufacturing. ECHA documentation requirements for sustainable production practices now filter procurement decisions toward recombinant Factor C producers with certified animal-free supply chains. German and French sterile injectable facilities are prioritizing these suppliers in tender evaluations.
Consolidated purchasing agreements are displacing spot procurement for endotoxin testing consumables. Large biopharmaceutical manufacturers in Massachusetts and California are negotiating multi-year supply contracts that bundle assay kits, validation support, and regulatory filing assistance. This concentration is squeezing independent distributors while favoring integrated life science suppliers with in-house regulatory affairs capabilities.
Recombinant Factor C Assay Market Segmentation
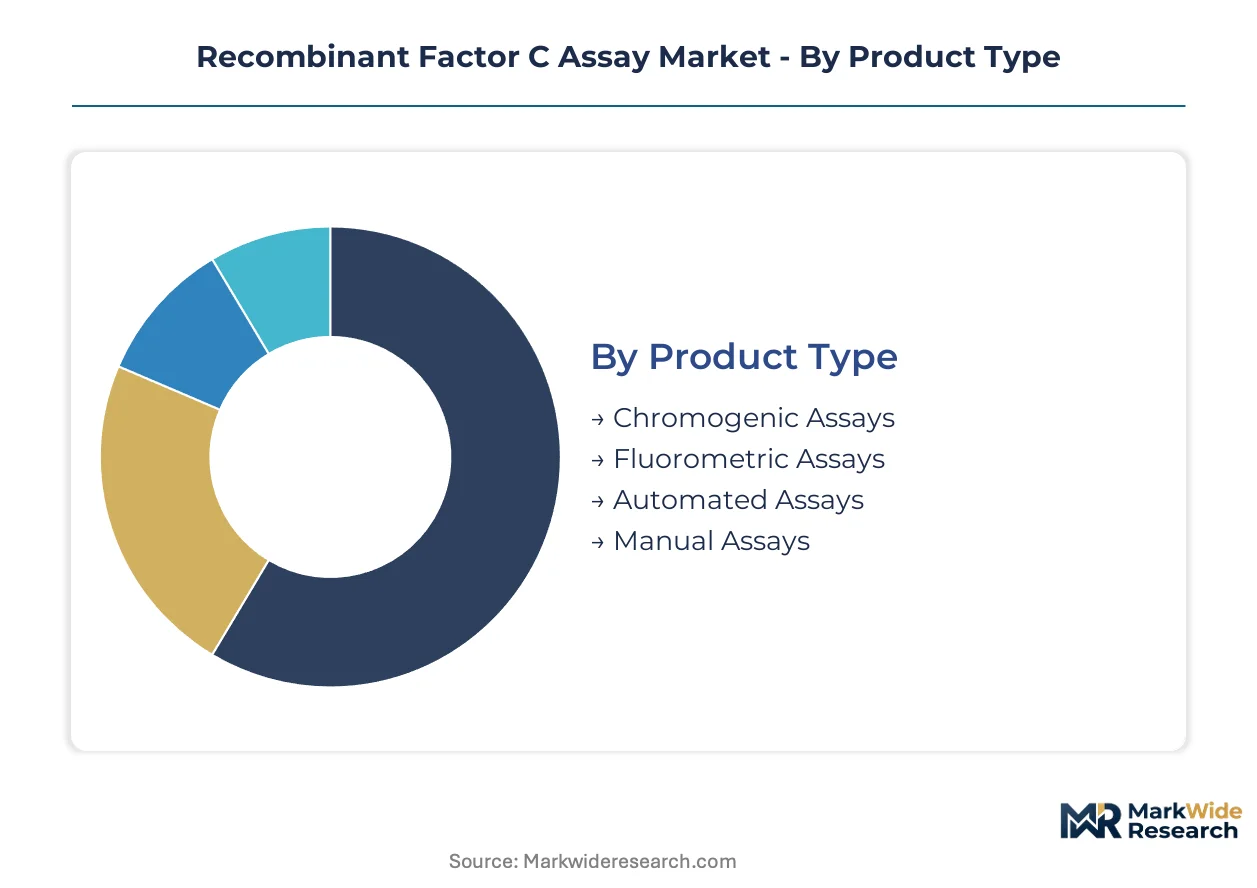
Segmentation in recombinant Factor C assays reveals how detection chemistry, automation level, and end-user workflow requirements create distinct procurement clusters. Pharmaceutical manufacturers prioritize validated formats compatible with regulatory filing pathways, while research settings tolerate manual protocols that sacrifice throughput for capital efficiency.
Product Type:
Detection chemistry and automation level together determine assay economics, with photometric readout familiarity driving near-term procurement while robotic integration shapes long-term contracts.
- Chromogenic Assays:These assays employ synthetic peptide substrates that release para-nitroaniline upon Factor C enzymatic cleavage, enabling straightforward absorbance measurement at 405-660 nm. German sterile injectable facilities in Baden-Württemberg and Bavaria standardize procurement on these formats due to established pharmacopeial validation packages and technician familiarity with photometric instrumentation. The format dominates current batch release volumes for monoclonal antibody and vaccine production.
- Automated Assays:Robotics-compatible microplate formats integrate with liquid handling workstations for continuous bioprocessing lines, eliminating manual pipetting variability. Massachusetts contract manufacturing organizations running high-volume parenteral production are validating these systems to meet throughput demands for cell therapy batch release. The segment gains procurement priority where labor costs and reproducibility requirements intersect.
- Fluorometric Assays:These systems utilize methylumbelliferyl-linked substrates requiring specialized plate readers with excitation/emission filtering, occupying high-sensitivity niches for complex biologics matrices.
- Manual Assays:Benchtop formats requiring technician-operated pipetting and timing protocols persist in academic and small-scale research settings where capital constraints outweigh throughput needs.
Chromogenic formats command the established base. The steepest expansion runs through automated assays.
Application:
Regulatory context and sample throughput requirements segment demand across pharmaceutical manufacturing, clinical testing, and research functions.
- Quality Control:GMP-compliant endotoxin testing for sterile drug batch release represents the revenue concentration point, with Swiss and German facilities driving procurement of validated assay kits under EMA Chapter 2.6.32. The application demands documented traceability, controlled reagent lots, and regulatory filing support from suppliers.
- Research Laboratory:Exploratory endotoxin detection in protein purification and cell culture media development operates outside formal batch release protocols, tolerating broader method variability in exchange for cost efficiency.
- Clinical Diagnostics:Patient sample testing for sepsis markers and dialysis fluid monitoring requires clinical-grade assay certifications distinct from pharmaceutical QC formats.
- Blood Banking:Plasma and platelet unit screening for bacterial contamination employs rapid endotoxin detection as an adjunct to culture-based methods.
Quality control absorbs the dominant procurement volume. Research laboratory applications expand most quickly as cell and gene therapy development accelerates.
End User:
Capital availability, regulatory burden, and technical staffing levels determine which customer types drive premium versus economy assay procurement.
- Contract Research Organizations:These entities multiplex endotoxin testing across diverse client programs, requiring flexible assay formats compatible with varying sample matrices and regulatory filing jurisdictions. North Carolina and Massachusetts CRO clusters are consolidating purchasing through multi-year supply agreements that bundle validation support.
- Hospitals:Clinical laboratories within hospital systems prioritize integrated platforms that consolidate endotoxin testing with other microbiological assays, favoring suppliers with established service networks.
- Academic Institutes:University research groups operate with constrained capital budgets, sustaining demand for manual assay formats and smaller kit sizes.
- Diagnostic Laboratories:Independent testing facilities serving outpatient dialysis centers and specialty clinics require high-throughput formats with minimal technical complexity.
Contract research organizations concentrate premium procurement. Hospital systems are gaining share fastest as clinical endotoxin testing protocols expand.
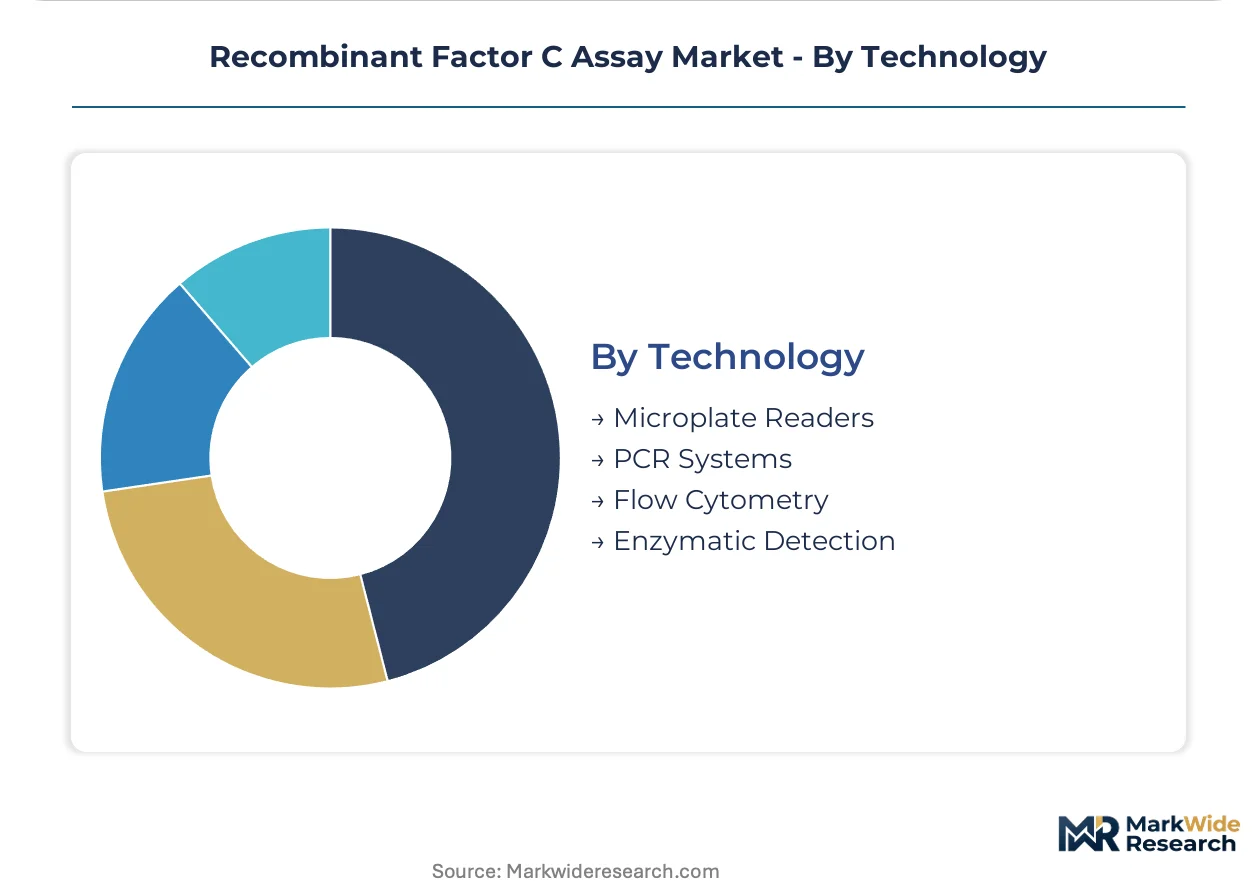
Technology:
Instrumentation compatibility and detection sensitivity specifications segment the underlying platform technologies that enable recombinant Factor C signal readout.
- Microplate Readers:Standard photometric and fluorometric plate readers dominate installed bases, with 96-well and 384-well formats enabling parallel sample processing. German and Swiss pharmaceutical QC laboratories standardize on these platforms for batch release documentation.
- Enzymatic Detection:The core recombinant Factor C biochemistry enabling lipopolysaccharide-specific signal generation underpins all commercial assay formats, with supplier differentiation residing in enzyme formulation stability and substrate kinetics.
- PCR Systems:Quantitative PCR platforms adapted for endotoxin detection via recombinant Factor C coupling occupy specialized niches requiring nucleic acid quantification alongside endotoxin measurement.
- Flow Cytometry:Cell-based endotoxin detection formats utilizing fluorescent reporter systems remain experimental, with limited commercial penetration outside research applications.
Microplate readers anchor the installed instrument base. Enzymatic detection biochemistry commands the steepest R&D investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Switzerland and Germany absorb price premiums for validated assay formats, while procurement teams in India and China negotiate aggressively on kit costs. Price elasticity diverges sharply between mature regulatory jurisdictions with EMA-aligned pharmacopeial requirements and emerging markets where cost-per-test dominates vendor selection.
United States
FDA's Center for Drug Evaluation and Research accepts recombinant Factor C data in New Drug Applications, driving validation investment by Massachusetts contract manufacturing organizations. The Biologics Price Competition and Innovation Act framework incentivizes rapid endotoxin testing for biosimilar batch release. Greater Boston cell therapy clusters are converting from Limulus Amebocyte Lysate to synthetic methods ahead of anticipated conservation restrictions.
Germany
EMA Chapter 2.6.32 recognition creates immediate procurement pull across Baden-Württemberg and Bavaria sterile manufacturing facilities. REACH sustainable chemistry incentives filter supplier qualification toward animal-free production documentation. Heidelberg and Munich biopharmaceutical corridors are consolidating purchasing through multi-year assay supply contracts bundled with regulatory filing support.
Switzerland
Swissmedic guidance aligns with EMA pharmacopeial standards, enabling seamless batch release protocols for Basel-based pharmaceutical exporters. The country's precision manufacturing heritage sustains premium pricing tolerance for fluorometric high-sensitivity formats. Roche and Novartis supplier ecosystems in the Basel-Land region are driving standardization on automated microplate platforms.
Japan
PMDA's continued preference for Limulus-based methods creates regulatory friction for multinational pharmaceutical companies seeking harmonized global protocols. METI industrial policy supports domestic horseshoe crab harvesting interests, delaying recombinant Factor C compendial acceptance. Osaka and Tokyo pharmaceutical QC laboratories maintain dual validation tracks to satisfy both domestic and export market requirements.
India
CDSCO's evolving pharmacopeial standards create uncertainty for contract research organizations serving European and North American clients. The PLI scheme for active pharmaceutical ingredients does not extend to endotoxin testing reagents, constraining domestic manufacturing investment. Hyderabad and Bangalore biotech corridors rely heavily on imported assay kits, with procurement teams prioritizing cost reduction over format standardization.
Recombinant Factor C Assay Market Vendor Landscape
Capability concentration sits with integrated life science conglomerates; scale advantage sits with specialized endotoxin testing suppliers. The market structures around three tiers: full-service reagent manufacturers with regulatory affairs infrastructure, niche biochemistry specialists with enzyme engineering expertise, and regional distributors with local validation support capabilities. Dominant competitive moves include strategic partnerships between assay developers and automated platform manufacturers, plus backward integration into recombinant protein production to secure supply chain control.
Among the integrated conglomerates, Thermo Fisher Scientific Inc. and Lonza Group AG exemplify the scale-driven tier with extensive distribution networks and captive manufacturing demand. Charles River Laboratories International, Inc. occupies a distinct position anchoring the pharmaceutical services integration archetype, bundling endotoxin testing within broader contract research portfolios. These three entities represent the primary competitive anchors against which specialized players differentiate on sensitivity specifications or regional price positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Hyglos GmbH |
| Lonza Group AG |
| Xiamen Bioendo Technology Co., Ltd. |
| GenScript Biotech Corporation |
| Charles River Laboratories International, Inc. |
| Associates of Cape Cod, Inc. |
| bioMérieux SA |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint risk at the Japanese Pharmacopoeia acceptance gap determines both three-tier pricing stratification across premium, standard, and economy levels and the geographic shape of supplier networks. Pharmaceutical manufacturers facing dual validation requirements absorb cost premiums for EMA-aligned formats while procurement teams in cost-sensitive markets negotiate aggressively on per-test kit economics.
Pricing Analysis
Validation support contracts and multi-year regulatory filing assistance drive lifetime value beyond the initial kit sale. The dominant structure runs through tiered subscription models bundling reagent supply with method transfer documentation, with price differentiation anchored in certification grade and automation integration level. Cost compression in manual assay tiers intensifies as academic buyers consolidate purchasing through group procurement organizations. Contract manufacturing organizations in Germany and Switzerland exhibit lowest price sensitivity, while Indian and Chinese CROs drive hardest bargain on per-unit costs.
Supply Chain Analysis
Recombinant protein feedstock production concentrates in Germany, Switzerland, and select Chinese biomanufacturing zones. The supply chain draws from genetically engineered cell lines, specialized fermentation media, and chromogenic or fluorometric substrate chemistries. Single-source vulnerability sits with enzyme formulation suppliers holding proprietary Factor C expression systems. Distribution runs through direct sales teams for large pharmaceutical accounts and specialized life science distributors for mid-tier CROs and academic institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated purchasing agreements among Massachusetts and German biopharmaceutical manufacturers, forcing suppliers to bundle validation services and absorb pricing pressure.
For Market Incumbents: Build regulatory filing moats by embedding dedicated EMA and FDA liaison teams within key account structures. Secure backward integration into recombinant protein production to eliminate enzyme supply vulnerability from third-party fermentation houses. Expand capacity in Baden-Württemberg to serve Swiss and German sterile manufacturing clusters with sub-48-hour delivery guarantees. For New Entrants and Emerging Players: Build out water quality monitoring applications for municipal utilities and dialysis center networks, the most penetrable segment outside pharmaceutical QC. Target Indian CRO corridors with economy-tier chromogenic formats priced below established import costs. Lead go-to-market through regional distributors offering local validation support rather than direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a regulatory substitution phase that favors enzyme engineering specialists with documented pharmacopeial acceptance. Long-term viability hinges on compendial harmonization completion across USP, EP, and JP standards. Watch Japanese PMDA guidance revisions as the critical inflection signal for global protocol unification and associated valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Chapter 2.6.32 alignment unlocks German and Swiss sterile manufacturing procurement. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Bavaria reduces enzyme supply lead times for European QC labs. |
| Strategic Partnership | Automation platform integration with liquid handling workstation vendors captures CRO throughput demand. |
| Geographic Expansion | Hyderabad and Bangalore service infrastructure addresses Indian CRO cost sensitivity with local support. |
| Backward Integration | In-house recombinant Factor C production insulates margins from third-party enzyme price volatility. |
Methodological Framework
Operator-level perspectives from QC laboratory directors, regulatory affairs managers at sterile manufacturing facilities, CRO procurement leads, and endotoxin testing assay developers anchored the qualitative base. These interviews combined with secondary validation from EMA guidance documents, FDA Type II Drug Master File submissions, European Pharmacopoeia revision tracking, and REACH compliance databases. Bottom-up demand modeling across detection chemistry formats triangulated against top-down pharmaceutical manufacturing capacity expansion data.
Scenario bracketing around Japanese Pharmacopoeia acceptance timing, horseshoe crab harvesting restriction severity, and automation adoption curves framed the projection horizon. Segmentation dimensions modeled include detection chemistry type, automation level, application context, and end-user facility scale. CAGRs were derived from regression analysis of historical assay kit procurement volumes against biologics manufacturing expansion indicators, with sensitivity testing for regulatory harmonization acceleration or delay.
Stress conditions across enzyme stability thresholds, cold chain logistics disruption, and compendial deadline shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EMA adoption trajectories and biologics pipeline maturation. Cross-checking against IQVIA pharmaceutical manufacturing capacity data and BCG bioprocessing investment surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Proteinase K Market