
 Europe Halal Food and Beverage Market | 2026-2036
Europe Halal Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Halal Food and Beverage Market Foresight
Supermarket retail is rebalancing toward dedicated halal aisles as mainstream grocers recognize the purchasing power of Muslim and health-conscious shoppers. BRF SA leverages its integrated poultry supply chain to anchor shelf presence across Iberia and Central Europe. Nestlé SA sustains R&D intensity in halal-compliant confectionery and infant nutrition formulations. Danish Crown competes through specialized halal slaughtering facilities that meet both Islamic requirements and Danish veterinary standards.
Halal food and beverage encompasses consumable products prepared according to Islamic dietary law, requiring absence of pork derivatives, alcohol, and non-halal animal byproducts, with slaughter performed by a Muslim invoking Allah's name while ensuring complete blood drainage. The category serves both religious observance and expanding commercial demand from non-Muslim consumers seeking perceived cleanliness and ethical sourcing. Meat and dairy segments dominate current revenue due to established certification infrastructure and higher per-unit value, while snacks and beverages represent faster-growth pockets as younger Muslim consumers seek convenient, on-the-go formats. Supervised certification types command premium positioning among risk-averse buyers, whereas halal-compliant labels penetrate mass retail through lower audit burdens.
EFSA guidelines on food labeling and traceability, coupled with national halal certification bodies in France (AFNOR-compatible schemes), the United Kingdom (HFA, HMC), and Germany (European Halal Authority networks), create a fragmented but tightening compliance landscape that raises barriers for uncertified imports. The EU Green Deal's sustainable agriculture targets intersect with halal supply chains through demands for grass-fed sourcing and reduced antibiotic use. Stakeholders must monitor divergence between member-state certification mutual recognition and emerging EU-wide halal standardization proposals that could reshape market access rules.
Market Dynamics
EFSA labeling requirements and EU-wide traceability mandates under the General Food Law are tightening compliance thresholds, forcing halal suppliers to restructure certification workflows and cross-border documentation systems.
Growth Catalysts
- EFSA traceability mandates:The EU General Food Law now requires batch-level documentation for halal meat imports, creating competitive advantage for suppliers with pre-existing digital tracking infrastructure.
- France's concentrated Muslim consumer base:Paris and Marseille sustain category volume through established halal retail networks and restaurant procurement patterns.
- Supermarket shelf expansion:Dedicated halal aisles in German, French, and UK retail chains are normalizing halal product placement alongside conventional categories.
Market Restraints
- Certification cost structure:Multiple national halal bodies across Europe impose overlapping audit fees that disproportionately burden small and mid-sized meat processors.
- Supply concentration in poultry:Iberian and Central European poultry suppliers control critical slaughtering capacity, creating bottleneck risk for downstream halal product manufacturers.
- Regulatory friction from fragmented standards:Mutual non-recognition between AFNOR-compatible French schemes, UK HFA/HMC certifications, and German European Halal Authority networks complicates cross-border trade.
Strategic Opportunities
- Underpenetrated Central European markets:Poland and Czech Republic show emerging halal demand from Muslim immigrant communities and export-oriented food manufacturers seeking halal certification for Middle East re-export.
- EU Green Deal intersection:Sustainable agriculture targets create positioning space for halal suppliers with verified grass-fed sourcing and reduced antibiotic protocols.
- E-commerce direct-to-consumer channels:Specialized halal delivery platforms bypass traditional retail gatekeepers and capture margin from convenience-seeking urban Muslim households.
Industry Challenges
- Slaughter certification talent scarcity:Qualified Muslim slaughterers with simultaneous veterinary compliance training remain concentrated in established production regions, constraining geographic expansion.
- Legacy ERP integration with halal tracking:Many European meat processors operate decades-old inventory systems that cannot accommodate EFSA-mandated batch segregation and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Halal Food and Beverage Market |
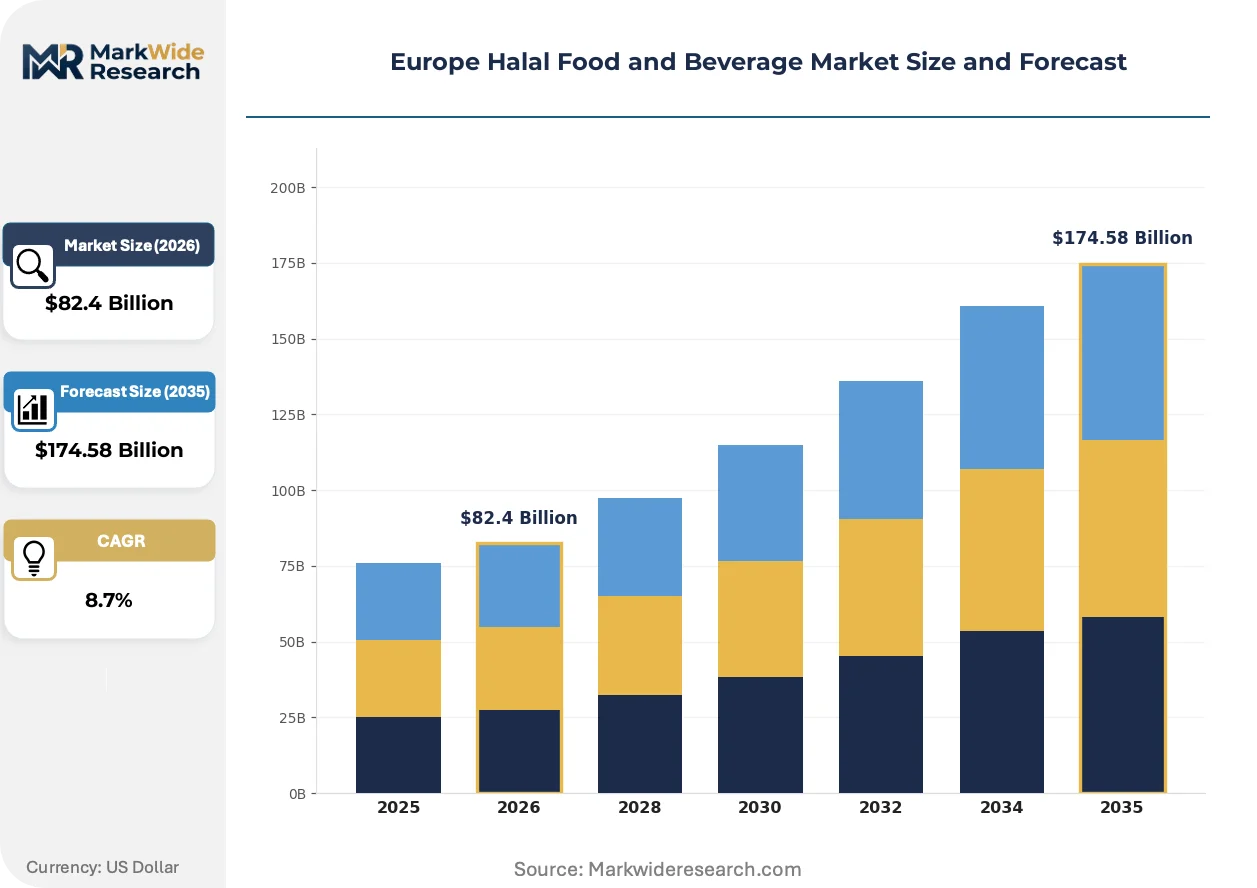
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $174.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Snacks, Beverages Certification Type: Halal Certified, Halal Compliant, Supervised, Verified Sales Channel: Supermarkets, Online, Convenience Stores, Specialty Stores Consumer Type: Muslim Consumers, Health-Conscious Buyers, Ethical Consumers, Others |
| Companies Covered | BRF SA, Danish Crown, Nestlé SA, Mars Incorporated, Ferrero International, Isla Délice, One World Foods, Al Islami Foods, Cargill Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Halal Food and Beverage Market Shifts & Advancements
Blockchain-based supply chain verification is reshaping how halal integrity is demonstrated to risk-averse buyers. Digital traceability layers now sit atop physical logistics, compressing audit timelines and reducing documentation disputes.
Blockchain ledger technology is integrating halal certification data with veterinary health records and transport temperature logs. Major French and UK supermarket procurement teams now require this integrated data package for private-label halal meat contracts. The technology is compressing supplier onboarding timelines from months to weeks by automating cross-border documentation verification.
EFSA guidelines on food labeling and traceability are mandating machine-readable QR codes linking to origin and slaughter documentation. This industrial consequence forces halal meat packers to retool packaging lines and invest in serialization equipment. The ready-meal and processed meat segments are responding fastest, with French manufacturers leading implementation to maintain retail shelf access.
Younger Muslim consumers are shifting toward convenience formats that do not sacrifice religious observance. Single-serve halal snacks and on-the-go beverages are displacing traditional family-size purchases in urban UK and French convenience stores. This pattern is most visible among 18-34 year old consumers in London and Paris, where halal foodservice delivery apps now capture significant meal occasion share from home cooking.
Europe Halal Food and Beverage Market Segmentation
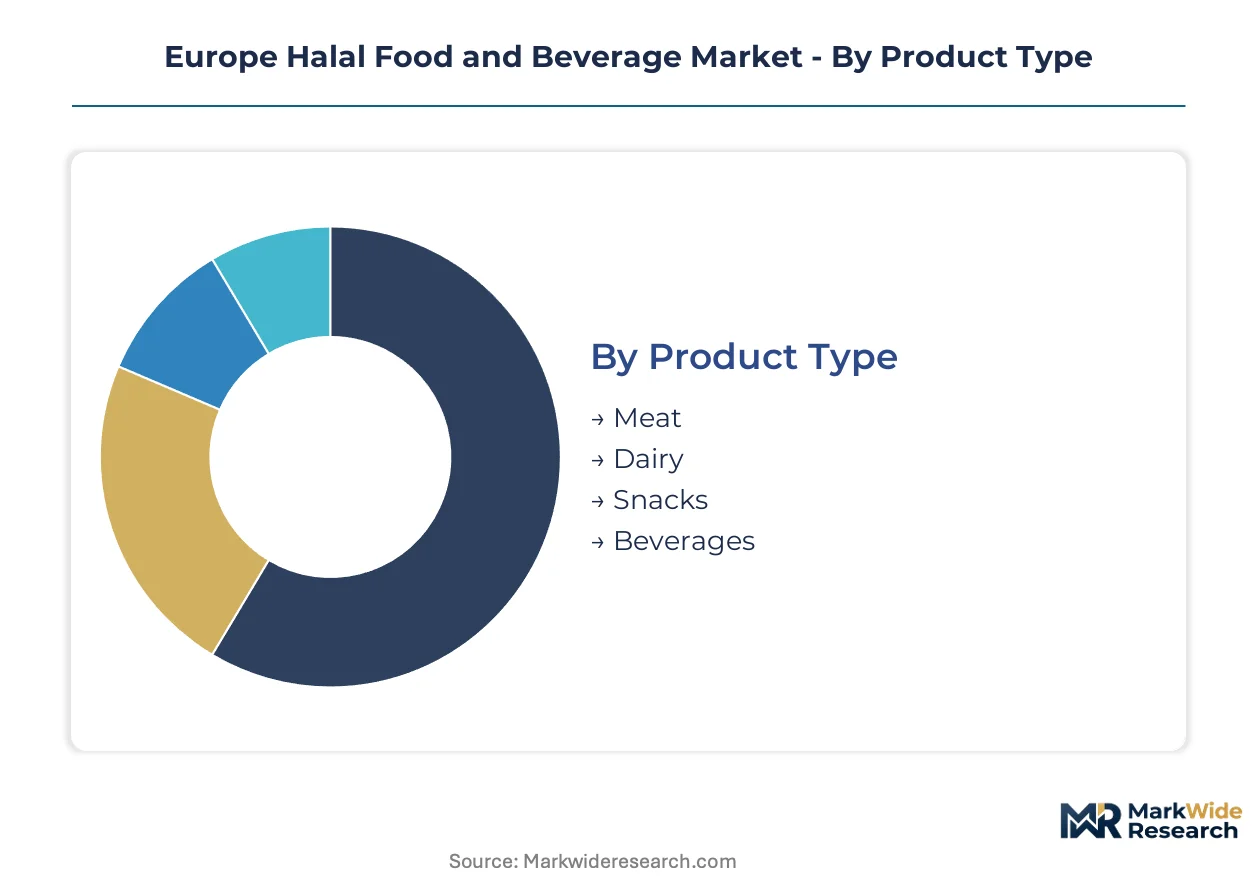
Halal food and beverage segmentation in Europe reflects competing pressures between religious observance, retail accessibility, and evolving consumer identity. Category boundaries increasingly blur as health-conscious non-Muslim buyers enter segments originally designed for faith-based compliance.
Product Type:
Meat and dairy anchor revenue through higher per-unit value and established certification infrastructure, while snacks and beverages climb fastest on convenience demand from younger urban consumers.
- Meat:Poultry dominates slaughter capacity across Iberia and Central Europe, with EFSA batch-level traceability mandates now standard for cross-border trade. French and German retail procurement concentrates in supervised halal certification tiers to minimize reputational risk.
- Dairy:Infant nutrition and cheese formulations command premium positioning through Nestlé's R&D investment in halal-compliant processing lines. Demand clusters in UK and French supermarket chains expanding dedicated halal shelf space.
- Snacks:Single-serve formats displace family-size purchases among 18-34 year old consumers in London and Paris convenience stores.
- Beverages:Alcohol-free positioning intersects with broader health trends, capturing non-Muslim trial in German urban markets.
Mature deployment sits with Meat. Newer deployment is concentrated in Snacks.
Certification Type:
Audit intensity creates a three-tier cost structure that directly shapes market access and margin capture across European retail channels.
- Halal Certified:Full third-party verification by national bodies such as France's AFNOR-compatible schemes or UK HFA/HMC standards. Supermarket private-label contracts in Germany and France increasingly mandate this tier for shelf placement.
- Supervised:Continuous on-site Muslim oversight during production, commanding premium positioning among risk-averse institutional buyers in French hospital and school catering networks.
- Halal Compliant:Self-declared adherence without external audit, penetrating mass retail through lower compliance burdens but facing pressure from tightening EFSA documentation requirements.
- Verified:Blockchain-linked supply chain confirmation integrating veterinary records with slaughter documentation, compressing supplier onboarding timelines for UK and French supermarket procurement teams.
Established volume flows through Halal Certified. Verified certification is expanding most quickly as blockchain infrastructure spreads.
Sales Channel:
Channel strategy determines certification tier requirements and directly influences margin structure through gatekeeper power.
- Supermarkets:Dedicated halal aisle expansion across German, French, and UK chains normalizes product placement alongside conventional categories. EAN-compliant labeling and EFSA traceability documentation are now table stakes for listing.
- Online:Specialized halal delivery platforms bypass traditional retail gatekeepers, capturing margin from convenience-seeking urban Muslim households in London and Paris.
- Convenience Stores:Single-serve and on-the-go formats dominate, responding to younger consumer shift away from planned family meals.
- Specialty Stores:Ethnic grocery networks in Marseille and Birmingham maintain procurement relationships with smaller processors lacking supermarket scale.
Volume concentration remains with Supermarkets. Online channels show steepest expansion trajectory as delivery platforms consolidate.
Consumer Type:
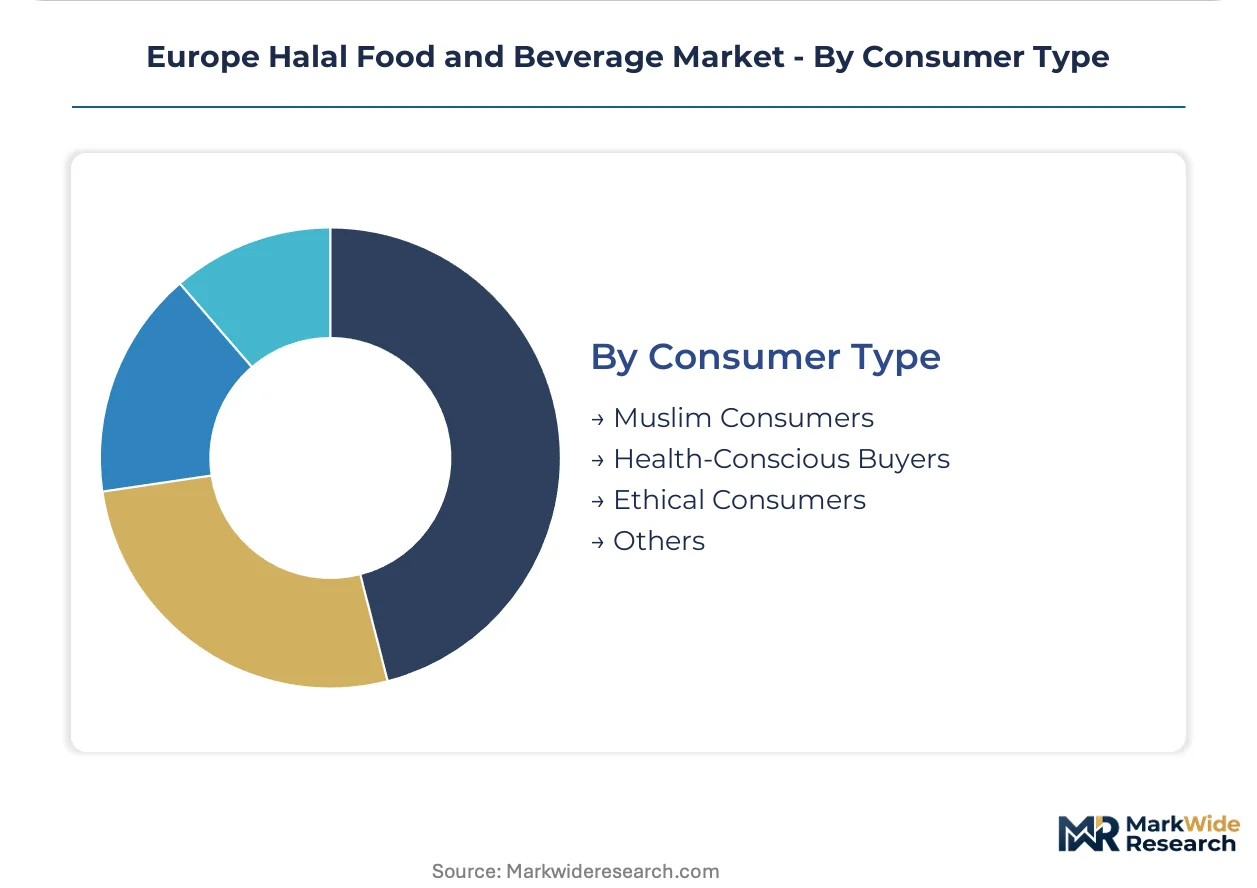
Buyer identity increasingly decouples from religious practice, creating segmentation complexity around motivation rather than demographic.
- Muslim Consumers:Core demand driver sustaining category volume through Paris, Marseille, and London population concentration. Religious observance mandates strict certification tier requirements.
- Health-Conscious Buyers:Perceived cleanliness and ethical sourcing attract non-Muslim trial, particularly in German and UK markets where antibiotic reduction aligns with EU Green Deal targets.
- Ethical Consumers:Grass-fed and reduced-antibiotic protocols intersect with halal supply chain positioning, creating dual-claim product opportunities.
- Others:Institutional procurement including export-oriented manufacturers seeking halal certification for Middle East re-export from Poland and Czech Republic.
Established demand anchors with Muslim Consumers. Health-Conscious Buyers represent the fastest-growing recruitment pool as certification transparency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Halal Economic Zone near Paris-Charles de Gaulle Airport concentrates slaughtering capacity and cold-chain logistics, drawing processors seeking EFSA-compliant export infrastructure. This tax-advantaged cluster anchors European halal trade flows toward Middle Eastern markets.
France
Paris and Marseille sustain the continent's densest Muslim consumer concentration, driving procurement volume through dedicated halal retail networks and institutional catering contracts. AFNOR-compatible certification schemes under national standardization policy tighten audit requirements for imported meat. The Île-de-France industrial corridor hosts specialized slaughtering facilities that supply both domestic supermarket chains and re-export channels.
Germany
Munich and Berlin anchor demand from Turkish and Arab immigrant communities, with supermarket chains expanding dedicated shelf space in response to purchasing power concentration. The European Halal Authority network coordinates certification mutual recognition across federal states, though fragmentation persists between regional bodies. North Rhine-Westphalia's food processing belt integrates halal lines into conventional meatpacking plants to serve both domestic and Dutch export markets.
United Kingdom
London and Birmingham concentrate category volume through established ethnic retail networks and mainstream supermarket penetration. HFA and HMC certification bodies operate parallel schemes with diverging slaughter supervision standards, complicating procurement for national retail chains. The Midlands industrial corridor hosts mid-scale processors supplying both domestic foodservice and European re-export channels.
Netherlands
Rotterdam's port infrastructure positions the country as a halal meat re-export hub, with specialized cold storage facilities serving Middle Eastern and Southeast Asian markets. Dutch veterinary standards for ritual slaughter exceed baseline EU requirements, creating compliance premiums for suppliers. The Gelderland processing cluster integrates halal certification into conventional poultry and beef operations.
Spain
Barcelona and Madrid emerge as growth markets, driven by North African immigrant communities and tourism-sector foodservice demand. Iberian poultry suppliers leverage existing slaughtering capacity to capture halal market share without dedicated facility investment. The Catalonia meatpacking corridor adapts production lines for dual conventional-halal output to serve French and Italian buyers.
Europe Halal Food and Beverage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated protein companies controlling upstream slaughtering and packaged goods multinationals dominating downstream formulation. Market structure tilts toward consolidation in meat processing, where capital-intensive halal certification and EFSA traceability infrastructure favor scale players, while snacks and beverages retain fragmentation due to lower entry barriers. Three archetypes dominate: integrated poultry suppliers with captive slaughtering capacity, multinational CPG conglomerates with dedicated halal R&D facilities, and regional ethnic food specialists with deep distribution in immigrant communities. Competitive dynamics center on backward integration into certified slaughtering and strategic partnerships with retail chains for dedicated shelf space allocation.
Among Brazil-based integrated protein suppliers, BRF SA exemplifies the upstream-anchored archetype through its Iberian and Central European poultry operations. Danish Crown occupies a position within the supervised-certification tier, leveraging specialized slaughtering infrastructure that bridges Islamic requirements with stringent veterinary protocols. Nestlé SA represents the multinational formulation specialist, sustaining R&D intensity in halal-compliant confectionery and infant nutrition. Mars Incorporated and Ferrero International sit within the branded confectionery segment, competing through portfolio adaptation rather than supply chain control.
| Leading Market Players |
|---|
| BRF SA |
| Danish Crown |
| Nestlé SA |
| Mars Incorporated |
| Ferrero International |
| Isla Délice |
| One World Foods |
| Al Islami Foods |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Slaughter certification labor costs cascade through three distinct pricing tiers as supervised halal commands premium positioning over compliant-labeled alternatives. Poultry feed and veterinary compliance expenses concentrate in Iberian and Central European processing clusters, transmitting cost pressure downstream to French and German retail procurement teams.
Pricing Analysis
Short lead-time delivery premiums separate supervised certification tiers from standard halal-compliant products in French and UK supermarket contracts. Three-tier pricing structure across premium, standard, and economy levels reflects audit intensity, with blockchain-verified batches capturing highest margins from risk-averse institutional buyers. Cost compression in the compliant tier is intensifying because EFSA documentation mandates force packaging line retooling investments. Price-sensitive ethnic grocery networks in Marseille and Birmingham resist premium migration, while hospital and school catering procurement shows lowest elasticity.
Supply Chain Analysis
Certification-qualified Muslim slaughterers with veterinary training credentials gate entry into supervised halal production tiers. Supply concentrates in Spain, Poland, and Denmark for poultry and beef slaughtering capacity, with raw material flows drawing from Iberian grain belts and Baltic feedstock corridors. Single-source vulnerability sits with concentrated slaughtering talent pools in the Île-de-France and North Rhine-Westphalia corridors. Distribution runs through Rotterdam port infrastructure for Middle Eastern re-export, alongside direct cold-chain delivery to German and French supermarket distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around scale players with captive slaughtering infrastructure as EFSA traceability mandates raise compliance barriers beyond mid-processor reach.
For Market Incumbents: Extend blockchain verification coverage across supplier networks to compress audit timelines and defend supermarket private-label contracts from emerging integrated poultry competitors. Anchor backward integration into Polish and Czech slaughtering capacity to preempt re-export channel capture by Iberian rivals. Certification investment in dual conventional-halal production lines protects margin structure as Dutch veterinary standards tighten. For New Entrants and Emerging Players: Begin with Central European ethnic grocery networks in Prague and Warsaw where halal shelf space remains underdeveloped relative to Paris saturation. Target convenience-format snacks and beverages for 18-34 urban consumers, leveraging direct-to-consumer delivery platforms to bypass established retail gatekeepers. A halal-compliant positioning without full supervised audit offers lowest-friction entry before EFSA standardization tightens. For Investors and Strategic Acquirers: EU-wide halal standardization proposal advancement is the leading indicator that certification mutual recognition will reshape market access rules and reward pan-European scale. Mid-cap processors with existing EFSA-compliant documentation infrastructure and Rotterdam port access represent prime acquisition targets. Watch for French AFNOR scheme expansion into German retail networks as consolidation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Supply Chain Verification | Automated documentation compresses supplier onboarding from months to weeks for French supermarket procurement. |
| Dual Conventional-Halal Production Lines | Catalonia meatpacking corridor adaptation captures French and Italian buyer volume without dedicated facility investment. |
| Central European Slaughtering Capacity Expansion | Polish and Czech processing clusters serve emerging domestic demand plus Middle East re-export channels. |
| Direct-to-Consumer Delivery Platform Launch | Specialized halal apps capture margin from convenience-seeking urban Muslim households in London and Paris. |
| EU Green Deal Compliance Positioning | Verified grass-fed sourcing and reduced antibiotic protocols attract health-conscious non-Muslim German buyers. |
Research Methodology
Independent corroboration across certification body audit records, EFSA traceability filings, and supermarket procurement documentation underwrites the qualitative findings in this analysis. Primary interviews with halal certification auditors, meat processing plant managers, French and German retail category buyers, and veterinary compliance officers combined with secondary validation from customs trade data, EFSA guidance documents, and national halal body certification registries. Bottom-up volume modeling triangulated against top-down consumer expenditure estimates anchored the market sizing framework.
Rate-of-change decomposition across product type, certification tier, sales channel, and consumer motivation segments structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories and price evolution assumptions, with specific inputs including EFSA mandate implementation timelines and Muslim population concentration shifts in Paris, Marseille, London, and Berlin urban corridors.
Underlying measurement precision varies by segment; meat and dairy carry tighter precision than emerging snacks and beverages due to established certification infrastructure transparency. Forecasts reflect documented assumptions about regulatory harmonization progress and slaughtering capacity expansion rates. A model refresh is warranted upon material change in EU-wide halal standardization proposal advancement or EFSA batch-level documentation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Konjac Noodles Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Zhacai Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Poke Food Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Triphala Powder Market