
 Halal Foods Market | 2026-2036
Halal Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Foods Market Analysis
Slaughterhouse certification expertise is collapsing across traditional halal-producing regions, constraining throughput expansion just as demand accelerates. Cargill Inc. leverages its integrated protein supply chains to secure multi-country halal accreditation at scale. Nestle S.A. sustains portfolio-wide reformulation capabilities that maintain compliance across varying national halal standards. QL Foods Sdn Bhd anchors Malaysian domestic supply through captive aquaculture and poultry processing infrastructure.
Halal foods comprise consumable products prepared according to Islamic dietary law (Sharia), requiring species permissibility, ritual slaughter (dhabihah), and absence of alcohol, blood, or cross-contaminants such as porcine derivatives; the standard governs ingredient provenance, processing equipment sanitation, and supply chain segregation to serve both religious observance and quality-assurance functions for Muslim and non-Muslim consumers. Meat commands the dominant value share within product type segmentation due to protein premiumization and ritual compliance complexity, while beverages represents the fastest-expanding category as functional halal drinks penetrate convenience retail. Distribution channel dynamics reveal supermarkets controlling volume throughput in established markets, whereas online channels are capturing disproportionate growth in markets with fragmented specialty retail infrastructure.
Indonesia's BPJPH, Malaysia's JAKIM, and Saudi Arabia's SFDA operate the most consequential halal certification regimes, each imposing distinct slaughter protocols, audit frequencies, and cross-border mutual recognition requirements that determine market access eligibility. The EU's recent extension of halal labeling requirements under EFSA guidance is forcing reformulation investments among exporters targeting European Muslim populations. Stakeholders must monitor certification reciprocity negotiations between Southeast Asian and Gulf regulatory bodies, as harmonization failures would fragment supply chain economics and duplicate compliance costs.
Market Dynamics
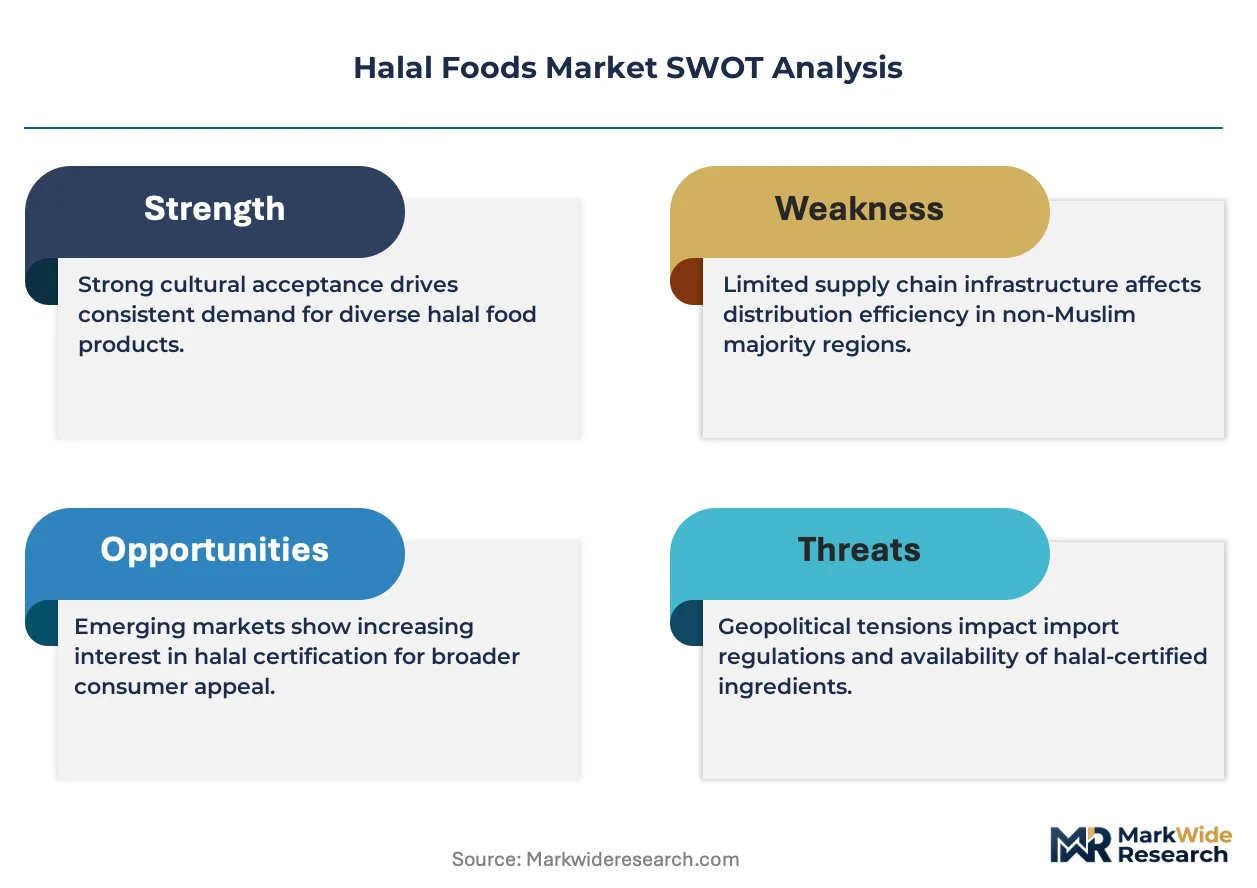
Certification fragmentation across Indonesia's BPJPH, Malaysia's JAKIM, and Saudi Arabia's SFDA is forcing supply chain duplication as exporters pursue multi-jurisdictional accreditation to access concentrated Muslim consumer bases.
Growth Catalysts
- Urban protein premiumization:Middle-income households in Jakarta and Kuala Lumpur are prioritizing verified halal supply chains for poultry and aquaculture, tightening procurement specifications at quick-service restaurants.
- EFSA labeling extension:The EU's expanded halal disclosure requirements under EFSA guidance are compelling reformulation investments that expand compliant product availability for European Muslim populations.
- Blockchain traceability deployment:Distributed ledger systems are decomposing opaque supply chains into auditable segments, accelerating certification verification and reducing cross-contamination risk.
Market Restraints
- Slaughterhouse certification scarcity:Collapsing expertise in traditional halal-producing regions is constraining throughput expansion just as demand accelerates, creating processing bottlenecks.
- Input cost volatility:Feed grain price fluctuations and aquaculture input inflation are compressing margins for integrated protein processors operating captive supply chains.
- Mutual recognition failures:stalled harmonization negotiations between Southeast Asian and Gulf regulatory bodies are fragmenting supply chain economics and duplicating compliance expenditures.
Strategic Opportunities
- Functional beverage penetration:Halal-certified functional drinks represent underexploited white space in convenience retail channels across Indonesia's secondary cities.
- Online channel capture:E-commerce platforms are capturing disproportionate growth in markets with fragmented specialty retail infrastructure, bypassing traditional supermarket dominance.
- Cross-border audit standardization:Accelerating reciprocity frameworks between JAKIM and BPJPH could consolidate certification costs for processors serving both markets simultaneously.
Industry Challenges
- Slaughter technician shortage:Declining pools of dhabihah-certified personnel are extending certification timelines and limiting facility utilization rates.
- Equipment segregation capex:Dedicated processing lines and sanitation infrastructure require substantial capital deployment to prevent porcine derivative cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Foods Market |
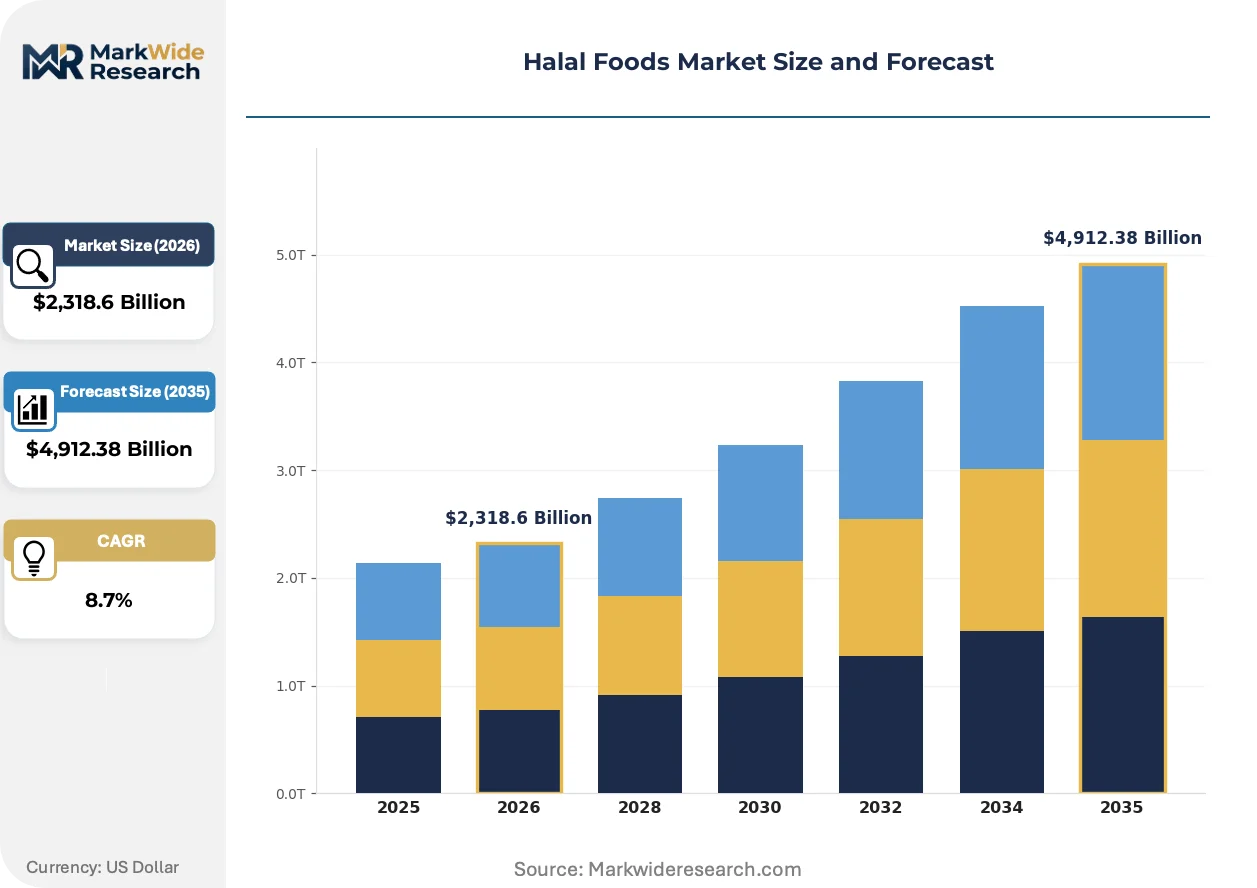
| Market Size in 2026 | $2,318.6 Billion |
| Market Size in 2035 | $4,912.38 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Grain, Beverages Packaging Type: Boxes, Pouches, Cans, Jars Distribution Channel: Supermarkets, Online, Food Service, Specialty Stores Consumer Type: Muslims, Non-Muslims, Health-Conscious, Ethical Consumers |
| Companies Covered | Al Islami Foods, QL Foods Sdn Bhd, Cargill Inc., Nestle S.A., BRF S.A., Saffron Road, Kawan Foods Berhad, DagangHalal Group, Almarai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Foods Market Emerging Trajectories
Digital traceability infrastructure and shifting procurement specifications are restructuring how halal compliance is verified and monetized across protein supply chains.
Blockchain-based provenance tracking is decomposing traditional paper-based certification into granular, real-time audit trails. Quick-service restaurant chains in Southeast Asia are piloting these systems to satisfy tightening JAKIM and BPJPH documentation requirements. The technology is decomposing intermediary verification roles and compressing certification cycle times from months to weeks.
EFSA's extended halal labeling guidance is mandating ingredient disclosure granularity that exceeds prior national standards. European exporters are reformulating product lines to capture compliance premiums in markets with concentrated Muslim populations. Beverage and processed meat categories face the steepest adaptation costs as they retest supply chains against the new benchmarks.
Certification-driven preference formation is displacing price-first procurement in Indonesia's urban retail channels. Supermarket buyers are prioritizing multi-standard accredited suppliers to reduce stock-keeping complexity. This behavioral shift is most visible in Jakarta's modern trade format, where shelf-space allocation increasingly correlates with certification breadth rather than unit economics alone.
Halal Foods Market Segmentation
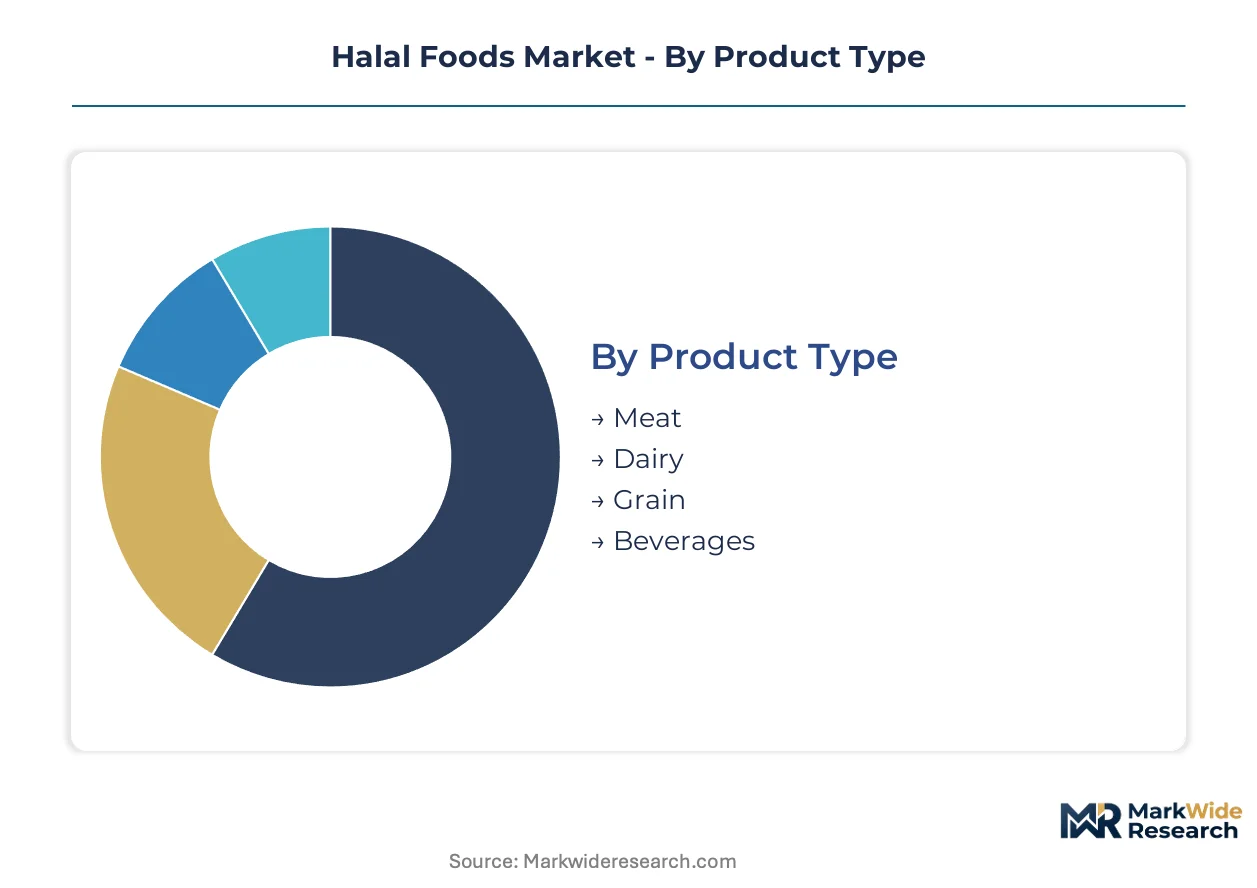
Halal food segmentation reflects divergent margin economics across ritual-intensive categories versus commodity-adjacent formats. Certification complexity and channel access requirements fragment profitability pools unevenly across product types and distribution pathways.
Product Type:
Margin pools concentrate in categories where ritual slaughter protocols and supply chain segregation create defendable quality premiums.
- Meat:Ritual dhabihah slaughter and species permissibility verification impose processing complexity that sustains price premiums over conventional proteins. Demand concentrates in Southeast Asian quick-service restaurant chains where JAKIM and BPJPH accreditation determines supplier eligibility.
- Beverages:Functional halal-certified drinks are penetrating convenience retail in Indonesia's secondary cities, displacing conventional alternatives through certification-driven preference formation.
- Dairy:Enzyme sourcing and cross-contamination protocols dominate compliance costs for cheese and fermented products.
- Grain:Bread and cereal categories face lower ritual barriers but require alcohol-free flavoring verification.
Meat holds installed capacity. Beverages is rotating up the share rankings.
Packaging Type:
Packaging selection tracks shelf-life requirements and channel-specific merchandising constraints across ambient and chilled distribution.
- Pouches:Flexible retort pouches dominate ready-to-eat halal meal formats in Southeast Asian convenience retail, balancing portability with extended ambient stability.
- Boxes:Corrugated and folding carton formats serve bulk retail and food service procurement where stacking strength and print surface for certification marks matter.
- Cans:Metal packaging sustains ambient shelf life for processed meats and beverages in markets with unreliable cold chain infrastructure.
- Jars:Glass containers preserve product visibility for premium condiments and spreads targeting gift and specialty retail channels.
Pouches command food service volume. Boxes are rotating up the share rankings.
Distribution Channel:
Channel economics diverge between volume-throughput formats and emerging digital pathways that bypass traditional retail gatekeepers.
- Supermarkets:Modern trade formats in Jakarta and Kuala Lumpur control volume throughput, with shelf-space allocation increasingly tied to multi-standard certification breadth.
- Online:E-commerce platforms capture disproportionate growth in markets with fragmented specialty retail infrastructure, collapsing geographic access constraints for certified products.
- Food Service:Quick-service restaurant procurement specifications are tightening across Southeast Asia, requiring documented halal supply chain segregation.
- Specialty Stores:Ethnic grocery and religious bookshop formats serve concentrated Muslim populations with curated certification portfolios.
Supermarkets hold installed capacity. Online is climbing the fastest.
Consumer Type:
Consumer segmentation reveals quality-assurance motivations extending beyond religious observance into health and ethical positioning.
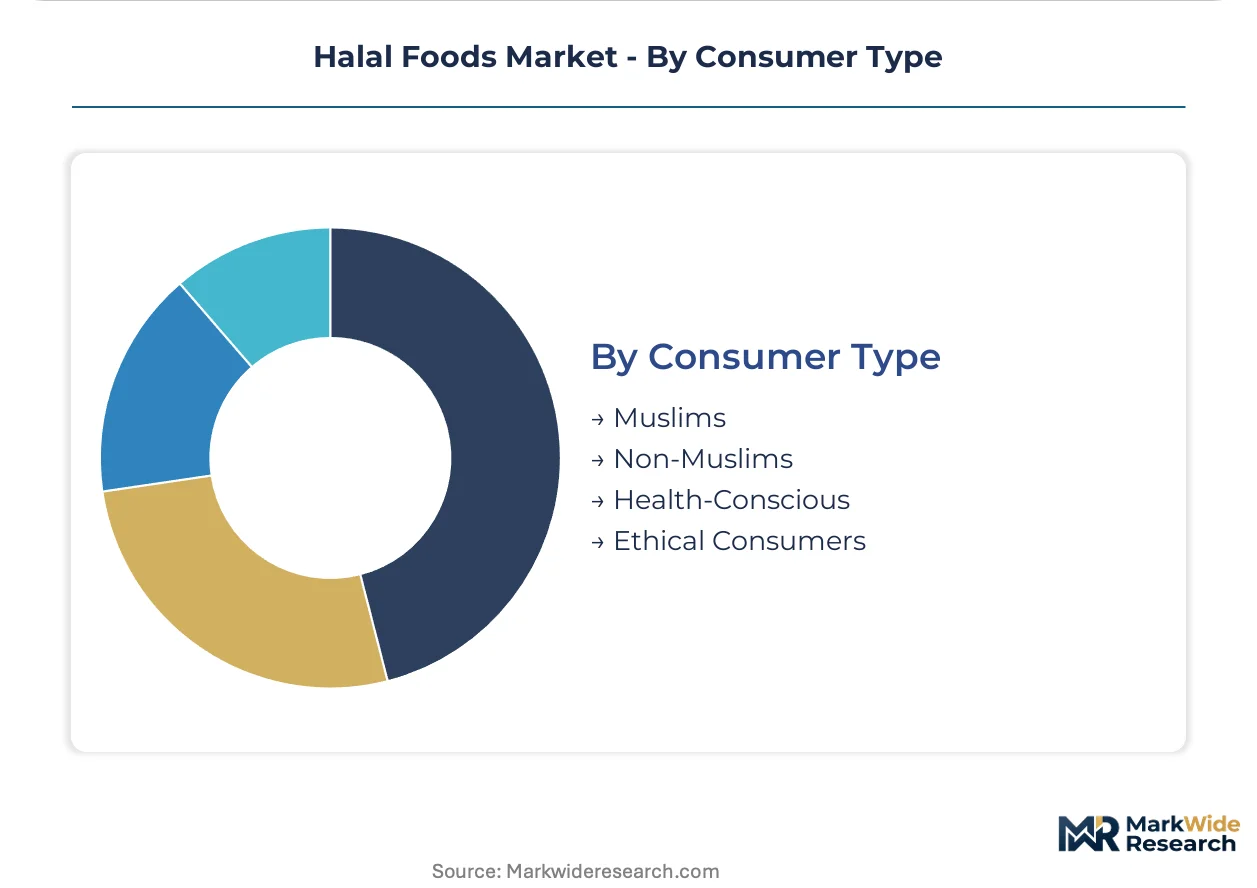
- Muslims:Religious observance drives baseline demand, with urban middle-income households prioritizing verified supply chains over price-first procurement.
- Health-Conscious:Non-Muslim consumers are adopting halal products as shorthand for ingredient transparency and processing rigor, particularly in European markets under EFSA labeling guidance.
- Non-Muslims:Price-sensitive mainstream consumers purchase halal products incidentally where certification carries no premium penalty.
- Ethical Consumers:Animal welfare and environmental claims intersect with halal slaughter protocols in premium positioning for select meat categories.
Muslims hold installed capacity. Health-Conscious is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Halal food consumption patterns diverge sharply between Muslim-majority markets where religious observance drives baseline demand and Western markets where certification functions as a quality-assurance signal for health-conscious non-Muslim consumers. The former prioritizes ritual compliance verification and supply chain segregation, while the latter responds to EFSA labeling transparency requirements.
Indonesia
Urban middle-income households in Jakarta and Surabaya are shifting protein procurement toward verified halal supply chains for poultry and processed foods. BPJPH mandates under Law No. 33 of 2014 impose mandatory certification deadlines that compress processor compliance timelines. The Greater Jakarta corridor concentrates quick-service restaurant expansion where procurement specifications now require documented halal accreditation.
Malaysia
JAKIM certification requirements are tightening cross-border compliance standards for exporters serving domestic quick-service restaurant chains. The National Halal Industry Master Plan channels investment into integrated poultry and aquaculture processing zones. Penang and Selangor host captive supply infrastructure that anchors domestic protein security.
Saudi Arabia
SFDA operates the Gulf's most consequential halal certification regime with distinct slaughter protocols and audit frequencies that determine market access eligibility. Food service channels across Riyadh and Jeddah are expanding procurement of multi-standard accredited proteins. The Kingdom's Vision 2030 food security agenda prioritizes domestic processing capacity over import dependency.
United States
Concentrated Muslim populations in Michigan, Illinois, and New Jersey drive demand for ritual-compliant proteins in ethnic retail formats. USDA oversight intersects with private halal certification bodies that lack federal standardization, creating compliance variability. The Chicago metropolitan area anchors domestic halal meat processing and distribution infrastructure.
Germany
EFSA labeling extensions under EU guidance are compelling reformulation investments among exporters targeting European Muslim populations. Turkish and North African diaspora communities in Berlin and the Ruhr region sustain demand for ritual-compliant products. The country's federal structure fragments certification recognition across Länder boundaries.
Halal Foods Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on certification breadth and captive supply reliability. The market structure rewards players with multi-jurisdictional accreditation capabilities and backward integration into protein sourcing. Three archetypes dominate: diversified conglomerates with portfolio-wide reformulation capabilities, regional processors with JAKIM or BPJPH captive supply infrastructure, and specialty brands targeting diaspora convenience retail. Competitive moves concentrate on certification reciprocity negotiations and blockchain traceability deployment to compress audit cycle times.
Within the integrated protein tier, Cargill Inc. and Nestle S.A. represent multinational scale advantages in securing simultaneous multi-country halal accreditation. QL Foods Sdn Bhd exemplifies the regional captive supply archetype through its Malaysian aquaculture and poultry processing infrastructure. These three anchors illustrate how certification complexity favors players with dedicated compliance infrastructure and documented supply chain segregation capabilities.
| Leading Market Players |
|---|
| Al Islami Foods |
| QL Foods Sdn Bhd |
| Cargill Inc. |
| Nestle S.A. |
| BRF S.A. |
| Saffron Road |
| Kawan Foods Berhad |
| DagangHalal Group |
| Almarai |
| Others |
Supply Flow & Price Mechanics
Ninety-day certification timelines from BPJPH and JAKIM submission to approval compress inventory cycles and amplify pricing power for processors with pre-cleared multi-standard accreditation. This lead-time compression rewards captive supply infrastructure while penalizing spot-market procurement strategies.
Pricing Analysis
Long-term offtake agreements dominate protein procurement between integrated processors and quick-service restaurant chains, insulating certified suppliers from spot-market volatility. Pricing stratifies across JAKIM-BPJPH dual certification, single-standard compliance, and uncertified commodity tiers. Cost compression in single-standard tiers is intensifying because slaughterhouse certification scarcity extends fulfillment timelines. Quick-service chains demonstrate lowest price sensitivity due to mandatory compliance requirements, while ethnic retail formats retain higher elasticity.
Supply Chain Analysis
Malaysia and Indonesia anchor captive poultry and aquaculture processing infrastructure that feeds Southeast Asian food service channels. Feed grain imports from Argentina and Ukraine, combined with aquaculture inputs from domestic hatcheries, rest on volatile commodity pricing. Single-source vulnerability concentrates in JAKIM-accredited slaughter technicians whose declining numbers constrain facility utilization. Distribution runs through integrated cold-chain networks serving modern trade formats in Jakarta and Kuala Lumpur.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain traceability deployment across protein supply chains constitutes a regulatory inflection that will separate accredited leaders from compliance laggards within the forecast window.
For Market Incumbents: Secure multi-jurisdictional reciprocity agreements between JAKIM and BPJPH before harmonization negotiations stall, eliminating duplicate audit costs. Expand captive aquaculture capacity in Selangor and Penang to offset feed grain price volatility. Certification investment in blockchain-enabled provenance systems addresses emerging quick-service restaurant procurement specifications. For New Entrants and Emerging Players: BPJPH fast-track accreditation for functional beverage categories represents the most penetrable white space, given underdeveloped halal-compliant probiotic and protein drink portfolios in Indonesia's secondary cities. Target Surabaya and Medan convenience retail through direct-to-store distribution partnerships that bypass established supermarket gatekeepers. Digital-native branding emphasizing transparent supply chain documentation accelerates trial among urban middle-income households. For Investors and Strategic Acquirers: Long-term, this sits as a quality-assurance infrastructure play because halal certification complexity creates durable moats around processors with documented segregation capabilities and multi-standard accreditation. Acquisition candidates should demonstrate backward integration into protein sourcing and established relationships with at least two of Indonesia's BPJPH, Malaysia's JAKIM, or Saudi Arabia's SFDA. The signal to watch is reciprocity framework announcements between Southeast Asian and Gulf regulatory bodies that would consolidate compliance economics for dual-market operators.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Dual JAKIM-BPJPH accreditation unlocks procurement eligibility across Malaysia and Indonesia's quick-service restaurant chains. |
| Blockchain Traceability Deployment | Distributed ledger systems compress audit cycle times from months to weeks for BPJPH documentation requirements. |
| Captive Aquaculture Expansion | Integrated poultry and fish farming in Malaysian processing zones insulates margins from feed grain volatility. |
| Functional Beverage Line Extension | Halal-certified probiotic and protein drinks penetrate Indonesia's underexploited secondary city convenience retail. |
| Cross-Border Reciprocity Advocacy | Harmonization negotiations between Southeast Asian and Gulf regulators would eliminate duplicate compliance expenditures. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, JAKIM and BPJPH certification officers, integrated protein processor operations heads, and aquaculture farm managers. Secondary validation drew from SFDA regulatory filings, ASEAN trade statistics, EFSA labeling guidance documents, and customs records for feed grain imports. Bottom-up volume estimates from facility-level throughput data were triangulated against top-down consumer expenditure projections across the analysis window.
Across the projection horizon, the analytical framework modeled product type segmentation by ritual compliance complexity, distribution channel dynamics by certification documentation requirements, and consumer type by religious observance versus quality-assurance motivation. CAGRs were derived from trend extrapolation of urban protein premiumization patterns and regulatory deadline impacts on processor compliance timelines. Forecast inputs incorporated BPJPH mandate enforcement schedules and blockchain adoption curves in Southeast Asian food service procurement.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and stable feed grain supply; material deviation in certification reciprocity negotiations or commodity price spikes would warrant model refresh. Specific risks include stalled harmonization between JAKIM and BPJPH, accelerated slaughter technician attrition, and EFSA labeling requirement extensions beyond current guidance. Recalibration cycles align with material shifts in regulatory enforcement intensity and technology adoption thresholds in protein traceability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Moringa Products Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
North America Hummus Market
Specialty Foods
Honey Spread Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Konjac Noodles Market