
 Tahini Market | 2026-2036
Tahini Market Size, Share, and Industry Trends Forecast 2026-2036
Tahini Market Analysis
Ingredient supply contracting is tilting margin pools toward in-house sesame sourcing and controlled-origin processing. Prince Tahina Ltd leverages long-term grower relationships in Ethiopia to secure consistent seed supply. Kevala International LLC differentiates through certified organic processing infrastructure in California. Halwani Bros Co. Ltd dominates Middle Eastern private-label manufacturing with integrated roasting and grinding operations.
Tahini is a sesame seed paste produced by hulling, roasting, and mechanically grinding sesame seeds into a smooth or coarse emulsion with typical fat content exceeding 50 percent and protein near 17 percent; it functions as a foundational ingredient in hummus, halva, dressings, and plant-based protein formulations. Conventional tahini occupies the volume core due to lower raw material costs and broader food-service penetration, while organic tahini captures expanding shelf space in health food stores and specialty retailers across North America and Western Europe. Glass jar packaging leads premium positioning despite higher logistics costs, whereas bulk packages serve industrial food processors seeking formulation flexibility.
FDA enforces aflatoxin and allergen labeling standards for sesame under the Food Allergy Safety, Treatment, Education, and Research Act, directly affecting import documentation and facility audits for tahini entering United States distribution. EFSA and national regulators across Germany, France, and the Netherlands apply maximum residue limits for pesticides on sesame seeds, shaping supplier qualification protocols for European importers. Stakeholders must monitor evolving seed-origin traceability mandates and certification requirements that will determine market access trajectories in key consuming regions.
Market Dynamics
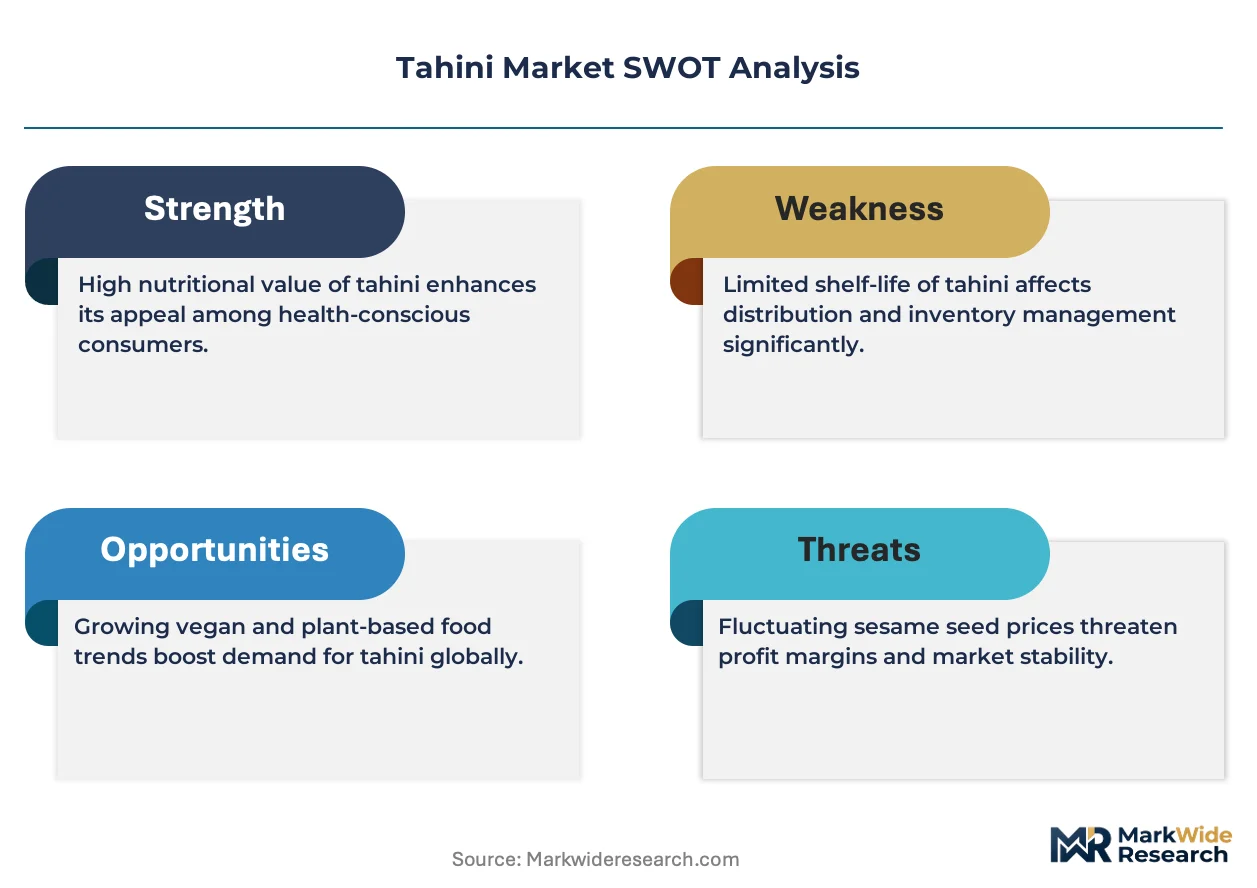
Ingredient traceability mandates and aflatoxin compliance thresholds are compressing supplier qualification timelines and tilting procurement toward vertically integrated processors with captive seed sourcing.
Growth Catalysts
- Plant-based protein formulation:Food manufacturers in Germany and the Netherlands are substituting tahini for dairy and egg emulsifiers in vegan dressings and spreads, expanding industrial offtake volumes.
- FDA sesame allergen labeling:The Food Allergy Safety, Treatment, Education, and Research Act mandates clear sesame disclosure, elevating certified tahini to preferred-supplier status in US retail and food-service channels.
- Ethiopian seed cluster development:Commercial farming expansion in Humera and Wollega zones is diversifying origin supply beyond traditional Sudanese and Indian sources.
Market Restraints
- Sesame price volatility:Raw seed costs fluctuate with Indian monsoon patterns and Sudanese export quotas, squeezing processor margins without forward-contract coverage.
- Single-origin concentration risk:Ethiopian supply disruptions from civil conflict or port congestion at Djibouti expose buyers to force-majeure exposure.
- Aflatoxin technical ceiling:Israel's Ministry of Health maintains 4 ppb thresholds for total aflatoxins, rejecting shipments that meet looser CODEX or US standards.
Strategic Opportunities
- Japanese functional food channel:METI-backed health claim approvals for sesame lignans position tahini as an ingredient in nutricosmetics and senior nutrition products.
- Carbon-accounting premium tier:EU Green Deal supply-chain disclosure requirements favor processors with verified low-emission roasting and water-recycling infrastructure.
- Direct-to-chef distribution:Specialty importers in California and New York are bypassing broadline distributors to supply Mediterranean and Middle Eastern restaurant groups with temperature-controlled bulk deliveries.
Industry Challenges
- Sensory evaluation talent scarcity:Few laboratories outside Tel Aviv and Ankara maintain trained panels for detecting oxidative rancidity and off-flavors in roasted sesame paste.
- Organic certification timeline:Three-year land-conversion periods and parallel organic handling audits delay new entrant market access by 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tahini Market |
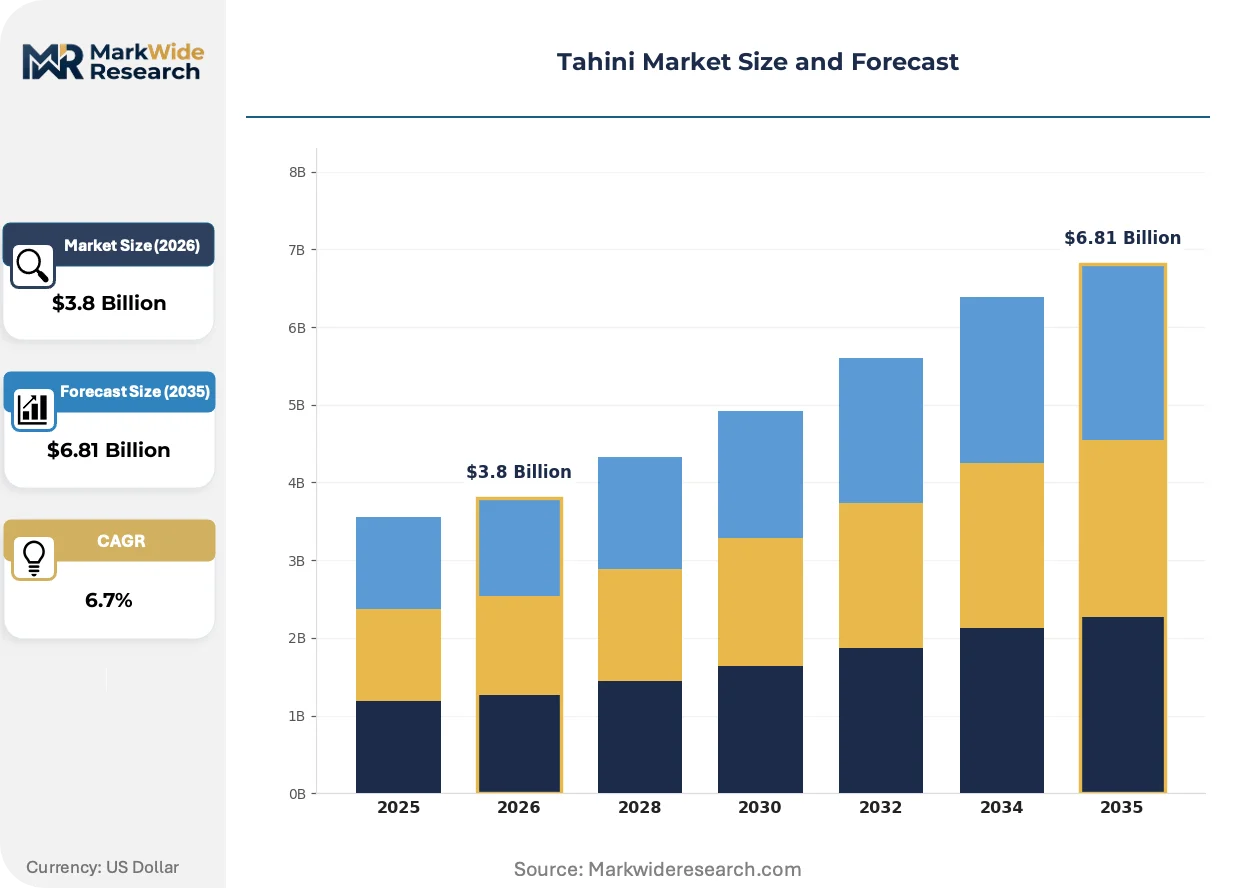
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tahini, Conventional Tahini, Light Tahini, Dark Tahini End User: Restaurants, Retail Consumers, Food Processing, Catering Services Packaging Type: Glass Jars, Plastic Containers, Tetra Packs, Bulk Packages Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Prince Tahina Ltd, Kevala International LLC, Halwani Bros Co. Ltd, Dipasa USA Inc., El Rashidi El Mizan, Haitoglou Bros SA, Sunshine International Foods Inc., Carwari International Pty Ltd, Al Wadi Al Akhdar SAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tahini Market Emerging Trajectories
Cold-press extraction methods and blockchain seed tracing are reconfiguring how quality premiums are captured and communicated across the tahini value chain.
High-pressure processing is hybridizing traditional stone-ground tahini with extended ambient shelf stability. California-based organic processors are adopting HPP units to eliminate thermal degradation of sesamin and sesamolin compounds. This technology is compressing the refrigeration-dependent distribution footprint for premium retail SKUs.
EFSA's updated maximum residue limits for pesticides on sesame seeds entered force in 2024, requiring importers to document pre-harvest intervals for 43 active substances. German and Dutch food manufacturers are now demanding batch-specific residue testing from Ethiopian and Sudanese suppliers. Small-scale processors without in-house laboratory partnerships face exclusion from EU retail supply chains.
Chef-driven specification is displacing commodity-grade purchasing in North American food service. Restaurant groups in Los Angeles and Chicago now contract directly with Israeli and Lebanese processors for single-origin, single-harvest tahini with specified roast profiles. This pattern concentrates volume with mid-size processors capable of custom grinding and small-batch labeling.
Tahini Market Segmentation
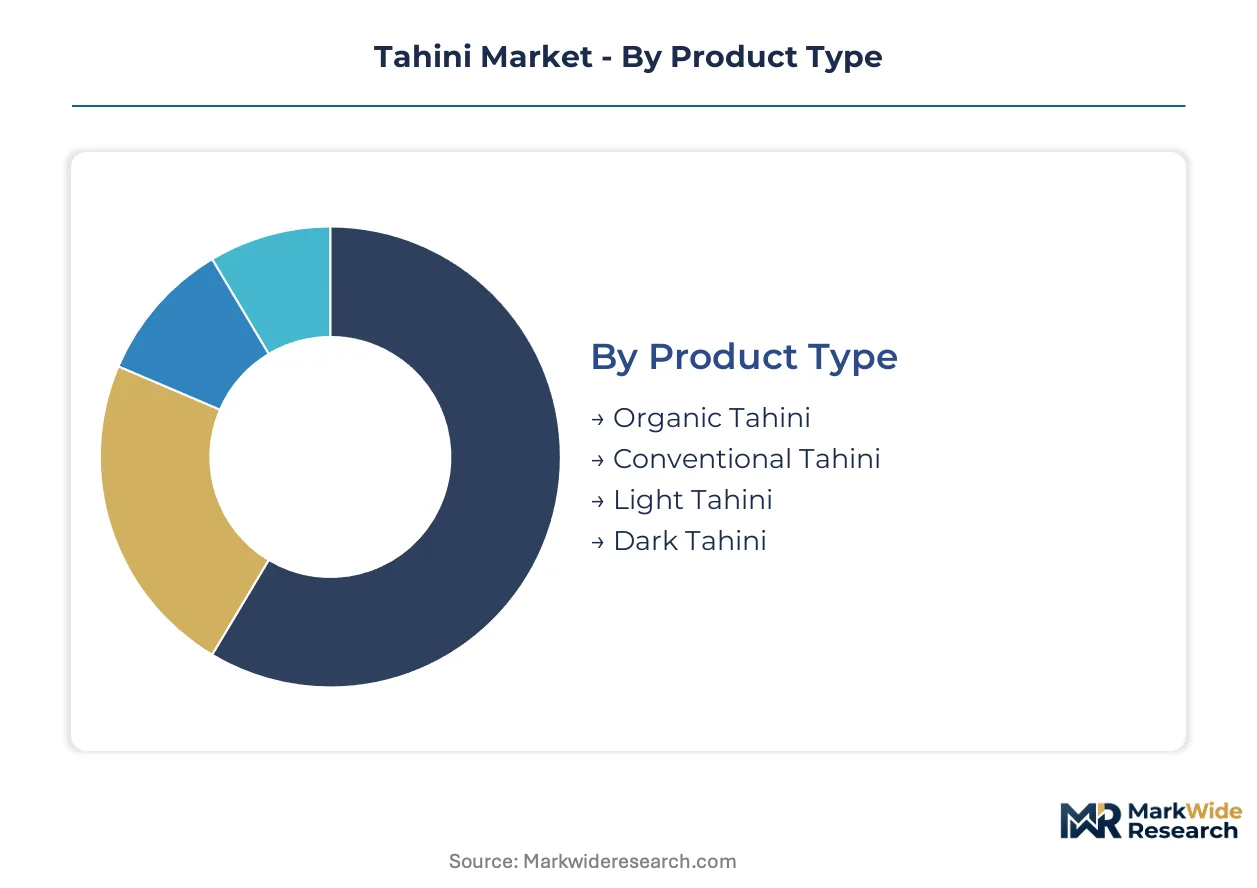
Tahini segmentation reveals divergent margin structures across product grades and channel economics. Cycle times vary dramatically: food-service bulk turns weekly while organic retail jars rotate monthly, creating distinct working capital requirements for processors.
Product Type:
Cycle times compress toward conventional grades for industrial buyers, while organic certification extends inventory holding periods through traceability documentation.
- Conventional Tahini:Standard hulled and roasted sesame paste with fat content exceeding 50 percent serves as the formulation backbone for hummus manufacturers and confectionery processors across Turkey and Israel. Demand concentrates in Turkish industrial zones where Izmir-based processors supply European private-label contracts under EFSA pesticide residue protocols.
- Organic Tahini:Certified organic processing requires three-year land conversion and parallel handling audits, limiting supplier pools to established operators like California-based processors with dedicated infrastructure. North American health food retailers in Los Angeles and New York metropolitan areas command premium shelf placement for cold-pressed variants with preserved sesamin compounds.
- Light Tahini:Hulled seed processing produces milder flavor profiles preferred by Mediterranean restaurant groups in Chicago and Dallas for tableside service and dressing applications.
- Dark Tahini:Unhulled seed retention increases fiber and mineral content, attracting functional food formulators in Japanese nutricosmetic channels backed by METI health claim approvals.
Conventional tahini dominates installed base. Organic tahini is where expansion concentrates.
End User:
Cost tier stratification separates commodity-volume food processing from premium chef-direct specifications.
- Food Processing:Industrial hummus and halva manufacturers in Germany and the Netherlands drive bulk offtake volumes, substituting tahini for dairy emulsifiers in plant-based formulations under EU Green Deal carbon accounting pressures.
- Restaurants:Chef-driven procurement in Los Angeles and Chicago now bypasses broadline distributors for single-origin, single-harvest contracts with specified roast profiles from Israeli and Lebanese processors.
- Retail Consumers:Supermarket and health store shoppers in California and Western Europe prioritize glass jar packaging and certified organic labeling despite logistics cost premiums.
- Catering Services:Institutional buyers in Middle Eastern markets favor bulk packaging with consistent viscosity specifications for high-volume event service.
Food processing commands volume share. Restaurants are gaining share fastest through direct-procurement restructuring.
Packaging Type:
Application requirements dictate material selection: thermal stability for ambient retail, chemical inertness for premium positioning, and cost minimization for industrial scale.
- Bulk Packages:Food manufacturers seeking formulation flexibility in German and Dutch plant-based protein operations source tanker and drum quantities with customized viscosity and roast specifications.
- Glass Jars:Premium retail positioning in North American specialty stores and Mediterranean markets maintains oxygen barrier performance despite higher freight costs and breakage rates.
- Plastic Containers:Mid-tier supermarket distribution favors polyethylene terephthalate and polypropylene formats for reduced shipping weight and drop-shock resistance.
- Tetra Packs:Aseptic carton formats extend ambient shelf stability for export markets with limited cold chain infrastructure.
Bulk packages dominate industrial throughput. Glass jars anchor premium tier expansion.
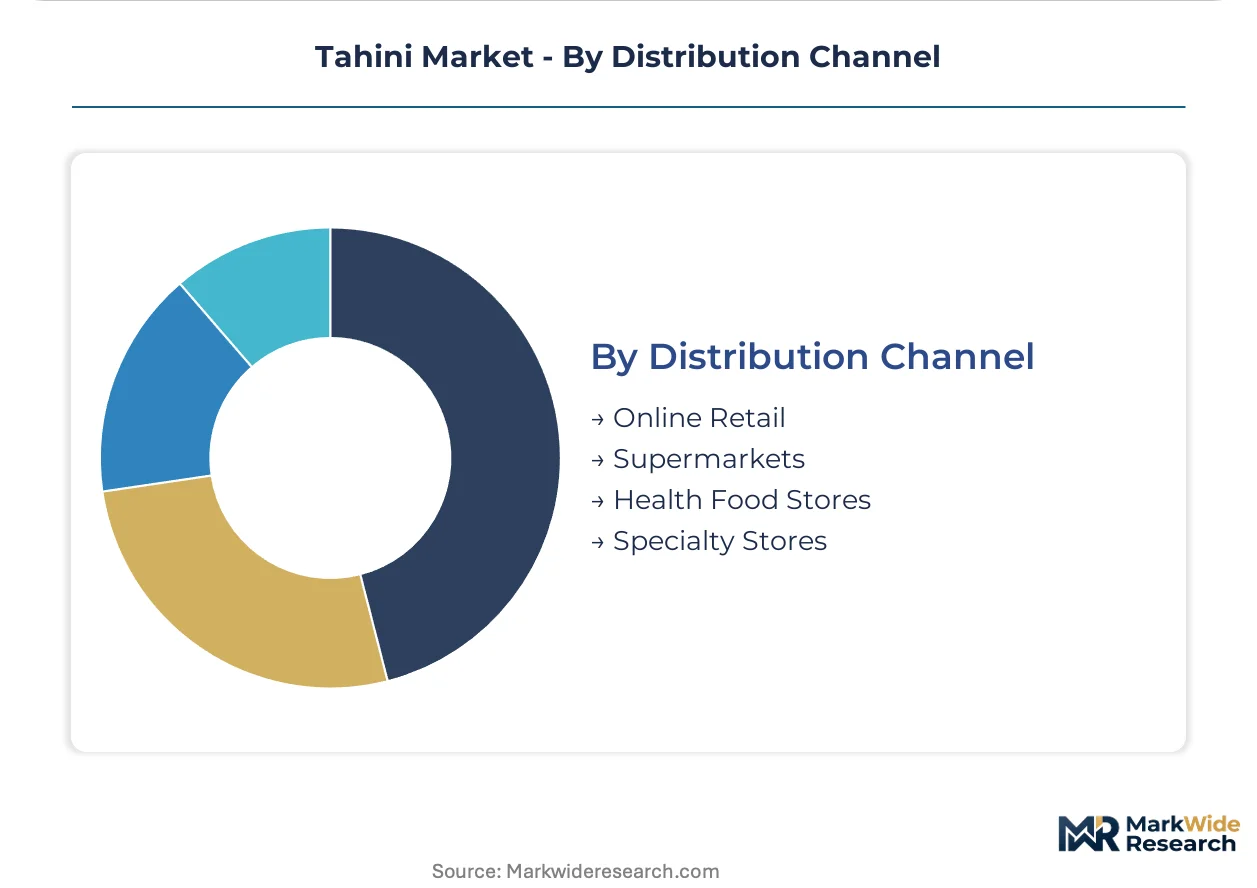
Distribution Channel:
Customer type fragmentation splits between convenience-seeking digital buyers and specification-driven physical channel shoppers.
- Supermarkets:Mass retail chains in France, Germany, and the Netherlands consolidate volume through centralized procurement of conventional grades with standardized labeling under FASTER Act compliance requirements.
- Online Retail:Direct-to-consumer platforms enable California and New York-based specialty importers to bypass distributor markups for temperature-controlled bulk deliveries to restaurant groups and home chefs.
- Health Food Stores:Independent retailers in Los Angeles and Chicago metropolitan areas curate certified organic and cold-pressed SKUs with blockchain traceability documentation.
- Specialty Stores:Mediterranean and Middle Eastern ethnic grocers in Detroit and Dearborn maintain destination status for imported Lebanese and Israeli single-origin varieties.
Supermarkets maintain volume concentration. Online retail is climbing the fastest through disintermediation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across demand centers. United States buyers absorb organic premiums readily, while Turkish industrial processors squeeze margins on conventional bulk contracts. German and Dutch food manufacturers balance carbon-accounting compliance against formulation costs.
United States
Specialty importers in California and New York metropolitan areas command premium positioning for certified organic and cold-pressed variants. FDA enforcement of the FASTER Act's sesame allergen labeling elevates certified tahini to preferred-supplier status in retail and food-service channels. Temperature-controlled direct-to-chef distribution is bypassing broadline distributors for Mediterranean and Middle Eastern restaurant groups.
Germany
Industrial hummus and halva manufacturers drive bulk offtake volumes, substituting tahini for dairy emulsifiers in plant-based formulations. EFSA's 2024 updated maximum residue limits for pesticides on sesame seeds requires importers to document pre-harvest intervals for 43 active substances. Hamburg and Rotterdam serve as consolidation points for Ethiopian and Sudanese seed shipments entering EU distribution.
Turkey
Izmir and Adana function as processing and export hubs for European and North American buyers seeking formulation flexibility in tanker and drum quantities. Turkish industrial zones supply European private-label contracts under EFSA pesticide residue protocols. Conventional grade dominance reflects food-service penetration and lower raw material costs.
Israel
Single-origin, single-harvest specifications with custom roast profiles attract chef-driven procurement from Los Angeles and Chicago restaurant groups. The Ministry of Health maintains 4 ppb thresholds for total aflatoxins, rejecting shipments that meet looser CODEX or US standards. Tel Aviv maintains trained sensory panels for detecting oxidative rancidity in roasted sesame paste.
Japan
METI-backed health claim approvals for sesame lignans position tahini as an ingredient in nutricosmetics and senior nutrition products. Dark tahini variants with unhulled seed retention attract functional food formulators seeking elevated fiber and mineral content. Import channels favor aseptic carton formats for ambient shelf stability.
Tahini Market Vendor Landscape
Capability concentration sits with mid-size processors offering custom grinding and small-batch labeling; scale advantage sits with integrated operators controlling captive seed sourcing. The vendor base stratifies across three archetypes: vertically integrated processors with Ethiopian grower relationships, certified organic specialists with California infrastructure, and Middle Eastern private-label manufacturers with integrated roasting operations. Dominant competitive moves include backward integration into sesame cultivation and geographic expansion through direct-to-chef distribution networks.
Within the integrated processor tier, Prince Tahina Ltd and Halwani Bros Co. Ltd exemplify archetypes combining seed sourcing control with manufacturing scale. Kevala International LLC occupies a position representing the certified organic specialist vector with dedicated infrastructure. These three entities anchor competitive positioning across conventional bulk, organic premium, and private-label manufacturing segments respectively.
| Leading Market Players |
|---|
| Prince Tahina Ltd |
| Kevala International LLC |
| Halwani Bros Co. Ltd |
| Dipasa USA Inc. |
| El Rashidi El Mizan |
| Haitoglou Bros SA |
| Sunshine International Foods Inc. |
| Carwari International Pty Ltd |
| Al Wadi Al Akhdar SAL |
| Others |
Supply Flow & Price Mechanics
Underutilized roasting capacity in Izmir and Adana is compressing spot prices for conventional bulk tahini while simultaneously pressuring processors to secure forward seed contracts. This utilization gap drives margin-seeking behavior toward premium organic grades and direct-to-chef channels where pricing power remains intact.
Pricing Analysis
After-sales service contracts for temperature-controlled bulk delivery to restaurant groups now drive lifetime value capture. Three-tier pricing structure across premium organic, certified conventional, and commodity bulk levels separates processors by certification investment and origin traceability. Price differentiation hinges on organic certification status and EFSA residue documentation. Cost compression in commodity bulk is intensifying because Ethiopian seed supply volatility forces processors to absorb margin hits or lose European private-label contracts. Food manufacturers in Germany and the Netherlands exhibit highest price sensitivity due to carbon-accounting compliance costs, while Los Angeles and New York chef-direct buyers absorb organic premiums readily.
Supply Chain Analysis
Contract-manufacturing concentration sits with Izmir-based processors supplying European private-label contracts and California-certified organic facilities serving North American health food channels. Geographic supply concentration centers on Ethiopia, Sudan, and India as primary seed origins. Raw material dependencies rest on sesame seed availability, hulling capacity, and aflatoxin testing infrastructure. Single-source vulnerability from Ethiopian civil conflict and Djibouti port congestion exposes buyers to force-majeure disruption. Distribution runs through Rotterdam and Hamburg consolidation points for EU industrial buyers, with direct temperature-controlled shipments bypassing broadline distributors for North American restaurant groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in plant-based protein formulation is accelerating tahini incorporation as dairy and egg emulsifier substitutes. Penetration into Japanese nutricosmetic channels backed by METI health claim approvals extends addressable demand beyond traditional culinary applications.
For Market Incumbents: Build captive seed sourcing moats through long-term grower relationships in Ethiopia's Humera and Wollega zones. Secure backward integration into hulling operations to control aflatoxin compliance timelines. Add certified organic handling capacity in California to capture health food retailer shelf space expansion. Defend against emerging organic specialists by accelerating three-year land conversion timelines for new origin supply. For New Entrants and Emerging Players: Establish a beachhead in direct-to-chef distribution for Mediterranean and Middle Eastern restaurant groups in Chicago and Dallas. Target the Japanese functional food channel where METI-backed sesame lignan health claims create specification-driven demand with limited incumbent presence. Penetrate through single-origin, single-harvest positioning with custom roast profiles that bypass commodity bulk competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified organic processing infrastructure due to three-year land conversion requirements and parallel handling audit investments. Five-to-ten-year viability favors processors with demonstrated EFSA compliance documentation and established Ethiopian grower networks. Acquisition target archetype: mid-size processors with custom grinding capability and small-batch labeling infrastructure. Signal to watch: FDA enforcement intensity on FASTER Act allergen labeling as indicator of certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethiopian Seed Cultivation | Long-term grower contracts in Humera and Wollega zones secure supply against Sudanese export quota volatility. |
| Certified Organic Infrastructure Investment | California-based dedicated facilities capture premium shelf placement in Los Angeles and New York health food retailers. |
| Direct-to-Chef Distribution Network | Temperature-controlled bulk deliveries bypass broadline distributors for Mediterranean restaurant groups in Chicago and Dallas. |
| Japanese Nutricosmetic Channel Entry | METI-backed sesame lignan health claims position dark tahini variants in functional food formulations. |
| Blockchain Seed Traceability Implementation | Batch-specific documentation satisfies EFSA pesticide residue protocols for German and Dutch industrial buyers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted to construct this analysis. Primary interviews engaged tahini processors, sesame seed procurement managers at food manufacturers, health food retail category buyers, and restaurant group executive chefs. Secondary validation drew from FDA enforcement documentation, EFSA pesticide residue limit updates, Ethiopian agricultural export statistics, and Israeli Ministry of Health aflatoxin compliance records. Bottom-up volume modeling across product grades and end-use segments was triangulated against top-down trade flow analysis.
Calibration against historical price volatility in sesame seed markets and documented processor margin structures anchored the analytical framework. Segmentation dimensions modeled include product type, end-user category, packaging format, and distribution channel across the analysis window. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points. Key forecast inputs encompassed Ethiopian farming expansion rates and FDA FASTER Act enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in freight rates, currency volatility in seed-origin countries, or energy costs for roasting operations would shift the trajectory. Forecasts reflect documented assumptions on certification timeline completion and port infrastructure capacity at Djibouti. Quarterly review of Ethiopian civil conflict indicators, EFSA residue limit updates, and FDA facility audit schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Curculin Market
Specialty Foods
Kosher Food Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
United States Tofu Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Miso Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Postbiotic Pet Food Market