
 Smartwatch Display Panel Market | 2026-2036
Smartwatch Display Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Smartwatch Display Panel Market Analytics
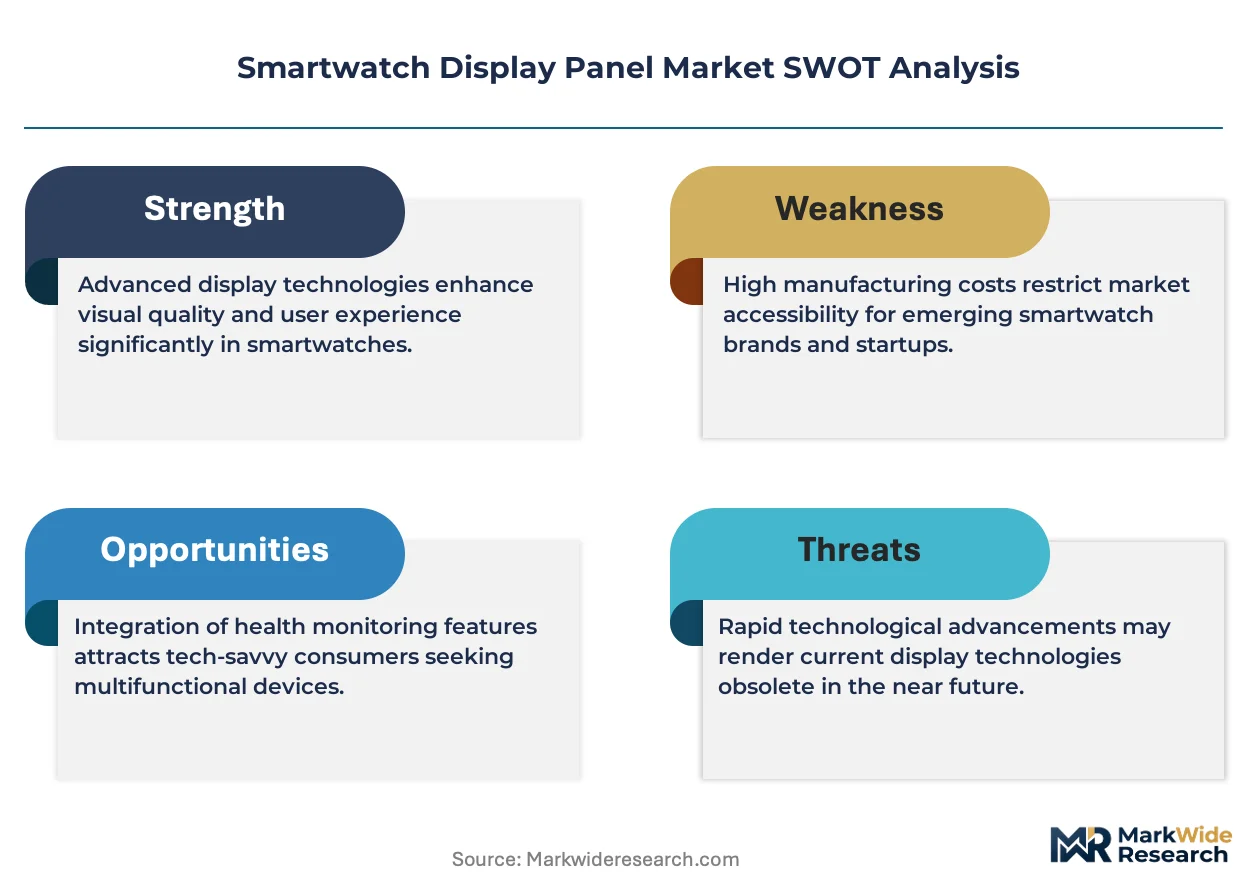
The gap between premium AMOLED flexible panels and commodity LCD fixed displays is recalibrating procurement strategies across wearable brands. Samsung Electronics leverages captive OLED capacity to dominate high-end smartwatch supply, while BOE Technology Group competes aggressively on cost-engineered rigid OLED alternatives for mid-tier devices. LG Display anchors its position through specialized LTPO backplane technology that sustains power efficiency in always-on configurations.
Smartwatch display panels are compact emissive or transmissive visual interfaces, typically measuring 1.5 to 2.0 inches diagonally with pixel densities exceeding 300 PPI, manufactured through thin-film transistor lithography on glass or polyimide substrates to enable touch interaction and persistent biometric readout. OLED technology leads in value contribution due to superior contrast ratios and form-factor flexibility, while Mini-LED remains nascent but occupies the premium endurance segment where sunlight visibility commands design priority. Flexible display technology is displacing rigid alternatives fastest among fashion-forward consumer applications where wraparound and curved geometries differentiate brand aesthetics.
EPA energy consumption guidelines and FCC electromagnetic emission standards constrain display driver architecture and wireless integration in US-bound devices, while REACH substance restrictions and EU Ecodesign frameworks limit heavy metal content and mandate recyclability disclosures for European market access. SAMR certification requirements and GB standards in China add parallel compliance layers for brightness uniformity and blue-light emission thresholds. Stakeholders must monitor how diverging regional sustainability mandates reshape substrate material roadmaps and foundry qualification timelines.
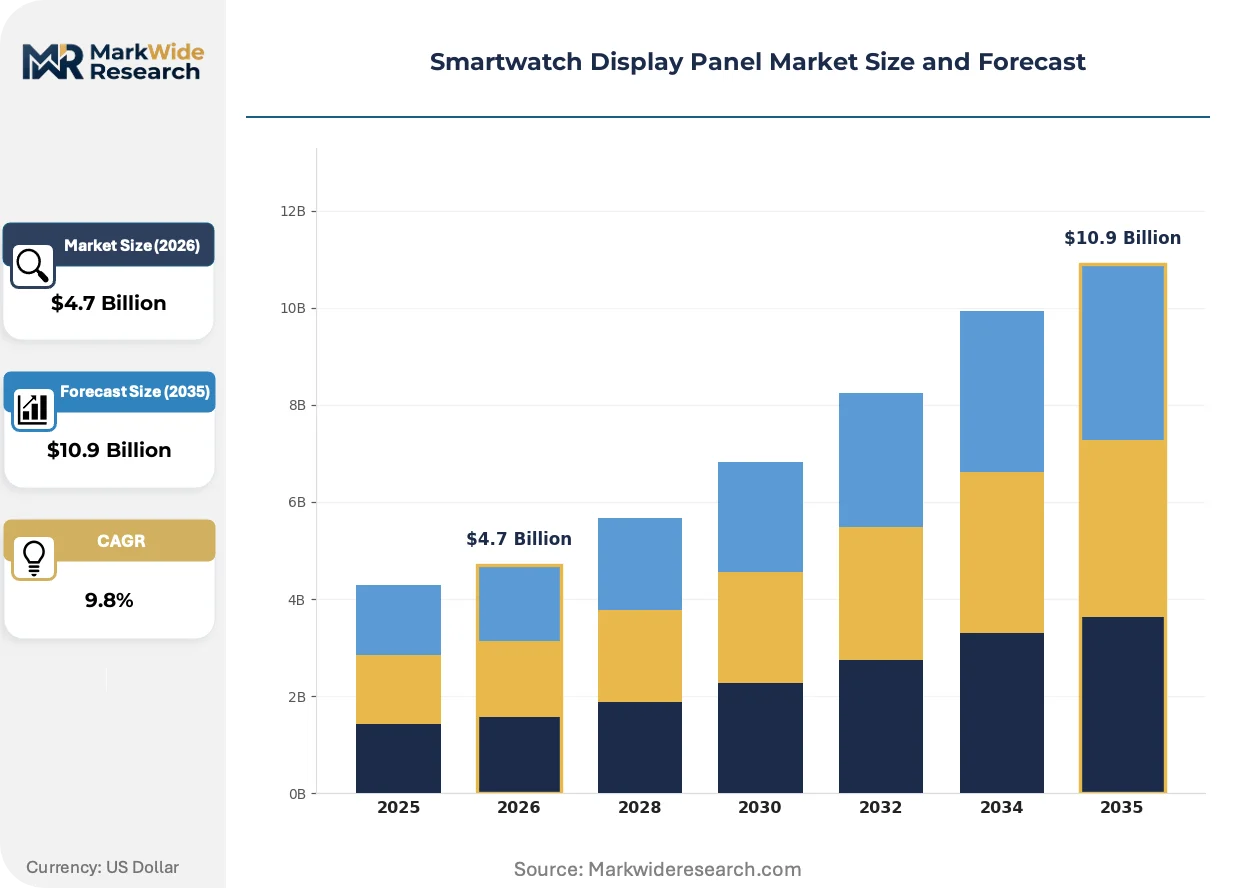
Market Dynamics
Flexible AMOLED manufacturing is concentrating supply among Korean and Chinese panel makers, compressing margins for rigid OLED alternatives while EU chemical restrictions force substrate material substitutions across the value chain.
Growth Catalysts
- Health-monitoring integration:Biometric-capable displays are pulling demand from fitness trackers into full-featured smartwatches, expanding the addressable user base for high-PPI panels.
- REACH substance restrictions:European chemical compliance is accelerating development of cadmium-free quantum dot emitters and low-cobalt driver ICs in display stack engineering.
- China domestic supply chains:Visionox Technology and BOE Technology Group have built captive polyimide substrate capacity, reducing import dependency for flexible panel production.
Market Restraints
- Driver IC cost volatility:28nm specialty foundry capacity constraints in Taiwan and South Korea are inflating display driver semiconductor input costs for panel assemblers.
- Technical yield limitations:Laser lift-off processing for flexible substrates remains below 75% yield at Gen 6 scale, capping output expansion for curved form factors.
- Substitution pressure:Reflective LCD and transflective hybrid panels are capturing price-sensitive outdoor sports segments where sunlight readability trumps color saturation.
Strategic Opportunities
- Medical-grade certification pathways:FDA breakthrough device designation for continuous glucose monitoring displays opens premium reimbursement channels in US healthcare systems.
- India manufacturing incentives:PLI scheme subsidies for electronics component production are attracting display module assembly investments targeting domestic wearable brands.
- LTPO backplane convergence:Integration of low-temperature polycrystalline oxide transistors with variable refresh logic is enabling week-long battery life in always-on configurations.
Industry Challenges
- MicroLED transfer yield gaps:Mass transfer equipment for sub-50 micron chips lacks the throughput and placement accuracy needed for smartwatch-scale commercialization.
- SAMR certification timelines:China's brightness uniformity and blue-light emission testing protocols extend product launch cycles by four to six months for foreign panel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartwatch Display Panel Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.9 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, AMOLED, Mini-LED Technology: Touchscreen, Flexible Display, Color E-Ink, Display Driver IC End User: Sports Enthusiasts, Health-Conscious Users, Tech Savvy Consumers, Fashion-Forward Consumers Application: Fitness Tracking, Navigation, Communication, Entertainment |
| Companies Covered | Samsung Electronics, LG Display, BOE Technology Group, Japan Display Inc., Sharp Corporation, AU Optronics, Visionox Technology, TCL Technology, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartwatch Display Panel Market Evolving Landscape
Panel architecture is bifurcating between power-frugal always-on designs and immersive full-bleed displays, with manufacturing process innovation determining which suppliers capture margin in each tier.
LTPO backplane technology is overtaking LTPS alternatives in premium smartwatch segments by enabling dynamic refresh rate scaling from 1Hz to 120Hz. Apple Watch and Samsung Galaxy Watch product lines have standardized on hybrid oxide-polysilicon transistors since 2021, compressing demand for conventional low-temperature polysilicon panels in devices above $300 retail price points. This transition is forcing rigid OLED specialists to defend position through cost-engineered alternatives in mid-tier Android wearable portfolios.
EU Ecodesign requirements for energy-related products are mandating minimum display efficiency thresholds and recyclability disclosures for wearable devices entering European markets. These frameworks are compelling panel makers to redesign driver IC power architectures and substrate material selections to meet standby power caps. Flexible AMOLED suppliers with established halogen-free polyimide supply chains are capturing preferential qualification status with brands prioritizing EU market access.
Direct-to-consumer wearable brands are bypassing traditional distributor networks to negotiate panel supply contracts directly with BOE Technology Group and Visionox Technology. This channel disintermediation is compressing working capital cycles for emerging brands in China and India while exposing established distributors to volume erosion in entry-level smartwatch categories. The shift is most pronounced among fitness-focused brands targeting Southeast Asian e-commerce platforms where component cost transparency drives procurement centralization.
Smartwatch Display Panel Market Segmentation
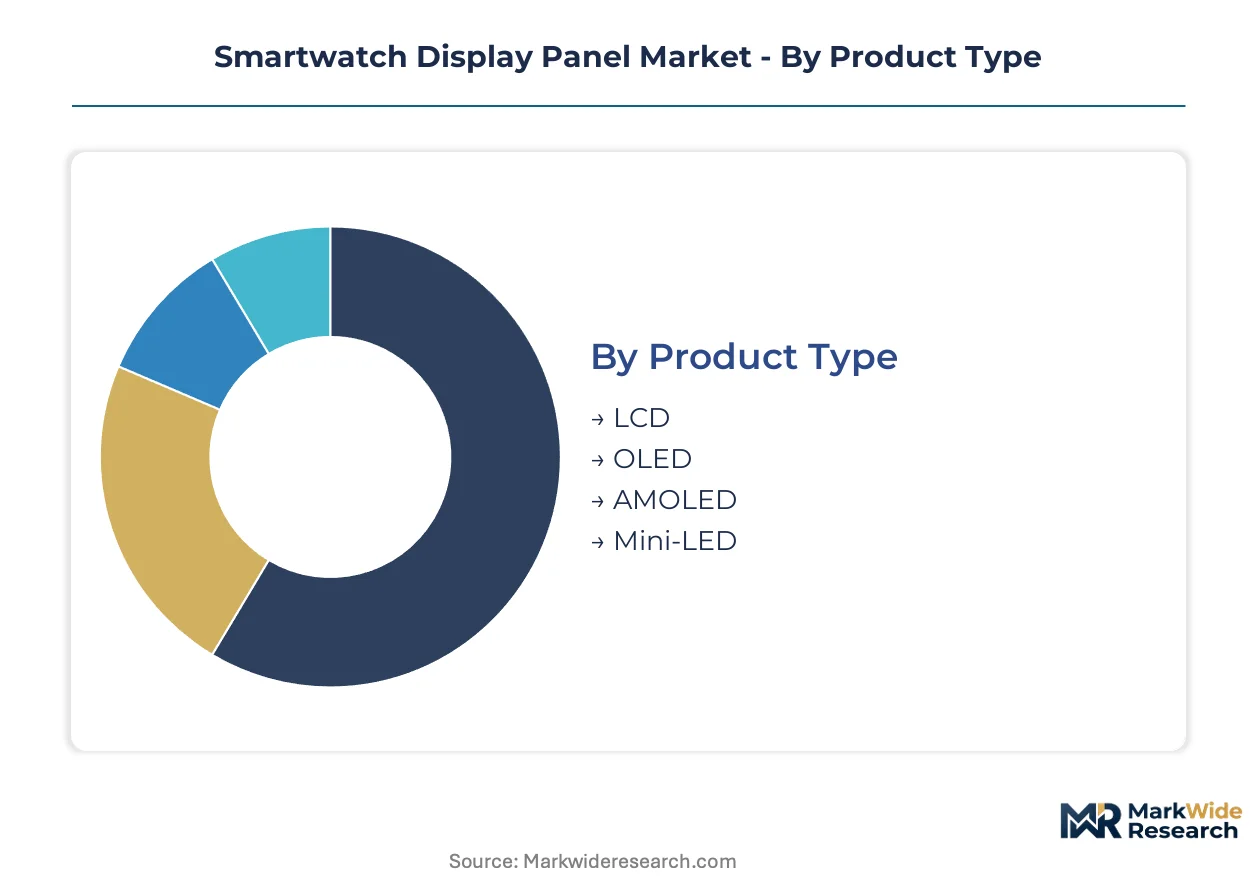
Smartwatch display panel procurement strategies diverge sharply across technology tiers and user profiles. Upgrade cycles compress to 18-24 months for health-monitoring features while fashion-driven replacements accelerate to 12-18 months for form-factor novelty.
Product Type:
Replacement velocity varies dramatically by panel technology, with premium emissive displays commanding shorter upgrade windows than transmissive alternatives due to burn-in degradation and feature evolution.
- AMOLED:Active-matrix organic LED stacks deliver sub-millisecond response times and true black states through individual pixel deactivation. Health-conscious users in China and South Korea drive replacement demand for SpO2 and ECG-capable biometric panels. LTPO backplane integration extends battery endurance, tightening upgrade cycles for always-on health monitoring.
- OLED:Conventional organic emissive layers without active-matrix addressing occupy mid-tier price bands where rigid glass substrates dominate. Sports enthusiasts in North America and Europe prioritize sunlight visibility over color depth, constraining replacement frequency to 30-36 month intervals.
- LCD:Transmissive liquid crystal panels with LED backlighting serve entry-level price tiers through mature manufacturing scale. Tech-savvy consumers in India and Southeast Asia accept thicker form factors for cost-engineered navigation and communication functions.
- Mini-LED:Thousands of local dimming zones behind LCD matrices enable HDR-grade contrast without organic degradation. Outdoor sports segments in Australia and alpine European markets pay premiums for 1000+ nit sustained brightness in endurance racing applications.
AMOLED sits at the top of the volume ranking, with Mini-LED climbing the fastest among premium endurance segments.
Technology:
Manufacturing process maturity determines which technology layers capture margin versus commoditize, with substrate flexibility and driver integration emerging as the primary value-differentiation axes.
- Flexible Display:Polyimide substrate laser lift-off enables curved and wraparound geometries unattainable with glass. Fashion-forward consumers in Milan, Tokyo, and Shanghai replace devices seasonally as wearable aesthetics converge with jewelry positioning.
- Touchscreen:Capacitive multi-layer stacks with force-sensing integration remain the universal interface standard. Every major smartwatch platform embeds haptic feedback and gesture recognition, making this layer non-discretionary across all price tiers.
- Display Driver IC:28nm specialty foundry silicon controls pixel addressing and power management. Taiwan and South Korean fab capacity constraints inflate input costs, compressing assembler margins regardless of end-market application.
- Color E-Ink:Reflective bistable displays consume power only during image updates. Niche adoption concentrates in month-long battery life segments where always-on visibility trumps animation and video playback.
Touchscreen layers generate the highest unit volume, while flexible display technology expands most quickly through fashion-forward consumer adoption.
End User:
User psychographics segment replacement behavior more precisely than demographics, with health anxiety and social signaling driving divergent upgrade priorities.
- Health-Conscious Users:Continuous glucose monitoring and arrhythmia detection requirements pull demand from dedicated medical devices into consumer wearables. FDA breakthrough device designations for glucose-integrated panels accelerate replacement cycles as diagnostic accuracy improves generationally.
- Fashion-Forward Consumers:Aesthetic differentiation through case materials and display curvature drives 12-18 month replacement velocity. European luxury houses and Asian fast-fashion brands compete for share of wrist real estate through seasonal collection drops.
- Sports Enthusiasts:GPS accuracy, barometric altimetry, and training load metrics dominate purchase criteria over display specifications. Garmin and Polar loyalists replace devices at 24-36 month intervals aligned with battery degradation rather than feature advancement.
- Tech Savvy Consumers:Early adoption of novel interaction modalities—gesture control, ultra-wideband proximity sensing—drives upgrade behavior. This segment tolerates first-generation manufacturing defects in exchange for platform ecosystem integration.
Health-conscious users represent the largest addressable base, with fashion-forward consumers gaining share fastest through luxury brand portfolio expansion.
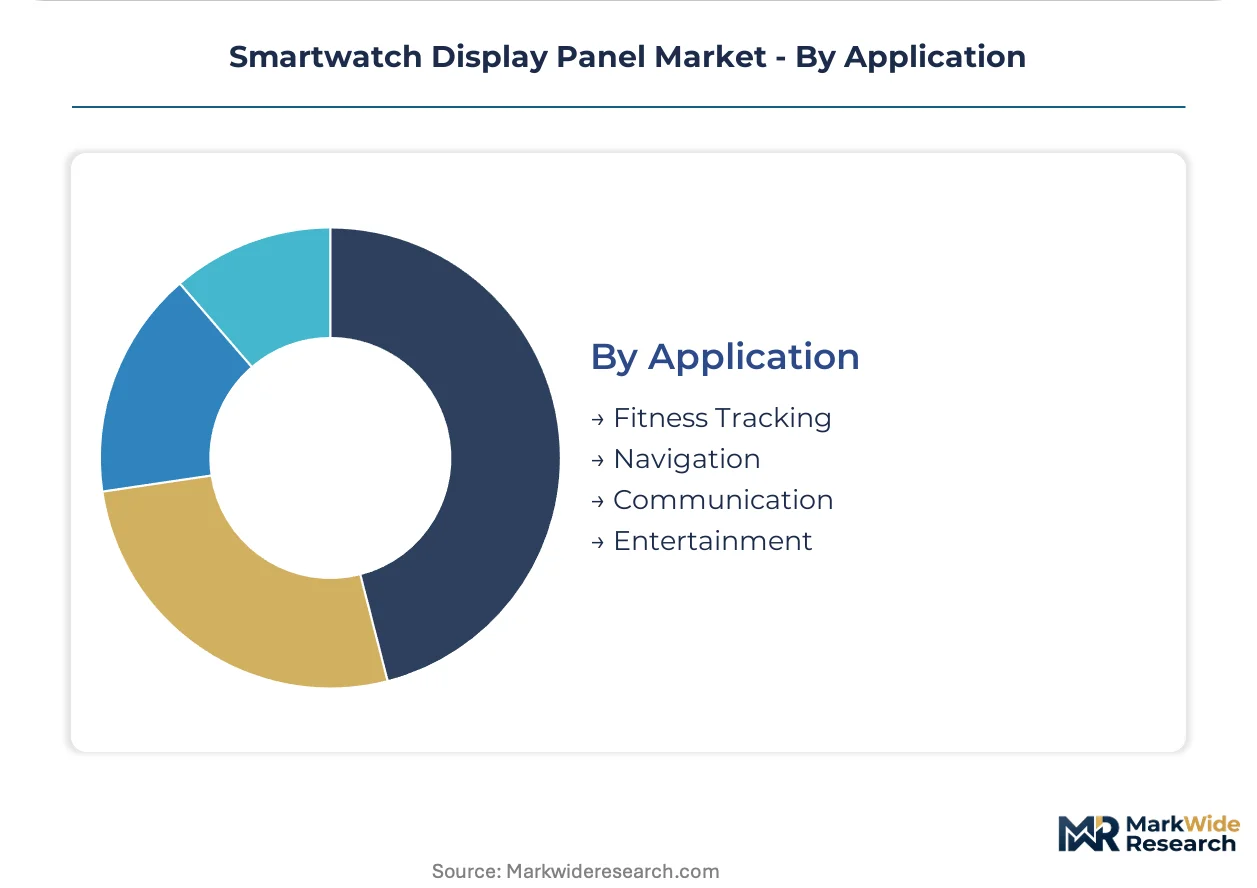
Application:
Functional use cases determine display specification requirements, with biometric readout fidelity and outdoor visibility emerging as the primary technical trade-offs.
- Fitness Tracking:Heart rate variability, blood oxygen saturation, and recovery metrics demand high-PPI panels with photoplethysmography sensor integration. Gym and studio environments prioritize touch responsiveness during high-intensity interval training.
- Communication:Notification triage and voice assistant interaction require always-on display states with sub-1Hz refresh capability. LTPO backplane technology enables week-long battery life despite persistent screen activation.
- Navigation:Turn-by-turn directions and breadcrumb tracking in remote environments demand 600+ nit minimum brightness. Reflective LCD and transflective hybrid panels capture share in ultramarathon and mountaineering segments.
- Entertainment:Video streaming and gaming applications drive demand for 120Hz variable refresh and HDR color gamut coverage. Premium AMOLED panels with diamond pixel arrangements minimize subpixel visibility at close viewing distances.
Fitness tracking anchors current volume leadership, while communication applications expand most quickly through voice-first interface adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing scale for flexible AMOLED substrates while South Korea retains process leadership in LTPO backplane integration, creating divergent supply chain strategies across wearable brands.
China
Domestic brands Xiaomi and Huawei drive volume demand for biometric-capable panels with SpO2 and ECG integration. SAMR certification protocols mandate brightness uniformity testing that extends foreign supplier qualification timelines. BOE Technology Group and Visionox Technology anchor production clusters in Beijing and Hefei, where captive polyimide substrate capacity reduces import dependency for curved form factors.
South Korea
Samsung Electronics leverages captive OLED fabrication for Galaxy Watch supply chains while consumer appetite for always-on health monitoring compresses replacement cycles. The Ministry of Trade, Industry and Energy (METI) coordinates display technology roadmaps with national semiconductor initiatives. Seoul-Suwong industrial corridor concentrates laser lift-off processing equipment and 28nm driver IC foundry partnerships.
United States
FDA breakthrough device designations for continuous glucose monitoring displays open reimbursement pathways in employer-sponsored wellness programs. EPA energy consumption guidelines constrain display driver architectures for devices sold through domestic retail channels. Austin and Phoenix metro areas host module assembly operations serving North American wearable brands with regional fulfillment requirements.
Japan
Precision equipment suppliers in Nagoya and Osaka deliver mass transfer systems for MicroLED development programs targeting 2026 commercialization. METI funding for next-generation display manufacturing supports domestic substrate material research. Sharp Corporation maintains fabrication presence in Sakai for specialized LTPO backplane production serving premium tier device makers.
Germany
EU Ecodesign requirements for energy-related products mandate standby power caps that reshape driver IC selection for European market entry. ECHA REACH substance restrictions accelerate cadmium-free quantum dot emitter development across supply chains. Dresden and Munich clusters concentrate display research partnerships between Fraunhofer institutes and automotive-tier wearable device integrators.
Smartwatch Display Panel Market Competitive Landscape
Top-tier vendors anchor premium AMOLED supply through captive fabrication capacity, while mid-tier specialists compete on cost-engineered rigid alternatives for price-sensitive Android portfolios. The vendor base stratifies across three functional layers: integrated device manufacturers with internal display divisions, independent panel fabricators with foundry relationships, and module assemblers sourcing substrates from merchant suppliers. Two dominant competitive moves define current positioning: backward integration into polyimide substrate production to secure flexible panel yield, and strategic partnerships with 28nm specialty foundries to lock driver IC allocation amid Taiwan and South Korean capacity constraints.
Within the integrated device manufacturer tier, Samsung Electronics and Apple Inc. exemplify captive supply strategies that internalize premium panel procurement. Among independent fabricators, LG Display occupies a position representing specialized backplane technology differentiation, while BOE Technology Group anchors the cost-competitive rigid OLED segment serving mid-tier wearable brands. Japan Display Inc. sits within the reflective display specialization tier, serving outdoor sports applications where sunlight visibility commands design priority over color saturation.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| BOE Technology Group |
| Japan Display Inc. |
| Sharp Corporation |
| AU Optronics |
| Visionox Technology |
| TCL Technology |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
LTPO-backplane premium tiers and rigid-OLED commodity segments diverge sharply in procurement economics, with the former commanding captive foundry allocation in South Korea while the latter feeds from open-market substrate auctions in China. This bifurcation concentrates margin capture among integrated device manufacturers and compresses assembler returns in mid-tier Android wearable portfolios.
Pricing Analysis
Capacity additions in China are reshaping price floors for rigid AMOLED panels as BOE Technology Group and Visionox Technology expand Gen 6 polyimide substrate output. Three-tier pricing structure across premium, standard, and economy levels separates LTPO-integrated flexible displays from conventional LTPS alternatives and entry-level LCD modules. Cost compression in rigid OLED tiers is intensifying because 28nm driver IC foundry constraints in Taiwan inflate semiconductor input costs. Fitness-tracker brands in Southeast Asia exhibit highest price sensitivity, while medical-grade wearable integrators in the United States tolerate substantial premiums for FDA-cleared biometric panels.
Supply Chain Analysis
Specialized process engineers in Beijing, Hefei, and the Seoul-Suwon corridor face acute competition from semiconductor fabs for lithography talent. Manufacturing gravity centers on China, South Korea, and Japan, with polyimide substrate production, laser lift-off equipment, and precision mass-transfer systems anchoring respective national clusters. Panel assembly draws from indium tin oxide sputtering targets, halogen-free polyimide films, and 28nm CMOS driver wafers as critical inputs. Single-source vulnerability concentrates in Taiwan's specialty foundry capacity for display driver ICs. Distribution runs through direct OEM contracts and module assembler relationships, bypassing traditional component distributors for emerging wearable brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand, with EU Ecodesign standby power mandates and FDA breakthrough device pathways for glucose-integrated displays forcing procurement upgrades across wearable portfolios.
For Market Incumbents: Extend captive substrate capacity through backward integration into polyimide film production, securing yield control for curved form factors amid REACH substance restrictions. Defend LTPO backplane differentiation against emerging oxide-polysilicon alternatives by deepening foundry partnerships in South Korea. Channel control through direct-to-consumer brand relationships compresses working capital exposure for emerging competitors. For New Entrants and Emerging Players: EU Ecodesign requirements in Germany and France open a window for halogen-free polyimide substrate specialists to capture preferential qualification status with luxury wearable brands. Target India's PLI-subsidized module assembly incentives as the most penetrable geography for cost-engineered rigid OLED supply. A go-to-market angle anchored to SAMR pre-certification services for foreign panel makers compresses launch timelines for China-bound devices. For Investors and Strategic Acquirers: Consolidation pressure builds where laser lift-off yield gaps and driver IC allocation constraints strand mid-tier panel assemblers without captive foundry relationships. Long-term viability favors vertically integrated specialists with in-house polyimide substrate production and established LTPO backplane partnerships. Acquisition target archetype: rigid OLED assemblers in China with certified SAMR testing capabilities and underutilized Gen 6 capacity. The signal to watch is 28nm foundry utilization rates in Taiwan as inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Substrate Production | Captive supply of halogen-free films secures EU Ecodesign qualification with German wearable brands. |
| LTPO Backplane Foundry Partnership | Locked allocation at South Korean 28nm specialty fabs defends power-efficiency positioning in always-on segments. |
| Direct-to-Consumer Brand Supply Contracts | Bypassing distributors compresses working capital cycles for Xiaomi and Huawei ecosystem entrants. |
| SAMR Pre-Certification Service Offering | Accelerated brightness uniformity testing captures foreign panel maker demand for China market entry. |
| Medical-Grade FDA Submission Pathway | Breakthrough device designation for glucose-integrated displays unlocks employer wellness program reimbursement channels. |
Research Methodology
Multiple input streams — panel maker procurement executives, wearable brand supply chain directors, 28nm foundry account managers, and regulatory affairs specialists at SAMR and FDA — were reconciled against secondary validation from SEC component supplier filings, customs trade records for display driver ICs, and EU Ecodesign compliance databases. Bottom-up assembly cost modeling and top-down wearable shipment projections were cross-referenced to anchor volume estimates.
Historical capacity expansion patterns and panel maker capex disclosures were cross-referenced against analyst panel inputs to construct the projection framework. Segmentation dimensions modeled include display technology tier, substrate flexibility class, end-user psychographic profile, and regional regulatory compliance cluster. CAGRs were derived from slope-consistent growth trajectory analysis rather than endpoint anchoring. Key forecast inputs span laser lift-off yield improvement curves and LTPO backplane adoption rates in premium wearable portfolios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Taiwan foundry capacity disruption or accelerated MicroLED mass-transfer breakthroughs. Assumptions underlying volume projections reflect sustained health-monitoring feature penetration and stable REACH substance restriction enforcement. Material deviation in 28nm driver IC allocation or EU standby power cap stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global LED Digital Signage Market
Display Technologies
Display Mask Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Rugged Display Market
Display Technologies
Smartphone Display Market
Display Technologies
4K VR Displays Market
Display Technologies
Flexible Display Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Microdisplay Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Smart Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
8K Display Resolution Market
Display Technologies
Holographic Display Market