
 4K VR Displays Market | 2026-2036
4K VR Displays Market Size, Share, and Industry Trends Forecast 2026-2036
4K VR Displays Market Outlook
Chinese display panel manufacturing is broadening its reach into high-resolution VR substrates. Samsung Display leverages vertical integration across OLED deposition equipment to sustain cost leadership in premium headset panels. BOE Technology Group anchors supply for domestic Chinese VR hardware brands through massive Gen 6 OLED fab capacity. Sony specializes in micro-OLED architectures for enterprise-grade headsets, differentiating on pixel density thresholds exceeding 3000 ppi.
4K VR displays are high-resolution emissive or transmissive panels engineered to deliver 3840 x 2160 pixels across compact form factors under 3.5 inches diagonal, typically employing RGB stripe or pentile subpixel arrangements with refresh rates above 90 Hz to mitigate motion sickness in immersive environments. Headset applications dominate volume demand, while microLED technology captures emerging margin pools as luminance efficiency and burn-in resistance outpace incumbent OLED solutions. Gaming and defense end users concentrate procurement around low-persistence specifications, whereas healthcare training modules prioritize color accuracy and extended thermal stability.
FDA device classification rules for VR-based surgical training systems shape healthcare demand pathways, while FCC Part 15 emissions standards govern wireless headset radio architectures in the United States. REACH substance restrictions and EU RoHS compliance directives constrain European supply chain chemistry for OLED phosphor materials and indium tin oxide deposition processes. Stakeholders must monitor evolving Ecodesign requirements and emerging eye safety standards from ISO as regulatory fragmentation intensifies across key demand jurisdictions.
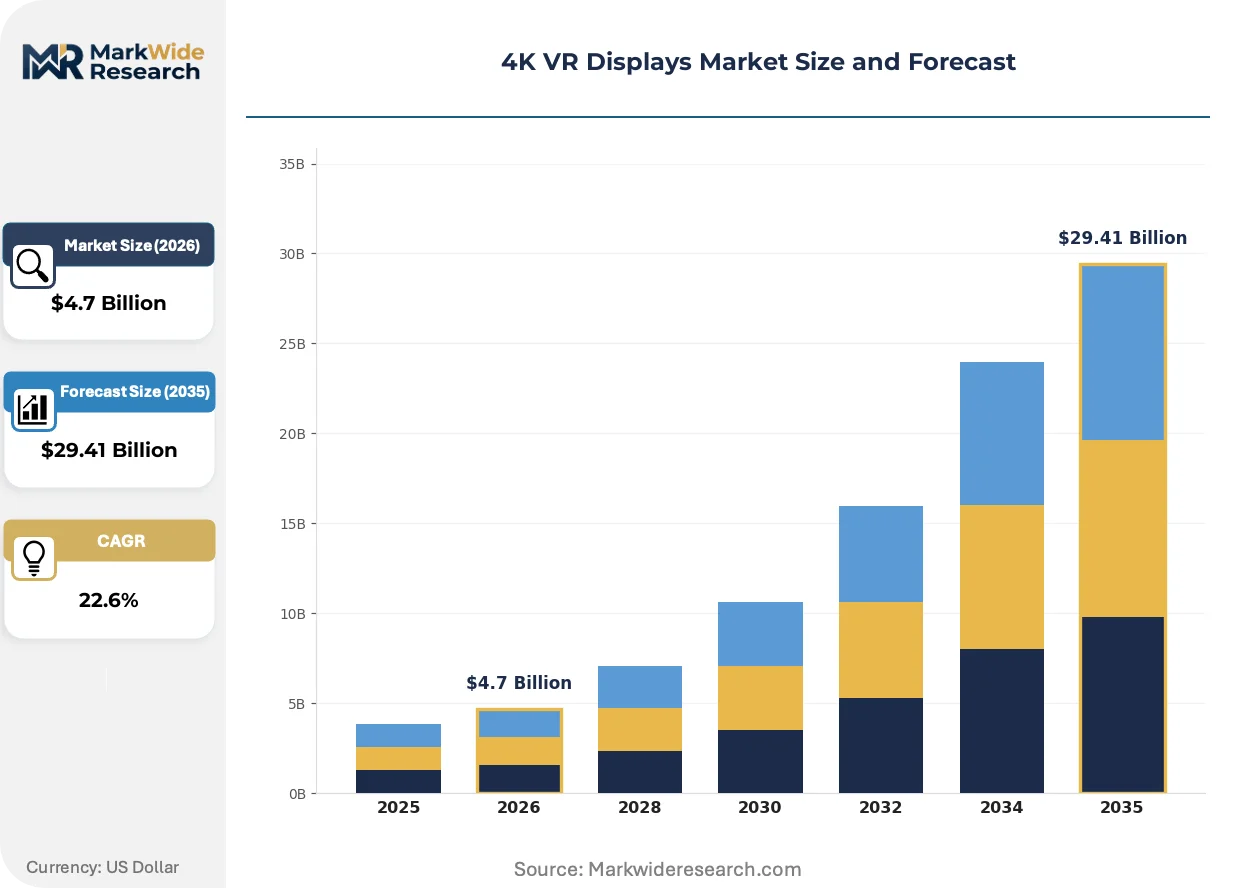
Market Dynamics
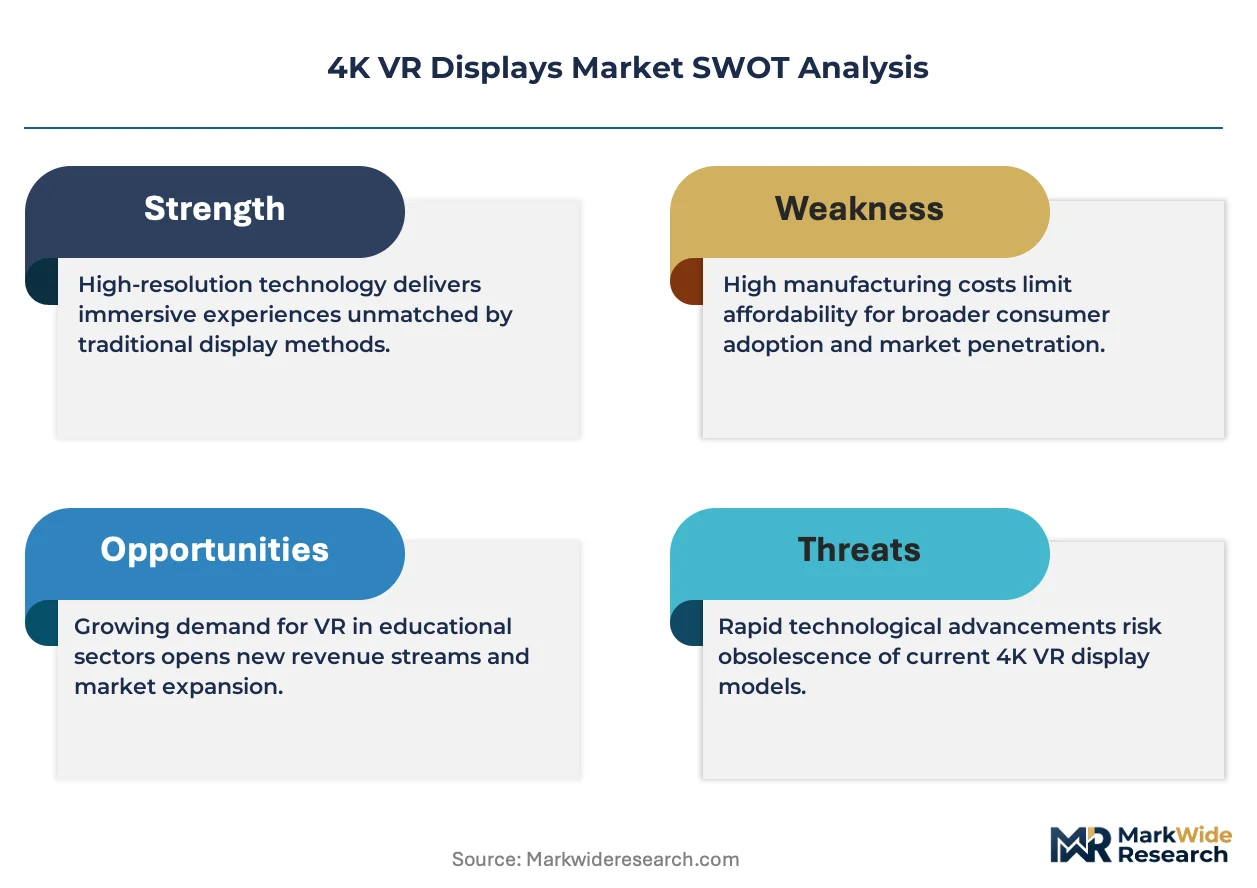
MicroLED process innovation is modularizing display architectures, compressing panel thickness while preserving luminance output. This structural shift reconfigures capex allocation across deposition equipment and backend assembly stages.
Growth Catalysts
- FCC Part 15 emissions standards:Wireless headset radio architectures in the United States must demonstrate electromagnetic compatibility, accelerating certification-driven demand for integrated RF-shielded display modules.
- Gaming headset procurement:Low-persistence specifications below 10 milliseconds dominate consumer volume, pulling RGB stripe subpixel arrangements into mainstream production.
- China domestic supply chain concentration:Gen 6 OLED fab capacity anchors captive substrate supply for local VR hardware brands, reducing import dependency.
Market Restraints
- Indium tin oxide cost volatility:Deposition process chemistry faces REACH substance restrictions and EU RoHS compliance directives, constraining European supply chain flexibility.
- Technical limitation in pixel density scaling:Micro-OLED architectures above 3000 ppi require specialized photolithography equipment with limited supplier base.
- Substitution threat from laser scanning displays:MEMS-based retinal projection systems bypass panel manufacturing entirely for select enterprise training applications.
Strategic Opportunities
- Healthcare training modules:FDA device classification rules for VR-based surgical training systems create regulated demand pathways for color-accurate panels with extended thermal stability.
- Defense end-use procurement:Night-vision compatible luminance specifications open specialized volume for microLED solutions with burn-in resistance.
- ISO eye safety standards evolution:Emerging photobiological safety testing protocols favor displays with tunable blue-light emission profiles.
Industry Challenges
- Backend assembly capex intensity:Chip-on-flex bonding equipment for sub-3.5 inch diagonal form factors requires precision placement accuracy below 5 microns.
- Certification timeline compression:Ecodesign requirements and dual carbon goals in China add environmental compliance layers to existing electromagnetic and safety testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4K VR Displays Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Monitors, Projectors, Glasses Technology: OLED, LCD, LED, MicroLED Application: Gaming, Training, Simulation, Education End User: Entertainment, Healthcare, Automotive, Defense |
| Companies Covered | Synaptics Incorporated, Himax Technologies, Raydium Semiconductor, New Vision Display, Samsung Display, Varjo, BOE Technology Group, LG Display, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K VR Displays Market Strategic Shifts
Display architecture is fragmenting across competing emissive technologies, each optimizing for distinct performance vectors. Panel makers must now support parallel process development tracks without consolidating on a single dominant platform.
MicroLED epitaxy is modularizing across wafer-level bonding and mass transfer equipment. Defense contractors and medical device OEMs are adopting tiled microLED arrays for luminance specifications exceeding 5000 nits. This technology is modularizing supply chain relationships, allowing fabless display designers to source emitters, backplanes, and optics from separate vendors rather than captive integrated fabricators.
EU RoHS compliance directives are tightening restrictions on cadmium-based quantum dot phosphors used in OLED color conversion layers. Industrial consequence includes accelerated transition to indium phosphide alternatives with narrower emission spectra. Healthcare headset manufacturers targeting European procurement are responding with redesigned emitter stacks and expanded material declaration documentation.
After-sales service unbundling is separating panel replacement from full headset refurbishment. Enterprise VR deployment managers in North American surgical training centers now specify modular display subassemblies with field-replaceable unit designs. This pattern is most visible in academic medical center procurement, where uptime guarantees override initial hardware cost minimization.
4K VR Displays Market Segmentation
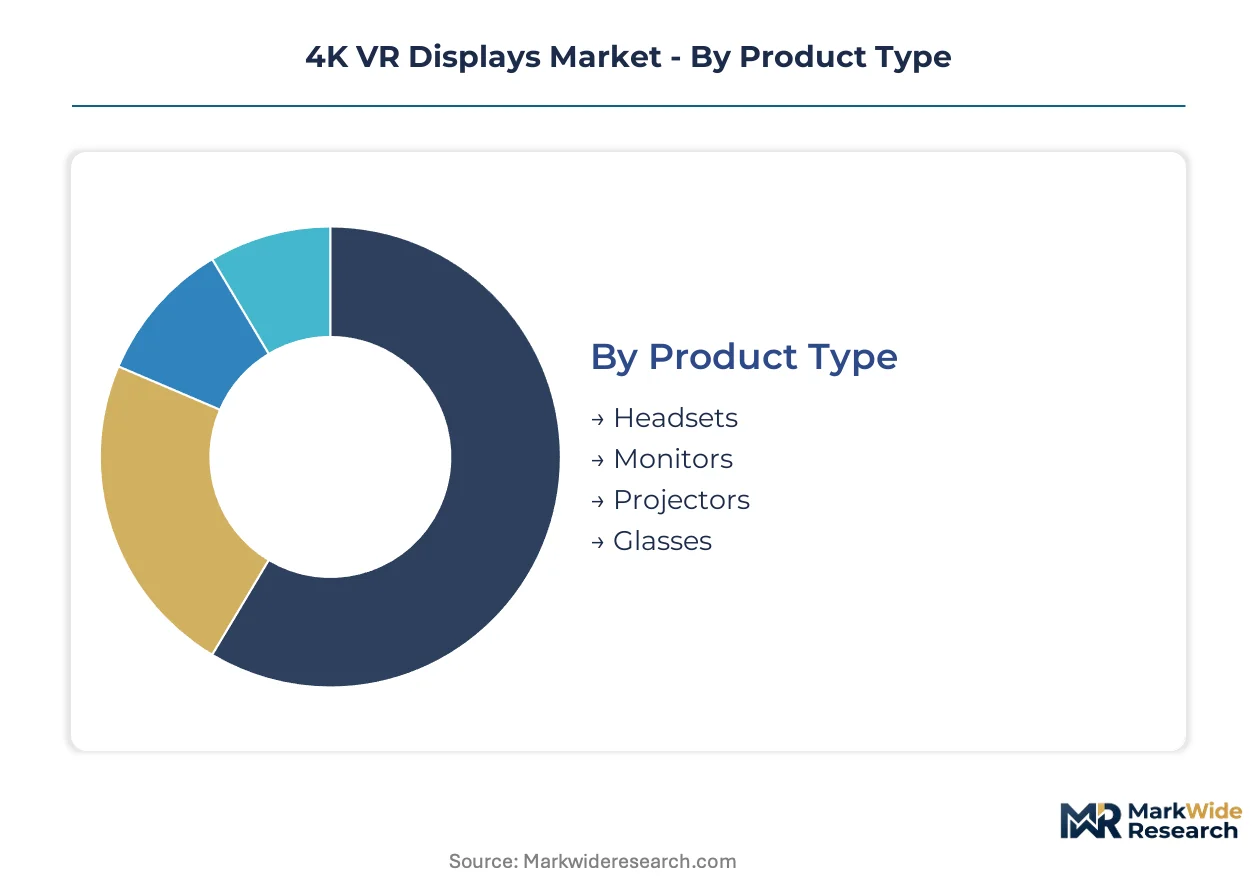
4K VR display procurement patterns diverge sharply across hardware form factors and underlying emissive technologies. Panel makers must calibrate fab output across incompatible specification sets while serving end users with radically different luminance, persistence, and thermal requirements.
Product Type:
Supply concentration in headset-dedicated Gen 6 OLED fabs has compressed lead times for immersive form factors while leaving ancillary display categories import-dependent.
- Headsets:Compact emissive panels under 3.5 inches diagonal with RGB stripe subpixel arrangements and sub-10ms persistence specifications. Demand concentrates in Chinese domestic supply chains serving local VR hardware brands through BOE Technology Group captive capacity.
- Monitors:Larger-format 4K panels for seated VR experiences and development workstations. Procurement is shifting toward gaming peripheral OEMs in South Korea and Taiwan seeking direct panel relationships outside headset-optimized supply chains.
- Projectors:Laser-illuminated or LCoS-based 4K projection systems for cave automatic virtual environments and large-scale simulation.
- Glasses:Waveguide-coupled microLED or OLED microdisplays for augmented reality overlays with see-through optical combiners.
Today's leader: Headsets. Tomorrow's challenger: Glasses.
Technology:
Cost tier stratification separates premium emissive architectures from commodity backlit alternatives, with microLED commanding specialized defense and medical procurement at substantial price premiums.
- OLED:Active-matrix organic light-emitting diode stacks with individual pixel illumination and true black states. Volume concentrates in China where Gen 6 fab scale has depressed unit costs for consumer headset integration.
- MicroLED:Inorganic gallium nitride emitters with luminance efficiency exceeding 5000 nits and immunity to burn-in degradation. Defense contractors and surgical training system OEMs specify tiled microLED arrays for night-vision compatibility and extended thermal stability requirements.
- LCD:Transmissive liquid crystal panels with LED edge or direct backlighting for cost-sensitive simulation and education deployments.
- LED:Direct-view LED video walls for large-format immersive environments with viewing distances exceeding conventional headset focal planes.
Volume dominance rests with OLED. Margin capture is climbing fastest for microLED.
Application:
Customer type differentiation separates entertainment procurement focused on low-persistence gaming performance from regulated healthcare and defense acquisition with extended certification timelines.
- Gaming:Consumer volume demand prioritizing refresh rates above 90 Hz and motion-to-photon latency below 20 milliseconds. Procurement runs through integrated headset OEMs with direct fab relationships in China and South Korea.
- Training:Enterprise and institutional deployment for workforce skill development with uptime guarantees and modular field-replaceable display subassemblies. North American academic medical centers specify color-accurate panels with FDA device classification compliance for surgical simulation systems.
- Simulation:Military flight and vehicle simulators requiring night-vision goggle compatibility and extreme luminance range.
- Education:K-12 and university VR labs with cost-constrained procurement and durability specifications for high-turnover usage environments.
Gaming commands current volume. Training is expanding most quickly as regulated healthcare pathways mature.
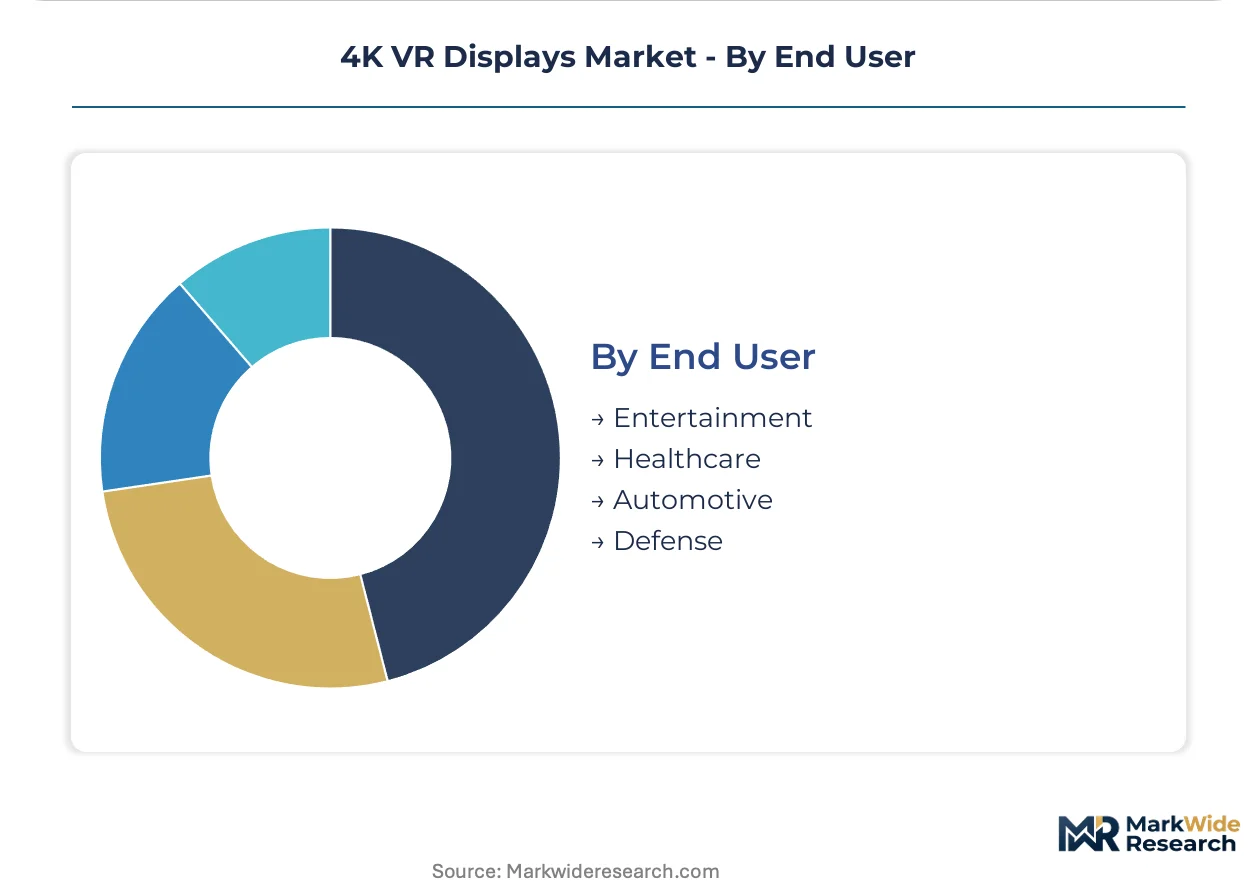
End User:
Application maturity varies dramatically across sectors, with entertainment and defense at opposite poles of procurement standardization.
- Entertainment:Consumer gaming and location-based VR attractions driving RGB stripe subpixel standardization and 90 Hz minimum refresh rate adoption across mainstream production.
- Defense:Night-vision compatible luminance specifications below 0.1 nits minimum and above 5000 nits maximum with burn-in resistance requirements. Procurement concentrates in US and European military contractors with specialized microLED qualification programs.
- Healthcare:FDA device classification rules for VR-based surgical training systems create regulated demand pathways with extended thermal stability and color accuracy specifications.
- Automotive:Design review and virtual prototyping applications with CAD-integrated headset deployment for engineering workstation integration.
Entertainment anchors present scale. Healthcare represents the steepest expansion trajectory as regulated training pathways proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel manufacturing migrates toward jurisdictions with streamlined chemical handling permits and lower energy costs for deposition equipment. China leverages dual carbon goal compliance frameworks to consolidate Gen 6 OLED capacity. South Korea and Taiwan maintain specialized photolithography clusters for premium micro-OLED architectures.
China
Domestic VR hardware brands source captive substrate supply from BOE Technology Group's massive Gen 6 OLED fab operations. SAMR certification requirements and GB standards for electromagnetic compatibility compress product launch timelines for local headset OEMs. Beijing-Tianjin-Hebei and Yangtze River Delta clusters anchor backend assembly capacity with precision chip-on-flex bonding equipment.
South Korea
Samsung Display sustains cost leadership in premium headset panels through in-house production of OLED deposition equipment. MFDS medical device registration creates regulated pathways for surgical training system exports. Seoul Capital Area concentration of display R&D facilities accelerates microLED process innovation for defense luminance specifications.
Japan
Specialized photolithography equipment suppliers serve micro-OLED architectures exceeding 3000 ppi for enterprise-grade headsets. METI technology roadmaps prioritize indium phosphide quantum dot alternatives to cadmium-based phosphors under REACH-aligned substance restrictions. Kansai and Chubu industrial corridors host precision optics integration for waveguide-coupled microdisplays.
United States
FCC Part 15 emissions standards drive certification demand for RF-shielded display modules in wireless headset architectures. FDA device classification rules for VR-based surgical training systems shape healthcare procurement with extended thermal stability requirements. Greater Boston and Pacific Northwest clusters concentrate enterprise VR deployment managers specifying modular field-replaceable display subassemblies.
Germany
EU RoHS compliance directives and Ecodesign requirements constrain OLED phosphor material chemistry for European-bound panel exports. KBA automotive certification pathways extend to design review headset applications for engineering workstation integration. Bavaria and Baden-Württemberg precision manufacturing corridors supply deposition process equipment to Asian fab operators.
4K VR Displays Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized luminance specifications for defense and medical procurement. The vendor base stratifies across three capability tiers: integrated fabricators with captive deposition equipment, fabless designers sourcing emitters and backplanes separately, and precision assembly specialists for sub-3.5 inch diagonal form factors. Dominant competitive moves include backward integration into OLED deposition equipment manufacturing and strategic partnerships for mass transfer microLED assembly capacity.
Among Asia-Pacific display specialists, Samsung Display, BOE Technology Group, and Sony exemplify divergent strategic archetypes. Samsung Display anchors the integrated fabricator position with upstream control over deposition equipment. BOE Technology Group represents the scale-driven domestic supply model serving captive Chinese VR hardware demand. Sony occupies the premium specialization tier with emphasis on micro-OLED architectures for regulated healthcare and defense procurement pathways.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Himax Technologies |
| Raydium Semiconductor |
| New Vision Display |
| Samsung Display |
| Varjo |
| BOE Technology Group |
| LG Display |
| Sony |
| Others |
Value Chain & Pricing Dynamics
Chinese domestic VR hardware OEMs anchor procurement volume, compressing supplier margins through captive fab relationships and long-term offtake contracts with BOE Technology Group. This buyer concentration forces pricing stratification across certification tiers rather than brand premiums.
Pricing Analysis
Direct-to-OEM volume discounts dominate channel economics, with distributor margins compressed to single-digit percentages for Gen 6 OLED substrates. Pricing stratifies across premium, standard, and economy tiers based on FDA device classification status and ISO eye safety certification levels. Cost compression in standard-tier panels intensifies as BOE's captive capacity floods Chinese domestic supply. Healthcare procurement committees demonstrate lowest price sensitivity due to uptime guarantee requirements, while education sector buyers drive aggressive unit-cost negotiation.
Supply Chain Analysis
Dual-sourcing mandates from defense contractors and FDA-registered medical device OEMs require qualified secondary suppliers for microLED emitters and precision backplane substrates. Manufacturing gravity centers on China, South Korea, and Taiwan for OLED deposition equipment and photolithography clusters. Raw material dependencies include indium tin oxide sputtering targets, gallium nitride epitaxy wafers, and phosphor quantum dot materials. Single-source vulnerability persists for sub-3000 ppi micro-OLED photolithography equipment. Distribution runs through integrated headset OEMs with direct fab relationships, bypassing traditional electronics distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South Korean and Japanese precision equipment suppliers capture margin premiums unavailable to Chinese substrate manufacturers facing SAMR carbon compliance costs.
For Market Incumbents: Hedge against microLED substitution by securing mass transfer equipment partnerships before defense procurement shifts entirely to tiled inorganic emitters. BOE Technology Group's captive supply model threatens Samsung Display's premium positioning; backward integration into OLED deposition equipment manufacturing offers defensive moat construction. Prioritize MFDS medical device registration to maintain Korean export access for surgical training panels. For New Entrants and Emerging Players: Begin with waveguide-coupled microdisplays for augmented reality glasses, the least penetrated hardware form factor with minimal incumbent lock-in. North American academic medical centers offer accessible entry point through modular field-replaceable unit designs with uptime guarantees. Pursue direct relationships with enterprise VR deployment managers rather than competing for consumer gaming headset slots. For Investors and Strategic Acquirers: Defense contractors are the most active acquirer in this space, seeking burn-in resistant microLED arrays for night-vision compatible luminance specifications. Long-term viability hinges on regulatory pathway expertise rather than manufacturing scale alone. Watch for ISO eye safety standards evolution as inflection indicator favoring tunable blue-light emission profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Transfer MicroLED Assembly Partnership | Enables defense contractors to meet 5000+ nits luminance specifications for night-vision compatibility. |
| FDA Device Classification Pathway Investment | Unlocks regulated procurement channels for surgical training system panel suppliers. |
| Indium Phosphide Quantum Dot Transition | Ensures EU RoHS compliance for European-bound OLED color conversion layers. |
| Gen 6 OLED Fab Capacity Expansion | Captures Chinese domestic VR hardware brand demand through BOE-style captive supply models. |
| Precision Chip-on-Flex Bonding Capability | Addresses backend assembly bottleneck for sub-3.5 inch diagonal headset form factors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with display panel procurement managers, VR hardware OEM supply chain directors, FDA regulatory affairs consultants, and precision optics integration engineers with secondary validation against SEC filings, SAMR certification databases, and MFDS medical device registration records. Bottom-up substrate volume estimates triangulated against top-down headset shipment projections across the analysis window.
Segment-weighting approaches calibrated output across product type, emissive technology, application vertical, and end-user sector dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating gaming refresh rate specifications, healthcare thermal stability requirements, and defense luminance thresholds. Forecast inputs included Gen 6 OLED fab utilization rates and microLED epitaxy wafer pricing trends.
Several conditions sit outside the modeled scope, including potential REACH substance restriction expansions beyond cadmium-based phosphors and disruptive laser scanning display adoption in enterprise training. Forecasts assume stable FCC Part 15 certification timelines and unchanged FDA device classification frameworks. Deviation in ISO eye safety standards implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America Head-Up Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Display Mask Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Portable Projector Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Visual Computing Market
Display Technologies
Projector Screen Market
Display Technologies
Global Embedded Display Market
Display Technologies
Backlit Displays Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Middle East and Africa Industrial Display Market