
 Collaboration Display Market | 2026-2036
Collaboration Display Market Size, Share, and Industry Trends Forecast 2026-2036
Collaboration Display Market Analysis
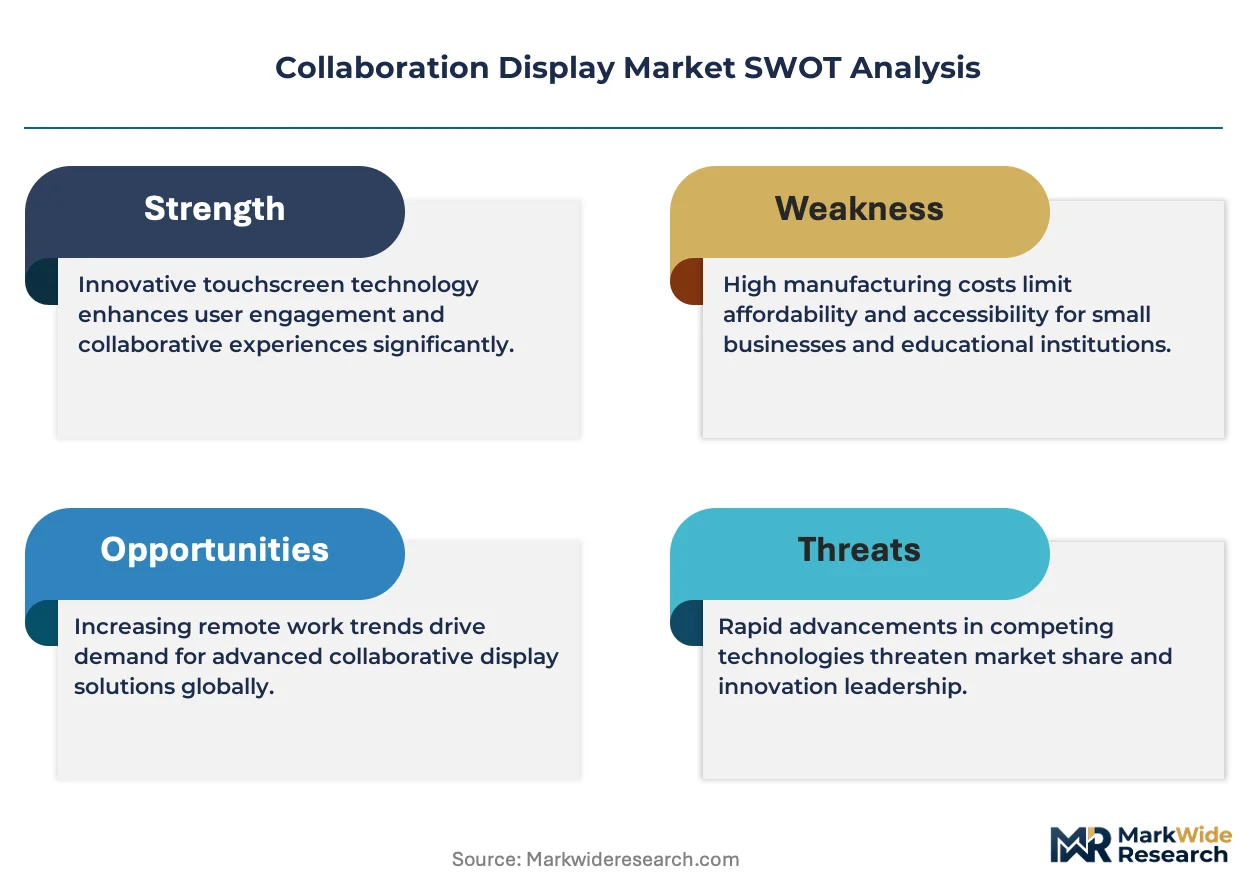
IEC 62368-1 hazard-based safety engineering is unwinding vendor participation in the collaboration display sector, forcing smaller OEMs to retest entire product lines. Samsung Electronics leverages in-house semiconductor fabrication to control panel supply chains. Microsoft anchors its market position through deep Azure integration with Surface Hub ecosystems. Cisco Systems competes on enterprise security certifications and Webex-native hardware lock-in.
Collaboration displays encompass large-format interactive screens enabling multi-user digital whiteboarding, video conferencing, and real-time content annotation, typically incorporating 4K resolution panels with infrared or capacitive touch layers spanning 55 to 98 inches diagonally. Their primary commercial purpose centers on replacing legacy projection systems in meeting rooms and classrooms with persistent, network-connected canvases. Flat panel displays dominate procurement volumes among corporate buyers seeking minimal installation footprint, while interactive whiteboards sustain stronger traction in education budgets where stylus precision matters. LED backlighting leads technology shipments due to luminance efficiency, though OLED penetration climbs in premium executive briefing rooms where contrast ratios justify cost premiums.
FCC equipment authorization rules in the United States govern wireless transmission modules embedded within smart displays, while the EU RoHS Directive restricts hazardous substances in panel assemblies sold across Europe. REACH compliance adds substance disclosure burdens for manufacturers importing finished goods into Germany or France. Stakeholders must monitor whether emerging EU Ecodesign regulations will mandate minimum repairability scores for large-format displays before committing to platform architectures.
Market Dynamics
Enterprise IT refresh cycles in North American corporate headquarters are compressing replacement timelines from seven to four years, forcing procurement teams to prioritize interoperability with existing Microsoft Teams and Zoom deployments over standalone hardware specifications.
Growth Catalysts
- Hybrid Work Infrastructure Mandates:Corporate real estate teams in the United States, Germany, and Japan are standardizing on interactive flat panels as baseline meeting room equipment. Persistent network-connected canvases replace legacy projection systems.
- IEC 62368-1 Harmonization:The hazard-based safety engineering standard creates compliance clarity across audio-visual equipment categories. Vendors achieving certification gain preferential access to enterprise procurement shortlists.
- Education Budget Reallocations:K-12 and higher education institutions redirect capital toward stylus-precision interactive whiteboards. These systems support collaborative pedagogy requirements in STEM curricula.
Market Restraints
- Panel Supply Concentration:Semiconductor fabrication capacity constraints in East Asia limit availability of 4K resolution driver ICs. OEMs face allocation battles for premium display components.
- IEC 62368-1 Retesting Burden:Smaller OEMs must retest entire product lines to meet tightened safety thresholds. Compliance costs disproportionately impact mid-tier vendors without in-house testing laboratories.
- Projection System Residual Demand:Budget-constrained school districts in rural geographies continue purchasing lamp-based projectors. Price sensitivity delays interactive display penetration in underfunded markets.
Strategic Opportunities
- OLED Premium Executive Segments:Contrast ratio advantages justify cost premiums in C-suite briefing rooms. OLED penetration climbs where visual fidelity commands procurement priority.
- EU Ecodesign Repairability Mandates:Emerging regulations may mandate minimum repairability scores for large-format displays. Early architectural commitments to modular component design secure competitive positioning.
- Cloud-Native Whiteboarding Convergence:Real-time content annotation integrated with Azure and AWS cloud storage creates sticky enterprise ecosystems. Vendors embedding native cloud sync differentiate from hardware-only competitors.
Industry Challenges
- Touch Layer Calibration Expertise:Infrared and capacitive touch system integration requires specialized firmware engineering. Talent scarcity in multi-point touch algorithm development constrains product roadmap velocity.
- Legacy AV Infrastructure Interoperability:Corporate meeting rooms retain HDMI switching matrices and ceiling microphone arrays. New display deployments must negotiate signal handshakes with decade-old control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaboration Display Market |
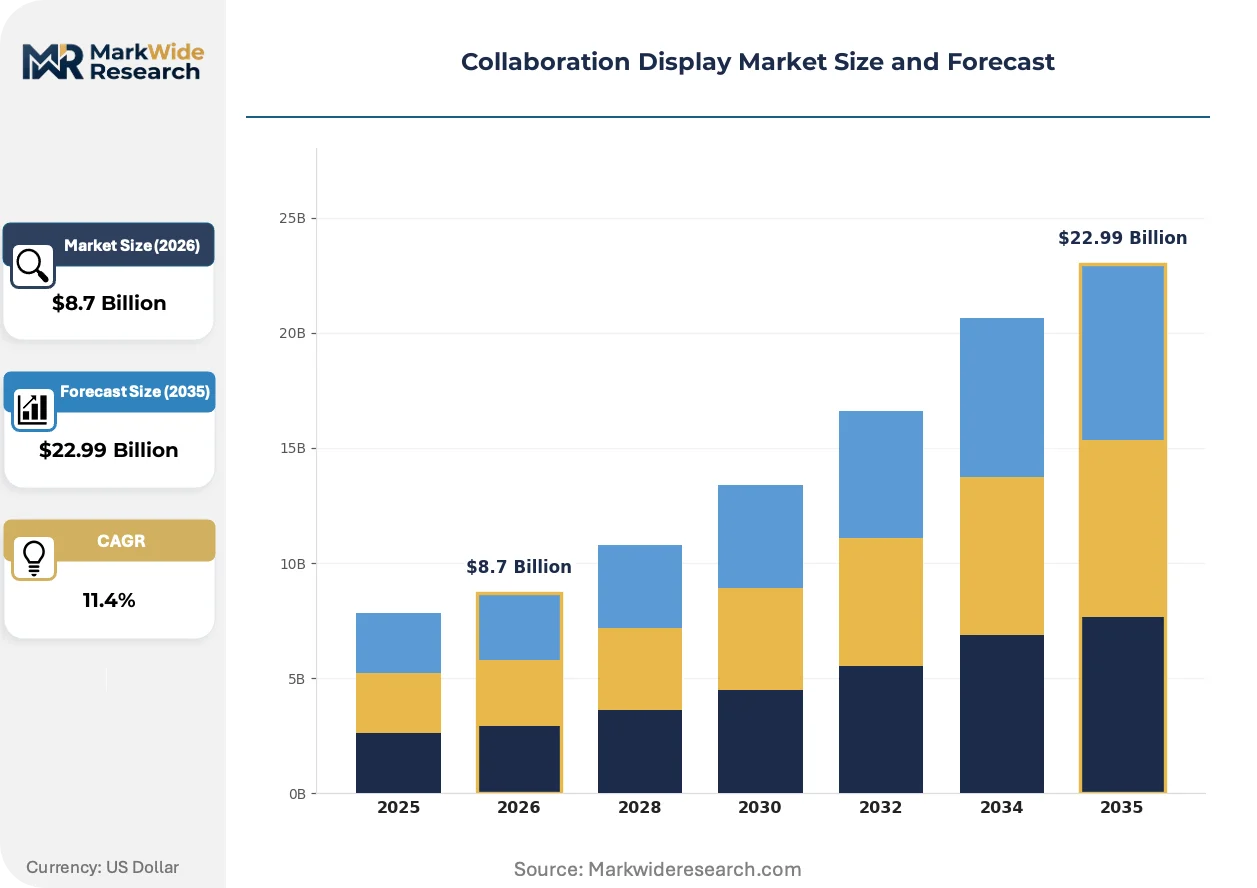
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Whiteboards, Flat Panel Displays, Projection Systems, Touchscreens End User: Education, Corporate, Healthcare, Government Technology: LED, LCD, OLED, DLP Installation: Wall-mounted, Portable, Ceiling-mounted, Integrated Systems |
| Companies Covered | Samsung Electronics, LG Electronics, Microsoft, Cisco Systems, ViewSonic Corporation, Sharp Corporation, Google LLC, SMART Technologies, BenQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaboration Display Market Emerging Trajectories
Touch sensing architectures are diverging rapidly as end-users prioritize either precision stylus input or multi-finger gesture recognition, fragmenting R&D investment across incompatible technical paths.
Micro-LED backlighting is fragmenting the premium collaboration display segment. The technology enables zone-dimming precision for video conferencing applications. Financial services and legal sector buyers in London and New York are specifying micro-LED for executive boardrooms. This specification tier is compressing margins for vendors locked into conventional LED edge-lit designs.
REACH substance disclosure requirements are tightening supply chain documentation burdens for manufacturers importing finished goods into Germany and France. ECHA enforcement of SVHC candidate list updates forces quarterly supplier re-certification cycles. Panel assembly vendors with European distribution footprints are consolidating supplier bases to reduce compliance audit complexity.
Enterprise buying committees are unbundling hardware procurement from installation and managed services. Large corporate real estate teams now source displays through furniture dealers while contracting AV integrators separately for deployment. This pattern is most visible in United States Fortune 500 headquarters where procurement functions have centralized technology category management.
Collaboration Display Market Segmentation
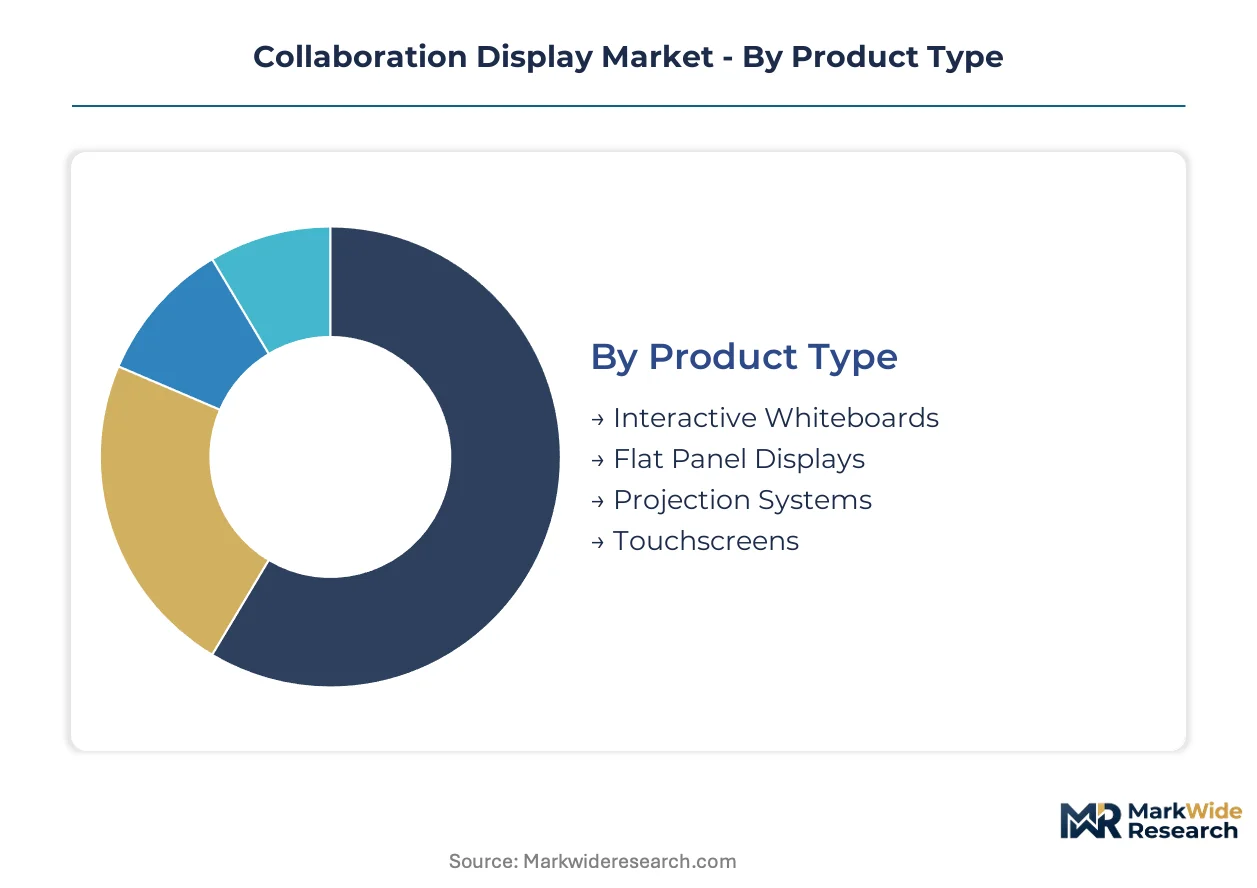
Collaboration display procurement patterns diverge sharply across product architectures and deployment contexts. Understanding these fault lines clarifies why vendor portfolios must span multiple technical tiers rather than optimizing for single-use cases.
Product Type:
Flat panel displays dominate export-led procurement from East Asian manufacturing hubs, while interactive whiteboards retain stronger domestic production footprints in North American and European education markets.
- Flat Panel Displays:Large-format 4K panels with embedded infrared or capacitive touch layers span 55 to 98 inches. Corporate real estate teams in the United States and Germany specify these for standardized meeting room deployments where minimal installation footprint matters. Persistent network connectivity replaces legacy projection infrastructure.
- Interactive Whiteboards:Stylus-precision surfaces with resistive or electromagnetic digitizer layers support fine-grained annotation. K-12 institutions in Japan and higher education campuses in Germany allocate capital here for STEM collaborative pedagogy where handwriting recognition accuracy commands priority.
- Projection Systems:Lamp-based and laser phosphor projectors persist in budget-constrained rural school districts.
- Touchscreens:Compact integrated displays serve huddle room and individual workstation deployments.
Flat panel displays hold the largest share; momentum sits with interactive whiteboards in education budget reallocations.
End User:
Corporate and education segments split procurement volumes roughly evenly, though healthcare and government buyers operate on extended tender cycles that compress margin realization timelines.
- Corporate:Fortune 500 real estate teams and mid-market firms standardize on Microsoft Teams and Zoom-certified hardware. IT refresh cycles compress from seven to four years, forcing interoperability prioritization over standalone specifications. Hybrid work infrastructure mandates in the United States and Germany anchor demand.
- Education:K-12 districts and universities redirect capital toward collaborative learning infrastructure. Stylus-precision requirements in STEM curricula sustain interactive whiteboard traction against flat panel alternatives.
- Healthcare:Hospital systems and telemedicine providers specify antimicrobial surface treatments and HIPAA-compliant data handling.
- Government:Federal and municipal agencies mandate TAA compliance and domestic assembly certifications.
Corporate deployment value leads absolute revenue; education unit volumes are expanding most quickly across the analysis window.
Technology:
LED backlighting commands volume leadership due to luminance efficiency and supply chain maturity, while OLED and emerging micro-LED architectures concentrate in premium price tiers with concentrated geographic demand.
- LED:Edge-lit and direct-lit configurations deliver 300-500 nits brightness for standard conference room ambient conditions. Panel supply chains from South Korea and Taiwan support mass-market pricing tiers.
- OLED:Self-emissive pixels enable infinite contrast ratios and sub-millisecond response times. Financial services and legal sector buyers in London and New York specify these for executive boardrooms where visual fidelity justifies cost premiums.
- LCD:Legacy fluorescent-backlit and modern LED-backlit variants serve cost-sensitive replacement cycles.
- DLP:Digital micromirror devices persist in high-brightness projection applications for large venue installations.
LED technology anchors current procurement volumes; OLED penetration is gaining share fastest in premium executive segments.
Installation:
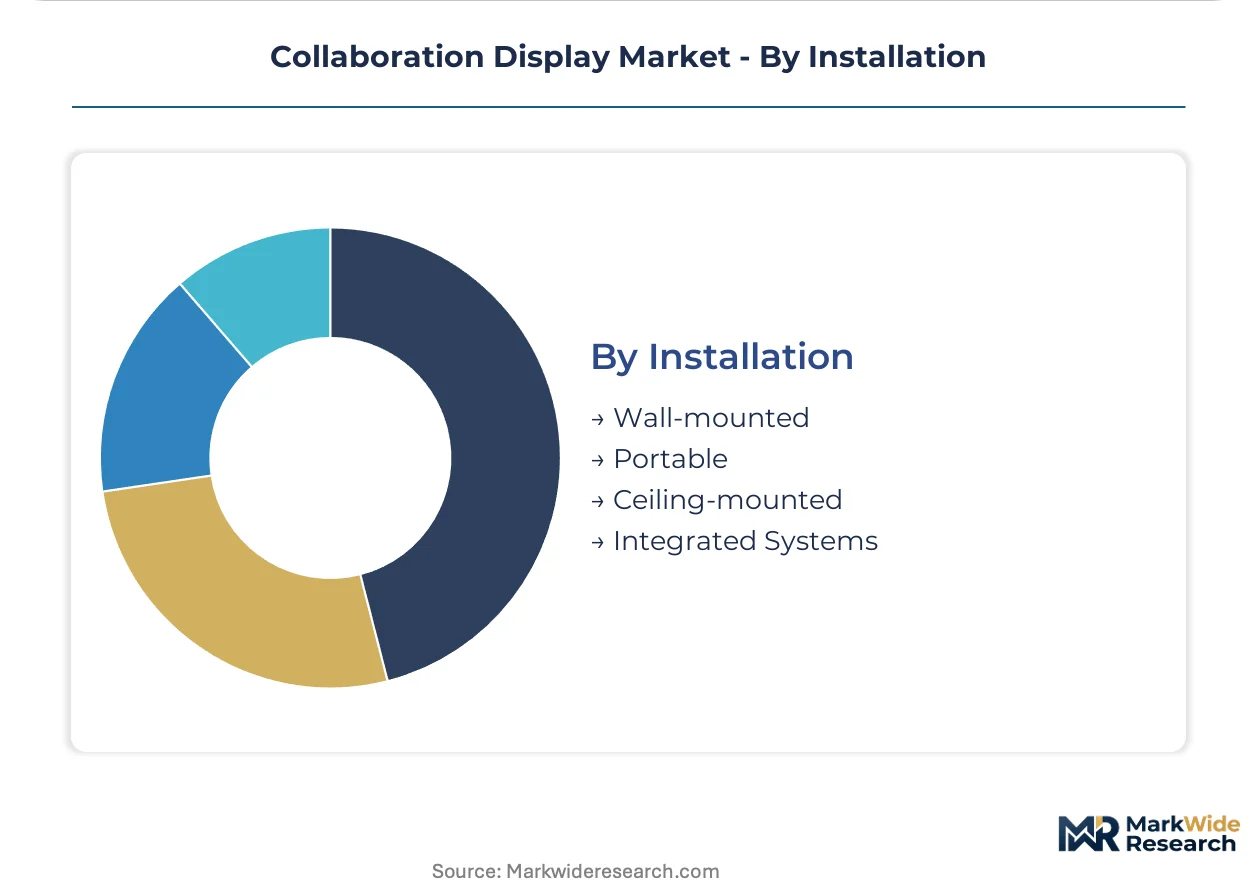
Wall-mounted deployments dominate new construction and full renovation projects, while portable and ceiling-mounted alternatives serve retrofit contexts with structural or lease constraints.
- Wall-mounted:Fixed bracket installations integrate power, data, and AV signal routing within wall cavities. Corporate headquarters in Japan and Germany favor this architecture for clean aesthetic integration with modular furniture systems.
- Portable:Rolling stands with integrated compute and battery options enable reconfiguration between meeting spaces. Coworking operators and agile workplace teams in the United States deploy these for rapid space repurposing without construction permits.
- Ceiling-mounted:Suspended projector and display configurations preserve wall space for whiteboard retention.
- Integrated Systems:Furniture-embedded displays combine surface, compute, and connectivity in single SKUs.
Wall-mounted installations represent the dominant configuration; portable systems show the steepest expansion trajectory in flexible workplace deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 real estate teams and education procurement officers concentrate demand in the United States, Germany, and Japan. Hybrid work infrastructure mandates and STEM curriculum investments anchor purchasing volumes in these markets.
United States
Corporate headquarters in Manhattan and Chicago accelerate IT refresh cycles from seven to four years. FCC equipment authorization rules govern wireless transmission modules embedded within smart displays. Dallas-Fort Worth and Atlanta clusters see concentrated deployment of portable systems for agile workplace reconfiguration.
Germany
Industrial Mittelstand firms and automotive headquarters in Stuttgart standardize on interactive flat panels for engineering collaboration. EU RoHS Directive restricts hazardous substances in panel assemblies sold across Europe. Munich and Frankfurt procurement teams prioritize IEC 62368-1 certified hardware for enterprise shortlist compliance.
Japan
Corporate real estate teams in Tokyo and Osaka deploy wall-mounted configurations for clean aesthetic integration with modular furniture. METI efficiency standards influence display procurement specifications in public sector tenders. Nagoya manufacturing clusters sustain domestic production footprints for education-market interactive whiteboards.
United Kingdom
Financial services buyers in the City of London specify micro-LED backlighting for executive boardrooms where contrast ratios justify cost premiums. REACH substance disclosure requirements tighten supply chain documentation burdens for panel assemblies. Canary Wharf and Manchester technology corridors concentrate cloud-native whiteboarding deployments.
South Korea
Chaebol-affiliated construction and electronics firms anchor domestic demand for large-format 4K panels. MFDS standards alignment creates certification clarity for antimicrobial surface treatments in healthcare applications. Seoul Capital Area and Busan-Ulsan clusters control semiconductor fabrication capacity for driver IC supply.
Collaboration Display Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with captive display panel supply. The vendor base concentrates around three strategic tiers: vertically integrated semiconductor-to-system manufacturers, cloud-platform-anchored hardware specialists, and education-focused interactive whiteboard pure-plays. Dominant competitive moves include backward integration into panel supply chains and strategic certification pursuit for Microsoft Teams and Zoom hardware compatibility programs.
Among diversified Korean electronics conglomerates, Samsung Electronics and LG Electronics exemplify the vertically integrated archetype with in-house semiconductor fabrication capabilities. Microsoft occupies a position as the cloud-platform-anchored specialist through Azure-integrated Surface Hub ecosystems. Cisco Systems sits within the enterprise security certification tier, competing on Webex-native hardware lock-in. SMART Technologies represents the education-focused pure-play archetype with concentrated interactive whiteboard expertise.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Microsoft |
| Cisco Systems |
| ViewSonic Corporation |
| Sharp Corporation |
| Google LLC |
| SMART Technologies |
| BenQ Corporation |
| Others |
Supply Flow & Price Mechanics
Panel fabrication scale economies in South Korea and Taiwan compress unit costs for 4K driver ICs while simultaneously elevating price floors for mid-tier OEMs lacking allocation priority. This concentration dynamic forces procurement teams to accept longer lead times or premium spot pricing for premium display components.
Pricing Analysis
Cost-plus contracts with Taiwanese panel suppliers index to quarterly wafer pricing adjustments, creating transparency for enterprise buyers negotiating multi-year refresh cycles. Three-tier pricing structure across premium, standard, and economy levels separates OLED executive briefing room specifications from LED edge-lit conference room deployments. Pricing pressure stems from semiconductor fabrication capacity constraints that compress margins for vendors locked into conventional LED designs. Education procurement officers exhibit highest price sensitivity, while financial services buyers in London and New York tolerate substantial premiums for micro-LED contrast ratios.
Supply Chain Analysis
South Korea and Taiwan anchor semiconductor fabrication for 4K resolution driver ICs, while Chinese manufacturers dominate LED backlighting module assembly. The supply chain draws from indium tin oxide for transparent conductive layers, rare earth phosphors for white LED generation, and copper-laminated substrates for touch sensor matrices. Single-source vulnerability concentrates in advanced node wafer production where only two foundries serve the collaboration display sector. Distribution runs through East Asian manufacturing hubs to regional fulfillment centers in Rotterdam, Los Angeles, and Singapore before final-mile AV integrator handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from software-native collaboration platforms that reduce hardware dependency through bring-your-own-device meeting room architectures.
For Market Incumbents: Consolidate panel supply chain relationships through multi-year offtake agreements with Taiwanese foundries to secure allocation priority during capacity crunches. Deepen backward integration into touch layer firmware development to reduce reliance on scarce calibration engineering talent. Microsoft Teams and Zoom certification investments remain essential defensive levers against pure-play software entrants. For New Entrants and Emerging Players: IEC 62368-1 fast-track certification programs offer accelerated enterprise shortlist access for vendors willing to front-load compliance testing costs. White-space opportunity concentrates in portable rolling-stand configurations for United States coworking operators seeking rapid space reconfiguration without construction permits. Direct-to-AV-integrator channel strategies bypass entrenched furniture dealer relationships that incumbent hardware vendors have cultivated. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native whiteboarding platform vendors with Azure and AWS storage integration. Long-term viability across a five-to-ten-year window favors acquisition targets with modular component architectures positioned for EU Ecodesign repairability mandates. The signal to watch is procurement committee unbundling patterns where hardware and installation services separate into distinct vendor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Supply | Samsung Electronics and LG Electronics leverage captive semiconductor fabrication to control panel allocation priority during East Asian capacity constraints. |
| Cloud-Native Whiteboarding Platform Integration | Microsoft anchors enterprise stickiness through Azure-embedded Surface Hub ecosystems that synchronize real-time annotation across distributed teams. |
| IEC 62368-1 Certification Fast-Track | Vendors achieving hazard-based safety engineering certification gain preferential access to Fortune 500 procurement shortlists in Germany and Japan. |
| Modular Component Architecture Development | Early architectural commitments to repairable designs secure competitive positioning against emerging EU Ecodesign mandates for large-format displays. |
| AV Integrator Channel Partnership Expansion | Enterprise buying committee unbundling patterns create direct contracting opportunities with deployment specialists separate from furniture dealer networks. |
Methodological Framework
Initial hypotheses were tested against primary input from corporate real estate directors, AV procurement managers, education technology coordinators, and display panel supply chain executives and refined through secondary validation against SEC 10-K filings, customs and trade data from South Korean and Taiwanese export authorities, hyperscaler hardware partnership disclosures, and IEC certification registry databases. Bottom-up unit shipment estimates from panel assembly vendors were triangulated against top-down enterprise IT refresh cycle surveys.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, end-use vertical, installation configuration, and regional regulatory cluster. CAGRs were derived from segmented growth trajectory modeling incorporating procurement cycle compression patterns, education budget reallocation timelines, and emerging technology substitution elasticities. Forecast inputs include semiconductor fabrication capacity utilization projections and enterprise software platform certification pipeline visibility.
Decision-makers should treat outputs as directional under assumptions of sustained hybrid work infrastructure investment and stable East Asian panel supply; material deviation in either driver would warrant model refresh. Specific risks include tariff escalation on Chinese-assembled components, faster-than-expected OLED cost reduction curves, and regulatory acceleration of EU repairability mandates. Recalibration cycles align with material shifts in enterprise procurement centralization patterns and foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Glass Substrate Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
8K Display Resolution Market
Display Technologies
Laptop Panels Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Phosphor Screen Market
Display Technologies
Global Center Stack Display Market
Display Technologies
OLED Laptops Market
Display Technologies
North America Industrial Display Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Display Material Market
Display Technologies
Low Power Display Market
Display Technologies
Global Embedded Display Market