
 United States Microdisplay Market | 2026-2036
United States Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
United States Microdisplay Market Intelligence
Photonics engineering talent is rotating from legacy telecom and semiconductor fabs toward microdisplay foundries, easing a bottleneck that had constrained domestic OLED-on-silicon capacity. Kopin Corporation leverages its Massachusetts-based defense contracting relationships to sustain military display orders. eMagin anchors the organic LED microdisplay segment through its direct-patterning technology leadership. Sony Semiconductor Solutions Corporation dominates CMOS backplane supply for near-to-eye devices, extending its position from image sensors into display substrates.
A microdisplay is a compact screen, typically under two diagonal inches, fabricated on silicon or glass substrates with pixel densities exceeding two thousand per inch for near-to-eye viewing applications. These devices integrate active-matrix backplanes with emissive or reflective frontplanes to project magnified imagery through optical engines in headsets, weapon sights, and head-up displays. OLED microdisplays command premium pricing in military and medical headsets where contrast ratio and response time determine procurement decisions. LCD variants occupy cost-sensitive projector and consumer AR glasses segments where brightness and manufacturing maturity offset lower efficiency. LCoS technology leads pico-projection applications, with reflective architecture enabling higher aperture ratios than transmissive alternatives.
FCC equipment authorization rules govern radio-enabled smart glasses and wearable displays entering the US market, while FDA 510(k) pathways shape clinical AR device commercialization timelines for surgical and diagnostic applications. NHTSA driver distraction guidelines influence automotive head-up display field-of-view and placement standards, directly constraining microdisplay optical engine design parameters. Military buyers must navigate ITAR export controls administered by the Department of State, creating captive domestic demand for cleared suppliers. Stakeholders should monitor how BIS semiconductor export restrictions reshape silicon backplane sourcing strategies for next-generation micro-LED architectures.
Market Dynamics
Defense procurement from the Department of Defense is accelerating adoption of head-mounted displays for pilot training and battlefield situational awareness, creating captive domestic demand that insulates cleared suppliers from commercial cyclicality.
Growth Catalysts
- FDA 510(k) Pathways:Streamlined clearance for augmented reality surgical navigation systems reduces commercialization timelines for healthcare OEMs targeting operating room integration.
- Silicon Valley Clustering:AR/VR hardware startups concentrate in California's San Diego corridor near semiconductor fabrication partners, shortening prototyping cycles.
- Photonics Talent Migration:Engineering expertise is rotating from legacy telecom and semiconductor fabs toward microdisplay foundries, easing domestic OLED-on-silicon capacity constraints.
Market Restraints
- ITAR Export Controls:Department of State administration creates captive domestic demand but blocks foreign revenue expansion for military-grade suppliers.
- CMOS Backplane Concentration:Dominant supply position from Japanese and Korean substrate manufacturers creates single-source vulnerability for near-to-eye device producers.
- Micro-LED Yield Limitations:Mass transfer inefficiencies and defect rates during chiplet placement constrain scalable production economics.
Strategic Opportunities
- Texas and Arizona Fab Expansion:Underpenetrated domestic backplane capacity in southwestern states offers greenfield foundry investment potential.
- Automotive HUD Mandates:NHTSA driver distraction guidelines are spurring OEM integration of augmented reality windshields in premium vehicle segments.
- Micro-LED and Silicon Photonics Convergence:Hybrid architectures combining emissive frontplanes with waveguide coupling enable next-generation optical engine form factors.
Industry Challenges
- OLED-on-Silicon Process Engineering Talent:Specialized wafer-level bonding and thin-film encapsulation expertise remains concentrated among a handful of veteran practitioners.
- FCC Equipment Authorization Timelines:Radio-enabled smart glasses face extended certification cycles that compress commercial launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Microdisplay Market |
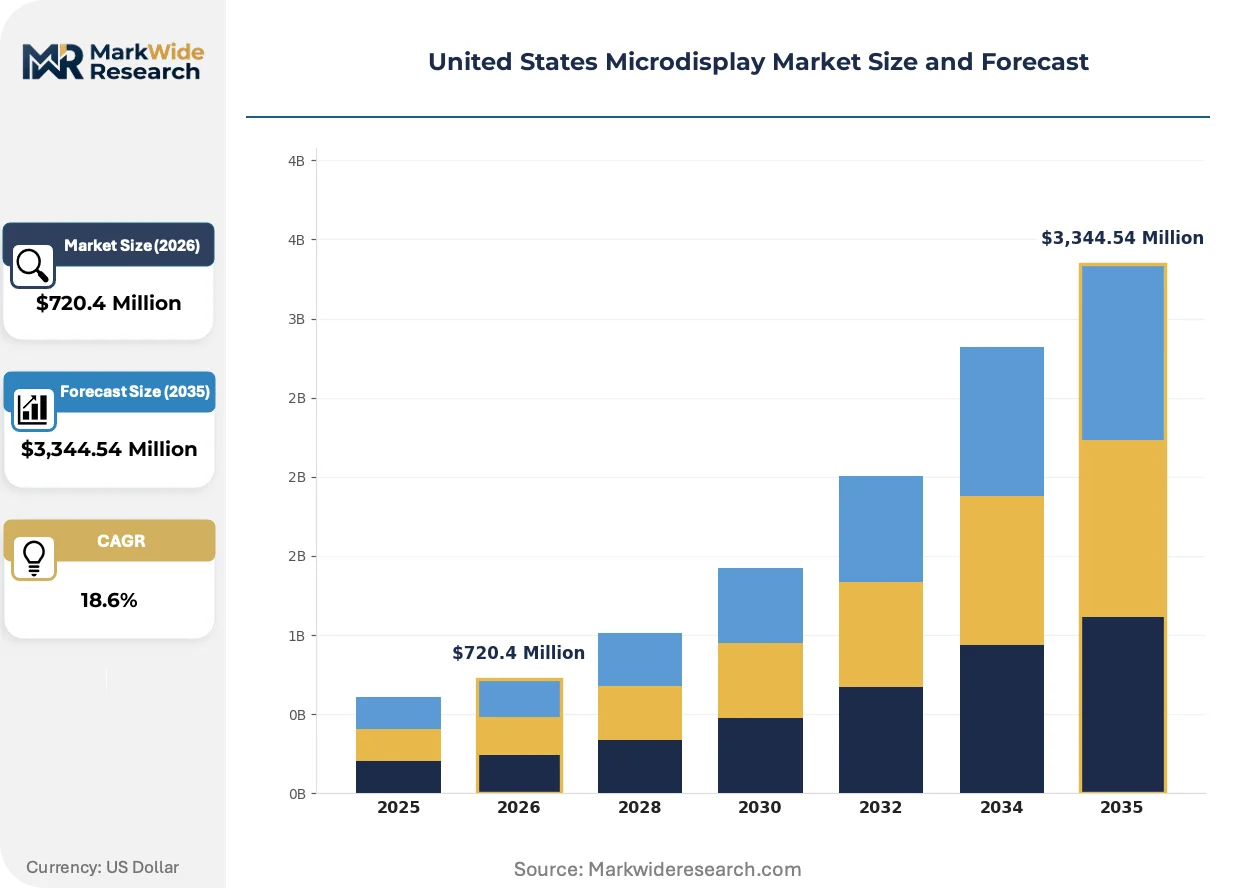
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $3,344.54 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, LCoS, DLP Technology: Near-to-Eye, Projector, Head-mounted Display, Micro-LED Application: Augmented Reality, Virtual Reality, Smart Glasses, Wearable Displays End User: Consumer Electronics, Automotive, Military, Healthcare |
| Companies Covered | Kopin Corporation, eMagin, Micron Technology, Himax Technologies, Universal Display, MicroVision, Sony Semiconductor Solutions Corporation, Seiko Epson Corporation, OLEDWorks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Microdisplay Market Strategic Shifts & Innovations
Domestic microdisplay development is pivoting from LCD legacy architectures toward emissive technologies, with fabrication partnerships and regulatory clearance pathways determining competitive tempo across defense, medical, and consumer verticals.
Micro-LED architecture is fragmenting the incumbent technology hierarchy in pico-projection and transparent display applications. Defense contractors and automotive Tier-1s are piloting micro-LED engines for head-up displays at accelerated evaluation cycles. This technology is fragmenting procurement patterns by enabling direct-emitting solutions that bypass backlight and color filter subsystems entirely.
FDA breakthrough device designation for AR surgical navigation is compressing clinical validation timelines for near-to-eye medical devices. Pre-submission pathway meetings now resolve technical questions before 510(k) filing, reducing regulatory uncertainty for OEMs. Healthcare OEMs in Massachusetts and Minnesota are restructuring quality management systems to align with FDA digital health software guidance.
Contract manufacturing is displacing captive fabrication for mid-volume AR headset producers seeking to avoid wafer-level packaging capital intensity. Original design manufacturers in Texas and Oregon are capturing assembly and test functions previously held by vertically integrated brands. This shift is most visible among Silicon Valley hardware startups outsourcing backplane sourcing while retaining optical engine design.
United States Microdisplay Market Segmentation
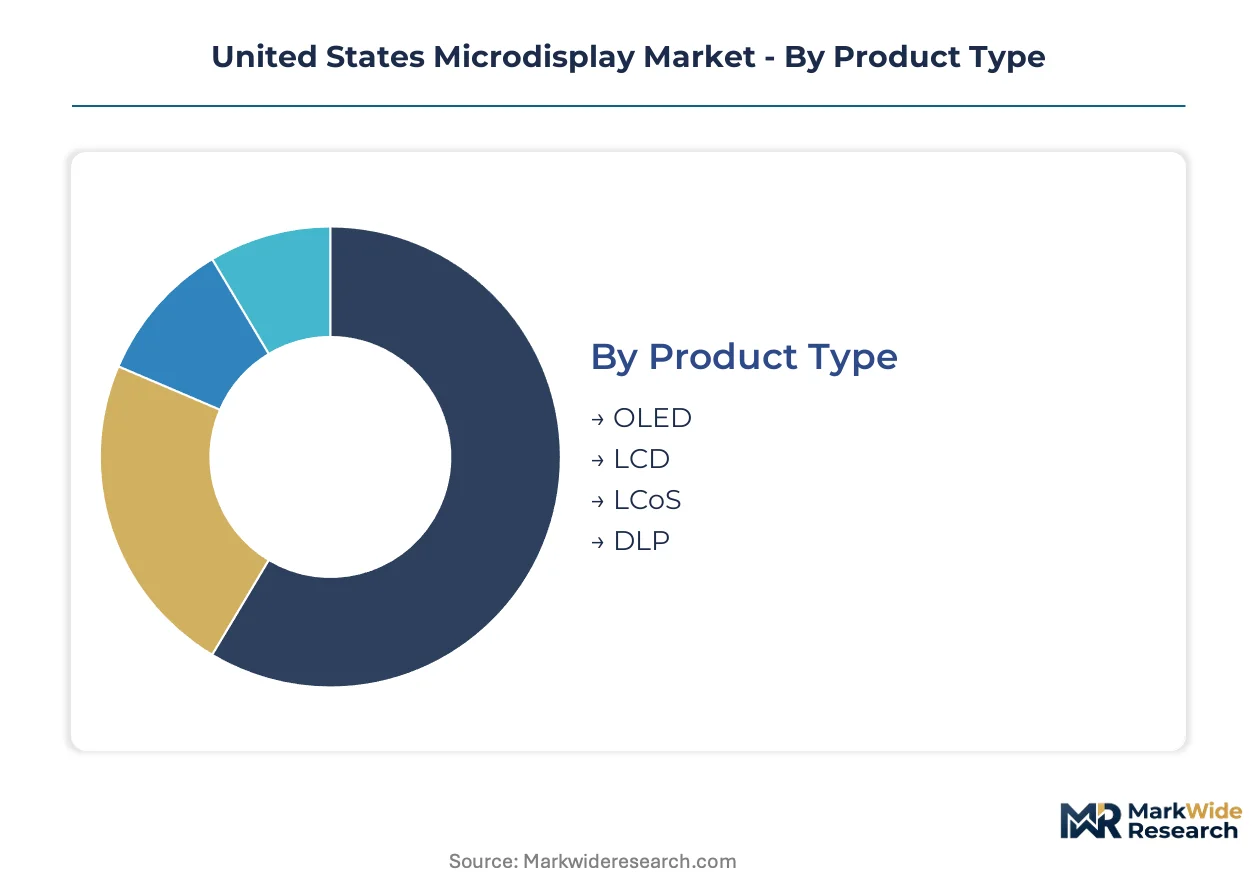
Microdisplay procurement channels diverge sharply by technology maturity and certification requirements. Defense buyers route through cleared contractors with ITAR compliance, while healthcare OEMs navigate FDA 510(k) pathways that favor established emissive technologies.
Product Type:
OLED and LCD variants flow through distinct channel structures—premium emissive panels reach military and medical buyers via defense integrators, while cost-optimized LCD volumes move through consumer electronics distributors.
- OLED:Organic LED-on-silicon architectures achieve contrast ratios exceeding 100,000:1 through direct emissive pixels without backlight subsystems. Military pilot training headsets and AR surgical navigation systems in Massachusetts and California concentrate procurement, with FDA clearance pathways streamlining healthcare adoption.
- LCD:Transmissive liquid crystal cells paired with LED backplanes deliver brightness levels above 5,000 nits for outdoor-readable applications. Consumer AR glasses and pico-projector OEMs in Texas and Oregon drive volume procurement where manufacturing maturity offsets efficiency limitations.
- LCoS:Reflective liquid crystal on silicon leverages CMOS backplane aperture ratios for compact optical engines.
- DLP:Digital micromirror devices from Texas Instruments anchor high-brightness projection applications with mature foundry supply.
By volume, LCD leads. By growth pace, OLED is ahead.
Technology:
Cost tiers separate near-to-eye military displays from mass-market projector engines, with micro-LED development consuming premium R&D allocation.
- Near-to-Eye:Compact optical engines with pixel densities above 2,000 per inch magnify microdisplay imagery for immersive viewing. Defense pilot training programs and healthcare surgical navigation in California and Minnesota concentrate procurement, with ITAR controls creating captive domestic demand.
- Micro-LED:Chiplet-based direct-emitting architectures bypass color filters through monolithic or mass-transfer integration. Automotive head-up display pilots by Tier-1 suppliers in Michigan and Arizona are gaining share fastest as NHTSA guidelines spur augmented reality windshield adoption.
- Projector:LCoS and DLP engines dominate pico-projection with established optical component supply chains.
- Head-mounted Display:Integrated headset systems combine microdisplays with waveguide optics for soldier modernization programs.
By revenue concentration, Near-to-Eye dominates. By expansion trajectory, Micro-LED is climbing the fastest.
Application:
Customer type determines margin structure—enterprise healthcare and defense buyers accept premium pricing, while consumer wearable segments demand cost-down engineering.
- Augmented Reality:See-through optical systems overlay digital imagery on physical environments through waveguide or birdbath combiner architectures. Healthcare surgical navigation in Massachusetts and defense situational awareness programs drive procurement, with FDA breakthrough device designation compressing validation timelines.
- Virtual Reality:Fully immersive displays with wide field-of-view requirements for training and simulation applications. Military pilot training centers in Florida and Texas concentrate demand, with procurement insulated from consumer cyclicality by multi-year defense contracts.
- Smart Glasses:Lightweight near-to-eye displays for enterprise logistics and field service workflows.
- Wearable Displays:Wrist-mounted or body-worn screens for industrial and fitness applications.
By installed base, Virtual Reality leads. By commercial momentum, Augmented Reality is expanding most quickly.
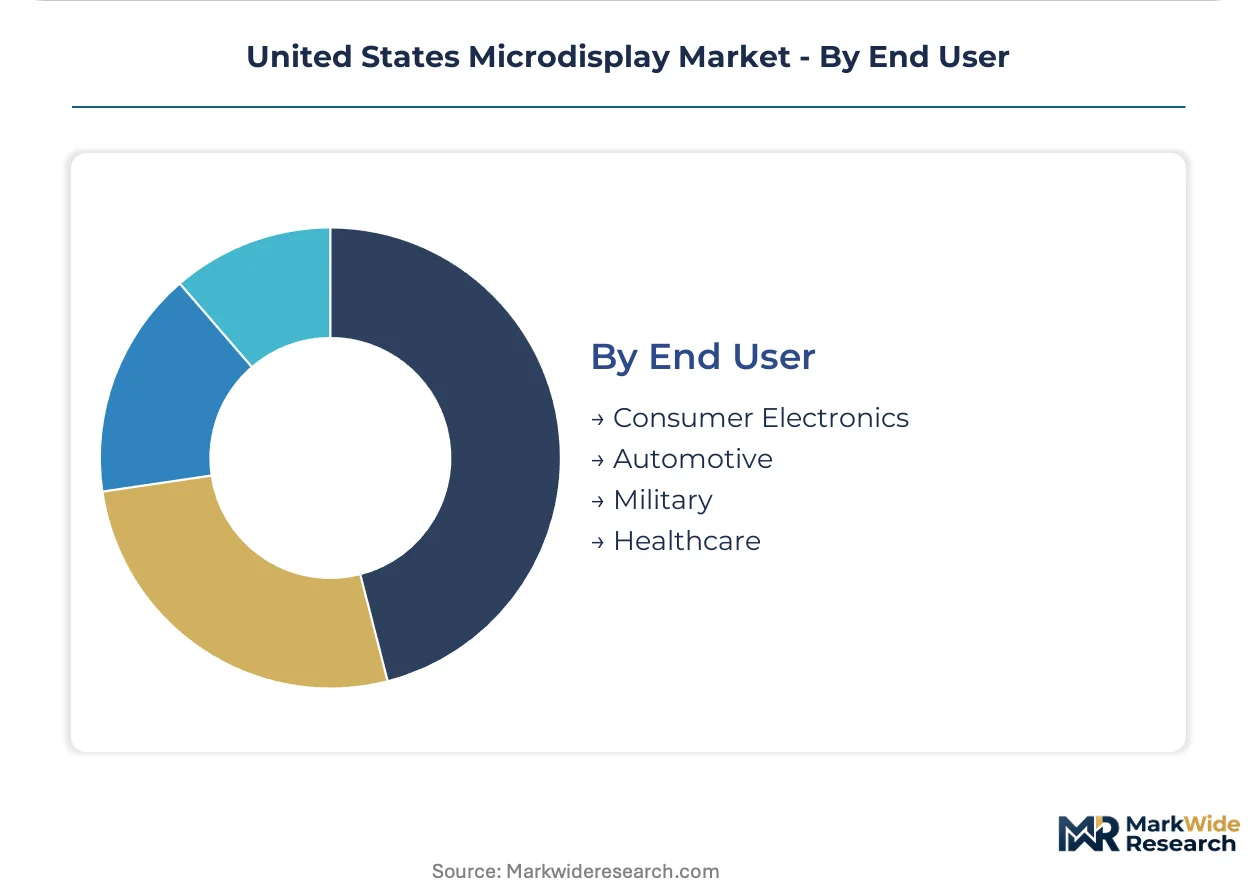
End User:
Supply concentration varies by vertical—defense procurement clusters around cleared Massachusetts and California suppliers, while automotive demand disperses across Midwest Tier-1 integration hubs.
- Military:ITAR-controlled procurement for pilot training, night vision, and battlefield situational awareness systems. Department of Defense modernization programs and Silicon Valley defense contractors anchor demand, with export restrictions blocking foreign revenue expansion for domestic suppliers.
- Healthcare:FDA-regulated AR surgical navigation and diagnostic imaging applications. OEMs in Minnesota and Massachusetts restructure quality systems around digital health software guidance, with 510(k) pre-submission meetings reducing regulatory uncertainty.
- Consumer Electronics:Gaming headsets and AR glasses through retail and direct-to-consumer channels.
- Automotive:Head-up displays and augmented reality windshields for premium vehicle segments.
By contract value, Military leads. By regulatory tailwinds, Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules and FDA 510(k) pathways anchor demand concentration across domestic microdisplay clusters. State-level tax incentives and defense procurement geography reshape where fabrication capacity and design talent locate.
California
AR/VR hardware startups concentrate in Silicon Valley and San Diego near semiconductor fabrication partners. FDA breakthrough device designation for surgical navigation compresses validation timelines for healthcare OEMs in the San Francisco Bay Area. Los Angeles anchors entertainment industry demand for virtual production volumes.
Massachusetts
Defense contracting relationships sustain military display orders through cleared suppliers. ITAR export controls administered by the Department of State create captive domestic demand for battlefield situational awareness systems. Greater Boston's photonics engineering talent rotates from legacy telecom toward microdisplay foundries.
Texas
Underpenetrated domestic backplane capacity in the southwestern corridor offers greenfield foundry investment potential. Original design manufacturers capture assembly and test functions for mid-volume AR headset producers. Austin and Dallas-Fort Worth clusters shorten prototyping cycles for consumer electronics distributors.
Minnesota
Healthcare OEMs restructure quality management systems to align with FDA digital health software guidance. Pre-submission pathway meetings resolve technical questions before 510(k) filing. Minneapolis-Saint Paul anchors diagnostic imaging and surgical navigation device development.
Arizona
Automotive Tier-1 suppliers pilot micro-LED engines for head-up displays at accelerated evaluation cycles. NHTSA driver distraction guidelines spur augmented reality windshield adoption in premium vehicle segments. Phoenix-Tucson corridor attracts semiconductor packaging investment for next-generation optical engine form factors.
United States Microdisplay Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with technology licensing and defense contracting relationships determining competitive position. The vendor base separates into emissive technology architects, CMOS backplane suppliers, and optical engine integrators. Strategic moves concentrate on foundry partnerships for OLED-on-silicon capacity and ITAR compliance infrastructure for military-grade procurement.
Among domestic emissive display specialists, eMagin and OLEDWorks exemplify the direct-patterning technology tier. Kopin Corporation represents the defense-anchored integrator archetype, with Massachusetts-based contracting relationships sustaining military orders. Sony Semiconductor Solutions Corporation occupies the backplane supply position, extending from image sensors into display substrates for near-to-eye devices.
| Leading Market Players |
|---|
| Kopin Corporation |
| eMagin |
| Micron Technology |
| Himax Technologies |
| Universal Display |
| MicroVision |
| Sony Semiconductor Solutions Corporation |
| Seiko Epson Corporation |
| OLEDWorks |
| Others |
Cost & Logistics Intelligence
ITAR export controls administered by the Department of State simultaneously gate supplier qualification and segment price tiers, with cleared defense contractors commanding substantial premiums over commercial-grade alternatives while non-ITAR suppliers face margin compression in commoditized consumer segments.
Pricing Analysis
Geographic price spreads between Massachusetts defense corridors and Texas consumer electronics clusters exceed three-to-one for equivalent pixel-density panels. Pricing stratifies across ITAR-cleared premium tiers, FDA-validated medical grades, and unregulated consumer economy levels. Cost compression in LCD consumer segments is intensifying because contract manufacturers in Oregon and Texas are consolidating assembly volumes. Healthcare OEMs in Minnesota exhibit lowest price sensitivity due to reimbursement-anchored procurement budgets, while gaming headset distributors face acute margin pressure.
Supply Chain Analysis
Inventory lead times for CMOS backplane substrates have extended from legacy telecom norms as photonics talent migration strains domestic OLED-on-silicon foundry capacity. Supply concentrates in Japan and South Korea for CMOS backplane fabrication, with Taiwan anchoring advanced packaging nodes. Raw material dependencies span silicon wafers, rare-earth phosphors, and organic emitter materials. Single-source vulnerability around Sony Semiconductor Solutions Corporation's substrate supply creates procurement risk for near-to-eye device producers. Distribution runs through defense integrators for military-grade volumes and consumer electronics distributors for mass-market AR glasses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as optical engine interoperability standards emerge, with waveguide coupling architectures enabling ecosystem substitution between emissive frontplane suppliers and backplane providers.
For Market Incumbents: Consolidate defense contracting relationships through ITAR compliance infrastructure expansion in Massachusetts and California corridors. Deepen captive OLED-on-silicon capacity via foundry partnerships in underpenetrated southwestern states. Micro-LED substitution technology threatens emissive display incumbents in automotive HUD segments.
For New Entrants and Emerging Players: Anchor in Texas and Arizona greenfield backplane fabrication where domestic capacity scarcity meets automotive Tier-1 demand concentration. Target FDA 510(k) pre-submission pathways for surgical navigation white-space in Minnesota healthcare clusters. Pursue contract manufacturing partnerships to bypass wafer-level packaging capital intensity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing sub-segments as mid-volume AR headset producers outsource assembly functions. Long-term viability favors optical engine design houses with waveguide IP over captive fabrication plays. Acquisition target archetype: photonics engineering teams with thin-film encapsulation expertise. Watch BIS semiconductor export restriction announcements as inflection signals for silicon backplane sourcing strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Compliance Infrastructure Expansion | Defense procurement from the Department of Defense creates captive revenue streams for cleared Massachusetts suppliers. |
| FDA 510(k) Pre-Submission Pathway Investment | Breakthrough device designation for AR surgical navigation compresses validation timelines for healthcare OEMs. |
| Foundry Partnership for OLED-on-Silicon Capacity | Photonics talent migration from legacy telecom eases domestic backplane constraints for near-to-eye applications. |
| Micro-LED Pilot Program with Automotive Tier-1s | NHTSA driver distraction guidelines spur augmented reality windshield adoption in Michigan and Arizona corridors. |
| Waveguide Optical Engine Platform Standardization | Interoperability between emissive frontplanes and coupling architectures enables supplier ecosystem substitution. |
Research Approach
The analysis maps OLED-on-silicon, LCD, LCoS, and micro-LED technology sub-sectors, each validated through defense procurement officers, healthcare OEM regulatory affairs leads, and automotive Tier-1 platform engineers. Primary interviews with FDA submission consultants and ITAR compliance specialists combined with secondary validation against SEC 10-K filings, FDA 510(k) clearance databases, and Department of Defense contract announcements. Bottom-up and top-down triangulation cross-checked foundry capacity announcements against optical engine shipment estimates.
Consistency checks validated volume and value outputs against hyperscaler AR/VR hardware capex disclosures and defense modernization budget line items across the projection horizon. Segmentation dimensions modeled include technology type, application archetype, and end-user vertical. CAGRs derived from installed base growth curves and replacement cycle assumptions. Industry-specific forecast inputs encompass ITAR-controlled procurement volumes and FDA breakthrough device designation trajectories.
Material uncertainties — BIS semiconductor export restriction expansions, micro-LED mass transfer yield inflections, and NHTSA augmented reality windshield mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding defense budget continuity and healthcare reimbursement stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Digital Kiosk Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Volumetric Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Touch Screen Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Privacy Screens Market