
 Borage Oil Market | 2026-2036
Borage Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Borage Oil Market Intelligence
The EU Green Deal is consolidating demand for traceable botanical oils across European personal care supply chains. AOS Products Pvt. Ltd. leverages integrated cultivation networks in India to secure raw seed supply for international refiners. Gustav Heess GmbH anchors premium cold-pressed extraction capacity in Germany, serving cosmetic houses with certified organic grades. ConnOils LLC competes on flexible toll-refining services for North American dietary supplement brands.
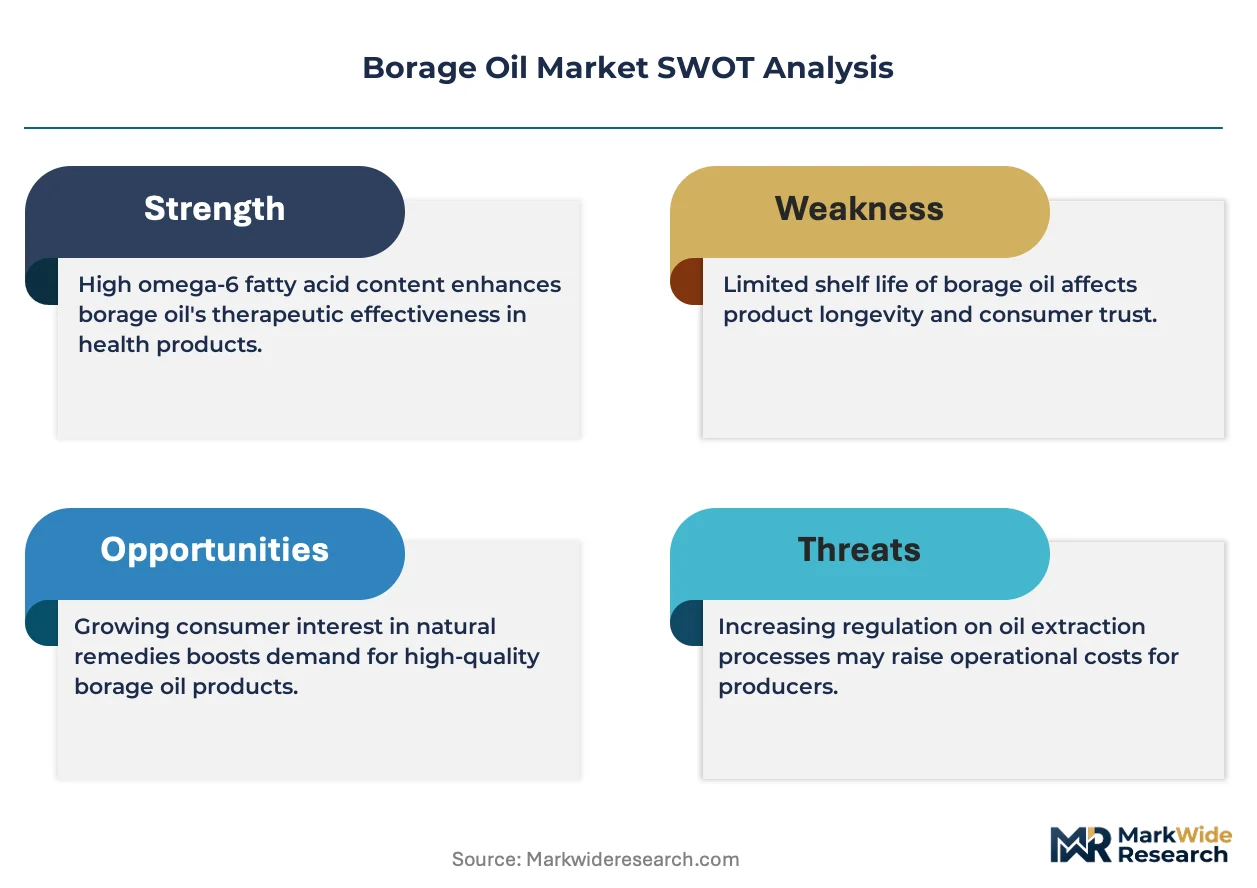
Borage oil is a fixed oil extracted from seeds of Borago officinalis, containing up to 24% gamma-linolenic acid by weight and typically refined via cold pressing or solvent extraction for use in anti-inflammatory and skin-barrier formulations. Cold pressed grades command the widest use in cosmetics due to retained phytosterol content and minimal thermal degradation, while organic certification creates the fastest-growing margin pool as clean-label procurement expands. Dietary supplements represent a structurally smaller but higher-growth application as GLA clinical validation accumulates for atopic dermatitis and hormonal balance protocols.
EMA guidelines on herbal medicinal products shape quality thresholds for pharmaceutical-grade borage oil in Europe, while FDA GRAS status governs food and supplement incorporation in the United States. REACH compliance and ECHA substance evaluation further constrain solvent residues and allergen labeling for EU market access. Stakeholders must monitor evolving monograph standards from pharmacopeial authorities and adapt extraction certifications ahead of tightening contaminant limits in major destination markets.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are compressing procurement timelines for botanical extract suppliers, forcing rapid certification upgrades across European dermo-cosmetic supply chains while cold-pressed extraction capacity struggles to match clean-label procurement velocity.
Growth Catalysts
- EMA Herbal Medicinal Products Guidelines:Quality thresholds for pharmaceutical-grade borage oil in Europe are consolidating demand around certified refiners capable of pharmacopeial compliance.
- Dietary Supplement Formulators:Clinical validation of gamma-linolenic acid for atopic dermatitis protocols is pulling GLA concentrates into hormonal balance and anti-inflammatory supplement stacks.
- Cold-Pressed Extraction:Retained phytosterol content and minimal thermal degradation in cosmetic-grade output is commanding premium positioning in German dermo-cosmetic supply chains.
Market Restraints
- Seed Supply Concentration:Raw Borago officinalis cultivation clusters in Indian agricultural networks, exposing international refiners to monsoon-dependent yield volatility and export tariff friction.
- Solvent Residue Limits:REACH compliance and ECHA substance evaluation constrain solvent-extracted grades, forcing costly reprocessing or cold-press conversion for EU market access.
- Evening Primrose Oil Substitution:Competing botanical GLA sources with established supply chains and lower organic certification burdens pressure borage oil margin structures in mid-tier supplement positioning.
Strategic Opportunities
- CSRD-Driven Traceability:Corporate sustainability reporting mandates in Europe are creating first-mover advantage for integrated cultivator-refiners with blockchain-verified organic seed-to-oil chains.
- Clean-Label Pet Nutrition:GLA inclusion in veterinary dermatological formulations represents an underpenetrated application channel with lower regulatory barriers than human pharmaceutical grades.
- Supercritical CO2 Convergence:Combination with molecular distillation is enabling contaminant-free, high-GLA concentrates without thermal degradation, opening pharmaceutical-grade positioning beyond cold-press limitations.
Industry Challenges
- Organic Certification Timelines:Three-year conversion periods for conventional Borago officinalis acreage strain working capital for cultivators responding to EU Green Deal procurement windows.
- Phytosterol Standardization:Batch-to-batch variability in cold-pressed output complicates cosmetic formulator specification compliance, requiring investment in in-house analytical chemistry capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borage Oil Market |
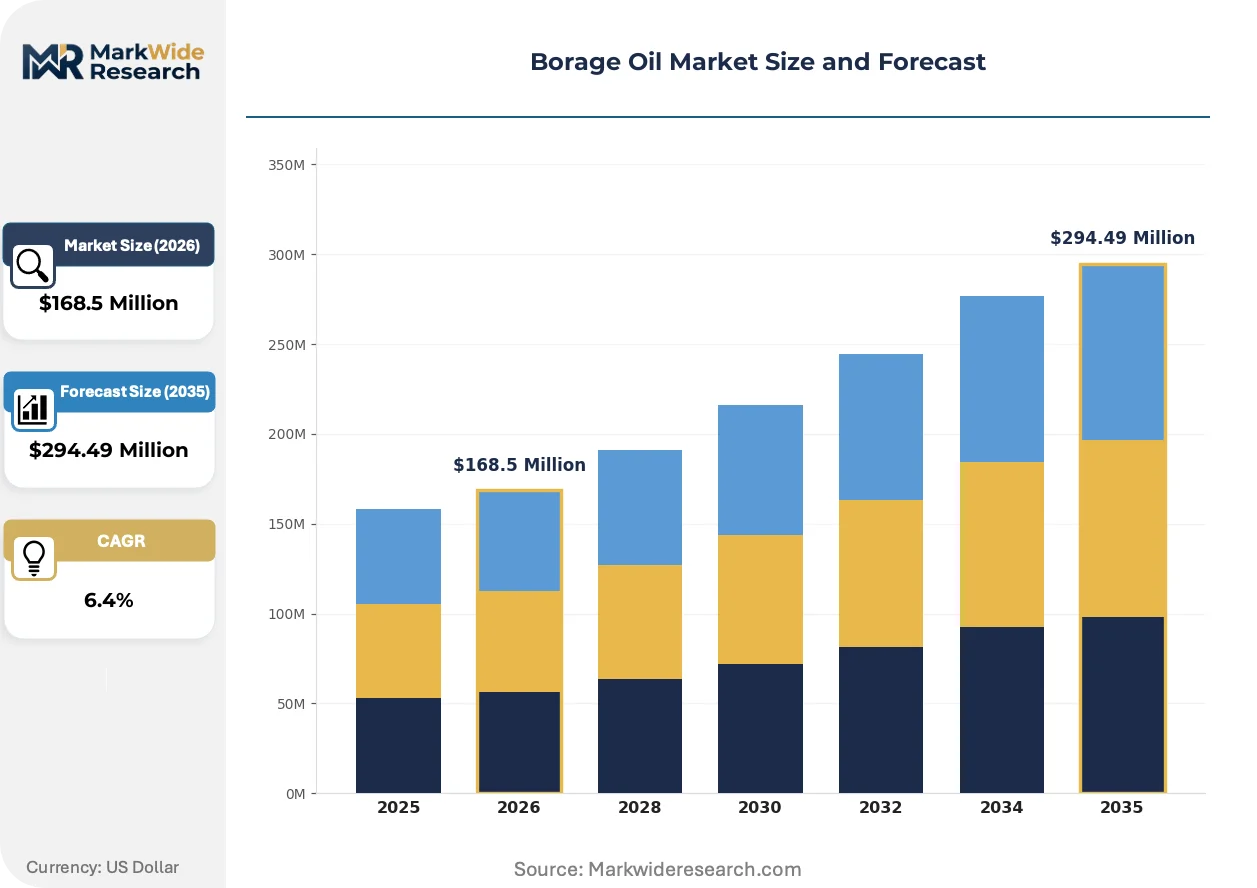
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $294.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Organic, Conventional Application: Cosmetics, Food, Pharmaceuticals, Dietary Supplements Packaging Type: Bottles, Jars, Tetra Packs, Bulk Containers End User: Personal Care Manufacturers, Food Manufacturers, Healthcare Providers, Retail Consumers |
| Companies Covered | AOS Products Pvt. Ltd., ConnOils LLC, Premium Crops, Aromex Industry, Icelandirect LLC, Avestia Pharma, Gustav Heess GmbH, Soyatech International, Parchem Fine & Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borage Oil Market Strategic Shifts & Innovations
Extraction technology convergence and regulatory traceability mandates are compressing traditional supplier hierarchies, rewarding integrated players with captive cultivation while fragmenting toll-refining margins.
Supercritical CO2 extraction combined with molecular distillation is rewriting quality benchmarks for pharmaceutical-grade borage oil. German cosmetic houses and Nordic supplement brands are adopting these systems at pilot scale. The technology is compressing the premium gap between cold-pressed cosmetic grades and solvent-extracted pharmaceutical concentrates.
REACH substance evaluation and ECHA allergen labeling requirements are tightening residue thresholds for EU-bound botanical oils. Industrial consequence includes mandatory third-party testing for polycyclic aromatic hydrocarbons and pesticide traces. Cold-pressed organic grades serving German dermo-cosmetic supply chains are absorbing the highest compliance costs through dedicated batch certification.
Direct contracting between end-use formulators and certified organic cultivators is displacing traditional broker-mediated seed procurement. Cosmetic houses in France and supplement manufacturers in California are establishing multi-year offtake agreements with Indian agricultural cooperatives. This pattern is most visible in Germany, where cold-pressed borage oil traceability has become a non-negotiable entry ticket for clean-label personal care positioning.
Borage Oil Market Segmentation
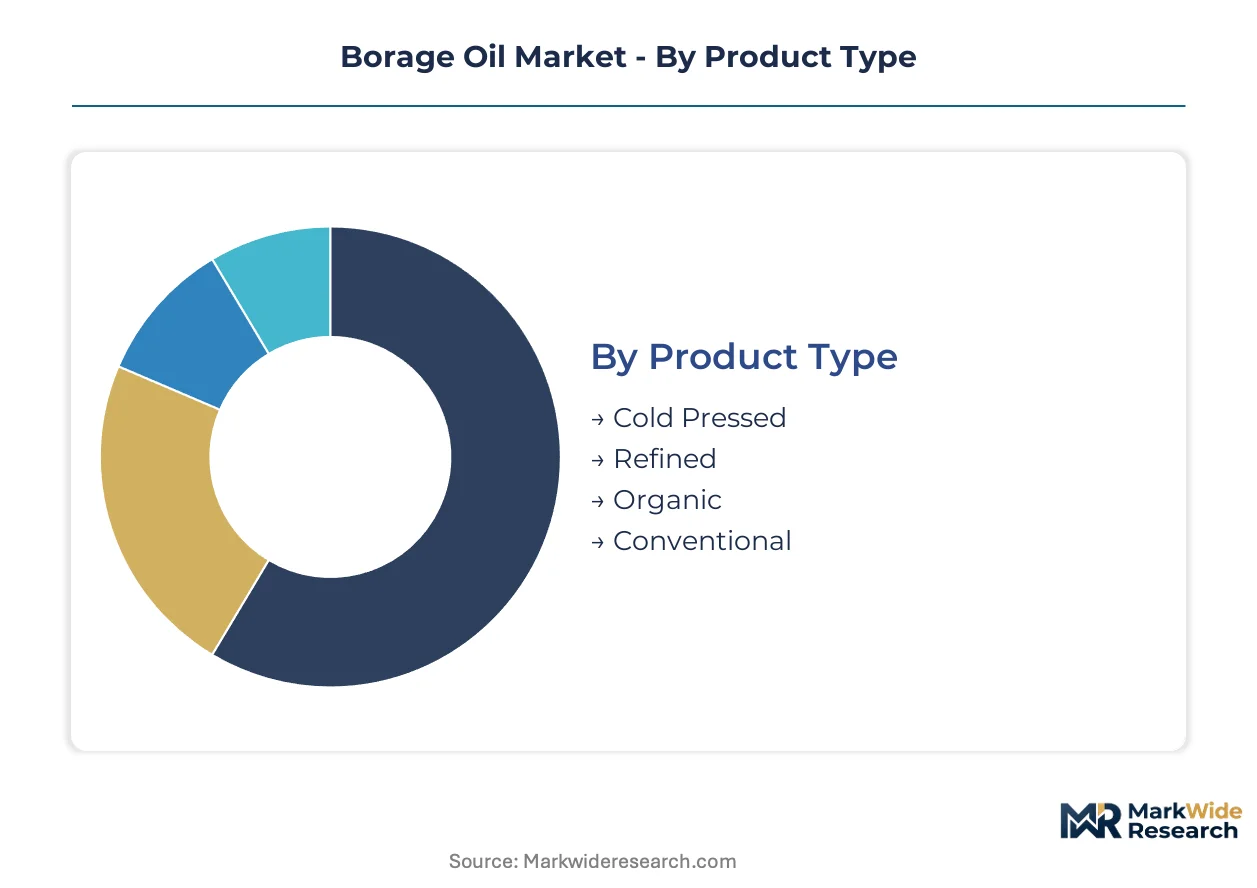
Borage oil procurement patterns diverge sharply across extraction grades and end-use specifications, with certification tiers creating distinct margin pools that reshape supplier competitiveness. Understanding these segment boundaries reveals where cold-pressed organic capacity concentrates versus where solvent-extracted volumes compete on cost.
Product Type:
Supply concentration in cold-pressed extraction capacity creates tiered availability constraints across European dermo-cosmetic supply chains, while organic certification timelines strain cultivator working capital.
- Cold Pressed:Mechanical extraction at temperatures below 40°C preserves phytosterol integrity and delivers the oxidative stability German cosmetic houses demand for premium facial oil formulations. Demand concentrates in Stuttgart and Hamburg, where certified organic cold-pressed grades command three-year offtake contracts from dermo-cosmetic brands seeking EU Green Deal compliance.
- Organic:Certified Borago officinalis cultivation requires three-year conversion periods and blockchain-verified seed-to-oil traceability, creating captive supply relationships between Indian agricultural cooperatives and Nordic supplement brands. REACH residue thresholds and ECHA allergen labeling requirements absorb the highest compliance costs through dedicated batch testing.
- Refined:Solvent-extracted grades undergo degumming, neutralization, and bleaching to achieve pharmaceutical-grade GLA standardization for dietary supplement concentrates.
- Conventional:Non-certified cultivation serves cost-sensitive food-grade applications and mid-tier cosmetic formulations with lower phytosterol retention requirements.
Today's leader: Cold Pressed. Tomorrow's challenger: Organic.
Application:
Cost tier stratification separates premium cosmetic positioning from commodity food-grade procurement, with pharmaceutical validation creating a distinct value band.
- Cosmetics:German and French dermo-cosmetic houses drive specification demand for cold-pressed organic grades in barrier-repair serums and anti-inflammatory facial oils, with phytosterol content serving as the key differentiator against evening primrose oil substitution.
- Dietary Supplements:GLA concentrates for atopic dermatitis and hormonal balance protocols are climbing the fastest as clinical validation accumulates, with North American brands pulling supercritical CO2-extracted grades into premium anti-inflammatory stacks.
- Pharmaceuticals:EMA herbal medicinal product guidelines consolidate procurement around pharmacopeial-compliant refiners capable of contaminant-free GLA standardization for prescription-grade formulations.
- Food:GRAS-status borage oil incorporation into functional food products remains structurally smaller, constrained by taste profile limitations and competing omega-3 sources.
Cosmetics commands current margin premiums. Dietary Supplements shows steepest expansion trajectory.
Packaging Type:
Volume concentration in bulk pharmaceutical procurement contrasts with unit-dose premiumization in direct-to-consumer channels.
- Bulk Containers:200-liter drums and IBC totes dominate pharmaceutical and dietary supplement manufacturing inputs, with nitrogen-flushed specifications preserving GLA potency through extended supply chains.
- Bottles:Amber glass and UV-protective PET formats serve retail cosmetic positioning, with German brands specifying pump-dispense designs for oxidation-sensitive facial oil applications.
- Jars:Wide-mouth containers accommodate balm and salve formulations in artisanal personal care segments.
- Tetra Paks:Aseptic cartons remain experimental for food-grade liquid supplement delivery, constrained by oil compatibility with laminated packaging barriers.
Bulk Containers anchor industrial procurement. Bottles capture retail premium extraction.
End User:
Customer type maturity separates established cosmetic house specifications from emerging veterinary and pet nutrition demand.
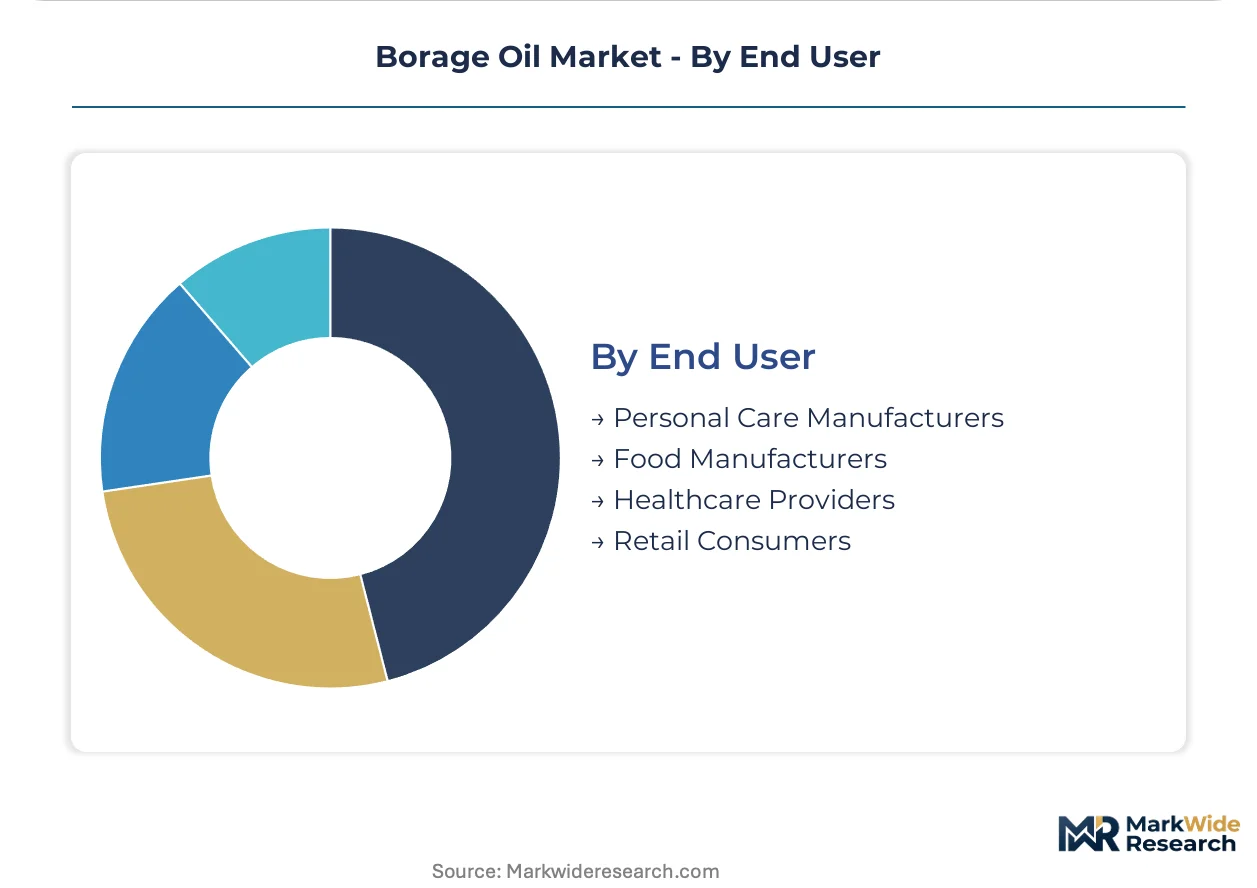
- Personal Care Manufacturers:L'Oréal, Beiersdorf, and Indie Lee specify cold-pressed organic grades with phytosterol certificates, integrating borage oil into clean-label barrier-repair lines for eczema-prone skin positioning.
- Food Manufacturers:Functional food and beverage brands incorporate refined borage oil into omega-fortified products, constrained by GRAS dosage limitations and competing flaxseed oil cost structures.
- Healthcare Providers:Dermatology clinics and integrative medicine practices prescribe pharmaceutical-grade GLA concentrates for atopic dermatitis protocols, with EMA compliance requirements filtering supplier eligibility.
- Retail Consumers:Direct-to-consumer channels through Sephora, Whole Foods, and specialty apothecaries drive small-format organic bottle demand, with transparency requirements pushing blockchain-verified origin claims.
Personal Care Manufacturers dominate current procurement. Healthcare Providers represent emerging prescription-grade volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borage oil commercialization traces its industrial roots to post-war European botanical extraction, with German cold-press refiners establishing quality benchmarks that persist in today's dermo-cosmetic supply chains.
Germany
Stuttgart and Hamburg harbor Europe's densest cold-pressed borage oil refining capacity, serving L'Oréal and Beiersdorf with certified organic grades. EU Green Deal sustainable sourcing mandates compress procurement timelines for traceable botanical oils. The Baden-Württemberg cluster anchors premium extraction infrastructure for pharmaceutical-grade GLA standardization.
United States
California dietary supplement brands and New Jersey-based toll refiners pull GLA concentrates into anti-inflammatory and hormonal balance formulations. FDA GRAS status governs food and supplement incorporation, while California's Proposition 65 drives contaminant testing investment. The Pacific Northwest hosts emerging organic cultivation trials for captive seed supply.
India
Gujarat and Madhya Pradesh agricultural cooperatives supply raw Borago officinalis seeds to international refiners, with monsoon-dependent yields creating export volatility. FSSAI food safety standards and DGFT export tariff structures shape outbound logistics. The Indore-Ratlam corridor concentrates solvent-extraction capacity for refined grades.
France
Paris-based dermo-cosmetic houses specify cold-pressed organic borage oil for barrier-repair serums targeting eczema-prone skin positioning. ANSM cosmetic safety guidelines and CNIL data governance requirements apply to blockchain-verified traceability systems. The Provence-Alpes-Côte d'Azur region trials lavender-adjacent organic cultivation for co-branding premiums.
United Kingdom
London-headquartered indie personal care brands and Manchester supplement distributors source cold-pressed grades for clean-label positioning. MHRA herbal medicine regulations align with EMA quality thresholds for pharmaceutical-grade procurement. The Southeast England logistics corridor handles bulk pharmaceutical drum imports for contract manufacturing.
Borage Oil Market Key Industry Players
Premium-margin players sit above commodity-margin players across extraction-grade certification tiers, with cold-pressed organic capacity commanding three-year offtake premiums against solvent-extracted commodity volumes. The supplier base stratifies into integrated cultivator-refiners with captive Indian seed networks, German cold-press specialists serving cosmetic houses, and North American toll refiners competing on flexible batch sizes. Three archetypes dominate: traceability-integrated agricultural cooperatives, pharmacopeial-certified extraction houses, and formulation-ready concentrate blenders. Competitive moves concentrate on multi-year direct contracting with organic cultivators and supercritical CO2 capacity installation for pharmaceutical-grade positioning.
Among integrated cultivator-refiners, AOS Products Pvt. Ltd. represents the archetype of backward-controlled Indian seed supply for international refiners. Gustav Heess GmbH anchors the premium cold-pressed extraction tier with German pharmacopeial compliance capabilities. ConnOils LLC occupies a position within North American toll-refining services for dietary supplement brands seeking flexible GLA concentrate procurement.
| Leading Market Players |
|---|
| AOS Products Pvt. Ltd. |
| ConnOils LLC |
| Premium Crops |
| Aromex Industry |
| Icelandirect LLC |
| Avestia Pharma |
| Gustav Heess GmbH |
| Soyatech International |
| Parchem Fine & Specialty Chemicals |
| Others |
Cost & Logistics Intelligence
Cold-pressed organic certification creates a three-tier pricing structure across premium, standard, and economy levels, compressing margin pools for solvent-extracted commodity grades while concentrating procurement power among German dermo-cosmetic houses and Nordic supplement brands with multi-year offtake mandates. EU Green Deal traceability requirements and REACH residue thresholds absorb compliance costs unevenly, forcing backward integration investments that reshape supplier competitiveness across extraction-grade categories.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical and cosmetic procurement, with price differentiation driven by organic certification status and phytosterol content verification. Cost compression in refined solvent-extracted grades intensifies because evening primrose oil substitution erodes borage oil positioning in mid-tier supplement stacks. Dietary supplement manufacturers exhibit highest price sensitivity, while German dermo-cosmetic houses tolerate premium positioning for blockchain-verified cold-pressed organic supply.
Supply Chain Analysis
Dual-sourcing requirements from EU cosmetic houses and North American supplement brands mandate qualified supplier networks spanning Indian seed cooperatives, German cold-press refiners, and North American toll processors. Raw Borago officinalis cultivation draws from Gujarat and Madhya Pradesh agricultural networks, with supercritical CO2 extraction equipment sourced from German and Italian engineering specialists. Monsoon-dependent yield volatility in India creates single-source vulnerability for international refiners lacking captive cultivation. Distribution runs through nitrogen-flushed bulk pharmaceutical drums for industrial buyers and amber glass retail bottles for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The borage oil market functions as a geographic-arbitrage play where EU regulatory compliance costs exceed Indian cultivation economics by margins sufficient to justify integrated seed-to-oil investments across continents.
For Market Incumbents: Anticipate supercritical CO2 extraction convergence by securing pharmacopeial-grade capacity ahead of EMA herbal medicinal product guideline tightening. Defensive consolidation moves center on captive organic cultivation in India to offset seed supply concentration risk, and in-house analytical chemistry capabilities to resolve batch-to-batch phytosterol variability. Evening primrose oil substitution pressure demands premium cold-pressed positioning reinforcement through blockchain-verified traceability systems. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable entry vector for clean-label pet nutrition formulations, where GLA inclusion in veterinary dermatological applications faces lower regulatory barriers than human pharmaceutical grades. White-space targets include supercritical CO2-extracted concentrates for North American anti-inflammatory supplement stacks, and co-branded organic cultivation in Provence-adjacent French regions for cosmetic house supply. Go-to-market execution should leverage pilot-scale toll-refining partnerships to bypass three-year organic certification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where CSRD-driven traceability mandates exceed working capital capacity of mid-tier Indian agricultural cooperatives. Long-term viability across the analysis window favors integrated cultivator-refiners with captive seed networks and pharmacopeial-certified extraction infrastructure. Acquisition target archetype: German cold-press specialists with EMA compliance capabilities and established offtake relationships with L'Oréal or Beiersdorf. Signal to watch: accelerating direct contracting between California supplement brands and Indian organic cooperatives bypassing traditional broker networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive Borago officinalis supply in India mitigates monsoon yield volatility for EU cosmetic house contracts. |
| Supercritical CO2 Capacity Installation | Contaminant-free GLA concentrates open pharmaceutical-grade positioning beyond cold-press thermal limitations. |
| Blockchain-Verified Traceability Implementation | CSRD compliance creates first-mover advantage for seed-to-oil chain transparency in German dermo-cosmetic procurement. |
| Clean-Label Pet Nutrition Formulation Partnership | Veterinary dermatological GLA applications penetrate underdeveloped channels with lower FDA regulatory barriers. |
| Pharmacopeial Certification Investment | EMA herbal medicinal product compliance filters supplier eligibility for prescription-grade borage oil procurement. |
Research Approach
Direct dialogue with extraction technology engineers, organic certification auditors, dermo-cosmetic procurement directors, and Indian agricultural cooperative managers grounded qualitative assessment in operational realities across the value chain. Secondary validation drew from EMA herbal medicinal product guidelines, REACH substance evaluation databases, FSSAI food safety standards, and EU Green Deal sustainable sourcing mandate documentation. Bottom-up seed supply modeling and top-down end-use demand estimation were cross-referenced through triangulation.
Bottom-up volume constructs aggregated cultivation acreage estimates, yield coefficients, and extraction recovery rates across cold-pressed, solvent-extracted, and supercritical CO2 grades. Top-down demand calibration applied patient population sizing for atopic dermatitis protocols and cosmetic formulation intensity assumptions. Segmentation dimensions spanned extraction technology, certification tier, application category, and regional regulatory cluster. CAGRs emerged from logistic diffusion curves fitted to historical adoption patterns and policy implementation timelines.
Monsoon failure severity, EMA guideline acceleration, and evening primrose oil price competitiveness are the dominant revision risks embedded in the forecast framework. Deviation in Indian agricultural output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carrot Fiber Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
High Protein Flour Market
Ingredients
Chickpea Fiber Market
Ingredients
Horehound Extract Market
Ingredients
Global Tomato Powder Market
Ingredients
India Soy Protein Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Gum Arabic Market
Ingredients
Bread Flour Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Camelina Oil Market
Ingredients
Potato Protein Market