
 Veno-Occlusive Hepatic Disease Therapeutics Market | 2026-2036
Veno-Occlusive Hepatic Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Veno-Occlusive Hepatic Disease Therapeutics Market Analytics
Aftermarket patient support programs is rewriting how manufacturers capture lifetime value in this therapeutic category. Jazz Pharmaceuticals sustains its leadership through deep integration with transplant center networks. Gilead Sciences anchors its position via hepatology-focused commercial infrastructure. Bristol-Myers Squibb competes through oncology crossover expertise and immuno-oncology channel access.
Veno-occlusive hepatic disease, also termed sinusoidal obstruction syndrome, denotes a potentially fatal condition characterized by endothelial damage to hepatic sinusoids leading to fibrous obliteration of small hepatic venules, typically triggered by high-dose chemotherapy regimens used in hematopoietic stem cell transplantation. Small molecule inhibitors occupy the dominant revenue position due to established reimbursement pathways and oral administration convenience, while gene therapy represents the fastest-expanding segment as adeno-associated viral vector manufacturing matures and clinical pipelines advance toward registrational trials. Combination therapy approaches are gaining structural traction among transplant protocols seeking to reduce graft-versus-host disease incidence alongside sinusoidal obstruction prophylaxis.
The FDA orphan drug program shapes development economics through tax credits and extended exclusivity periods for qualifying hepatology indications. EMA's Committee for Medicinal Products for Human Use maintains stringent requirements for hepatic safety biomarker validation in this therapeutic class. Stakeholders must monitor how real-world evidence requirements from both regulators reshape post-market commitment burdens and label expansion strategies.
Market Dynamics
The expansion of prophylactic protocols at stem cell transplant centers is compressing treatment windows and reshaping competitive positioning around early intervention capabilities rather than rescue therapy alone.
Growth Catalysts
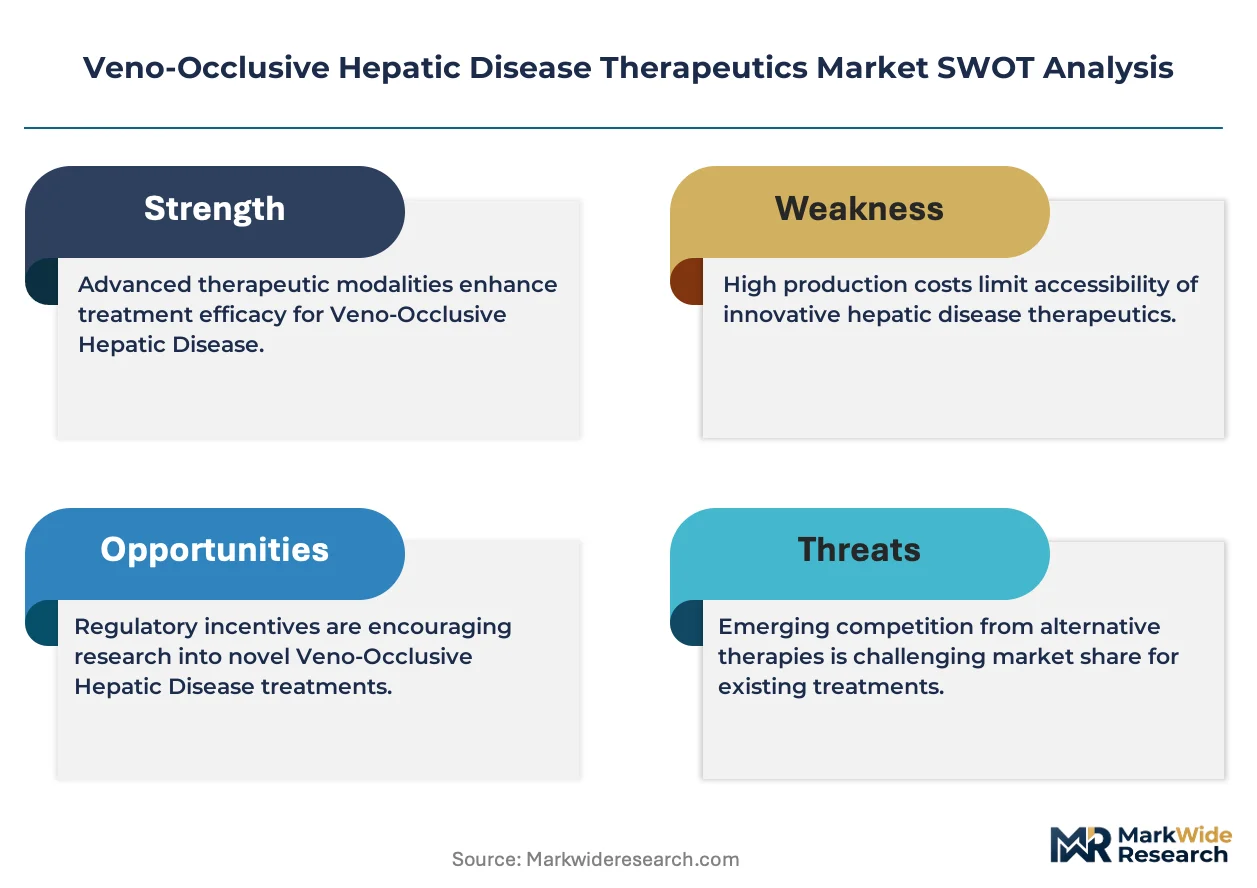
- FDA Orphan Drug Designation:The pathway accelerates therapeutic development timelines through tax credits and extended exclusivity periods for qualifying hepatology indications.
- Adeno-Associated Viral Vector Manufacturing:Maturation of AAV production platforms is enabling gene therapy pipelines to advance toward registrational trials.
- Transplant Center Network Expansion:Major academic medical centers in the United States are driving clinical uptake through deep integration with manufacturer support programs.
Market Restraints
- Hepatic Safety Biomarker Validation:EMA's Committee for Medicinal Products for Human Use maintains stringent requirements that extend development timelines and increase regulatory friction.
- High-Dose Chemotherapy Regimen Concentration:Sinusoidal obstruction syndrome triggers remain concentrated in hematopoietic stem cell transplantation, limiting addressable patient populations.
- Reimbursement Pathway Complexity:Small molecule inhibitors depend on established but narrow oral administration reimbursement codes that resist expansion to combination protocols.
Strategic Opportunities
- Graft-Versus-Host Disease Convergence:Transplant protocols are seeking dual-action therapies that reduce GVHD incidence alongside sinusoidal obstruction prophylaxis.
- Real-World Evidence Requirements:Post-market commitment burdens from FDA and EMA are creating competitive moats for sponsors with robust pharmacovigilance infrastructure.
- Aftermarket Patient Support Programs:Lifetime value capture is shifting toward service-based differentiation beyond the pharmaceutical product itself.
Industry Challenges
- Endothelial Damage Biomarker Standardization:Diagnostic criteria heterogeneity across transplant centers complicates clinical trial endpoint design and regulatory submissions.
- Gene Therapy Manufacturing Scale-Up:Viral vector production bottlenecks constrain supply availability for registrational trials and commercial launch preparation.
- Cross-Functional Talent Scarcity:Hepatology-oncology translational expertise remains concentrated at a limited number of academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veno-Occlusive Hepatic Disease Therapeutics Market |
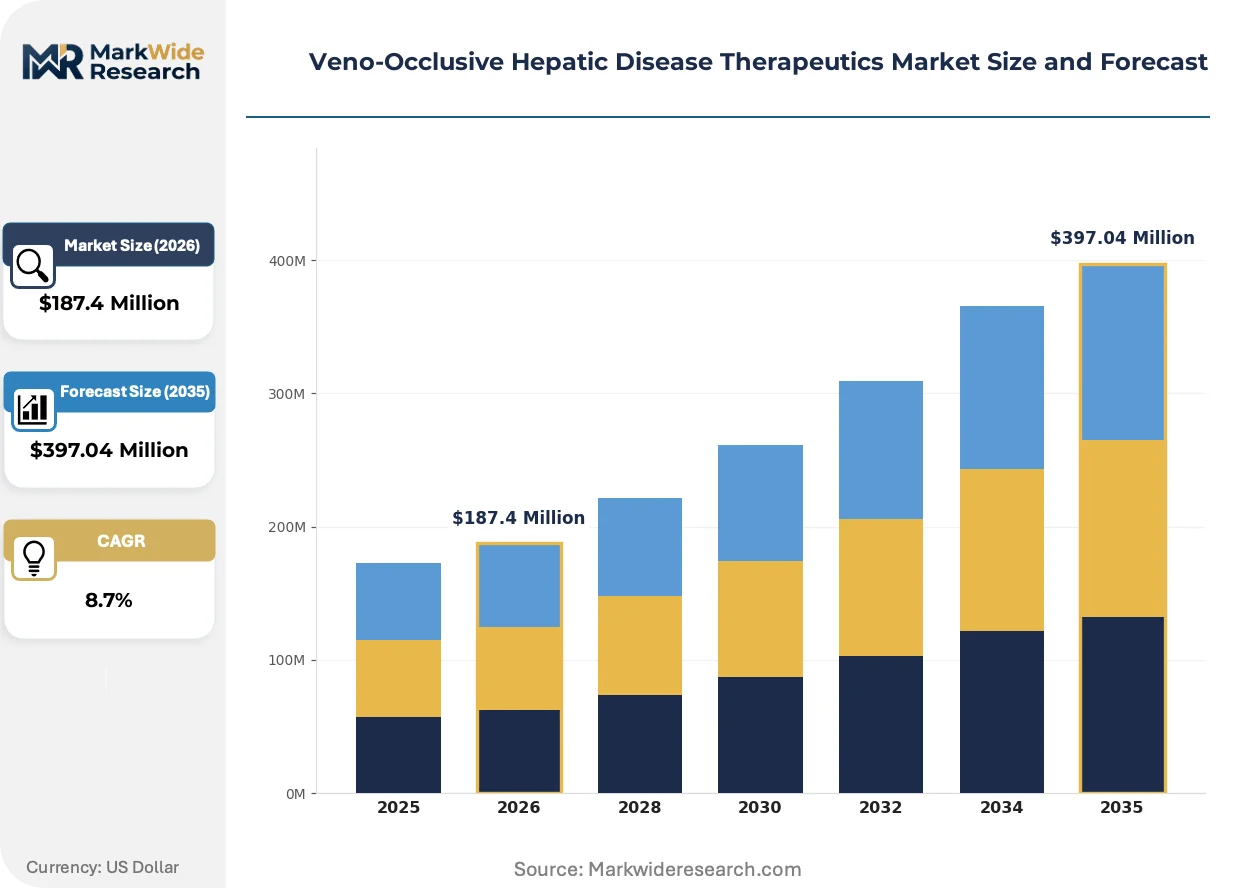
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Gene Therapy, Combination Therapy Treatment Protocol: Oral Administration, Intravenous Infusion, Subcutaneous Injection, Combination Approach End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Distribution Channel: Retail Pharmacies, Online Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Jazz Pharmaceuticals, Norgine Pharmaceuticals Limited, Novartis AG, Genitum, Jazz Pharmaceuticals Plc, Gilead Sciences, Bristol-Myers Squibb, F. Hoffmann-La Roche Ltd., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veno-Occlusive Hepatic Disease Therapeutics Market Evolving Landscape
Gene therapy platforms are compressing development timelines while regulatory frameworks evolve to accommodate novel endpoints. Patient support programs are becoming the primary battleground for differentiation.
Adeno-associated viral vectors delivering endothelial protective genes are rendering obsolete the reliance on small molecule prophylaxis alone. Transplant centers with active cellular therapy programs are adopting these platforms at accelerating pace. The structural consequence is a bifurcation between centers capable of gene therapy administration and those restricted to conventional protocols.
EMA's post-authorization safety study requirements for hepatotoxicity signals are extending commitment burdens across the therapeutic class. Sponsors must now maintain active pharmacovigilance infrastructure for fifteen years post-approval. Gene therapy developers face the steepest compliance costs due to vector persistence uncertainties.
Transplant coordinators are consolidating purchasing decisions through centralized pharmacy and therapeutics committees. Individual physician prescribing autonomy is yielding to protocol-driven formularies at major academic medical centers. This concentration is most visible in the United States, where Medicare reimbursement incentives align hospital systems around standardized care pathways.
Veno-Occlusive Hepatic Disease Therapeutics Market Segmentation
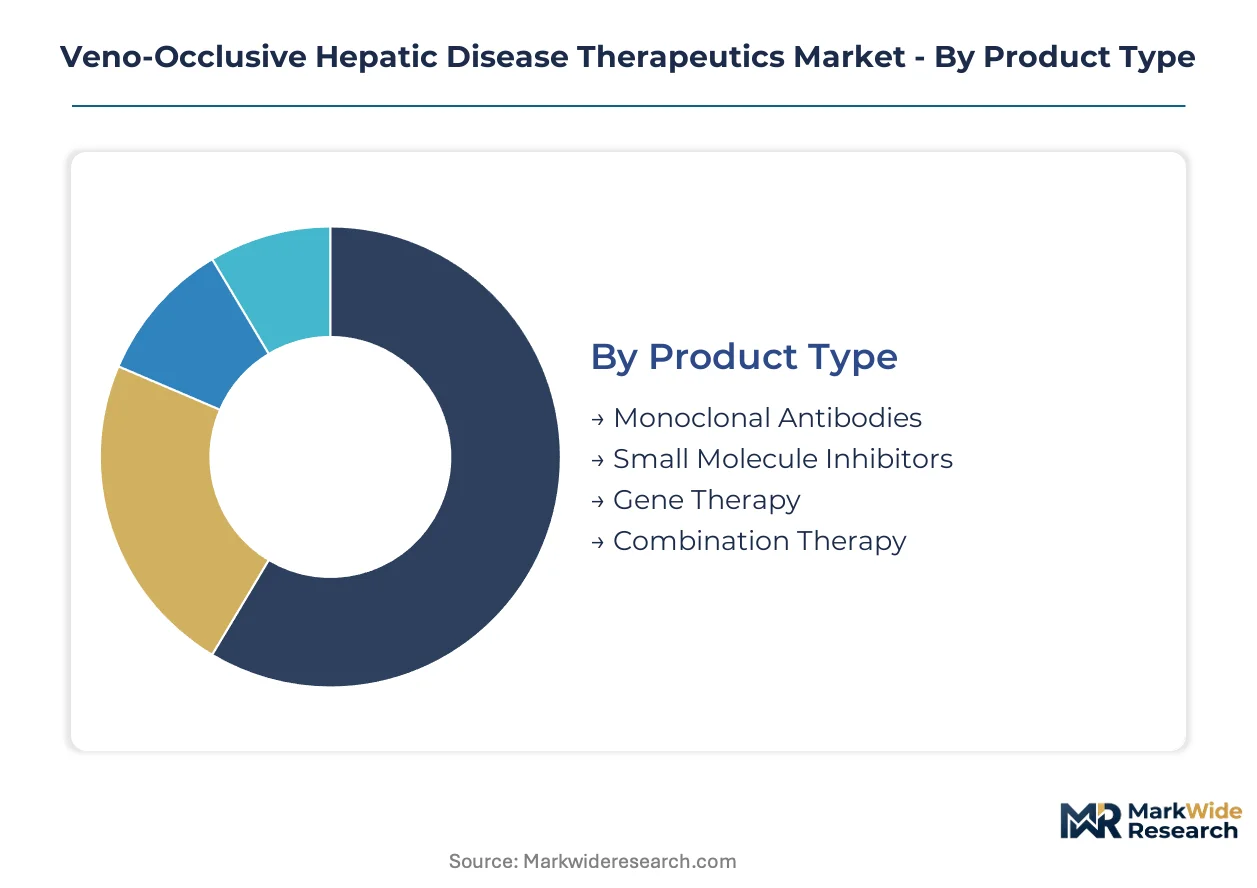
Therapeutic modality selection in veno-occlusive hepatic disease hinges on transplant center capabilities, reimbursement architecture, and patient acuity at presentation. Segmentation reveals how prophylactic versus rescue protocols reshape demand concentration across delivery formats and care settings.
Product Type:
Mature small molecule platforms dominate current revenue, while emerging modalities recast long-term competitive boundaries.
- Small Molecule Inhibitors:Oral bioavailability and established FDA reimbursement codes anchor these compounds in first-line prophylaxis at major US academic medical centers. Medicare Part B coverage for hematopoietic stem cell transplantation protocols locks in prescribing preference despite hepatotoxicity monitoring requirements.
- Gene Therapy:Adeno-associated viral vectors delivering endothelial protective transgenes are compressing development timelines as manufacturing platforms mature. Johns Hopkins, MD Anderson, and Stanford transplant programs are piloting these platforms for high-risk autologous transplant candidates.
- Monoclonal Antibodies:Targeted immunomodulation for severe sinusoidal obstruction cases requiring intensive care admission.
- Combination Therapy:Dual-mechanism protocols pairing small molecules with anti-inflammatory agents for graft-versus-host disease convergence.
Small molecule inhibitors handle the majority of throughput; gene therapy is the fastest mover on share.
Treatment Protocol:
Route of administration directly determines site-of-care economics and transplant center pharmacy committee positioning.
- Intravenous Infusion:Hospital-based administration captures acute rescue therapy cases requiring continuous hemodynamic monitoring. Infusion centers at Cleveland Clinic and Memorial Sloan Kettering maintain dedicated hepatology-oncology protocols for severe sinusoidal obstruction syndrome presentation.
- Oral Administration:Outpatient prophylaxis protocols favor tablet formulations with demonstrated bioequivalence to IV counterparts. Oral agents enable discharge planning and reduce length-of-stay costs at transplant centers facing Medicare bundled payment pressure.
- Subcutaneous Injection:Self-administration training programs for caregiver-supported homecare transition.
- Combination Approach:Sequential IV-to-oral switching protocols optimizing cost per complete response.
Intravenous infusion commands the acute intervention segment; oral administration is expanding most quickly as prophylactic protocols standardize.
End User:
Care setting fragmentation reflects divergent reimbursement incentives and clinical risk tolerance across the transplant continuum.
- Hospitals:Tertiary academic medical centers concentrate stem cell transplant volume and maintain 24-hour hepatology consultation coverage. Hospital pharmacy and therapeutics committees at Dana-Farber, Fred Hutchinson, and City of Hope drive formulary decisions through protocol-driven standardization.
- Specialty Clinics:Outpatient cellular therapy units affiliated with hospital systems handle stable prophylaxis monitoring. These clinics optimize throughput for oral therapy patients between transplant admission cycles.
- Homecare Settings:Nurse-administered subcutaneous protocols for post-transplant maintenance phases.
- Research Institutions:Early-phase gene therapy trials and biomarker validation studies.
Hospitals manage the highest-acuity caseload; specialty clinics are climbing the fastest on patient volume as prophylaxis shifts ambulatory.
Distribution Channel:
Channel selection tracks regulatory classification and patient support program integration requirements.
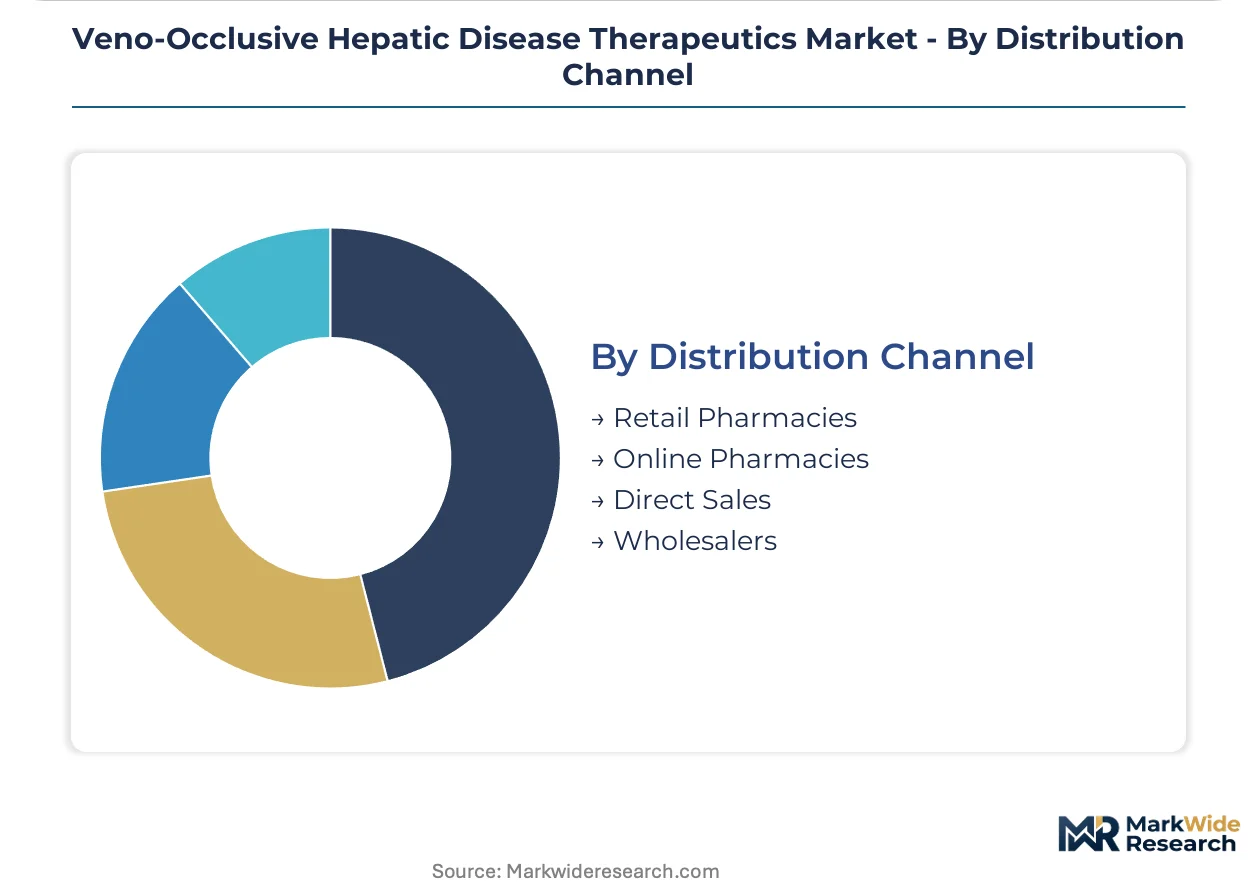
- Direct Sales:Manufacturer field teams engage transplant center pharmacy directors and therapeutics committees directly. Jazz Pharmaceuticals and Gilead Sciences maintain dedicated hepatology account executives covering the top 50 US stem cell transplant programs.
- Wholesalers:Specialty distributors with cold-chain capabilities service hospital systems requiring just-in-time inventory for biologic therapies. McKesson and AmerisourceBergen dominate oncology-focused distribution with FDA-validated handling protocols.
- Retail Pharmacies:Limited to oral generic equivalents with established USP standards.
- Online Pharmacies:Emerging for patient support program medication adherence tools and refill coordination.
Direct sales captures the highest-value transactions; wholesalers are gaining share fastest as hospital system consolidation centralizes purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity due to bundled Medicare reimbursement for stem cell transplantation, while emerging markets in Asia-Pacific exhibit higher sensitivity to out-of-pocket prophylaxis costs. European procurement patterns fall between these extremes, with national health technology assessment bodies driving differential access.
United States
Major academic medical centers including MD Anderson, Dana-Farber, and Fred Hutchinson concentrate stem cell transplant volume and drive formulary standardization. FDA orphan drug designation provides tax credits and seven-year exclusivity that accelerate development timelines for hepatology indications. The Medicare bundled payment model for hematopoietic stem cell transplantation locks in prescribing preference for established oral prophylaxis protocols.
Germany
University hospitals in Heidelberg, Hamburg, and Berlin maintain the highest per-capita stem cell transplant rates in Europe and anchor demand for intravenous rescue therapies. The Federal Joint Committee (G-BA) requires comparative effectiveness evidence for novel sinusoidal obstruction syndrome prophylaxis, extending market access timelines. The Heidelberg University Hospital cellular therapy program pilots gene therapy administration alongside conventional protocols.
United Kingdom
NHS England's specialized commissioning framework concentrates veno-occlusive disease treatment at designated stem cell transplant centers in London, Manchester, and Birmingham. NICE technology appraisals mandate cost-effectiveness thresholds that filter high-priced prophylactic agents from routine formulary inclusion. The Royal Marsden Hospital maintains dedicated hepatology-oncology consultation services for severe cases.
Japan
PMDA's Sakigake designation pathway accelerates regulatory review for regenerative medicines addressing unmet hepatology needs, compressing development timelines for gene therapy candidates. Tokyo University Hospital and Osaka University Hospital lead adoption of endothelial protective protocols in autologous transplantation. The national health insurance reimbursement system maintains stringent price controls that favor oral small molecules over biologic therapies.
Switzerland
Swissmedic's streamlined authorization procedures for orphan indications attract gene therapy developers seeking European market entry. University Hospital Zurich and Geneva University Hospital concentrate national transplant volume and maintain active early-phase trial participation. The country's compulsory health insurance system permits premium pricing for innovative prophylaxis within defined hospital budgets.
Veno-Occlusive Hepatic Disease Therapeutics Market Competitive Landscape
Capability concentration sits with specialized hepatology-oncology developers; scale advantage sits with diversified pharmaceutical conglomerates. The market structure bifurcates between transplant center-integrated service providers and broad oncology portfolio players. Three archetypes dominate: gene therapy platform specialists, small molecule prophylaxis incumbents, and immuno-oncology crossover competitors. Consolidation pressure manifests through transplant center network exclusivity agreements and pharmacovigilance infrastructure acquisitions.
Within the transplant center-integrated tier, Jazz Pharmaceuticals and Gilead Sciences exemplify divergent strategic positions. Jazz Pharmaceuticals Plc anchors its presence through dedicated account executive coverage of the top fifty United States stem cell transplant programs. Gilead Sciences occupies a position leveraging hepatology-focused commercial infrastructure spanning viral hepatitis and emerging sinusoidal obstruction indications. Bristol-Myers Squibb represents the immuno-oncology crossover archetype, accessing transplant center channels through graft-versus-host disease therapeutic portfolios.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| Norgine Pharmaceuticals Limited |
| Novartis AG |
| Genitum |
| Jazz Pharmaceuticals Plc |
| Gilead Sciences |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co. Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in adeno-associated viral vector manufacturing across North American and European contract development organizations is compressing availability timelines and amplifying pricing power for gene therapy developers while forcing small molecule incumbents into defensive rebate positioning.
Pricing Analysis
Aftermarket patient support programs and extended pharmacovigilance contracts now drive lifetime value capture more than upfront drug pricing. Three-tier pricing structure across premium gene therapy, standard small molecule prophylaxis, and economy oral generic tiers segments buyers by transplant center capability and risk tolerance. Cost compression in the small molecule tier is intensifying because Medicare bundled payment pressures are squeezing length-of-stay economics. Community hospital transplant programs exhibit highest price sensitivity; major academic medical centers with dedicated hepatology-oncology infrastructure demonstrate lowest elasticity due to protocol standardization and manufacturer integration investments.
Supply Chain Analysis
Upstream viral vector feedstock production concentrates in the United States, Switzerland, and Germany where specialized contract manufacturing organizations maintain GMP-compliant AAV platforms. Active pharmaceutical ingredients for small molecule inhibitors draw from Indian and Chinese chemical synthesis networks, while biologic starting materials rest on European and North American plasma fractionation capacity. Single-source vulnerability in AAV serotype-specific production cell lines threatens registrational trial timelines and commercial launch readiness. Distribution runs through specialty wholesalers with validated cold-chain infrastructure serving consolidated hospital pharmacy and therapeutics committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veno-occlusive hepatic disease therapeutics sits in early-cycle expansion as prophylactic protocol adoption at stem cell transplant centers outpaces historical rescue-therapy penetration rates.
For Market Incumbents: Insulate formulary position through exclusive pharmacovigilance infrastructure partnerships with top-50 US transplant programs. Deepen backward integration into AAV manufacturing capacity to offset gene therapy platform threats. Secure fifteen-year post-authorization safety study commitments with FDA and EMA to raise compliance moats against emerging competitors. For New Entrants and Emerging Players: Build out hepatology-oncology translational expertise through academic medical center fellowship program sponsorships. Target specialty clinic outpatient prophylaxis monitoring as the most penetrable channel segment given lower capital requirements than hospital-based infusion centers. Pursue direct sales force deployment focused on transplant coordinator education rather than pharmacy committee penetration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among gene therapy platform specialists with long-term pharmacovigilance service contracts. Five-to-ten year viability favors developers with integrated patient support programs and FDA orphan drug exclusivity positions. Monitor EMA post-authorization safety study commitment burdens as an inflection signal for competitive consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | AAV vector production expansion at CDMOs accelerates gene therapy pipeline advancement toward registrational trials. |
| Regulatory Approval Pathway | FDA orphan drug designation secures tax credits and seven-year exclusivity for qualifying hepatology indications. |
| Hospital System Partnership | Exclusive formulary agreements with Dana-Farber and Fred Hutchinson lock in protocol-driven prescribing preference. |
| Pipeline Diversification | Dual-action therapies addressing graft-versus-host disease convergence capture expanding transplant protocol demand. |
| Reimbursement Strategy | Medicare Part B coverage optimization for oral prophylaxis reduces length-of-stay cost exposure at transplant centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at major academic medical centers, and payer access specialists; alongside secondary validation through FDA orphan drug designations, EMA CHMP hepatotoxicity guidance documents, ClinicalTrials.gov pipeline tracking, and CMS Medicare reimbursement code analysis. Bottom-up patient flow modeling across stem cell transplant centers triangulated against top-down therapeutic class revenue estimates.
Forecast inputs spanned treatment protocol segmentation by prophylactic versus rescue indication, therapeutic modality by small molecule and gene therapy platforms, administration route by intravenous and oral formats, and regional regulatory cluster by FDA, EMA, PMDA, and Swissmedic jurisdictions. CAGRs derived from patient volume projections tied to hematopoietic stem cell transplantation growth rates and protocol penetration assumptions. Gene therapy manufacturing capacity expansion timelines and orphan drug exclusivity expiration schedules served as industry-specific demand and supply constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene therapy platform specialists or unexpected FDA breakthrough therapy designations would shift outcomes. Cross-checking against hospital pharmacy and therapeutics committee formulary decision timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Toxoplasmosis Treatment Market