
 Bread and Baked Food Market | 2026-2036
Bread and Baked Food Market Size, Share, and Industry Trends Forecast 2026-2036
Bread and Baked Food Market Analysis
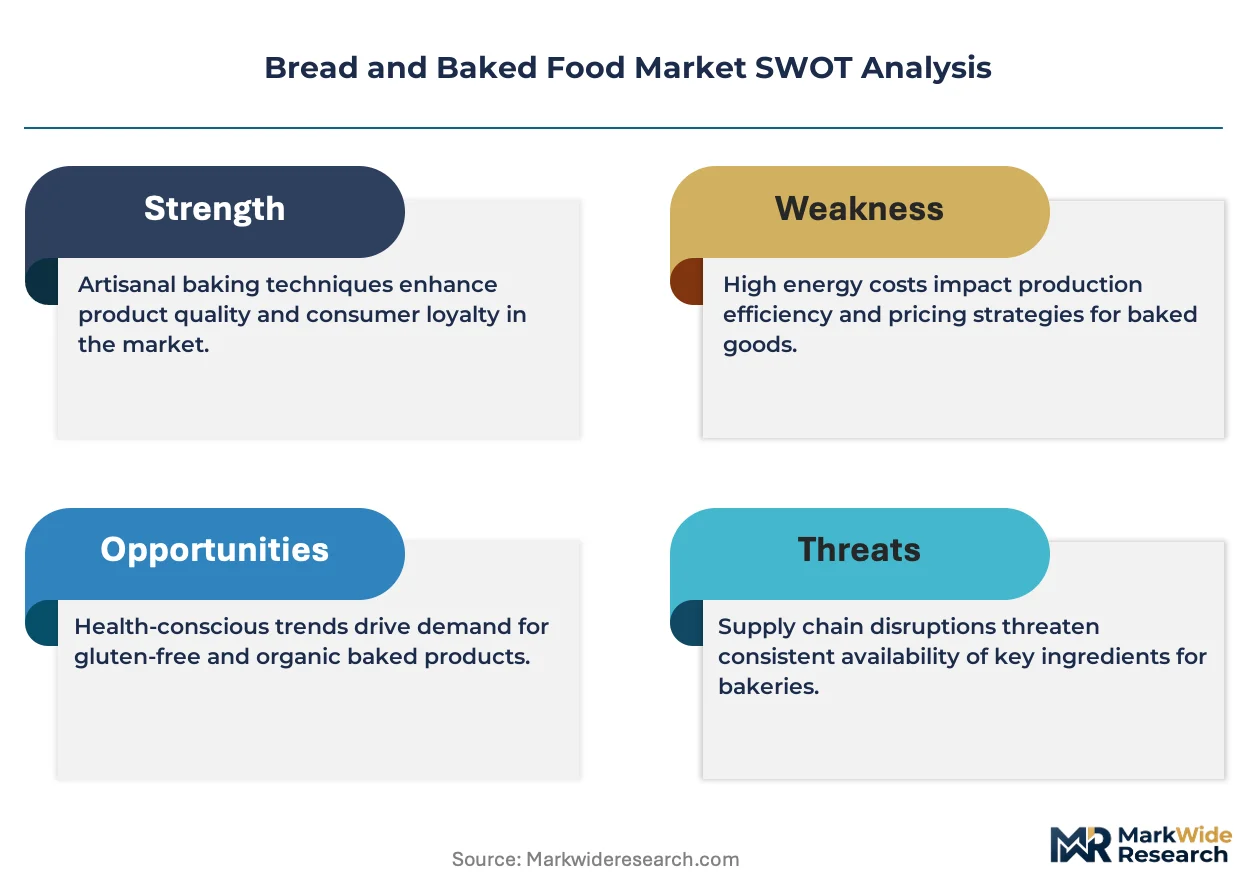
EU Green Deal is restructuring the cost-of-entry calculus for European baked goods producers, forcing reformulation investments and carbon accounting across supply chains. Grupo Bimbo leverages its vertically integrated flour milling network to absorb these compliance costs without margin erosion. Yamazaki Baking anchors its position through R&D intensity in enzyme-based shelf-life extension. Flowers Foods competes via hyper-regional brand portfolios that dominate the southeastern United States.
Bread and baked food comprises cereal-based products manufactured through fermentation, thermal processing, and controlled moisture management, typically containing 35-45% water content and achieving specific loaf volume through gluten network development. The category serves as a dietary staple, convenience meal component, and foodservice input across retail and institutional channels. Bread holds mature volume leadership in developed economies where per-capita consumption exceeds forty kilograms annually, while pastries and cakes capture faster growth in emerging markets driven by café culture expansion. The frozen form segment attracts capital as industrial bakeries seek to decouple production from distribution through blast-freezing and par-bake technologies.
FDA food safety modernization rules in the United States, EFSA nutrition and health claims protocols in Europe, and FSSAI fortification mandates in India collectively reshape product standards and market access conditions across major producing regions. These frameworks elevate compliance costs for smaller operators while creating certification-based differentiation for scaled manufacturers. Stakeholders must monitor evolving front-of-pack labeling requirements and carbon disclosure rules as these become decisive factors in retail listing negotiations and consumer preference formation.
Market Dynamics
EU Green Deal carbon accounting mandates are restructuring capital allocation across European flour milling and thermal processing infrastructure, forcing producers to embed emissions tracking from farm gate through retail shelf.
Growth Catalysts
- Par-bake freezing technology:Industrial bakeries deploy blast-freezing systems to decouple production peaks from distribution constraints, extending product reach without freshness degradation.
- FSSAI fortification mandates:India's mandatory micronutrient enrichment rules for packaged bread expand addressable demand through nutritional positioning in tier-two and tier-three urban centers.
- Café culture penetration:Emerging-market foodservice channels absorb premium pastry and cake volumes as branded coffee chains establish footprint in Southeast Asian and Latin American metropolitan districts.
Market Restraints
- Wheat price volatility:Input cost swings tied to Black Sea supply disruptions compress margin predictability for non-integrated milling operations.
- Gluten network replication limits:Plant-based protein alternatives fail to achieve equivalent loaf volume and crumb structure in clean-label formulations, constraining substitution elasticity.
- REACH chemical compliance:European enzyme and additive suppliers face extended registration timelines and toxicity testing burdens that delay new ingredient commercialization.
Strategic Opportunities
- Carbon label differentiation:Producers achieving ISO 14067 product carbon footprint verification capture retail listing preference as EU supermarkets implement scope-three disclosure requirements.
- Quick-service restaurant embedded lines:Artisan bread programs integrated into fast-casual menus create captive demand channels with volume commitments and reduced slotting fee exposure.
- Enzyme-based shelf-life extension:R&D convergence of amylase and lipase technologies enables clean-label moisture retention without chemical preservatives, unlocking extended distribution radius for ambient products.
Industry Challenges
- Retrofitting thermal efficiency:Legacy oven infrastructure requires substantial capital redeployment to meet tightening emissions standards under EU Green Deal implementation timelines.
- Traceability system integration:Farm-to-fork data architecture demands interoperability investments across fragmented supplier bases, particularly for cooperative and smallholder flour sourcing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread and Baked Food Market |
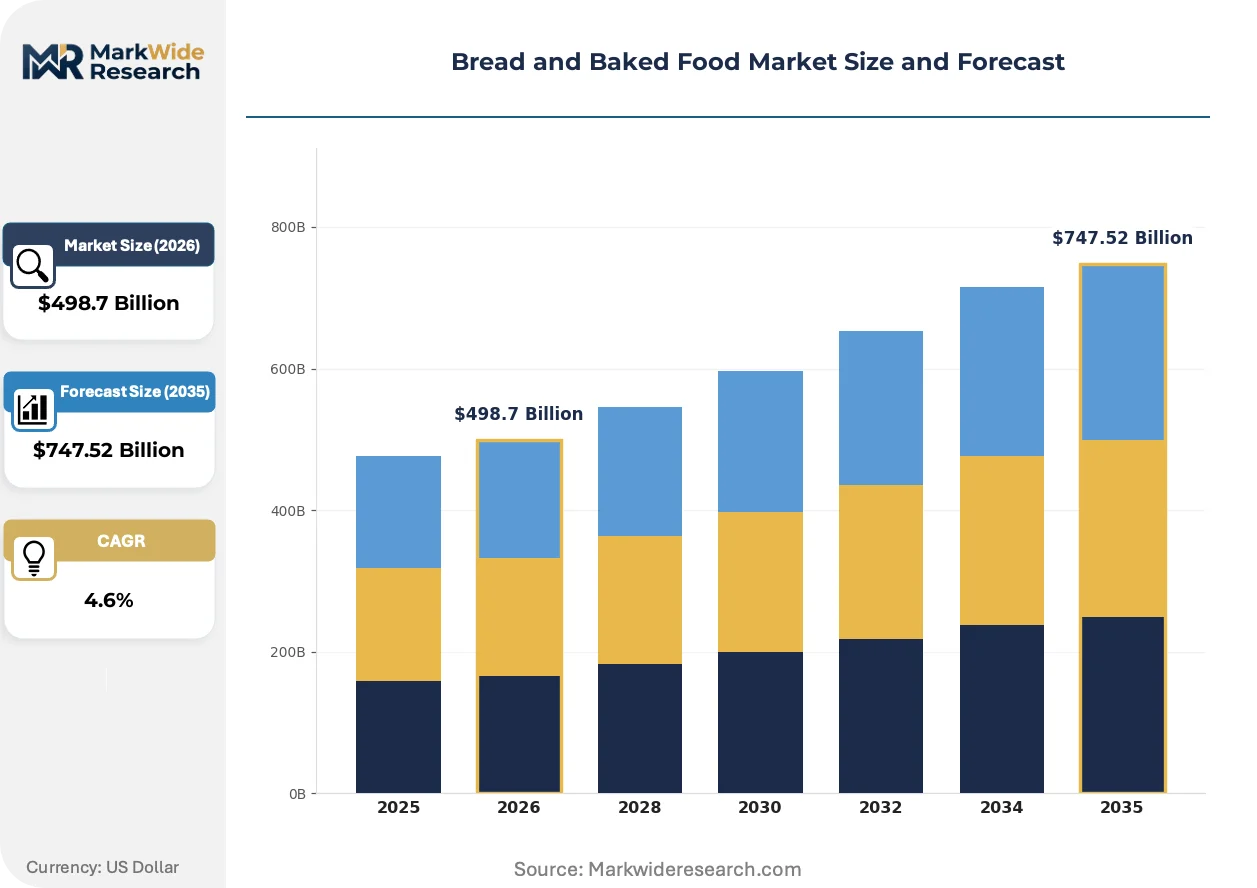
| Market Size in 2026 | $498.7 Billion |
| Market Size in 2035 | $747.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies Form: Frozen, Packaged, Fresh, Organic Sales Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Customer Type: Households, Bakeries, Restaurants, Cafés |
| Companies Covered | Grupo Bimbo, Mondelez International, Flowers Foods, Associated British Foods, General Mills, Yamazaki Baking, Britannia Industries, Aryzta AG, Premier Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread and Baked Food Market Emerging Trajectories
Active fermentation control systems and precision moisture management are compressing batch-to-batch variation while enabling novel texture profiles that respond to shifting consumption occasions.
High-pressure processing for ambient-stable sourdough is overtaking traditional chemical preservation in premium retail segments. Clean-label retailers and specialty grocers adopt this non-thermal pasteurization method to extend refrigerated shelf life without additive declarations. The technology is compressing the price gap between artisan and industrial production methods.
EU Green Deal Farm-to-Fork Strategy traceability protocols now require ingredient origin documentation across all member states. This regulatory architecture elevates compliance software and blockchain verification system adoption among mid-scale producers. Organic and heritage grain categories face the steepest documentation burdens but capture corresponding price premiums.
Direct-to-foodservice procurement platforms are disintermediating traditional wholesale bakery distribution in urban concentration zones. Restaurant groups and institutional caterers consolidate supplier relationships through digital tendering systems that prioritize consistency metrics over historical credit terms. This pattern concentrates most visibly in German and French metropolitan foodservice clusters.
Bread and Baked Food Market Segmentation
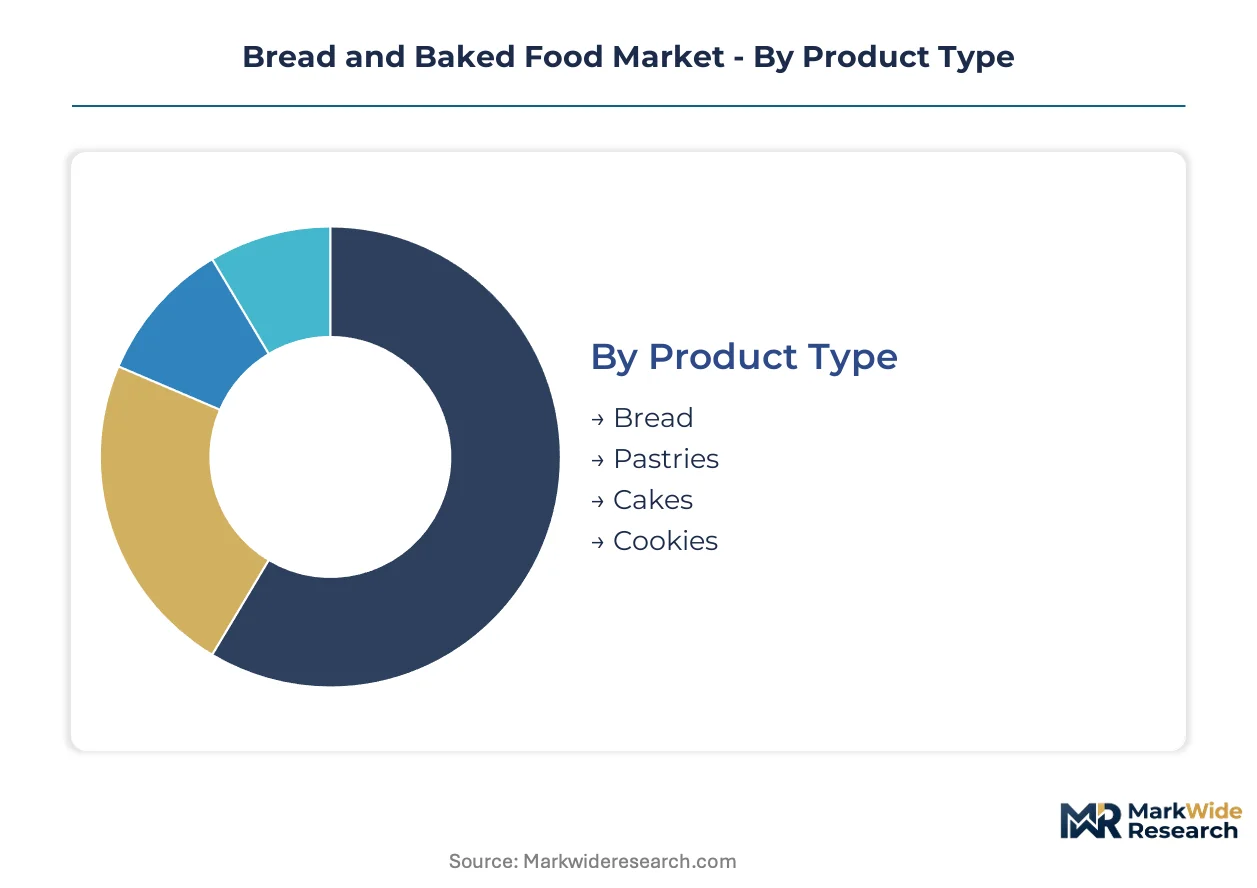
Segmentation in baked goods reveals how consumption occasions, preservation requirements, and procurement channels fragment demand into distinct margin pools. Understanding these divisions exposes where reformulation investments and distribution infrastructure deliver differential returns.
Product Type:
Buyers differentiate primarily by consumption occasion and perishability tolerance, with daily staples commanding volume leadership and indulgence categories capturing premium positioning.
- Bread:Fermented cereal products with 35-45% moisture content serving as dietary staples across retail and institutional channels. Household penetration exceeds forty kilograms annually in developed economies, while FSSAI fortification mandates in India expand packaged bread into tier-two urban centers.
- Pastries:Laminated or chemically leavened products with elevated fat content and shorter shelf windows. Café culture expansion across Southeast Asian metropolitan districts absorbs premium volumes as branded coffee chains establish footprint.
- Cakes:Aerated sponge or butter-based celebration and convenience desserts. Demand concentrates in emerging markets where foodservice channels absorb production from industrial bakeries deploying par-bake freezing technology.
- Cookies:Low-moisture baked snacks with extended ambient stability. Supermarket private-label programs and impulse placement at convenience stores sustain volume turnover with reduced distribution complexity.
Bread leads volumes today; pastries are gaining share fastest through café channel penetration.
Form:
Preservation technology and label positioning determine price realization, with frozen formats enabling production decoupling and organic claims commanding shelf-space premiums.
- Frozen:Blast-frozen or par-baked products decoupling manufacturing peaks from distribution constraints. Industrial bakeries deploy capital-intensive freezing infrastructure to extend geographic reach without freshness degradation.
- Packaged:Modified-atmosphere or preservative-stabilized products for extended retail shelf life. Enzyme-based shelf-life extension technologies enable clean-label moisture retention without chemical declarations.
- Fresh:Unpreserved products with sub-72-hour consumption windows. Hyper-regional brand portfolios dominate southeastern United States foodservice procurement through consistency metrics prioritized over historical credit terms.
- Organic:Certified ingredient systems with farm-to-fork documentation burdens. EU Green Deal traceability protocols force blockchain verification adoption among mid-scale producers serving specialty grocers.
Packaged formats dominate current volume; frozen forms are expanding most quickly through foodservice consolidation.
Sales Channel:
Channel selection reflects buyer urgency, basket composition, and procurement scale, with digital platforms disintermediating traditional wholesale relationships in urban concentration zones.
- Supermarkets:Full-assortment retail with slotting fee exposure and front-of-pack label scrutiny. EU supermarkets implement scope-three carbon disclosure requirements that elevate ISO 14067 verification to listing preference.
- Convenience Stores:Impulse-oriented limited assortment with premium pricing tolerance. High-frequency purchase patterns sustain turnover for ambient-stable cookies and single-serve pastry formats.
- Online Retail:Direct-to-consumer fulfillment with cold-chain requirements for fresh segments. Last-mile logistics constraints favor frozen and long-shelf-life packaged categories over preservative-free alternatives.
- Foodservice:Institutional and restaurant procurement through digital tendering platforms. German and French metropolitan clusters concentrate supplier relationship consolidation as restaurant groups prioritize consistency metrics.
Supermarkets retain volume leadership today; foodservice channels are climbing the fastest through quick-service restaurant embedded artisan bread programs.
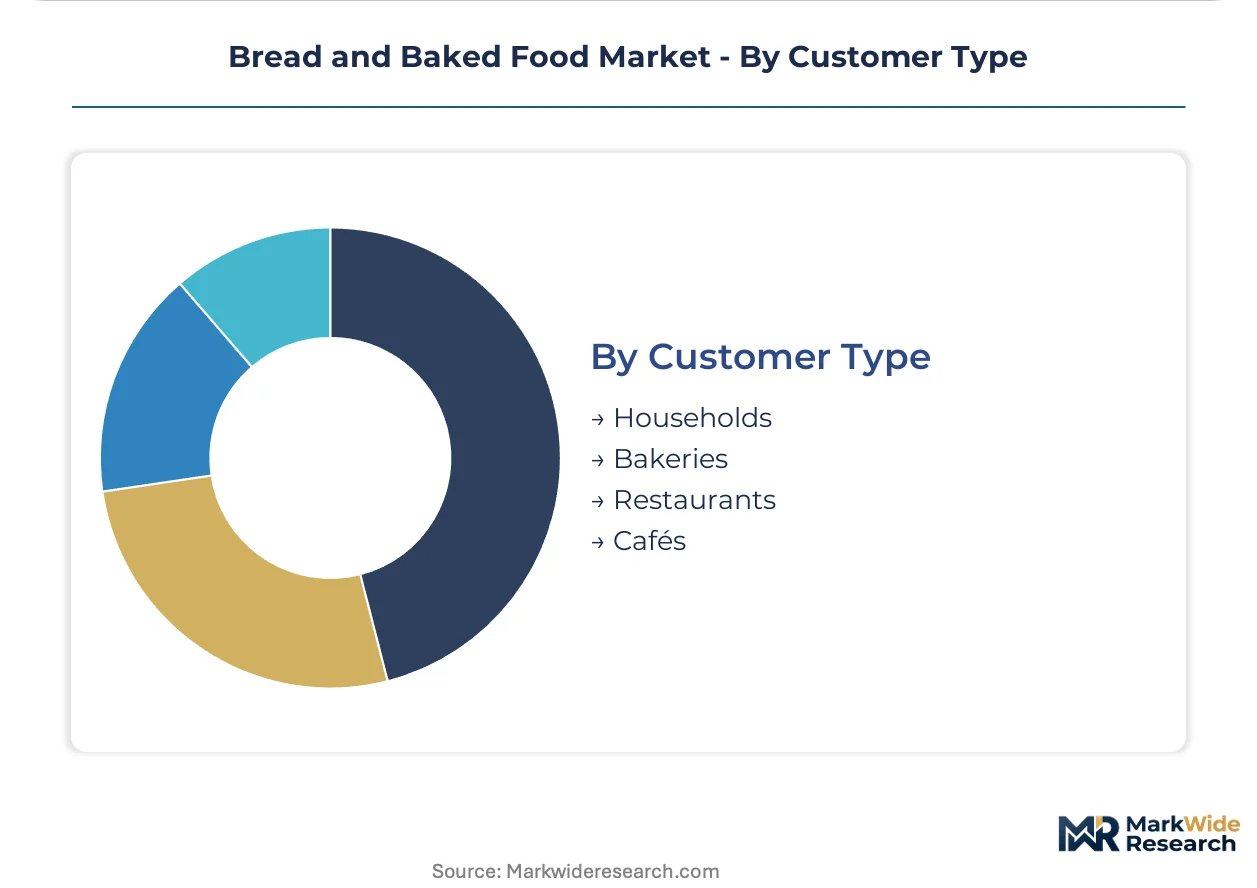
Customer Type:
End-user scale and technical capability determine whether buyers source finished goods or intermediate inputs, fragmenting supplier relationships by operational complexity.
- Households:Final consumers purchasing through retail channels for at-home consumption. Per-capita bread consumption maturity in developed economies constrains volume growth while premiumization sustains value expansion.
- Bakeries:Artisan and industrial operations requiring flour, frozen dough, or par-baked inputs. Vertically integrated milling networks absorb EU Green Deal compliance costs without margin erosion through captive supply control.
- Restaurants:Foodservice operators integrating bread into meal composition or table service. Quick-service restaurants embed artisan bread lines into standard menus with volume commitments reducing slotting fee exposure.
- Cafés:Coffee-focused establishments with pastry-forward complementary offerings. Branded chain expansion across Latin American metropolitan districts drives premium cake and pastry absorption.
Households dominate consumption volumes today; cafés are showing the steepest expansion trajectory through emerging-market café culture penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bread and baked food production traces its industrial lineage to nineteenth-century European milling centers, where roller-milling technology first enabled mass flour refinement. Commercial baking scaled through German and British urbanization, then dispersed through colonial trade networks into North American and South Asian manufacturing clusters.
United States
Per-capita bread consumption exceeds forty kilograms annually across American households, sustaining mature demand for packaged sandwich loaves and foodservice buns. FDA food safety modernization rules elevate compliance costs for smaller operators while creating certification-based differentiation for scaled manufacturers. The southeastern United States concentrates hyper-regional brand portfolios that dominate institutional procurement through consistency metrics prioritized over historical credit terms.
Germany
EU Green Deal carbon accounting mandates restructure capital allocation across German flour milling and thermal processing infrastructure, forcing emissions tracking from farm gate through retail shelf. REACH chemical compliance extends registration timelines for enzyme and additive suppliers, delaying new ingredient commercialization. Metropolitan foodservice clusters in Berlin and Hamburg consolidate supplier relationships through digital tendering platforms that disintermediate traditional wholesale bakery distribution.
India
FSSAI fortification mandates for packaged bread expand addressable demand through nutritional positioning in tier-two and tier-three urban centers. Britannia Industries and local cooperatives scale penetration beyond metropolitan cores into secondary cities with rising disposable incomes. Mumbai and Delhi-NCR anchor industrial bakery capacity expansion as frozen dough and par-bake technologies extend distribution reach into heat-stressed interior regions.
Japan
Yamazaki Baking anchors market position through R&D intensity in enzyme-based shelf-life extension, enabling clean-label moisture retention without chemical preservatives. METI industrial standards guide thermal processing efficiency investments as domestic energy costs pressure legacy oven infrastructure. Tokyo-Osaka corridor bakeries deploy high-pressure processing for ambient-stable sourdough, compressing the price gap between artisan and industrial production methods.
Brazil
Café culture penetration across São Paulo and Rio de Janeiro metropolitan districts absorbs premium pastry and cake volumes as branded coffee chains establish footprint. Local milling cooperatives face traceability system integration challenges under emerging farm-to-fork documentation requirements. The southeastern industrial belt concentrates frozen dough production capacity serving quick-service restaurant embedded artisan bread programs with volume commitments reducing slotting fee exposure.
Bread and Baked Food Market Vendor Landscape
The competitive structure tilts toward vertically integrated multinational conglomerates with captive flour milling networks. Consolidation pressure concentrates volume leadership among scale-driven operators capable of absorbing regulatory compliance costs without margin erosion. Three archetypes dominate: diversified packaged-food conglomerates with global brand portfolios, regional baking specialists with hyper-local distribution density, and frozen-dough industrial suppliers serving foodservice consolidation. M&A activity targets artisan brand acquisitions for premium positioning, while capacity expansion focuses on blast-freezing infrastructure for geographic reach extension.
Within the diversified conglomerate tier, Grupo Bimbo exemplifies scale-driven consolidation through its vertically integrated milling network spanning multiple continents. Mondelez International occupies a position as snack-forward diversified operator with baked goods embedded within broader packaged-food portfolios. Flowers Foods represents the hyper-regional specialist archetype, anchoring southeastern United States market presence through distributed bakery networks optimized for fresh product velocity rather than national brand uniformity.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Mondelez International |
| Flowers Foods |
| Associated British Foods |
| General Mills |
| Yamazaki Baking |
| Britannia Industries |
| Aryzta AG |
| Premier Foods |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU Green Deal-compliant organic heritage grain systems and commodity flour sourcing creates parallel supply chains with divergent cost structures. Premium tiers absorb blockchain traceability investments and carbon accounting overhead, while standard tiers compete on volume scale and geographic proximity to milling infrastructure.
Pricing Analysis
Fresh versus frozen format unbundling separates immediate-consumption premiums from production-deferred value capture. Three-tier pricing structure across premium artisan, standard packaged, and economy private-label levels reflects input certification and shelf-life technology intensity. Pricing pressure stems from wheat cost volatility tied to Black Sea supply disruptions, compressing margin predictability for non-integrated operators. Quick-service restaurants exhibit lowest price sensitivity due to volume commitment structures, while household retail buyers in tier-two Indian cities show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor hub-and-spoke patterns for ambient and frozen product categories. Wheat supply draws from Black Sea origins, North American plains, and Australian export corridors, with enzyme and additive inputs sourced through REACH-regulated European suppliers. Single-source vulnerability concentrates in specialty grain heritage varieties with limited geographic cultivation. Distribution runs through foodservice procurement platforms disintermediating traditional wholesale relationships in metropolitan concentration zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage potential concentrates between EU Green Deal compliance jurisdictions and emerging markets with fortification-driven demand expansion, where regulatory cost differentials exceed fifteen percentage points in comparable production capacity.
For Market Incumbents: Anticipate margin compression from plant-based protein substitution attempts by securing captive enzyme R&D pipelines and par-bake freezing capacity additions in India. Vertically integrated milling networks absorb EU carbon accounting mandates without margin erosion through supply chain control. Certification investments in ISO 14067 verification capture retail listing preference as scope-three disclosure requirements harden. For New Entrants and Emerging Players: Artisan bakery cooperatives in tier-two Indian cities represent the most penetrable buyer archetype, underserved by Britannia Industries' metropolitan concentration. Frozen dough supply to quick-service restaurant embedded bread programs offers volume commitment structures with reduced slotting fee exposure. Direct-to-foodservice digital tendering platforms in German metropolitan clusters provide channel access without legacy wholesale relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Green Deal compliance costs exceed ten percent of revenue for sub-scale operators without backward flour milling integration. Mid-scale heritage grain specialists with blockchain traceability infrastructure present acquisition targets for premium portfolio expansion. The signal to watch is FSSAI fortification mandate enforcement intensity in Indian tier-three urban centers as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Capacity Expansion | Par-bake technology decouples production peaks from distribution constraints in heat-stressed regions. |
| Enzyme-Based Shelf-Life R&D | Amylase-lipase convergence enables clean-label moisture retention without chemical preservative declarations. |
| Carbon Footprint Certification | ISO 14067 verification secures retail listing preference under EU supermarket scope-three disclosure mandates. |
| Heritage Grain Supply Agreements | Blockchain-tracked organic sourcing captures price premiums through EU Green Deal traceability compliance. |
| Quick-Service Restaurant Partnership | Embedded artisan bread programs generate captive demand with volume commitments reducing slotting fee exposure. |
Methodological Framework
Direct dialogue with industrial bakery plant managers, flour milling procurement leads, quick-service restaurant supply chain directors, and EU regulatory affairs specialists grounded qualitative insights. Secondary validation drew from FSSAI fortification mandate documentation, EU Green Deal Farm-to-Fork Strategy protocols, FDA food safety modernization rule filings, and customs trade data on wheat and enzyme imports. Bottom-up capacity assessments and top-down consumption models triangulated volume estimates.
Bottom-up modeling tracked production capacity across frozen, packaged, fresh, and organic form segments, while top-down approaches validated against household penetration rates and foodservice procurement volumes. Analytical frameworks incorporated product type, preservation technology, sales channel, and customer archetype dimensions across the projection horizon. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and input cost volatility patterns.
Underlying measurement precision varies by segment; frozen and packaged categories carry tighter precision than fresh artisan sub-segments with fragmented cooperative production. Forecasts reflect documented assumptions on wheat price stabilization, enforcement timelines for EU carbon accounting, and FSSAI fortification compliance rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
US Frozen Bakery Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Bakery Improvers Market
Bakery Products
Soft Biscuit Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Pancake Mixes Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Fondant Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Flour Mixes Market
Bakery Products
Bakery Fillings Market
Bakery Products
Toasted Flour Market
Bakery Products
Pancakes Market
Bakery Products
Ice Cream Market
Bakery Products
No-Fat Cake Market
Bakery Products
Aerating Cake Emulsifier Market