
 Cake Concentrate Market | 2026-2036
Cake Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Concentrate Market Analysis
Single-serve sachet and portion-controlled tub formats are pivoting how home bakers and small foodservice operators purchase cake concentrates, shifting volume away from bulk bag configurations. Dawn Food Products leverages its North American distribution network to sustain leadership in foodservice channels. Bakels Worldwide anchors its position in European bakery supply through specialized concentrate formulations for artisan producers. General Mills competes in retail baking mixes by extending its brand recognition into concentrate-adjacent categories.
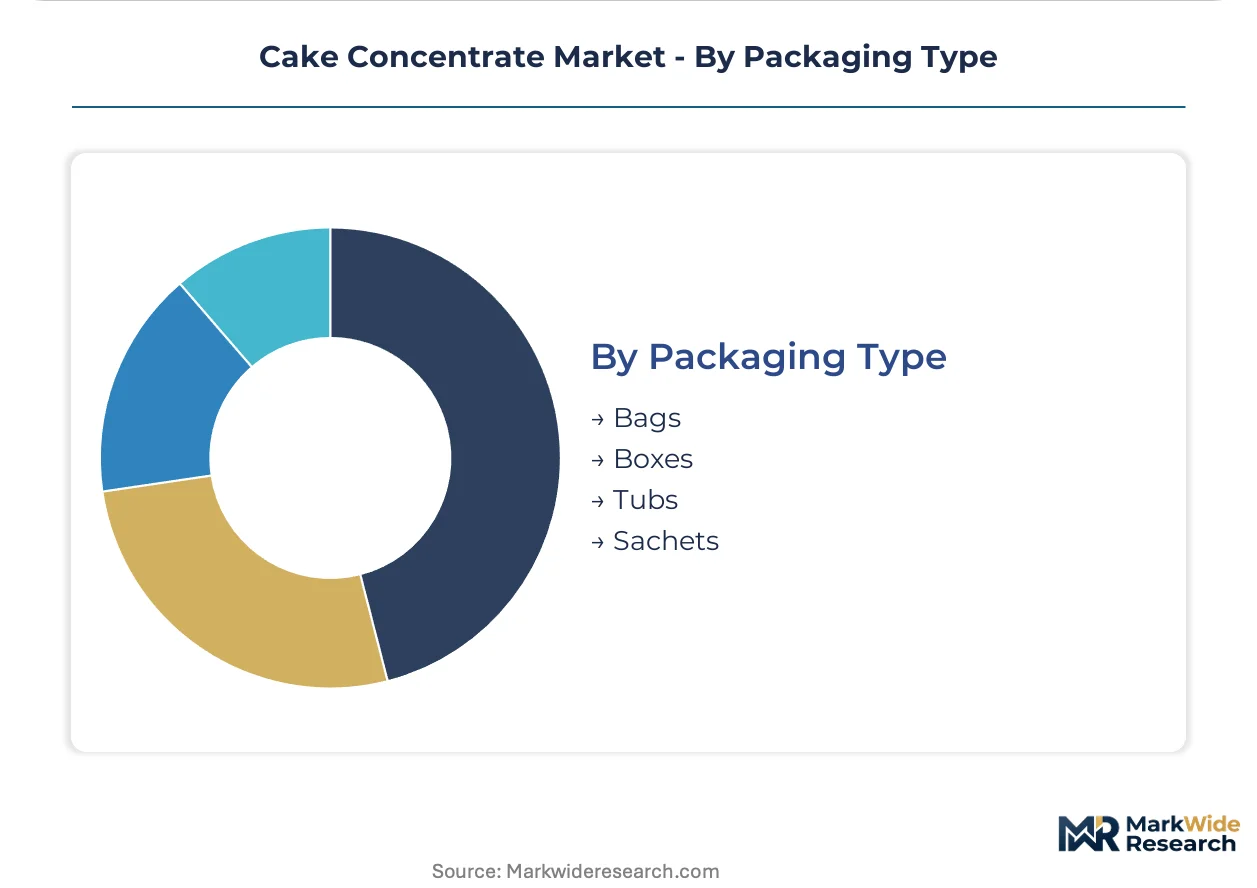
Cake concentrate denotes a pre-formulated dry or semi-dry blend of flour, sugar, emulsifiers, leavening agents, and flavor compounds requiring only the addition of liquid and fat before baking, typically standardized to specific gravity and moisture retention parameters for batch consistency. Its primary commercial purpose is to reduce labor input, minimize ingredient inventory, and ensure product uniformity across multi-site bakery operations. Chocolate cake concentrate dominates volume in the product type dimension due to its ubiquity in foodservice dessert menus and retail celebration cake applications. The food service application segment carries elevated margin pools as operators prioritize labor efficiency over per-unit ingredient cost. Sachet packaging is expanding fastest among packaging types, driven by single-use convenience in home baking and small commercial kitchens.
The FDA governs ingredient labeling and GRAS status for emulsifiers and preservatives used in US-manufactured cake concentrates, while the EMA and EFSA frameworks influence additive acceptance thresholds across European markets. BIS certification requirements in India affect import access for concentrate suppliers targeting that country's growing bakery sector. Stakeholders must monitor evolving clean-label regulations and emulsifier approval revisions, as these will determine which formulation platforms retain market access in key jurisdictions.
Market Dynamics
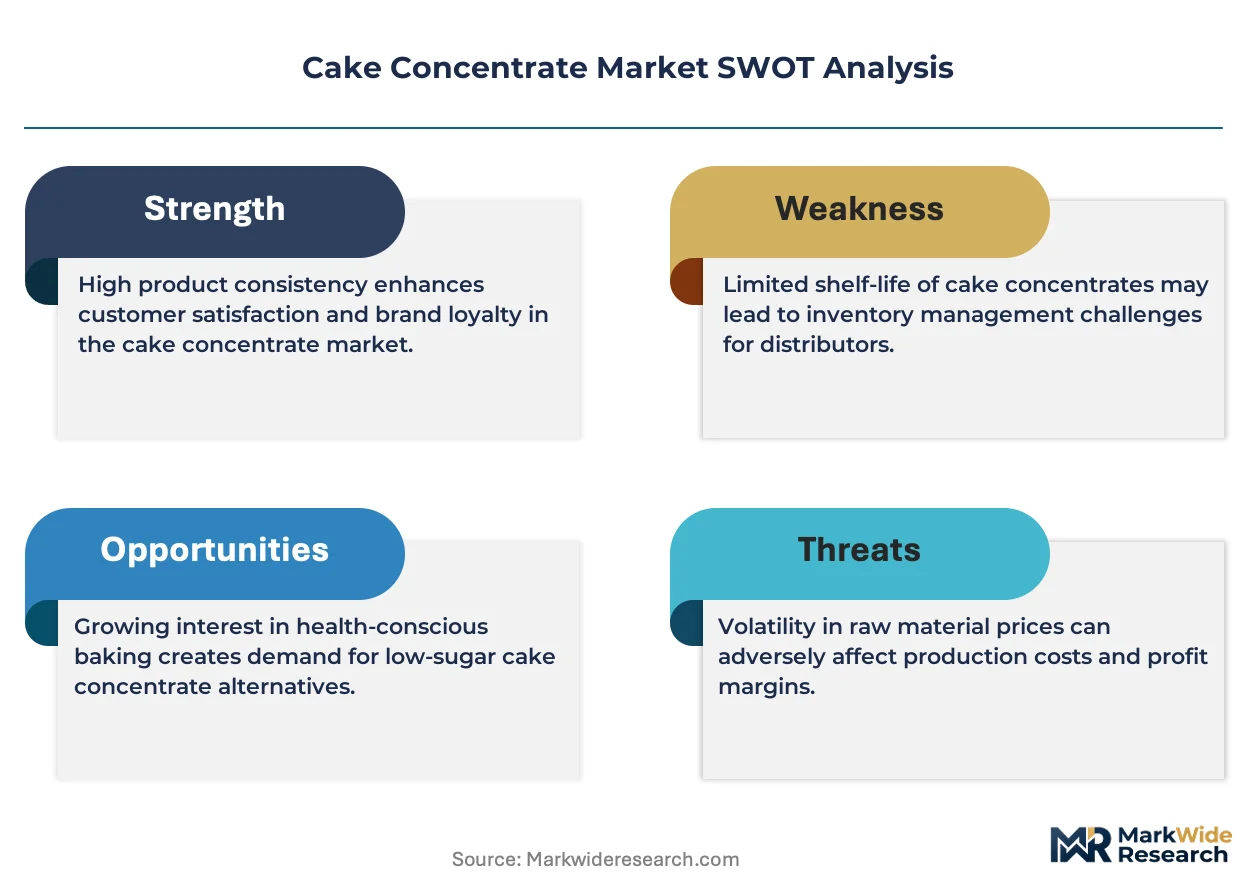
Clean-label mandates from EFSA and FDA are compressing formulation cycles as manufacturers reformulate emulsifier systems to maintain functionality while eliminating synthetic additives. This regulatory pressure sits at the center of competitive positioning, forcing R&D prioritization toward natural stabilizers and clean-label credentials.
Growth Catalysts
- EU Additive Thresholds:EFSA's revised acceptable daily intake limits for synthetic emulsifiers are accelerating clean-label concentrate adoption among industrial bakeries seeking preemptive compliance.
- Foodservice Labor Efficiency:Commercial kitchens are standardizing on concentrate-based workflows to reduce prep time and ingredient inventory complexity across multi-location operations.
- German Bakery Modernization:Industrial and craft bakeries across Germany are deploying concentrates to offset acute shortages of trained pastry chefs and skilled labor.
Market Restraints
- Natural Emulsifier Cost Volatility:Lecithin and plant-derived stabilizers face price instability tied to agricultural commodity swings, compressing margins on clean-label formulations.
- Supply Concentration Risk:Specialty hydrocolloid suppliers cluster in Southeast Asia, creating geographic vulnerability for concentrate manufacturers dependent on consistent gum arabic and xanthan sourcing.
- Functionality Trade-offs:Natural emulsifier systems deliver shorter shelf stability than synthetic alternatives, limiting distribution radius for ambient-storage concentrates.
Strategic Opportunities
- India Bakery Sector Expansion:BIS certification requirements create barriers for imports, but domestic formulation partnerships unlock access to a fast-growing commercial baking market.
- Single-Serve Sachet Channels:Convenience-oriented packaging formats are penetrating home baking and small foodservice segments previously served by bulk configurations.
- EU Green Deal Alignment:Sustainability-linked procurement criteria from major European retail chains favor concentrates with verified lower carbon intensity in ingredient sourcing.
Industry Challenges
- Reformulation Technical Expertise:Natural emulsifier replacement requires specialized food science capability scarce among mid-tier concentrate producers.
- Clean-Label Certification Timelines:Third-party verification for additive-free claims extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Concentrate Market |
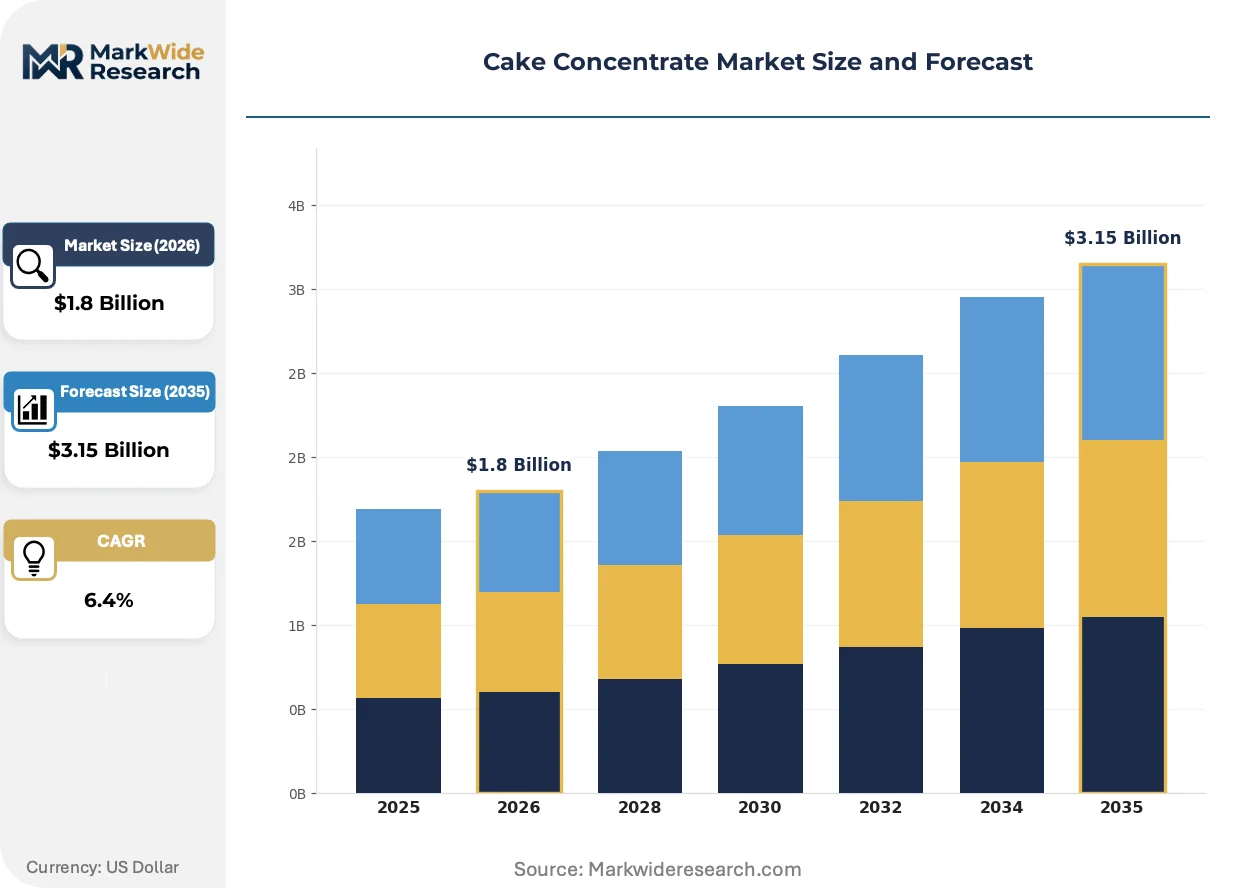
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cake, Vanilla Cake, Red Velvet Cake, Carrot Cake Application: Baking Mixes, Food Service, Home Baking, Ready-to-Eat End User: Bakeries, Restaurants, Cafes, Retail Chains Packaging Type: Bags, Boxes, Tubs, Sachets |
| Companies Covered | Dawn Food Products, Conagra Brands, Bakels Worldwide, Key Blends, General Mills, Embassy Ingredients, Dr. Oetker, Andrew Ingredients, IFFCO Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Concentrate Market Emerging Trajectories
Formulation science and packaging engineering are converging to redefine how cake concentrates reach end-users. Three developments are compressing traditional supply relationships and opening new competitive vectors.
Enzymatic flour modification is converging with concentrate platforms to deliver extended freshness without chemical preservatives. European industrial bakeries are piloting these systems at scale. The technology is compressing the shelf-life gap between natural and synthetic formulations, enabling broader clean-label distribution.
REACH regulation updates on microplastic labeling are forcing disclosure of polymer-based encapsulation systems used for flavor stability. Manufacturers must reformulate or transparently label these components. Premium concentrate lines targeting EU retail channels are most affected, accelerating migration to lipid-based encapsulation alternatives.
Small-batch procurement from digital-native ingredient suppliers is displacing traditional distributor relationships among artisan bakeries. These buyers now source concentrates through direct-to-manufacturer platforms with transparent formulation data. Germany and France show the highest penetration of this channel shift, particularly among independent patisseries seeking customization.
Cake Concentrate Market Segmentation
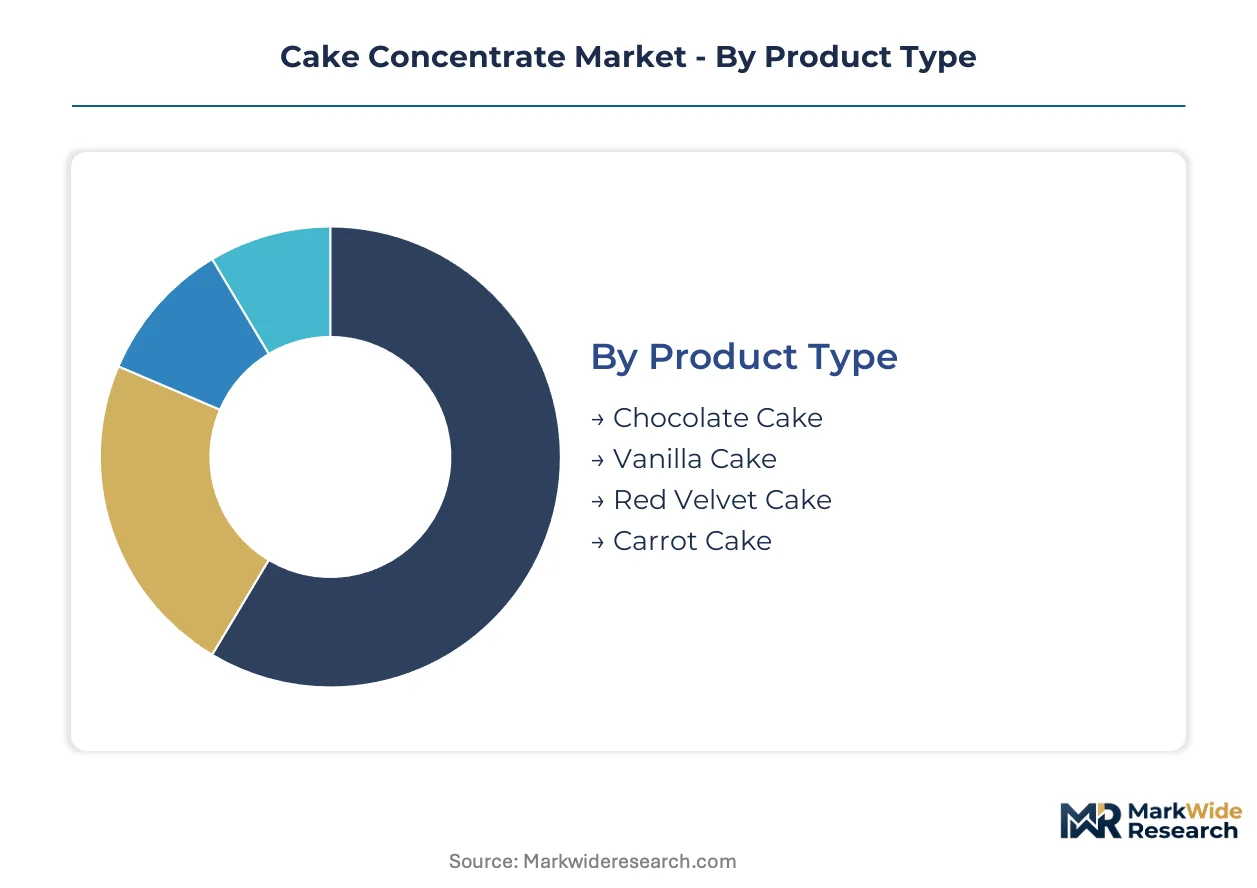
Segmentation in the cake concentrate market reveals how formulation specialization and packaging engineering align with distinct operational workflows across commercial and consumer channels. Each dimension carries implications for margin structure, regulatory exposure, and supply chain configuration.
Product Type:
Supply concentration in chocolate cake concentrate reflects its dominance in foodservice dessert pipelines and celebration cake manufacturing, where standardization demands are highest.
- Chocolate Cake:Formulated with cocoa solids, chocolate flavor compounds, and optimized emulsifier systems for moisture retention in high-volume production. Demand concentrates in North American bakery chains and German industrial bakeries, driven by menu standardization requirements and labor shortage mitigation.
- Vanilla Cake:Serves as the neutral base for customization in artisan and retail applications, with formulations emphasizing clean-label vanilla sourcing and natural color stability. European craft producers and US regional bakery chains represent the primary demand nodes, pressured by EFSA and FDA additive thresholds.
- Red Velvet Cake:Specialized formulations incorporating cocoa, buttermilk flavoring, and pH-sensitive color systems for signature appearance.
- Carrot Cake:Spice-forward blends with particulate tolerance specifications for shredded vegetable inclusions.
Chocolate cake concentrate absorbs the bulk of installed capacity; sachet-format vanilla is expanding most quickly in home baking channels.
Application:
Cost tier differentiation separates foodservice operators prioritizing labor efficiency from retail channels emphasizing ingredient transparency.
- Food Service:Commercial kitchens deploy concentrate-based workflows to compress prep time and reduce ingredient inventory complexity across multi-location operations. North American contract foodservice providers and German institutional caterers anchor volume, with procurement decisions weighted toward batch consistency over per-unit ingredient cost.
- Baking Mixes:Retail-facing formulations balance convenience claims with clean-label positioning for supermarket shelf placement. US and European retail chains drive specification requirements, with EFSA and FDA emulsifier approvals determining formulation platform viability.
- Home Baking:Single-serve and small-format packaging dominates, with convenience-oriented consumers in Germany and France adopting sachet configurations.
- Ready-to-Eat:Pre-hydrated or ambient-stable concentrates for industrial finishing operations.
Food service commands the highest margin pool; home baking climbs the fastest as sachet penetration accelerates.
End User:
Volume concentration in industrial bakeries contrasts with margin-rich artisan segments demanding formulation transparency.
- Bakeries:Industrial and craft producers across Germany deploy concentrates to offset skilled pastry chef shortages, with procurement shifting toward direct-to-manufacturer platforms for customization. Clean-label reformulations under EFSA additive limits dominate R&D priorities.
- Restaurants:Full-service and limited-service operators standardize dessert production through concentrate-based systems, with US chains emphasizing labor efficiency.
- Cafes:Smaller-format foodservice requiring portion flexibility and rapid inventory turnover.
- Retail Chains:Private-label and branded concentrate programs for in-store bakery operations.
Industrial bakeries represent the steepest expansion trajectory; restaurants retain the largest absolute volume position.
Packaging Type:
Margin structure varies sharply across format scale, with single-serve configurations commanding premium positioning.
- Sachets:Single-serve pouches penetrating home baking and small commercial kitchens in Germany and France, driven by convenience orientation and reduced waste claims. Digital-native procurement platforms accelerate adoption among independent patisseries.
- Tubs:Portion-controlled containers for foodservice operators requiring measured dispensing and extended ambient stability.
- Bags:Bulk configurations for high-volume industrial users, facing volume pressure from format migration.
- Boxes:Retail-oriented packaging with recipe integration and brand differentiation features.
Bags retain the largest volume base; sachets gain share fastest through convenience-channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the largest volume of cake concentrates in Europe, yet formulation innovation originates from specialized suppliers across multiple jurisdictions. Production clusters concentrate near industrial baking hubs, while regulatory divergence shapes regional competitive advantage.
United States
Foodservice chains and contract caterers drive concentrate procurement, prioritizing labor efficiency in multi-location dessert operations. The FDA governs emulsifier GRAS status and labeling requirements for interstate commerce. Chicago anchors North American distribution networks, with regional bakeries adopting clean-label reformulations to meet evolving additive scrutiny.
Germany
Industrial and craft bakeries deploy concentrates to offset acute shortages of trained pastry chefs, with procurement shifting toward direct-manufacturer platforms. EFSA additive thresholds and EU Green Deal sustainability criteria redirect R&D spending toward natural stabilizer systems. Munich and Stuttgart host formulation development clusters serving Central European bakery modernization.
France
Artisan patisseries and independent bakeries source concentrates through digital-native procurement platforms demanding transparent formulation data. REACH regulation updates on microplastic labeling force disclosure of polymer-based encapsulation systems. Paris and Lyon concentrate premium concentrate development for celebration cake applications.
India
Commercial bakery sector expansion creates demand for standardized production inputs, with domestic formulation partnerships unlocking market access. BIS certification requirements affect import pathways for international concentrate suppliers. Mumbai and Bangalore industrial zones anchor contract manufacturing relationships with multinational ingredient firms.
United Kingdom
Retail bakery chains and in-store operations standardize on concentrate-based workflows to reduce skilled labor dependency. Post-Brexit regulatory divergence from EU additive frameworks creates parallel compliance pathways. London and Manchester distribution hubs manage cross-channel supply relationships with European formulation specialists.
Cake Concentrate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct channel tiers. The vendor base stratifies into three layers: multinational food manufacturers with broad ingredient portfolios, regional bakery supply specialists with formulation expertise, and private-label producers serving retail chains. Consolidation pressure operates selectively, with acquisition activity concentrating in European artisan supply and North American foodservice distribution. Capacity expansion and clean-label certification partnerships constitute the dominant competitive moves.
Within the multinational tier, Dawn Food Products and General Mills occupy positions spanning foodservice and retail channels. Bakels Worldwide exemplifies the regional specialist archetype, anchoring European artisan bakery supply through concentrated formulation expertise. Dr. Oetker represents the branded consumer goods vector, leveraging retail recognition into adjacent concentrate-adjacent categories.
| Leading Market Players |
|---|
| Dawn Food Products |
| Conagra Brands |
| Bakels Worldwide |
| Key Blends |
| General Mills |
| Embassy Ingredients |
| Dr. Oetker |
| Andrew Ingredients |
| IFFCO Ingredients |
| Others |
Supply Flow & Price Mechanics
Clean-label certification tiers bifurcate concentrate economics, with EU EFSA-compliant natural emulsifier formulations commanding substantial premia over synthetic-stabilized commodity grades while simultaneously tethering procurement to volatile agricultural supply channels in Southeast Asia and Eastern Europe.
Pricing Analysis
Margin tightening in standard-grade concentrates reflects lecithin and plant-derived stabilizer cost volatility tied to sunflower and rapeseed commodity swings. Three-tier pricing structure across premium clean-label, standard industrial, and economy synthetic-stabilized levels segments buyer archetypes. Foodservice chains show lowest price sensitivity, prioritizing batch consistency over per-unit cost. Home baking channels exhibit acute price responsiveness, accelerating sachet-format volume migration.
Supply Chain Analysis
Lecithin and specialty hydrocolloid supply rests on Southeast Asian gum arabic processors and Eastern European sunflower cultivation regions. Xanthan gum and guar dependencies concentrate in China and India. Single-source vulnerability for enzymatic flour modification inputs creates geographic concentration risk. Distribution runs through regional bakery supply distributors serving industrial clusters in Germany and North American foodservice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is intensifying as concentrate manufacturers pursue captive sourcing of natural emulsifiers and direct-to-bakery digital platforms to secure margin control.
For Market Incumbents: To counter margin compression from agricultural commodity volatility, secure backward integration into lecithin processing or long-term offtake agreements with Southeast Asian hydrocolloid suppliers. Accelerate clean-label certification pipelines to preempt EFSA additive threshold revisions. For New Entrants and Emerging Players: Digital-native procurement platforms serving German and French artisan patisseries represent the most penetrable channel white space. Target sachet-format home baking segments through transparent formulation disclosure. Pursue domestic formulation partnerships in India to bypass BIS certification barriers for import-dependent competitors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European specialists possessing clean-label formulation expertise and direct-manufacturer platform infrastructure given accelerating regulatory divergence. Monitor EFSA emulsifier approval revisions and EU Green Deal procurement criteria adoption as inflection signals for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Emulsifier Supply | Captive lecithin and hydrocolloid sourcing insulates margins from agricultural commodity volatility. |
| Clean-Label Certification Investment | Third-party additive-free verification unlocks EU retail channel access under EFSA threshold pressure. |
| Direct-to-Manufacturer Platform Launch | Digital procurement transparency captures German and French artisan bakery demand migrating from distributors. |
| Domestic India Formulation Partnership | BIS-compliant local production bypasses import certification barriers in fast-growing commercial bakery sector. |
| Enzymatic Shelf-Life Extension R&D | Natural preservation systems compress shelf-life gap with synthetic alternatives, expanding clean-label distribution radius. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with industrial bakery procurement directors, craft patisserie owners, foodservice chain operations executives, and emulsifier supplier technical sales teams combined with EFSA additive guidance documents, FDA GRAS notifications, and BIS certification databases. Bottom-up concentrate volume estimates triangulated against top-down bakery sector expenditure data.
Data-stream reconciliation across product type, application channel, packaging format, and end-user scale dimensions shaped the analytical framework. CAGRs derived from segmented growth rate modeling across the projection horizon. Enzymatic modification technology adoption curves and clean-label reformulation timelines informed industry-specific trajectory assumptions.
Caveats apply where EFSA emulsifier approval revisions, EU Green Deal procurement enforcement, or Southeast Asian hydrocolloid supply disruptions could materially shift the outlook. A small set of regulatory and agricultural triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Bakery Fillings Market
Bakery Products
Bread Premix Market
Bakery Products
Europe Zwieback Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Low Calorie Flour Market
Bakery Products
United States Bread Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Frozen Bakery Market
Bakery Products
Bread Crumbs Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Bakery Emulsions Market