
 Vegan Donuts Market | 2026-2036
Vegan Donuts Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Donuts Market Analytics
Market Context
The gap between premium artisan and mass-market commodity vegan donuts is realigning as ingredient transparency becomes a decisive purchase factor. Dun-Well Doughnuts leverages small-batch production and single-origin sourcing to anchor its position in the premium tier. Mighty-O Donuts competes through certified organic supply chains and regional kitchen density. Blue Star Donuts differentiates via brioche-style vegan formulations that occupy a middle price position.
Technical Definition and Segment Structure
Vegan donuts exclude all animal-derived inputs, substituting egg binders with aquafaba or flax meal and dairy fats with coconut oil or oat-based shortenings, yielding a moisture content typically between 25% and 35% for cake-style variants. Glazed and filled formats lead volume due to operational simplicity in food service channels, while almond flour and oat flour bases capture the fastest growth among ingredient segments as allergen-friendly positioning expands. Specialty stores and direct online channels concentrate margin pools through subscription and limited-release models.
Regulatory Frame and Outlook
FDA enforcement of allergen disclosure under FALCPA and USDA oversight of plant-based label claims shape formulation standards and packaging requirements for vegan donut producers. State-level cottage food laws in California and New York create uneven market access for emerging brands without commercial kitchen investments. Stakeholders must monitor evolving FDA guidance on cell-cultured and precision-fermented ingredients as next-generation egg and dairy replacements approach regulatory clearance.
Market Dynamics
Ingredient transparency mandates and precision-fermented alternatives are compressing formulation cycles while expanding the addressable consumer base beyond traditional vegan cohorts into flexitarian and allergen-avoidant segments.
Growth Catalysts
- FDA Plant-Based Labeling Clarity:Standardized nomenclature for vegan claims reduces consumer confusion and accelerates retail shelf placement velocity in US grocery channels.
- Precision-Fermented Proteins:Commercial-scale production of animal-identical whey and casein without livestock inputs resolves texture deficits in brioche and raised donut formats.
- Quick-Service Restaurant Rollouts:Major chains adding dedicated vegan SKUs normalize plant-based donuts as standard menu items rather than specialty offerings.
Market Restraints
- Coconut Oil Price Volatility:Weather-driven supply disruptions in Southeast Asian producing regions create margin compression for fat-dependent formulations.
- Commercial Kitchen Concentration:Cottage food law restrictions in California and New York limit small-batch producer scaling without capital-intensive facility upgrades.
- Egg Replacer Performance Ceiling:Aquafaba and flax meal alternatives fail to replicate the structural integrity required for laminated and long-ferment doughs.
Strategic Opportunities
- German Retail Expansion:EU Green Deal-aligned consumer incentives and EFSA novel food approvals create favorable entry conditions for US and UK brands.
- Direct-to-Consumer Subscriptions:Limited-release and seasonal flavor models capture recurring revenue pools unavailable through traditional wholesale bakery distribution.
- Dual Allergen Positioning:Simultaneous gluten-free and vegan certification accesses the underserved intersection of multiple dietary restriction cohorts.
Industry Challenges
- Cross-Contamination Protocols:Shared equipment facilities struggle to maintain vegan integrity standards required by third-party certifiers like Vegan Action.
- Fermentation Scale-Up Talent:Shortage of bioprocess engineers with food-grade precision fermentation experience delays next-generation ingredient integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Donuts Market |
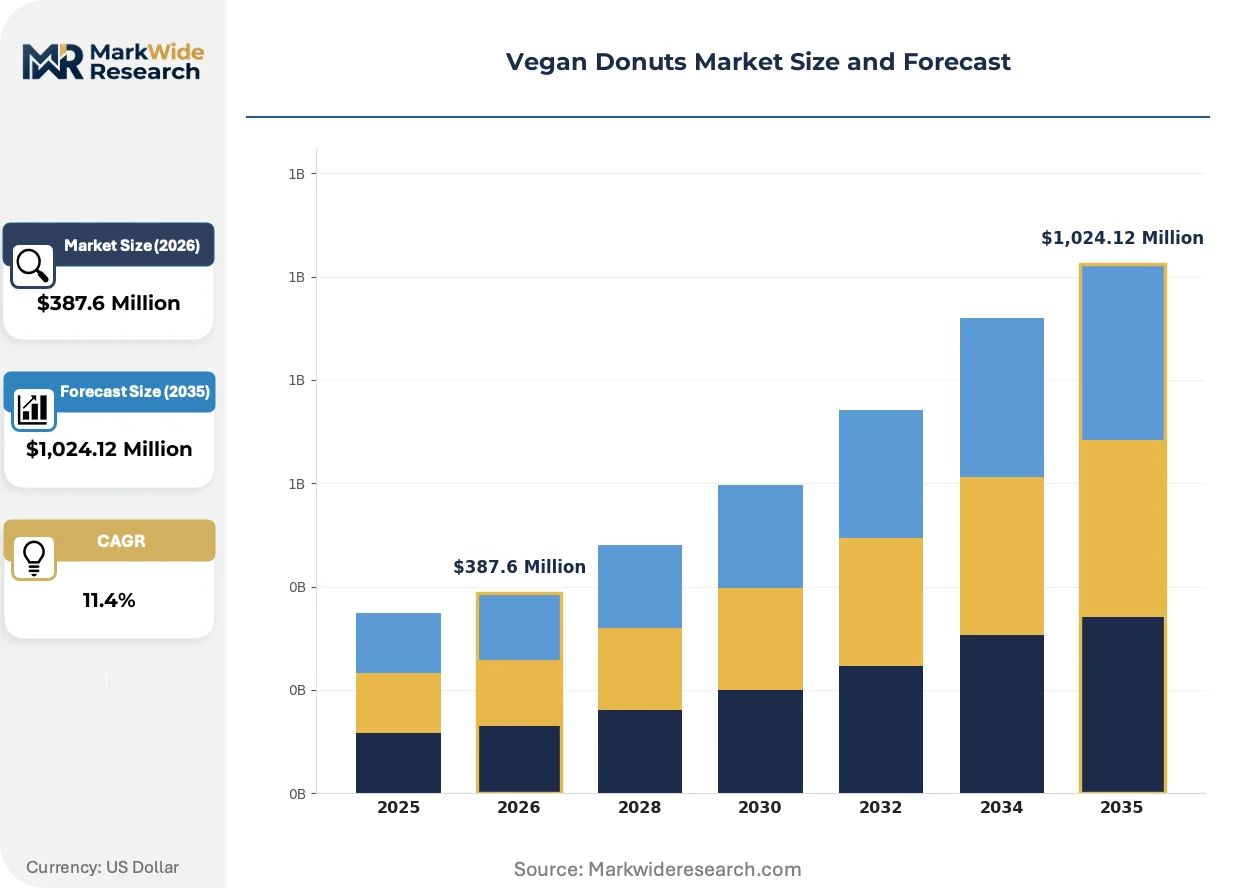
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Filled, Cake, Ring Ingredient Base: Chickpea Flour, Almond Flour, Oat Flour, Coconut Flour Distribution Channel: Online, Retail, Food Service, Specialty Stores Customer Type: Health Conscious, Vegans, Flexitarians, Snack Enthusiasts |
| Companies Covered | Dun-Well Doughnuts, Mighty-O Donuts, Voodoo Doughnut, The Cinnamon Snail, Blue Star Donuts, Dottie's Donuts, Rise Biscuits Donuts, Glam Doll Donuts, Crosstown Doughnuts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Donuts Market Evolving Landscape
Formulation science and distribution infrastructure are converging to dissolve the quality gap between plant-based and conventional donuts, with sensory parity now achievable at production scale.
Precision-fermented dairy proteins from Perfect Day and similar suppliers are rewriting textural expectations for vegan brioche and raised donut categories. Artisan producers in Portland and Brooklyn are adopting these inputs for limited runs, compressing the development timeline for mass-market rollout. The technology is rewriting the competitive boundary between premium and commodity tiers by eliminating the sensory trade-off that previously justified price stratification.
EU F-Gas Regulation phase-down schedules are accelerating industrial refrigeration retrofits across European bakery operations. Manufacturers serving export markets must certify compliance to maintain access, raising capital requirements for mid-scale producers. German and Dutch facilities are responding fastest, integrating CO2-based cooling systems that align with both regulatory mandates and corporate sustainability disclosures.
Subscription-based procurement is displacing traditional wholesale relationships for specialty vegan donut brands. Direct channels capture margin pools previously allocated to distributor markups, while enabling real-time flavor customization based on subscriber preference data. California and New York metropolitan clusters show the highest concentration of these models, with seasonal and collaboration drops driving retention rates above conventional bakery benchmarks.
Vegan Donuts Market Segmentation
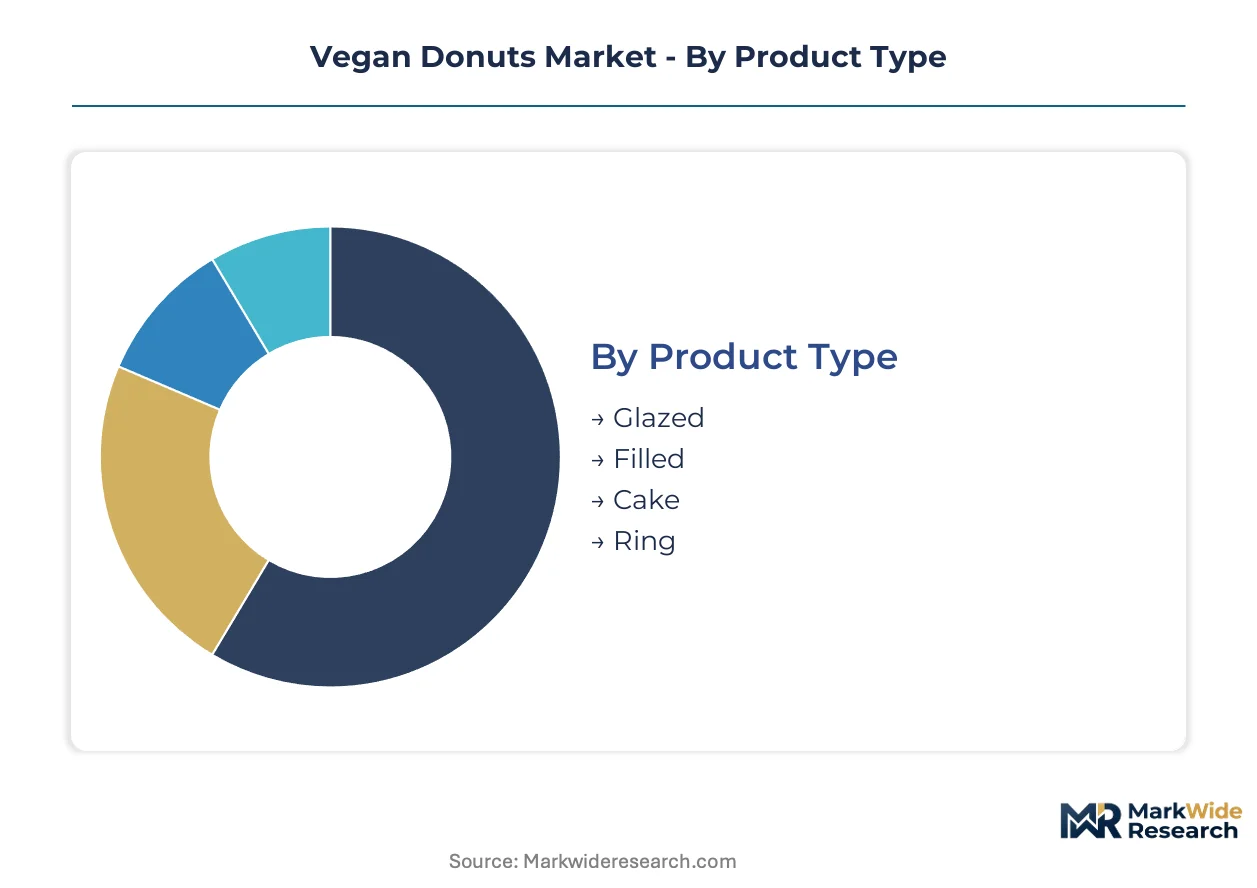
Segmentation in the vegan donuts market determines equipment requirements, margin structures, and certification pathways. Each category carries distinct capital thresholds and regulatory exposure that shape producer strategy and market entry feasibility.
Product Type:
Capital intensity varies sharply across production methods, with raised and laminated formats demanding proofing infrastructure that cake-style variants bypass entirely.
- Glazed:Simple sugar-based coatings applied post-frying require minimal additional equipment beyond cooling racks and glazing screens. Quick-service restaurants in California metropolitan clusters drive volume for this format due to operational simplicity and extended shelf stability.
- Filled:Precision injection systems and refrigerated filling stations add significant upfront cost. Specialty cafes in Brooklyn and Portland concentrate demand here, drawn to premium pricing enabled by limited-release flavor collaborations.
- Cake:Chemically leavened batters bake in standard convection ovens without proofing infrastructure, lowering barrier to entry for cottage food producers.
- Ring:Traditional raised doughs requiring extended fermentation and specialized cutting equipment occupy the highest capital tier among format categories.
Most installed capacity flows through Glazed. Expansion is steepest in Filled.
Ingredient Base:
Supply chain configuration and allergen certification costs create divergent margin profiles across flour alternatives.
- Almond Flour:High-fat content delivers moisture retention comparable to wheat-based brioche, though tree-nut allergen labeling triggers FALCPA compliance costs. California and New York specialty stores concentrate demand for this premium-positioned base.
- Oat Flour:Neutral flavor profile and gluten-free positioning access dual-allergen consumer segments without tree-nut regulatory burden. German retail channels show particular strength for oat-based formulations aligned with EU Green Deal sustainability signaling.
- Chickpea Flour:Protein content supports structural integrity in cake-style applications, though beany off-notes limit adoption in premium tiers.
- Coconut Flour:High fiber and natural sweetness reduce added sugar requirements, but Southeast Asian supply concentration exposes producers to price volatility.
Almond Flour commands the highest price realization. Oat Flour is gaining share fastest.
Distribution Channel:
Channel selection dictates working capital intensity, with direct-to-consumer models requiring inventory risk absorption that wholesale relationships transfer to distributors.
- Food Service:High-volume contracts with quick-service restaurants and specialty cafes demand consistent production scale and HACCP-certified facilities. This channel captures the largest revenue pool through multi-unit commitments.
- Specialty Stores:Curated placement in vegan-focused retail generates margin premiums but requires dedicated sales infrastructure and promotional support.
- Online:Subscription and limited-release models capture recurring revenue with higher customer acquisition costs offset by lifetime value concentration.
- Retail:Grocery placement requires slotting fees and packaging compliance that strain emerging brand balance sheets.
Food Service absorbs the most production volume. Online channels show the steepest expansion trajectory.
Customer Type:
Motivation-based segmentation determines messaging architecture and product attribute prioritization across formulation and packaging decisions.
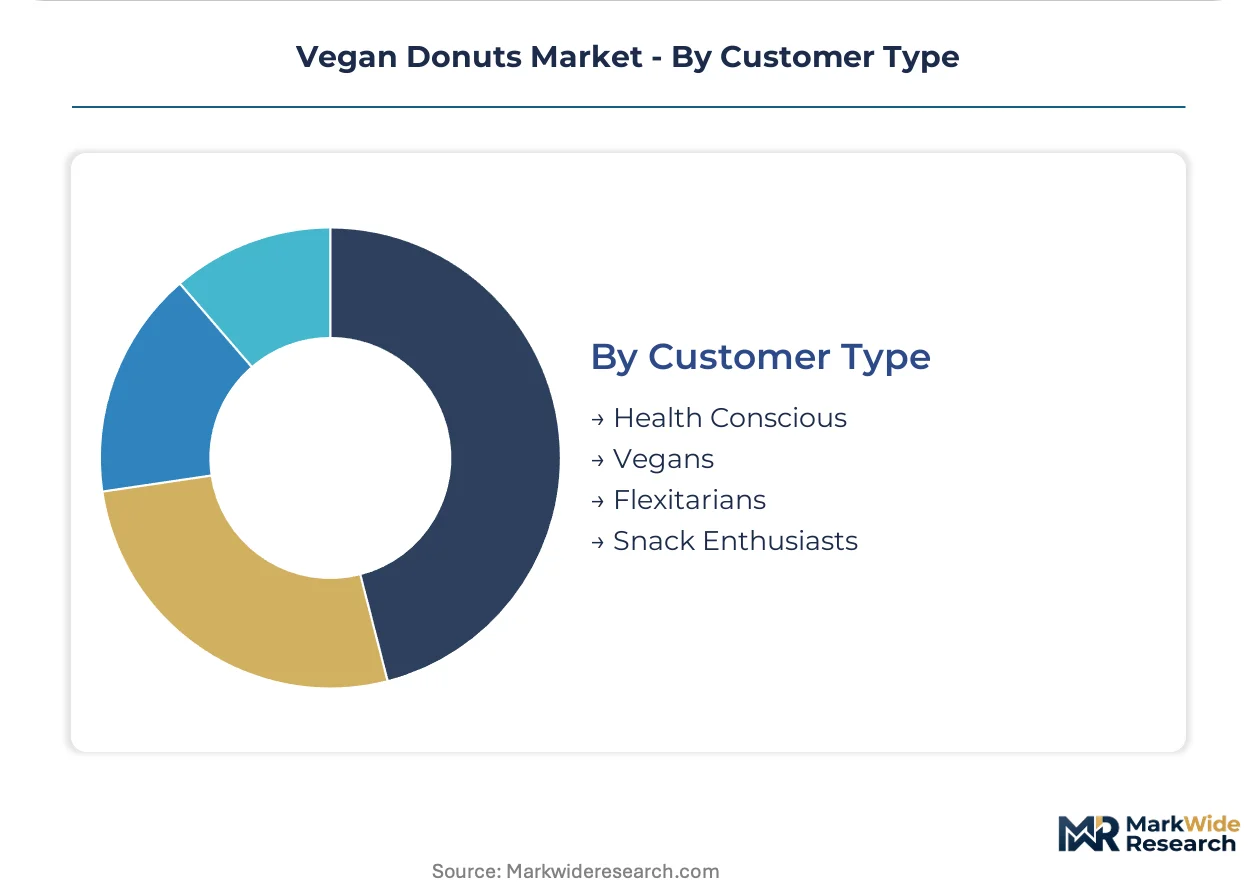
- Flexitarians:Sensory parity with conventional donuts drives purchase decisions, making this segment most receptive to precision-fermented protein formulations. Quick-service restaurant rollouts target this cohort specifically.
- Vegans:Third-party certification by Vegan Action or similar bodies functions as a non-negotiable filter, with ingredient transparency extending to supply chain ethics.
- Health Conscious:Clean-label positioning and reduced sugar claims resonate here, though taste compromise tolerance remains lower than for strict vegans.
- Snack Enthusiasts:Novelty and limited-edition drops drive engagement, with seasonal flavors and collaboration products capturing disproportionate attention.
Flexitarians represent the largest addressable population. Vegan-identified consumers generate the highest loyalty metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision-fermentation infrastructure outpaces US regulatory clearance timelines, while California metropolitan clusters generate higher per-capita vegan donut consumption than any European counterpart.
United States
Quick-service restaurant rollouts and specialty cafe density in Brooklyn and Portland drive volume. FDA plant-based labeling clarity under FALCPA reduces retail friction. California's cottage food law restrictions force emerging brands toward commercial kitchen investments in Los Angeles and San Francisco Bay Area clusters.
Germany
EU Green Deal-aligned consumer incentives and EFSA novel food approvals create favorable entry conditions for precision-fermented ingredient integration. The country's F-Gas Regulation phase-down accelerates industrial refrigeration retrofits. Berlin and Hamburg facilities lead CO2-based cooling adoption for bakery operations.
United Kingdom
Subscription-based procurement models concentrate in London metropolitan zones with higher customer lifetime value than wholesale channels. REACH compliance costs shape packaging material selection. Crosstown Doughnuts anchors the premium tier through limited-release collaborations in Soho and Shoreditch.
Canada
Health Canada oversight of novel food ingredients delays precision-fermented protein approvals relative to US timelines. Toronto and Vancouver specialty cafe markets show strong flexitarian demand. Provincial cottage food regulations in Ontario and British Columbia create uneven scaling pathways for small-batch producers.
Australia
TGA-aligned food standards and clean-label positioning resonate with health-conscious segments in Sydney and Melbourne. The country's agricultural export infrastructure supports almond flour supply chain integration. Melbourne's specialty coffee culture accelerates vegan donut placement in third-wave cafe channels.
Vegan Donuts Market Competitive Landscape
Top-tier vendors anchor premium artisan positioning, while mid-scale regional chains compete through certified organic supply chains and kitchen density. The vendor base stratifies across three archetypes: precision-fermentation early adopters, small-batch single-origin specialists, and quick-service franchise expanders. Dominant competitive moves include strategic partnerships with ingredient technology suppliers and geographic expansion through direct-to-consumer subscription models.
Within the small-batch specialist tier, Dun-Well Doughnuts and Mighty-O Donuts exemplify contrasting supply chain philosophies—Dun-Well leverages single-origin sourcing while Mighty-O competes through certified organic infrastructure. Blue Star Donuts occupies a middle-market position via brioche-style formulation differentiation. These three represent the competitive spectrum from premium artisan to accessible specialty without mass-market commodity positioning.
| Leading Market Players |
|---|
| Dun-Well Doughnuts |
| Mighty-O Donuts |
| Voodoo Doughnut |
| The Cinnamon Snail |
| Blue Star Donuts |
| Dottie's Donuts |
| Rise Biscuits Donuts |
| Glam Doll Donuts |
| Crosstown Doughnuts |
| Others |
Value Network & Pricing Analysis
Captive sourcing of precision-fermented proteins from Perfect Day and similar suppliers anchors premium-tier pricing power for US-based artisan producers, while commodity oat flour dependence compresses margins for mass-market entrants in Germany and the United Kingdom. This integration choice separates brands that command subscription premiums from those competing on grocery shelf velocity.
Pricing Analysis
Capacity additions in California and New York metropolitan clusters are reshaping price floors for small-batch vegan donuts as commercial kitchen density intensifies local competition. Three-tier pricing structure across premium artisan, certified organic, and mass-market economy levels segments buyers by certification grade and ingredient sourcing transparency. Pricing pressure stems from coconut oil volatility in Southeast Asian supply regions, with flexitarian consumers in quick-service channels showing highest price sensitivity and vegan-identified subscribers demonstrating lowest elasticity.
Supply Chain Analysis
Bioprocess engineering talent shortages in German precision-fermentation facilities and US commercial kitchen labor markets constrain scaling velocity for next-generation ingredient integration. Raw material flows center on coconut oil from Indonesia and the Philippines, almond flour from California agricultural zones, and oat flour from Nordic and North American grain belts. Single-source vulnerability in precision-fermented protein supply creates concentration risk for brioche-format producers. Distribution runs through direct-to-consumer subscription platforms for premium tiers and food-service wholesale contracts for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA clearance timelines for novel ingredients and EFSA's faster precision-fermentation approval pathways creates cost-advantaged production positioning for European facility investments relative to North American counterparts.
For Market Incumbents: Lock in exclusive supply agreements with precision-fermentation ingredient suppliers before commercial-scale capacity tightens. Defend subscription retention through limited-release flavor calendars that exploit the performance ceiling of aquafaba and flax meal alternatives to justify premium positioning against commodity entrants. For New Entrants and Emerging Players: Enter via dual allergen certification in oat flour-based cake formats, the most penetrable white space where gluten-free and vegan positioning intersect with underserved health-conscious segments. Target German retail channels leveraging EU Green Deal consumer incentives and favorable EFSA novel food timelines for faster market access than US regulatory pathways permit. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty cafe chains with established direct-to-consumer subscription infrastructure because customer acquisition costs amortize across recurring revenue pools unavailable to wholesale-dependent competitors. Monitor FDA guidance on cell-cultured ingredient labeling as the inflection signal for next-generation formulation parity and tier collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Partnership | Perfect Day whey integration resolves textural deficits in brioche formats previously unavailable to plant-based producers. |
| Direct-to-Consumer Subscription Launch | California and New York metropolitan clusters show retention rates above conventional bakery benchmarks through seasonal drops. |
| Dual Allergen Certification Investment | Simultaneous gluten-free and vegan positioning accesses intersection cohorts with limited competitive density. |
| German Retail Market Entry | EU Green Deal incentives and EFSA novel food approvals reduce regulatory friction relative to FDA timelines. |
| Commercial Kitchen Consolidation | Cottage food law restrictions in California and New York force capital-efficient regional kitchen network expansion. |
Research Methodology
Multiple input streams — primary interviews with vegan donut brand founders, commercial kitchen operators, and precision-fermentation ingredient suppliers; secondary validation through FDA plant-based labeling guidance documents, EFSA novel food approval databases, and specialty food retail audit data; plus customs records for coconut oil and almond flour trade flows — were reconciled through bottom-up production volume estimates and top-down consumer expenditure triangulation.
Data-stream reconciliation across product type, ingredient base, distribution channel, and customer motivation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate convergence modeling, with precision-fermented protein adoption curves and quick-service restaurant rollout schedules as category-specific forecast inputs.
Inputs from FDA enforcement records and EFSA approval timelines were available through the study window; gaps in real-time precision-fermentation capacity expansion data introduce uncertainty bands around next-generation ingredient cost projections. Forecasts reflect documented assumptions regarding regulatory clearance velocity and consumer willingness-to-pay for sensory parity. Material deviation in FDA guidance release schedules or coconut oil supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Calorie Pie Market
Bakery Products
Pastries Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Sourdough Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Pie Shells Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Teaseed Cake Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Lentil Bread Market
Bakery Products
Specialty Bakery Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Specula Market
Bakery Products
Global Cake Mix Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market