
 Acoustic Materials Market | 2026-2036
Acoustic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Materials Market Analysis
The capital-intensity divergence between integrated mineral wool producers and specialized foam fabricators is unwinding as raw material volatility forces portfolio rebalancing. ROCKWOOL International A/S leverages its captive stone wool supply chain to sustain margin stability across European project pipelines. Saint Gobain anchors its position through multi-material platforms that span fiberglass, gypsum, and composite acoustic systems. Owens Corning differentiates via building science integration, bundling thermal and acoustic performance in single specification packages for North American contractors.
Acoustic materials encompass engineered substrates designed to absorb, damp, or block sound energy across frequencies from 125 Hz to 4 kHz, typically fabricated from open-cell foams, mineral fibers, or perforated composites with Noise Reduction Coefficients ranging from 0.70 to 1.05. Their primary commercial purpose centers on controlling reverberation and airborne sound transmission in occupied spaces, machinery enclosures, and vehicle cabins. Mineral wool leads product type segments due to fire-rated performance in commercial construction, while foam competes aggressively on lightweighting in automotive applications. The entertainment end user category shows structural momentum as streaming content production drives studio buildouts requiring precision acoustic treatment.
The US EPA and OSHA set occupational noise exposure limits that mandate hearing conservation programs and engineered controls in manufacturing facilities, directly stimulating industrial acoustic enclosure procurement. The EU Green Deal and F-Gas Regulation push manufacturers toward bio-based binders and recycled content in insulation products, reshaping material qualification requirements. REACH compliance in Europe and evolving GB standards in China add testing cost layers that favor scaled laboratories with established certification pathways. Stakeholders must monitor how building decarbonization mandates merge thermal and acoustic specifications into unified performance codes that could disqualify legacy product formulations.
Market Dynamics
Building decarbonization mandates are merging thermal and acoustic performance into unified specification codes, forcing material suppliers to reformulate legacy products for dual-compliance or face disqualification from public procurement pipelines.
Growth Catalysts
- EU Green Deal implementation:The F-Gas Regulation and building renovation wave are mandating higher acoustic performance in retrofits across Germany, France, and Italy, pulling mineral wool and bio-based panels into public tenders.
- Automotive lightweighting:Electric vehicle manufacturers in China and the United States are specifying micro-perforated composites and recycled PET foams to offset battery weight while maintaining cabin NVH targets.
- Streaming studio buildouts:Content production facilities in Los Angeles, London, and Mumbai are driving precision acoustic treatment demand for dialogue recording and mixing environments.
Market Restraints
- Raw material volatility:Flux in basalt and slag availability is compressing margins for stone wool producers dependent on captive smelter partnerships in Scandinavia and Eastern Europe.
- REACH compliance costs:European chemical registration requirements for formaldehyde-free binders are adding testing layers that disadvantage smaller foam fabricators without established certification pathways.
- Substitute competition:Mass timber and cross-laminated timber systems with inherent acoustic mass are displacing conventional panel installations in Nordic commercial construction.
Strategic Opportunities
- India infrastructure buildout:Metro rail expansions in Delhi, Mumbai, and Bangalore are creating specification windows for trackbed isolation and station acoustic treatment as the country upgrades urban transit.
- Healthcare acoustics:Hospital renovation programs in Japan and Germany are adopting sound-absorbing ceiling systems to meet patient recovery metrics and HCAHPS-equivalent scoring frameworks.
- Digital specification platforms:Building information modeling integration is enabling direct-to-contractor acoustic product selection, bypassing traditional distributor markup in North American commercial construction.
Industry Challenges
- Acoustic engineer scarcity:Specialized talent for computational aeroacoustics and material damping modeling is concentrated in German and Japanese research institutes, creating recruitment bottlenecks for product development teams.
- Multi-certification timelines:Simultaneous pursuit of LEED, BREEAM, and WELL certification for acoustic products extends commercialization cycles by 8-14 months in premium building segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Materials Market |
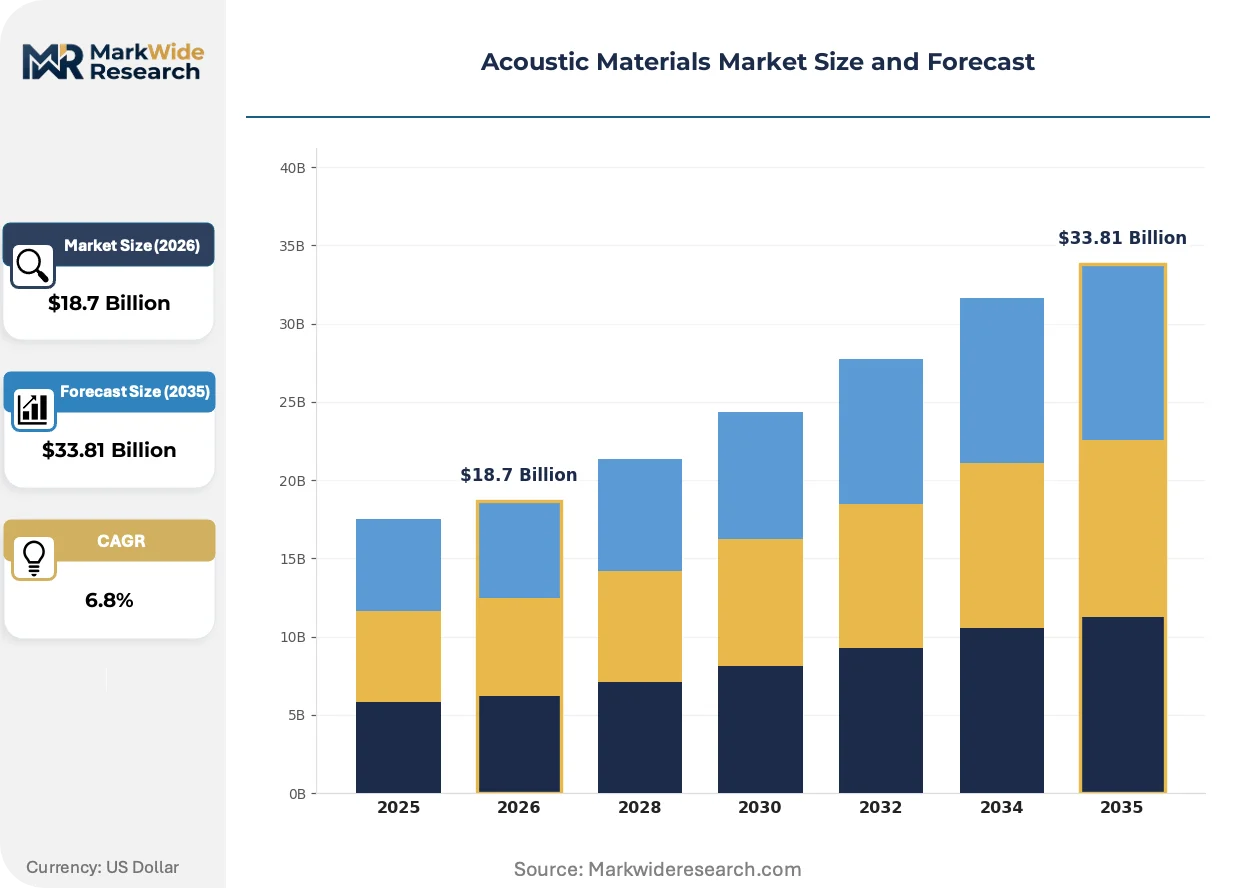
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fiberglass, Mineral Wool, Acoustic Panels Application: Soundproofing, Noise Control, Acoustic Treatment, Insulation End User: Construction, Automotive, Aerospace, Entertainment Material: Polyester, Wood, Rubber, Others |
| Companies Covered | Armstrong World Industries, Inc., ROCKWOOL International A/S, Acoustical Solutions, Inc., Knauf Insulation, Saint Gobain, Sound Seal, Owens Corning, Johns Manville, Vertisol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Materials Market Emerging Trajectories
Active noise control systems and metamaterial architectures are compressing the performance gap between bulky passive treatments and space-constrained applications, reshaping R&D allocation across substrate categories.
Metamaterial acoustic liners with subwavelength resonant structures are miniaturizing sound absorption into millimeter-scale geometries. Aerospace and automotive OEMs in Germany and Japan are piloting these substrates for engine nacelles and HVAC modules. The technology is miniaturizing equipment envelopes that previously required 50-100mm of conventional foam or fiber thickness.
The EPA's updated occupational noise exposure guidelines are tightening enforcement of hearing conservation programs in metal fabrication and food processing facilities. Industrial buyers in the United States are responding with engineered acoustic enclosure procurement rather than administrative controls alone. OSHA-mandated engineering controls are accelerating specification of modular machine guarding with integrated absorption.
Streaming platform technical standards are compressing studio construction cycles as content houses race to operationalize new production capacity. Acoustic treatment vendors in Los Angeles, London, and Seoul are unbundling design services from material supply, selling performance-guaranteed packages directly to facility owners. This disintermediation is visible most acutely in podcast and voice-over studio buildouts where rapid deployment outweighs traditional architectural acoustic consulting relationships.
Acoustic Materials Market Segmentation
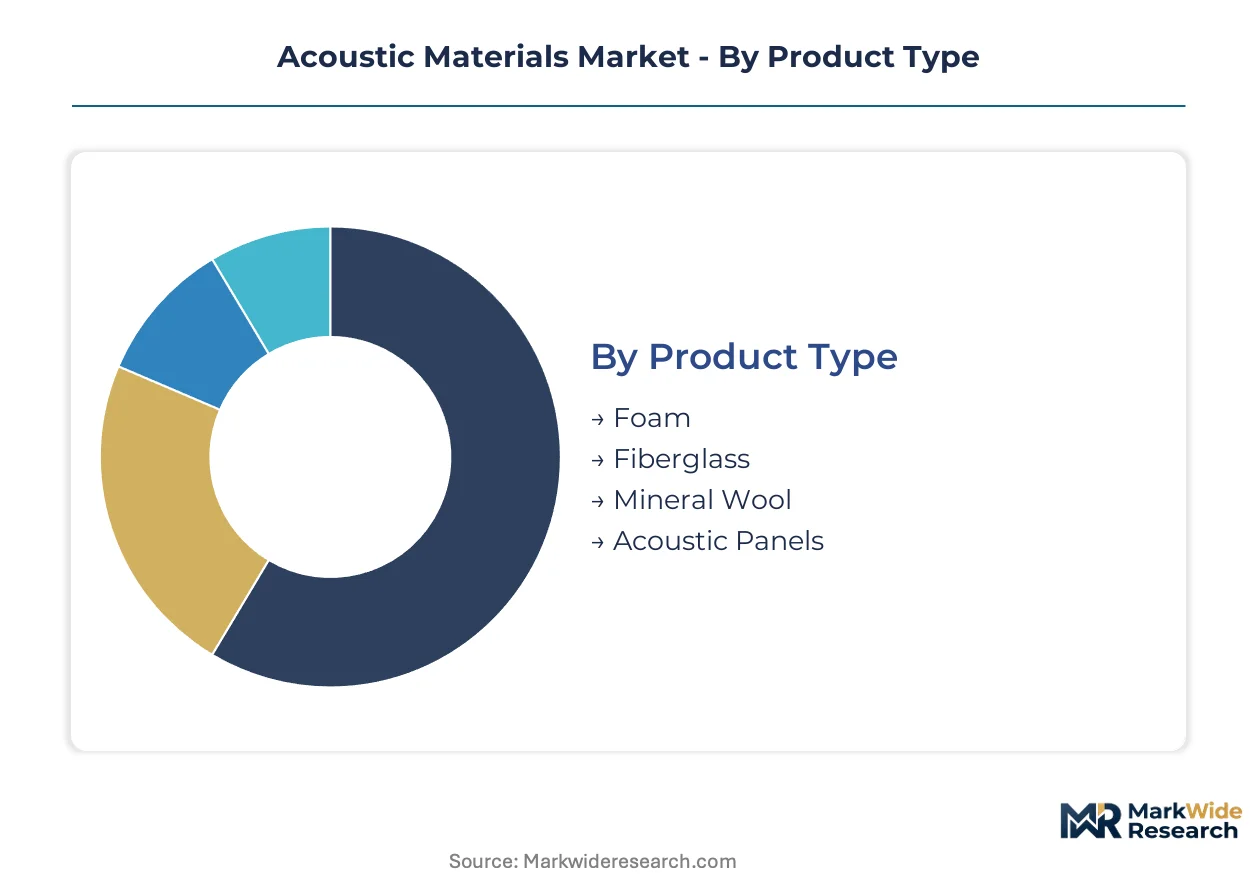
Acoustic materials procurement diverges sharply across end-use verticals, with construction buyers prioritizing fire-rated mineral formulations while automotive engineers chase gram-level weight reductions. Specification standards in Germany, China, and the United States create incompatible certification pathways that fragment product portfolios.
Product Type:
Mineral wool and fiberglass production clusters in Scandinavia and Eastern Europe serve export-heavy project pipelines, while foam fabrication localizes near automotive assembly plants in China and the southern United States.
- Foam:Open-cell polyurethane and melamine formulations achieve Noise Reduction Coefficients above 0.90 in thicknesses under 25mm. Electric vehicle manufacturers in China specify micro-perforated variants to offset battery pack mass while maintaining cabin quietness targets.
- Mineral Wool:Stone wool spun from basalt and slag delivers fire resistance ratings exceeding 1000°C without combustion. German and French public tenders under the EU Green Deal renovation wave specify bio-based binders that disqualify conventional formaldehyde-cured production.
- Fiberglass:Fine-diameter glass fibers bound with thermosetting resins dominate North American commercial ceiling systems. Owens Corning bundles these with thermal insulation for single-source contractor procurement.
- Acoustic Panels:Perforated wood, metal, and composite facings over absorbent cores serve architectural visibility requirements in corporate and hospitality interiors.
Mineral wool commands the established base. The steepest expansion runs through foam lightweighting for electrified transport.
Application:
Cost-tier stratification separates commodity insulation from precision acoustic treatment, with the latter commanding 3-4x material cost premiums for certified studio and healthcare environments.
- Soundproofing:Mass-loaded barriers and decoupled wall assemblies block airborne transmission between occupied zones. Metro rail expansions in Delhi, Mumbai, and Bangalore create specification windows for trackbed isolation systems.
- Acoustic Treatment:Precision absorption tuning for reverberation control in recording studios and broadcast facilities. Streaming platform technical standards in Los Angeles and London compress construction cycles for dialogue-critical spaces.
- Noise Control:Industrial machinery enclosures and HVAC silencers addressing OSHA and EPA occupational exposure mandates in US metal fabrication plants.
- Insulation:Thermal-acoustic dual-performance products merging building decarbonization codes with sound transmission class requirements.
Soundproofing absorbs the largest project volumes. Acoustic treatment climbs fastest as content production infrastructure multiplies.
End User:
Customer-type concentration varies by margin structure, with aerospace and entertainment buyers accepting performance premiums that construction procurement rarely tolerates.
- Construction:Commercial and residential builders specifying mineral wool and panels under tightened energy codes. The EU Green Deal and evolving GB standards in China merge thermal and acoustic compliance into unified tender requirements.
- Automotive:Cabin NVH and powertrain isolation for internal combustion and electric platforms. Recycled PET foams gain specification as OEMs respond to EU F-Gas Regulation pressures on synthetic alternatives.
- Entertainment:Studio buildouts for streaming content production in Los Angeles, London, and Mumbai. Vendors disintermediate traditional acoustic consultants by selling performance-guaranteed packages directly to facility owners.
- Aerospace:Engine nacelle liners and cabin sidewall treatments where gram-level weight penalties compound across fleet scales. German and Japanese OEMs pilot metamaterial architectures for subwavelength absorption.
Construction anchors volume demand. Entertainment generates the most rapid specification evolution as technical standards tighten.
Material:
Supply concentration for polyester and wood substrates differs fundamentally from rubber compounding, with the latter dependent on petrochemical feedstock integration.
- Polyester:Recycled PET fiber felts and thermoformed shapes serve automotive and architectural applications. REACH compliance for formaldehyde-free binders favors scaled European producers with established ECHA registration pathways.
- Wood:Perforated and grooved timber facings over mineral fiber cores meet biophilic design specifications. Mass timber construction in Nordic markets displaces conventional panel installations through inherent acoustic mass.
- Rubber:EPDM and neoprene sheets for vibration isolation and duct lining in industrial and transportation applications.
- Others:Emerging bio-based and aerogel formulations under early commercialization for premium thermal-acoustic performance.
Polyester scales fastest on recycled content mandates. Wood maintains steady specification in sustainability-weighted procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French specification markets where EU Green Deal mandates enforce bio-based binder requirements, while Chinese producers compete on volume without equivalent regulatory premium capture.
United States
Infrastructure renewal programs and automotive manufacturing clusters drive procurement across the Midwest and Southeast. OSHA mandates engineering controls for occupational noise exposure, accelerating specification of modular acoustic enclosures in metal fabrication plants. Detroit and Nashville automotive corridors specify lightweight foam treatments for electric vehicle NVH targets.
Germany
Public tender volumes under the EU Green Deal renovation wave pull mineral wool and bio-based panels into commercial retrofits. REACH compliance for formaldehyde-free binders favors scaled producers with established ECHA registration pathways. The Ruhr industrial belt and Bavarian automotive clusters concentrate specification activity for dual-performance thermal-acoustic systems.
China
Metro rail expansions in Beijing, Shanghai, and Shenzhen create demand for trackbed isolation and station acoustic treatment. GB standards evolution merges thermal and acoustic compliance into unified building codes. Yangtze River Delta manufacturing bases localize foam fabrication near electric vehicle assembly plants.
India
Urban transit upgrades in Delhi, Mumbai, and Bangalore drive specification windows for precision acoustic treatment. Central Electricity Authority noise regulations for power infrastructure stimulate industrial enclosure procurement. Maharashtra and Karnataka industrial corridors attract material suppliers targeting infrastructure buildout timelines.
Japan
Hospital renovation programs adopt sound-absorbing ceiling systems to meet patient recovery metrics and equivalent HCAHPS scoring frameworks. METI building efficiency standards tighten acoustic performance requirements in commercial retrofits. Osaka and Nagoya manufacturing clusters concentrate precision acoustic engineering talent for automotive and aerospace applications.
Acoustic Materials Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated mineral wool producers sustaining margin stability through captive raw material supply while specialized foam fabricators compete on lightweighting specifications. The vendor base stratifies across three tiers: multinational building science platforms with multi-material portfolios, regional insulation specialists with deep distribution relationships, and niche acoustic treatment vendors serving entertainment and precision industrial applications. Dominant competitive moves include backward integration into basalt and slag supply chains, and portfolio diversification into bio-based binder formulations to meet EU regulatory requirements.
Among Denmark and France-based building materials platforms, ROCKWOOL International A/S and Saint Gobain occupy positions representing integrated mineral fiber supply chain control and multi-material specification breadth respectively. Owens Corning exemplifies the North American building science integration archetype, bundling thermal and acoustic performance for single-source contractor procurement. These three anchors illustrate how geographic regulatory exposure and raw material access shape competitive positioning across distinct specification environments.
| Leading Market Players |
|---|
| Armstrong World Industries, Inc. |
| ROCKWOOL International A/S |
| Acoustical Solutions, Inc. |
| Knauf Insulation |
| Saint Gobain |
| Sound Seal |
| Owens Corning |
| Johns Manville |
| Vertisol |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day raw material inventory positions among Scandinavian stone wool producers translate directly into pricing power over project contractors facing compressed construction timelines in Germany and France. This lead-time buffer insulates integrated suppliers from basalt and slag volatility while forcing smaller foam fabricators to absorb spot-market swings or surrender margin.
Pricing Analysis
Configured-to-order acoustic treatment packages for streaming studios command 40-60% premiums over standard mineral wool batts sold through distribution. Project-based pricing dominates construction procurement, with differentiation driven by fire-rating certification tier and customization depth for architectural visibility requirements. Pricing pressure stems from recycled PET foam capacity expansion in China's Yangtze River Delta, which is compressing margins in automotive lightweighting tiers. Construction buyers exhibit highest price sensitivity, while aerospace and entertainment procurement accepts performance premiums without volume negotiation.
Supply Chain Analysis
Just-in-time inventory strategies prevail among automotive foam fabricators locating near assembly plants, while mineral wool producers maintain strategic stockpiles of basalt and slag to hedge smelter partnership volatility. Supply concentrates in Denmark, Germany, and China for stone wool and fiberglass production, with foam fabrication localizing near electric vehicle clusters in the United States and China. Raw material dependencies include basalt feedstock, formaldehyde-free binder chemistries, and recycled PET flake. Single-source vulnerability runs through captive Scandinavian smelter relationships for stone wool. Distribution runs through specification-influencer channels where acoustic consultants and building information modeling platforms direct contractor procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers defensive moats through regulatory entrenchment: REACH compliance and EU Green Deal bio-based mandates create certification barriers that scaled incumbents leverage to exclude smaller competitors from public tender pipelines.
For Market Incumbents: Secure backward integration into basalt and slag supply chains to defend margin stability against raw material volatility in Eastern European smelter partnerships. Expand captive binder chemistry capabilities to meet ECHA registration requirements for formaldehyde-free formulations, preempting disqualification from French and German renovation tenders. Threat substitution from mass timber acoustic systems in Nordic commercial construction demands portfolio diversification into composite panel architectures. For New Entrants and Emerging Players: Anchor in India's metro rail expansion corridors where trackbed isolation specification windows remain underpenetrated by established European suppliers. Target precision acoustic treatment for podcast and voice-over studio buildouts in secondary US and European cities, where rapid deployment needs outpace traditional consultant-led procurement cycles. Go-to-market traction requires performance-guaranteed direct sales models that disintermediate distributor markups and accelerate facility owner decision velocity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based binder formulation segments as ECHA registration costs concentrate capability among scaled laboratories. Long-term viability favors platforms with multi-material portfolios spanning mineral wool, fiberglass, and foam architectures that adapt to unified thermal-acoustic building codes. Acquisition targets should display established certification pathways for REACH and evolving GB standards. Monitor EU F-Gas Regulation enforcement intensity as the inflection signal for recycled PET foam substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive basalt and slag access insulates ROCKWOOL and regional peers from smelter partnership volatility. |
| Bio-Based Binder Certification Investment | Formaldehyde-free formulation registration with ECHA secures eligibility for EU Green Deal public tenders. |
| Building Information Modeling Platform Integration | Direct-to-contractor specification through Autodesk and Bentley platforms bypasses traditional distributor markup capture. |
| Metamaterial Architecture R&D Partnership | Subwavelength resonant structures piloted by German and Japanese aerospace OEMs compress equipment envelope requirements. |
| Healthcare Acoustics Portfolio Expansion | Sound-absorbing ceiling systems align with Japan's patient recovery metrics and Germany's HCAHPS-equivalent frameworks. |
Methodological Framework
Cross-validation between primary interviews with acoustic material procurement managers and secondary trade data anchors the qualitative findings in observable contract flow patterns. Stakeholder engagement spanned building science directors at multinational insulation platforms, specification engineers at automotive OEMs, acoustic consultants in Los Angeles and London studio markets, and procurement leads at Indian metro rail authorities. Secondary sources included customs records for basalt and slag trade flows, ECHA registration databases for binder chemistry compliance, SEC filings from listed building materials platforms, and EU tender documentation for Green Deal renovation awards. Bottom-up project pipeline enumeration triangulates against top-down construction spending forecasts.
Sensitivity analysis across raw material cost scenarios and regulatory enforcement intensity brackets tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type tier, end-use vertical, application specificity, and regional regulatory cluster. CAGRs derive from polynomial trend fitting to historical procurement volumes, adjusted for policy-driven inflection points. Industry-specific inputs encompass electric vehicle production schedules for foam lightweighting demand and streaming platform content budget disclosures for studio buildout timing.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal implementation and OSHA enforcement stability; material deviation would warrant model refresh. Forecasts incorporate baseline scenarios for REACH compliance cost trajectories and GB standards evolution in China. Revision becomes warranted when bio-based binder cost parity crosses threshold viability against conventional formaldehyde-cured alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Technical Foam Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Phase Change Materials Market