
 Asia-Pacific Insulation Materials Market | 2026-2036
Asia-Pacific Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insulation Materials Market Analytics
Japan's Top Runner Program for building energy efficiency is realigning specification priorities across the region. Owens Corning leverages its fiberglass technology leadership to anchor premium commercial projects in East Asian metropolitan zones. BASF SE competes through polyurethane foam formulations that sustain higher R-value performance in tropical humidity conditions. Rockwool International A/S specializes in fire-resistant mineral wool systems that dominate industrial equipment applications across ASEAN manufacturing hubs.
Asia-Pacific insulation materials encompass engineered thermal barriers with defined thermal conductivity coefficients, typically ranging below 0.040 W/m·K for high-performance grades, manufactured through blown fiber, extruded foam, or spun mineral processes to reduce heat transfer in built environments and mechanical systems. Mineral wool commands established volume in heavy industrial settings across the region, while polyurethane foam captures expanding share in cold storage and HVAC applications where space-constrained envelope performance matters most. Fiberglass maintains cost competitiveness in residential construction, though polystyrene variants face substitution pressure from higher-performing alternatives in premium commercial specifications.
China's MEE enforces building energy codes that mandate minimum insulation thicknesses for new commercial structures, while India's BIS certification requirements for fire safety performance create compliance barriers for uncertified imports. Japan's METI standards and Australia's NCC energy efficiency provisions collectively shape product development roadmaps for suppliers operating across multiple Asia-Pacific jurisdictions. Stakeholders must monitor divergence between national fire safety protocols and thermal performance benchmarks when configuring regional manufacturing and distribution strategies.
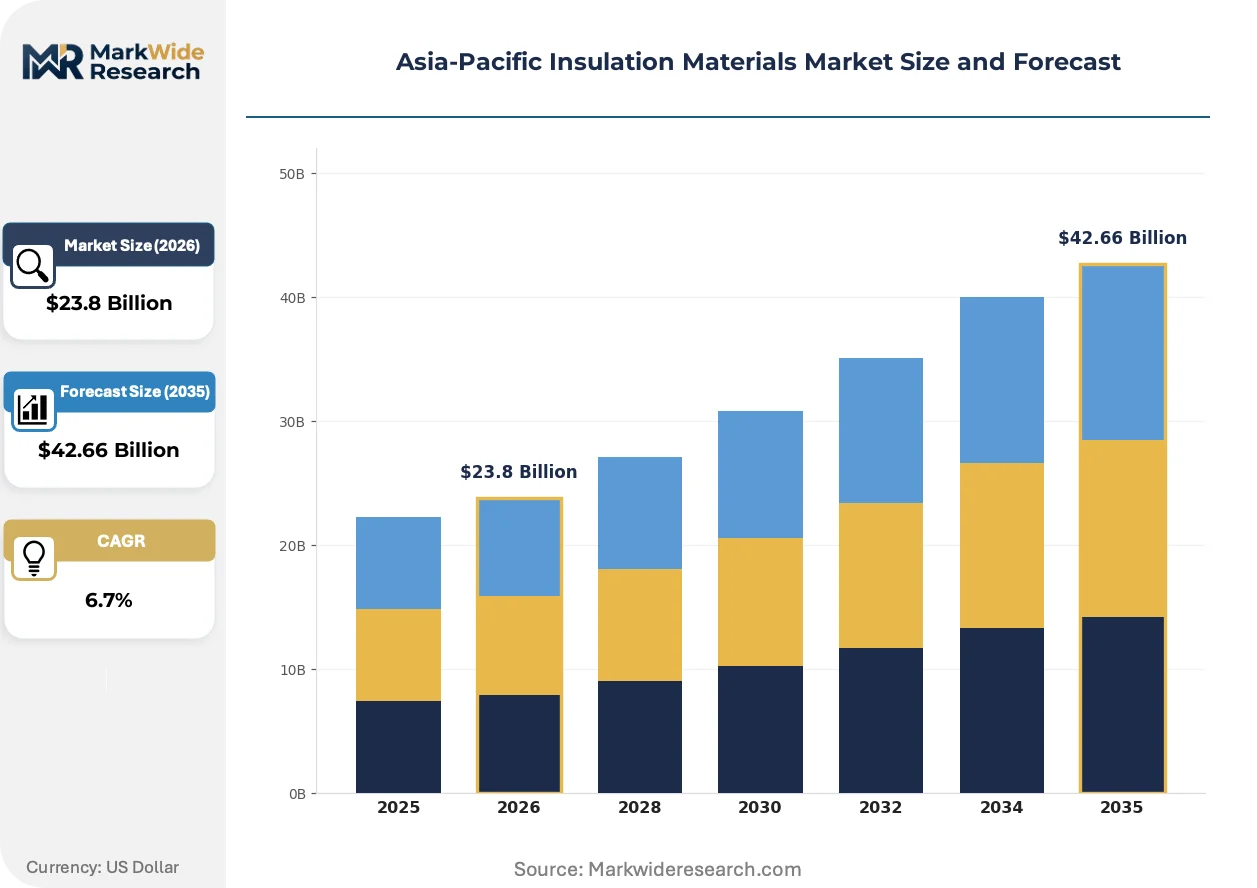
Market Dynamics
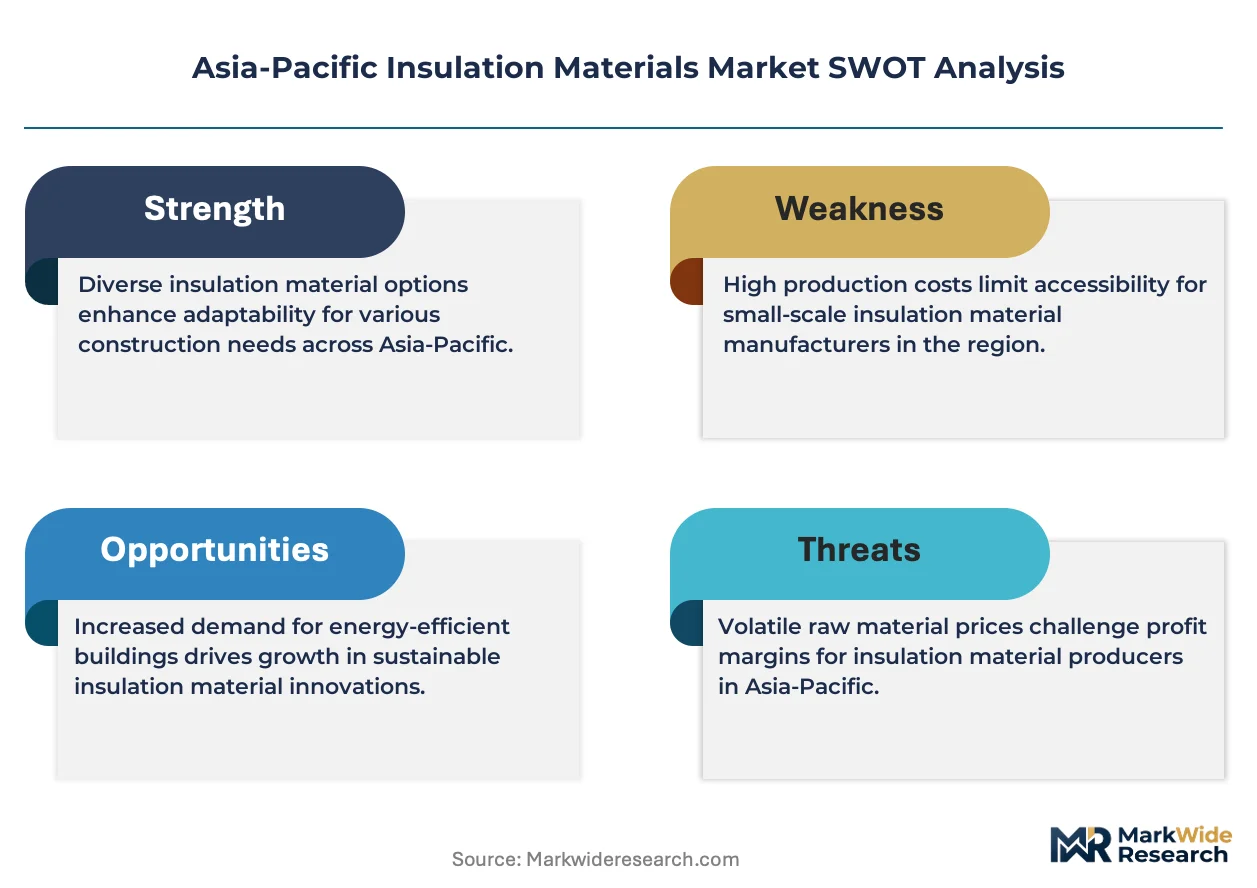
China's dual carbon goals and Japan's METI Top Runner Program are compressing thermal performance thresholds across the region, forcing specification upgrades in commercial construction and industrial equipment faster than supply chains can adapt material formulations.
Growth Catalysts
- Cold Storage Logistics Expansion:Southeast Asian 3PL operators are retrofitting warehouse envelopes with higher R-value materials to meet pharmaceutical and food-grade temperature stability requirements.
- Japan's METI Building Efficiency Codes:Mandatory insulation thickness minimums for commercial structures are pulling premium-grade mineral wool and polyurethane foam into new construction specifications.
- Industrial Corridor Concentration:India's Gujarat-Maharashtra-Tamil Nadu manufacturing belt is driving sustained demand for fire-resistant insulation in process equipment and HVAC infrastructure.
Market Restraints
- Petrochemical Input Volatility:Polyurethane foam producers face margin compression from benzene and MDI price swings that resist full pass-through in contract pricing.
- Import Certification Barriers:India's BIS fire safety certification requirements block uncertified mineral wool and fiberglass shipments from ASEAN manufacturing hubs.
- Fiberglass Substitution Pressure:Polystyrene and fiberglass face displacement in premium commercial specifications where polyurethane foam delivers higher thermal resistance per unit thickness.
Strategic Opportunities
- Vietnam Industrial Zones:Underpenetrated northern manufacturing clusters offer first-mover positioning for suppliers establishing local mineral wool production capacity.
- Australia Commercial Retrofit Wave:NCC energy efficiency upgrades are creating replacement demand in Sydney and Melbourne office stock built before 2010 thermal codes.
- Prefabricated Panel Integration:Cold storage and data center builders are specifying factory-integrated insulation systems that compress installation labor and field waste.
Industry Challenges
- Fire Safety Testing Bottlenecks:BIS and JIS certification timelines stretch 8-14 months, delaying product launches and locking working capital in compliance pipelines.
- Technical Workforce Scarcity:Proper installation of spray polyurethane foam and vacuum-insulated panels requires certified applicators that Southeast Asian markets lack at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insulation Materials Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fiberglass, Mineral Wool, Polystyrene Application: Building and Construction, HVAC, Cold Storage, Industrial Equipment Material: Polyurethane, EPS, XPS, Cellulose End User: Residential, Commercial, Industrial, Other |
| Companies Covered | Owens Corning, BASF SE, Rockwool International A/S, Saint-Gobain S.A., Kingspan Group PLC, Armacell International S.A., Knauf Insulation, Asahi Kasei Corporation, Johns Manville, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insulation Materials Market Evolving Landscape
Aerogel composites and bio-based polyurethane formulations are penetrating high-value niches as established materials hit thermal performance ceilings. The competitive frontier is shifting toward integrated envelope systems rather than commodity batt and board sales.
Vacuum insulation panels are absorbing share in space-constrained cold chain applications where conventional materials cannot achieve target U-values within envelope thickness limits. Japanese pharmaceutical distributors and Australian supermarket chains are specifying VIP retrofits for existing refrigerated warehouses. This technology is absorbing margin from commodity polystyrene in premium segments where floor space economics dominate material cost considerations.
China's MEE enforcement of GB 50189 building energy codes is mandating real-time thermal performance monitoring in commercial structures above 20,000 square meters. Developers in Shanghai and Shenzhen are pre-specifying higher-grade insulation to guarantee compliance margins against inspection uncertainty. Northern Chinese provinces with stricter winter heating regulations are seeing accelerated substitution of mineral wool for lower-performing alternatives in residential high-rises.
Data center operators across Singapore, Sydney, and Tokyo are unbundling insulation specification from general contractor procurement, engaging directly with material suppliers for thermal envelope design. This disintermediation compresses distributor margins while rewarding suppliers with computational fluid dynamics modeling capabilities. The shift is most visible in hyperscale cloud facility builds where thermal management directly impacts PUE targets and carbon disclosure requirements.
Asia-Pacific Insulation Materials Market Segmentation
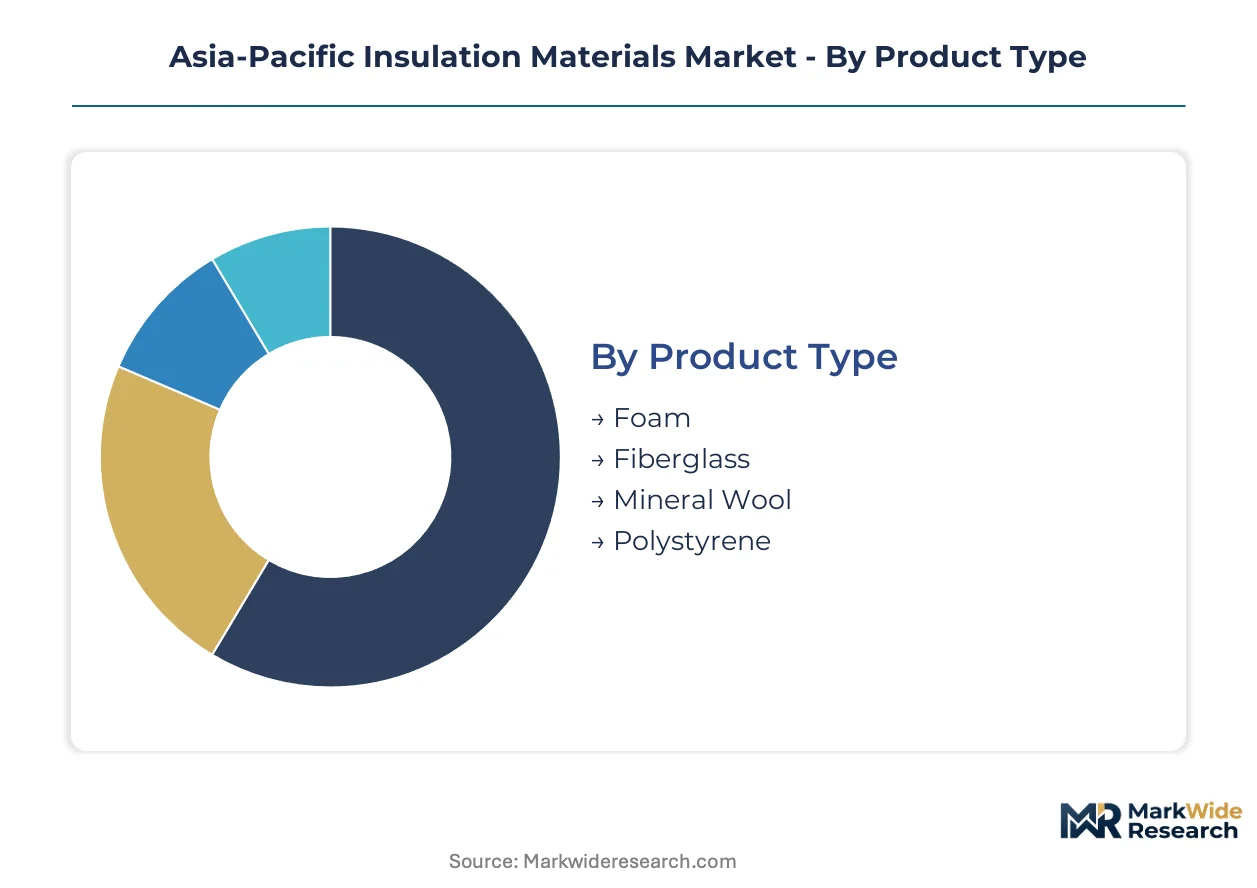
Insulation material selection across Asia-Pacific hinges on thermal performance coefficients, fire safety ratings, and installation labor economics. Specification patterns diver sharply between standalone retrofit applications and factory-integrated envelope systems where material choice is locked at the panel fabrication stage.
Product Type:
Foam and fiberglass dominate standalone specification for contractor-driven installations, while mineral wool and polystyrene concentrate in embedded systems where fire ratings and dimensional stability are predetermined at the manufacturing node.
- Foam:Polyurethane and polyisocyanurate formulations deliver thermal conductivity below 0.025 W/m·K, enabling thinner envelope assemblies. Cold storage operators in Vietnam and Thailand specify spray-applied foam for retrofit warehouse ceilings where headroom constraints prohibit thicker mineral wool batts. The material's adhesion to irregular substrates reduces thermal bridging at structural penetrations.
- Fiberglass:Blown and batt configurations manufactured through rotary fiberization maintain cost positions 15-30% below foam alternatives. Residential developers in India's Pune and Hyderabad corridors default to fiberglass for multi-story housing where code minimums do not mandate higher R-values per unit thickness.
- Mineral Wool:Spun rock and slag fibers achieve non-combustibility ratings under China's GB 8624 and Japan's JIS A 9511 standards. Industrial boiler cladding and petrochemical facility insulation across Indonesia's Cilegon and Malaysia's Pasir Gudang zones specify mineral wool for process safety compliance.
- Polystyrene:Expanded and extruded variants face substitution pressure in premium specifications where thermal drift in humid tropical conditions degrades long-term performance. Remaining demand concentrates in cost-sensitive residential foundations and below-grade waterproofing assemblies.
Volume placements concentrate in fiberglass; the faster expansion belongs to foam.
Application:
Building and construction absorbs the majority of material tonnage, yet HVAC and cold storage applications command premium pricing through performance-specified procurement channels that bypass commodity distribution tiers.
- Building and Construction:Envelope insulation for commercial high-rises and residential towers across China's Yangtze River Delta and India's National Capital Region. METI's Top Runner Program and MEE's GB 50189 enforcement are compressing U-value maximums, forcing specification upgrades in curtain wall spandrel panels and roof assemblies.
- HVAC:Chilled water pipe insulation and air handling unit lining in Australia's NCC-regulated commercial retrofits and Singapore's tropical high-rise districts. Phenolic foam and closed-cell elastomers compete for ductwork applications where condensation control intersects with energy efficiency targets.
- Cold Storage:Warehouse envelope and refrigerated transport box specifications for pharmaceutical and food-grade 3PL operators. Vacuum insulation panels penetrate this segment where floor space economics override material cost premiums in Tokyo and Sydney distribution hubs.
- Industrial Equipment:Furnace lining, turbine insulation, and process vessel cladding across ASEAN manufacturing corridors. Fire-resistant mineral wool and calcium silicate boards dominate where equipment surface temperatures exceed 400°C and hot work permits mandate non-combustible materials.
Building and construction claims the largest material offtake; cold storage is climbing the fastest on a value-per-kilogram basis.
Material:
Polyurethane and XPS occupy the high-performance tier with closed-cell structures that resist moisture ingress, while EPS and cellulose serve cost-optimized applications where thermal drift tolerance is higher.
- Polyurethane:Rigid foam boards and spray-applied systems achieve the highest R-values per inch among mass-produced insulation materials. Japanese pharmaceutical cold chain operators and Australian supermarket refrigeration retrofits specify polyurethane for envelope thickness constraints in existing building footprints.
- EPS:Molded bead foam for foundation perimeter insulation and geofoam applications where compressive strength requirements are moderate. Indian residential developers in Gujarat and Maharashtra deploy EPS for below-grade waterproofing protection boards.
- XPS:Extruded polystyrene with homogeneous closed-cell structure resists water absorption in inverted roof assemblies and plaza deck applications. Commercial podium developments in Singapore and Hong Kong specify XPS for green roof substrates where long-term load-bearing capacity is critical.
- Cellulose:Recycled fiber loose-fill and dense-pack systems for timber-framed residential construction. Australian bushfire-prone regions restrict cellulose applications where ember attack ratings override sustainability preferences.
Polyurethane commands the highest value density; cellulose holds the smallest regional share.
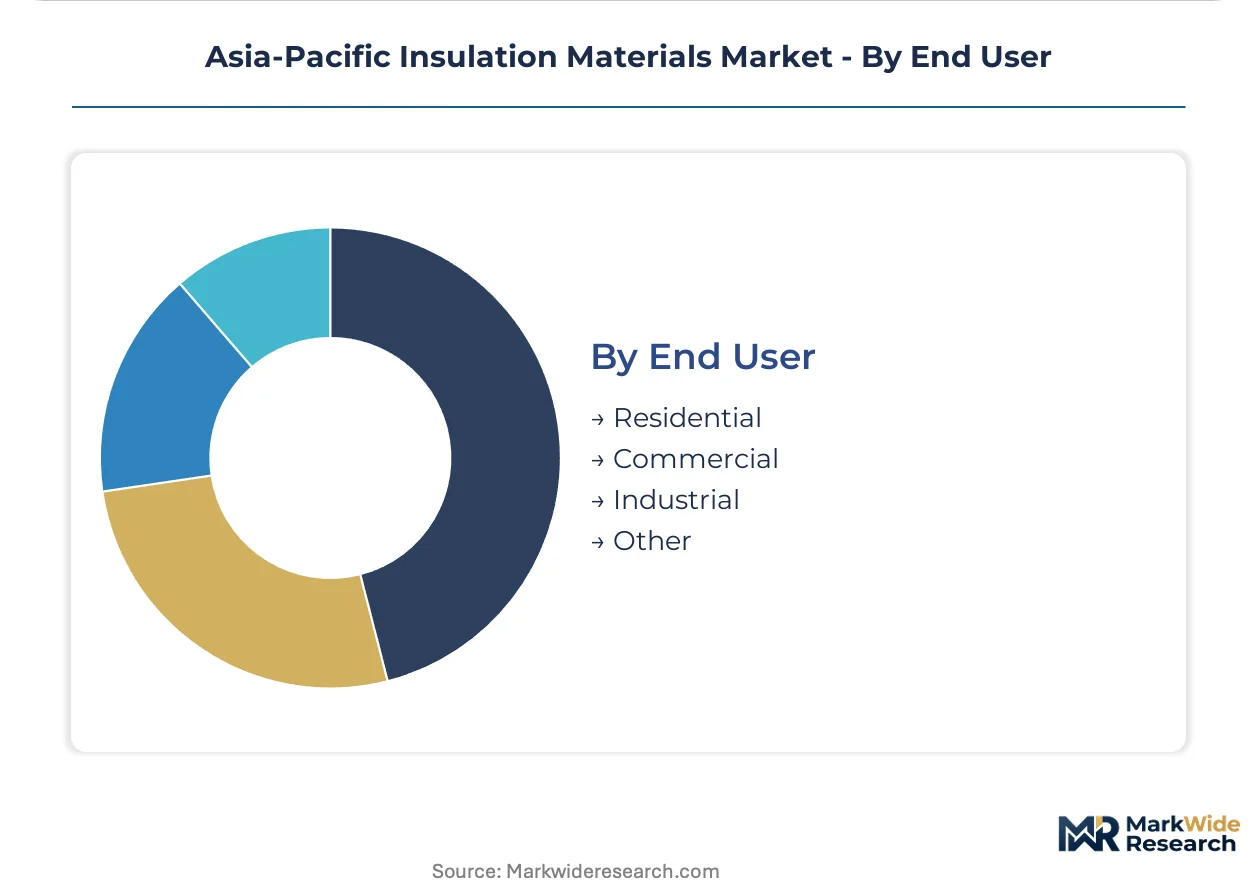
End User:
Industrial buyers specify through engineered procurement channels with thermal modeling validation, while residential demand flows through contractor networks with limited design oversight and code-minimum compliance focus.
- Residential:Single-family and multi-family housing across China's tier-2 cities and India's state capital districts. Northern Chinese provinces with district heating networks mandate minimum insulation thicknesses that default to fiberglass and mineral wool in high-rise concrete construction.
- Commercial:Office towers, retail complexes, and hospitality developments in Tokyo, Seoul, and Sydney. NCC energy efficiency provisions and METI building codes are disintermediating general contractors as developers engage insulation suppliers directly for thermal envelope design liability.
- Industrial:Process equipment, power generation, and manufacturing facility operators across ASEAN industrial zones. Fire safety certification under India's BIS and Indonesia's SNI standards creates compliance barriers for uncertified imports, favoring local mineral wool production.
- Other:Agricultural structures, transportation equipment, and specialized infrastructure including data centers. Hyperscale cloud facilities in Singapore and Tokyo are unbundling insulation specification from general contractor procurement to optimize PUE targets.
Residential absorbs the greatest material volume; industrial procurement is gaining share fastest through direct supplier engagement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors thermal envelope specification activity across the Asia-Pacific, with developers pre-empting China's MEE enforcement of GB 50189 energy codes through higher-grade insulation procurement. Cold storage logistics operators in Singapore and Sydney are retrofitting warehouse envelopes to meet pharmaceutical-grade temperature stability requirements. Industrial corridor expansion across Vietnam's northern provinces and India's western states is pulling fire-resistant mineral wool into process equipment applications.
China
Developers in Shenzhen and Beijing are specifying vacuum insulation panels for data center envelopes where floor space economics override material cost premiums. The MEE's real-time thermal performance monitoring mandate for commercial structures above 20,000 square meters is compressing U-value maximums in curtain wall assemblies. Northern provinces with district heating networks are accelerating mineral wool substitution for lower-performing alternatives in residential high-rises.
Japan
Tokyo's pharmaceutical cold chain operators are specifying polyurethane foam for refrigerated warehouse retrofits where envelope thickness constraints prohibit mineral wool batts. METI's Top Runner Program mandates minimum insulation thicknesses for commercial structures, pulling premium-grade materials into new construction specifications. Osaka-based supermarket chains are absorbing vacuum insulation panels for existing refrigerated facilities where conventional materials cannot achieve target U-values.
India
The Gujarat-Maharashtra-Tamil Nadu manufacturing belt is driving sustained demand for fire-resistant insulation in process equipment and HVAC infrastructure. BIS certification requirements for fire safety performance create compliance barriers for uncertified mineral wool and fiberglass shipments from ASEAN manufacturing hubs. Residential developers in Pune and Hyderabad corridors default to fiberglass for multi-story housing where code minimums do not mandate higher R-values per unit thickness.
Australia
Sydney and Melbourne office stock built before 2010 thermal codes is generating replacement demand under NCC energy efficiency upgrades. Data center operators are unbundling insulation specification from general contractor procurement to optimize PUE targets and carbon disclosure requirements. Bushfire-prone regions restrict cellulose applications where ember attack ratings override sustainability preferences in timber-framed residential construction.
Vietnam
Underpenetrated northern manufacturing clusters offer first-mover positioning for suppliers establishing local mineral wool production capacity. Cold storage operators in Ho Chi Minh City are retrofitting warehouse envelopes with higher R-value materials to meet food-grade temperature stability requirements. Spray-applied polyurethane foam captures retrofit share where headroom constraints prohibit thicker batt installations in existing warehouse ceilings.
Asia-Pacific Insulation Materials Market Competitive Landscape
The competitive structure tilts toward diversified material specialists with cross-regional formulation capabilities. The vendor base spans multinational chemical conglomerates, dedicated insulation fabricators, and regional mineral wool producers with fire safety certification depth. Three archetypes dominate: technology leaders with proprietary foam chemistry, scale-driven fiberglass manufacturers, and fire-resistant mineral wool specialists with industrial safety positioning. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers configure regional manufacturing to bypass import certification bottlenecks.
Among diversified chemical conglomerates, BASF SE and Saint-Gobain S.A. occupy positions spanning polyurethane formulations and glass-based thermal barriers. Owens Corning and Rockwool International A/S exemplify the technology-specialist and fire-safety archetypes respectively, with the former anchored in fiberglass innovation and the latter in non-combustible mineral systems. Kingspan Group PLC represents the integrated envelope systems approach, while Asahi Kasei Corporation sits within the Asia-Pacific regional specialist tier. These named entities serve as anchors for understanding how competitive positioning fragments across material technologies and end-use specifications.
| Leading Market Players |
|---|
| Owens Corning |
| BASF SE |
| Rockwool International A/S |
| Saint-Gobain S.A. |
| Kingspan Group PLC |
| Armacell International S.A. |
| Knauf Insulation |
| Asahi Kasei Corporation |
| Johns Manville |
| Others |
Value Network & Pricing Analysis
Sovereign-backed mineral wool producers in China and family-owned polyurethane specialists across ASEAN anchor regional supply concentration, compressing pricing discipline through captive raw material access and long-term offtake contracts with cold storage developers.
Pricing Analysis
Value-based pricing anchored to thermal performance guarantees dominates premium specifications, with polyurethane foam commanding premiums tied to R-value retention in tropical humidity. Three-tier pricing structure across VIP-integrated systems, certified mineral wool, and commodity fiberglass segments price differentiation by certification grade and installation labor bundling. Cost compression in polystyrene intensifies because fiberglass substitution accelerates in India's residential corridors. Industrial buyers exhibit lowest price sensitivity where fire safety certification under BIS and JIS mandates non-negotiable compliance spend.
Supply Chain Analysis
Freight cost volatility from Middle East benzene and South Korean MDI feedstocks strains polyurethane foam margins across Southeast Asian manufacturing zones. Supply concentrates in China for glass fiber and mineral wool, South Korea for polyol intermediates, and Australia for calcium silicate boards. Raw material dependencies rest on petrochemical derivatives, metallurgical slag, and soda ash. Single-source vulnerability in MDI supply chains exposes formulators to benzene price swings. Distribution runs through regional distributors serving contractor networks, with direct supplier engagement penetrating data center and cold storage procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around fire safety certification depth and petrochemical backward integration, with India's BIS enforcement and China's MEE codes forcing sub-scale mineral wool importers into distressed exits.
For Market Incumbents: Anchor defensive positioning through captive MDI supply agreements and JIS-certified mineral wool production in Vietnam's northern industrial zones. Threat from vacuum insulation panel substitution in Tokyo pharmaceutical cold chain demands R&D investment in hybrid VIP-foam composite systems. Channel control through direct specification engagement with Australian data center operators preserves margin against distributor disintermediation. For New Entrants and Emerging Players: Launch via factory-integrated panel partnerships with Vietnamese cold storage developers seeking turnkey envelope solutions. White-space targets concentrate in Australia's NCC-mandated commercial retrofits and Indonesia's SNI certification gap for fire-resistant industrial insulation. Go-to-market angle centers on technical workforce training programs addressing Southeast Asia's certified spray foam applicator shortage. For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-certified mineral wool specialists in Gujarat-Maharashtra corridors facing working capital strain from 14-month certification timelines. Long-term viability hinges on regulatory compliance moats deepening across ASEAN jurisdictions. Watch for MEE real-time thermal monitoring mandate expansion beyond 20,000 square meter thresholds as inflection signal for premium insulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstocks | Captive benzene supply secures margin stability against petrochemical volatility in polyurethane formulations. |
| JIS/BIS Certification Investment | Fire safety approval depth unlocks Japanese pharmaceutical and Indian industrial equipment specifications. |
| Direct Data Center Engagement | PUE optimization liability shifts insulation procurement from general contractors to material suppliers. |
| Vietnam Mineral Wool Capacity Buildout | Local production bypasses ASEAN import barriers while serving underpenetrated northern manufacturing clusters. |
| Vacuum Insulation Panel Joint Venture | Japanese pharmaceutical distributor partnerships absorb VIP share in space-constrained Tokyo warehouse retrofits. |
Research Methodology
Independent corroboration across plant managers at ASEAN mineral wool facilities, procurement leads at Australian cold storage 3PLs, and technical R&D directors at polyurethane formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, China's MEE enforcement disclosures, BIS certification registries, and SEC filings of listed insulation specialists. Bottom-up volume estimates triangulate against top-down construction activity indices and industrial equipment investment flows.
Rate-of-change decomposition across material type, application, and end-user segments structures the analytical framework throughout the forecast period. CAGRs derive from segment-level volume trajectories weighted by regional construction permitting data and MEE code enforcement timelines. Industry-specific inputs include thermal conductivity coefficient evolution, fire safety certification pipeline durations, and cold storage logistics capacity expansion announcements.
Petrochemical input volatility, BIS/JIS certification timeline extensions, and MEE enforcement intensity variations are the dominant revision risks. Forecasts reflect documented assumptions on regulatory implementation pacing and construction sector credit availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Global Microporous Insulation Market