
 Brahmi Market | 2026-2036
Brahmi Market Size, Share, and Industry Trends Forecast 2026-2036
Brahmi Market Outlook
Wellness-focused consumers are bifurcating from traditional Ayurvedic practitioners as the fastest-growing buyer archetype in Brahmi procurement. Dabur India Ltd. leverages its integrated herb sourcing networks across India to secure raw material consistency. Himalaya Global Holdings Ltd. differentiates through pharmaceutical-grade extraction protocols that meet export quality benchmarks. Sabinsa Corp. anchors North American supply with its proprietary bacoside standardization technology.
Brahmi (Bacopa monnieri) denotes a perennial creeping herb containing active bacosides A and B, typically extracted through hydro-alcoholic processes to achieve standardized potency for cognitive and anxiolytic applications. Powder formulations dominate volume consumption in traditional medicine channels, while extract segments capture concentrated margin pools in pharmaceutical and nutraceutical applications. Capsule formats are expanding fastest among urban professionals seeking standardized dosing convenience through online distribution channels.
India's Ministry of AYUSH and the Food Safety and Standards Authority of India (FSSAI) govern Brahmi product standards, with AYUSH pharmacopeia specifications mandating minimum bacoside content for therapeutic claims and FSSAI labeling rules constraining health assertion language on packaged goods. The European Medicines Agency (EMA) and the United States Pharmacopeia (USP) additionally shape export market access through monograph compliance requirements for botanical identity and heavy metal thresholds. Stakeholders must monitor evolving pharmacopeial harmonization between Indian and international standards to preserve cross-border commercialization pathways.
Market Dynamics
Standardized bacoside extraction protocols are compressing traditional whole-herb supply chains as pharmaceutical buyers demand certificate-of-analysis documentation for every batch. This quality-tier bifurcation is forcing raw material processors to choose between commodity Ayurvedic channels and premium nutraceutical certification tracks.
Growth Catalysts
- PLI scheme for herbal products:India's production-linked incentive scheme subsidizes capital equipment for standardized extract manufacturing, accelerating domestic processing capacity expansion.
- Cognitive health formulations:Nutraceutical manufacturers are expanding bacoside procurement for nootropic supplement lines targeting urban professionals.
- Organic cultivation clusters:Karnataka and Madhya Pradesh state agricultural departments are consolidating smallholder growers into certified organic supply pools with direct extractor linkages.
Market Restraints
- Wild-harvest dependency:Rain-fed collection from wetlands creates 40-60% annual yield volatility that extractors cannot hedge through contract farming.
- Heavy metal thresholds:USP and EMA monograph compliance requires cadmium and lead testing that disqualifies 30% of Indian-origin material without remediation.
- Synthetic nootropics:Piracetam and modafinil derivatives compete directly with Brahmi extracts on cognitive efficacy claims at lower dose costs.
Strategic Opportunities
- Direct-to-consumer capsules:E-commerce platforms enable standardized-dose formats to bypass traditional Ayurvedic practitioner intermediaries.
- Cosmeceutical applications:Anti-aging topical formulations represent an untapped bacoside demand vertical beyond oral supplements.
- FSSAI-AYUSH harmonization:Pending alignment of domestic pharmacopeia with export standards would reduce dual-certification costs for Indian processors.
Industry Challenges
- Phytochemical assay standardization:HPLC quantification of bacoside A versus B ratios requires analytical chemists scarce in traditional herb processing centers.
- Batch-to-batch potency variance:Monsoon-dependent cultivation creates extraction yield unpredictability that pharmaceutical buyers reject under fixed-formula contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brahmi Market |
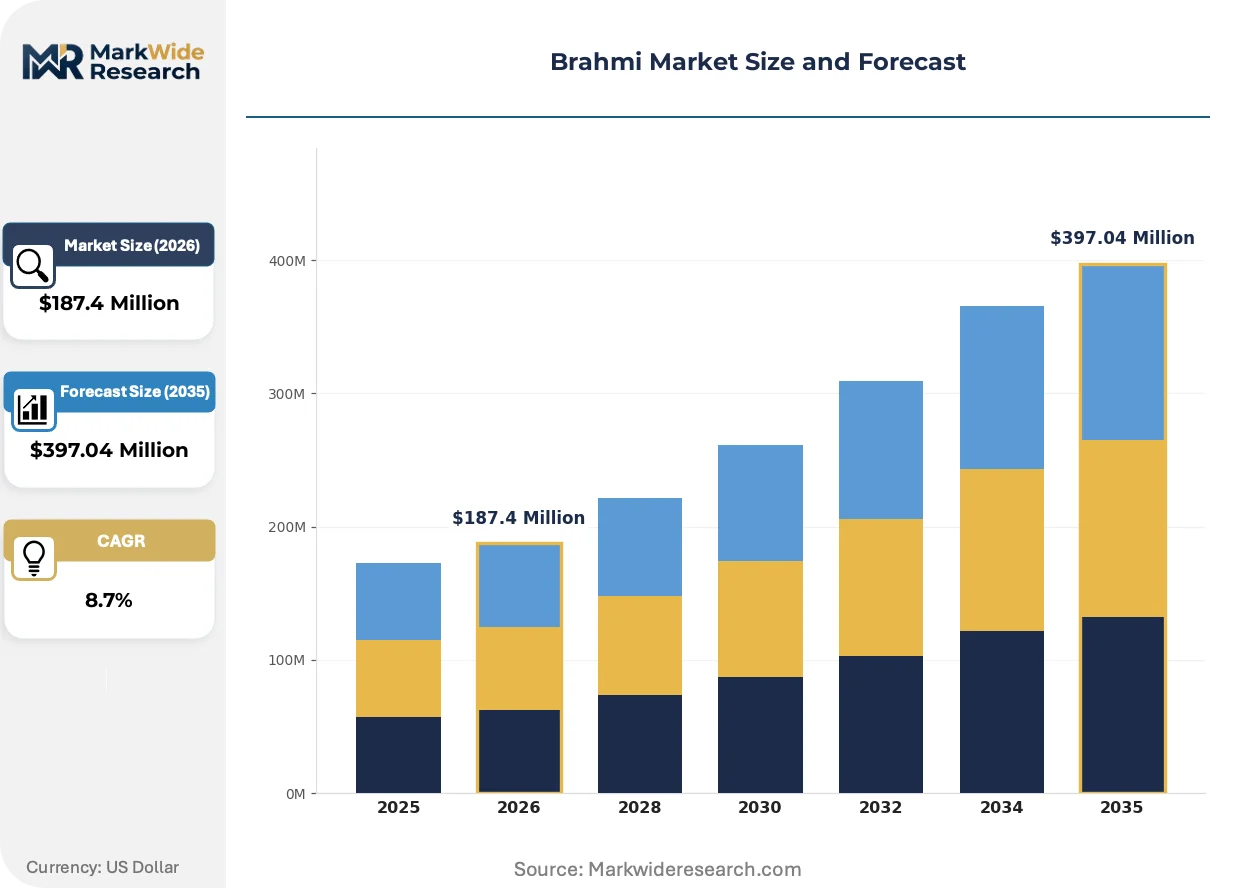
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Extract, Tincture Application: Healthcare, Nutraceuticals, Cosmetics, Herbal Remedies End User: Individuals, Health Professionals, Retailers, Manufacturers Distribution Channel: Online, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Dabur India Ltd., Himalaya Global Holdings Ltd., Hamdard Laboratories, Patanjali Ayurved Ltd., Organic India Pvt. Ltd., Natures Velvet Lifecare, Morpheme Remedies, Sabinsa Corp., Herbal Creations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brahmi Market Strategic Shifts
Supercritical CO2 extraction is displacing hydro-alcoholic methods as the dominant processing technology, driven by solvent residue regulations in export markets. This equipment transition favors capitalized processors over traditional solvent-based operations.
Supercritical CO2 extraction systems operate at 31°C critical temperature, preserving heat-sensitive bacoside integrity while eliminating ethanol solvent residues. North American and European nutraceutical contract manufacturers are mandating this technology in supplier qualification audits. The capital intensity of CO2 systems is supplanting small-batch artisanal processors with centralized extraction facilities capable of tonnage-scale output.
EMA's updated herbal monograph for Bacopa monnieri now mandates DNA barcoding for botanical identity verification alongside traditional morphological assessment. European importers are rejecting shipments lacking ISO/IEC 17025-accredited laboratory documentation. Indian extractors serving EU markets are retrofitting quality labs to meet this dual-verification requirement.
Urban professionals now source cognitive supplements through subscription e-commerce platforms rather than brick-and-mortar Ayurvedic dispensaries. This channel pivot rewards brands with direct fulfillment infrastructure and punishes traditional distributor-dependent suppliers. Metro Indian cities and North American coastal metros exhibit the fastest platform adoption rates for Brahmi-based nootropics.
Brahmi Market Segmentation
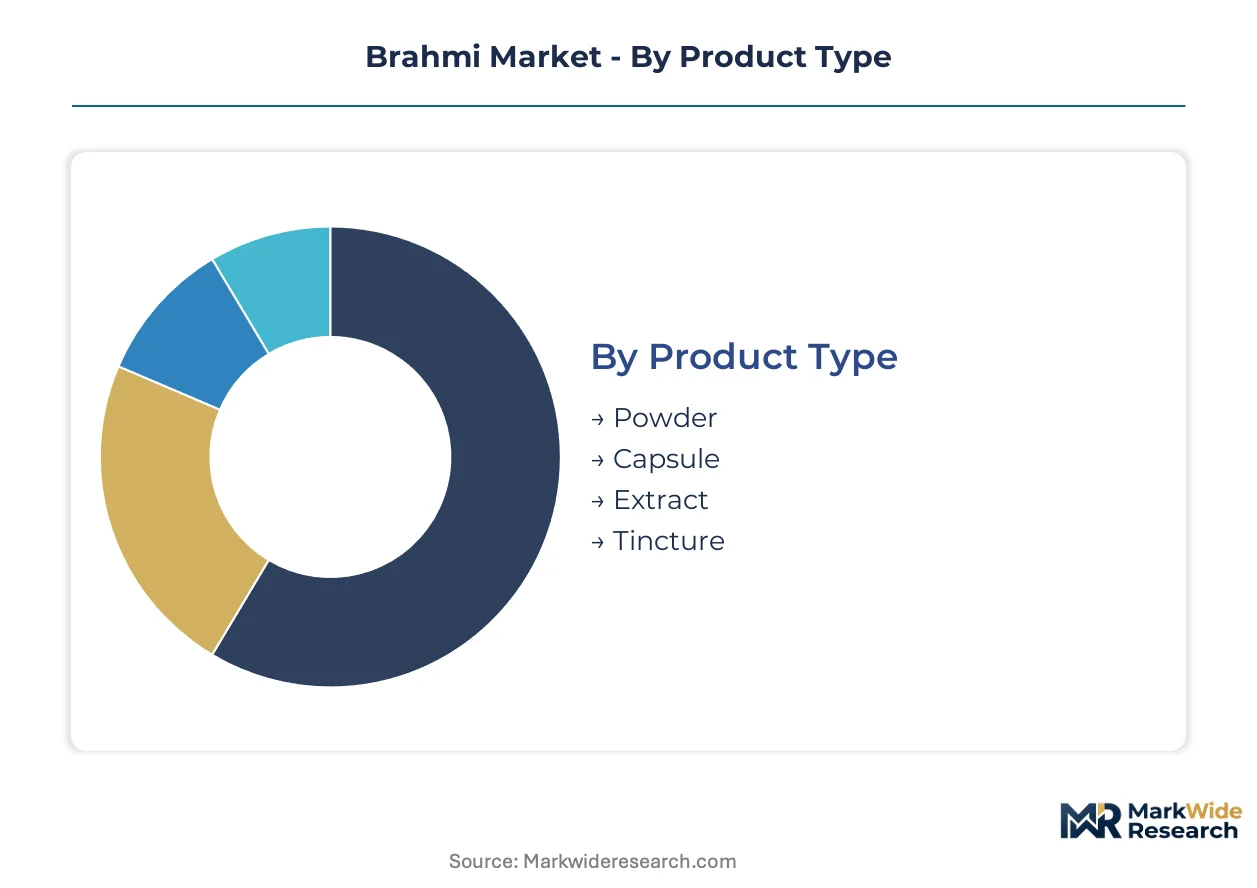
Brahmi market segmentation reveals how regulatory frameworks and processing standards fragment demand across quality tiers. Each dimension exposes distinct procurement patterns between traditional Ayurvedic channels and pharmaceutical-grade supply chains.
Product Type:
FSSAI labeling rules and USP monograph compliance create three quality tiers that determine export eligibility and pricing power.
- Extract:Standardized bacoside concentrates produced through hydro-alcoholic or supercritical CO2 methods achieve pharmaceutical-grade certification required by EMA and USP import protocols. North American nutraceutical contract manufacturers now mandate CO2-extracted material for nootropic formulations targeting urban professionals.
- Capsule:Pre-measured dosing formats bypass traditional practitioner intermediaries through direct-to-consumer e-commerce channels. Metro Indian cities and US coastal markets exhibit steepest adoption curves as subscription platforms displace brick-and-mortar Ayurvedic dispensaries.
- Powder:Whole-herb preparations dominate traditional medicine volumes in domestic Indian markets with minimal processing overhead.
- Tincture:Alcohol-based liquid extracts serve niche practitioner compounding and home-use applications with limited standardization.
Established volume favors Powder; emerging adoption favors Capsule.
Application:
End-use concentration determines bacoside potency requirements and certification investment levels.
- Nutraceuticals:Cognitive health supplements demand certificate-of-analysis documentation for every batch, forcing extractors into pharmaceutical-grade processing tracks. India's PLI scheme subsidizes capital equipment for manufacturers serving this quality tier.
- Healthcare:Clinical formulations under AYUSH pharmacopeia specifications require minimum bacoside content for therapeutic claims, creating compliance costs that commodity processors avoid.
- Herbal Remedies:Traditional Ayurvedic preparations operate with whole-herb specifications and minimal analytical testing.
- Cosmetics:Anti-aging topical formulations represent nascent bacoside demand with evolving regulatory status under FSSAI cosmetic ingredient rules.
Margin concentration sits with Nutraceuticals; volume scale sits with Herbal Remedies.
End User:
Procurement sophistication divides buyers between specification-driven and tradition-driven purchasing.
- Manufacturers:Pharmaceutical and nutraceutical companies impose standardized extraction protocols and heavy metal testing that disqualifies 30% of raw material without remediation. These buyers anchor premium pricing tiers through fixed-formula contracts.
- Individuals:Direct purchasing through online channels favors standardized-dose convenience over traditional preparation methods.
- Health Professionals:Ayurvedic practitioners and integrative medicine clinicians source both whole-herb and extract materials depending on patient compliance requirements.
- Retailers:Brick-and-mortar health stores and pharmacies intermediate between processors and end consumers with inventory risk concentrated in slower-turning SKUs.
Specification pressure concentrates with Manufacturers; channel disruption concentrates with Individuals.
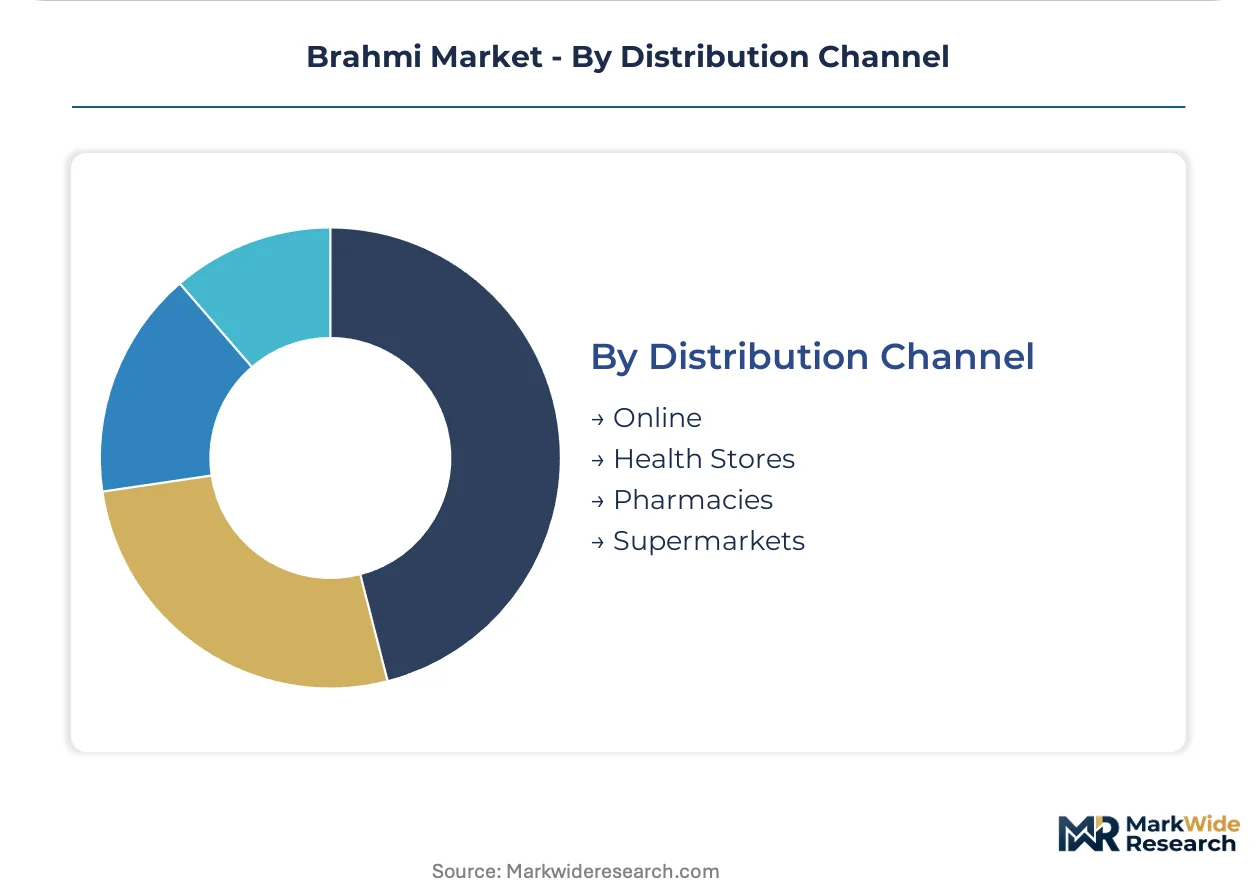
Distribution Channel:
Fulfillment infrastructure determines brand access to wellness-focused consumer segments.
- Online:Subscription e-commerce platforms enable standardized-dose formats to bypass traditional distribution layers. This channel rewards direct fulfillment capabilities and punishes distributor-dependent suppliers.
- Health Stores:Specialty retailers curate premium-positioned products with organic and pharmaceutical-grade certifications.
- Pharmacies:Regulated dispensing channels require FSSAI or FDA compliance documentation for Brahmi-based products with therapeutic claims.
- Supermarkets:Mass-market placement favors commoditized powder formats with minimal margin and high volume turnover.
Platform adoption climbs fastest in Online; margin protection concentrates in Health Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian extractors ship standardized bacoside concentrates to North American nutraceutical contract manufacturers and European pharmaceutical formulators, with Karnataka and Madhya Pradesh cultivation clusters supplying the raw material base.
India
Domestic Ayurvedic consumption and export-oriented extract manufacturing drive dual demand streams. The PLI scheme for herbal products subsidizes capital equipment for standardized extract facilities. Organic cultivation clusters in Karnataka's Coorg district and Madhya Pradesh's Nimar region consolidate smallholder growers into certified supply pools with direct extractor linkages.
United States
Nootropic supplement brands and integrative medicine practitioners anchor bacoside procurement for cognitive health formulations. FDA dietary supplement regulations and USP monograph compliance requirements constrain import acceptance to CO2-extracted, heavy-metal-tested material. West Coast nutraceutical contract manufacturers in California and Oregon specify supercritical extraction protocols in supplier qualification audits.
Germany
Phytopharmaceutical manufacturers and pharmacy-channel distributors dominate regulated herbal product demand. EMA's updated Bacopa monnieri monograph mandates DNA barcoding and ISO/IEC 17025-accredited laboratory documentation for import acceptance. Bavaria-based extract processors retrofit quality labs to meet dual-verification requirements for EU market access.
China
Traditional medicine manufacturers and domestic nutraceutical brands source both indigenous and imported Brahmi raw material. NMPA herbal medicine regulations and GB standards for botanical extracts shape processing requirements. Zhejiang and Jiangsu province extraction facilities expand capacity for standardized bacoside concentrates serving Southeast Asian export markets.
Australia
Complementary medicine practitioners and direct-to-consumer wellness brands drive capsule-format demand. TGA listing requirements for listed medicines constrain therapeutic claim language and mandate evidence of bacoside standardization. Sydney and Melbourne-based formulators source CO2-extracted material through subscription e-commerce platforms bypassing traditional distributor channels.
Brahmi Market Competitive Environment
Listed leaders compete with private specialists across certification-tier and channel-access dimensions. The market structure bifurcates between commodity Ayurvedic processors serving domestic traditional medicine channels and pharmaceutical-grade extractors meeting EMA and USP export protocols. Three archetypes dominate: integrated herb-to-brand conglomerates with captive cultivation networks, specialist extractors with proprietary standardization technology, and private-label formulators serving subscription e-commerce platforms. Competitive moves concentrate on backward integration into organic cultivation clusters and technology licensing for supercritical CO2 extraction capacity.
Within the integrated conglomerate tier, Dabur India Ltd. and Himalaya Global Holdings Ltd. occupy positions defined by herb sourcing network scale and pharmaceutical-grade extraction protocol investment. Sabinsa Corp. anchors the North American specialist extractor archetype through bacoside standardization technology positioning. These three exemplify how geographic origin and company structure map to competitive positioning across quality-tier and regulatory-compliance vectors.
| Leading Market Players |
|---|
| Dabur India Ltd. |
| Himalaya Global Holdings Ltd. |
| Hamdard Laboratories |
| Patanjali Ayurved Ltd. |
| Organic India Pvt. Ltd. |
| Natures Velvet Lifecare |
| Morpheme Remedies |
| Sabinsa Corp. |
| Herbal Creations |
| Others |
Value Chain & Pricing Dynamics
EMA's updated Bacopa monnieri monograph gates both supply qualification and price differentiation simultaneously, forcing extractors to invest in DNA barcoding and ISO/IEC 17025-accredited laboratories to access premium European pricing tiers while commodity processors serve domestic Ayurvedic channels at compressed margins.
Pricing Analysis
Supercritical CO2 extraction commands price premiums over hydro-alcoholic methods as North American nutraceutical contract manufacturers mandate solvent-free certification in supplier audits. Three-tier pricing structure across pharmaceutical-grade, organic-certified, and commodity whole-herb levels reflects bacoside standardization investment and heavy metal remediation costs. Pricing pressure stems from synthetic nootropics competing on cognitive efficacy claims at lower dose costs. Traditional Ayurvedic practitioners exhibit highest price sensitivity; pharmaceutical buyers prioritize certificate-of-analysis consistency over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical procurement as buyers reject monsoon-dependent cultivation lots under fixed-formula contracts, while strategic stockpiling persists among traditional Ayurvedic processors absorbing annual yield volatility. Raw material supply concentrates in India, with Karnataka and Madhya Pradesh cultivation clusters feeding domestic extractors and export-oriented processors. The supply chain draws from wild-harvested wetlands and certified organic smallholder pools, with bacoside-rich biomass and analytical chemist labor representing critical input dependencies. Single-source vulnerability runs through rain-fed collection regions without irrigation infrastructure. Distribution runs through direct extractor-to-manufacturer contracts for premium tiers and layered distributor networks for traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brahmi market rewards processors possessing supercritical CO2 extraction capabilities and pharmacopeial compliance expertise, assets scarce among traditional solvent-based operators serving commodity Ayurvedic demand.
For Market Incumbents: Compound defensive positioning through backward integration into certified organic cultivation clusters in Karnataka and Madhya Pradesh, securing captive supply pools insulated from wild-harvest yield volatility. Expand in-house analytical chemistry capacity to meet EMA and USP dual-verification requirements, converting compliance investment into pricing power over distributor-dependent competitors facing batch rejection risks. For New Entrants and Emerging Players: Differentiate on cosmeceutical applications as an underpenetrated bacoside demand vertical beyond oral supplements, where FSSAI cosmetic ingredient rules remain less stringent than pharmaceutical-grade protocols. Target direct-to-consumer capsule formats through subscription e-commerce platforms in metro Indian cities and North American coastal markets, bypassing traditional Ayurvedic practitioner intermediaries with standardized-dose convenience positioning. For Investors and Strategic Acquirers: EMA's DNA barcoding mandate reshapes the acquisition landscape toward extractors with existing ISO/IEC 17025-accredited laboratory infrastructure and European import track records. Long-term viability favors processors capable of serving both domestic AYUSH pharmacopeia specifications and export monograph compliance without dual-certification cost duplication. Watch for FSSAI-AYUSH harmonization progress as the signal indicating margin compression or expansion for Indian-origin material.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Capacity Addition | Meets North American and European solvent residue regulations while preserving heat-sensitive bacoside integrity. |
| Organic Cultivation Cluster Integration | Consolidates smallholder growers in Karnataka and Madhya Pradesh into certified supply pools with direct extractor linkages. |
| ISO/IEC 17025 Laboratory Accreditation | Enables EMA DNA barcoding compliance and USP heavy metal testing for pharmaceutical-grade export eligibility. |
| Direct-to-Consumer E-Commerce Launch | Bypasses traditional Ayurvedic practitioner intermediaries through subscription platforms targeting urban professionals. |
| Cosmeceutical Formulation Development | Expands bacoside demand into anti-aging topical applications beyond saturated oral supplement markets. |
Study Parameters
A standing panel of extraction facility operations managers, AYUSH regulatory consultants, nutraceutical procurement directors, and organic certification auditors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through FSSAI pharmacopeia publications, EMA herbal monograph updates, USP dietary supplement standards, and India's PLI scheme disbursement records. Bottom-up cultivation yield estimates and top-down nutraceutical formulation demand triangulated market sizing.
Consistency checks validated volume and value outputs against customs export data for standardized bacoside concentrates and subscription platform SKU proliferation rates. The analytical framework segmented across product type, application, end user, and distribution channel dimensions throughout the forecast period. CAGRs derived from extractor capacity expansion timelines and cultivation cluster consolidation trajectories, with monsoon variability and synthetic nootropic substitution elasticity as key demand-side inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EMA and USP monograph stability; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding PLI scheme continuity and organic certification cost trajectories. Revision becomes warranted when wild-harvest yield volatility or synthetic nootropic pricing crosses thresholds disrupting traditional-processor viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Cultures Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
North America Hummus Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Kosher Food Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Miso Market
Specialty Foods
Global Bee Products Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Middle East and Africa Yerba Mate Market