
 GCC Halal Food Market | 2026-2036
GCC Halal Food Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Halal Food Market Intelligence
Supermarket private-label halal ranges across the Gulf are rewriting procurement relationships between retailers and processors. Al Islami Foods leverages its UAE production base to anchor supply contracts with major grocery chains. BRF S.A. competes through Brazilian-origin poultry volumes that sustain price competitiveness in Saudi Arabia and Kuwait. Nestle differentiates via packaged convenience formats that dominate shelf space in hypermarket halal sections.
GCC halal food comprises consumable products prepared according to Islamic dietary law, requiring slaughter by a Muslim with invocation, complete blood drainage, and absence of pork derivatives or intoxicants. Meat and poultry segments lead volume due to mandatory halal compliance for domestic consumption across all six Gulf states. Online retail channels represent the fastest-growing distribution pathway as delivery platforms and dedicated e-grocers expand cold-chain fulfillment. Third-party certification from bodies such as ESMA or accredited international authorities commands premium positioning, while in-house claims face tightening retail acceptance standards.
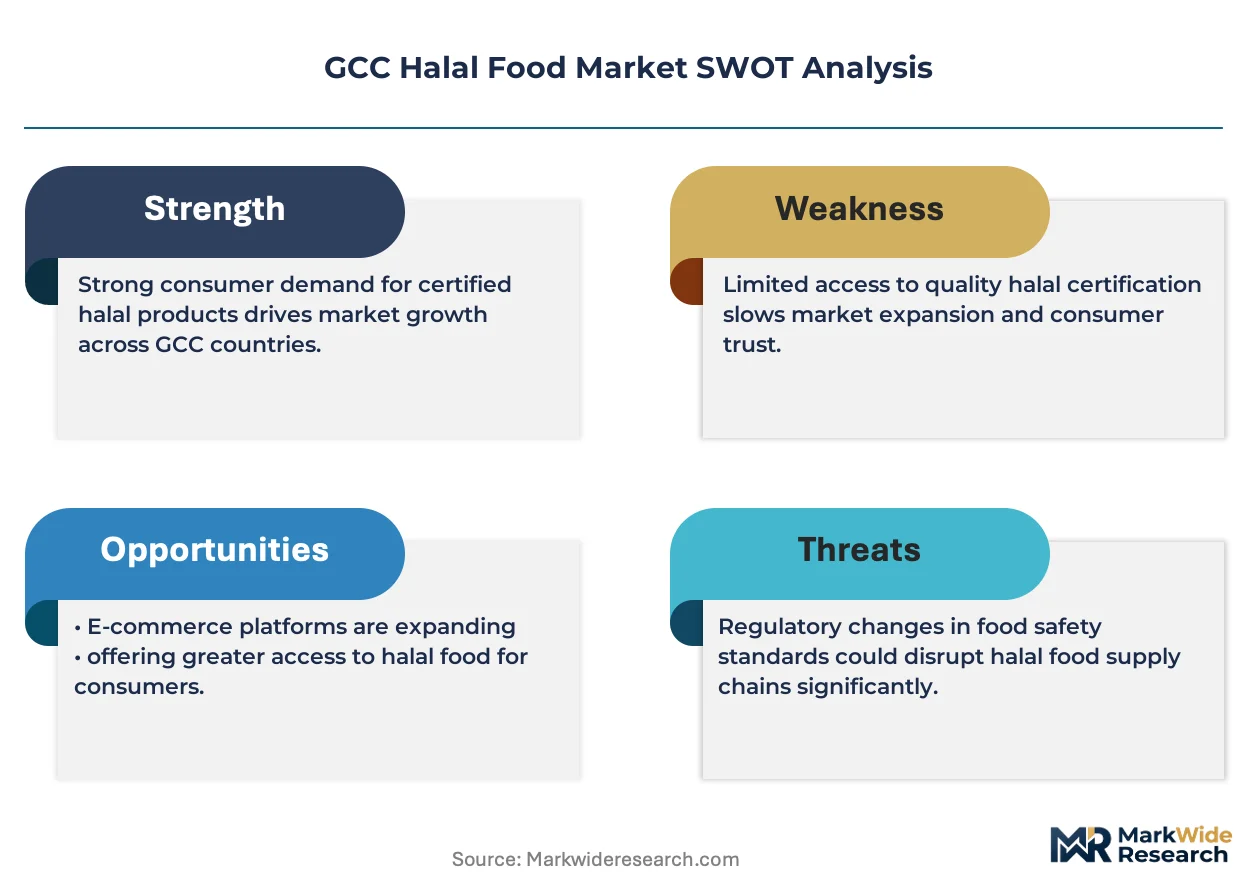
SFDA in Saudi Arabia, ESMA in the UAE, and GSO standardization frameworks collectively govern halal integrity, import licensing, and cross-border mutual recognition across the Gulf Cooperation Council. These bodies mandate slaughterhouse audits, supply chain traceability documentation, and periodic facility recertification that raise compliance costs but filter non-compliant imports. Stakeholders must monitor evolving GSO halal standard harmonization talks and the divergence between local authority certification and internationally accredited alternatives when structuring multi-country distribution.
Market Dynamics
SFDA import documentation tightening for meat and poultry is forcing Gulf procurement teams to restructure supplier qualification workflows around traceability infrastructure, compressing lead times for certification renewals while expanding audit scope across cold-chain nodes.
Growth Catalysts
- SFDA Documentation Mandates:Saudi Arabia's tightened import rules for meat and poultry are accelerating investment in slaughterhouse traceability systems that filter non-compliant suppliers from GCC distribution networks.
- Hotel and Catering Procurement Expansion:Gulf hospitality procurement teams are embedding halal-certified sourcing requirements into RFP specifications, creating volume commitments that stabilize processor utilization rates.
- Dubai Logistics Infrastructure:The emirate's cold-chain redistribution capacity anchors regional supply consolidation, enabling same-day fulfillment to Saudi Arabia and Kuwait that supports just-inventory models.
Market Restraints
- Feed Cost Volatility:Brazilian and Argentine grain price swings transmit directly into poultry processor margins across the Gulf, compressing profitability for operations without backward integration into feed sourcing.
- Slaughterhouse Concentration:Domestic halal-certified abattoir capacity clusters in the UAE and Saudi Arabia, creating single-point vulnerability for processors serving Bahrain, Oman, and Qatar.
- GSO Harmonization Delays:Divergent interpretation of Gulf Standardization Organization halal protocols between national regulators generates duplicate certification costs for multi-country distributors.
Strategic Opportunities
- Oman and Bahrain Underpenetration:These smaller GCC states lack domestic slaughterhouse scale, creating first-mover advantage for UAE-based processors with ESMA certification seeking captive supply contracts.
- E-Grocer Cold-Chain Expansion:Dedicated online halal platforms are building last-mile frozen fulfillment networks that bypass traditional hypermarket slotting fee structures.
- ESMA-Accredited Premium Positioning:Third-party certification from the Emirates Authority for Standardization and Metrology commands retail shelf priority as in-house halal claims face tightening acceptance standards.
Industry Challenges
- Halal Auditor Talent Scarcity:Qualified slaughterhouse inspectors with dual competency in Islamic jurisprudence and food safety protocols remain concentrated in Egypt and Pakistan, creating recruitment bottlenecks for facility expansions.
- Multi-Jurisdiction Compliance Timelines:Parallel SFDA, ESMA, and GSO recertification cycles demand dedicated regulatory affairs headcount that smaller processors struggle to maintain.
- Legacy ERP Integration:Batch-level traceability requirements for import licensing force upgrades to inventory management systems that lack native halal segregation modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Halal Food Market |
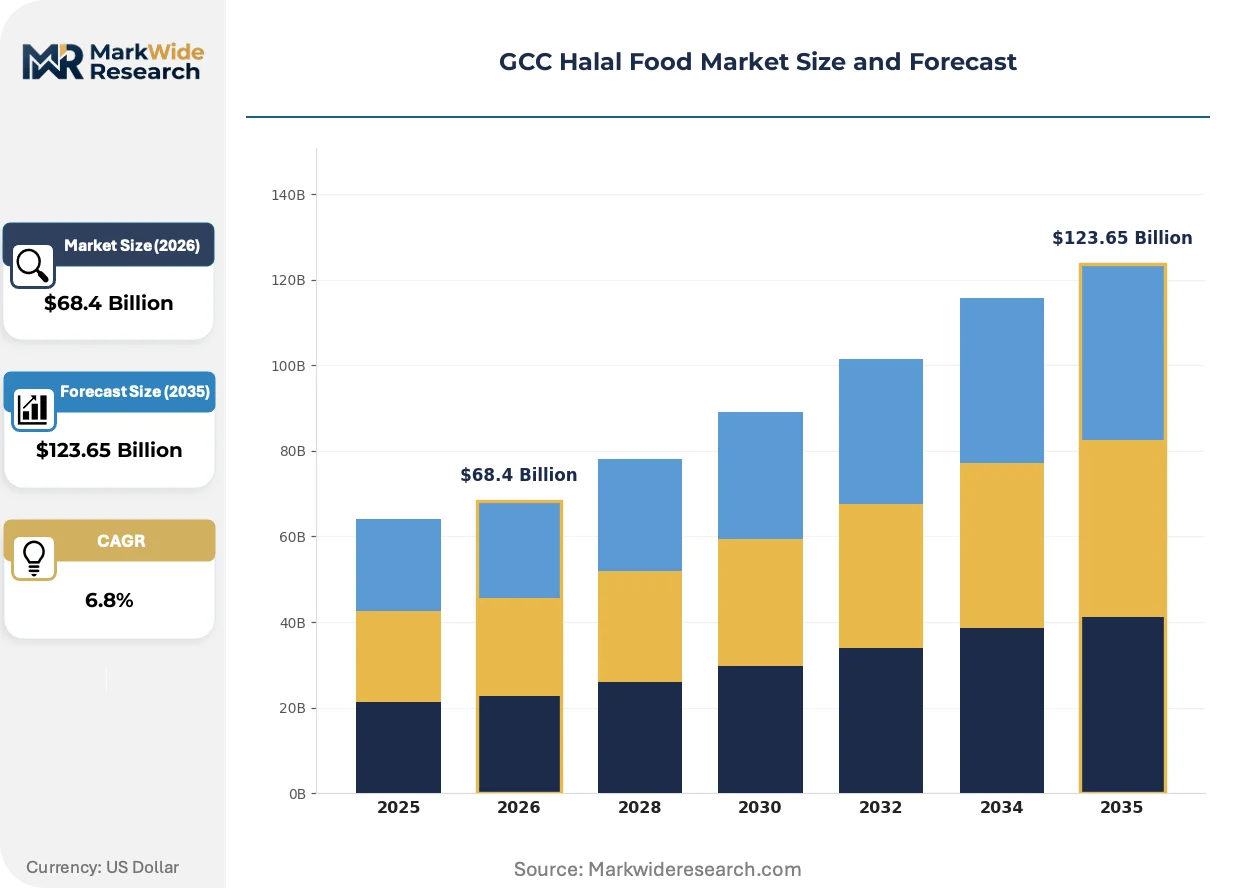
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
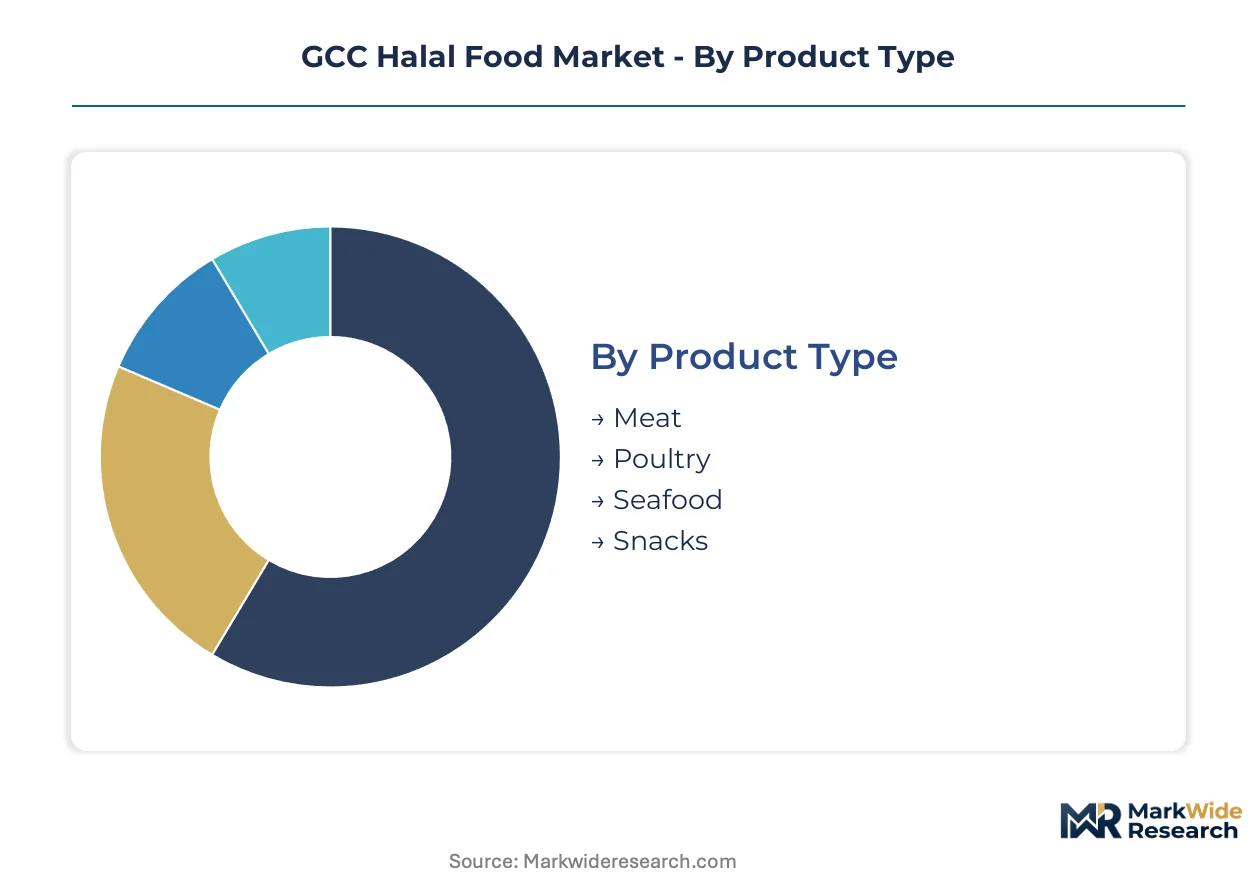
| Segmentation | Product Type: Meat, Poultry, Seafood, Snacks Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores Certification Type: Local Authority, International Standard, In-House, Third Party End User: Households, Restaurants, Hotels, Catering Services |
| Companies Covered | Unilever, Salwa Foods, Al Islami Foods, Al Ghurair Foods, Noor Al Jazeera Food, Cargill, BRF S.A., NAMET, Nestle, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Halal Food Market Strategic Shifts & Innovations
Blockchain-enabled supply chain verification is displacing paper-based halal certificates across Gulf procurement networks, compressing audit cycles while raising the technical bar for supplier participation.
Blockchain traceability platforms are migrating from pilot slaughterhouse deployments to mandatory retail acceptance criteria. Carrefour and Lulu Group procurement teams now require QR-linked certificate verification for private-label halal ranges. This technology is migrating from compliance documentation into real-time temperature and custody logging that underpins insurance and trade finance instruments.
GSO halal standard harmonization talks are creating regulatory uncertainty as Saudi Arabia's SFDA advances stricter slaughterhouse audit protocols than ESMA's current framework. Processors serving multiple GCC states face parallel compliance tracks until mutual recognition agreements finalize. Meat and poultry importers are responding by segmenting product flows through Dubai for UAE/Kuwait distribution and direct Jeddah entry for Saudi Arabia-exclusive SKUs.
Buyer certification preference is shifting from in-house halal claims to third-party accredited seals that satisfy procurement team liability concerns. Hotel and catering contract tenders now specify ESMA, SFDA, or Malaysia JAKIM recognition as mandatory pass/fail criteria. This shift is most visible in Saudi Arabia's foodservice sector, where government entity catering contracts exclude suppliers without accredited certification regardless of price competitiveness.
GCC Halal Food Market Segmentation
Procurement teams across Gulf hospitality and retail channels configure sourcing strategies around certification grade, channel velocity, and end-use specification. Segment boundaries shift as SFDA documentation mandates tighten import pathways and e-grocers build dedicated halal fulfillment infrastructure.
Product Type:
Inventory velocity varies sharply across protein categories, with poultry turning fastest due to price accessibility and daily household consumption patterns while seafood moves slowest owing to cold-chain sensitivity and seasonal supply fluctuations.
- Meat:Beef and lamb segments require slaughterhouse certification from SFDA or ESMA-accredited facilities. Saudi Arabia's import documentation tightening has compressed supplier qualification timelines, forcing distributors to pre-qualify abattoirs before tender participation. Hotels in Riyadh and Jeddah anchor premium chilled beef demand through contracted procurement programs that specify grain-fed origin and 21-day aging protocols.
- Poultry:Brazilian-origin frozen chicken dominates volume through BRF S.A. and similar processors competing on price-point consistency. Dubai's logistics infrastructure enables same-day redistribution to Kuwait and Bahrain, supporting just-inventory models for supermarket private-label ranges. Feed cost volatility from Argentine grain markets transmits directly into processor margins, compressing profitability for operations without backward integration into feed sourcing.
- Seafood:Wild-caught and aquaculture products face extended certification cycles due to vessel-to-retail traceability requirements under GSO frameworks.
- Snacks:Packaged savory and confectionery items leverage ESMA-accredited halal seals to secure hypermarket shelf positioning against in-house label competition.
Meat dominates installed base through mandatory compliance for domestic consumption. Poultry is where expansion concentrates as price accessibility drives per-capita consumption growth across lower-income segments.
Distribution Channel:
Channel selection determines compliance burden intensity, with supermarkets demanding full certification documentation while convenience stores accept simplified in-house claims that face tightening retail acceptance standards.
- Supermarkets:Carrefour and Lulu Group procurement teams mandate QR-linked blockchain verification for private-label halal ranges, displacing paper-based certificates. Slotting fee structures favor established processors with ESMA accreditation, creating barrier-to-entry for new market participants. Hypermarket halal sections concentrate shelf space for Nestle convenience formats and Al Islami Foods frozen ranges.
- Online Retail:Dedicated e-grocers and delivery platforms are expanding last-mile frozen fulfillment networks that bypass traditional retail slotting structures. Cold-chain infrastructure investments in Dubai enable same-day delivery promises to Saudi Arabia and Kuwait urban centers. This channel gains share fastest as smartphone penetration and delivery subscription models mature across Gulf urban households.
- Wholesalers:Foodservice redistribution through Dubai's Jebel Ali corridor supplies restaurants and catering operations with bulk frozen poultry and portion-controlled meat cuts.
- Convenience Stores:Limited SKU depth restricts presence to ambient snacks and shelf-stable processed items with extended certification validity periods.
Supermarkets dominate installed base through established private-label programs and certification infrastructure. Online retail is where expansion concentrates as delivery platforms capture younger household segments.
Certification Type:
Cost tier stratification separates premium-positioned third-party accreditation from economy-tier in-house claims that face exclusion from government catering contracts and major retail tenders.
- Local Authority:SFDA and ESMA seals command mandatory acceptance for Saudi Arabia and UAE import licensing respectively. Slaughterhouse audit protocols differ between regulators, generating duplicate compliance costs for multi-country distributors until GSO harmonization finalizes.
- International Standard:Malaysia JAKIM and Indonesia MUI accreditation satisfies procurement specifications for hotel chains with pan-Islamic guest demographics. Recognition agreements between GCC regulators and Asian certification bodies remain incomplete, requiring supplementary local authority documentation for domestic distribution.
- In-House:Processor self-certification faces tightening retail acceptance as liability concerns drive procurement teams toward accredited alternatives.
- Third Party:Independent accreditation from bodies such as ESMA-accredited laboratories commands shelf priority and trade finance access.
Local authority certification dominates installed base through regulatory mandate. Third-party accreditation is where expansion concentrates as retail and foodservice procurement specifications tighten.
End User:
Customer type determines volume commitment stability, with hotels and catering services offering contracted utilization rates while household demand fragments across channel preferences.
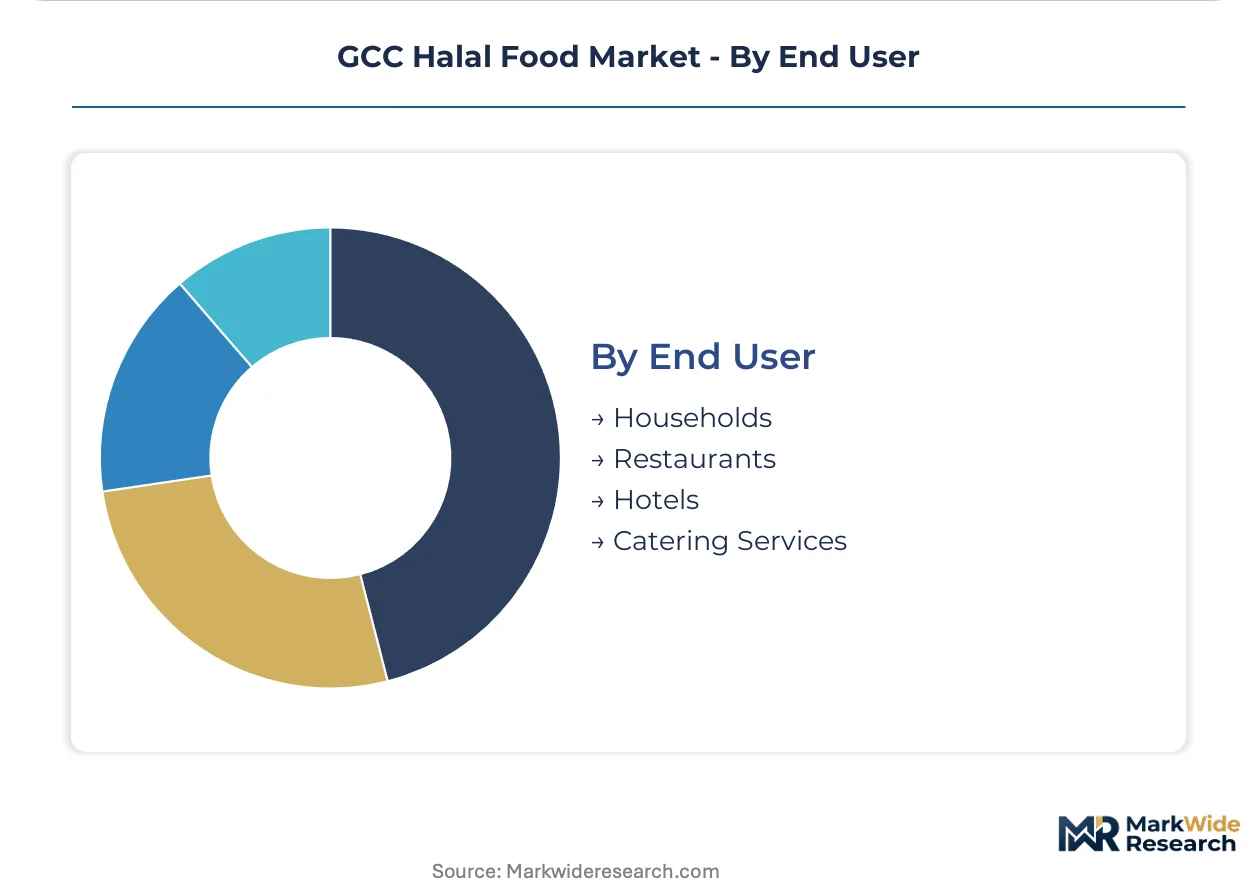
- Households:Daily consumption of poultry and ambient snacks drives frequency-based purchasing through supermarket and online channels. Price sensitivity concentrates in Saudi Arabia and Kuwait, where Brazilian-origin frozen chicken competes against premium UAE-processed alternatives.
- Restaurants:Independent foodservice operations prioritize cost-competitive wholesale supply with flexible minimum order quantities. ESMA or SFDA certification serves as pass-fail tender criteria for chain restaurant procurement, filtering non-compliant suppliers regardless of price positioning.
- Hotels:International chain properties specify grain-fed beef origin and extended aging protocols that support premium menu pricing.
- Catering Services:Government entity contracts in Saudi Arabia exclude suppliers without accredited certification, creating volume concentration among ESMA and SFDA-approved processors.
Households dominate installed base through population scale and daily consumption frequency. Catering services is where expansion concentrates as government contract specifications tighten compliance requirements across the supply base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port and Dubai's cold-chain logistics corridor anchor regional redistribution, enabling same-day fulfillment to Saudi Arabia and Kuwait while supporting just-inventory procurement models across the Gulf Cooperation Council.
Saudi Arabia
Domestic consumption of beef and lamb drives contracted procurement programs for grain-fed origin specifications. The Saudi Food and Drug Authority tightened import documentation rules for meat and poultry, forcing distributors to pre-qualify abattoirs before tender participation. Riyadh and Jeddah hotels anchor premium chilled beef demand through aging protocol specifications.
United Arab Emirates
Dubai's logistics infrastructure concentrates regional supply consolidation for frozen poultry redistribution. The Emirates Authority for Standardization and Metrology governs halal certification with slaughterhouse audit protocols that differ from Saudi frameworks. Jebel Ali Free Zone clusters processing capacity that serves captive supply contracts in Bahrain and Oman.
Kuwait
Price-sensitive household demand for Brazilian-origin frozen chicken sustains volume throughput via Dubai intermediaries. The Public Authority for Food and Nutrition aligns import licensing with Gulf Standardization Organization frameworks. Kuwait City retail channels concentrate shelf space for ESMA-accredited private-label ranges.
Qatar
Hospitality procurement for international events drives premium protein specifications with extended traceability requirements. The Ministry of Public Health mandates third-party certification for foodservice contracts. Doha logistics corridors depend on UAE-based cold-chain redistribution given limited domestic slaughterhouse scale.
Oman
Underpenetrated domestic processing capacity creates first-mover opportunity for UAE-certified suppliers seeking captive contracts. The Ministry of Regional Municipalities and Water Resources administers halal import licensing with recognition of ESMA-accredited facilities. Muscat retail channels remain dependent on cross-border supply from Dubai consolidation hubs.
GCC Halal Food Market Key Industry Players
On the supply side, the industry is bifurcated between multinational processors with backward integration into feed sourcing and regional specialists leveraging proximity to Gulf retail networks. Strategic archetypes divide into Brazilian-origin volume players, UAE-based halal-certified processors, and packaged convenience specialists with hypermarket shelf dominance. Competitive moves concentrate on certification infrastructure investment and cold-chain capacity expansion to satisfy tightened SFDA documentation requirements.
Among multinational food conglomerates, Nestle and Unilever occupy positions exemplifying packaged convenience specialization with ambient and frozen formats. Al Islami Foods and BRF S.A. anchor distinct geographic sourcing strategies, with the former representing UAE-based production proximity and the latter embodying Brazilian-origin poultry volume competitiveness. These three named entities illustrate the certification-grade and origin-based differentiation that structures procurement team evaluation criteria across Gulf retail and foodservice channels.
| Leading Market Players |
|---|
| Unilever |
| Salwa Foods |
| Al Islami Foods |
| Al Ghurair Foods |
| Noor Al Jazeera Food |
| Cargill |
| BRF S.A. |
| NAMET |
| Nestle |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors anchor cost dynamics that concentrate supply power among UAE-based processors while forcing three-tier price stratification across certification grades. Cold-chain logistics expenses from Dubai redistribution hubs transmit directly into Saudi and Kuwaiti landed costs, compressing margins for Brazilian-origin poultry shipments and amplifying ESMA-certified premium positioning.
Pricing Analysis
Volume-discount tiering separates ESMA-accredited premium SKUs from standard-grade halal products and economy-tier in-house certified alternatives. Price differentiation hinges on certification authority recognition and cold-chain integrity guarantees, with feed cost volatility from Argentine grain markets intensifying margin pressure at the economy tier. Households in Kuwait and Saudi Arabia exhibit highest price sensitivity, while government catering contracts in Riyadh and Jeddah prioritize accredited certification over cost positioning.
Supply Chain Analysis
Extended payment terms through Dubai-based trade finance facilities concentrate working capital demands on UAE processors serving Bahrain and Oman redistribution. Supply draws from Brazil, Argentina, and domestic UAE slaughterhouse capacity, with feed grain and live animal inputs anchoring cost structures. Single-source vulnerability clusters in Jebel Ali cold-chain nodes, while distribution feeds through hypermarket private-label programs and e-grocer last-mile networks bypassing traditional slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC halal food market represents early-cycle expansion as e-grocer cold-chain infrastructure penetrates underdeveloped last-mile networks across smaller Gulf states. SFDA documentation mandates accelerate this transition by filtering non-compliant suppliers and consolidating procurement relationships around certified processors with traceability systems.
For Market Incumbents:Pre-empt certification infrastructure investment ahead of GSO harmonization finalization. Lock long-term supply contracts with Oman and Bahrain hospitality procurement teams before regional competitors establish ESMA-accredited cold-chain presence. Defensive consolidation around Dubai redistribution capacity protects against Brazilian-origin volume players expanding direct Saudi distribution.
For New Entrants and Emerging Players:Oman and Bahrain underpenetration offers captive contract acquisition with lower competitive intensity than UAE and Saudi markets. Target government catering tenders in Muscat and Manama that specify ESMA recognition as mandatory criteria. Build Jebel Ali-based cold-chain partnerships rather than greenfield infrastructure to compress time-to-revenue.
For Investors and Strategic Acquirers:Carve-out targets emerge from multinational food conglomerates divesting non-core halal processing units lacking certification infrastructure. Five-to-ten-year viability favors processors with backward integration into feed sourcing and multi-country accreditation portfolios. Monitor GSO mutual recognition agreement progress as inflection signal for multi-jurisdiction compliance cost normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Investment | SFDA audit protocol divergence demands parallel accreditation tracks for Saudi market access. |
| Cold-Chain Capacity Expansion | Dubai redistribution hubs enable same-day fulfillment commitments to Kuwait and Bahrain. |
| Blockchain Traceability Deployment | Carrefour and Lulu Group procurement mandates QR-linked certificate verification for private-label ranges. |
| Backward Integration into Feed Sourcing | Argentine grain price volatility compresses margins for processors without captive supply. |
| E-Grocer Partnership Development | Last-mile frozen fulfillment networks bypass hypermarket slotting fee structures. |
Research Approach
The analysis maps meat, poultry, seafood, and packaged snack sub-sectors, each validated through procurement directors at Gulf hotel chains, supermarket category buyers, cold-chain logistics operators, and regulatory affairs specialists at certification bodies. Primary interviews with SFDA and ESMA compliance officers combined with secondary validation from GSO standardization frameworks, customs import licensing records, and hospitality industry procurement databases. Bottom-up volume triangulation across product categories reconciled against top-down market sizing from distribution channel throughput.
Assumption sets held Brazilian real exchange rates and Argentine feed grain prices within historical bands while varying GSO harmonization timeline scenarios across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, certification authority, and end-user category. CAGRs derived from trend extrapolation of per-capita protein consumption patterns and channel shift velocity from traditional retail to e-grocer platforms. Slaughterhouse capacity utilization rates and cold-chain infrastructure investment pipelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive certification infrastructure moves by Brazilian-origin volume players would shift competitive outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Miso Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
United States Tofu Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Chamomile Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Asia-Pacific Tofu Market