
 Poke Food Market | 2026-2036
Poke Food Market Size, Share, and Industry Trends Forecast 2026-2036
Poke Food Market Intelligence
Prepared bowl assembly revenue is fragmenting across build-your-own formats, third-party delivery kitchens, and grocery retail counters. Pokeworks leverages its national franchise footprint to sustain presence in major metropolitan corridors. Sweetfin anchors its position through proprietary sauce formulations and sustainable sourcing commitments. ALOHA POKE Co. competes through aggressive Midwest expansion beyond coastal strongholds.
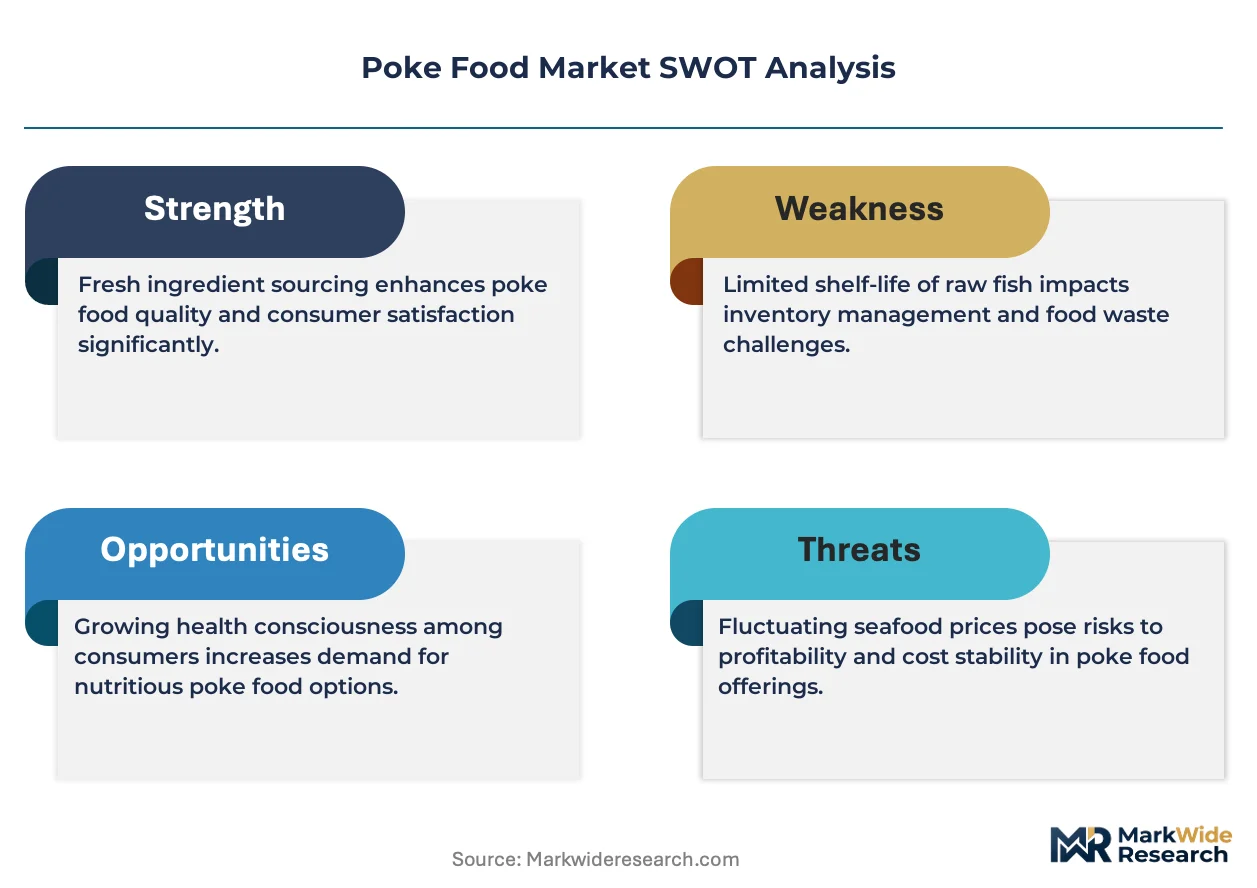
Poke food comprises diced raw fish—typically ahi tuna or salmon—marinated in soy-based sauces and served over rice or greens with vegetable toppings, requiring sustained cold-chain integrity below 40°F throughout preparation. The dish functions as a protein-dense, customizable meal format bridging sushi accessibility with salad-bar personalization. Raw fish bowls dominate current revenue pools, while tofu and vegetable-based alternatives capture the fastest-growing customer segment among health enthusiasts. Wild-caught ingredient sourcing commands premium positioning, though farmed supply chains offer more predictable cost structures for multi-unit operators.
FDA seafood HACCP regulations govern hazard control across all domestic poke production, while state-level health departments enforce additional cold-holding inspections at the point of service. The EU's EFSA and REACH frameworks shape import requirements for any European market entry, particularly concerning raw fish parasite destruction protocols. Stakeholders must monitor evolving consumer protein preferences and regulatory scrutiny of raw seafood handling as determinants of format viability and geographic expansion feasibility.
Market Dynamics
The poke food market is restructuring around cold-chain virtualization and distributed production models that separate final assembly from ingredient sourcing. Fast-casual operators now pre-position proteins in commissary kitchens while completing bowls at satellite locations, compressing real estate footprints and labor costs simultaneously.
Growth Catalysts
- FDA HACCP modernization:Updated seafood hazard controls are standardizing cold-chain documentation across multi-state operators, reducing compliance friction for franchise expansion.
- Build-your-own format proliferation:Customizable bowl assembly is pulling demand from traditional sushi counter service, particularly among office-district lunch segments in dense metropolitan corridors.
- Third-party delivery kitchen density:Ghost kitchen infrastructure in Texas and Florida is extending poke availability beyond coastal population centers without full-service restaurant investment.
Market Restraints
- Wild-caught tuna price volatility:Yellowfin and bigeye supply fluctuations from Pacific fisheries create margin compression that farmed salmon alternatives cannot fully offset.
- Parasite destruction protocol costs:FDA-mandated freezing requirements for raw fish add processing steps that commodity-grade suppliers struggle to absorb.
- Substitution by cooked-protein bowls:Grilled chicken and plant-based alternatives from Mediterranean and grain-bowl competitors capture price-sensitive trial occasions.
Strategic Opportunities
- Midwest metropolitan penetration:Chicago, Denver, and Minneapolis office districts show underdeveloped poke density relative to coastal saturation levels.
- Grocery retail counter integration:Supermarket prepared-foods sections are adding poke stations as destination traffic drivers, bypassing dedicated restaurant buildout.
- Corporate wellness program contracts:Large employers in Texas and Georgia are subsidizing healthy lunch options, creating institutional demand pools outside traditional consumer channels.
Industry Challenges
- Seafood handler certification scarcity:State-level food safety managers with raw-fish specialization are concentrated in coastal labor markets, constraining inland expansion timelines.
- Cold-chain equipment capex intensity:Reach-in blast chillers and continuous temperature monitoring systems require upfront investment that franchisees in secondary markets resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poke Food Market |
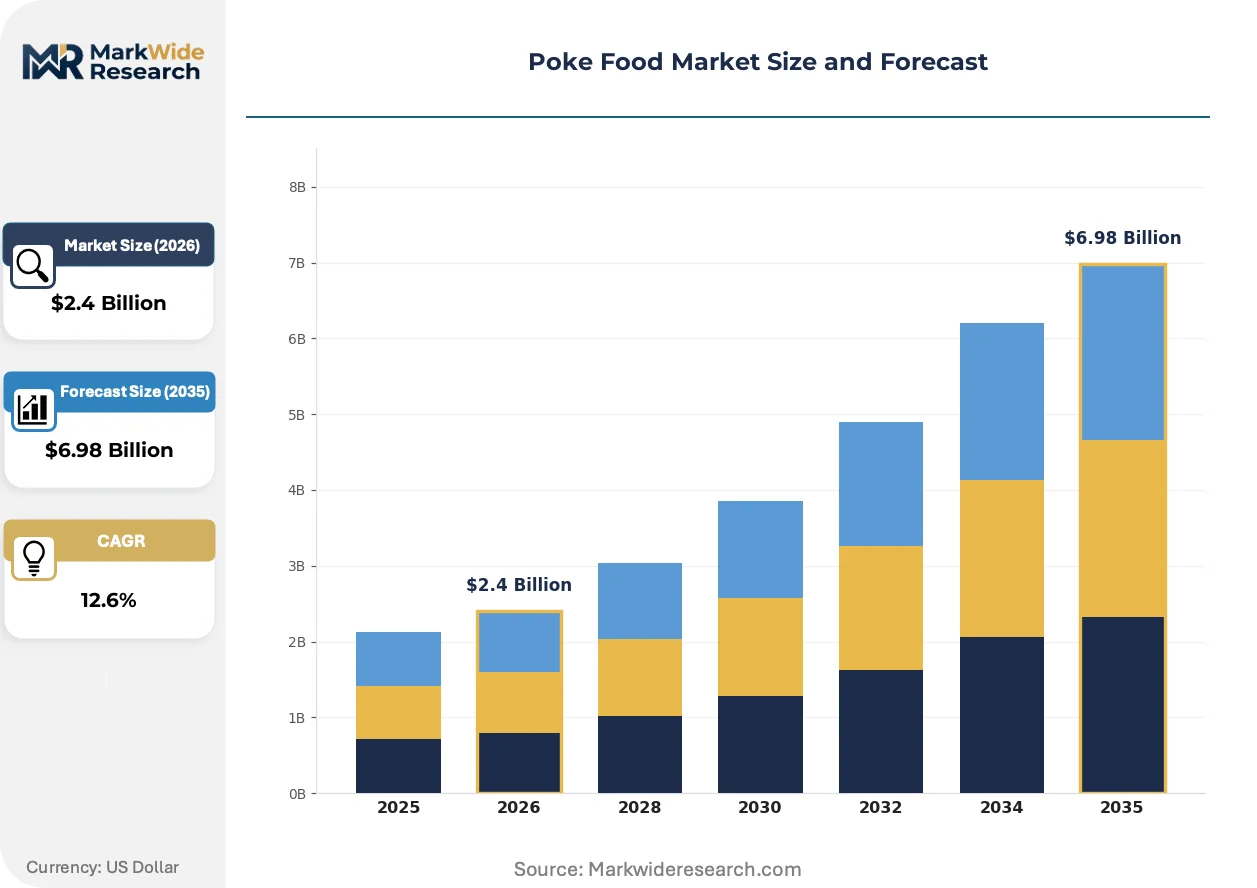
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Fish, Tofu, Vegetables, Sauces Serving Style: Bowl, Wrap, Sushi, Salad Ingredient Source: Wild-Caught, Farmed, Organic, Conventional Customer Type: Casual Diners, Health Enthusiasts, Foodies, Meal Planners |
| Companies Covered | Pokeworks, Ahipoki Bowl, ALOHA POKE Co., Sweetfin, Island Fin Poke Co., FreshFin Poke, Annasea Foods Group, HARTFORD POKE Co., Ahi Poke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poke Food Market Strategic Shifts & Innovations
Digital ordering infrastructure is virtualizing the entire poke production sequence from ingredient sourcing through final handoff. Three converging developments are compressing the traditional restaurant model into modular, asset-light formats.
Cloud-based kitchen management software is virtualizing temperature monitoring and inventory tracking across dispersed production nodes. Multi-unit operators in California and Hawaii are deploying these systems to maintain HACCP documentation without on-site quality managers at every location. The technology is virtualizing compliance oversight, enabling centralized control over dozens of micro-kitchens from a single operations center.
California's CalCode amendments and New York's retail food protection rules are tightening cold-holding inspection frequencies for raw fish operators. These state-level overlays add documentation burdens beyond federal FDA baselines, particularly affecting franchisees with limited back-of-house space. Fast-casual chains are responding with automated temperature logging systems that preempt inspector findings.
Subscription meal programs are capturing recurring lunch occasions that single-visit poke counters previously dominated. Corporate aggregators in Seattle and San Francisco are bundling weekly poke deliveries into employee benefit platforms, displacing walk-in traffic at traditional storefronts. This channel shift is most pronounced among technology sector employers with subsidized meal allowances.
Poke Food Market Segmentation
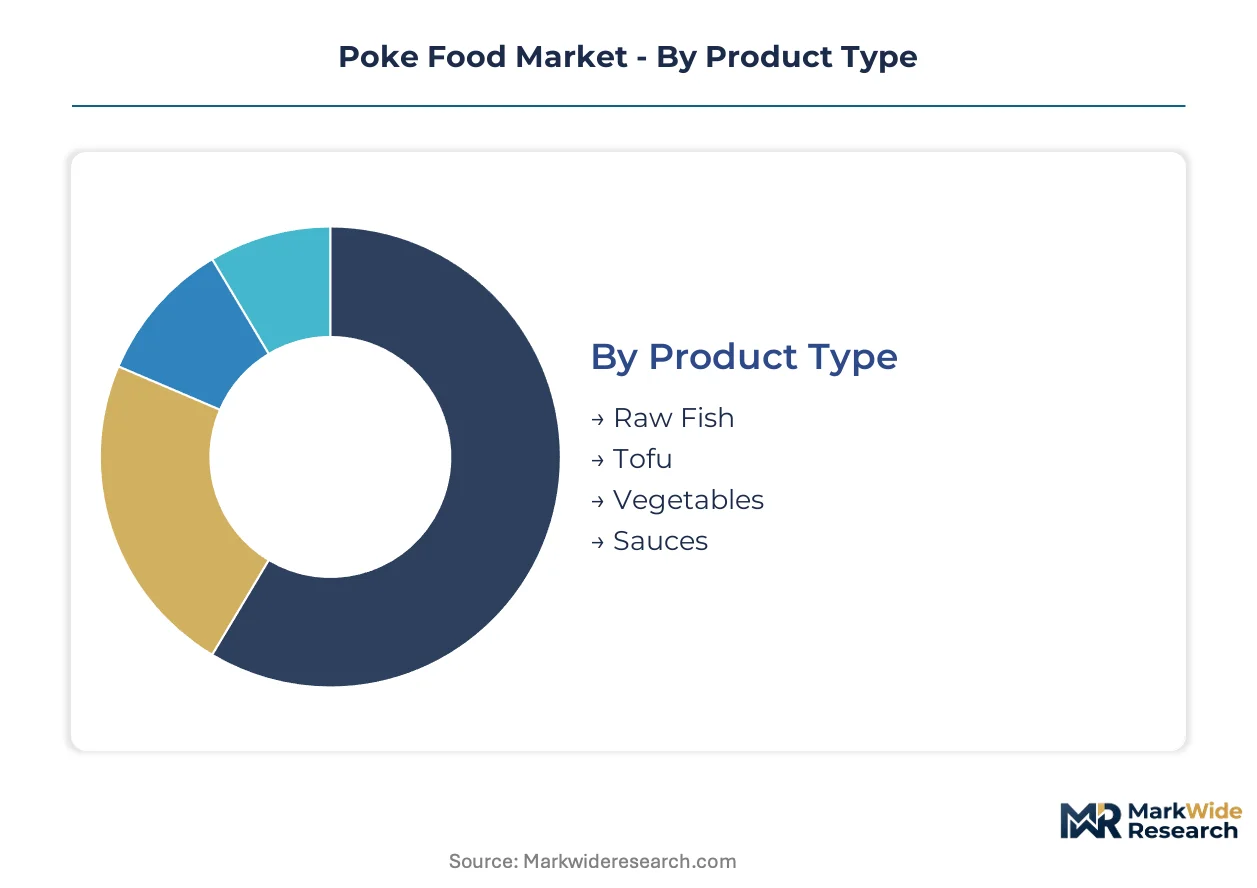
Poke food segmentation reveals how format innovation and protein sourcing create distinct operational requirements. Each category carries different cold-chain burdens, margin profiles, and geographic concentration patterns that shape operator strategy.
Product Type:
After-sales service intensity varies dramatically across protein categories, with raw fish demanding continuous temperature verification that tofu and vegetable alternatives simply do not require.
- Raw Fish:Ahi tuna and salmon dominate revenue pools, requiring FDA-mandated freezing protocols and sustained cold-chain integrity below 40°F from vessel to service counter. California and Hawaii fast-casual operators concentrate procurement here, though parasite destruction costs compress margins for smaller players.
- Tofu:Plant-based protein alternatives are expanding most quickly among health enthusiasts seeking lower-mercury options without sacrificing bowl completeness. No freezing mandates apply, simplifying supply chain documentation and enabling broader geographic distribution from centralized production.
- Vegetables:Topping arrays and base greens complete bowl architecture with minimal regulatory burden beyond standard produce handling.
- Sauces:Proprietary formulations differentiate brand positioning while adding minimal cold-chain complexity.
Raw Fish holds the largest share; momentum sits with Tofu.
Serving Style:
Cost tier separation is pronounced, with build-your-own bowl formats commanding premium positioning against grab-and-go alternatives.
- Bowl:Customizable assembly over rice or greens generates the highest per-transaction values in office-district lunch corridors. Fast-casual chains in metropolitan Texas and Florida are deploying ghost kitchen infrastructure specifically for this format.
- Wrap:Portable formats sacrifice some customization for speed, capturing commuter traffic and third-party delivery optimization.
- Sushi:Traditional presentation appeals to foodies seeking elevated experience over convenience.
- Salad:Greens-forward positioning competes directly with established salad-bar chains for health-conscious trial.
Bowl formats capture dominant revenue; Wrap configurations are gaining share fastest among delivery-native operators.
Ingredient Source:
Volume concentration patterns diverge sharply between unpredictable wild-caught supply and contractable farmed alternatives.
- Wild-Caught:Pacific yellowfin and bigeye tuna command premium menu positioning but expose operators to price volatility from fishery fluctuations. Hawaii-based concepts anchor brand identity here.
- Farmed:Atlantic salmon and aquaculture tuna deliver cost predictability that multi-unit operators require for franchise expansion into secondary markets.
- Organic:Certification premiums attract health enthusiasts in affluent coastal suburbs.
- Conventional:Standard sourcing meets price-sensitive demand in grocery retail counter deployments.
Farmed supply holds the largest share; Wild-Caught maintains steepest expansion trajectory among premium-positioned concepts.
Customer Type:
Application context determines frequency and occasion, with meal planners offering subscription potential that casual diners cannot match.
- Casual Diners:Spontaneous traffic in food halls and entertainment districts drives trial but suffers from low repeat predictability.
- Health Enthusiasts:Protein-conscious consumers in Seattle and San Francisco corporate wellness programs generate recurring weekly orders through employer-subsidized platforms.
- Foodies:Experience-seeking segments prioritize provenance storytelling and chef-driven innovation over convenience metrics.
- Meal Planners:Subscription-oriented households value portion consistency and nutritional transparency for weekly menu integration.
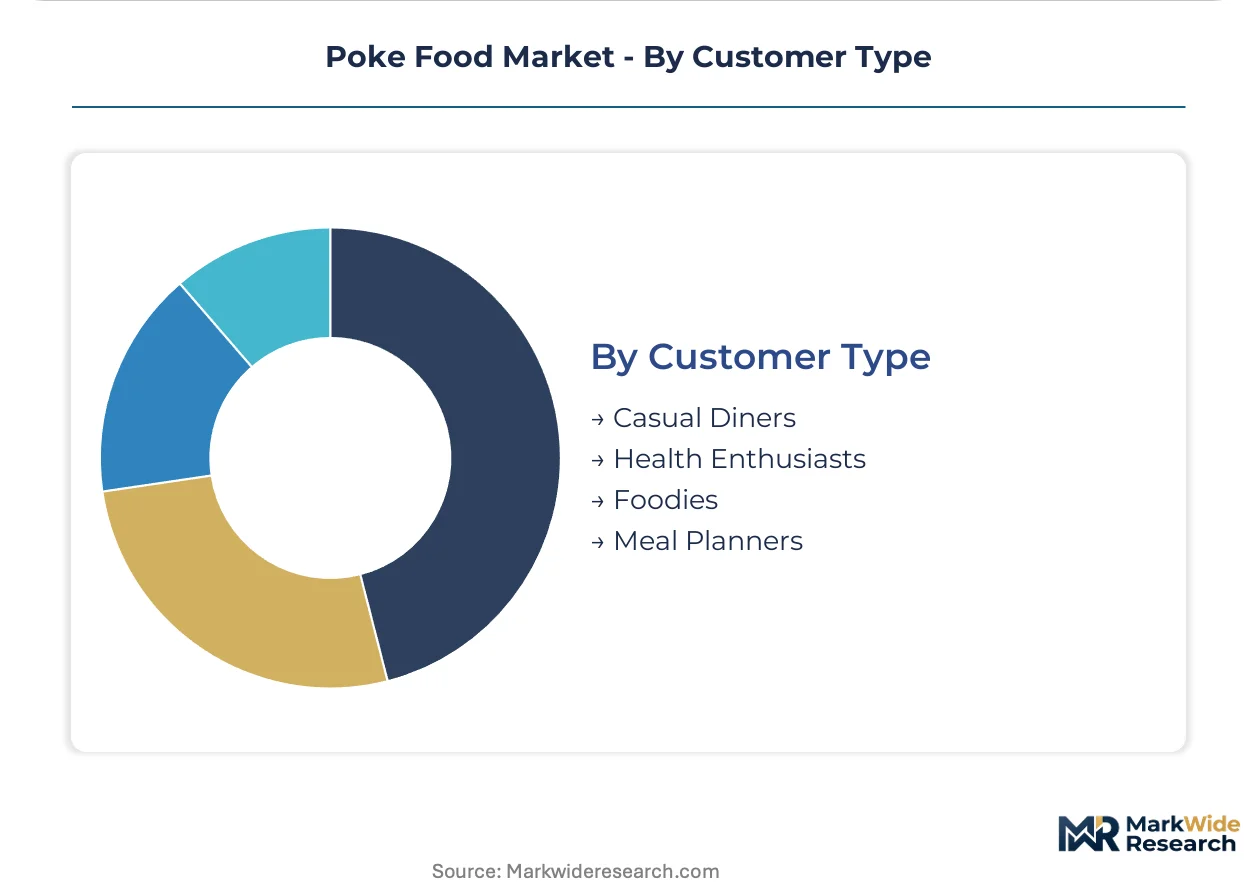
Health Enthusiasts represent the fastest-growing customer pool; Casual Diners retain largest absolute transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for poke food diverge sharply between coastal markets where raw fish familiarity runs deep and inland metropolitan areas where build-your-own formats must overcome protein-safety skepticism through corporate wellness channel entry.
United States
California and Hawaii anchor domestic demand through cultural proximity to Pacific Rim cuisine, while Texas and Florida ghost kitchens extend reach via third-party delivery infrastructure. FDA HACCP modernization standardizes cold-chain documentation across multi-state operators, reducing compliance friction for franchise expansion. Chicago and Denver office districts show underdeveloped poke density relative to coastal saturation, creating whitespace for Midwest penetration.
Canada
Toronto and Vancouver metropolitan corridors concentrate demand among health-conscious professionals seeking protein-dense lunch alternatives. Health Canada enforces parallel seafood safety protocols to FDA baselines, including parasite destruction requirements for raw fish service. Alberta's corporate headquarters clusters in Calgary are emerging as subscription meal program targets through employer-subsidized platforms.
Australia
Sydney and Melbourne coastal populations demonstrate established raw fish consumption habits from sushi culture, easing poke format trial. Food Standards Australia New Zealand governs seafood handling through Chapter 3 of the Food Standards Code, mandating temperature control and supplier verification. Brisbane's subtropical climate is accelerating demand for cold, customizable meal formats in central business district lunch corridors.
United Kingdom
London's financial district generates premium demand for customizable bowl formats competing against established grab-and-go salad chains. Food Standards Agency regulations require food business registration and hazard analysis for raw fish operations, with additional London Borough environmental health inspections. Manchester and Birmingham are seeing initial poke counter deployments in grocery retail prepared-foods sections as destination traffic drivers.
Japan
Tokyo and Osaka markets present paradoxical positioning where poke competes against deeply entrenched traditional sushi infrastructure rather than filling accessibility gaps. Japan's Ministry of Health, Labour and Welfare sets stringent food sanitation standards for raw fish handling through the Food Sanitation Act. Fukuoka's younger demographic corridors are experimenting with Hawaiian-style poke as differentiated casual dining against conventional kaiten-zushi formats.
Poke Food Market Key Industry Players
Capability concentration sits with coastal-origin specialists who command raw fish sourcing relationships and cold-chain expertise; scale advantage sits with national franchise systems deploying commissary kitchen models across dispersed geographies. The market structures around three archetypes: Hawaii-anchored authenticity brands, fast-casual franchise expanders, and grocery retail counter operators. Dominant competitive moves include ghost kitchen infrastructure deployment in secondary markets and proprietary sauce formulation differentiation to escape commodity protein positioning.
Within the coastal-specialist tier, Sweetfin and ALOHA POKE Co. exemplify contrasting geographic strategies—Sweetfin anchors West Coast presence through sustainable sourcing commitments while ALOHA POKE Co. occupies a position as aggressive Midwest expander beyond traditional coastal strongholds. Among national franchise systems, Pokeworks represents the scale-driven archetype leveraging distributed production models to compress real estate footprints across metropolitan corridors.
| Leading Market Players |
|---|
| Pokeworks |
| Ahipoki Bowl |
| ALOHA POKE Co. |
| Sweetfin |
| Island Fin Poke Co. |
| FreshFin Poke |
| Annasea Foods Group |
| HARTFORD POKE Co. |
| Ahi Poke |
| Others |
Cost & Logistics Intelligence
Pacific yellowfin and bigeye tuna landings from Hawaii and California fisheries anchor upstream supply concentration, concentrating margin pools with fast-casual operators who command cold-chain expertise and direct vessel relationships. Price differentiation across the poke market hinges on protein sourcing tier and geographic proximity to coastal distribution hubs.
Pricing Analysis
Long-term offtake agreements with Pacific tuna suppliers dominate procurement for established coastal operators, while spot market exposure concentrates among inland franchisees lacking direct sourcing relationships. Three-tier pricing structure across wild-caught premium, farmed standard, and plant-based economy levels reflects certification grade and cold-chain investment intensity. Cost compression in the wild-caught tier is intensifying because yellowfin supply fluctuations from Pacific fisheries create unpredictable landed costs. Price-sensitive trial occasions concentrate among office-district lunch segments in secondary metropolitan markets, while least sensitivity sits with health enthusiasts in employer-subsidized corporate wellness programs.
Supply Chain Analysis
Extended payment terms from seafood distributors to fast-casual operators stretch working capital cycles, particularly for franchisees in Texas and Florida ghost kitchen deployments. Supply concentration sits with Hawaii, California, and Indonesia for tuna landings; Atlantic salmon farms in Norway and Chile provide cost-predictable alternatives. Raw material dependencies center on sashimi-grade tuna, sushi rice, and proprietary sauce bases. Single-source vulnerability from Pacific yellowfin fisheries exposed to climate-driven migration pattern shifts threatens supply continuity. Distribution runs through commissary kitchen networks that pre-position proteins for final assembly at satellite locations, compressing real estate footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized seafood handler certification scarcity constrains inland expansion timelines, creating asymmetric capability advantages for coastal-origin operators with established cold-chain workforces.
For Market Incumbents: Harden cold-chain documentation systems against tightening state-level inspection frequencies in California and New York. Pursue backward integration into commissary kitchen infrastructure to reduce third-party dependency and defend margin position against wild-caught price volatility. Consolidate position through proprietary sauce formulation investment that escapes commodity protein positioning. For New Entrants and Emerging Players: Chicago, Denver, and Minneapolis office districts present underpenetrated whitespace relative to coastal saturation levels. Target grocery retail counter integration as a bypass strategy avoiding dedicated restaurant buildout costs. Lead with build-your-own bowl formats through employer-subsidized corporate wellness channel entry rather than competing for spontaneous walk-in traffic. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fast-casual franchise systems that have exhausted coastal expansion runway. Long-term viability over the next decade rests on successful Midwest penetration and ghost kitchen infrastructure deployment. Monitor FDA HACCP modernization implementation pace as the inflection signal for reduced compliance friction enabling multi-state rollup opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Kitchen Network Expansion | Enables centralized protein sourcing for distributed micro-kitchen deployment across secondary metropolitan corridors. |
| Proprietary Sauce Formulation Investment | Differentiates brand positioning beyond commodity protein sourcing to escape price-based competition. |
| Ghost Kitchen Infrastructure Deployment | Extends poke availability through Texas and Florida third-party delivery density without full-service restaurant capex. |
| Corporate Wellness Program Integration | Captures recurring subscription revenue from Seattle and San Francisco technology sector employer platforms. |
| Automated Temperature Logging Implementation | Preempts CalCode and New York retail food protection inspection findings through continuous HACCP documentation. |
Research Approach
Cross-validation between executive interviews with fast-casual franchise operators and secondary analysis of FDA HACCP compliance documentation anchors the qualitative findings. Primary fieldwork engaged seafood procurement directors, state health department inspectors, ghost kitchen facility managers, and corporate wellness program administrators. Secondary sources included FDA seafood safety guidance documents, state-level retail food protection regulations, fast-casual franchise disclosure documents, and cold-chain equipment manufacturer specifications. Bottom-up location-level demand estimation triangulated against top-down market sizing from protein import and domestic landings data.
Calibration against historical expansion patterns of comparable fast-casual formats refined the analytical framework across the analysis window. Segmentation dimensions modeled include protein type, serving format, ingredient sourcing tier, and customer occasion context. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and cold-chain infrastructure deployment rates. Forecast inputs incorporated ghost kitchen density projections and corporate wellness program adoption curves in target metropolitan markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed rollup platforms or rapid ghost kitchen saturation would shift outcomes. Macroeconomic deviation affecting discretionary lunch spending, regulatory acceleration of raw fish handling requirements, or breakthroughs in plant-based protein texture replication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Edible Mushroom Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Chamomile Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Acacia Honey Market
Specialty Foods
United States Tofu Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Therapeutic Dog Food Market