
 Carbonic Maceration Market | 2026-2036
Carbonic Maceration Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonic Maceration Market Outlook
French wine cooperatives is pivoting toward controlled-atmosphere fermentation infrastructure to preserve fruit-forward aromatics. Laffort leverages its enological supply chain to dominate yeast and enzyme distribution for carbonic setups. Oenobrands anchors Southern European demand through specialized fermentation aids. Torres competes on scale, operating carbonic programs across multiple Spanish appellations.
Carbonic maceration denotes an anaerobic fermentation process where intact grape berries undergo enzymatic intracellular fermentation in a carbon dioxide-rich environment, typically at temperatures between 25°C and 30°C, before conventional yeast fermentation completes extraction; the method preserves primary fruit esters while reducing tannin extraction, serving commercial wineries seeking approachable, early-release wines. Red wine occupies the dominant share of carbonic output given Beaujolais-style Gamay production, though sparkling wine applications are gaining traction among producers experimenting with pet-nat methodologies. Commercial production sustains the largest application segment as mid-size wineries scale tank infrastructure, while direct sales channels capture premium margin pools from estate-bottled carbonic offerings.
EU REACH frameworks govern enological additive approvals, while France's national regulator ANSM oversees food-contact material standards for fermentation vessels; both bodies shape equipment investment cycles and chemical input compliance costs for producers. EFSA wine labeling directives further constrain how carbonic-derived products communicate production methodology to export markets. Stakeholders must monitor evolving organic certification harmonization between EU member states and third-country equivalency agreements.
Market Dynamics
Controlled-atmosphere tank infrastructure is concentrating investment among mid-size European wineries seeking to replicate Beaujolais-style aromatics without Gamay varietal constraints. This capital reallocation is compressing traditional open-fermentation capacity and reshaping supplier relationships across the enological equipment chain.
Growth Catalysts
- EU Green Deal sustainability mandates:Lower-intervention fermentation methods align with carbon-reduction targets for wine production, creating preferential treatment for carbonic-derived labels in export certification schemes.
- Premium red wine segment expansion:Beaujolais Nouveau release cycles demonstrate commercial viability of early-market positioning, pulling investment from conventional barrel-aging programs toward rapid-turnover tank systems.
- Enzyme stabilization technology:Advanced pectolytic preparations now permit consistent intracellular fermentation across non-Gamay varietals, extending carbonic applicability to Tempranillo and Grenache production.
Market Restraints
- Stainless steel input cost volatility:Fermentation vessel fabrication depends on nickel alloy pricing, exposing equipment buyers to commodity swings that delay infrastructure scaling decisions.
- Technical limitation in tannin management:Carbonic protocols inherently suppress phenolic extraction, constraining output to light-bodied styles that command narrower price premiums in established Cabernet and Nebbiolo markets.
- EFSA labeling friction:Methodology disclosure requirements for carbonic-derived wines create compliance overhead that disadvantages smaller producers against conventional fermentation competitors.
Strategic Opportunities
- Pet-nat sparkling application expansion:Natural wine producers in Italy's Emilia-Romagna region are adapting carbonic protocols for ancestral-method sparkling production, opening volume channels beyond still red categories.
- Organic certification harmonization:Pending equivalency agreements between EU member states and third-country organic regulators will streamline carbonic wine export into North American natural wine distribution networks.
- Direct-to-consumer channel innovation:Estate-bottled carbonic programs bypass traditional three-tier distribution, capturing margin pools through subscription and cellar-door sales models in France's Loire Valley.
Industry Challenges
- Specialized enologist talent scarcity:Carbonic protocol optimization requires expertise in enzymatic kinetics and temperature-gradient management that outpaces vocational training program output in Southern Europe.
- Tank infrastructure capex intensity:Sealed fermentation systems with CO2 injection capability demand capital allocation that strains cooperative winery balance sheets against conventional open-vat alternatives.
- REACH additive approval timelines:Novel fermentation aids face extended safety evaluation periods that delay product formulation updates and compress competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonic Maceration Market |
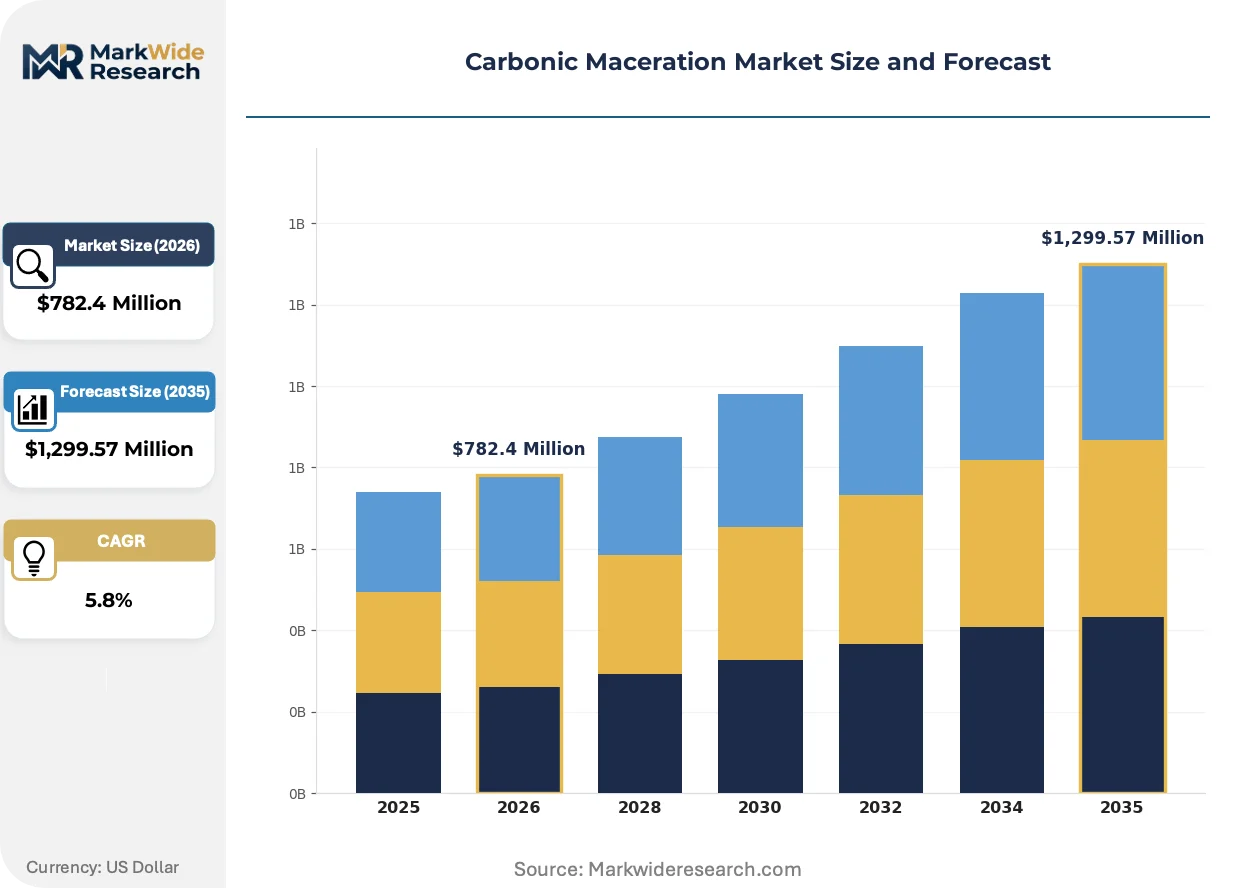
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Dessert Wine Application: Home Brewing, Commercial Production, Wine Enthusiasts, Educational Institutions Distribution Channel: Retail, Online, Wholesalers, Direct Sales End User: Restaurants, Hotels, Bars, Wineries |
| Companies Covered | Laffort, Oenobrands, IMAWAVE, Vincor International, Vinadeis, Torres, Maison Joseph Drouhin, Louis Jadot, Jean Foillard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonic Maceration Market Strategic Shifts
Temperature-modulated tank systems are compressing fermentation cycle variance, enabling precise aromatic preservation across diverse grape varieties. This technological maturation is pulling investment from traditional cellar infrastructure toward programmable controlled-atmosphere environments.
Automated CO2 saturation monitoring is overtaking manual tank sampling protocols in commercial-scale wineries. Mid-size producers in Spain's Catalonia region are deploying dissolved-gas sensors at 48-hour intervals, compressing labor input while tightening aromatic consistency across multi-tank programs. This sensor integration is overtaking conventional punch-down labor models and reshaping cellar staffing structures.
France's ANSM is tightening food-contact material standards for fermentation vessel coatings, mandating expanded migration testing for epoxy and polyurethane linings. Equipment fabricators face reformulation costs that pass through to winery buyers, concentrating procurement among suppliers with pre-certified material portfolios. Beaujolais-based cooperatives are responding by consolidating orders with established tank manufacturers possessing existing ANSM documentation.
Natural wine buyer clusters are compressing release-to-consumption cycles, demanding carbonic wines within months of fermentation completion. Distributors in Paris and London are bypassing traditional aging-mandate inventory models, replacing them with direct-import relationships that prioritize tank-fresh aromatic profiles. This behavioral shift is most visible in urban on-premise accounts where sommelier education programs now feature carbonic methodology as a distinct service category.
Carbonic Maceration Market Segmentation
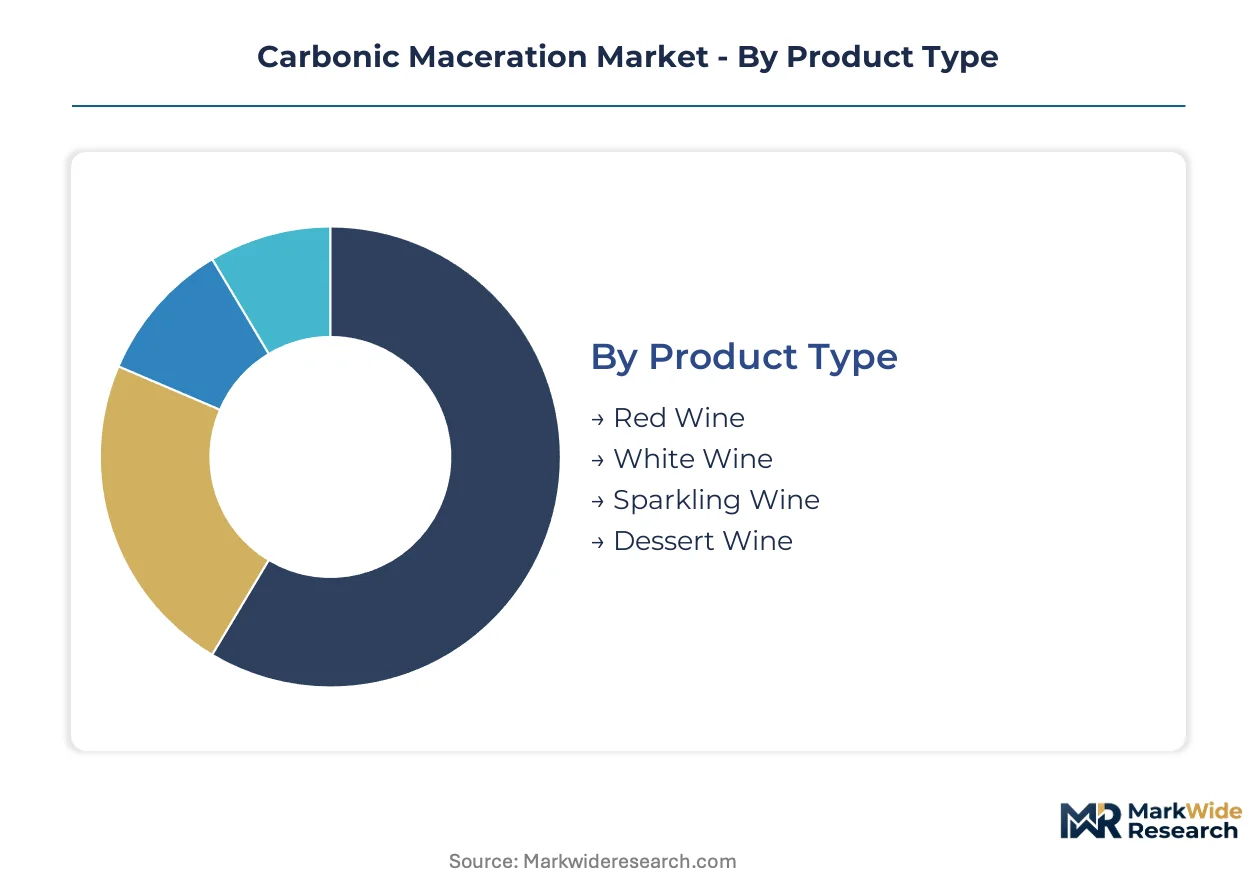
Carbonic maceration deployment varies sharply by output format and buyer sophistication. Volume producers prioritize tank-scalable formats while premium positioning demands controlled-atmosphere precision. Segmentation reveals where capital equipment investments concentrate versus where artisan methodology commands margin premiums.
Product Type:
Volume production gravitates toward early-release red formats, while premium positioning exploits aromatic preservation in niche white and sparkling categories.
- Red Wine:Intact-berry anaerobic fermentation preserves primary fruit esters while suppressing tannin extraction, producing light-bodied, approachable styles. Beaujolais cooperatives in France anchor commercial demand, with Gamay-dominant programs driving tank infrastructure investment cycles.
- Sparkling Wine:Pet-nat producers in Italy's Emilia-Romagna region adapt carbonic protocols for ancestral-method sparkling, capturing natural wine distribution channels through tank-fresh aromatic profiles.
- White Wine:Limited carbonic application for aromatic whites in Loire Valley estates seeking differentiation from conventional press-and-settle methods.
- Dessert Wine:Experimental deployment in fortified production, constrained by sugar-alcohol balance challenges during intracellular fermentation.
Mature deployment sits with Red Wine. Newer deployment is concentrated in Sparkling Wine.
Application:
Capital intensity separates commercial-scale programs from enthusiast-grade experimentation, with education channels serving as equipment trial grounds.
- Commercial Production:Mid-size wineries across Spain's Catalonia region scale sealed tank systems with CO2 injection capability, compressing labor input through automated dissolved-gas monitoring at 48-hour intervals.
- Home Brewing:Enthusiast-grade carbonic experimentation concentrates in urban natural wine communities, with small-batch fermentation vessels sourced through specialized enological suppliers.
- Wine Enthusiasts:Collector-driven demand for estate-bottled carbonic offerings bypasses traditional three-tier distribution through subscription and cellar-door models in France's Loire Valley.
- Educational Institutions:Viticulture programs in Italy and France deploy carbonic modules for enology training, generating equipment trial exposure for graduating cellar managers.
Commercial Production commands infrastructure investment. Home Brewing exhibits the steepest expansion trajectory among non-commercial segments.
Distribution Channel:
Margin capture separates direct relationships from wholesale intermediation, with digital channels accelerating release-to-consumption compression.
- Direct Sales:Estate-bottled programs in Beaujolais bypass distributor markup through cellar-door and subscription models, capturing premium pools from natural wine buyer clusters in Paris and London.
- Online:Digital platforms accelerate tank-fresh aromatic positioning, with urban on-premise accounts sourcing carbonic inventories through direct-import relationships that bypass aging-mandate traditional models.
- Retail:Specialist wine merchants stock carbonic-derived labels for early-release seasonal positioning, constrained by inventory turnover requirements.
- Wholesalers:Three-tier intermediation dominates conventional Beaujolais Nouveau release cycles, though margin compression pushes producers toward alternative channels.
Direct Sales anchor premium positioning. Online channels are gaining share fastest among mid-tier producers.
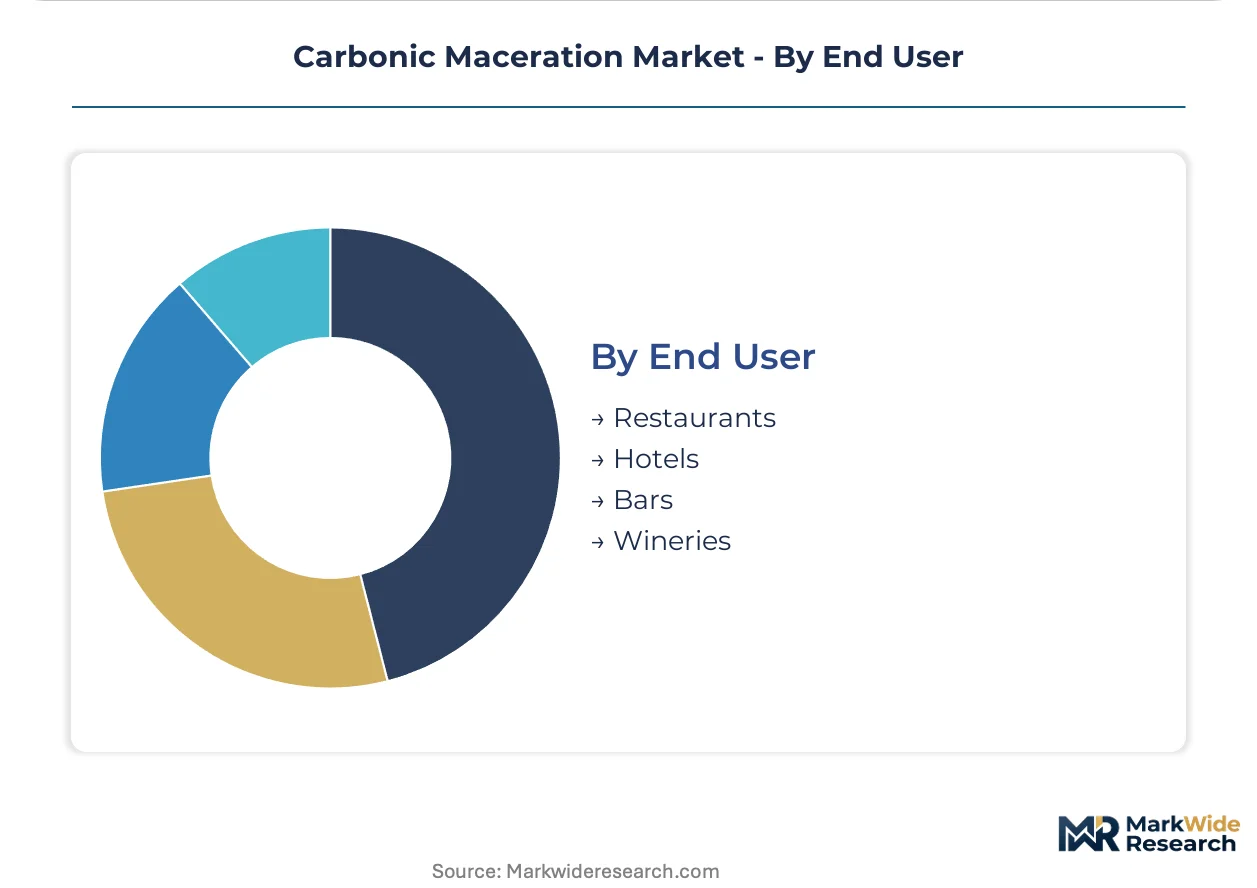
End User:
On-premise sophistication separates sommelier-driven adoption from hotel banquet standardization, with winery estate programs controlling methodology narrative.
- Wineries:Estate-controlled carbonic programs dominate output volume, with France's Beaujolais cooperatives and Spain's Torres operating multi-appellation tank infrastructure.
- Restaurants:Urban on-premise accounts in Paris and London feature carbonic methodology as a distinct service category, with sommelier education programs now covering intracellular fermentation protocols.
- Bars:Natural wine-focused establishments prioritize tank-fresh carbonic offerings for by-the-glass programs, compressing release-to-consumption cycles.
- Hotels:Luxury property beverage programs stock carbonic-derived labels for seasonal list rotation, with procurement decisions centralized at group purchasing level.
Wineries control production methodology. Restaurants drive on-premise education and consumer exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beaujolais granite soils anchor carbonic maceration geography, with Gamay cultivation concentrating tank infrastructure investment across specific European viticultural zones. Equipment fabrication clusters trace stainless steel supply chains through Northern Italian and Spanish metalworking regions.
France
Boutique cooperatives in Beaujolais drive controlled-atmosphere fermentation adoption for Nouveau release cycles. ANSM food-contact material standards mandate expanded migration testing for tank coatings, concentrating procurement among pre-certified fabricators. The Loire Valley estates are pivoting toward subscription-based direct sales of estate-bottled carbonic offerings.
Spain
Torres operates multi-appellation carbonic programs across Catalonia, scaling sealed tank systems with automated CO2 monitoring. REACH frameworks govern enological additive approvals for pectolytic enzyme preparations. Barcelona-area equipment suppliers are consolidating orders to offset nickel alloy price volatility in vessel fabrication.
Italy
Emilia-Romagna pet-nat producers adapt carbonic protocols for ancestral-method sparkling, capturing natural wine distribution channels. EFSA wine labeling directives constrain methodology disclosure requirements for export certification. Parma-based fermentation aid specialists are expanding enzyme stabilization technology for Tempranillo and Grenache applications.
United States
Urban natural wine communities in California concentrate small-batch carbonic experimentation through specialized enological suppliers. FDA oversight applies to imported fermentation aids and food-contact materials in cellar operations. Sonoma County wineries are deploying temperature-modulated tank systems for aromatic preservation across diverse grape varieties.
Australia
Viticulture programs in Victoria and South Australia deploy carbonic modules for enology training, generating equipment trial exposure. The country's national food standards regulator oversees additive approvals for intracellular fermentation aids. Adelaide Hills estates are experimenting with carbonic white wine production for aromatic differentiation.
Carbonic Maceration Market Competitive Environment
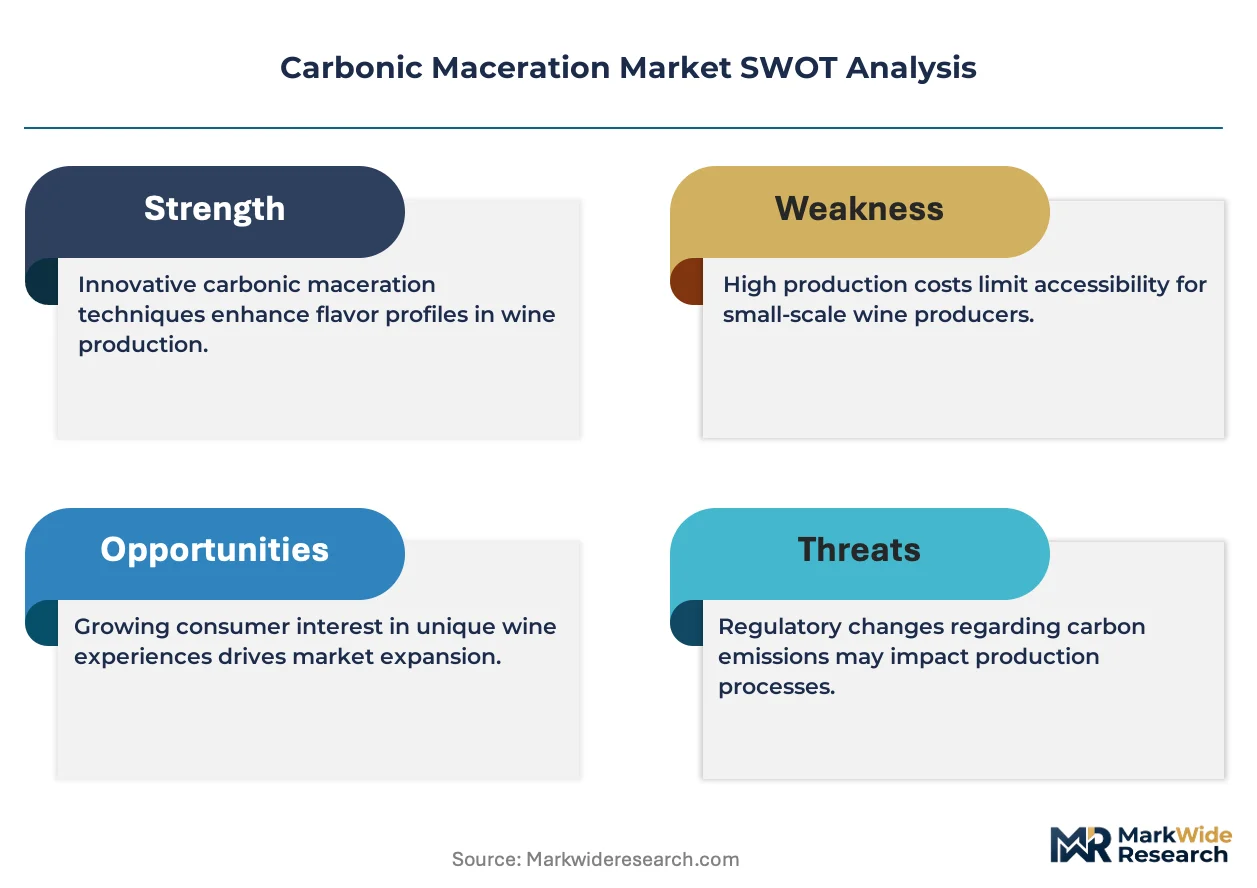
Established producers occupy the standard tier; emerging entrants pursue natural wine distribution and pet-nat methodology adjacent spaces. The competitive structure concentrates around enological supply chain dominance and multi-appellation scale operations. Three archetypes define positioning: yeast and enzyme distributors, fermentation aid specialists, and vertically integrated winery operators. Capacity expansion in controlled-atmosphere tank infrastructure and strategic partnerships for organic certification harmonization represent dominant competitive moves.
Within the supply chain tier, Laffort leverages its enological distribution network, while Oenobrands anchors Southern European demand through specialized fermentation aids. At the integrated winery end, Torres exemplifies multi-appellation scale operations. These three occupy positions that span equipment procurement, additive supply, and estate production methodologies.
| Leading Market Players |
|---|
| Laffort |
| Oenobrands |
| IMAWAVE |
| Vincor International |
| Vinadeis |
| Torres |
| Maison Joseph Drouhin |
| Louis Jadot |
| Jean Foillard |
| Others |
Value Chain & Pricing Dynamics
Family-owned cooperatives in France's Beaujolais region anchor controlled-atmosphere tank procurement, their collective purchasing power compressing supplier margins while preserving pricing discipline for estate-bottled carbonic offerings through direct-channel premiums.
Pricing Analysis
Service-bundling separates equipment suppliers offering ANSM-certified tank coatings and installation support from bare-vessel competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and automation sophistication. Pricing pressure stems from nickel alloy cost volatility in stainless steel fabrication, squeezing mid-tier fabricators. Boutique wineries exhibit highest price sensitivity, while multi-appellation operators like Torres absorb capex through scale economies.
Supply Chain Analysis
Direct-to-winery channels handle sealed fermentation system demand from France, Italy, and Spain, bypassing distributor markups for large cooperative orders. Vessel fabrication draws from Northern Italian and Spanish metalworking clusters, sourcing nickel-chromium alloys and specialized epoxy linings. Single-source vulnerability concentrates in ANSM-pre-certified coating suppliers, creating procurement bottlenecks. Distribution runs through enological equipment specialists and direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere tank fabrication capacity constraints prop pricing power for certified suppliers, as lead times extend for ANSM-compliant vessel delivery.
For Market Incumbents: Deploy backward integration into stainless steel alloy sourcing to offset nickel price volatility. Consolidate procurement relationships with Beaujolais cooperatives facing REACH additive approval delays. Anchor market position through captive supply of pectolytic enzyme formulations, neutralizing emerging fermentation aid specialists. For New Entrants and Emerging Players: Begin with pet-nat sparkling applications in Italy's Emilia-Romagna region, where carbonic protocol adaptation remains underdeveloped. Target natural wine distribution channels in Paris and London urban on-premise accounts. Pursue direct-import relationships that bypass traditional three-tier aging-mandate inventory models. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation aid specialists with pre-certified ANSM documentation in Southern Europe. Long-term viability hinges on organic certification harmonization between EU member states and North American equivalency agreements. Monitor EFSA labeling directive enforcement as inflection indicator for compliance-cost advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Tank Capacity Expansion | Mid-size wineries in Catalonia scale automated CO2 monitoring to compress labor input. |
| Backward Integration into Enzyme Formulation | Laffort secures captive supply of pectolytic preparations for non-Gamay varietal extension. |
| Direct-to-Consumer Channel Development | Loire Valley estates capture margin pools through subscription-based carbonic release programs. |
| Organic Certification Harmonization Partnership | Streamlined EU-US equivalency agreements unlock North American natural wine distribution. |
| Temperature-Modulated System R&D Investment | Sonoma County producers deploy programmable environments for aromatic preservation across varieties. |
Study Parameters
Trade publications, EU regulatory filings, and enological equipment manufacturer disclosures formed the secondary backbone, cross-referenced against primary interviews with cellar managers, cooperative procurement officers, fermentation aid specialists, and ANSM compliance consultants. Bottom-up tank installation tracking and top-down wine production statistics enabled triangulation across the analysis window.
Historical capacity utilization trends informed projection modeling across product type, application scale, distribution channel, and end-user sophistication dimensions. CAGRs derived from equipment shipment correlations with Nouveau release cycle timing. Forecast inputs incorporated REACH additive approval timelines and organic certification equivalency negotiation status.
Underlying measurement precision varies by segment; commercial production and direct sales channels carry tighter precision than home brewing experimentation. Forecasts reflect assumptions regarding nickel alloy price stability and EFSA labeling enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Natural Honey Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
North America Hummus Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Cultures Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Space Food Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Low Calorie Chocolate Desserts Market