
 Zhacai Market | 2026-2036
Zhacai Market Size, Share, and Industry Trends Forecast 2026-2036
Zhacai Market Insights
China's GB 2714 national food safety standard for pickled vegetables is decoupling artisanal producers from modern retail channels. Chongqing Fuling Zhacai Group leverages its captive mustard green supply across the Three Gorges Reservoir region to sustain cost advantages. Yu Quanzhacai anchors premium positioning through controlled fermentation protocols that yield consistent crispness. Fansaoguang Food competes on volume scale, operating automated brining lines that supply food service distributors nationwide.
Zhacai denotes a lacto-fermented mustard tuber product, typically brined for 3-6 months in ceramic vessels with salt concentrations of 6-10% and pressed to achieve characteristic texture. The product serves as a condiment, soup base ingredient, and protein accompaniment across East Asian cuisines. Aged zhacai commands the deepest margin pools due to extended curing cycles and heritage branding, while vacuum-sealed packaging dominates retail velocity by extending shelf life without preservatives. Online marketplaces represent the fastest-growing distribution channel, though wholesalers still control restaurant procurement volumes.
SAMR enforces GB standards for additive limits and labeling, while China's MEE monitors wastewater discharge from brine processing facilities. BIS certification requirements constrain Indian import channels, forcing exporters to maintain dual compliance documentation. Stakeholders must monitor how evolving salt-reduction mandates reshape traditional fermentation recipes without compromising shelf stability.
Market Dynamics
China's GB 2714 national food safety standard for pickled vegetables is decoupling artisanal producers from modern retail channels, forcing facility upgrades and documentation protocols that favor capitalized operators with centralized fermentation capacity.
Growth Catalysts
- Urban household adoption:Packaged zhacai penetration accelerates in China's tier-one and tier-two cities as time-constrained consumers shift from wet-market bulk purchases to shelf-stable retail formats with standardized labeling.
- GB 2714 compliance infrastructure:SAMR enforcement of additive limits and traceability requirements is consolidating production into HACCP-certified facilities capable of supplying chain supermarkets and export channels.
- Three Gorges mustard green cultivation:Captive agricultural supply in the Yangtze River reservoir region secures raw material cost advantages for processors with long-term grower contracts.
Market Restraints
- Brine wastewater discharge costs:China's MEE monitors fermentation facility effluent, requiring tertiary treatment systems that add operational overhead for small and mid-scale producers.
- Artisanal supply fragmentation:Thousands of village-level workshops lack capital for ceramic vessel standardization and automated pressing equipment, constraining volume scalability.
- Fresh pickle substitution:Refrigerated short-ferment vegetable products compete for condiment shelf space in premium urban retail, pressuring aged zhacai margin pools.
Strategic Opportunities
- Indian import channel development:BIS certification requirements constrain current export volumes, creating first-mover advantage for processors establishing dual compliance documentation and dedicated South Asian product lines.
- Online marketplace distribution:E-commerce platforms represent underpenetrated velocity for heritage-branded aged zhacai, bypassing traditional wholesaler markups to reach direct-to-consumer households.
- Salt-reduction formulation R&D:Evolving dietary guidelines create technical white space for fermentation protocols that maintain shelf stability at reduced sodium concentrations without preservative additives.
Industry Challenges
- Master fermenter skill scarcity:Traditional lacto-fermentation expertise resides with aging practitioners in Sichuan and Chongqing, creating knowledge transfer gaps as facilities automate brining and pressing operations.
- Dual carbon compliance capex:China's dual carbon goals mandate energy efficiency retrofits for steam pasteurization and vacuum sealing lines, requiring capital deployment ahead of depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zhacai Market |
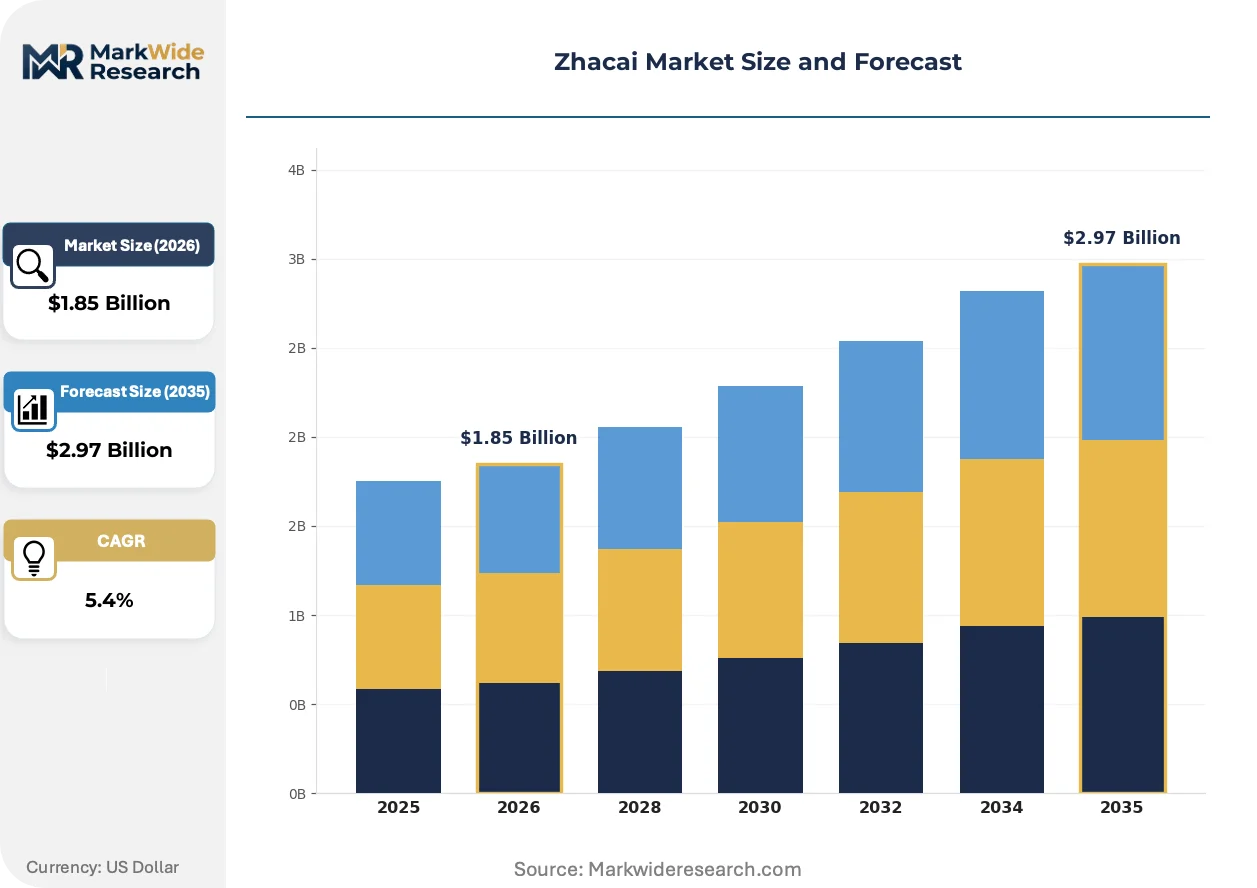
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aged Zhacai, Fresh Zhacai, Pickled Zhacai, Spiced Zhacai Packaging Type: Bottled, Vacuum-Sealed, Bagged, Jarred Distribution Channel: Retail Stores, Online Marketplaces, Wholesalers, Food Service End User: Households, Restaurants, Food Manufacturers, Exporters |
| Companies Covered | Chongqing Fuling Zhacai Group, Yu Quanzhacai, Fansaoguang Food, Jixiangju Food, Huitong Food, Ningbo Tongxianqiao, Lameizi, Weijute Food, Sichuan Chuannan Brewing Limited Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zhacai Market Trends and Innovations
Controlled fermentation protocols and packaging automation are reshaping competitive positioning in zhacai processing, compressing quality variance and extending shelf life without chemical preservatives.
Automated brining lines with programmable salt concentration monitoring are expanding into mid-scale processing facilities previously dependent on manual ceramic vessel management. Food service distributors and institutional buyers are adopting these systems to secure consistent texture specifications across batch volumes. The technology is expanding into contract manufacturing arrangements where brand owners outsource production to certified third-party facilities.
China's SAMR is tightening GB 2714 enforcement timelines for pickled vegetable additive declarations and origin labeling. Facilities must now maintain batch-level traceability documentation linking mustard tuber harvest zones to finished product codes. Small workshops in Chongqing and Sichuan face exclusion from supermarket supply chains as compliance costs outpace revenue per unit.
Restaurant procurement is consolidating around food service distributors with cold-chain logistics and automated inventory replenishment systems. Independent zhacai wholesalers in Shanghai and Jiangsu are losing share to national distributors operating ERP-integrated platforms that guarantee lot consistency and just-in-time delivery to chain restaurant kitchens. This concentration is most visible in the Yangtze River Delta processing clusters where processor-distributor vertical alignment is deepening.
Zhacai Market Segmentation
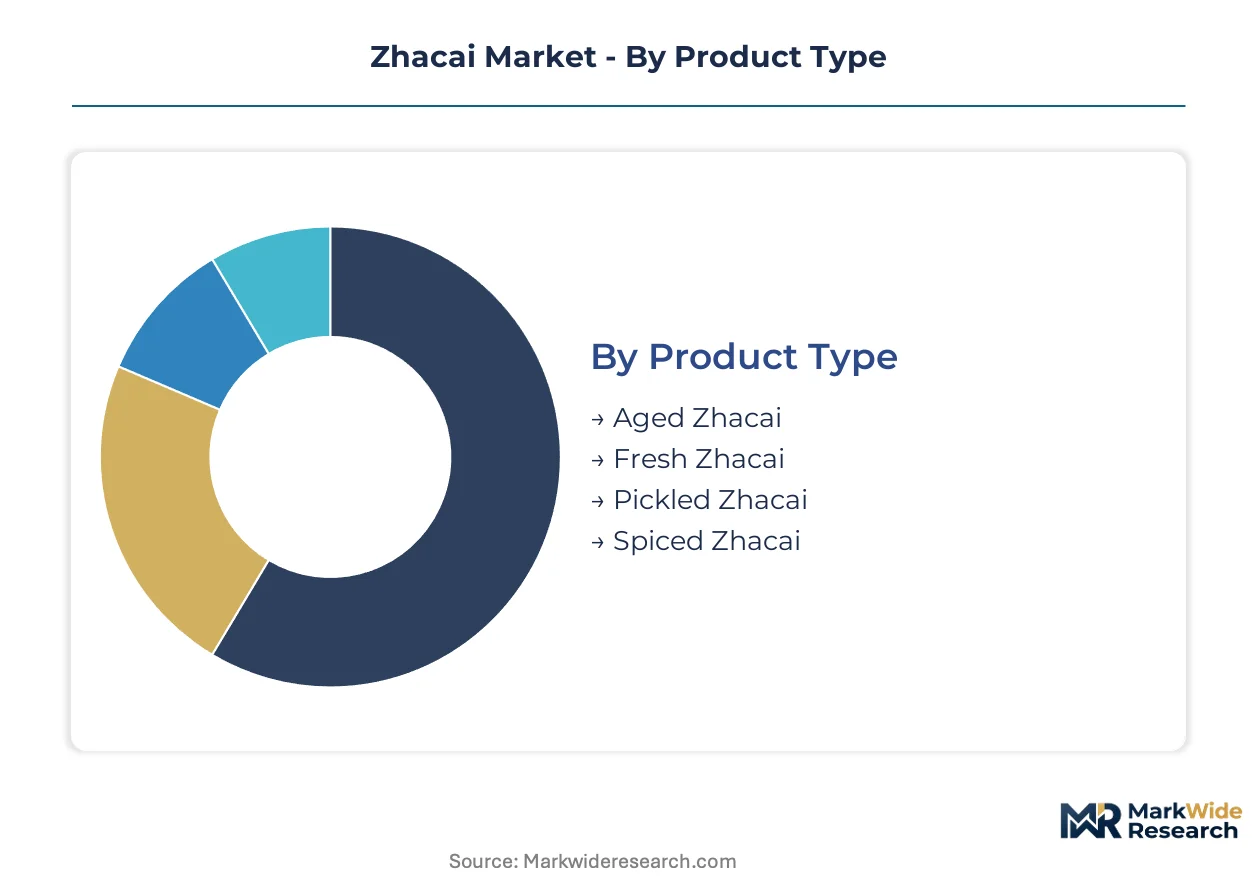
Zhacai segmentation reveals how regulatory compliance burdens concentrate across product tiers and packaging formats. SAMR's GB 2714 enforcement creates divergent certification requirements that reshape competitive boundaries between heritage-aged products and industrial-scale alternatives.
Product Type:
Certification intensity escalates with curing duration, as SAMR mandates stricter additive documentation and traceability protocols for extended-fermentation products entering modern retail channels.
- Aged Zhacai:Traditional lacto-fermentation in ceramic vessels spanning 6-12 months yields concentrated umami profiles and premium positioning. Heritage branding from Sichuan and Chongqing workshops commands deep margin pools in Shanghai and Jiangsu urban retail, though batch-to-batch variance challenges HACCP standardization.
- Fresh Zhacai:Short-ferment variants with 2-4 week curing cycles target refrigerated retail sections in tier-one cities. Reduced sodium formulations attract health-conscious households, though compressed shelf life constrains distribution radius without cold-chain infrastructure.
- Pickled Zhacai:Industrial brining with standardized salt concentrations supplies food service distributors and export channels.
- Spiced Zhacai:Chili oil and Sichuan peppercorn infusions serve regional taste preferences in Chongqing and Chengdu metropolitan areas.
Aged Zhacai sits at the top of the volume ranking, with Fresh Zhacai climbing the fastest.
Packaging Type:
Packaging selection directly determines shelf-life extension capabilities and the distribution channels accessible to each processor tier.
- Vacuum-Sealed:Multi-layer barrier films with nitrogen flush eliminate oxygen exposure, enabling 12-18 month shelf stability without chemical preservatives. Automated sealing lines with HACCP certification unlock supermarket placement in Yangtze River Delta retail chains.
- Bottled:Glass containers with tamper-evident closures signal premium positioning for heritage-branded aged variants. Higher unit economics support direct-to-consumer e-commerce margins, though breakage rates elevate logistics costs versus flexible formats.
- Bagged:Flexible pouches with high-barrier laminates serve food service institutional buyers demanding portion control and storage efficiency.
- Jarred:Wide-mouth glass formats dominate wet-market bulk repositioning into retail-ready formats for rural and small-city distribution.
Vacuum-Sealed leads absolute volume throughput, with Bottled expanding most quickly in premium urban channels.
Distribution Channel:
Channel selection determines compliance documentation depth, with supermarket and export pathways demanding batch-level traceability that village workshops cannot sustain.
- Online Marketplaces:E-commerce platforms bypass traditional wholesaler markups, enabling heritage processors to reach direct-to-consumer households in tier-one and tier-two cities. SAMR-mandated origin labeling and additive declarations are digitized for platform compliance.
- Retail Stores:Chain supermarket procurement consolidates around HACCP-certified facilities with automated inventory replenishment systems. GB 2714 compliance documentation excludes non-standardized village producers from modern retail access.
- Wholesalers:Traditional independent distributors retain restaurant procurement dominance in lower-tier cities lacking cold-chain penetration.
- Food Service:National distributors with ERP-integrated platforms guarantee lot consistency to chain restaurant kitchens across Yangtze River Delta clusters.
Retail Stores maintain volume leadership, with Online Marketplaces gaining share fastest in premium heritage segments.
End User:
End-user segmentation tracks how procurement authority concentrates across institutional buyers versus fragmented household decision-making.
- Restaurants:Chain kitchen procurement standardizes around food service distributors with just-in-time delivery guarantees. Automated inventory systems favor vacuum-sealed formats with consistent texture specifications across batch volumes.
- Households:Urban time-constrained consumers shift from wet-market bulk purchases to shelf-stable retail formats with standardized labeling and origin transparency.
- Food Manufacturers:Processors of instant noodles and ready meals source zhacai as soup base ingredients, demanding consistent brine chemistry for formulation stability.
- Exporters:BIS certification requirements for Indian channels constrain volume, favoring processors with dual compliance documentation and dedicated export product lines.
Households represent the largest consumption base, with Exporters expanding most quickly for processors achieving Indian regulatory clearance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master fermenters with traditional lacto-fermentation expertise concentrate in Sichuan and Chongqing municipalities, anchoring supply-side capability for aged zhacai production. Their knowledge transfer to automated facilities determines quality consistency across processing clusters.
China
Urban households in Shanghai and Jiangsu province drive packaged zhacai adoption as time-constrained consumers abandon wet-market bulk purchases. SAMR enforces GB 2714 national food safety standards that decouple artisanal village workshops from modern retail channels. The Yangtze River Delta processing cluster deepens vertical alignment between fermentation facilities and food service distributors with ERP-integrated logistics platforms.
India
Condiment demand among urban middle-class households creates import channel opportunities for shelf-stable pickled vegetable products. BIS certification requirements constrain current zhacai export volumes and force dual compliance documentation maintenance. Mumbai and Delhi distribution hubs see consolidation around processors achieving Indian regulatory clearance for heritage-branded aged variants.
Japan
Tsukemono-adjacent palates in Tokyo and Osaka metropolitan areas sustain niche demand for premium lacto-fermented mustard tuber products. METI monitors food additive declarations under Food Sanitation Act enforcement timelines. Kansai region import distributors specialize in vacuum-sealed formats targeting izakaya restaurant procurement and direct-to-consumer e-commerce channels.
South Korea
Jeotgal and jangajji fermentation traditions create cultural receptivity for zhacai as protein accompaniment and soup base ingredient. MFDS enforces Hazard Analysis Critical Control Point certification for imported pickled vegetable products. Seoul Capital Area retail chains consolidate procurement around HACCP-certified suppliers with batch-level traceability documentation linking harvest zones to finished product codes.
United States
Asian-American household concentration in California and New York metro areas sustains specialty grocery demand for authentic condiment products. FDA enforces Food Safety Modernization Act preventive controls for fermented vegetable imports. Los Angeles and San Francisco Bay Area distributors develop direct-to-restaurant channels bypassing traditional wholesaler markups for heritage-branded aged zhacai.
Zhacai Market Competitive Landscape
The competitive structure tilts toward vertically integrated processors with captive agricultural supply and HACCP-certified fermentation capacity. Capitalized operators with centralized ceramic vessel standardization and automated pressing equipment consolidate supermarket placement as GB 2714 compliance costs exclude village workshops. Three archetypes dominate: heritage-brand aged specialists, volume-scale industrial briners, and contract manufacturing platforms. Competitive moves concentrate on facility automation upgrades and food service distributor vertical alignment.
Within the heritage-brand tier, Chongqing Fuling Zhacai Group and Yu Quanzhacai occupy positions exemplifying premium positioning through controlled fermentation protocols and Three Gorges mustard green supply control. Fansaoguang Food sits within the volume-scale archetype, representing automated brining line deployment for national food service distribution. These three entities anchor the competitive spectrum from artisanal heritage to industrial scale.
| Leading Market Players |
|---|
| Chongqing Fuling Zhacai Group |
| Yu Quanzhacai |
| Fansaoguang Food |
| Jixiangju Food |
| Huitong Food |
| Ningbo Tongxianqiao |
| Lameizi |
| Weijute Food |
| Sichuan Chuannan Brewing Limited Company |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply access and premium-tier pricing power, as carbon-intensive ceramic vessel fermentation and brine wastewater treatment costs separate HACCP-certified facilities from excluded village workshops. SAMR enforcement of GB 2714 additive documentation creates tiered market access where compliance investment directly determines pricing tier eligibility.
Pricing Analysis
Packaged versus bulk format splits dominate zhacai pricing architecture. Three-tier pricing structure across heritage-aged, standard vacuum-sealed, and economy pickled tiers separates processors by certification grade and curing duration. Pricing pressure stems from MEE-mandated tertiary wastewater treatment systems that add operational overhead for mid-scale producers. Food service distributors exhibit lowest price sensitivity due to just-in-time delivery requirements, while wet-market bulk buyers face highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Freight cost differentials between ceramic vessel heritage clusters in Chongqing and Yangtze River Delta consumption centers compress margins for non-integrated processors. Supply concentrates in China, with secondary processing nodes in South Korea and Japan for export-adjacent variants. Raw material dependencies center on Three Gorges mustard green cultivation, salt supply chains, and ceramic vessel fabrication. Single-source vulnerability runs through captive agricultural supply controlled by vertically integrated processors. Distribution runs through ERP-integrated food service platforms for institutional buyers and e-commerce direct-to-consumer channels for heritage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zhacai market functions as a stable compounder, with urban household packaged format adoption providing steady volume expansion resistant to cyclical downturns.
For Market Incumbents: Extend HACCP-certified capacity in Yangtze River Delta processing clusters to capture supermarket procurement consolidation. Deepen backward integration into Three Gorges mustard green supply through long-term grower contracts that lock out emerging competitors. Counter fresh pickle substitution threats with salt-reduction R&D that preserves shelf stability without additive preservatives. For New Entrants and Emerging Players: E-commerce marketplace routes offer lowest barrier entry for heritage-branded aged zhacai targeting tier-one urban households. White space concentrates in Indian import channel development where BIS certification requirements currently constrain supply. Food service distributor bypass through direct-to-restaurant platforms in California and New York metro areas provides viable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors with SAMR compliance infrastructure but lacking brand heritage positioning. Five-to-ten year viability favors facilities with automated pressing equipment and ceramic vessel standardization capable of serving both retail and export channels. Watch for salt-reduction formulation breakthroughs as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | Unlocks chain supermarket placement under SAMR GB 2714 enforcement timelines. |
| Three Gorges Supply Contracting | Secures captive mustard green access against raw material cost volatility. |
| Automated Brining Line Deployment | Enables consistent texture specifications for food service distributor procurement. |
| Salt-Reduction R&D Program | Addresses evolving dietary guidelines without compromising lacto-fermentation shelf stability. |
| E-Commerce Direct Channel Launch | Bypasses traditional wholesaler markups to reach urban household consumers directly. |
Research Methodology
Multiple input streams — fermentation facility site visits, procurement manager interviews, and customs trade records — were reconciled to construct supply-side and demand-side estimates. Primary interviews engaged zhacai processing plant managers, chain supermarket category buyers, food service distributor procurement leads, and SAMR regulatory compliance officers. Secondary validation drew from GB standard documentation, MEE wastewater discharge filings, Yangtze River Delta agricultural statistics, and e-commerce platform transaction data. Bottom-up volume modeling triangulated against top-down consumption surveys.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type by curing duration, packaging format by shelf-life extension capability, distribution channel by compliance documentation depth, and regional processing cluster by vertical integration intensity. CAGRs derived from historical volume trajectories adjusted for regulatory enforcement phase-ins and urban household format shift elasticities. Forecast inputs incorporated SAMR GB 2714 implementation timelines and dual carbon retrofit capex requirements.
Regulatory enforcement delays, raw material harvest variability, and carbon compliance cost inflation are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about SAMR inspection intensity and urban household packaged format adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Soft Tofu Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Moringa Products Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market