
 Global Microcellular Polyurethane Foam Market | 2026-2036
Global Microcellular Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microcellular Polyurethane Foam Market Foresight
The microcellular polyurethane foam market is consolidating around a sharp split between premium performance grades and commodity bulk supply. BASF SE leverages its integrated polyol and isocyanate chain to dominate high-specification automotive seating applications. Dow Inc. anchors North American supply through large-scale continuous slabstock operations that compete on throughput and logistics efficiency. Covestro AG differentiates via water-blown formulations that meet tightening volatile organic compound limits in European manufacturing.
Microcellular polyurethane foam denotes a closed-cell or open-cell polymer structure with cell diameters typically below 50 micrometers, manufactured through controlled reaction of polyols with isocyanates in the presence of physical or chemical blowing agents to achieve density reductions of 30-90% versus solid polyurethane while retaining mechanical integrity. The material serves primarily as a lightweighting and cushioning medium across transportation, construction, and consumer goods sectors. Flexible foam commands the largest volume share due to entrenched demand from furniture manufacturers and vehicle assemblers seeking seating and interior trim solutions. Supercritical CO2 technology represents the fastest-expanding process category as environmental regulations in Germany and Japan restrict conventional hydrofluorocarbon blowing agents. Rigid foam retains concentrated margin pools in thermal insulation for construction firms targeting passive house and near-zero-energy building standards across Northern Europe and coastal China.
The EPA regulates volatile organic compound emissions from foam manufacturing under Clean Air Act Title V permitting, while REACH restricts specific isocyanate and blowing agent chemistries in EU production facilities. China's MEE enforces GB standards on formaldehyde release and volatile organic content in interior applications, directly shaping formulation choices for suppliers serving electronic device makers and sports equipment producers. Stakeholders must monitor evolving chemical restriction schedules and blowing agent phase-down timelines to secure formulation approvals before supply chain disruptions materialize.
Market Dynamics
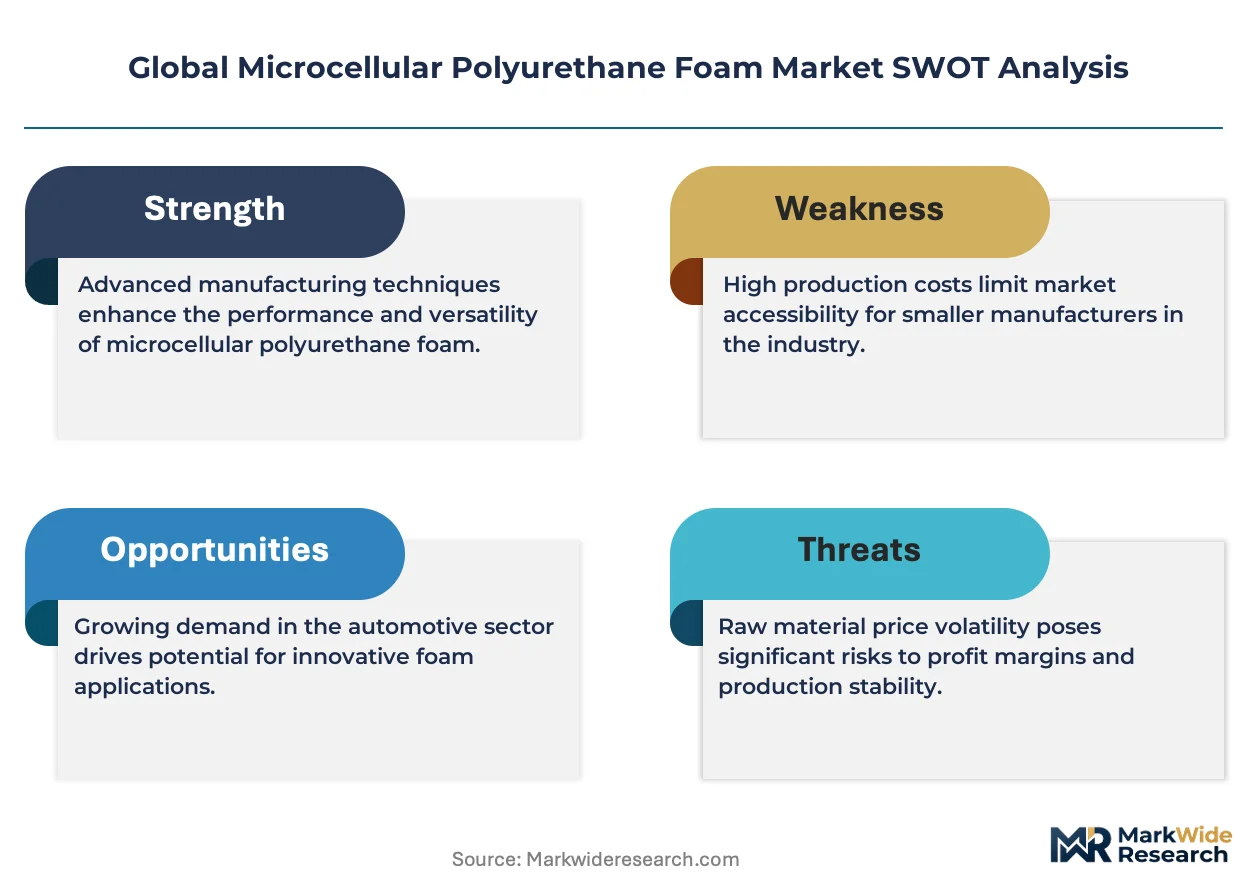
The transition from hydrofluorocarbon to supercritical CO2 blowing systems is compressing capital recovery timelines and forcing mid-scale producers into technology partnerships or exit decisions. This process shift, combined with REACH chemical restrictions and China's dual carbon goals, is redrawing competitive boundaries across automotive seating and construction insulation supply chains.
Growth Catalysts
- EU Green Deal vehicle lightweighting mandates:Automotive OEMs in Germany and France must reduce fleet emissions, accelerating foam substitution for heavier rubber and metal interior components.
- Supercritical CO2 process maturation:Equipment suppliers in Japan and Germany have standardized reactor designs, cutting process validation time for new entrants by half.
- Near-zero-energy building codes:Northern European construction markets now require thermal performance levels that rigid microcellular foam meets cost-effectively versus mineral wool alternatives.
Market Restraints
- Isocyanate price volatility:MDI and TDI feedstock costs fluctuate with crude oil and natural gas benchmarks, squeezing margin predictability for non-integrated foam converters.
- BASF-Covestro-Dow supply concentration:Three producers control over 60% of high-specification automotive foam supply, creating single-source risk for Tier 1 seating suppliers.
- Recyclability limitations:Cross-linked polyurethane structures resist mechanical recycling, exposing producers to extended producer responsibility fees under EU Circular Economy Action Plan.
Strategic Opportunities
- India automotive seating localization:PLI scheme incentives for electric vehicle component manufacturing are drawing foam molding investments to Chennai and Pune industrial corridors.
- Water-blown formulation premium:Covestro's commercialized aqueous blowing systems command price premiums in European medical device and food-contact applications where VOC limits are strictest.
- 3D-printed midsole integration:Athletic footwear brands in Vietnam and Indonesia are specifying microcellular foam pellets for fused-filament fabrication, bypassing traditional slabstock-mold supply chains.
Industry Challenges
- Process engineering talent scarcity:Supercritical CO2 reactor operation requires combined polymer chemistry and high-pressure systems expertise that vocational programs in China and Mexico have not scaled.
- REACH pre-registration timelines:New blowing agent chemistries face 18-24 month ECHA evaluation windows, delaying formulation launches for construction insulation seasons.
- Legacy slabstock asset stranding:Continuous foam lines optimized for HFC blowing agents require $2-4 million retrofit investments with uncertain residual value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microcellular Polyurethane Foam Market |
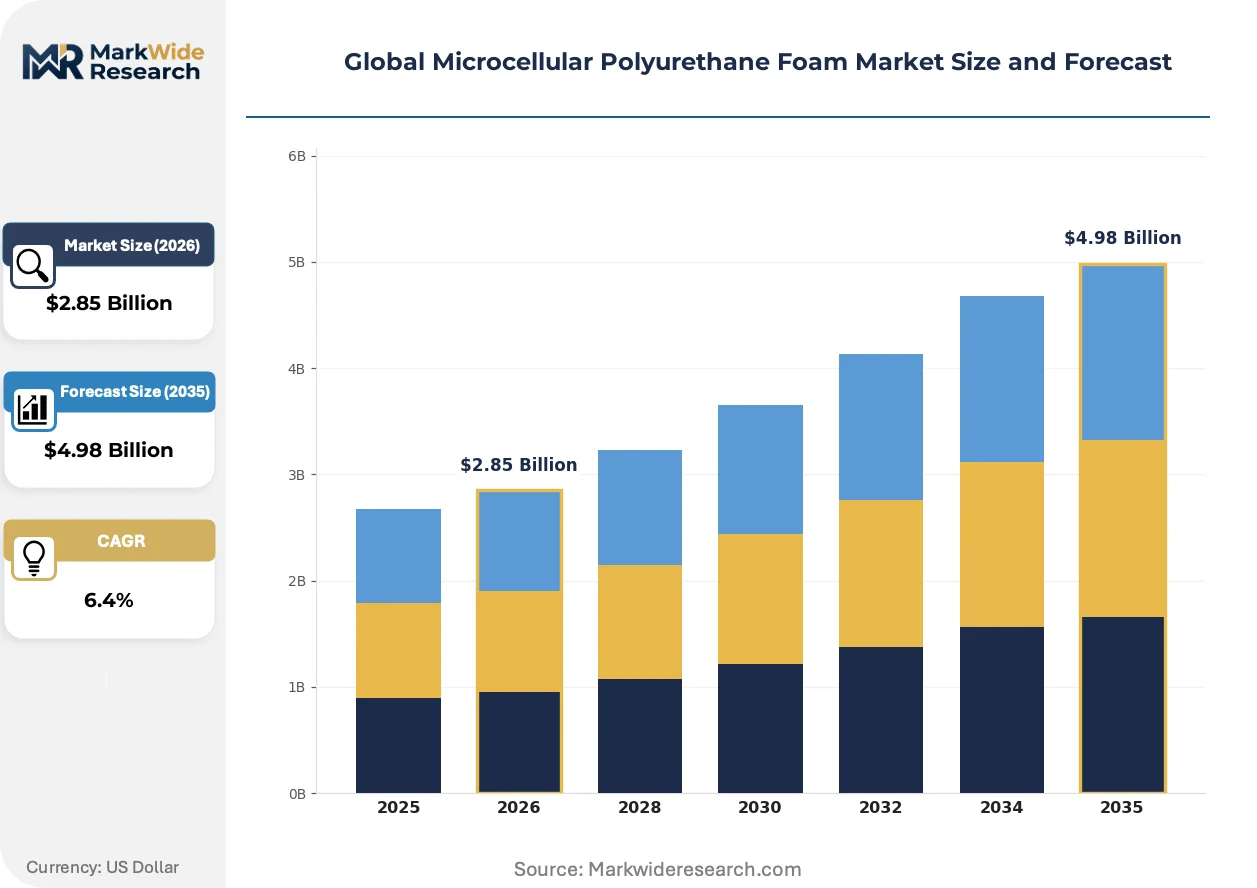
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Integral Skin Foam, Spray Foam, Reticulated Foam Technology: Physical Blowing Agents, Chemical Blowing Agents, Supercritical CO2, Water Blowing Application: Furniture & Bedding, Automotive Interiors, Thermal Insulation, Packaging Solutions, Footwear Components End User Industry: Furniture Manufacturers, Vehicle Assemblers, Construction Firms, Electronic Device Makers, Sports Equipment Producers |
| Companies Covered | BASF SE, Dow Inc., Huntsman Corporation, Covestro AG, Saint-Gobain, Evonik Industries, Rogers Corporation, INOAC Corporation, Recticel SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microcellular Polyurethane Foam Market Shifts & Advancements
Formulation science and process control advances are enabling density-performance combinations previously unattainable, while regulatory chemistry restrictions are accelerating equipment replacement cycles beyond normal depreciation schedules.
Supercritical CO2 physical foaming is electrifying process economics for thin-wall automotive interior panels. Tier 1 suppliers in Germany and the United States are qualifying CO2-blown systems for A-surface door trim applications where surface aesthetics previously required heavier solid polyurethane. The technology is electrifying competition between in-house captive molding operations and merchant foam converters, as OEMs reconsider vertical integration to protect process intellectual property.
REACH Annex XIV authorization requirements for specific isocyanate catalysts are forcing reformulation investments across European production networks. Manufacturers serving medical device and infant product markets face the tightest substitution deadlines, with some shifting catalyst systems to bismuth or zinc alternatives that extend cure times. Construction foam producers in Poland and the Czech Republic are absorbing higher raw material costs rather than passing through price increases to price-sensitive insulation distributors.
Direct-to-OEM specification engineering is displacing distributor-mediated technical sales in high-performance segments. Seating suppliers at BMW and Mercedes-Benz now require foam producers to co-locate application engineers at vehicle development centers, bypassing traditional chemical distribution channels. This pattern is most visible in southern Germany, where development cycle compression for electric vehicle platforms has eliminated the 12-18 month sampling windows that distributor inventories previously accommodated.
Global Microcellular Polyurethane Foam Market Segmentation
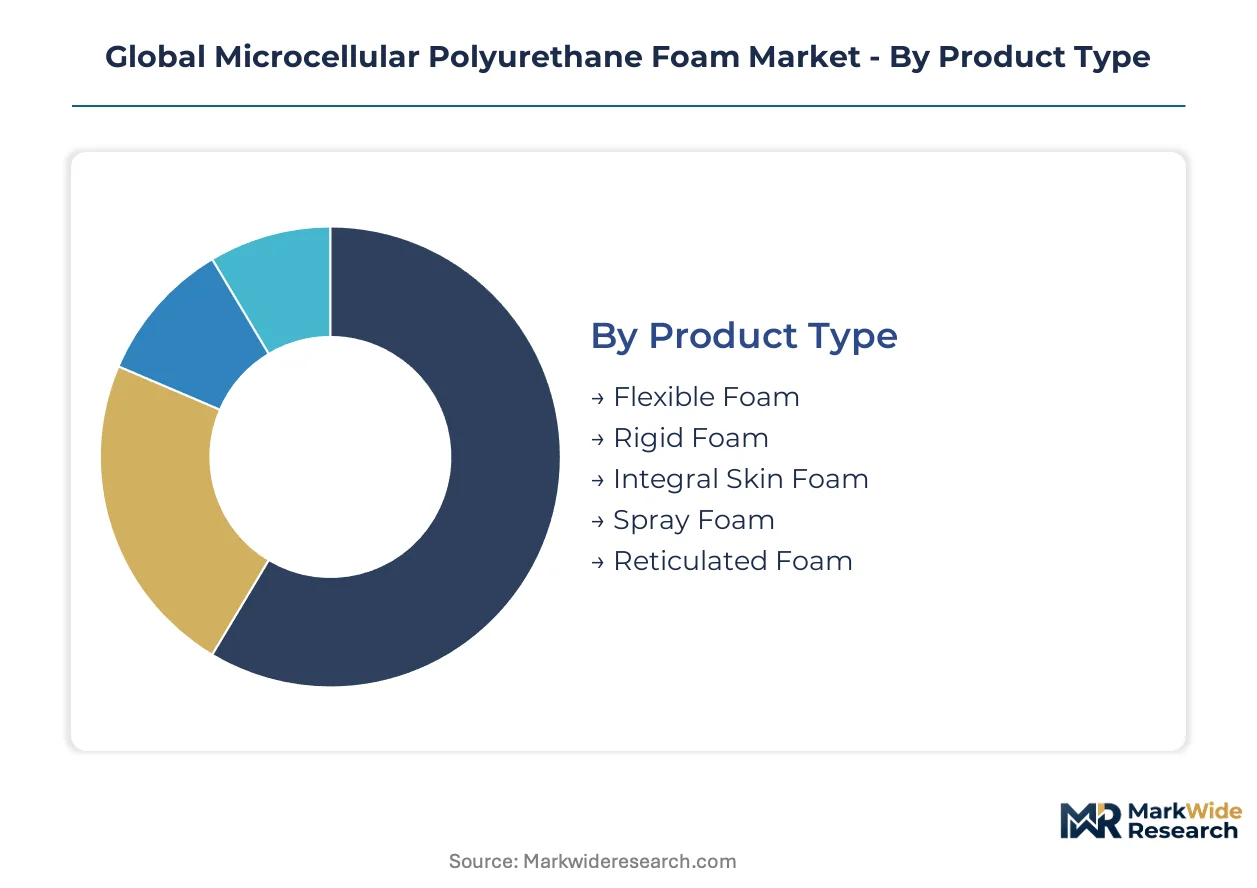
Segmentation in microcellular polyurethane foam reveals how formulation chemistry, process technology, and end-use performance requirements split demand into distinct procurement channels. Buyers prioritize density targets, blowing agent compliance, and surface finish specifications differently across automotive seating, construction insulation, and consumer goods applications.
Product Type:
Cost tier separates commodity converters from specification-driven compounders serving medical and automotive OEMs.
- Flexible Foam:Open-cell structures with densities of 20-80 kg/m³ dominate seating and cushioning applications. Furniture manufacturers in Vietnam and Poland absorb the highest volumes, though automotive seating specifications from BMW and Mercedes-Benz command price premiums for vibration-dampening grades.
- Rigid Foam:Closed-cell configurations achieve thermal conductivities below 20 mW/m·K, meeting passive house standards in Germany and coastal China. Construction firms in Northern Europe specify these grades for wall and roof assemblies where mineral wool cannot achieve equivalent R-values per inch.
- Integral Skin Foam:Self-skinning surfaces eliminate secondary finishing steps for armrests and steering wheels.
- Spray Foam:On-site application systems serve retrofit insulation contractors in the United States and Canada.
- Reticulated Foam:Open-pore structures filter air and fluids in medical devices and industrial equipment.
Volume sits with Flexible Foam; growth tilts toward Rigid Foam.
Technology:
Environmental compliance timelines now determine equipment investment cycles more than production efficiency metrics.
- Supercritical CO2:Physical foaming at pressures above 7.4 MPa eliminates hydrofluorocarbon residuals, qualifying automotive interior panels for EU F-Gas Regulation compliance. German and Japanese equipment suppliers have standardized reactor designs, cutting validation timelines for Tier 1 seating producers.
- Water Blowing:Aqueous systems react isocyanates to generate CO₂ in-situ, achieving densities competitive with HFC-blown foams. Covestro's commercialized formulations command premiums in European medical device applications where REACH VOC limits are strictest.
- Physical Blowing Agents:Hydrocarbon and HFC systems retain installed base in legacy slabstock operations.
- Chemical Blowing Agents:Azodicarbonamide and similar compounds decompose at processing temperatures to release nitrogen gas.
Installed capacity concentrates with Physical Blowing Agents; regulatory pressure is accelerating fastest toward Supercritical CO2.
Application:
Automotive procurement cycles now compress development timelines that previously accommodated distributor inventory buffers.
- Automotive Interiors:Door panels, headliners, and seating components require A-surface aesthetics combined with 30-50% weight reduction versus solid polyurethane. OEMs in Germany and the United States now co-locate foam application engineers at vehicle development centers, bypassing traditional chemical distribution channels.
- Thermal Insulation:Near-zero-energy building codes in Germany, France, and coastal China specify rigid microcellular foam for wall assemblies where space constraints favor thin high-performance layers over mineral wool.
- Furniture & Bedding:Mattress and upholstery producers in Vietnam and Turkey specify commodity flexible foam grades.
- Packaging Solutions:Electronics and appliance manufacturers use molded foam inserts for impact protection.
- Footwear Components:Athletic brands in Vietnam and Indonesia specify microcellular pellets for 3D-printed midsole fabrication.
Revenue concentrates with Automotive Interiors; application engineering intensity climbs fastest in Thermal Insulation.
End User Industry:
Vertical integration incentives vary by sector concentration and intellectual property sensitivity.
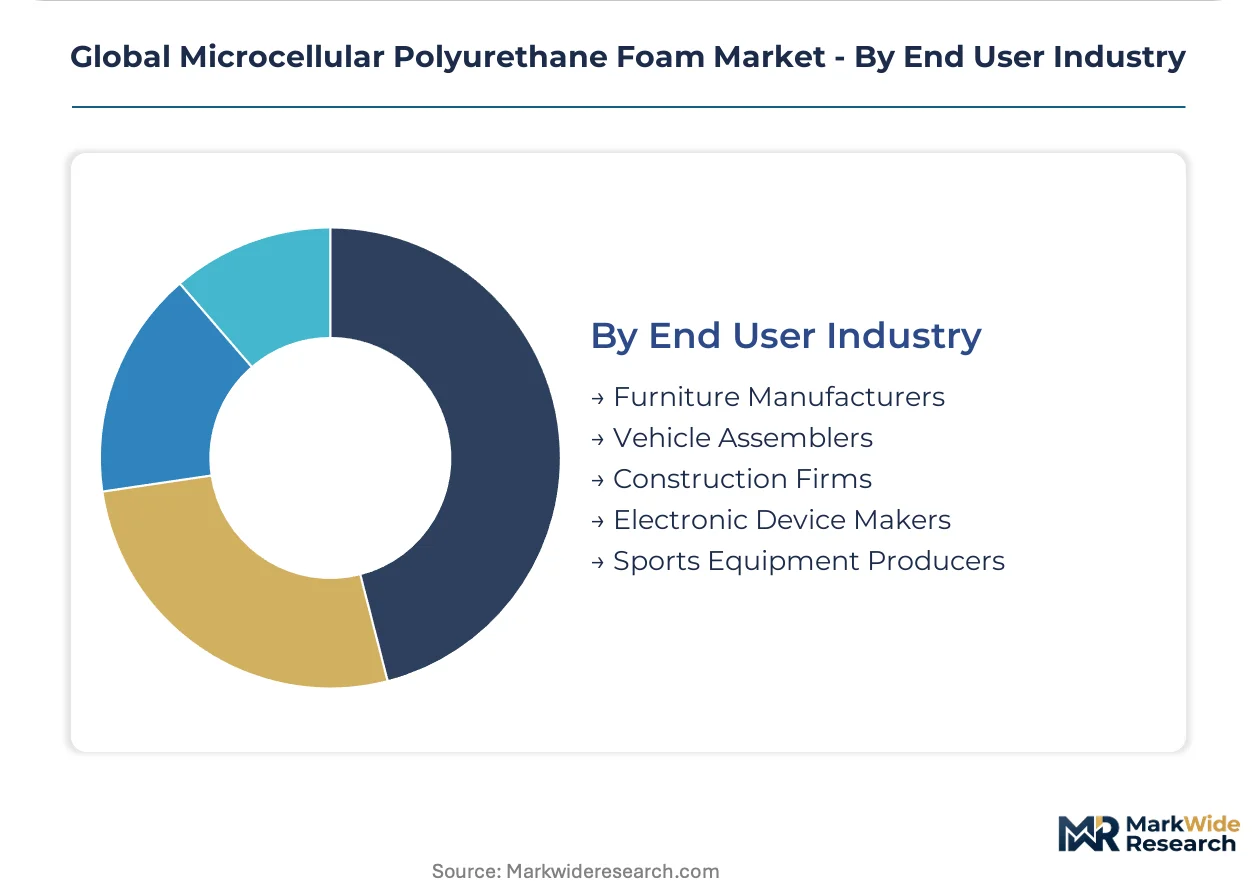
- Vehicle Assemblers:BMW, Mercedes-Benz, and Ford specify foam grades at the platform development stage, requiring suppliers to validate formulations 24-36 months before production launch. This procurement pattern favors integrated polyol-isocyanate producers with captive molding capabilities.
- Construction Firms:Price-sensitive insulation distributors in Poland and the Czech Republic absorb raw material cost increases rather than passing through to building contractors, compressing margins for foam converters serving this channel.
- Furniture Manufacturers:Commodity procurement through distributors dominates in Vietnam and Turkey.
- Electronic Device Makers:China's MEE enforces GB standards on formaldehyde release and VOC content, directly shaping formulation choices for laptop and smartphone packaging.
- Sports Equipment Producers:Running shoe brands specify pellet grades for fused-filament fabrication, bypassing traditional slabstock-mold supply chains.
Specification intensity peaks with Vehicle Assemblers; volume scale concentrates with Furniture Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive foam demand through Mercedes-Benz and Porsche development centers, while Shanghai's Yangtze River Delta cluster concentrates EV battery enclosure manufacturing. Germany, China, the United States, Japan, and India concentrate distinct supply chain configurations shaped by local regulations and OEM procurement patterns.
Germany
Automotive seating specifications from BMW and Mercedes-Benz drive demand for vibration-dampening grades. REACH Annex XIV authorization requirements for isocyanate catalysts force reformulation investments across Bavarian production networks. The Stuttgart-Munich corridor hosts co-located application engineers from major foam producers at vehicle development centers.
China
Electric vehicle manufacturing in Shenzhen and Shanghai consumes rigid foam for battery thermal management enclosures. MEE enforcement of GB standards on formaldehyde release shapes formulation choices for electronics packaging suppliers. The Yangtze River Delta industrial corridor concentrates slabstock operations serving domestic furniture and automotive markets.
United States
Detroit-based OEMs specify lightweight interior panels to meet NHTSA fuel economy standards. EPA Clean Air Act Title V permitting governs VOC emissions from foam manufacturing in Ohio and Michigan production zones. The Southeast automotive corridor from Tennessee to South Carolina attracts molding investments to serve BMW and Volkswagen assembly plants.
Japan
METI regulations restricting hydrofluorocarbon blowing agents accelerate supercritical CO2 equipment adoption. Nagoya-based Toyota and Honda procurement teams qualify foam grades 30 months before platform launches. The Chubu region hosts specialized reactor manufacturers that supply foaming equipment to domestic and export markets.
India
PLI scheme incentives for electric vehicle component manufacturing draw foam molding investments to Chennai and Pune. BIS certification requirements for automotive interior materials create entry barriers for unqualified imports. The Tamil Nadu industrial corridor concentrates seating supplier parks serving Hyundai and Kia export-oriented assembly operations.
Global Microcellular Polyurethane Foam Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and specification intensity. BASF SE, Covestro AG, and Dow Inc. control high-specification automotive supply through integrated polyol-isocyanate chains, while regional converters compete on throughput and logistics efficiency in furniture and construction segments. Two strategic archetypes dominate: integrated chemical producers with captive molding capabilities, and merchant foam converters serving price-sensitive distributors. Capacity expansion and technology licensing represent the dominant competitive moves as producers retrofit legacy slabstock lines for supercritical CO2 systems.
Among integrated chemical producers, BASF SE and Covestro AG exemplify the premium-tier archetype through backward control over raw material supply. Dow Inc. anchors North American merchant supply through large-scale continuous operations. These three producers collectively represent the concentration point for automotive OEM qualification programs, while Huntsman Corporation and Evonik Industries occupy positions in specialized formulation segments requiring distinct technical capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Huntsman Corporation |
| Covestro AG |
| Saint-Gobain |
| Evonik Industries |
| Rogers Corporation |
| INOAC Corporation |
| Recticel SA |
| Others |
Supply & Pricing Matrix
Tier 1 automotive seating suppliers concentrated in Germany and the United States command specification-driven pricing that separates vibration-dampening grades from commodity flexible foam. This buyer concentration enables value-based anchoring around thermal performance metrics and surface finish quality, with REACH compliance timelines adding certification premiums to European medical device grades.
Pricing Analysis
Automotive OEM qualification programs anchor pricing to NVH performance outcomes and 24-36 month validation cycles rather than raw material input costs. Price differentiation separates BMW-specified seating grades from furniture commodity tiers through density tolerances and blowing agent compliance certifications. Cost compression runs through rigid foam insulation distributors in Poland and the Czech Republic who absorb MDI feedstock volatility rather than pass through to construction contractors. Furniture manufacturers in Vietnam exhibit highest price sensitivity, while medical device compounders serving REACH Annex XIV deadlines show lowest sensitivity due to substitution timeline pressures.
Supply Chain Analysis
MDI and TDI feedstock supply rests on integrated polyol-isocyanate producers in Germany, the United States, and Japan. Raw material dependencies center on crude oil and natural gas benchmarks, specialty catalyst systems, and supercritical CO2 reactor equipment from Nagoya-based manufacturers. Single-source vulnerability concentrates in high-specification automotive foam where BASF-Covestro-Dow networks control over sixty percent of qualified supply. Distribution runs through merchant converters for furniture and construction segments, while direct-to-OEM technical sales displace distributor channels in automotive interiors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around supercritical CO2 process transitions that strand legacy HFC slabstock assets and force mid-scale producers toward exit or partnership. The technology shift favors integrated chemical producers with captive molding capabilities over merchant converters lacking reactor engineering expertise.
For Market Incumbents: Anchor automotive seating qualifications through co-located application engineers at Stuttgart and Detroit development centers, protecting specification control as OEMs compress 24-36 month validation windows. Pursue backward integration into specialty polyol formulations to offset MDI price volatility exposure. Prioritize water-blown formulation investments for European medical device segments facing REACH catalyst substitution deadlines. For New Entrants and Emerging Players: Enter via 3D-printed footwear pellet supply to Vietnamese and Indonesian athletic brands, bypassing established slabstock-mold infrastructure. Target India's PLI scheme corridors around Chennai and Pune for electric vehicle seating localization. Lead with supercritical CO2 process partnerships rather than greenfield reactor investments to compress qualification timelines. For Investors and Strategic Acquirers: The window for entry favors integrated mid-cap compounders with captive automotive qualifications and water-blown formulation portfolios. Long-term viability hinges on exposure to near-zero-energy building codes across Northern Europe and coastal China rather than commodity furniture supply. Watch supercritical CO2 equipment order backlogs from Japanese reactor manufacturers as inflection signal for process transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Retrofit Program | Qualifies automotive interior panels for EU F-Gas Regulation compliance in German Tier 1 supply. |
| Water-Blown Formulation Expansion | Captures REACH-driven substitution demand in European medical device and food-contact applications. |
| India PLI Corridor Investment | Positions seating supply within Chennai-Pune industrial zones serving Hyundai-Kia export platforms. |
| Direct-to-OEM Technical Sales | Bypasses distributor channels as BMW and Mercedes-Benz compress development cycle timelines. |
| Specialty Polyol Backward Integration | Insulates margin predictability from MDI-TDI feedstock volatility in non-integrated converter networks. |
Research Methodology
Document review covered customs and trade flow databases, SEC 10-K filings from integrated chemical producers, and ECHA REACH registration timelines, complemented by interviews with plant managers at German and U.S. slabstock operations, procurement leads at Tier 1 seating suppliers, and distribution channel partners serving Polish construction markets. Bottom-up triangulation across formulation-grade production volumes and top-down validation against end-use consumption patterns anchored market sizing.
Cross-referencing historical capacity expansion patterns against panel input from supercritical CO2 equipment suppliers established growth trajectory boundaries across the projection horizon. Segmentation modeling spanned product type tiers, blowing agent technology categories, application intensity levels, and regional production hub concentrations. CAGRs derived from equipment order backlogs, OEM platform launch schedules, and building code adoption timelines rather than extrapolated historical growth rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under isocyanate supply disruptions or accelerated REACH chemical restriction schedules. Forecasts reflect assumptions around supercritical CO2 process maturation timelines and PLI scheme incentive continuity. A small set of triggers—Japanese reactor equipment lead times, ECHA catalyst authorization decisions, and China MEE enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market