
 Global Linear Low Density Polyethylene Market | 2026-2036
Global Linear Low Density Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Low Density Polyethylene Market Intelligence
The EU Green Deal's circular economy action plan is realigning the cost-of-entry calculus for LLDPE producers, forcing investment in advanced recycling technologies and bio-based feedstocks. Dow Inc. leverages its global manufacturing scale to develop circular-ready resins. LyondellBasell Industries N.V. positions itself with a portfolio of recycled and renewable-based polymers. Borealis AG specializes in high-performance polyolefins for demanding packaging and automotive applications.
Linear Low Density Polyethylene is a polymer created through the copolymerization of ethylene with longer-chain olefins. Its structure, featuring short, uniform branches, imparts high tensile strength and puncture resistance compared to conventional LDPE. This material is primarily engineered for flexible film applications where durability and barrier properties are critical. Film grade products represent the largest product type, driven by extensive use in packaging films for the food & beverage industry.
Regulatory oversight from bodies like the US Environmental Protection Agency (EPA) and compliance with the EU's REACH regulation govern chemical safety and production emissions. In China, the Ministry of Ecology and Environment (MEE) implements policies aligned with dual carbon goals, influencing feedstock choices and recycled content mandates. Producer profitability will increasingly depend on navigating the volatile economics of virgin feedstocks versus the scaling costs of advanced chemical recycling infrastructure.
Market Dynamics
The imperative to align with a circular economy is the central force shaping the Linear Low Density Polyethylene market. Regulatory frameworks, particularly the EU Green Deal, are compelling producers to innovate beyond virgin feedstocks toward recyclable and bio-based alternatives.
Growth Catalysts
- Flexible Food Packaging:Expansion in the global food and beverage industry, especially for multi-layer films used in stand-up pouches and barrier packaging, directly stimulates demand for high-performance film-grade LLDPE.
- E-commerce Logistics:The rise of global e-commerce platforms requires durable and lightweight protective packaging, such as mailer bags and stretch wrap for pallet stabilization, which are primary applications for LLDPE films.
- Mono-Material Structures:Design-for-recycling initiatives are promoting the adoption of mono-material polyethylene packaging. This shift creates demand for advanced LLDPE grades that can replace other polymers in laminates, improving recyclability.
Market Restraints
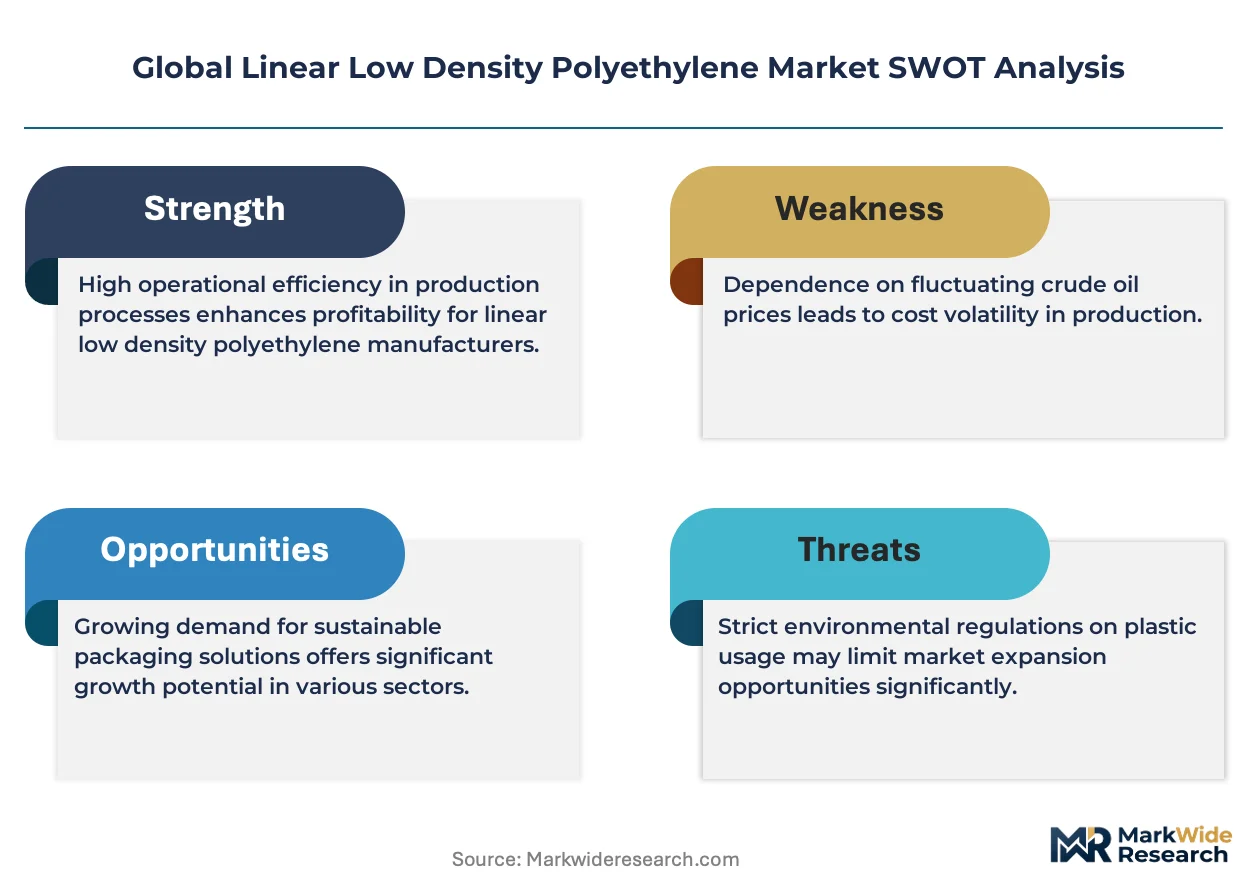
- Feedstock Price Volatility:LLDPE production costs are directly linked to the price of ethylene, a derivative of crude oil and natural gas. Price fluctuations in global energy markets create margin pressure and planning uncertainty for producers.
- Substitution by Other Polymers:In certain applications, particularly where high clarity or rigidity is required, LLDPE faces competition from materials like polypropylene (PP) and polyethylene terephthalate (PET), limiting its penetration.
- Regulatory Compliance Burden:Adhering to chemical safety and environmental regulations, such as the EU's REACH framework and emissions standards set by the US EPA, requires significant investment in compliance and reporting.
Strategic Opportunities
- Bio-Based Feedstocks:Developing LLDPE from renewable sources, such as bio-ethanol derived from sugarcane, presents a significant opportunity to reduce carbon footprints and appeal to sustainability-focused brand owners and consumers.
- Advanced Agricultural Films:There is an opportunity to engineer specialized films with tailored UV resistance and thermal properties for greenhouse and mulching applications in agricultural economies like India and Brazil.
- High-Purity Medical Packaging:Penetrating the market for sterile medical device packaging and pharmaceutical blister pack backing requires LLDPE grades with exceptional purity, puncture resistance, and seal integrity.
Industry Challenges
- Chemical Recycling Infrastructure:The capital-intensive nature of building advanced chemical recycling facilities, such as pyrolysis plants, at a scale sufficient to process post-consumer LLDPE waste remains a major operational hurdle.
- Recycled Content Standardization:A lack of globally harmonized standards for certifying and tracking post-consumer recycled (PCR) content creates complexity in supply chains and hinders consistent material specification across regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Low Density Polyethylene Market |
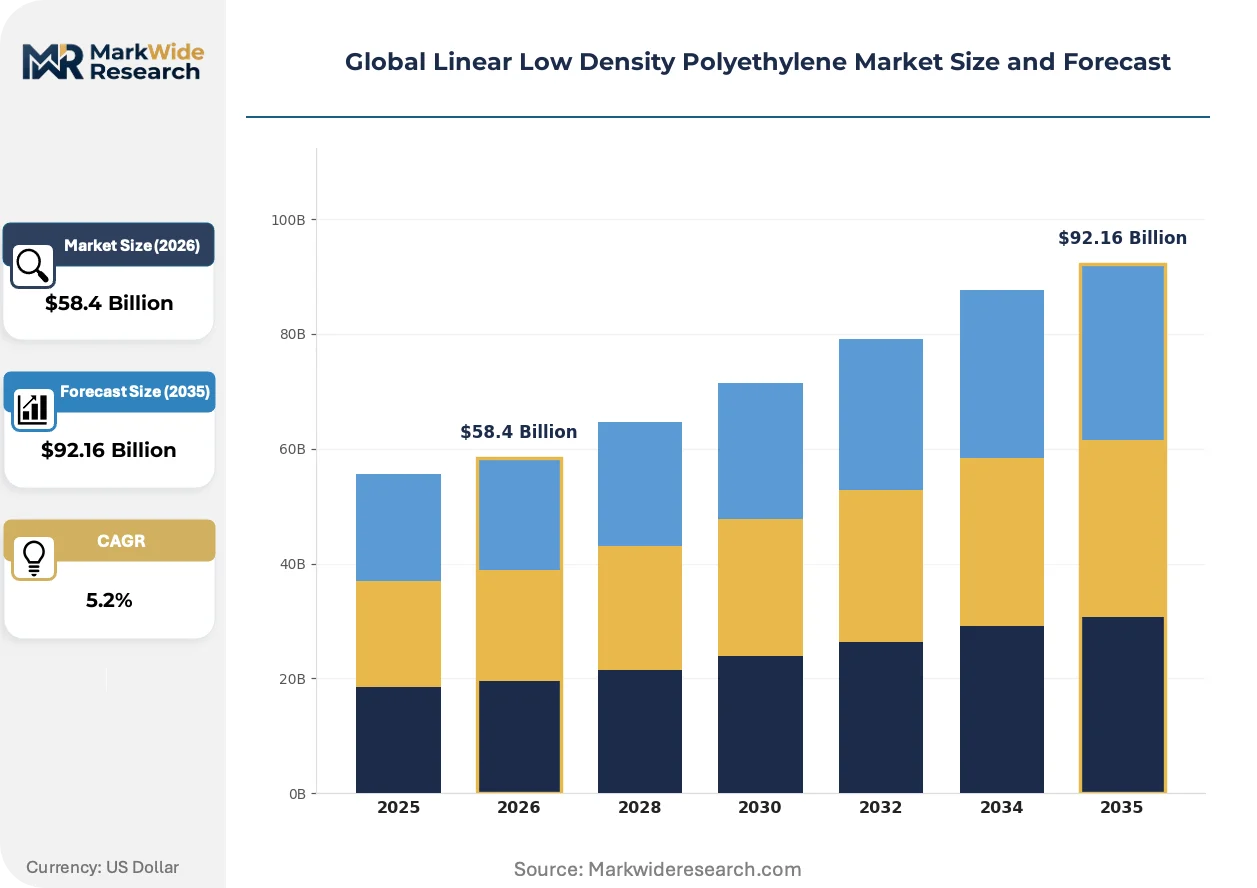
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Grade, Injection Molding Grade, Blow Molding Grade, Extrusion Coating Grade, Rotomolding Grade Application: Packaging Films, Consumer Goods, Agricultural Films, Automotive Components, Wire & Cable Insulation End User Industry: Food & Beverage, Personal Care, Construction Materials, Electrical & Electronics, Textile Manufacturing Packaging Type: Granules, Pellets, Sheets, Rolls, Bags |
| Companies Covered | China Petroleum & Chemical Corporation, Ineos Group Holdings S.A., LyondellBasell Industries N.V., Reliance Industries Limited, Borealis AG, Exxon Mobil Corporation, Saudi Basic Industries Corporation, Chevron Phillips Chemical Company LLC, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Low Density Polyethylene Market Strategic Shifts & Innovations
The material's evolution from a commodity polymer to a specialized solution engineered for performance and sustainability defines the current market landscape. This transition is driven by technological advancements in catalysis, stringent environmental policies, and changing procurement behaviors.
Metallocene catalyst technology enables the production of LLDPE with precisely controlled molecular structures, delivering superior toughness and clarity. Flexible packaging converters are adopting these grades to create thinner, stronger films, a process known as downgauging. This technology is consolidating the market around premium resins, displacing conventional grades in demanding applications where material efficiency is paramount.
China's "dual carbon" policy, enforced by the Ministry of Ecology and Environment (MEE), is a significant regulatory driver. The policy framework incentivizes the reduction of carbon intensity and promotes a circular economy, impacting feedstock choices and waste management. Consequently, LLDPE producers operating in China are accelerating the development of resins compatible with higher recycled content and investing in local recycling infrastructure.
A notable shift in purchasing behavior involves buyers emphasizing a product's total cost of ownership over its simple price-per-ton. End-users now evaluate LLDPE grades based on their ability to enable downgauging, which reduces overall material consumption, lowers packaging taxes, and cuts transportation costs. This value-based procurement is most visible in the European consumer packaged goods sector.
Global Linear Low Density Polyethylene Market Segmentation
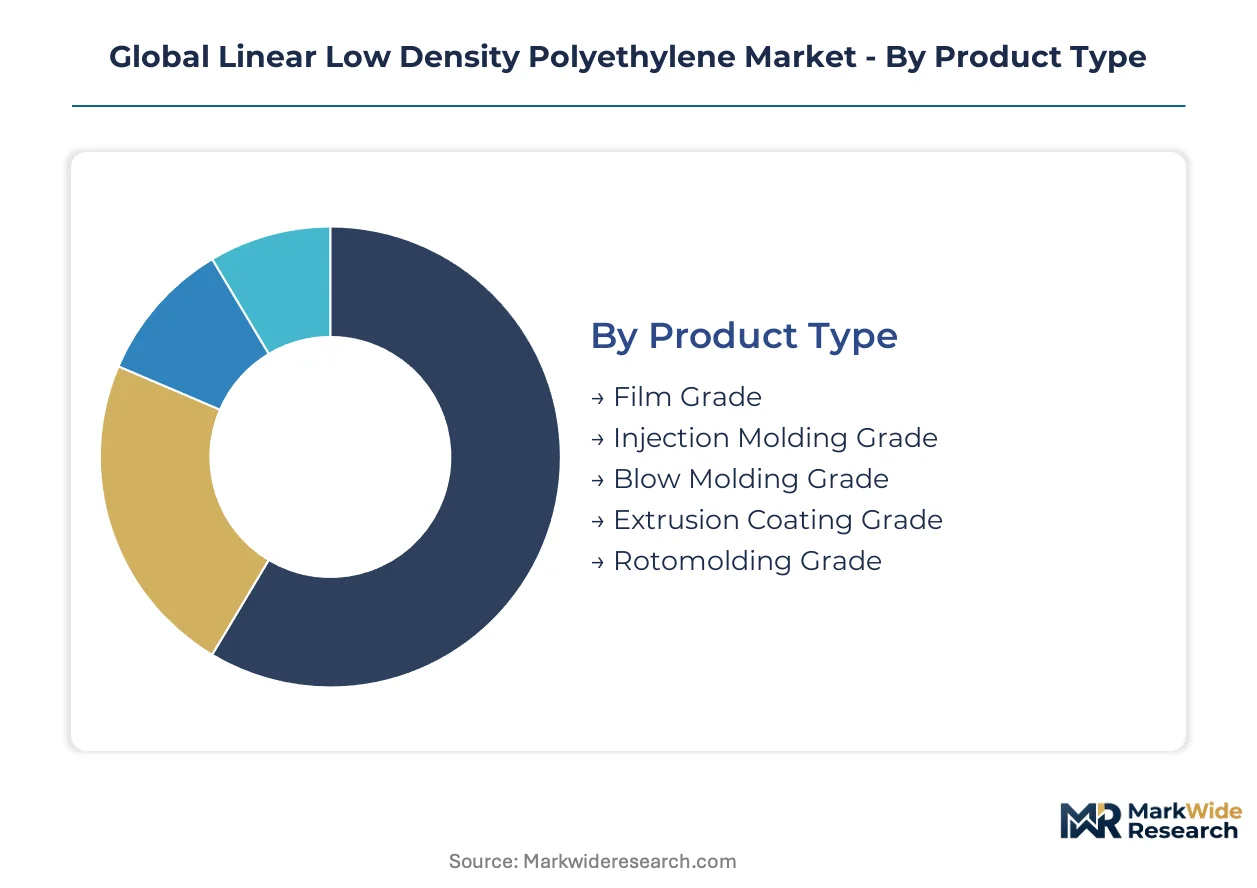
The Global Linear Low Density Polyethylene market exhibits diverse segmentation driven by end-use requirements, processing methods, and material forms. Understanding these segments provides clarity on demand drivers and technological shifts influencing LLDPE producers. Each segment reflects unique performance criteria and market dynamics, from specialized film applications to injection molded components.
Product Type:
What differentiates buyers in this category is the specific processing method and performance requirement for LLDPE.
- Film Grade:This LLDPE variant is optimized for producing thin, strong films, often featuring high tensile strength, puncture resistance, and excellent sealing properties. Demand concentrates in flexible packaging for the food and beverage sector, driven by the need for durable and efficient barrier solutions.
- Injection Molding Grade:Engineered for precision molding applications, this grade offers balanced flow characteristics, good rigidity, and impact strength, enabling complex part designs. Demand is growing in consumer goods and automotive components, where intricate shapes and mechanical integrity are essential.
- Blow Molding Grade:This LLDPE type is formulated for extrusion blow molding processes, providing good melt strength and resistance to environmental stress cracking. It is primarily used for containers and bottles in the personal care industry.
- Extrusion Coating Grade:Designed for coating substrates like paperboard or woven fabrics, this grade offers excellent adhesion, barrier properties, and heat sealability. It finds application in multi-layer packaging and protective coatings.
- Rotomolding Grade:Characterized by its finely ground powder form and good melt flow, this LLDPE is suitable for producing large, hollow parts with uniform wall thickness. Agricultural tanks and playground equipment utilize this material.
Volume sits with Film Grade; growth tilts toward Injection Molding Grade.
Application:
The end-use application dictates the required mechanical properties and barrier characteristics of LLDPE.
- Packaging Films:This segment encompasses a wide array of flexible films used for wrapping, bagging, and laminating products across various industries, prioritizing barrier properties and durability. Demand is robust in the food and beverage sector due to increased consumption of packaged goods and e-commerce logistics.
- Consumer Goods:LLDPE is utilized in a broad range of household items, toys, and sports equipment, valued for its toughness, flexibility, and chemical resistance. Global urbanization and rising disposable incomes drive demand for these versatile products.
- Agricultural Films:Specialized LLDPE films are used for greenhouse covers, mulching, and silage, offering UV stability, thermal insulation, and moisture retention. India and Brazil represent significant demand centers for these films.
- Automotive Components:LLDPE finds application in interior and exterior automotive parts, including bumpers, dashboards, and fuel tanks, due to its impact resistance and lightweight properties. Vehicle electrification initiatives are influencing material specifications.
- Wire & Cable Insulation:This application utilizes LLDPE for its excellent electrical insulation properties, abrasion resistance, and flexibility in protective sheathing. Telecommunications infrastructure expansion drives consistent demand.
Packaging Films command the largest share, while Consumer Goods applications are expanding most quickly.
End User Industry:
The industry served heavily influences material specification and regulatory compliance for LLDPE products.
- Food & Beverage:This industry relies on LLDPE for flexible packaging films, pouches, and containers, ensuring product freshness, extended shelf life, and safe transport. Strict regulatory standards from bodies like the US FDA govern material contact.
- Personal Care:LLDPE is used in packaging for cosmetics, toiletries, and hygiene products, valued for its aesthetic appeal, chemical resistance, and squeezability. The shift towards mono-material packaging structures impacts material selection.
- Construction Materials:LLDPE is incorporated into moisture barriers, protective sheeting, and geomembranes, providing durability and weather resistance for building and infrastructure projects. Urban development projects in China drive demand.
- Electrical & Electronics:This sector uses LLDPE for wire insulation, cable jacketing, and protective enclosures, benefiting from its dielectric properties and mechanical strength. Compliance with EU RoHS directives is critical for producers.
- Textile Manufacturing:LLDPE can be used in specialty non-woven fabrics and protective coverings, offering strength and moisture barrier properties. Industrial packaging applications utilize these materials.
Food & Beverage represents the primary demand, with Personal Care gaining share fastest.
Packaging Type:
The physical form of LLDPE delivery influences logistics and subsequent manufacturing processes for converters.
- Granules:LLDPE granules are small, uniform pellets that are easy to handle and feed into various processing equipment, representing a bulk form for transport and storage. This form is widely used by large-scale converters.
- Pellets:Similar to granules but often referring to slightly larger, more consistent shapes, LLDPE pellets are the standard form for most polymer processing operations, including extrusion and injection molding. They offer excellent flow characteristics for efficient manufacturing.
- Sheets:LLDPE sheets are pre-formed flat materials used in thermoforming or as protective layers, providing a ready-to-use format for certain applications. They are common in construction and industrial lining.
- Rolls:LLDPE films are typically supplied in large rolls to flexible packaging converters, enabling high-speed processing and minimal waste in converting operations. This format dominates the packaging film segment.
- Bags:LLDPE can be supplied in smaller bags, primarily for specialty grades, samples, or lower volume applications, ensuring ease of handling and reduced material waste for smaller users. This packaging type serves niche markets.
Granules and Pellets collectively account for the majority of LLDPE supply, with demand for Rolls showing a steep expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive industrial parks, particularly those in the Yangtze River Delta, concentrate significant LLDPE production and consumption. These zones benefit from preferential policies that attract investment in packaging and consumer goods manufacturing. This fosters a localized ecosystem for polymer processing and demand.
China
China's extensive consumer goods production and booming e-commerce logistics drive substantial demand for LLDPE packaging films. The Ministry of Ecology and Environment's (MEE) dual carbon policy influences feedstock choices and mandates recycled content. Production hubs in the Yangtze River Delta are rapidly developing advanced recycling infrastructure to meet these policy goals.
United States
Demand for LLDPE in the United States stems from robust food and beverage packaging and growing automotive component manufacturing. The US Environmental Protection Agency (EPA) governs chemical safety and production emissions for polymer facilities. The Gulf Coast petrochemical complex continues to expand LLDPE capacity, leveraging abundant natural gas feedstocks for polymer production.
Germany
Germany's advanced manufacturing sector, particularly in high-performance packaging and automotive applications, requires specialized LLDPE grades. The EU Green Deal and REACH regulation compel producers towards sustainable and circular polymer solutions. The Rhine-Ruhr industrial region is a hub for chemical companies innovating in bio-based feedstocks and advanced recycling technologies.
India
India's agricultural sector generates significant demand for specialized LLDPE films for mulching and greenhouse covers. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for plastic products across the nation. Gujarat's chemical industrial zones are expanding LLDPE production to serve both domestic packaging and agricultural film markets.
Saudi Arabia
Saudi Arabia's LLDPE production primarily serves global export markets, driven by its integrated petrochemical complexes. The Saudi Standards, Metrology and Quality Organization (SASO) ensures product quality for both domestic use and international trade. Jubail Industrial City is a key global LLDPE production hub, benefiting from low-cost feedstock and state-of-the-art facilities.
Global Linear Low Density Polyethylene Market Key Industry Players
Western chemical conglomerates anchor one tier of the LLDPE market; Asia-Pacific producers hold significant regional influence. The market structure exhibits a tiered consolidation, with large, integrated petrochemical companies competing alongside specialized resin manufacturers. Strategic archetypes include global commodity producers, sustainability-focused innovators, and regional players with strong local distribution. Competitive moves often involve substantial investment in advanced recycling infrastructure and strategic partnerships for bio-based feedstock development.
On the global scale-driven end, Dow Inc., a US-based chemical giant, exemplifies a major integrated producer leveraging extensive manufacturing capabilities. LyondellBasell Industries N.V., a Netherlands-based firm, occupies a position focused on a diversified portfolio of recycled and renewable-based polymers. China Petroleum & Chemical Corporation, a state-owned enterprise, anchors the substantial domestic LLDPE market within China, benefiting from integrated upstream operations and a vast internal demand base.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Ineos Group Holdings S.A. |
| LyondellBasell Industries N.V. |
| Reliance Industries Limited |
| Borealis AG |
| Exxon Mobil Corporation |
| Saudi Basic Industries Corporation |
| Chevron Phillips Chemical Company LLC |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's circular economy mandates gate both qualified LLDPE supply and premium-tier pricing access. Producers investing in advanced recycling technologies and bio-based feedstocks command higher prices for their sustainable polymer solutions.
Pricing Analysis
Lead times for specialized LLDPE grades often command a premium, while commodity LLDPE trades closer to spot market rates. The dominant pricing structure remains contract-based long-term offtake agreements for large volumes, supplemented by transactional spot purchases. Price differentiation stems from quality grade, particularly metallocene LLDPE for performance films, and compliance with certifications like REACH. Pricing pressure intensifies for conventional grades due to volatile feedstock costs. Specialized film converters exhibit lower price sensitivity for high-performance LLDPE, while commodity buyers remain highly price-sensitive.
Supply Chain Analysis
Workforce availability in key manufacturing geographies impacts LLDPE production efficiency and supply stability. Geographic supply concentrates heavily in China, the US Gulf Coast, and Saudi Arabia, leveraging abundant raw materials. The LLDPE supply chain draws from ethylene, a derivative of crude oil and natural gas, and longer-chain olefins. A primary structural risk involves the inherent commodity price volatility of these petrochemical feedstocks. Distribution runs through a dual model, with large producers directly supplying major converters and regional distributors serving smaller-volume buyers and niche markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Linear Low Density Polyethylene market is entering a vertical-integration race, with players aggressively pursuing control over advanced recycling infrastructure.
For Market Incumbents: Deepen investment in advanced chemical recycling technologies, such as pyrolysis, to process post-consumer LLDPE waste at scale. Secure long-term supply agreements for bio-based feedstocks to mitigate reliance on volatile fossil resources. This strategy addresses the threat of evolving regulatory mandates, like China's dual carbon policy, and positions companies for a circular economy. Prioritize R&D in mono-material LLDPE solutions to simplify packaging structures and enhance recyclability.
For New Entrants and Emerging Players: Capture niche segments requiring specialized LLDPE grades with unique performance attributes. Target high-purity medical packaging, where demand for sterile and puncture-resistant films is critical. Focus on developing advanced agricultural films for India and Brazil, offering tailored UV resistance and thermal properties. A successful go-to-market angle involves collaborating directly with sustainability-focused brand owners to co-develop custom, recyclable LLDPE solutions.
For Investors and Strategic Acquirers: Commercialization of large-scale advanced chemical recycling facilities is the leading indicator that signals the market's readiness for a sustainable transition. The market exhibits long-term viability, driven by persistent demand for durable flexible packaging across various sectors. Identify acquisition targets with proprietary advanced recycling technologies or established bio-based polymer portfolios. Material deviation in global energy prices or circular economy policy adoption warrants pause and re-evaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Circular-Ready Resins | Increases availability of sustainable LLDPE grades, meeting brand owner demand for recycled content. |
| Backward Integration into Bio-based Feedstocks | Secures renewable raw material supply, reducing dependence on fossil-based ethylene. |
| Green Manufacturing Transition via Pyrolysis Plants | Establishes infrastructure for chemical recycling, converting plastic waste into new polymers. |
| Long-term Supply Agreements for Recycled Content | Guarantees consistent access to post-consumer recycled material for LLDPE production. |
| Joint Venture for Advanced Recycling R&D | Accelerates innovation in chemical recycling processes, improving efficiency and material quality. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications, and corporate sustainability reports underwrites the qualitative findings. This study combines primary interviews with industry stakeholders, including polymer scientists, packaging engineers, procurement managers, and sustainability officers, with extensive secondary validation. The analysis incorporates bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
The rate-of-change decomposition framing informs the forecast framework, providing a granular understanding of market dynamics. This analytical approach models segmentation dimensions such as product type, application, end-user industry, packaging type, and regional regulatory landscape across the analysis window. Compound annual growth rates are derived from historical data and projected growth drivers. Key industry-specific forecast inputs include ethylene price forecasts and projected growth in flexible packaging demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability and technological breakthroughs in alternative materials. Forecasts reflect assumptions regarding volatile feedstock prices and evolving regulatory mandates. Material deviation in global energy prices or circular economy policy adoption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Acetal (POM) Copolymer Market