
 C5 Resin Market | 2026-2036
C5 Resin Market Size, Share, and Industry Trends Forecast 2026-2036
C5 Resin Market Analysis
ISO 9001 quality management certification is redrawing supplier eligibility for Tier-1 adhesive compounders, forcing smaller C5 resin refiners toward third-party audit investments. ExxonMobil leverages its integrated Gulf Coast petrochemical footprint to sustain feedstock cost advantages across aliphatic resin grades. Kolon Industries anchors its position through captive dicyclopentadiene extraction and downstream C5 fractionation in South Korea. Zeon Corporation differentiates via high-purity hydrogenated resin capabilities serving Japanese electronics laminators.
C5 resin denotes alicyclic hydrocarbon polymers synthesized from steam-cracked petroleum fractions rich in cyclopentadiene, isoprene, and piperylene, typically exhibiting ring-and-ball softening points between 80°C and 140°C and Gardner color values below 6. These thermoplastic resins function primarily as tackifiers, reinforcing agents, and compatibilizers in hot-melt adhesives, pressure-sensitive tapes, and traffic marking paints. The automotive application segment leads absolute consumption owing to solvent-free adhesive migration in vehicle interior assembly, while the packaging application segment registers the fastest structural expansion driven by flexible film lamination demand. Solid-form C5 resins command the dominant share of margin pools due to lower logistics complexity and broader compounding equipment compatibility versus liquid or powder variants.
EPA hazardous air pollutant standards under NESHAP constrain U.S. refinery emissions from C5 fractionation units, elevating capital requirements for domestic producers. REACH registration and SVHC disclosure obligations in Europe restrict certain unsaturated hydrocarbon resin grades from consumer-contact applications. BIS certification for adhesive raw materials in India creates non-tariff barriers for unqualified importers serving infrastructure coating contractors. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate reformulation mandates and qualify alternative hydrogenated resin platforms before specification lock-in at major adhesive formulators.
Market Dynamics
Steam cracker feedstock economics and automotive adhesive specification tightening are compressing margin pools for non-integrated C5 resin refiners while rewarding producers with captive dicyclopentadiene extraction and hydrogenation capabilities.
Growth Catalysts
- EPA NESHAP compliance deadlines:U.S. refiners face escalating capital requirements for emissions control on C5 fractionation units, advantaging producers with pre-installed scrubber infrastructure and hydrogenation assets.
- Solvent-free automotive assembly migration:Vehicle interior laminators in Germany and Japan are specifying low-odor hydrogenated tackifiers for dashboard and trim bonding, displacing solventborne neoprene systems.
- Flexible packaging film lamination:Food-grade compliant C5 resins are capturing specification share in retort pouch and lidding applications across Southeast Asian converting clusters.
Market Restraints
- Crude C5 feedstock cost volatility:Naphtha steam cracker operating rates fluctuate with olefin demand cycles, transmitting margin instability to non-integrated resin refiners lacking long-term offtake contracts.
- South Korean supply concentration:Captive dicyclopentadiene extraction capacity at Yeosu and Ulsan petrochemical complexes creates geographic single-source risk for high-purity hydrogenated grades.
- Rosin ester substitution in pressure-sensitive adhesives:Forestry-derived tackifiers from Scandinavian and Brazilian pine sources compete on sustainability credentials in European labeling applications.
Strategic Opportunities
- Indian infrastructure coating expansion:BIS-certified C5 resins for thermoplastic road marking paints face qualified supplier scarcity as highway construction accelerates in Maharashtra and Gujarat.
- Bio-based C5 fraction development:Pyrolysis oil upgrading from tire waste and plastic depolymerization projects in the Netherlands and Singapore are yielding circular feedstock streams for specialty resin grades.
- EU Green Deal carbon border adjustments:Import parity calculations for Asian resin shipments will reward European producers with verified low-carbon hydrogenation processes and renewable energy sourcing.
Industry Challenges
- ISO 9001 and IATF 16949 audit timelines:Tier-1 adhesive compounders are disqualifying uncertified resin suppliers from automotive qualification programs, forcing mid-scale refiners into 12-18 month certification investments.
- Legacy hot-melt equipment incompatibility:Narrow softening point specifications for new hydrogenated grades require compounders to reconfigure extrusion and pumping systems originally designed for conventional aliphatic resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C5 Resin Market |
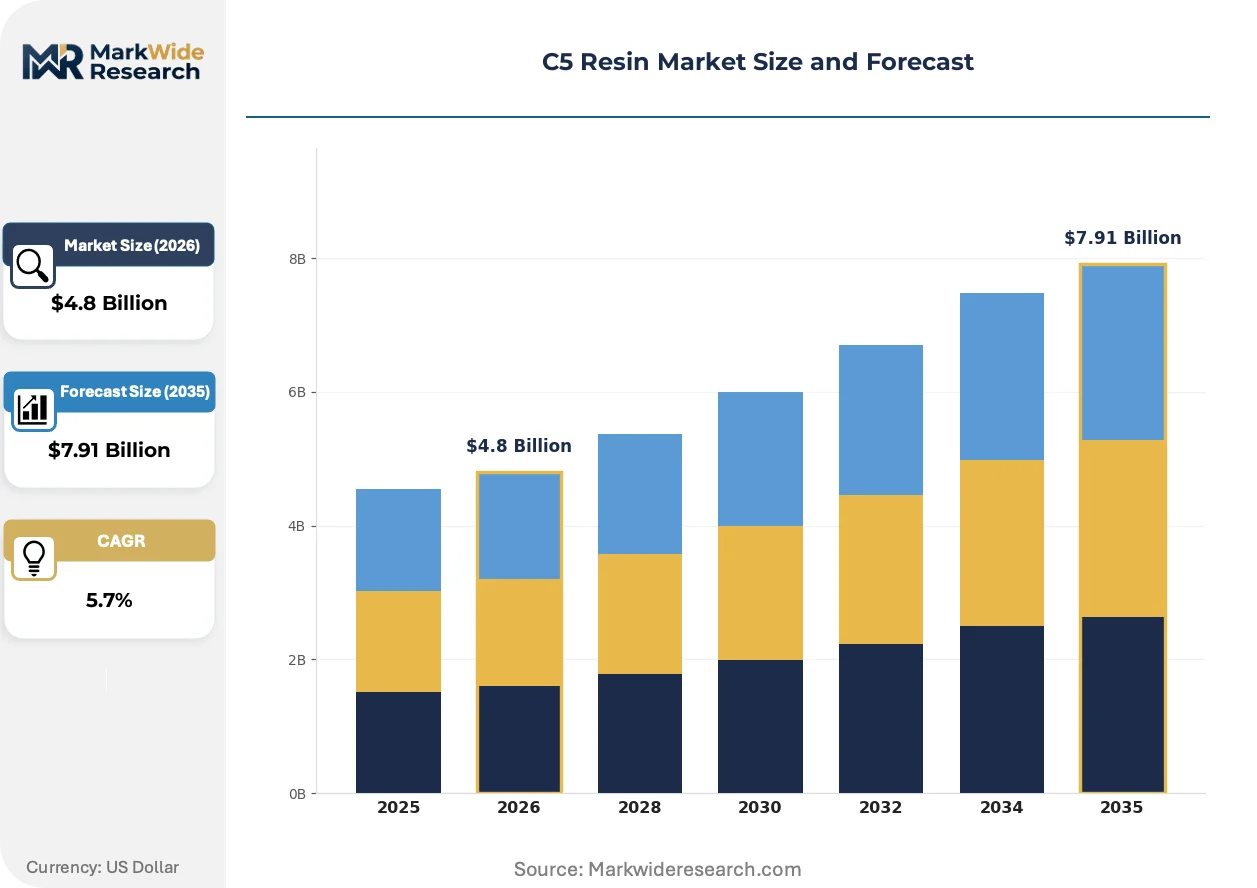
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Adhesive, Coating, Sealant Application: Automotive, Construction, Packaging, Electronics End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Liquid, Solid, Powder, Granular |
| Companies Covered | Braskem, Zeon Corporation, ExxonMobil, IDEMITSU, TotalEnergies, Eastman Chemical Company, Kolon Industries, Arakawa Chemical Industries, Neville Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C5 Resin Market Emerging Trajectories
Hydrogenation technology advancement, regulatory purity escalation, and procurement consolidation among adhesive formulators are restructuring competitive position in C5 resin supply.
Partial hydrogenation of C5 resins is fragmenting the conventional aliphatic tackifier landscape by enabling color-stable, low-odor grades that meet Japanese electronics laminator specifications without full saturation costs. Korean and German compounders are adopting these mid-tier hydrogenated resins at accelerating pace for automotive interior applications. The technology is fragmenting margin pools between commodity aliphatic producers and fully hydrogenated specialty suppliers.
REACH SVHC disclosure obligations and SCIP database requirements are compelling European adhesive formulators to document hydrocarbon resin composition down to 0.1% weight thresholds for consumer-contact applications. This regulatory pressure is disqualifying certain unsaturated C5 grades from food packaging and toy adhesive specifications. German and French compounders are responding by locking in hydrogenated resin platforms ahead of anticipated 2025-2027 restriction list expansions.
Consolidated procurement by multinational adhesive formulators is compressing supplier bases and extending qualification timelines for new resin entrants. Long-term supply agreements with embedded volume commitments and technical service provisions are displacing spot purchasing in automotive and electronics segments. This concentration is most visible in Japanese and German manufacturing clusters where formulator mergers have reduced qualified supplier lists to three or four hydrogenated resin sources.
C5 Resin Market Segmentation
Segmentation in C5 resin markets reveals where specification premiums concentrate and which customer channels transmit reformulation mandates fastest. Understanding these divides exposes where hydrogenation investments yield returns and where commodity aliphatic grades face substitution pressure.
Product Type:
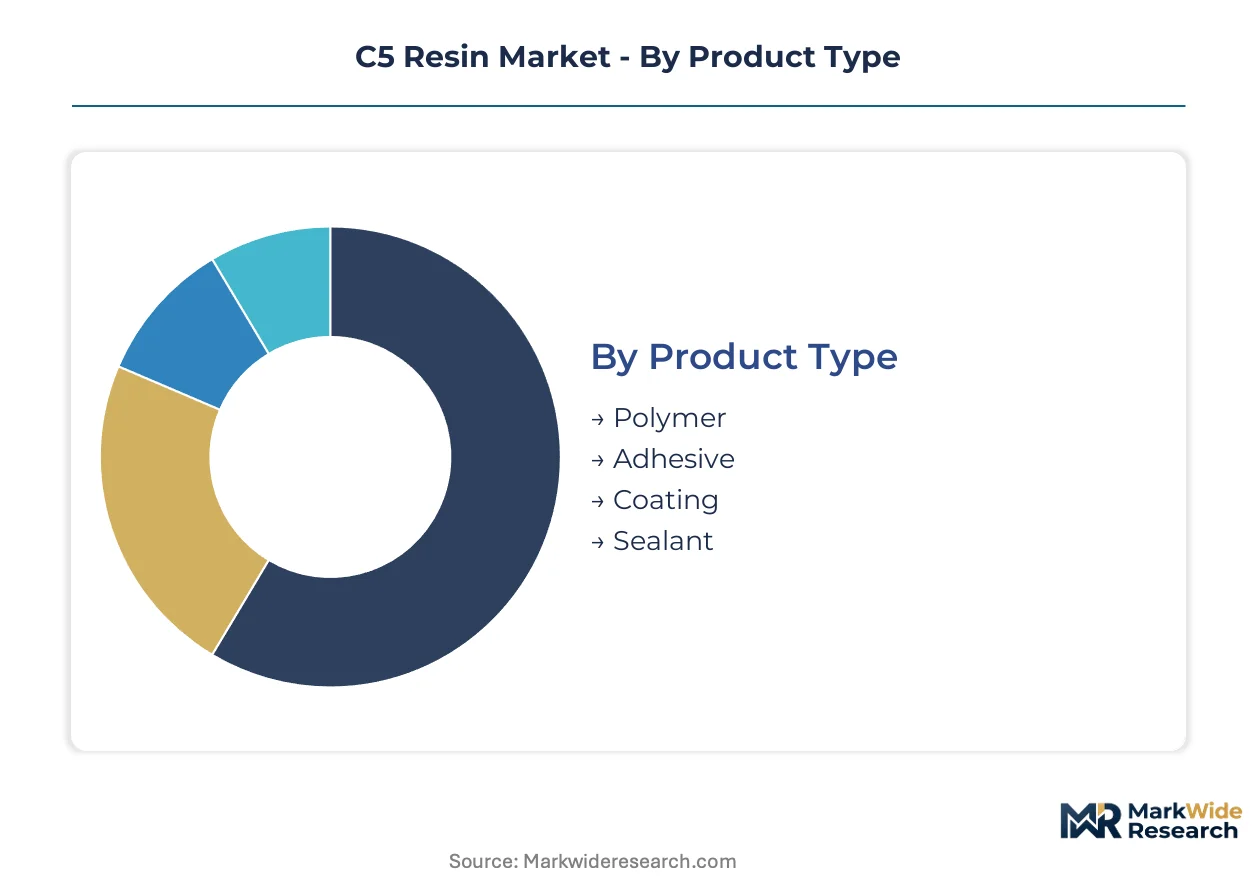
Margin pools concentrate in adhesive and coating grades where REACH SVHC disclosure and food-contact compliance command specification premiums over commodity polymer feedstocks.
- Polymer:Base aliphatic hydrocarbon polymers serve as raw inputs for downstream tackifier compounding, with demand anchored in Asian hot-melt adhesive manufacturing clusters. Specifications center on ring-and-ball softening point ranges between 80°C and 140°C for broad equipment compatibility.
- Adhesive:Formulated tackifier systems for pressure-sensitive tapes and hot-melt assembly capture the steepest value-add margins, particularly hydrogenated grades meeting German automotive interior specifications for low-odor dashboard bonding. German and Japanese vehicle laminators are locking in multi-year supply agreements for these certified grades.
- Coating:Thermoplastic road marking and traffic paint formulations consume C5 resins for durability and retroreflectivity, with Indian infrastructure contractors driving qualified supplier scarcity under BIS certification requirements.
- Sealant:Compatibilizer applications in construction and industrial sealing command narrower volumes but specification stickiness once qualified for joint movement and weathering resistance.
The dominant share belongs to Adhesive, while Coating is closing the gap fastest on Indian highway construction acceleration.
Application:
Application segmentation tracks where solvent-free specification migration is most advanced and where regulatory purity thresholds bite hardest.
- Automotive:Interior trim and dashboard laminators in Germany and Japan specify low-odor hydrogenated tackifiers, displacing legacy solventborne neoprene systems. EPA NESHAP compliance deadlines on U.S. fractionation units are tightening feedstock purity for these applications.
- Construction:Thermoplastic road marking paints and sealant compounding drive volume in India and China, with BIS certification creating qualified supplier bottlenecks for infrastructure coating contractors in Maharashtra and Gujarat.
- Packaging:Flexible film lamination for retort pouches and lidding represents the steepest expansion trajectory, as food-grade compliant C5 resins capture specification share across Southeast Asian converting clusters. REACH SVHC disclosure obligations are disqualifying unsaturated grades from consumer-contact specifications.
- Electronics:Japanese electronics laminators demand high-purity hydrogenated resins for circuit board and display bonding, with color stability specifications below Gardner 3 commanding premium positioning.
Automotive retains the largest volume footprint, though Packaging is expanding most quickly on food-grade compliance migration.
End User:
Channel segmentation determines qualification timelines and technical service intensity, with direct manufacturer relationships extending contract durations and locking out spot-market competitors.
- Manufacturers:Tier-1 adhesive compounders and automotive laminators in Germany and Japan consolidate procurement around three to four qualified hydrogenated resin sources, embedding volume commitments and technical service provisions. ISO 9001 and IATF 16949 certification is disqualifying uncertified refiners from these programs.
- Retailers:Construction and DIY coating channels move smaller volumes of standard aliphatic grades with shorter qualification cycles but thinner margins.
- Wholesalers:Regional distribution intermediaries serve mid-scale compounders in India and Southeast Asia, transmitting BIS and food-grade compliance requirements upstream.
- Distributors:Specialty chemical distributors handle import logistics for European and North American formulators sourcing Asian hydrogenated grades, managing REACH registration documentation and SCIP database submissions.
Manufacturers command the dominant procurement volume, while Distributors are gaining channel influence fastest on import compliance complexity.
Form:
Physical form segmentation maps directly onto logistics economics and compounding equipment compatibility, with solid forms capturing margin premiums through lower handling complexity.
- Liquid:Molten or solvent-diluted resins serve niche spray-applied coating and sealant formulations where pumping viscosity requirements exclude solid feedstocks. Storage and temperature-controlled transport elevate landed costs.
- Solid:Flaked or pelletized resins dominate hot-melt adhesive compounding for broad equipment compatibility and stable shelf life, commanding the largest margin pools in automotive and packaging applications. Solid-form logistics avoid temperature-controlled transport premiums.
- Powder:Micronized grades serve specialized powder coating and dry-blend adhesive applications with limited volume but high specification barriers to entry.
- Granular:Intermediate particle size distributions balance dissolution speed with handling flow properties for continuous compounding operations in high-throughput adhesive plants.
Solid forms hold the dominant share, while Liquid is narrowing the gap fastest in spray-applied industrial coating segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP compliance deadlines and REACH SVHC disclosure obligations are reshaping investment flows across major C5 resin production clusters. Germany, Japan, and South Korea concentrate hydrogenated grade capacity while India and China expand aliphatic resin output for domestic adhesive markets.
United States
Gulf Coast petrochemical complexes supply feedstock for aliphatic resin production serving automotive adhesive compounders. EPA NESHAP hazardous air pollutant standards elevate capital requirements for C5 fractionation unit emissions control. Houston-area refiners with pre-installed scrubber infrastructure capture specification share for low-odor hydrogenated grades.
Germany
Automotive interior laminators specify low-odor hydrogenated tackifiers for dashboard and trim bonding applications. REACH registration and SCIP database obligations compel adhesive formulators to document hydrocarbon resin composition down to 0.1% weight thresholds. The Ruhr industrial cluster hosts qualified suppliers serving Tier-1 vehicle manufacturers.
China
Flexible packaging film lamination drives food-grade compliant C5 resin consumption across Southeast Asian converting clusters. GB standards and evolving environmental regulations from MEE tighten purity thresholds for consumer-contact applications. Yangtze River Delta adhesive manufacturers expand hot-melt capacity for export markets.
India
Infrastructure coating contractors face qualified supplier scarcity for BIS-certified C5 resins in thermoplastic road marking paints. Highway construction acceleration in Maharashtra and Gujarat transmits demand upstream to domestic refiners. Mumbai-Pune industrial corridor compounders seek certification to serve government contracting requirements.
South Korea
Captive dicyclopentadiene extraction at Yeosu and Ulsan petrochemical complexes anchors high-purity hydrogenated grade production. Korean compounders adopt mid-tier hydrogenated resins for automotive interior specifications at accelerating pace. Busan-Ulsan manufacturing cluster exports specialty grades to Japanese electronics laminators.
C5 Resin Market Vendor Landscape
Player mix skews toward integrated petrochemical majors and regional specialty refiners with captive feedstock positions. Market structure concentrates around producers with backward integration into steam cracker operations and hydrogenation assets. Three archetypes dominate: Gulf Coast-integrated majors with feedstock cost advantages, Korean-Japanese specialists with high-purity hydrogenation capabilities, and European compounder-integrated formulators with REACH-compliant platforms. Competitive moves center on capacity expansion for hydrogenated grades and strategic partnerships with Tier-1 adhesive compounders seeking supply security.
Within the integrated major tier, ExxonMobil anchors its position through Gulf Coast petrochemical footprint and captive feedstock economics. Kolon Industries and Zeon Corporation exemplify the Asian specialist archetype with concentrated hydrogenation capabilities and electronics-grade purity positioning. These three companies occupy distinct competitive spaces: feedstock-integrated volume leadership, captive dicyclopentadiene extraction, and high-purity hydrogenated specialty production respectively.
| Leading Market Players |
|---|
| Braskem |
| Zeon Corporation |
| ExxonMobil |
| IDEMITSU |
| TotalEnergies |
| Eastman Chemical Company |
| Kolon Industries |
| Arakawa Chemical Industries |
| Neville Chemical Company |
| Others |
Supply Flow & Price Mechanics
Steam cracker scale economies at Yeosu and Ulsan complexes concentrate hydrogenated grade production in South Korea, compressing unit costs for high-purity resins while elevating price floors for non-integrated refiners lacking captive dicyclopentadiene extraction. This concentration rewards backward-integrated producers with procurement leverage over Asian adhesive compounders and forces spot-market competitors toward thinner margin pools.
Pricing Analysis
Certification level creates the primary spread across C5 resin tiers, with ISO 9001 and IATF 16949 compliance commanding premium positioning for automotive interior specifications. Three-tier pricing structure across hydrogenated specialty, mid-tier partially hydrogenated, and commodity aliphatic grades reflects purity thresholds and odor specifications. Pricing pressure stems from rosin ester substitution in European pressure-sensitive adhesive applications, where forestry-derived tackifiers compete on sustainability credentials. Tier-1 automotive laminators in Germany and Japan exhibit lowest price sensitivity due to specification lock-in, while Indian infrastructure coating contractors face acute cost consciousness under government contracting frameworks.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock flows to Southeast Asian flexible packaging converters, exposing resin shipments to piracy and congestion risks that elevate working capital requirements. Supply concentrates in South Korea, China, and Germany, with Yeosu and Ulsan complexes anchoring hydrogenated grade output and Yangtze River Delta facilities serving domestic hot-melt expansion. Raw material dependencies center on naphtha steam cracker operating rates, cyclopentadiene fractionation yields, and hydrogen supply for saturation processes. Single-source vulnerability concentrates in South Korean dicyclopentadiene extraction, where Yeosu and Ulsan capacity serves Japanese electronics laminators with limited qualified alternatives. Distribution runs through specialty chemical distributors managing REACH documentation and SCIP database submissions for European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
C5 resin markets sit in early-cycle expansion as solvent-free automotive assembly migration accelerates specification upgrades across German and Japanese manufacturing clusters. Hydrogenated grade penetration in dashboard bonding and flexible food packaging laminations creates durable tailwinds for qualified suppliers.
For Market Incumbents: Secure long-term offtake agreements with Tier-1 adhesive compounders before specification lock-in hardens supplier lists to three or four qualified sources. Defend against rosin ester substitution by accelerating hydrogenation capacity additions in South Korea and Germany. Prioritize IATF 16949 certification investments to disqualify uncertified competitors from automotive qualification programs. For New Entrants and Emerging Players: BIS certification fast-track for Indian infrastructure coating contractors addresses qualified supplier scarcity in Maharashtra and Gujarat highway construction. Target thermoplastic road marking paint formulations where domestic refiners lag compliance timelines. Pursue joint development agreements with Mumbai-Pune industrial corridor compounders seeking government contract eligibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogenation asset owners with electronics-grade purity capabilities over commodity aliphatic producers facing margin compression. Long-term viability rests on captive feedstock integration and regulatory compliance infrastructure rather than spot-market volume scale. Monitor EPA NESHAP compliance deadlines as inflection indicator for U.S. refinery consolidation and stranded asset risk among non-compliant fractionation units.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogenation Capacity Expansion | Captures specification share from German automotive interior laminators specifying low-odor grades. |
| Backward Integration into Dicyclopentadiene | Secures feedstock cost advantages at Yeosu and Ulsan petrochemical complexes against volatile naphtha cycles. |
| REACH-Compliant Platform Development | Locks in European adhesive formulators ahead of anticipated SVHC restriction list expansions. |
| Long-term Supply Agreement | Embeds volume commitments with Japanese electronics laminators demanding Gardner color below 3. |
| BIS Certification Investment | Opens Indian infrastructure coating procurement closed to unqualified importers under government contracting rules. |
Methodological Framework
A spread of perspectives from adhesive compounder procurement leads, steam cracker operations managers, hydrogenation technology specialists, and regulatory affairs directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across Korean petrochemical complexes, German automotive laminator facilities, and Indian infrastructure coating contractors with secondary validation from customs trade data, SEC filings of integrated majors, ECHA REACH registration databases, and BIS certification records. Bottom-up volume estimates from segment-level consumption patterns triangulated against top-down capacity assessments from identified production clusters.
Segmentation dimensions modeled include product grade tier, end-use application, physical form, and geographic production hub across the projection horizon. CAGRs derive from elasticity-adjusted demand projections incorporating automotive adhesive specification migration rates and flexible packaging lamination expansion. Forecast inputs incorporate steam cracker operating rate assumptions, hydrogenation technology yield curves, and regulatory compliance timeline probabilities without specific year anchoring.
Underlying assumptions cover naphtha feedstock cost stability, REACH SVHC list evolution, and EPA NESHAP enforcement intensity, with deviation risk concentrated in crude C5 fractionation margin volatility and South Korean supply concentration. Practitioners should keep alternative scenarios live as regulatory divergence across U.S., European, and Indian jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market