
 Rheological Additives Market | 2026-2036
Rheological Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Rheological Additives Market Analytics
Multi-source procurement of organoclays and fumed silica is hardening as formulators reduce dependency on single-supplier regions. BASF SE leverages its integrated pigment-additive complexes to sustain pricing leverage across European coatings accounts. Dow Inc. anchors North American supply through captive silicones-to-specialty-chemicals manufacturing. Elementis plc differentiates via water-based rheology technology leadership, while Evonik Industries AG controls premium fumed silica channels for high-solids industrial coatings.
Rheological additives are specialty chemicals that modify the flow, viscosity, and suspension characteristics of liquid and semi-solid formulations, typically functioning through polymer chain entanglement, particle network formation, or associative thickening mechanisms at loadings between 0.1% and 5.0% by weight. Their primary industrial purpose centers on preventing sag in vertical coatings, controlling leveling in automotive finishes, and maintaining pigment dispersion stability during storage and application. Thickeners occupy the dominant value position across construction and industrial coatings where sag resistance commands premium pricing, while dispersants represent the fastest-expanding category as waterborne systems displace solvent-based alternatives in regulated markets. Liquid-form additives capture growing share from powders due to reduced dust exposure and faster incorporation in high-throughput manufacturing.
EPA VOC regulations and REACH restrictions on hazardous substance classifications directly constrain solvent-borne formulation options, redirecting R&D investment toward bio-based and water-compatible rheology platforms. FDA and EFSA food-contact approvals govern additive selection in edible coatings and packaging adhesives, creating segmented compliance tiers that fragment supplier qualification requirements. Formulators must monitor evolving substance restriction lists across multiple jurisdictions while building dual-track qualification pipelines for legacy and next-generation thickening chemistries.
Market Dynamics
Waterborne coating systems are displacing solvent-borne alternatives across industrial and architectural segments, forcing rheological additive suppliers to reformulate associative thickeners and clay dispersions for polar solvent environments where sag control and leveling balance prove harder to achieve.
Growth Catalysts
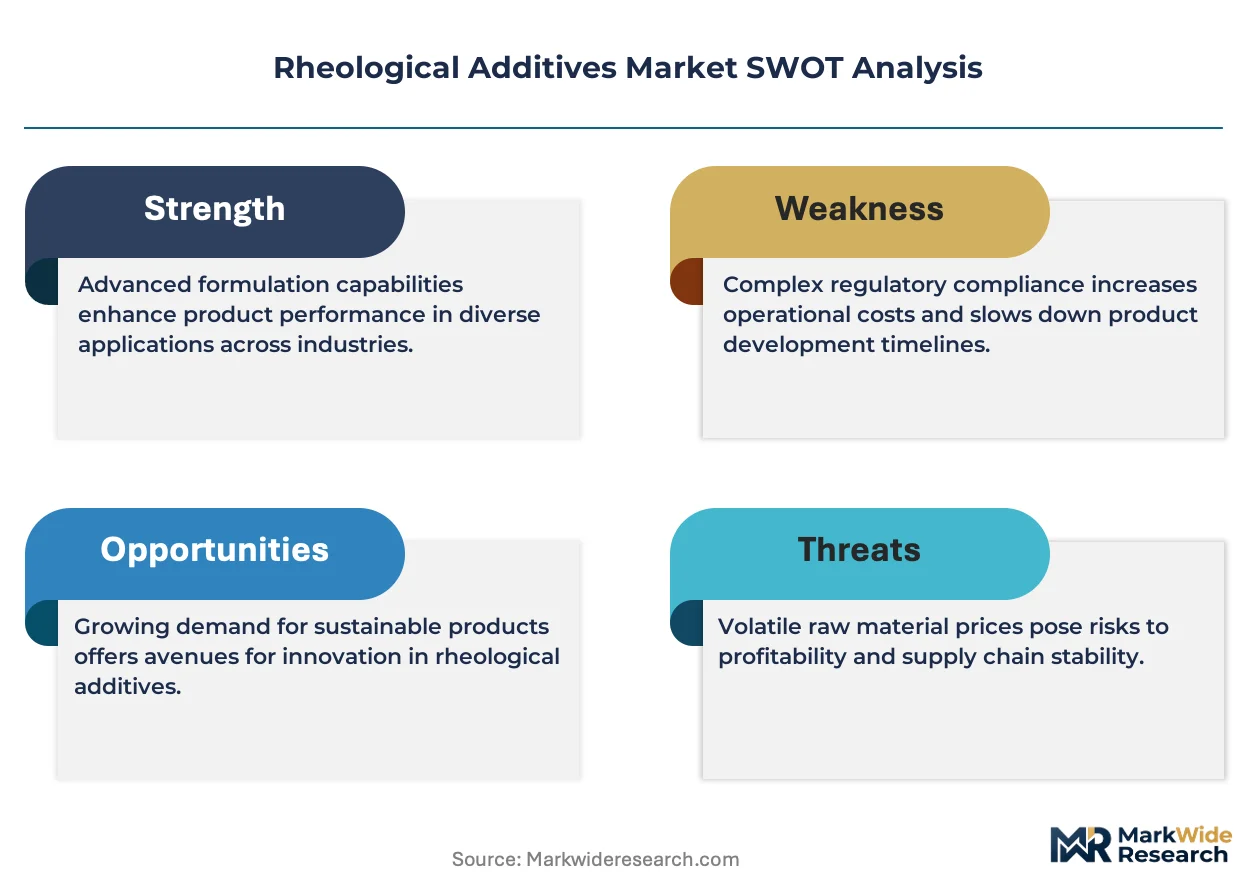
- EPA VOC regulations:Federal emission limits on architectural and industrial maintenance coatings mandate waterborne system adoption, expanding addressable demand for compatible associative thickeners and HEUR rheology modifiers.
- Construction coatings:Vertical application requirements in high-build exterior wall systems prioritize sag-resistant formulations, commanding premium positioning for organoclay and fumed silica additives in commercial building projects.
- India:PLI scheme incentives for domestic specialty chemical manufacturing are attracting additive producers to establish local compounding facilities, reducing import dependency for construction-grade rheology modifiers.
Market Restraints
- Bentonite supply concentration:Wyoming deposits and select Chinese clay beds control feedstock for organoclay production, exposing formulators to geopolitical disruption and freight cost volatility in premium thickener supply.
- REACH substance restrictions:ECHA classification reviews on certain quaternary ammonium compounds used in clay modification are forcing reformulation timelines and dual-track qualification costs for European coatings accounts.
- Cellulosic substitution:HEC and HPMC thickeners retain cost advantage in low-performance architectural segments, capping pricing power for synthetic associative technologies in commodity coating applications.
Strategic Opportunities
- Indonesia:Underdeveloped local additive manufacturing capacity creates first-mover advantage for water-based rheology technology licensing partnerships with regional coating compounders.
- 3D printing construction:Extrusion-based concrete printing requires novel thixotropic control mechanisms, opening specification opportunities for tailored nanoclay and colloidal silica platforms in emerging building methods.
- EU Green Deal:Carbon border adjustment mechanisms and bio-based content mandates favor renewable-sourced rheology platforms, rewarding early investment in cellulose-derived and fermentation-based thickener chemistries.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and particle network mechanics is aging out of the workforce faster than university programs replenish talent pipelines for coatings R&D functions.
- Dual-track qualification:Maintaining parallel legacy solvent-borne and next-generation waterborne additive portfolios strains technical service capacity and extends customer approval cycles for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheological Additives Market |
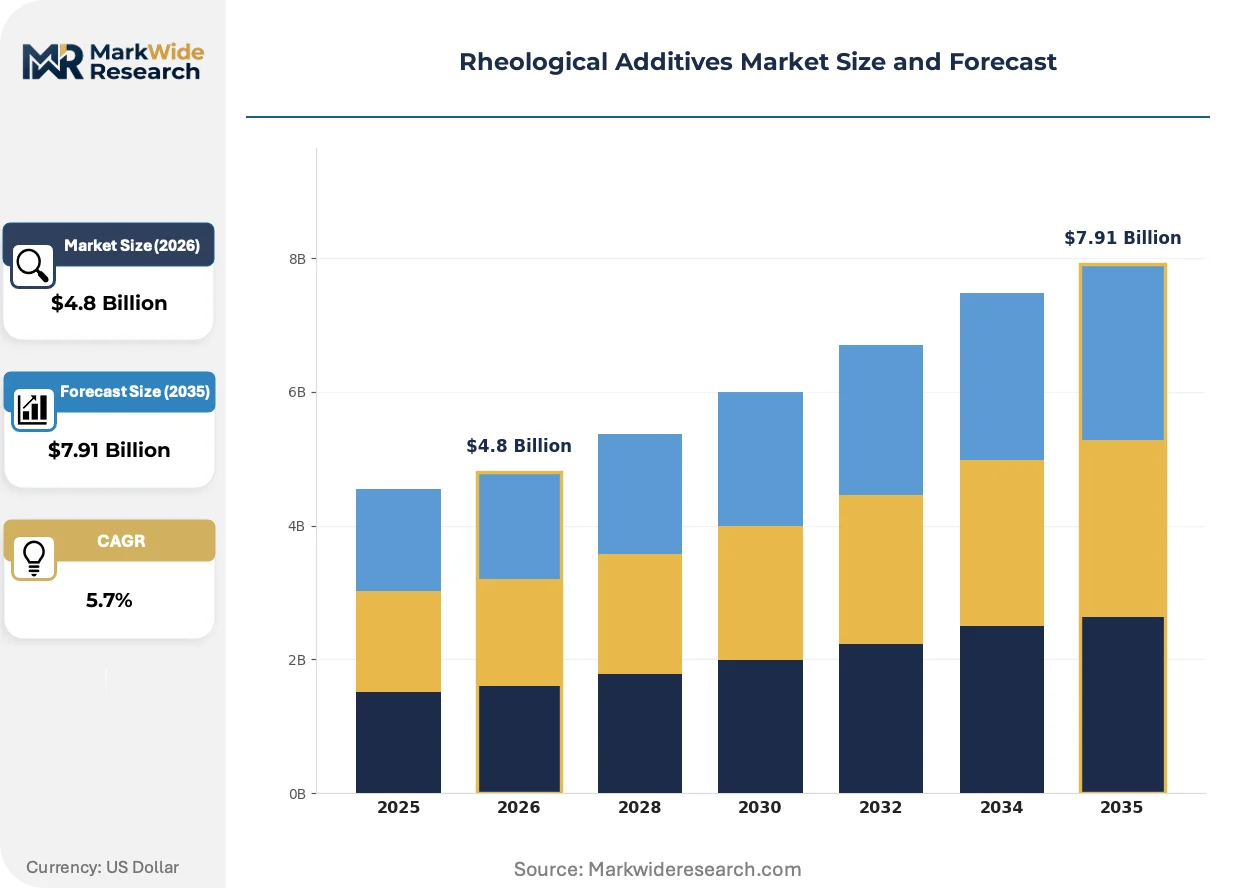
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
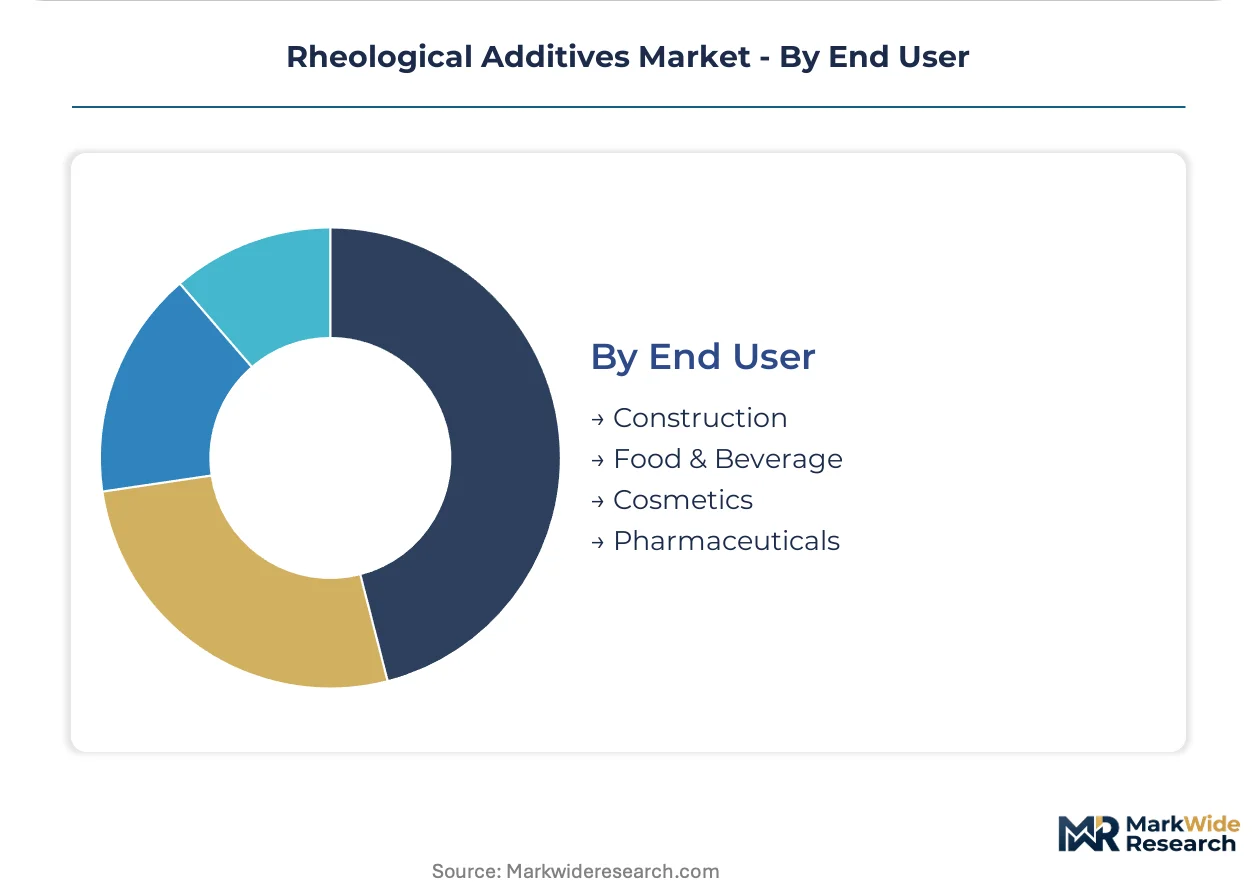
| Segmentation | Product Type: Thickeners, Stabilizers, Emulsifiers, Dispersants Application: Coatings, Adhesives, Plastics, Personal Care Form: Powder, Liquid, Granular, Paste End User: Construction, Food & Beverage, Cosmetics, Pharmaceuticals |
| Companies Covered | BASF SE, Dow Inc., Clariant AG, Elementis plc, The Lubrizol Corporation, Evonik Industries AG, Arkema, Akzo Nobel, BYK Additives & Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheological Additives Market Evolving Landscape
Formulation science is converging with process engineering as additive suppliers embed rheology control directly into pigment grinding and dispersion stages, collapsing traditional sequential manufacturing steps.
Associative thickener technology is absorbing volume from conventional cellulosic and inorganic alternatives in high-solids industrial coatings. Automotive OEM clearcoat formulators are adopting HEUR and HMPE platforms at accelerated qualification cycles. This shift is absorbing margin from commodity thickener suppliers while rewarding polymer architecture specialists with specification lock-in at major coatings accounts.
REACH restrictions on hazardous substance classifications are compressing solvent-borne formulation options across European industrial maintenance coatings. ECHA substance evaluation timelines are forcing premature reformulation investments before final restriction decisions. Decorative and protective coatings segments are responding with accelerated waterborne platform launches and bio-based thickener partnerships.
Coatings manufacturers are consolidating additive procurement through integrated dispersion supply agreements rather than separate chemical purchases. Regional coating compounders in Asia-Pacific are displacing traditional distributor channels with direct technical partnerships. This restructuring is most visible in South Korea and eastern China where automotive and electronics coatings producers demand embedded rheology expertise rather than commodity supply.
Rheological Additives Market Segmentation
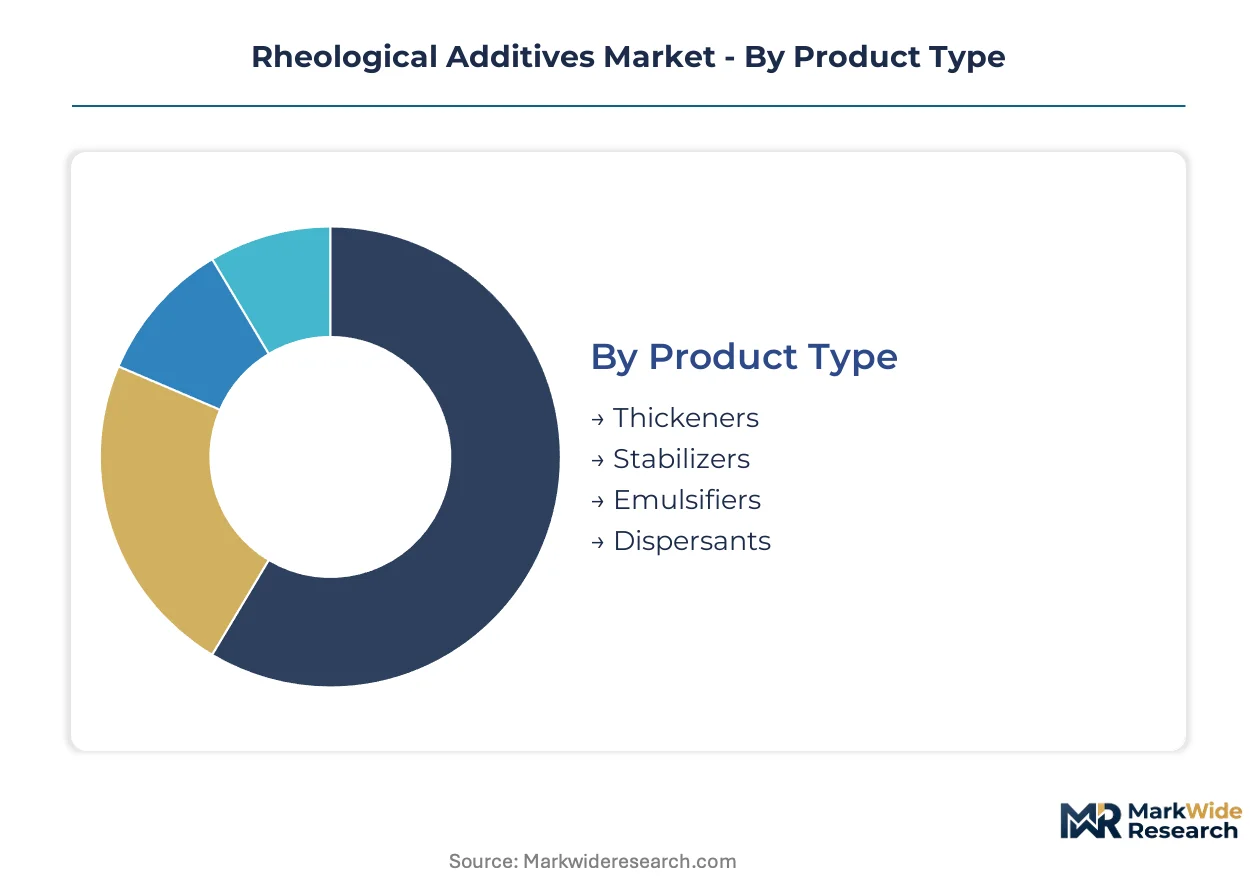
Rheological additives serve fundamentally different performance requirements across end-use verticals, driving specification divergence in molecular architecture and delivery form. Formulators select chemistries based on shear-thinning profiles, compatibility constraints, and regulatory exposure rather than commodity pricing alone.
Product Type:
Customization intensity spans from commodity cellulosic powders to engineered associative polymers with patent-protected backbone structures.
- Thickeners:Cellulosic ethers, organoclays, and associative polymers build viscosity through distinct mechanisms—chain entanglement, platelet stacking, or hydrophobic micelle formation. Construction coatings in China and India absorb the heaviest volumes where sag resistance in vertical exterior systems commands specification priority. Cellulosic substitution pressure from HEC and HPMC limits pricing power in commodity architectural segments.
- Stabilizers:Xanthan gum, guar derivatives, and synthetic polyacrylates prevent phase separation in waterborne systems with high pigment loading. Food and beverage applications concentrate demand where FDA and EFSA approvals create segmented compliance tiers with multi-year qualification timelines.
- Emulsifiers:Surfactant-stabilized systems reduce interfacial tension in multi-phase formulations.
- Dispersants:Polyelectrolyte and steric stabilizer platforms maintain particle separation in high-solids industrial coatings. Expansion is steepest in this category as waterborne systems displace solvent-borne alternatives under EPA VOC and REACH constraints.
Most installed capacity flows through Thickeners. Expansion is steepest in Dispersants.
Application:
Volume concentration correlates with coating system complexity and regulatory stringency rather than absolute market size.
- Coatings:Architectural, automotive, and industrial maintenance formulations consume the majority of specialty rheology additives. Automotive OEM clearcoats in South Korea and eastern China specify HEUR and HMPE platforms at accelerated qualification cycles. Sag control in high-build exterior wall systems drives premium positioning for organoclay and fumed silica grades.
- Adhesives:Pressure-sensitive, structural, and hot-melt systems require thixotropic control for bond line thickness management. Packaging and electronics assembly applications in Japan concentrate demand where METI chemical management protocols govern substance selection.
- Plastics:Melt flow modifiers and processing aids manage viscosity during extrusion and injection molding.
- Personal Care:Sensorial modifiers and suspension agents stabilize emulsions in skin and hair formulations.
Coatings dominate current consumption. Adhesives are gaining share fastest in high-performance segments.
Form:
Manufacturing throughput and occupational exposure regulations determine preference between powder handling and liquid delivery systems.
- Powder:Dry cellulosic ethers and organoclay powders retain cost advantage in low-throughput architectural coating plants. Dust exposure concerns and slower incorporation speeds are driving substitution in high-volume facilities.
- Liquid:Pre-dispersed associative thickeners and colloidal silica sols eliminate dust generation and accelerate batch cycle times. Construction coating compounders in India and Indonesia increasingly specify liquid forms to support high-throughput manufacturing.
- Granular:Low-dust powder alternatives for intermediate handling convenience.
- Paste:High-concentration dispersions for specialized industrial applications.
Powder retains the largest installed base. Liquid forms are expanding most quickly in regulated manufacturing environments.
End User:
Regulatory exposure and performance requirements create distinct procurement patterns across industrial and consumer-facing sectors.
- Construction:Vertical application requirements in commercial building projects prioritize sag-resistant formulations. China, India, and South Korea concentrate regional demand for construction-grade rheology modifiers with high-temperature stability and alkali resistance.
- Food & Beverage:Edible coatings and packaging adhesives require FDA and EFSA food-contact approvals. BIS standards in India and FSSAI compliance create additional qualification layers for suppliers targeting this segment.
- Cosmetics:Sensorial performance and preservative-free claims drive specification toward bio-derived stabilizers.
- Pharmaceuticals:Controlled-release and topical formulations demand excipient-grade rheology control with full regulatory documentation.
Construction absorbs the highest additive volumes. Food and beverage represents the steepest expansion trajectory as edible coating applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting rheological additive production toward jurisdictions with lower compliance costs while maintaining quality equivalence for multinational coatings accounts. Manufacturers are relocating compounding capacity to exploit gaps between EPA VOC enforcement and emerging economy environmental standards.
United States
Automotive OEM clearcoat formulators in Detroit and South Carolina specify HEUR platforms at accelerated qualification cycles. EPA VOC regulations mandate waterborne system adoption across architectural and industrial maintenance segments. The Gulf Coast petrochemical corridor anchors captive silicone-to-specialty-chemicals manufacturing for integrated rheology supply.
Germany
REACH substance restrictions on quaternary ammonium compounds force premature reformulation investments before ECHA final decisions. The EU Green Deal's carbon border adjustment mechanisms favor renewable-sourced rheology platforms. BASF SE leverages integrated pigment-additive complexes from Ludwigshafen to sustain pricing leverage across European coatings accounts.
China
Construction coatings in the Yangtze River Delta and Pearl River Delta absorb the heaviest volumes of organoclay and fumed silica grades for vertical exterior systems. MEE enforcement of dual carbon goals redirects investment toward water-compatible thickener chemistries. Regional coating compounders in eastern China displace traditional distributor channels with direct technical partnerships.
India
PLI scheme incentives for domestic specialty chemical manufacturing attract additive producers to establish local compounding facilities. BIS standards create additional qualification layers for food-contact applications in edible coatings. Construction-grade rheology modifier demand concentrates in Maharashtra and Gujarat where commercial building projects prioritize sag-resistant formulations.
South Korea
Automotive and electronics coatings producers in the Seoul Capital Area demand embedded rheology expertise rather than commodity supply. METI chemical management protocols govern substance selection for packaging and electronics assembly applications. MFDS regulatory alignment with FDA standards enables export qualification for pharmaceutical-grade stabilizer applications.
Rheological Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based and water-compatible formulation partnerships with regional compounders. The supplier base concentrates around integrated chemical conglomerates with captive feedstock positions and independent specialty additive houses with patent-protected polymer architectures. Three archetypes dominate: diversified materials conglomerates leveraging vertical integration, focused rheology technology specialists, and regional compounders with embedded technical service capabilities. Competitive moves center on strategic partnerships for waterborne platform development and capacity expansion in underpenetrated Asian markets.
Among European-based diversified producers, BASF SE and Evonik Industries AG exemplify the integrated conglomerate archetype with upstream control over key feedstocks. Elementis plc occupies a position within the focused specialty tier, representing water-based rheology technology leadership. These three anchors illustrate the competitive spectrum from captive supply chains to targeted application expertise.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Clariant AG |
| Elementis plc |
| The Lubrizol Corporation |
| Evonik Industries AG |
| Arkema |
| Akzo Nobel |
| BYK Additives & Instruments |
| Others |
Value Network & Pricing Analysis
Bentonite feedstock indices and Wyoming basin spot pricing cascade through organoclay production into three-tier pricing structures across premium, standard, and economy levels. Formulators absorbing volatile clay costs face compressed margins in commodity architectural segments while specialty grades retain pricing power through technical service bundling.
Pricing Analysis
Input-cost pass-through from Wyoming bentonite deposits and Chinese clay bed freight differentials shapes contract negotiations between additive producers and coatings compounders. Pricing stratifies across premium, standard, and economy tiers based on sag-resistance performance certification and volume scale commitments. Cost compression in commodity cellulosic thickeners is intensifying because HEC and HPMC substitution erodes synthetic associative polymer margins. Small-scale architectural coating plants in India exhibit highest price sensitivity, while automotive OEM clearcoat formulators in South Korea prioritize specification lock-in over unit economics.
Supply Chain Analysis
Freight cost volatility from Wyoming mining districts to European compounding facilities and intra-Asian container routing exposes formulators to landed cost swings exceeding raw material differentials. Supply concentrates in the United States, China, and Germany for organoclay feedstock, fumed silica synthesis, and associative polymer production respectively. The chain draws from bentonite clay deposits, silicone feedstocks, and acrylate monomer streams with single-source vulnerability in Wyoming premium clay grades. Distribution runs through integrated dispersion supply agreements rather than traditional chemical distributor networks, particularly in eastern China and South Korea where automotive coatings producers demand embedded technical partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification momentum toward HEUR and HMPE platforms in automotive OEM clearcoats rewards molecular architecture expertise over commodity supply.
For Market Incumbents: Cement specification lock-in at major coatings accounts through accelerated qualification cycles for waterborne rheology platforms. Deepen backward integration into captive silicone feedstocks to defend margin position against fumed silica supply disruption. Prioritize R&D investment in bio-based thickener chemistries ahead of EU Green Deal carbon border adjustments. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in Indonesian construction coatings offers white-space entry for water-based rheology technology licensing partnerships. Target underdeveloped local additive manufacturing capacity in Southeast Asian markets where regional compounders lack indigenous thickener production. Pursue direct technical service relationships with mid-scale coating producers seeking alternatives to established distributor channels. For Investors and Strategic Acquirers: Asymmetric upside sits with focused rheology technology specialists possessing patent-protected associative polymer architectures and established automotive OEM qualification pipelines. The five-to-ten year viability window favors acquisition targets with waterborne platform leadership and embedded technical partnerships in Asia-Pacific growth markets. Monitor ECHA substance evaluation timelines on quaternary ammonium compounds as an inflection signal for premature reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstocks | Secures silicone and bentonite supply against Wyoming deposit concentration risk. |
| Waterborne Platform Qualification Acceleration | Captures EPA VOC-driven specification shifts in automotive OEM clearcoats. |
| Bio-based Thickener Chemistry Partnerships | Positions suppliers for EU Green Deal carbon border adjustment compliance. |
| Direct Technical Service Expansion | Displaces distributor channels in South Korea and eastern China coating clusters. |
| Local Compounding Facility Establishment | Exploits PLI scheme incentives in Maharashtra and Gujarat construction markets. |
Research Methodology
Bottom-up coatings formulation modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with technical R&D directors at additive suppliers, procurement leads at downstream coatings OEMs, plant managers at compounding facilities, and distribution channel partners in Asia-Pacific markets combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Triangulation between demand-side specification trends and supply-side capacity announcements ensures coherence across volume and value estimates.
Input-output matrix framing connects raw material flow assumptions through segmentation dimensions including thickener chemistry type, coatings end-use vertical, delivery form factor, and regional production hub classification. CAGRs derive from regression analysis against historical volume relationships and forward projection of regulatory enforcement intensity across the analysis window. Industry-specific forecast inputs incorporate REACH substance restriction timelines and PLI scheme incentive disbursement patterns.
Caveats apply where ECHA classification decisions on quaternary ammonium compounds or MEE enforcement variability around dual carbon goals could materially shift the outlook. Forecasts reflect documented assumptions regarding waterborne displacement rates and automotive OEM qualification cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Apocarotenal Market
Additives
Ethoxyquin Market
Additives
Packaging Coating Additives Market
Additives
United States Citric Acid Market
Additives
Biofuel Additives Market
Additives
Drilling Fluid Additives Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Octane Improver Fuel Additives Market
Additives
Marine Fuel Additives Market
Additives
Global Zinc Stearate Market
Additives
Fuel Additives Market
Additives
Chitosan Powder Market
Additives
Viscosity Index Improvers Market
Additives
Low VOC Coating Additives Market
Additives
Wax Additives Market
Additives
Plasticizer Concrete Admixtures Market