
 Cetane Improver Additives Market | 2026-2036
Cetane Improver Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Cetane Improver Additives Market Insights
Specialized fuel chemist availability is bifurcating the competitive landscape between integrated petrochemical giants and niche additive houses. BASF SE leverages its Ludwigshafen manufacturing complex to sustain captive supply of alkyl nitrate precursors. Innospec anchors its position through dedicated naval and power generation distribution channels in Northern Europe. Chevron Corporation competes via backward integration into refinery-grade base stocks across its integrated downstream network.
Cetane improver additives are combustion-enhancing chemical compounds, primarily alkyl nitrates and peroxides, formulated to reduce diesel ignition delay and improve cold-start performance through accelerated radical formation during compression. These additives typically deliver measurable cetane number increases at treat rates between 0.1% and 0.5% by volume, enabling refiners to meet EN 590 and ASTM D975 specifications without costly hydrotreating upgrades. Alkyl nitrates occupy the dominant share of product type demand due to established efficacy and compatibility with existing fuel infrastructure. Marine applications within the application dimension are expanding fastest as vessel operators confront tightening IMO NOx Tier III limits in emission control areas. Liquid formulations lead the form category, though concentrate variants are gaining traction among large fleet operators seeking reduced logistics expenditure.
The U.S. EPA enforces Tier 3 gasoline and diesel standards that indirectly shape cetane additive demand through sulfur and particulate mandates, while REACH registrations in Europe govern the commercialization of novel nitrate ester chemistries. Germany's KBA implements roadside fuel quality testing that creates enforcement-driven replacement demand for off-specification diesel batches. India's BIS adoption of Euro VI-equivalent BS VI norms has opened formal compliance channels for imported additive packages. Stakeholders must monitor the trajectory of renewable diesel blending mandates, as paraffinic biofuels with inherently high cetane numbers could structurally displace conventional improver demand in regulated jurisdictions.
Market Dynamics
Refinery blending economics are compressing treat-rate tolerances as hydrotreater capacity constraints force operators toward higher-dose additive formulations rather than capital-intensive hardware upgrades.
Growth Catalysts
- IMO 2020 Sulfur Cap:Marine engine manufacturers are procuring high-cetane formulations to meet subsequent NOx Tier III limits in emission control areas.
- Renewable Energy Directive II:European refiners are redirecting blending strategies toward bio-derived cetane boosters to satisfy renewable diesel mandates.
- Paraffinic Biofuel Integration:Synthetic fuel producers require supplemental improvers to offset cetane variability in hydrotreated vegetable oil streams.
Market Restraints
- Nitrate Ester Feedstock Volatility:Alkyl nitrate precursor costs fluctuate with n-paraffin availability from steam cracker operations.
- REACH Registration Burden:Novel chemistries face multi-year ECHA approval timelines that freeze formulation innovation pipelines.
- Inherent Cetane Competition:Renewable diesel with natural cetane numbers above 70 threatens conventional additive demand in compliant jurisdictions.
Strategic Opportunities
- India BS VI Compliance Gap:Domestic refiners lack indigenous additive manufacturing, creating import channels for packaged improver solutions.
- Concentrate Formulation Uptake:Large fleet operators are adopting high-potency variants to reduce drum logistics and storage footprint.
- Naval Procurement Channels:Dedicated military fuel specifications favor long-term supply contracts with certified additive houses.
Industry Challenges
- Specialized Fuel Chemist Scarcity:Formulation expertise concentrates at integrated petrochemical complexes, constraining niche additive house scale-up.
- Cross-Batch Compatibility Certification:Each new base stock blend requires full engine-test validation against EN 590 and ASTM D975 protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetane Improver Additives Market |
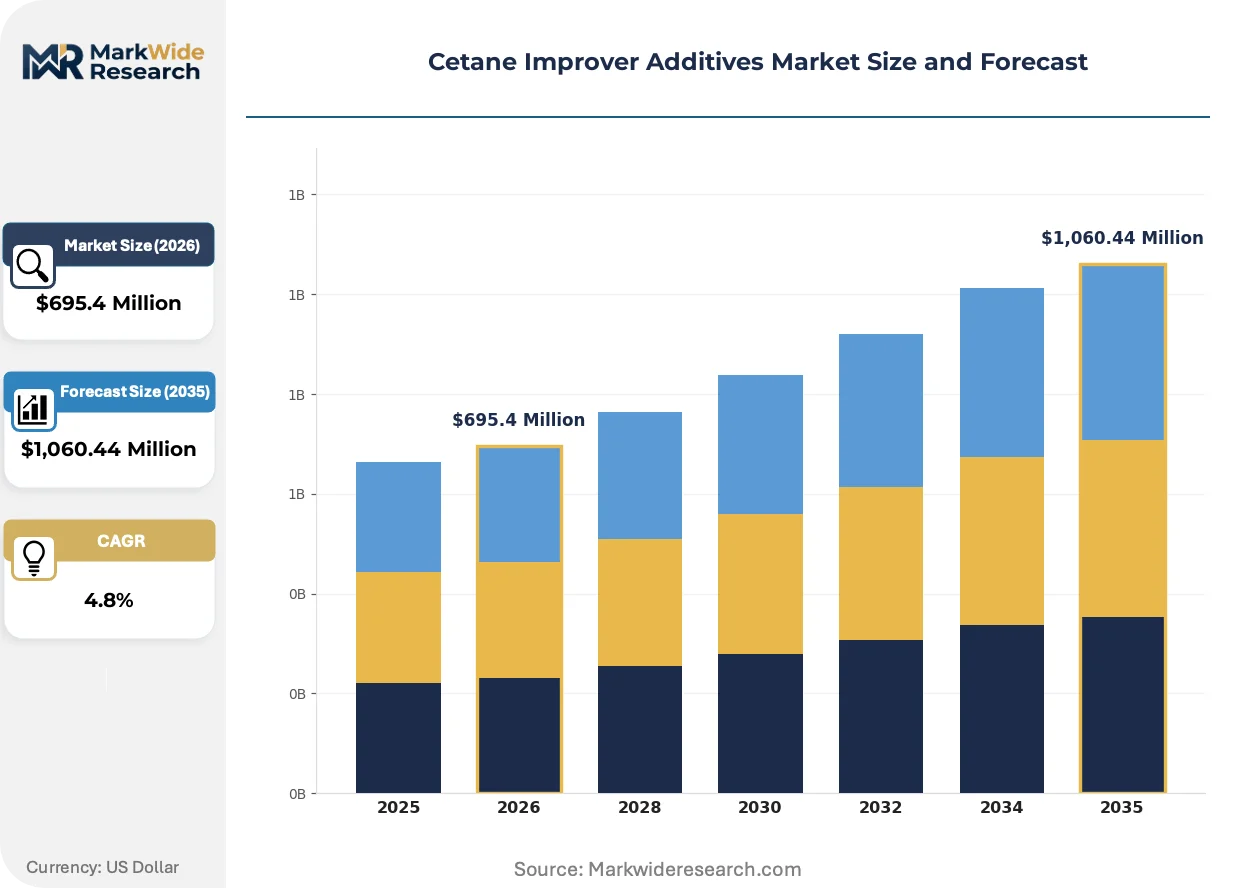
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $1,060.44 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Nitrates, Fatty Acid Esters, Aromatic Compounds, Others Application: Diesel Fuel, Automotive, Industrial, Marine Form: Liquid, Powder, Aerosol, Concentrate Delivery Model: Bulk, Retail, Direct Supply, E-commerce |
| Companies Covered | BASF SE, The Lubrizol Corporation, Innospec, Chevron Corporation, Afton Chemical, Eurenco, Cestoil Chemical Inc., Infineum International Limited, NITROERG S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetane Improver Additives Market Trends and Innovations
Formulation chemistry is diverging along performance-versus-sustainability axes as refiners balance immediate combustion efficiency against carbon intensity scoring in fuel certification schemes.
Peroxide-based cetane boosters are gaining treat-rate precision in cold-climate formulations. Arctic fleet operators in Scandinavia are adopting these chemistries for sub-zero ignition reliability. The technology is bifurcating the product landscape between cost-optimized alkyl nitrates and premium peroxide tiers.
REACH registrations are tightening disclosure requirements for nitrate ester impurities. ECHA's updated dossier standards are forcing reformulation of legacy products to eliminate residual alcohol carryover. Marine blenders in Northern Europe are accelerating pre-approval testing to maintain ECAS fuel supply contracts.
Fleet operators are consolidating procurement through direct additive manufacturer contracts rather than distributor intermediaries. Large road transport operators in Germany are negotiating volume-tier pricing with BASF and Innospec directly. This disintermediation is compressing regional distributor margins and reshaping logistics service requirements.
Cetane Improver Additives Market Segmentation
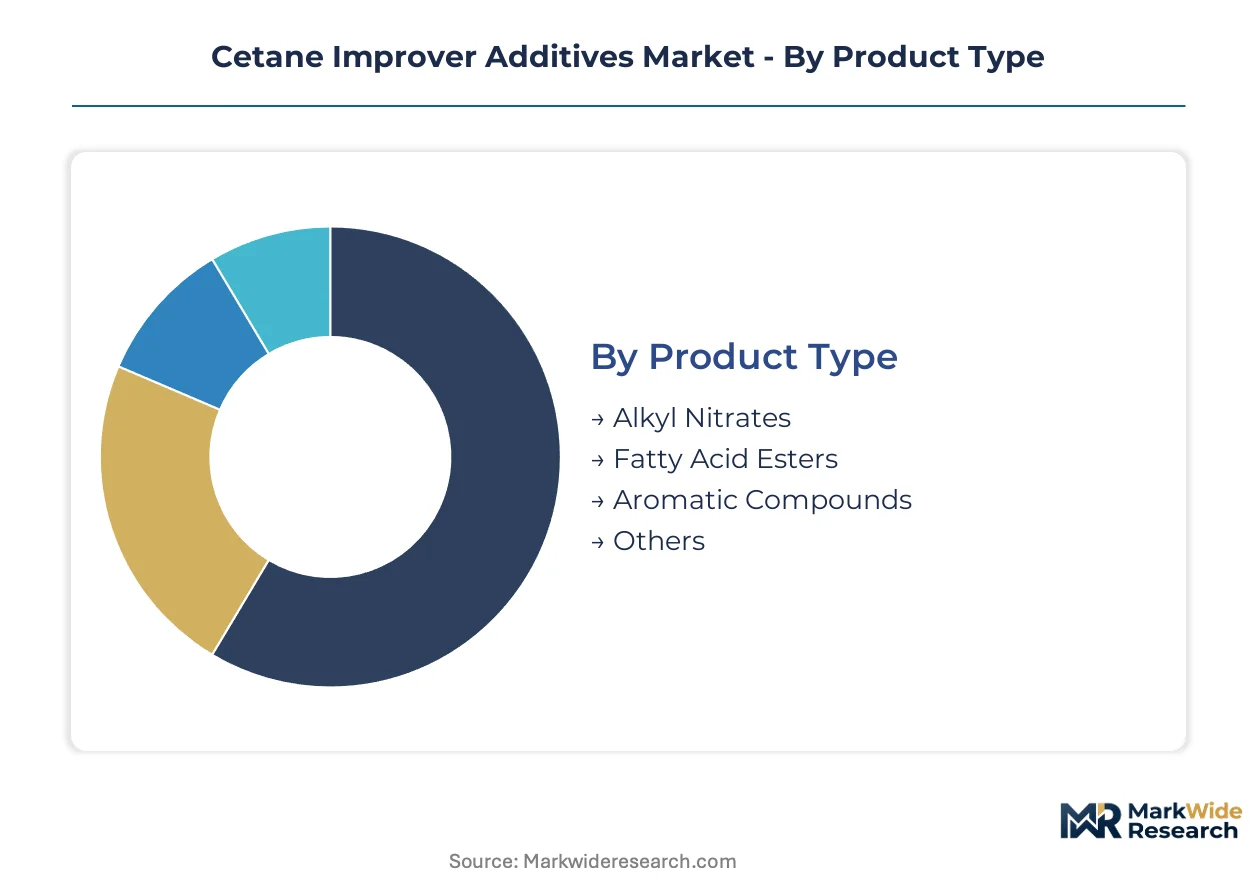
Cetane improver additive suppliers calibrate portfolio depth against treat-rate economics and end-use certification requirements. Segment boundaries increasingly blur as marine blenders demand automotive-grade purity and industrial operators adopt naval procurement standards.
Product Type:
Margin pools concentrate in nitrate ester chemistry where precursor integration and REACH registration amortization create defensive moats.
- Alkyl Nitrates:Nitrate ester formulations deliver cetane number improvements at treat rates between 0.1% and 0.5% by volume through accelerated radical formation during compression ignition. Refiners in Germany facing KBA roadside enforcement drive replacement demand for off-specification diesel batches requiring rapid cetane correction.
- Fatty Acid Esters:Bio-derived ester chemistry aligns with EU Renewable Energy Directive II mandates for renewable diesel blending, though inherent cetane variability in hydrotreated vegetable oil streams demands supplemental boosting. European refiners redirect procurement toward these formulations to satisfy carbon intensity scoring in fuel certification schemes.
- Aromatic Compounds:Legacy aromatic boosters retain niche positioning in cost-sensitive industrial heating oil applications.
- Others:Experimental chemistries including ether-based and metallic-organic compounds occupy pre-commercial testing phases.
The dominant share belongs to Alkyl Nitrates, while Fatty Acid Esters is closing the gap fastest.
Application:
Volume concentration tracks regulatory enforcement intensity rather than absolute fuel consumption.
- Marine:Vessel operators confronting IMO NOx Tier III limits in emission control areas procure high-cetane formulations to optimize combustion timing and aftertreatment efficiency. Northern European bunkering hubs in Rotterdam and Hamburg anchor demand concentration as ECAS compliance deadlines tighten.
- Diesel Fuel:Refinery blending operations represent the foundational demand layer, with hydrotreater capacity constraints forcing operators toward higher-dose additive formulations rather than capital-intensive hardware upgrades.
- Automotive:OEM factory-fill specifications and aftermarket retail channels serve light-duty and heavy-duty vehicle operators.
- Industrial:Power generation, mining equipment, and agricultural machinery applications prioritize cost per treated gallon over cetane number precision.
Marine commands the steepest expansion trajectory as emission control area expansion multiplies addressable vessel populations.
Form:
Logistics economics favor liquid handling infrastructure already embedded at refineries and terminals.
- Liquid:Standard liquid formulations dominate refinery injection systems and terminal blending operations due to compatibility with existing fuel infrastructure and metered dosing equipment.
- Concentrate:High-potency variants reduce drum logistics and storage footprint for large fleet operators negotiating direct manufacturer contracts in Germany.
- Powder:Solid formulations serve remote mining and construction sites lacking liquid handling capabilities.
- Aerosol:Pressurized canisters target aftermarket retail for emergency cold-start assistance.
Liquid formulations retain the installed base advantage, though Concentrate is gaining share fastest among volume-tier procurement consolidators.
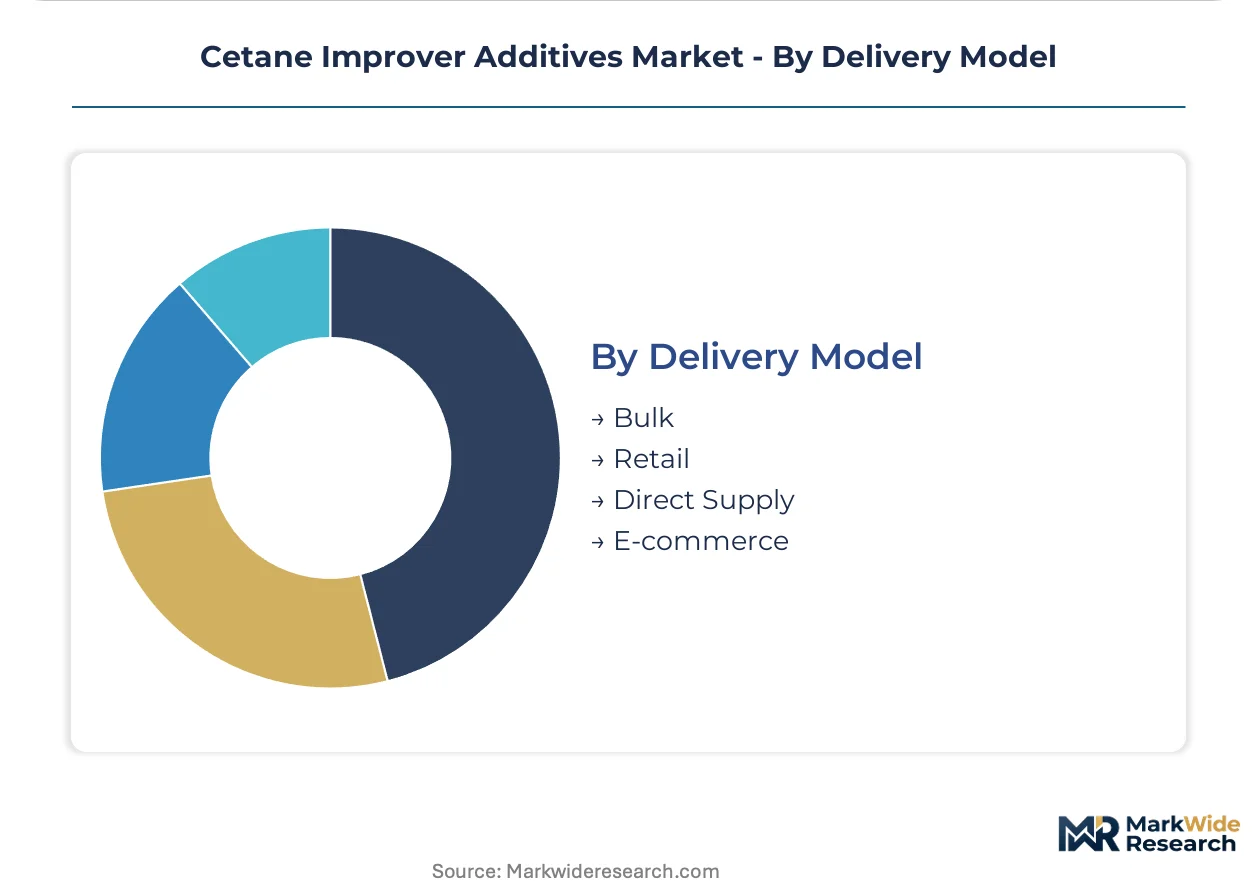
Delivery Model:
Channel selection bifurcates between capital-intensive bulk infrastructure and relationship-intensive direct contracting.
- Bulk:Tanker and railcar deliveries integrate with refinery additive injection skids and marine terminal blending systems, capturing economies of scale in high-throughput operations.
- Direct Supply:Large road transport operators in Germany negotiate volume-tier pricing with BASF and Innospec directly, compressing regional distributor margins and reshaping logistics service requirements.
- Retail:Packaged products move through automotive parts distributors and service station convenience stores.
- E-commerce:Digital procurement channels emerge for small fleet operators and agricultural customers seeking technical documentation transparency.
Bulk infrastructure locks in the volume base, while Direct Supply is climbing the fastest as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. European refiners prioritize bio-derived formulations for renewable diesel integration, while Asian markets emphasize cost-efficient alkyl nitrate dosing for compliance-driven retrofitting of aging hydrotreaters.
Germany
KBA roadside enforcement drives replacement demand for off-specification diesel batches requiring rapid cetane correction. REACH registrations govern commercialization of novel nitrate ester chemistries through multi-year ECHA approval timelines. The Ludwigshafen chemical cluster anchors integrated manufacturing of alkyl nitrate precursors for captive supply to domestic refiners.
United States
EPA Tier 3 standards indirectly shape additive demand through sulfur and particulate mandates that tighten combustion efficiency requirements. The EPA enforces compliance deadlines that force refiners toward higher-dose formulations rather than capital-intensive hardware upgrades. Gulf Coast refining corridors concentrate blending operations where hydrotreater capacity constraints persist.
India
BIS adoption of Euro VI-equivalent BS VI norms opened formal compliance channels for imported additive packages. Domestic refiners lack indigenous manufacturing capabilities, creating import-dependent procurement channels. Western refinery clusters in Gujarat and Maharashtra anchor demand concentration as compliance deadlines tighten for transport and industrial diesel.
China
MIIT emission standards for diesel vehicles drive treat-rate precision in refinery blending operations. GB standards govern fuel quality specifications that additive formulations must satisfy through full engine-test validation. Yangtze River Delta petrochemical complexes concentrate formulation expertise and precursor integration capabilities.
Netherlands
Rotterdam bunkering hubs anchor marine demand as vessel operators confront tightening IMO NOx Tier III limits in North Sea emission control areas. EU Renewable Energy Directive II redirects refinery blending strategies toward bio-derived cetane boosters. The Randstad logistics corridor enables bulk additive distribution to Northwest European terminals.
Cetane Improver Additives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market structure. Integrated petrochemical giants leverage captive precursor supply and amortized REACH registrations to defend position in high-volume refinery channels. Niche additive houses compete through dedicated naval and power generation distribution relationships. Strategic moves concentrate on backward integration into base stock supply and direct contracting with large fleet operators to compress distributor margins.
Among European-integrated chemical conglomerates, BASF SE and Eurenco exemplify the precursor-integrated archetype. Innospec occupies a position within the specialty distribution tier. Chevron Corporation anchors the refinery-integrated model through its downstream network control.
| Leading Market Players |
|---|
| BASF SE |
| The Lubrizol Corporation |
| Innospec |
| Chevron Corporation |
| Afton Chemical |
| Eurenco |
| Cestoil Chemical Inc. |
| Infineum International Limited |
| NITROERG S.A. |
| Others |
Pricing and Supply Chain Analysis
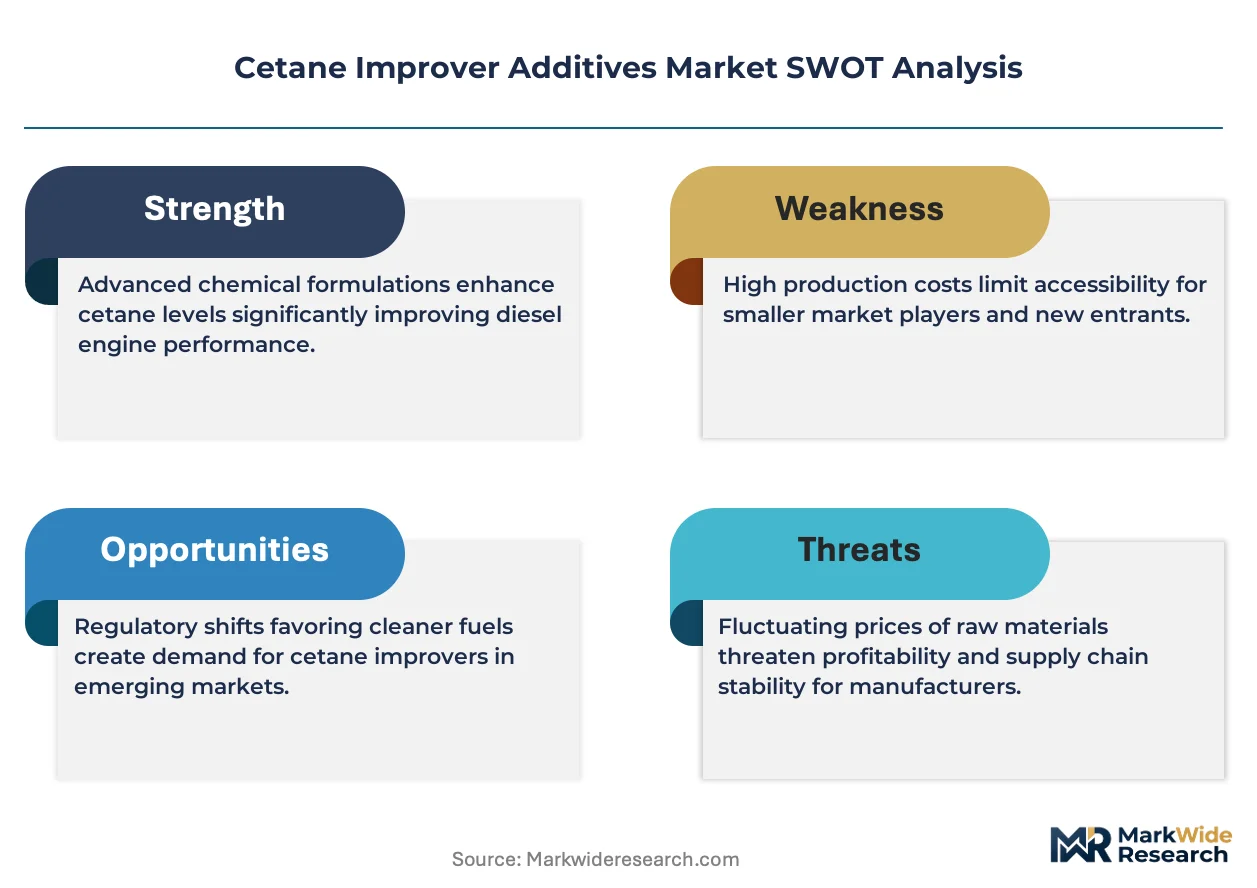
Steam cracker utilization rates at European petrochemical complexes dictate alkyl nitrate precursor availability and establish price floors for formulation houses lacking captive n-paraffin supply. This scale concentration enables integrated producers to absorb feedstock volatility while specialty additive houses pass through cost swings to marine and automotive blenders.
Pricing Analysis
Long-term offtake contracts dominate marine bunkering channels in Rotterdam and Hamburg, while spot procurement serves refiners facing emergency cetane correction after KBA roadside enforcement actions. Price differentiation rests on REACH registration amortization and treat-rate precision, with certified naval specifications commanding premiums over industrial heating oil grades. Cost compression in standard alkyl nitrate tiers is intensifying as hydrotreater capacity constraints force higher-dose formulations. Large fleet operators in Germany exhibit lowest price sensitivity due to direct manufacturer contracting, whereas remote mining sites purchasing powder formulations show acute cost responsiveness.
Supply Chain Analysis
Germany, the United States, and China anchor global production of alkyl nitrate precursors and finished cetane improver formulations. Supply chains draw from n-paraffin feedstocks, nitric acid, and specialized reaction vessels for nitrate ester synthesis. Single-source vulnerability concentrates in Ludwigshafen-derived precursor streams for European blenders. Distribution runs through bulk tanker and railcar networks integrating with refinery additive injection skids, supplemented by drum logistics for concentrate variants reaching fleet operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cetane improver additives market is entering a cyclical recovery phase as marine emission control area expansion and renewable diesel blending mandates drive replacement demand for off-specification fuel batches.
For Market Incumbents: Consolidate backward integration into n-paraffin supply and accelerate REACH dossier updates for legacy nitrate ester formulations to preempt ECHA impurity disclosure tightening. Captive precursor production at Ludwigshafen-scale complexes defends margin position against feedstock volatility. Direct contracting with German fleet operators compresses distributor intermediaries and locks in volume-tier pricing stability. For New Entrants and Emerging Players: Technical service gaps in BS VI compliance consulting for Indian refiners lacking indigenous additive manufacturing present immediate white-space opportunity. Concentrate formulation packaging for large Scandinavian arctic fleets offers second penetration vector. A certification-first go-to-market approach leveraging pre-approved naval fuel specifications bypasses incumbent REACH registration moats. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among additive houses with dedicated marine procurement channels and amortized ECHA registrations. Long-term viability across the projection horizon favors targets with integrated precursor supply and direct fleet operator relationships. The signal to watch is renewable diesel blending mandate acceleration in jurisdictions where paraffinic biofuels with inherent cetane above 70 threaten conventional improver displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive n-paraffin production at Ludwigshafen-scale complexes insulates margin from steam cracker volatility. |
| REACH Dossier Reformulation | ECHA impurity disclosure tightening forces legacy product updates to maintain ECAS marine fuel contracts. |
| Direct Fleet Operator Contracting | German road transport procurement centralization compresses distributor margins and secures volume-tier pricing. |
| Concentrate Formulation Scale-Up | High-potency variants reduce drum logistics costs for Scandinavian arctic fleet operators. |
| Naval Procurement Channel Certification | Military fuel specifications favor long-term supply relationships with additive houses meeting stringent purity standards. |
Research Methodology
Desk research of customs trade databases, ECHA registration dossiers, and refinery blending operation disclosures preceded structured interviews with fuel chemists at integrated petrochemical complexes, marine bunker procurement managers at Rotterdam terminals, fleet operations directors at German road transport companies, and regulatory affairs specialists at additive formulation houses. Primary fieldwork combined with secondary validation across SEC filings of downstream operators and IEA marine fuel quality reports enabled bottom-up treat-rate modeling and top-down market sizing triangulation.
Variance decomposition across product type, application, form, and delivery model dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level treat-rate elasticity modeling against hydrotreater capacity expansion timelines and renewable diesel blending mandate trajectories. Industry-specific forecast inputs incorporated KBA roadside enforcement frequency data and IMO emission control area expansion schedules.
Underlying assumptions cover sustained marine sulfur cap enforcement and REACH registration continuity, with deviation risk concentrated in renewable diesel displacement rates and n-paraffin feedstock availability from European steam cracker operations. Forecasts reflect these conditions with revision triggers tied to regulatory mandate acceleration or biofuel cetane variability breakthroughs. Recalibration cycles align with material shifts in ECHA disclosure standards and IMO NOx Tier III implementation deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tricalcium Citrate Market
Additives
Viscosity Index Improvers Market
Additives
Europe UV Stabilizers Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Sorbitan Tristearate Market
Additives
Middle East Feed Additives Market
Additives
Sodium Caprylate Market
Additives
Gluconic Acid and Derivatives Market
Additives
Global Low-Profile Additive Market
Additives
Polysorbate-80 Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Dispersing Agents Market
Additives
Humectants Market
Additives
Global Cement and Concrete Additives Market
Additives
Sodium Diacetate Market
Additives
Global Butylated Hydroxytoluene Market