
 North America Fuel Additives Market | 2026-2036
North America Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fuel Additives Market Analytics
Market Context
Buyer concentration among fleet operators is shifting as large logistics consolidators centralize fuel procurement and additive specification decisions. The Lubrizol Corporation leverages its integrated supply chain to serve these consolidated buyers with tailored deposit control packages. Innospec Inc. differentiates through specialized cetane improver formulations for high-pressure common rail diesel systems. Afton Chemical Corporation anchors its position in the aviation fuels segment, where FAA certification requirements create substantial switching costs for refiners.
Technical Definition and Segments
Fuel additives comprise chemical compounds blended at parts-per-million to parts-per-thousand concentrations to enhance combustion efficiency, prevent engine deposits, and protect fuel system components from corrosion or wear. These formulations typically contain active ingredients such as polyether amines, alkyl nitrates, or fatty acid esters dissolved in hydrocarbon carrier fluids, serving primarily to meet OEM warranty requirements and regulatory emission limits while extending engine operational life. Deposit control additives occupy the largest value pool within the product type dimension, reflecting their critical role in maintaining fuel injector performance across direct-injection gasoline and diesel platforms. Aviation fuels represent the fastest-growing application segment, driven by rising commercial air traffic and the operational necessity of jet fuel thermal stability additives for long-haul routes. Bio-based formulations within the formulation type dimension command premium positioning as refiners respond to California LCFS credit incentives and federal renewable fuel obligations.
Regulatory Framework
EPA Tier 3 gasoline sulfur standards and CARB low-carbon fuel regulations in California shape additive demand by mandating cleaner combustion and enabling higher renewable content blending that requires stabilizing chemistry. The US FAA maintains strict jet fuel additive certification protocols through its Fuel System Icing Inhibitor and static dissipator requirements, creating regulated entry barriers for suppliers. Stakeholders must monitor the trajectory of EPA heavy-duty vehicle emission standards and state-level clean fuel programs to anticipate reformulation cycles and qualification investments.
Market Dynamics
Fleet operator consolidation across the United States and Canada is concentrating additive specification authority into fewer procurement centers, forcing suppliers to restructure account management and technical service deployment around large logistics consolidators rather than dispersed regional buyers.
Growth Catalysts
- EPA Tier 3 sulfur standards:Refiners require deposit control additives to maintain combustion efficiency in ultra-low sulfur gasoline formulations, expanding precision dosing infrastructure across the US Gulf Coast.
- Direct-injection gasoline engines:Automaker warranty requirements mandate polyether amine-based injector cleaners, creating specification pull from Detroit and Ontario vehicle assembly corridors.
- California LCFS credit mechanisms:Bio-based additive formulations qualify for low-carbon fuel credits, incentivizing refiners to reformulate stabilizing chemistry for higher renewable content blends.
Market Restraints
- Alkyl nitrate feedstock volatility:Cetane improver manufacturers face margin compression from nitration-grade hydrocarbon supply fluctuations tied to Gulf Coast petrochemical outages.
- FAA certification timelines:Jet fuel additive qualification protocols extend 18-24 months, freezing supplier switching and entrenching incumbents in aviation thermal stability segments.
- Electrification substitution:Battery-electric commercial vehicle pilots in California and Quebec threaten long-term diesel additive demand in urban freight corridors.
Strategic Opportunities
- Mexico refining expansion:Pemex's Dos Bocas facility startup creates additive specification openings for deposit control and corrosion inhibitor suppliers serving new heavy crude processing units.
- Sustainable aviation fuel blending:FAA-approved synthetic paraffinic kerosene requires novel thermal stability chemistry, opening formulation development partnerships with US biofuel producers.
- Common rail diesel proliferation:High-pressure injection systems in Canadian mining and US agricultural equipment demand specialized cetane improvers with enhanced lubricity profiles.
Industry Challenges
- Formulation chemist scarcity:Gulf Coast additive laboratories compete for talent with broader specialty chemical sectors, extending product development cycles for customized refinery packages.
- Multi-jurisdictional compliance:Suppliers must simultaneously satisfy EPA registration requirements, California CARB approvals, and Canadian PMRA standards for cross-border fuel movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fuel Additives Market |
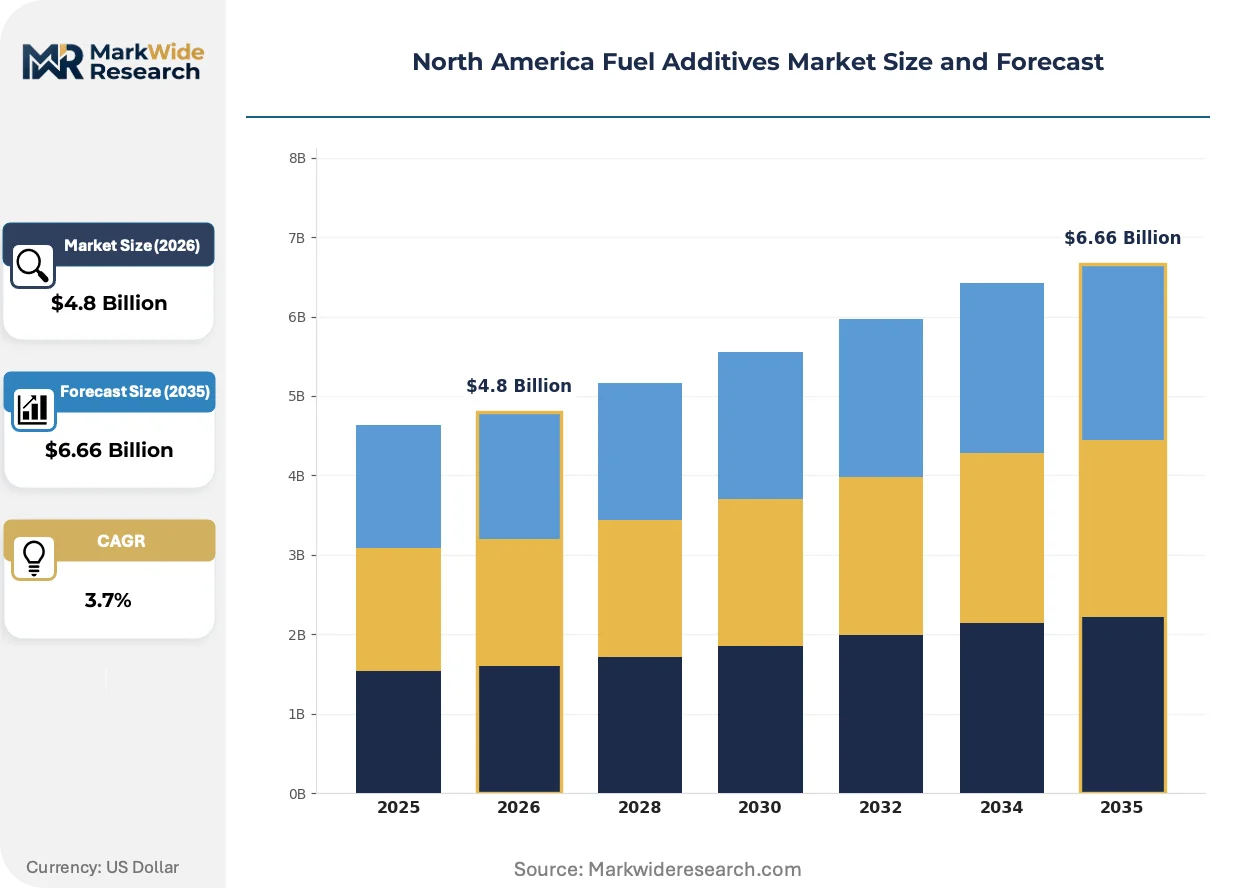
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deposit Control, Cetane Improvers, Lubricity Agents, Corrosion Inhibitors Application: Automotive Fuels, Aviation Fuels, Marine Fuels, Industrial Fuels End User: Refineries, OEMs, Fleet Operators, Distributors Formulation Type: Liquid Additives, Solid Additives, Concentrates, Bio-Based Additives |
| Companies Covered | The Lubrizol Corporation, Infineum International Limited, Innospec Inc., Evonik Industries AG, Baker Hughes Company, Chevron Oronite Company LLC, BASF SE, LANXESS AG, Afton Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fuel Additives Market Evolving Landscape
Digital dosing systems and predictive analytics are transforming how refiners manage additive injection, compressing the gap between laboratory formulation and real-time blend optimization.
Polyether amine detergent chemistry is converging with machine learning-driven injection control. US Gulf Coast refiners deploy sensor networks that adjust deposit control additive rates based on real-time fuel quality telemetry. This convergence is compressing the traditional specification cycle between additive suppliers and blend operators from quarterly reviews to continuous optimization protocols.
California's LCFS credit trading system tightens carbon intensity benchmarks biennially. Refiners reformulate gasoline and diesel additives to enable higher ethanol and renewable diesel blending without phase separation or oxidation instability. The bio-based additive segment responds fastest, with fatty acid ester stabilizers capturing credit-eligible volume in West Coast markets.
Logistics consolidators now centralize fuel procurement across multi-state fleets. Large trucking operators in the US Midwest negotiate directly with additive suppliers for tailored cetane improver and cold flow packages, bypassing traditional refinery-branded fuel programs. This concentration is most visible in Ohio and Illinois distribution hubs where fleet size thresholds trigger direct supplier relationships.
North America Fuel Additives Market Segmentation
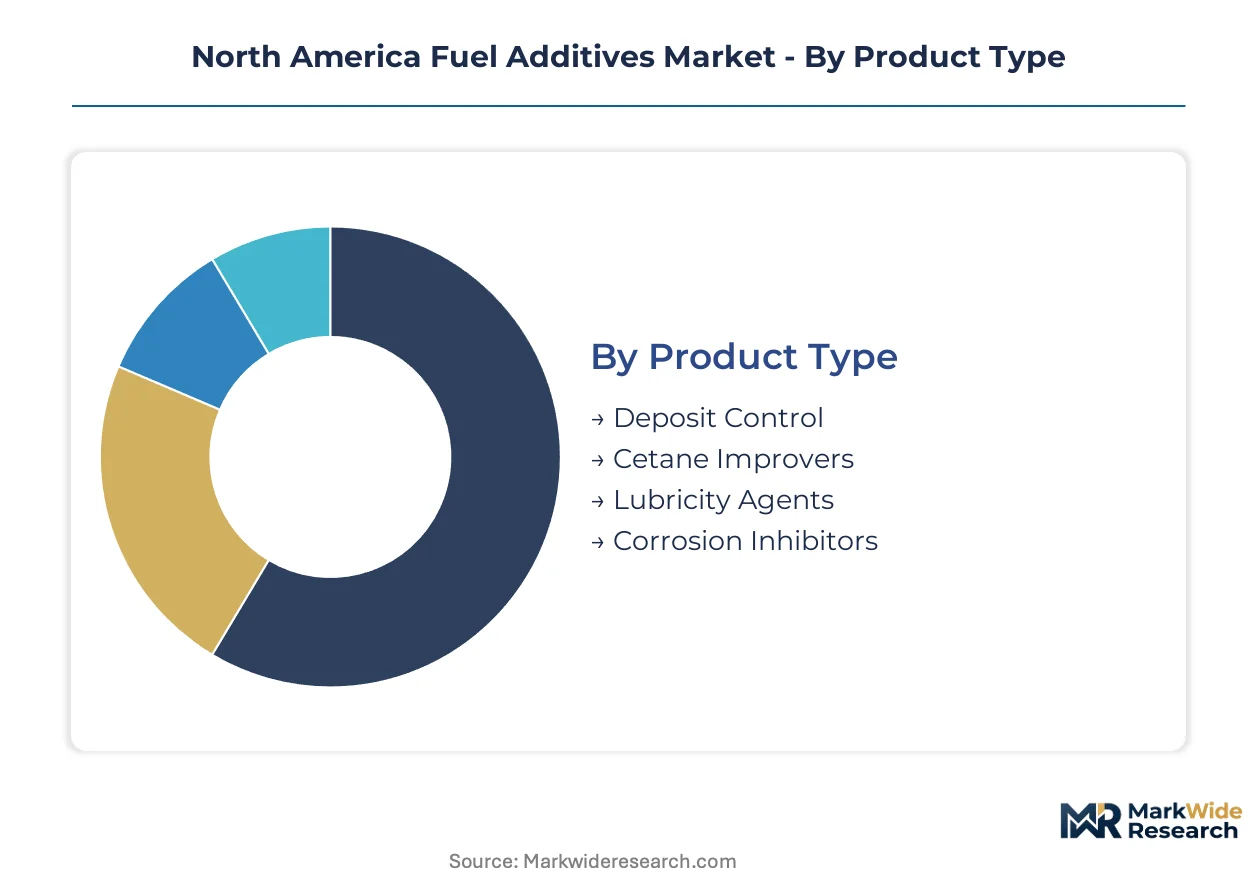
Fuel additive procurement patterns diverge sharply across customer types and fuel systems, with specification authority concentrating in fewer decision centers. Understanding these segment boundaries clarifies where formulation investments yield qualified volume versus commodity competition.
Product Type:
Refinery blending economics and engine technology roadmaps separate premium specification tiers from commodity additive categories.
- Deposit Control:Polyether amine-based detergent chemistry prevents injector fouling in direct-injection gasoline and high-pressure common rail diesel platforms. US Gulf Coast refiners deploy precision dosing infrastructure for ultra-low sulfur gasoline formulations, with EPA Tier 3 sulfur standards mandating cleaner combustion chemistry.
- Cetane Improvers:Alkyl nitrate compounds accelerate ignition quality in diesel fuels, critical for cold-start performance in Canadian mining equipment and US agricultural machinery. Demand concentrates where high-pressure injection systems require precise cetane number management to protect pump and injector longevity.
- Lubricity Agents:Fatty acid ester formulations restore lubricating properties to hydrotreated diesel streams stripped of natural sulfur compounds during desulfurization.
- Corrosion Inhibitors:Amine-based surface-active compounds protect fuel system metals from acidic condensation in ethanol-blended gasoline and biodiesel storage.
Volume sits with Deposit Control; growth tilts toward Cetane Improvers.
Application:
Operational severity and regulatory certification requirements create distinct margin profiles across fuel use cases.
- Automotive Fuels:Gasoline and diesel additives for light-duty and heavy-duty vehicles constitute the foundational demand pool. OEM warranty requirements in Detroit and Ontario assembly corridors mandate polyether amine injector cleaners as factory-fill and service-fill specifications.
- Aviation Fuels:Jet fuel thermal stability additives and static dissipators face FAA certification protocols extending 18-24 months, creating substantial switching costs for refiners serving commercial air traffic expansion on long-haul routes.
- Marine Fuels:Residual fuel treatments address combustion efficiency and emissions compliance for Great Lakes shipping and coastal vessel operators.
- Industrial Fuels:Power generation and heating oil applications require stability and combustion enhancement chemistry for stationary engine and boiler systems.
Automotive Fuels anchor current volume; Aviation Fuels present the steepest expansion trajectory.
End User:
Procurement centralization is reshaping which customer relationships command technical service investment and formulation customization.
- Refineries:Integrated oil companies and independent refiners specify additive packages during fuel blending operations, with CARB low-carbon fuel requirements in California driving reformulation for higher renewable content compatibility.
- OEMs:Vehicle and equipment manufacturers mandate additive specifications as warranty conditions, creating specification pull from assembly corridors in Michigan, Ohio, and Ontario.
- Fleet Operators:Large logistics consolidators in the US Midwest and Quebec now negotiate directly with additive suppliers for tailored cetane improver and cold flow packages, bypassing traditional refinery-branded fuel programs.
- Distributors:Terminal and rack operators blend additives into fuels for regional delivery, serving fragmented downstream customers without direct supplier relationships.
Refineries retain volume concentration; Fleet Operators are gaining share fastest in specification authority.
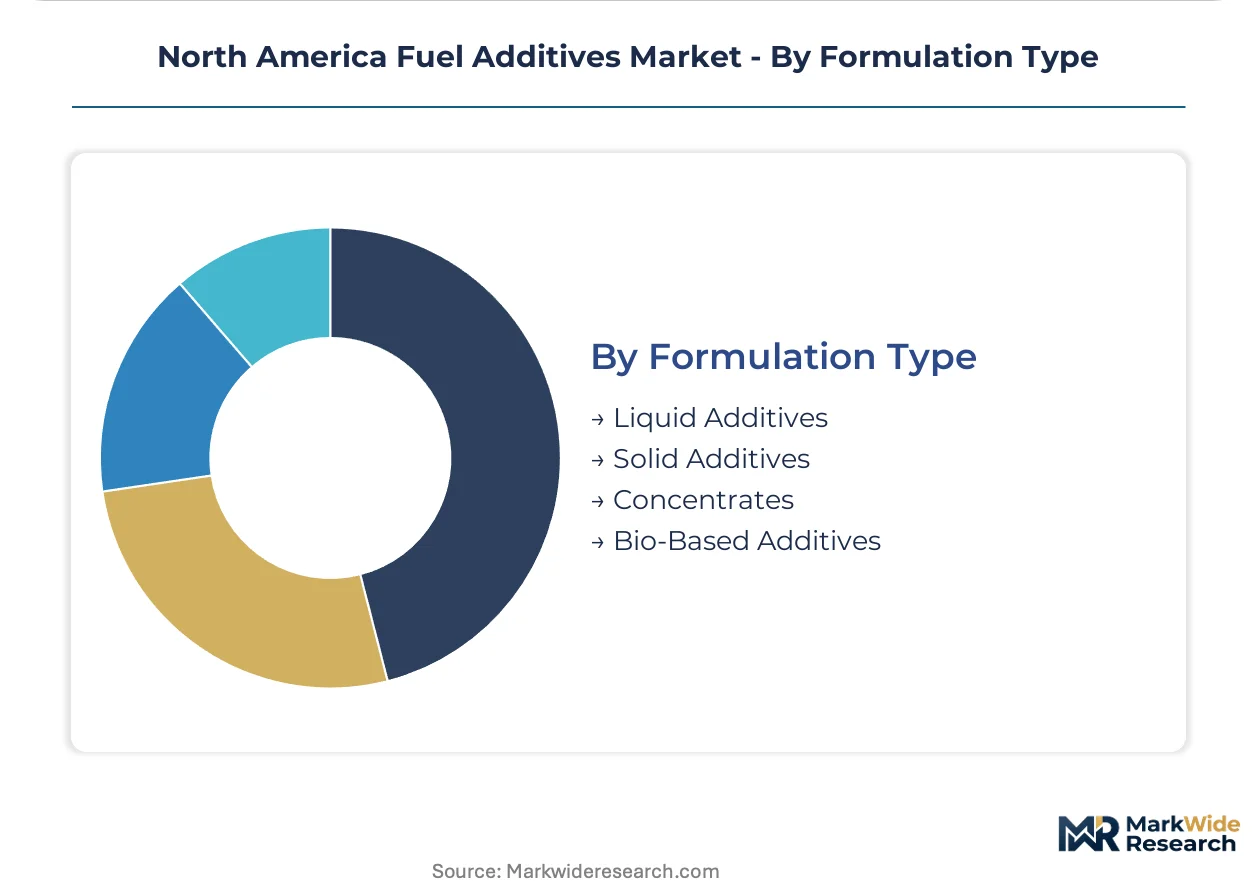
Formulation Type:
Physical state and feedstock origin determine handling infrastructure requirements and carbon intensity scoring eligibility.
- Liquid Additives:Hydrocarbon-dissolved formulations dominate refinery injection systems, with automated dosing skids and real-time blend optimization telemetry deployed across US Gulf Coast facilities.
- Bio-Based Additives:Fatty acid ester stabilizers and plant-derived detergents qualify for California LCFS credit mechanisms, capturing premium positioning as refiners reformulate for higher ethanol and renewable diesel blending without phase separation.
- Solid Additives:Powder or pellet forms serve specialized industrial applications and remote locations lacking liquid handling infrastructure.
- Concentrates:High-potency formulations reduce transportation costs and storage footprint for high-volume users with in-house dilution capability.
Liquid Additives dominate installed base; Bio-Based Additives climb the fastest on regulatory incentive alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along the US Gulf Coast anchors additive manufacturing infrastructure. Refinery concentration in Texas and Louisiana supports integrated supply chains for polyether amine and alkyl nitrate production. Cross-border fuel movements between the three North American economies create multi-jurisdictional formulation requirements.
United States
EPA Tier 3 sulfur standards mandate deposit control additive deployment across gasoline blending operations. The EPA maintains registration protocols for fuel additive chemistries used in interstate commerce. Houston and Beaumont refining corridors host precision dosing infrastructure serving ultra-low sulfur gasoline formulations.
Canada
Cold-start performance requirements in Alberta and Saskatchewan mining operations drive cetane improver consumption. Health Canada and PMRA regulate additive chemistries for cross-border fuel movements. Ontario's automotive assembly corridor in Windsor and Oshawa generates OEM warranty-driven specification pull for injector cleaners.
Mexico
Pemex's Dos Bocas refinery startup creates demand for heavy crude processing additives including deposit control and corrosion inhibitors. The country's energy regulator establishes fuel quality specifications for domestic consumption. Tabasco's refining expansion anchors new additive procurement relationships with international suppliers.
North America Fuel Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based formulation niches. The market exhibits moderate concentration with integrated petrochemical conglomerates holding refinery-facing positions alongside specialized additive houses. Three archetypes dominate: multinational chemical conglomerates with integrated supply chains, mid-sized specialty chemical firms with formulation expertise, and regional distributors with terminal blending capabilities. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the multinational tier, The Lubrizol Corporation and BASF SE exemplify integrated petrochemical positioning with refinery-direct relationships. Innospec Inc. occupies a specialist position emphasizing cetane improver chemistry for high-pressure diesel systems. Afton Chemical Corporation represents the certification-anchored archetype with aviation fuel additive qualifications.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Infineum International Limited |
| Innospec Inc. |
| Evonik Industries AG |
| Baker Hughes Company |
| Chevron Oronite Company LLC |
| BASF SE |
| LANXESS AG |
| Afton Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity along the US Gulf Coast compresses R&D cost differentials into premium-mid-economy pricing spreads. Labor-intensive polyether amine synthesis and alkyl nitrate production tether high-grade additive pricing to regional petrochemical talent pools.
Pricing Analysis
Volume concentrates in commodity deposit control packages while margin pools in FAA-certified aviation thermal stability formulations. Price differentiation rests on certification tier and customization depth, with CARB-compliant bio-based stabilizers commanding premiums over standard hydrocarbon carriers. Cost compression in cetane improvers intensifies because alkyl nitrate feedstock volatility squeezes mid-tier suppliers. Fleet operators in the US Midwest exhibit highest price sensitivity, negotiating direct supplier contracts, whereas aviation fuel refiners show lowest sensitivity due to FAA switching costs.
Supply Chain Analysis
Dual-sourcing requirements from US refiners mandate multi-supplier qualification for critical additives, fragmenting procurement across The Lubrizol Corporation, Innospec Inc., and Afton Chemical Corporation. Geographic supply concentration centers on the United States, Canada, and Mexico, with Gulf Coast petrochemical corridors feeding polyether amine and alkyl nitrate production. Raw material dependencies draw from nitration-grade hydrocarbons, fatty acid esters, and hydrocarbon carrier fluids. Single-source vulnerability persists in aviation thermal stability chemistry where FAA certification timelines freeze supplier switching. Distribution runs through refinery-direct injection systems and terminal rack blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward control over alkyl nitrate feedstock and captive polyether amine synthesis separates margin leaders from price-takers.
For Market Incumbents: Extend certification moats in aviation fuels while consolidating Gulf Coast formulation chemist talent pools. Battery-electric commercial vehicle pilots in California and Quebec threaten diesel additive demand, requiring incumbents to deepen bio-based additive R&D for renewable diesel compatibility. Capacity addition in Mexico's Dos Bocas corridor anchors regional supply security against Pemex procurement shifts. For New Entrants and Emerging Players: Machine learning-driven dosing optimization offers a technology-first wedge against legacy injection control systems. White-space targets include sustainable aviation fuel thermal stability partnerships with US biofuel producers and specialized cetane improvers for Canadian high-pressure mining equipment. Direct fleet operator relationships in Ohio and Illinois distribution hubs provide the most penetrable go-to-market angle, bypassing entrenched refinery channels. For Investors and Strategic Acquirers: The window for entry favors bio-based formulation specialists with California LCFS credit eligibility and FAA qualification pipelines. Long-term viability hinges on regulatory incentive alignment rather than commodity volume exposure. Acquisition targets should demonstrate dual capability in polyether amine chemistry and predictive analytics integration. The signal to watch is EPA heavy-duty vehicle emission standard trajectory, which would accelerate reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkyl Nitrate Feedstock | Captive nitration-grade hydrocarbon supply insulates cetane improver margins from Gulf Coast petrochemical outages. |
| FAA Certification Pipeline Investment | Jet fuel additive qualification protocols create 18-24 month switching costs that entrench aviation market share. |
| Bio-Based Formulation Scale-Up | California LCFS credit eligibility captures premium positioning in renewable diesel and ethanol blend stabilization. |
| Digital Dosing System Deployment | Sensor networks and predictive analytics compress specification cycles from quarterly reviews to continuous optimization. |
| Mexico Refinery Supply Agreement | Pemex Dos Bocas startup creates additive specification openings for heavy crude processing chemistry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with refinery blending managers, additive formulation chemists, fleet procurement directors, and FAA certification specialists combined with EPA registration databases, CARB approval records, and ACC industry reports. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from petrochemical production data and fuel consumption statistics.
Granularity-level modeling deployed separate forecasts for deposit control, cetane improvers, lubricity agents, and corrosion inhibitors by automotive, aviation, marine, and industrial applications. CAGRs derived from regression analysis of historical additive intensity per fuel volume, regulatory mandate implementation schedules, and OEM warranty specification trends. Industry-specific inputs included EPA Tier 3 sulfur standard compliance timelines and California LCFS credit trading volume projections.
Several conditions sit outside the modeled scope, including abrupt electrification acceleration in commercial vehicle segments and unilateral tariff disruptions on Gulf Coast petrochemical feedstock imports. Forecasts reflect assumptions about regulatory implementation pacing and OEM specification stability. Deviation in FAA certification timeline compression or EPA heavy-duty emission standard stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Crystal Growth Modifier Market
Additives
Global Asphalt Additives Market
Additives
Guanylic Acid Market
Additives
Chemical Silage Additives Market
Additives
Hydroxyethyl Cellulose Market
Additives
Feedstuff Additives Market
Additives
Inhibited Propylene Glycol Market
Additives
Antimicrobial Ingredients Market
Additives
Humectants Market
Additives
Plastic Additives Market
Additives
Organic Friction Modifier Additives Market
Additives
Calcium Stearate Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Ascorbyl Stearate Market
Additives
Plasticizer Alcohols Market