
 China Sodium Reduction Ingredient Market | 2026-2036
China Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
China Sodium Reduction Ingredient Market Outlook
Chinese yeast extract producers is broadening output of umami-rich sodium reduction bases to serve condiment and snack makers. Fufeng Group leverages its fermentation scale to supply amino acid-derived flavor enhancers across domestic food processing corridors. Angel Yeast Co. Ltd anchors its position through integrated yeast biotechnology that sustains consistent batch quality for industrial buyers. Cargill competes with imported potassium chloride and blended salt systems tailored to regional taste profiles.
Sodium reduction ingredients comprise functional compounds that replicate or amplify salty taste perception while lowering sodium chloride content, typically formulated through potassium salt blends, yeast extracts, or nucleotide-enhanced systems operating at sodium reductions of 25-50 percent without sensory loss. Their primary purpose is enabling food manufacturers to meet reformulation targets while preserving consumer acceptance of processed foods, bakery items, and savory sauces. Mineral salts currently lead product type value generation due to potassium chloride's cost position and technical familiarity among Chinese formulators, though natural extracts are gaining fastest traction as clean-label expectations intensify among premium sauce and snack brands. Powder form dominates institutional procurement channels, while liquid concentrates are expanding in ready-meal and restaurant applications where dosing precision and dissolution speed matter.
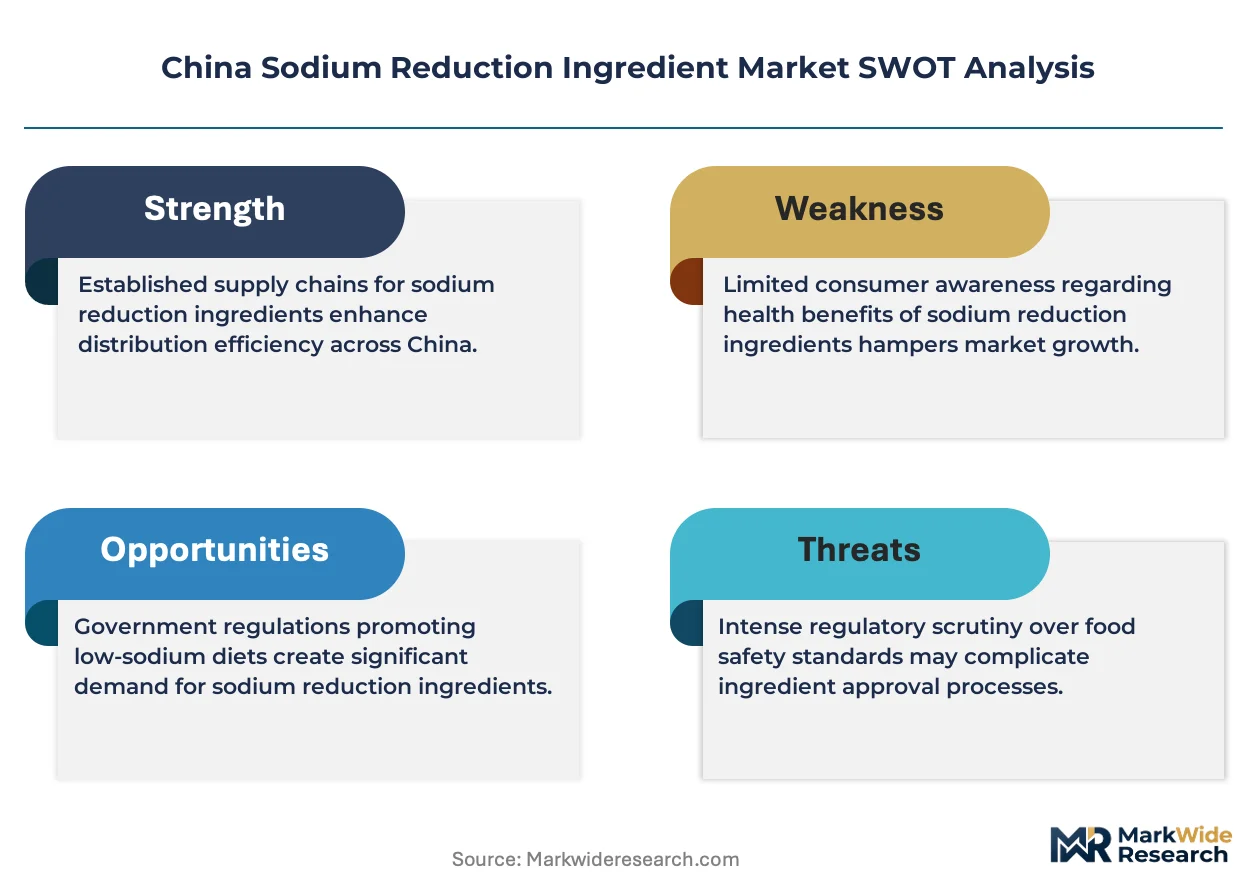
SAMR enforces GB standards on sodium content claims and additive usage limits, compelling reformulation investments from national food manufacturers. NHC dietary guidelines and provincial CDC campaigns amplify consumer awareness, indirectly pressuring restaurants and retailers to source lower-sodium inputs. The dual carbon goals framework from MEE also shapes supplier selection, as energy-intensive mineral salt refining faces emissions scrutiny. Stakeholders must monitor evolving GB standard revisions and provincial enforcement intensity to align R&D pipelines with compliance timelines.
Market Dynamics
GB standards tightening from SAMR and NHC dietary guideline revisions are compelling nationwide reformulation investments, reshaping procurement patterns across coastal processing clusters and interior provinces alike.
Growth Catalysts
- Dual carbon goals framework:MEE emissions scrutiny on energy-intensive mineral salt refining accelerates supplier transitions toward cleaner yeast extract and fermentation-based alternatives.
- Coastal processing concentration:Jiangsu and Zhejiang province clusters generate concentrated demand pull as packaged food manufacturers accelerate sodium reduction programs.
- GB labeling mandates:SAMR enforcement of sodium content claim standards creates compliance-driven procurement of potassium chloride blends and nucleotide-enhanced systems.
Market Restraints
- Potassium chloride cost volatility:Imported mineral salt feedstock exposes formulators to currency and shipping cost swings that compress margin predictability.
- Fermentation capacity concentration:Yeast extract supply concentrates among three domestic producers, creating bottleneck risk for clean-label sourcing.
- Sensory replication ceiling:Current amino acid-derived enhancers hit technical limits below 50 percent sodium reduction in premium sauce applications.
Strategic Opportunities
- Interior province penetration:Sichuan and Hunan processed food corridors remain underpenetrated for industrial sodium reduction ingredient supply.
- Ready-meal channel expansion:Liquid concentrate formats gain traction in restaurant and central kitchen applications requiring precise dosing.
- Clean-label premium tier:Natural extract positioning aligns with provincial CDC health campaigns amplifying consumer awareness.
Industry Challenges
- Reformulation talent scarcity:Food science professionals with dual competence in sensory science and regulatory compliance command premium compensation.
- Batch consistency certification:Industrial buyers demand documented quality variance below 2 percent across yeast extract shipments.
- Legacy equipment retrofit costs:Powder-to-liquid handling system upgrades strain capex budgets for mid-tier condiment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sodium Reduction Ingredient Market |
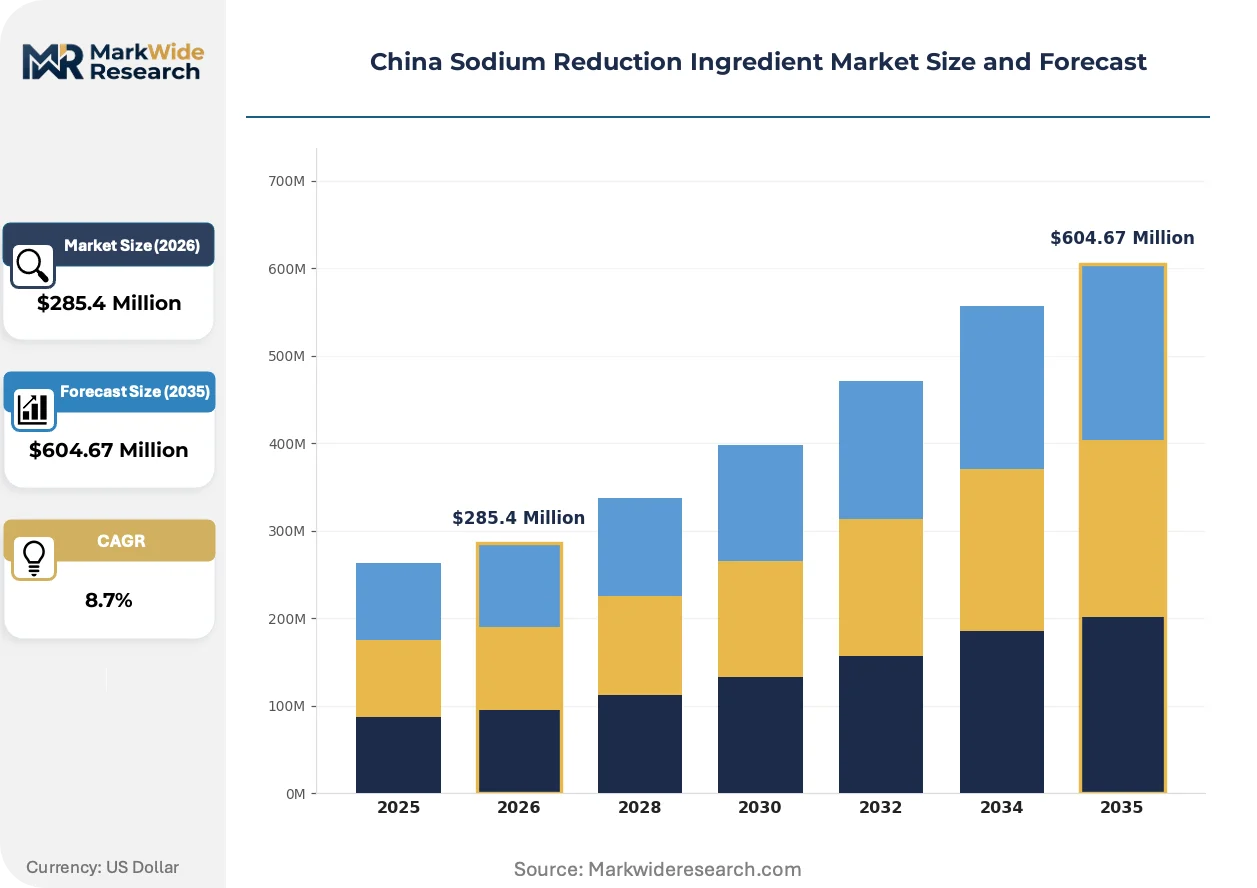
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Natural Extracts, Mineral Salts Application: Food Processing, Bakery, Snacks, Sauces Form: Powder, Granules, Liquid, Blends End User: Food Manufacturers, Restaurants, Retailers, Home Cooks |
| Companies Covered | Koninklijke DSM NV, Fufeng Group, Angel Yeast Co. Ltd, Cargill, Kerry Group, Givaudan, Tate & Lyle PLC, Jungbunzlauer, Corbion NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sodium Reduction Ingredient Market Strategic Shifts
Yeast biotechnology and fermentation scale-up are compressing cost curves for clean-label sodium reduction, while regulatory labeling mandates and procurement centralization reshape competitive positioning across China's food processing corridors.
Fermentation-derived umami base technology is modularizing. Yeast extract producers deploy standardized bioreactor platforms that swap strain inputs without retooling. Angel Yeast and Fufeng Group deploy these systems across Jiangsu and Hubei facilities. Modularization enables rapid product line expansion from nucleotide-enhanced to peptide-rich variants without greenfield capex.
SAMR's GB standards for sodium content claims and additive usage limits are tightening enforcement timelines. National food manufacturers face compressed reformulation windows to avoid label restrictions. Premium sauce and snack brands in Zhejiang are accelerating clean-label transitions to preempt compliance deadlines.
Buyer consolidation among national retail chains is centralizing sodium reduction ingredient procurement. Walmart China and Yonghui Superstores negotiate direct supply agreements with yeast extract producers, bypassing traditional distributor tiers. This concentration is most visible in Shanghai and Beijing metropolitan procurement corridors.
China Sodium Reduction Ingredient Market Segmentation
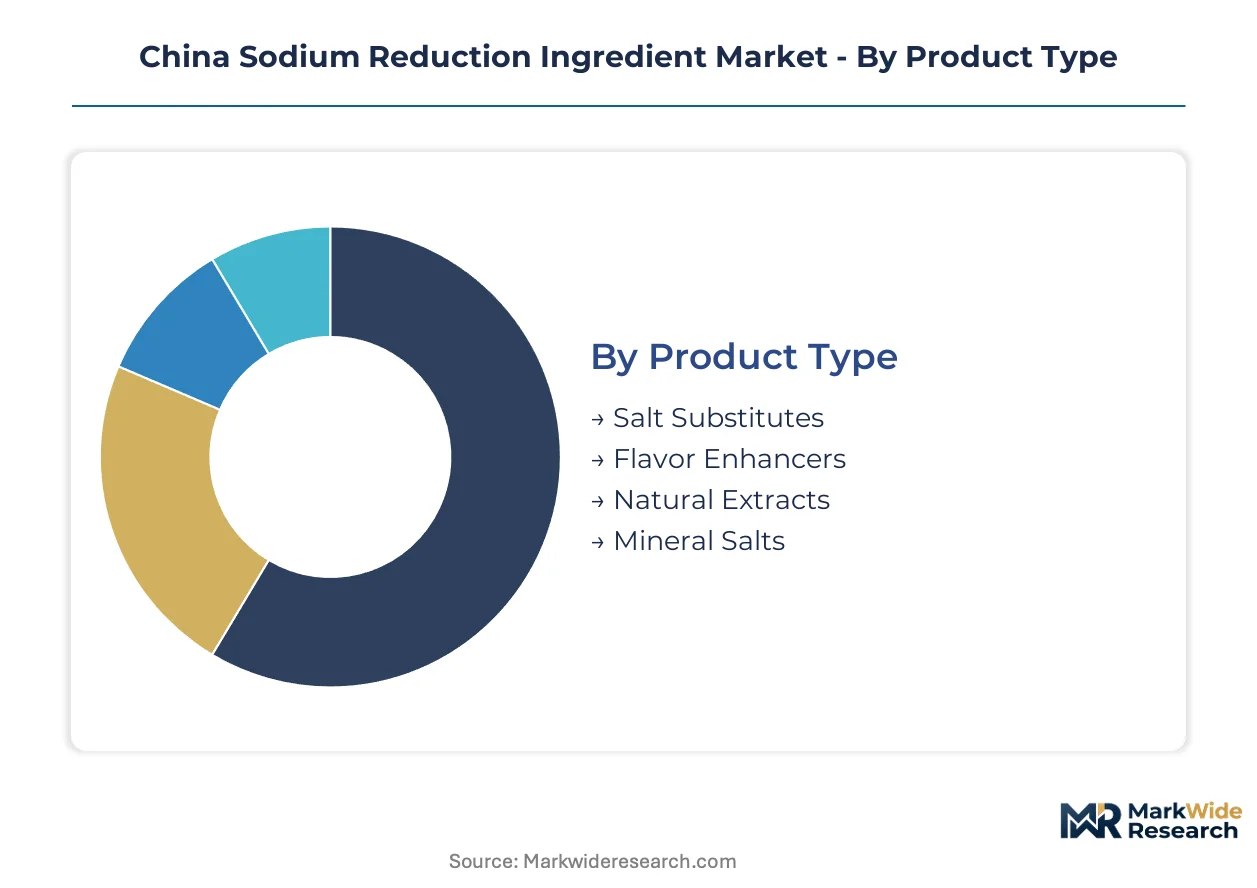
Segmentation in China's sodium reduction ingredient market reveals distinct procurement patterns across coastal processing clusters and interior provinces. Reformulation timelines from SAMR's GB standards create divergent demand profiles by product type and end-use channel.
Product Type:
Integration depth varies sharply: mineral salts and salt substitutes function as standalone drop-in replacements, while flavor enhancers and natural extracts embed within complex seasoning systems requiring co-development with formulators.
- Mineral Salts:Potassium chloride blends dominate institutional procurement for their cost position and technical familiarity among Jiangsu and Zhejiang formulators. Sodium reduction ceilings of 25-40 percent apply before bitter off-notes emerge in premium applications.
- Flavor Enhancers:Yeast extract and nucleotide-enhanced systems embed directly into sauce and snack seasoning matrices. Coastal manufacturers in Ningbo and Qingdao specify these for 35-50 percent sodium reduction targets where clean-label positioning commands procurement priority.
- Natural Extracts:Mushroom and seaweed-derived umami bases serve premium condiment brands responding to provincial CDC health campaigns.
- Salt Substitutes:Blended potassium-magnesium formulations target mid-tier bakery and processed meat segments seeking compliance-driven reformulation.
Mineral salts lead volumes today; natural extracts are gaining share fastest.
Application:
Cost tier stratification separates high-volume commodity reformulation from premium positioning plays across China's food processing corridors.
- Food Processing:Industrial meat and ready-meal manufacturers in Shandong province drive bulk procurement of powder-form mineral salts for standardized sodium reduction across product lines.
- Sauces:Zhejiang and Guangdong condiment makers specify liquid yeast extract concentrates for precise dosing in soy sauce and oyster sauce reformulations where sensory fidelity determines shelf placement.
- Snacks:Peptide-enhanced systems from Angel Yeast supply Fujian and Anhui chip and cracker producers targeting 30 percent sodium reduction without flavor degradation.
- Bakery:Potassium chloride blends face technical limits in yeast-leavened applications, constraining penetration in Shanghai and Beijing artisanal segments.
Sauce applications command premium pricing; snack reformulation is expanding most quickly.
Form:
Customer type dictates format selection: powder and granules serve food manufacturers with established handling infrastructure, while liquid and pre-blended formats target restaurants and central kitchens lacking reformulation expertise.
- Powder:Dominates Jiangsu and Zhejiang procurement channels where pneumatic conveying systems and batch mixing equipment support high-volume mineral salt integration.
- Liquid:Concentrates gain traction in Guangzhou and Chengdu restaurant supply chains where pump dosing and rapid dissolution reduce kitchen labor.
- Granules:Free-flowing potassium salt formulations suit automated seasoning deposition on snack production lines in Anhui and Henan.
- Blends:Pre-formulated salt-replacement systems target mid-tier condiment manufacturers lacking in-house sensory science capabilities.
Powder form anchors procurement volumes; liquid concentrates show steepest expansion trajectory.
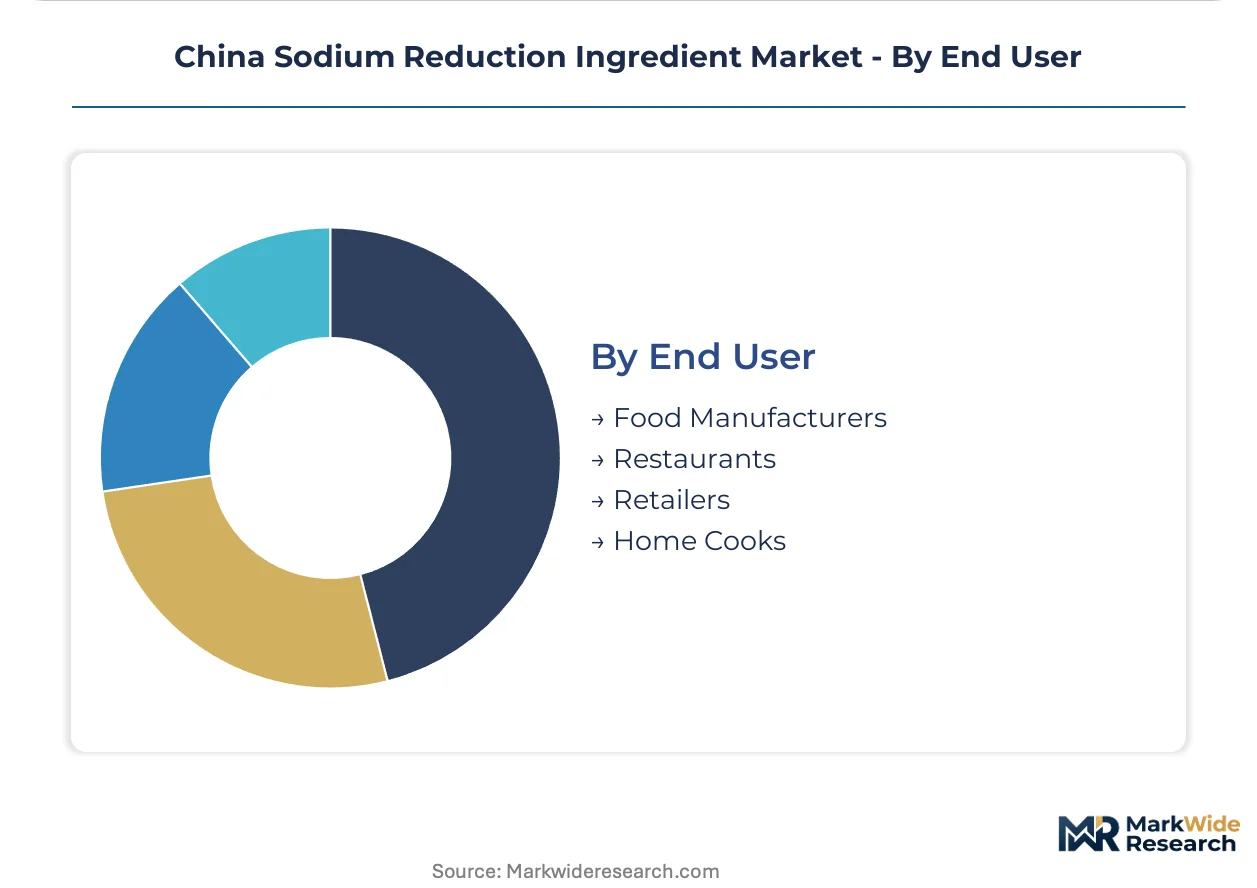
End User:
Supply concentration shapes access patterns: food manufacturers source direct from fermentation producers, while downstream channels fragment through distributor tiers.
- Food Manufacturers:National brands in Tingyi and Master Kong's supply chains negotiate direct agreements with Fufeng Group and Angel Yeast for captive yeast extract supply.
- Restaurants:Central kitchen operators in Beijing and Shanghai metropolitan corridors specify liquid concentrate formats for consistent sodium reduction across franchise locations.
- Retailers:Walmart China and Yonghui Superstores consolidate procurement of clean-label sodium reduction ingredients for private-label development.
- Home Cooks:Consumer-packaged salt substitutes remain underdeveloped relative to industrial channels, with limited penetration beyond tier-one city health-conscious segments.
Food manufacturers dominate procurement volumes; restaurant channel sourcing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reformulation cost differentials between coastal and interior provinces are redirecting procurement flows. SAMR enforcement intensity varies by province, creating compliance arbitrage that shapes supplier location decisions. Processing clusters migrate toward jurisdictions with clearer regulatory interpretation timelines.
Jiangsu
Nanjing and Suzhou food manufacturers drive yeast extract demand for premium sauce reformulation. Provincial CDC campaigns amplify consumer sodium awareness, pressuring Tingyi and Master Kong supply chains. Nantong's condiment corridor concentrates liquid concentrate procurement for precise dosing applications.
Zhejiang
Hangzhou and Ningbo snack producers specify nucleotide-enhanced systems for 30-40 percent sodium reduction targets. SAMR's GB labeling mandates compress reformulation windows for export-oriented brands. Shaoxing's traditional sauce makers face dual pressure from heritage positioning and clean-label expectations.
Shandong
Qingdao and Weifang meat processors anchor bulk mineral salt procurement for standardized product lines. MEE emissions scrutiny redirects supplier selection toward fermentation-based alternatives. Yantai's ready-meal manufacturers test liquid concentrate formats for central kitchen integration.
Guangdong
Guangzhou and Shenzhen restaurant chains specify pump-dosing systems for franchise consistency. Provincial health commission guidelines outpace national NHC timelines, accelerating procurement decisions. Foshan's soy sauce heritage producers balance traditional fermentation with sodium reduction requirements.
Sichuan
Chengdu's processed food corridor remains underpenetrated for industrial sodium reduction supply. Chongqing hotpot base manufacturers experiment with umami-rich yeast extracts to preserve mala profiles. Provincial CDC campaigns lag coastal intensity, delaying consumer-driven demand acceleration.
China Sodium Reduction Ingredient Market Competitive Environment
Chinese fermentation specialists anchor domestic supply tiers; multinational ingredient houses hold import-dependent positions. Market structure bifurcates between three domestic yeast extract producers and mineral salt traders facing feedstock volatility. Archetypes include integrated biotech platforms, commodity mineral salt blenders, and flavor system integrators. Capacity expansion and direct retail procurement agreements constitute dominant competitive moves.
Among domestic producers, Fufeng Group, Angel Yeast Co. Ltd, and Cargill occupy positions across the technology spectrum. Fufeng Group represents scale-driven fermentation capacity. Angel Yeast Co. Ltd exemplifies integrated biotechnology platforms. Cargill anchors imported mineral salt and blended system supply. These three names illustrate how supplier selection stratifies between captive fermentation supply and traded commodity inputs.
| Leading Market Players |
|---|
| Koninklijke DSM NV |
| Fufeng Group |
| Angel Yeast Co. Ltd |
| Cargill |
| Kerry Group |
| Givaudan |
| Tate & Lyle PLC |
| Jungbunzlauer |
| Corbion NV |
| Others |
Value Chain & Pricing Dynamics
Potassium chloride import costs from Chile and Canada cascade through three pricing tiers before reaching Jiangsu formulators, with currency hedging and bulk contracting separating multinational blenders from domestic traders absorbing spot volatility.
Pricing Analysis
Distributor margin compression defines the channel structure, with direct-to-manufacturer agreements from Angel Yeast and Fufeng Group bypassing traditional two-tier markups. Three-tier pricing structure across premium, standard, and economy levels separates nucleotide-enhanced yeast extracts from commodity potassium blends. Pricing pressure stems from MEE emissions scrutiny elevating cleaner fermentation alternatives. Mid-tier condiment manufacturers exhibit highest price sensitivity due to legacy equipment retrofit burdens.
Supply Chain Analysis
Freight cost differentials between coastal ports and interior provinces concentrate supply planning around Ningbo and Qingdao entry points. Domestic production draws from fermentation capacity in Hubei and Jiangsu, while mineral salt feedstock sources from Chile, Canada, and Belarus. Single-source vulnerability concentrates in yeast extract supply among three domestic producers. Distribution runs through food manufacturer procurement departments and central kitchen operators, with retail chain direct agreements bypassing distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's sodium reduction ingredient market reads as a late-cycle quality story where coastal sauce manufacturers trade up to nucleotide-enhanced systems ahead of SAMR compliance deadlines.
For Market Incumbents: Lock in captive supply relationships with Tingyi and Master Kong through dedicated fermentation capacity in Hubei. Deepen backward integration into yeast strain development to offset mineral salt price volatility. Anchor positioning through batch consistency certification below 2 percent variance to defend against emerging biotech entrants.
For New Entrants and Emerging Players: Launch via liquid concentrate formats targeting Chengdu and Chongqing central kitchens where pump-dosing infrastructure gaps create white-space. Penetrate Sichuan's underdeveloped processed food corridor before coastal saturation intensifies. Position around umami-rich mala profile preservation for hotpot base manufacturers.
For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation capacity concentration meets provincial CDC campaign acceleration. Five-to-ten year viability favors integrated biotech platforms with modular bioreactor deployment capability. Target acquisition archetype: mid-scale yeast extract producers with SAMR pre-certification and Jiangsu-Zhejiang customer relationships. Signal to watch: Yonghui Superstores and Walmart China expanding direct procurement agreements beyond current three domestic suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Bioreactor Deployment | Angel Yeast and Fufeng Group swap strain inputs without greenfield capex across Jiangsu facilities. |
| Direct Retail Procurement Agreements | Walmart China and Yonghui Superstores bypass distributor tiers for clean-label ingredient sourcing. |
| GB Standard Pre-Compliance Certification | Premium Zhejiang sauce brands accelerate reformulation to preempt SAMR enforcement timelines. |
| Liquid Concentrate Format Expansion | Guangzhou and Chengdu restaurant chains adopt pump-dosing systems for franchise consistency. |
| Potassium Chloride Cost Hedging | Mineral salt blenders secure long-term offtake from Chilean and Canadian suppliers to stabilize margins. |
Study Parameters
Multiple input streams — primary interviews with fermentation plant managers, SAMR regulatory affairs specialists, and condiment manufacturer procurement leads; secondary validation through customs trade data, NHC dietary guideline publications, and GB standard revision notices; plus SEC filings from multinational ingredient houses — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from yeast extract producers and mineral salt distributors across the projection horizon. Segmentation dimensions modeled include product type tier, application channel, form factor, and end-user procurement concentration. CAGRs were derived from shipment volume reconciliation and pricing trend extrapolation, with specific inputs from MEE emissions policy timelines and provincial CDC campaign intensity indices.
Several conditions sit outside the modeled scope, including potential GB standard revision delays, abrupt potassium chloride trade flow disruptions, and unanticipated breakthroughs in peptide-based sodium replacement technology. Forecasts reflect documented assumptions about SAMR enforcement consistency and coastal-interior demand convergence. Stakeholders should weight assumptions against their own operating context and regional regulatory interpretation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Calcium Acetate Market
Additives
Global Isosorbide Market
Additives
Fluoropolymer Additives Market
Additives
Calcium Stearate Market
Additives
Benzoates Market
Additives
Iso-Butyric Acid Market
Additives
Packaging Coating Additives Market
Additives
Ethoxyquin Market
Additives
Supplemental Coolant Additives Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Chelating Agents Market
Additives
Polyethylene Terephthalate Additives Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Global UV Absorbers Market
Additives
Global Sodium Acetate Market