
 Lubricant Additives Market | 2026-2036
Lubricant Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricant Additives Market Intelligence
API Group III and above base oil compatibility is collapsing the historical price premium between mineral-derived and synthetic additive packages. The Lubrizol Corporation leverages its captive polymer research to dominate viscosity modifier supply for high-performance engine oils. BASF SE anchors its position through backward integration into detergent chemistry, while Infineum International Limited competes on formulation breadth across passenger car and heavy-duty segments.
Lubricant additives are chemical compounds blended at concentrations of 0.1% to 30% by weight into base oils to impart oxidation stability, friction reduction, deposit control, and corrosion protection for mechanical systems operating under thermal and mechanical stress. Viscosity Index Improvers command the largest revenue share due to their irreplaceable role in multigrade engine oils across temperature extremes. Anti-wear agents represent the fastest-expanding product category as electric vehicle gearboxes and industrial precision machinery impose novel tribological demands. Engine oils retain the dominant application position, though metalworking fluids are gaining formulation complexity from advanced machining alloys.
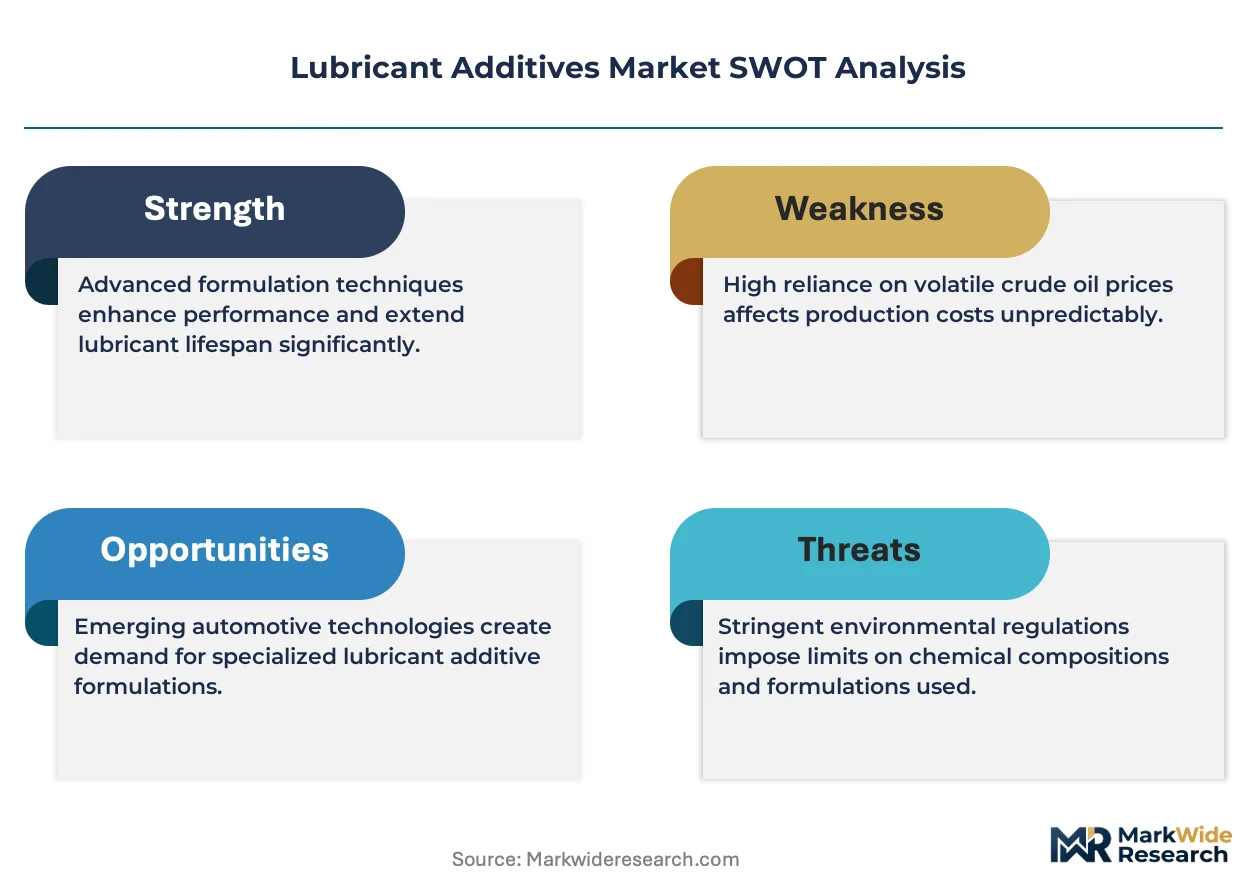
EPA emission mandates and ACEA oil sequences in North America, REACH chemical registration in Europe, and GB standards administered by SAMR in China collectively tighten permissible sulfur, phosphorus, and ash content in finished lubricants. These frameworks force additive suppliers to reformulate detergents and anti-wear chemistries without sacrificing performance, raising R&D barriers for non-integrated competitors. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's industrial decarbonization timelines redirect base oil sourcing and additive biodegradability requirements.
Market Dynamics
API Group III and above base oil compatibility is collapsing the historical price premium between mineral-derived and synthetic additive packages, forcing reformulation investments across the supply base.
Growth Catalysts
- EPA fuel economy standards:Stricter Corporate Average Fuel Economy mandates in the United States are concentrating demand for friction-modifying additives in passenger car motor oils.
- China's dual carbon goals:National decarbonization targets are redirecting base oil sourcing and raising biodegradability requirements for metalworking fluid additives.
- Electric vehicle gearboxes:Novel tribological demands from e-axle lubrication systems are pulling specialized anti-wear chemistries into high-volume production.
Market Restraints
- Phosphorus supply volatility:Anti-wear agent production depends on phosphate rock processing concentrated in Morocco and China, creating input cost instability.
- REACH chemical registration:European Union substance evaluation timelines extend 18-36 months for novel detergent chemistry, delaying market entry.
- Group II base oil substitution:Lower-tier mineral oils in price-sensitive industrial segments are displacing additive-intensive synthetic formulations in emerging markets.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced manufacturing are creating localized demand for high-performance engine oil additives.
- EU Green Deal industrial decarbonization:Timeline mandates for carbon-intensive process industries are opening biodegradable hydraulic fluid additive specifications.
- Direct-to-blender digital platforms:E-procurement channels are disintermediating traditional distributor networks for mid-volume lubricant compounders.
Industry Challenges
- Tribochemistry specialization gap:Formulation chemists with combined polymer and surface science expertise remain scarce across the additive supply base.
- ACEA sequence certification timelines:European Automobile Manufacturers Association engine test validation requires 24-30 months for new viscosity modifier platforms.
- Legacy ERP integration:Batch traceability requirements under China's GB standards are forcing costly system upgrades at regional blending facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricant Additives Market |
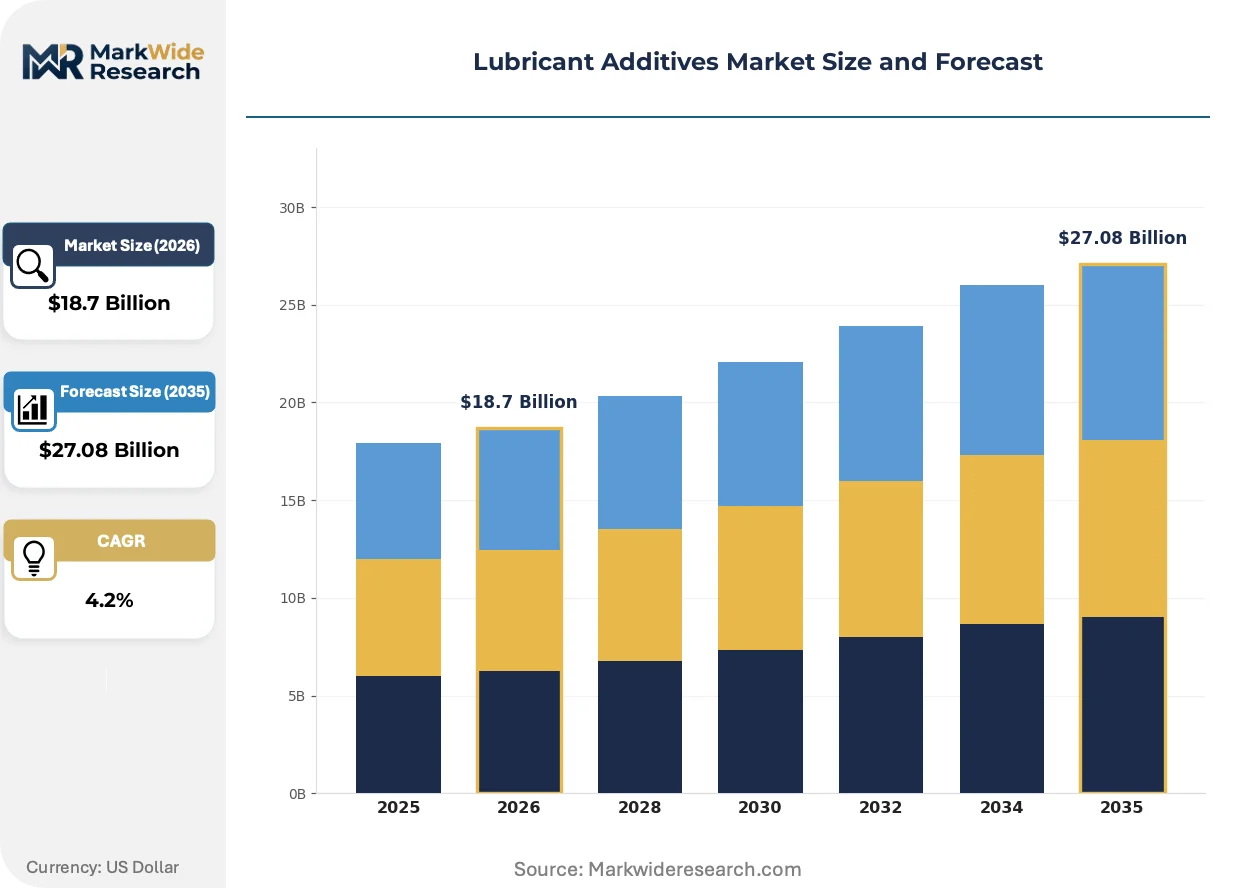
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscosity Index Improvers, Detergents, Antioxidants, Anti-wear Agents End User: Automotive Sector, Industrial Machinery, Marine Applications, Aerospace Application: Engine Oils, Gear Oils, Hydraulic Fluids, Metalworking Fluids Form: Liquid, Powder, Granules, Dispersion |
| Companies Covered | The Lubrizol Corporation, BASF SE, Afton Chemical, Chevron Oronite Company LLC, Infineum International Limited, Evonik Industries AG, LANXESS, Croda International plc, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricant Additives Market Strategic Shifts & Innovations
Polymer architecture advances and regulatory chemistry constraints are actively reshaping how additive suppliers design performance packages for next-generation lubricant specifications.
Star-branched polymethacrylate viscosity index improvers deliver superior shear stability compared to conventional linear polymers in heavy-duty diesel engine oils. Fleet operators in North America are accelerating adoption to extend drain intervals under severe operating conditions. This molecular architecture is supplanting older OCP-based thickeners in premium multigrade formulations.
REACH authorization requirements for zinc dialkyldithiophosphates are tightening permissible sulfur and phosphorus thresholds in European passenger car motor oils. Additive suppliers are reformulating anti-wear packages with alternative chemistries like ashless phosphorus esters and boron compounds. The heavy-duty segment faces the steepest compliance costs as legacy formulations lose regulatory clearance.
Integrated supply contracts linking additive suppliers directly to original equipment manufacturer technical centers are compressing traditional specification cycles. Lubricant blenders in Germany and Japan are bypassing conventional distributor networks for co-development agreements on factory-fill products. This channel consolidation is most visible in the electric vehicle drivetrain segment where OEMs specify proprietary e-fluids.
Lubricant Additives Market Segmentation
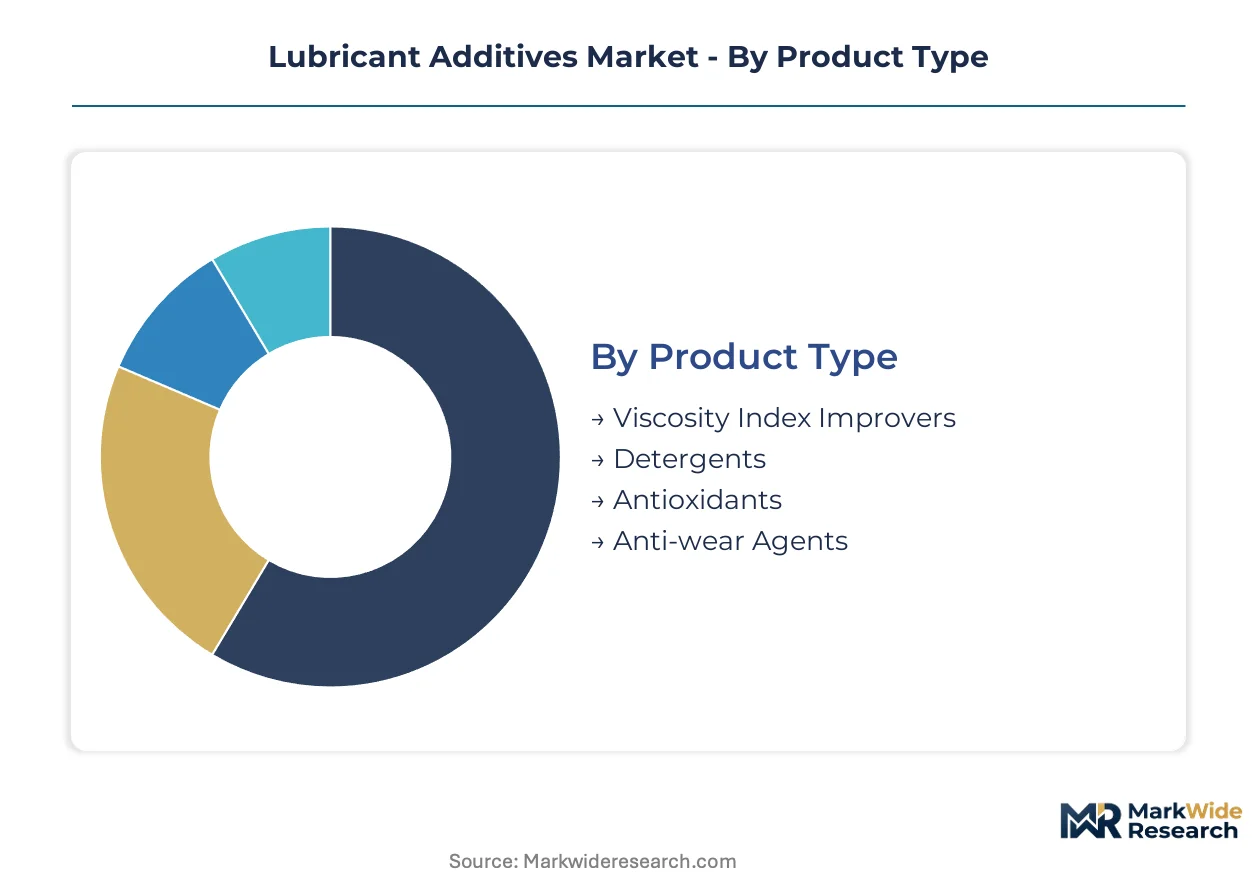
Lubricant additive suppliers configure their product portfolios around distinct performance specifications that align with regulatory chemistry limits and end-use operating conditions. Each segmentation dimension carries different margin profiles and technical barriers that reshape competitive positioning across the supply base.
Product Type:
REACH authorization timelines and EPA emission mandates are forcing reformulation priorities that concentrate R&D investment in specific chemistry families.
- Viscosity Index Improvers:Long-chain polymethacrylate or olefin copolymer architectures enable multigrade engine oils to maintain fluidity across temperature extremes. Demand concentrates in heavy-duty diesel formulations serving North American fleet operators seeking extended drain intervals under ACEA E6/E9 sequences.
- Anti-wear Agents:Zinc dialkyldithiophosphates and ashless phosphorus esters form protective tribofilms on metal surfaces under boundary lubrication conditions. Electric vehicle gearbox specifications in Germany and Japan are pulling novel boron-based chemistries into high-volume qualification programs.
- Detergents:Calcium and magnesium sulfonate complexes neutralize acidic combustion byproducts to prevent deposit formation on engine components.
- Antioxidants:Hindered phenols and amine-based radical scavengers interrupt oxidation chain reactions in thermally stressed lubricant systems.
Viscosity Index Improvers handles the majority of throughput; Anti-wear Agents is the fastest mover on share.
End User:
Customer procurement scale and specification authority determine formulation complexity and channel access for additive suppliers.
- Automotive Sector:Passenger car motor oils and commercial vehicle lubricants demand additive packages certified to ACEA, API, and ILSAC sequences. China's SAMR-administered GB standards and NEV subsidy programs are redirecting supplier technical resources toward e-axle fluid development for domestic OEMs.
- Industrial Machinery:Manufacturing equipment and power generation systems require oxidation-stable formulations with extended service life.
- Marine Applications:Two-stroke crosshead engines and four-stroke trunk piston systems operate under IMO 2020 sulfur caps that dictate cylinder oil alkalinity requirements.
- Aerospace:Gas turbine lubricants must meet SAE AS5780 and MIL-PRF-23699 specifications for thermal stability and load-carrying capacity.
Automotive Sector absorbs the dominant formulation volume; Industrial Machinery is expanding most quickly as predictive maintenance programs extend fluid change intervals.
Application:
Operating environment severity and fluid replacement economics create tiered performance requirements that segment pricing power.
- Engine Oils:Gasoline and diesel powertrain lubricants incorporate detergents, dispersants, anti-wear agents, and friction modifiers at treat rates up to 15% by weight. India's PLI scheme for automotive manufacturing is generating localized demand for high-performance additive packages meeting BIS IS 13656 specifications.
- Metalworking Fluids:Cutting and grinding formulations require extreme-pressure additives and corrosion inhibitors for precision machining of advanced alloys.
- Gear Oils:Hypoid and planetary gear systems demand sulfur-phosphorus extreme-pressure chemistries to prevent scuffing under high-contact stress.
- Hydraulic Fluids:Power transmission systems in construction and agriculture prioritize oxidation stability and filterability across wide temperature ranges.
Engine Oils commands the largest additive consumption; Metalworking Fluids is gaining share fastest from advanced manufacturing alloy proliferation.
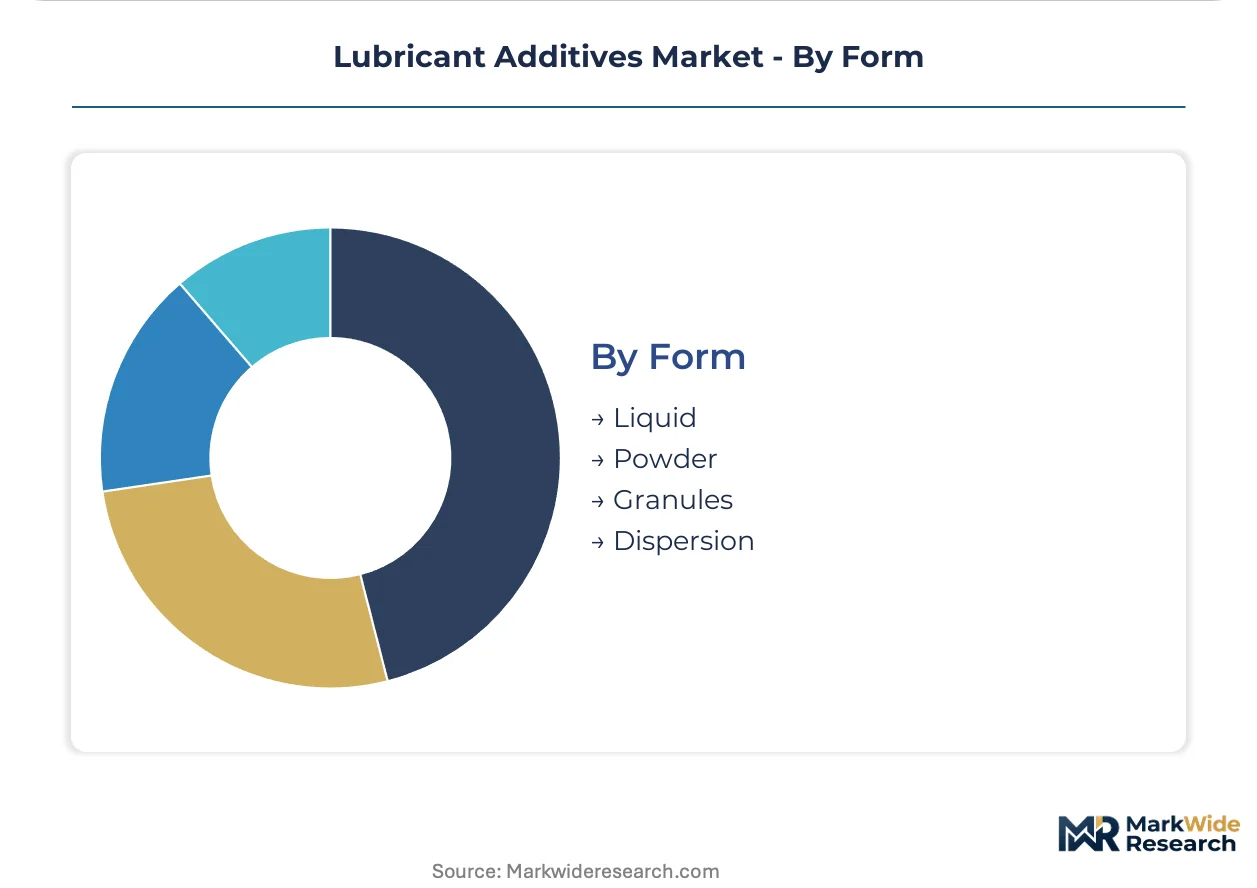
Form:
Physical state determines blending infrastructure requirements and logistics economics across regional supply networks.
- Liquid:Concentrated additive packages in solvent or base oil carriers enable direct injection into blending vessels without pre-dispersion steps. China's GB standards for batch traceability are forcing system upgrades at regional facilities handling liquid additive receipts.
- Dispersion:Pre-stabilized solid-liquid suspensions of insoluble performance chemicals reduce mixing time and quality variation.
- Powder:Dry solid additives require dust-controlled handling systems and dissolution protocols for homogeneous distribution.
- Granules:Agglomerated solid forms improve flow characteristics and reduce caking during storage and transport.
Liquid dominates current blending throughput; Dispersion is climbing the fastest as just-in-time compounding expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in industrial segments across India and Southeast Asia exhibit acute price sensitivity toward Group II base oil formulations, while German and Japanese automotive OEMs absorb premium additive costs for factory-fill e-axle fluids without volume elasticity.
United States
EPA Corporate Average Fuel Economy mandates concentrate demand for friction-modifying additives in passenger car motor oils serving Detroit Three technical centers. Fleet operators in the Midwest push extended drain intervals through ACEA E9-certified heavy-duty formulations. Houston-area blending facilities handle liquid additive receipts under evolving batch traceability protocols.
Germany
ECHA REACH authorization timelines for zinc dialkyldithiophosphates force reformulation of anti-wear packages toward ashless phosphorus esters. The EU Green Deal industrial decarbonization timeline opens biodegradable hydraulic fluid specifications for Ruhr Valley process industries. Stuttgart OEM technical centers specify proprietary e-fluids through integrated supply contracts.
China
SAMR-administered GB standards tighten permissible sulfur and phosphorus thresholds in finished lubricants. Dual carbon goals redirect base oil sourcing toward lower-carbon feedstocks for Yangtze River Delta blending facilities. Domestic NEV subsidy programs pull supplier technical resources toward e-axle fluid development for Shanghai and Shenzhen OEMs.
India
PLI scheme production-linked incentives for advanced manufacturing generate localized demand for high-performance engine oil additives meeting BIS IS 13656 specifications. Price-sensitive industrial segments in Gujarat displace additive-intensive synthetics with Group II mineral formulations. Maharashtra automotive clusters drive formulation complexity for commercial vehicle lubricants.
Japan
METI energy efficiency standards concentrate demand for low-viscosity engine oil additives in kei-car and hybrid powertrains. JIS certification requirements extend validation timelines for novel viscosity modifier platforms. Nagoya-area OEM technical centers co-develop factory-fill specifications through direct supplier integration.
Lubricant Additives Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the additive supply base. Integrated polymer researchers dominate viscosity modifier supply for high-performance specifications, while backward-integrated chemical conglomerates anchor detergent chemistry through captive sulfonate production. The market structure concentrates around three strategic archetypes: integrated formulators with captive polymer research, diversified chemical majors with backward integration into feedstocks, and specialized component suppliers focused on single chemistry families. Competitive moves center on co-development agreements with OEM technical centers and direct-to-blender digital platform deployment.
Within the integrated formulator tier, The Lubrizol Corporation and Infineum International Limited exemplify archetypes combining polymer architecture capabilities with formulation breadth across passenger car and heavy-duty segments. BASF SE occupies a position representing diversified chemical majors with upstream control over detergent chemistry. Among component specialists, Evonik Industries AG and Croda International plc sit within the niche chemistry tier focused on anti-wear and surface-active additive families.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| BASF SE |
| Afton Chemical |
| Chevron Oronite Company LLC |
| Infineum International Limited |
| Evonik Industries AG |
| LANXESS |
| Croda International plc |
| Nouryon |
| Others |
Cost & Logistics Intelligence
Captive polymer production at Lubrizol and Infineum facilities in the United States and United Kingdom anchors cost floors across viscosity modifier supply, concentrating pricing power among integrated formulators while forcing non-integrated competitors toward commodity detergent and dispersant segments.
Pricing Analysis
EPA emission mandates and ACEA oil sequences dictate the pricing tier structure across lubricant additive supply. Pricing stratifies across premium synthetic packages for Group III+ base oils, standard multigrade formulations for fleet operators, and economy mineral blends for price-sensitive industrial buyers in India and Southeast Asia. Cost compression in the economy tier intensifies as Group II base oil substitution accelerates in emerging markets. Fleet procurement teams in North America exhibit the lowest price sensitivity, absorbing premium additive costs for extended drain interval certifications.
Supply Chain Analysis
Phosphate rock processing concentration in Morocco and China creates input chokepoints for zinc dialkyldithiophosphate anti-wear agent production. Additive manufacturing draws from long-chain alpha-olefin feedstocks anchored in Gulf Coast petrochemical complexes, polymethacrylate monomers from European specialty chemical producers, and sulfonate detergents from integrated sulfonic acid operations. Single-source vulnerability runs through Moroccan phosphate supply for phosphorus-derived chemistries. Distribution runs through direct-to-blender digital platforms that disintermediate traditional distributor networks for mid-volume compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lubricant additives sit in early-cycle expansion as electric vehicle drivetrain fluid specifications create net-new formulation demand alongside legacy internal combustion engine refresh cycles.
For Market Incumbents: Compound formulation breadth advantages through captive polymer research investments in star-branched polymethacrylate architectures. Deepen backward integration into detergent sulfonate chemistry to defend margin position against commodity entrants. The threat of REACH authorization delays for zinc dialkyldithiophosphates demands accelerated ashless anti-wear chemistry qualification timelines. For New Entrants and Emerging Players: API SP/ILSAC GF-6A fast-track certification programs offer entry pathways into India's PLI-driven automotive clusters. Target biodegradable hydraulic fluid specifications for EU Green Deal process industries as the most penetrable white-space segment. Pursue co-development agreements with Shanghai and Shenzhen NEV OEMs for proprietary e-axle fluid qualifications. For Investors and Strategic Acquirers: Specialized boron-based anti-wear chemistry developers represent priority acquisition targets given electric vehicle gearbox specification pull. Long-term viability frames around dual carbon goal compliance capabilities and OEM technical center integration depth. Watch for inflection in China's NEV subsidy program renewal terms as demand signal for e-axle fluid technical resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detergent Sulfonate Chemistry | Captive sulfonic acid production secures margin control against phosphate rock volatility. |
| Star-Branched Polymethacrylate Capacity Expansion | Shear-stable VI improvers command premium positioning in ACEA E9 heavy-duty formulations. |
| Direct-to-Blender Digital Platform Deployment | E-procurement channels capture mid-volume compounder relationships bypassing distributors. |
| E-Axle Fluid Co-Development with NEV OEMs | Factory-fill specifications with BYD and NIO technical centers lock in proprietary formulation demand. |
| Biodegradable Hydraulic Fluid Certification Investment | EU Green Deal timelines for Ruhr Valley decarbonization open specification windows. |
Research Approach
The analysis maps viscosity index improvers, anti-wear agents, detergents, and dispersants, each validated through formulation chemists at additive suppliers, procurement leads at lubricant blenders, OEM technical center engineers, and fleet maintenance directors. Primary interview insights triangulate against customs trade data for base oil and additive flows, ACC and Cefic chemical industry reports, SEC 10-K disclosures from integrated chemical majors, and SAMR GB standard registration databases. Bottom-up segment sizing cross-checks against top-down lubricant demand modeling.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, end-use industry, application severity tier, and physical form dimensions throughout the forecast period. CAGRs derive from segmented demand elasticity analysis calibrated to EPA fuel economy mandate phase-ins, China's dual carbon goal implementation pacing, and electric vehicle production ramp assumptions. Forecast inputs incorporate ACEA sequence certification timeline distributions and REACH authorization probability weights.
Underlying assumptions cover regulatory chemistry threshold stability, phosphate rock supply continuity, and OEM factory-fill specification persistence, with deviation risk concentrated in REACH substance evaluation delays and China's NEV subsidy program adjustments. Practitioners should keep alternative scenarios live as ECHA authorization timelines and dual carbon goal enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Butylated Hydroxytoluene Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Global Ester Gum Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Global Glass Additives Market
Additives
Anti-Pollution Ingredients Market
Additives
Calcium Acetate Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Grease Additives Market
Additives
Tartaric Acid Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Tricalcium Citrate Market
Additives
Global Flame Retardant Masterbatches Market
Additives
North America Citric Acid Market
Additives
Canada Anti-Caking Market