
 Global Freeze-Dried Pet Food Market | 2026-2036
Global Freeze-Dried Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Freeze-Dried Pet Food Market Analysis
New Zealand lamb and venison sourcing networks is realigning toward North American freeze-drying capacity. Stella & Chewy's leverages captive raw-material relationships to secure protein traceability. Primal Pet Foods anchors its position through California-based cold-chain infrastructure. Wisconsin Freeze Dried dominates contract manufacturing for private-label entrants.
Freeze-dried pet food refers to raw or cooked formulations dehydrated through sublimation at pressures below 0.6 bar and shelf temperatures typically ranging from minus 40 to minus 20 degrees Celsius, preserving cellular structure and nutrient bioavailability for companion animal consumption. Dog Food commands the largest revenue share among product types, reflecting breed-size formulation diversity and veterinary endorsement of raw-aligned diets. Online Retail represents the fastest-expanding distribution channel, though Pet Stores retain higher basket values through staff-guided purchasing. Meat-based ingredient formulations capture premium pricing relative to vegetable or grain blends due to protein digestibility claims.
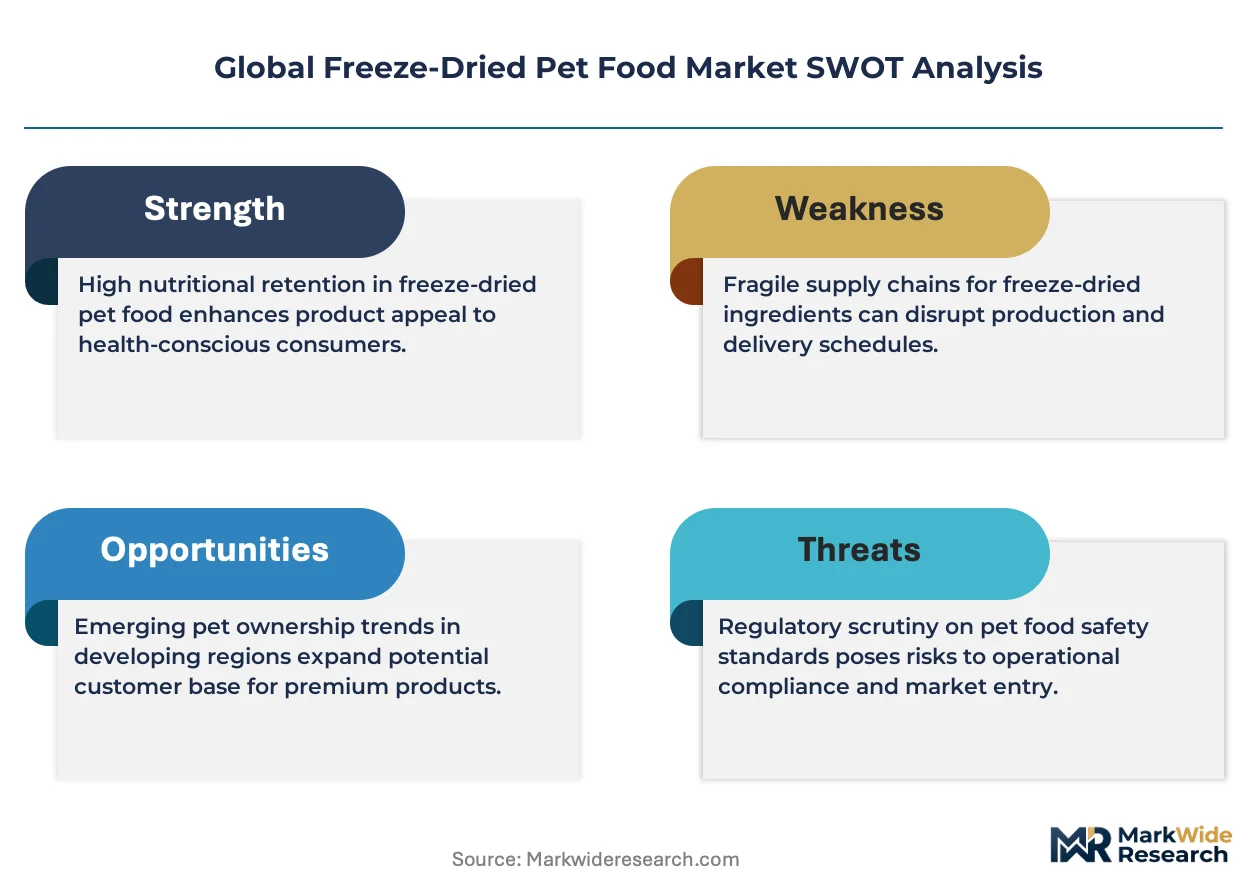
FDA Center for Veterinary Medicine guidelines govern raw pet food pathogen controls in the United States, while EU Regulation 183/2005 on feed hygiene mandates HACCP implementation across ingredient sourcing. China's SAMR enforces GB standards for imported pet food labeling and additive restrictions. Stakeholders must monitor evolving raw-material origin disclosure mandates and freeze-dry energy cost trajectories to preserve margin structures.
Market Dynamics
Freeze-dried pet food supply chains are consolidating around captive protein sourcing and dedicated sublimation capacity, as premiumization pressures force brands to secure traceable cold-chain infrastructure rather than rely on spot-market ingredients.
Growth Catalysts
- EU Farm to Fork traceability mandates:Ingredient origin disclosure requirements are accelerating investment in vertically controlled sourcing networks across Germany, France, and Italy.
- Urban dog ownership density:Metropolitan households in Shanghai, New York, and London are driving formulation diversity for breed-specific nutritional profiles.
- High-pressure sublimation advances:Vacuum chamber throughput improvements are compressing batch cycle times while preserving cellular nutrient structures.
Market Restraints
- Lamb and venison supply concentration:New Zealand pastoral land constraints limit raw material expansion for premium protein lines.
- Freeze-dry energy intensity:Industrial refrigeration loads face carbon pricing exposure under EU Emissions Trading System phase-in.
- Wet food substitution elasticity:Fresh refrigerated formats retain veterinary endorsement in markets with established cold-chain retail.
Strategic Opportunities
- India urban pet penetration:Mumbai and Bangalore present underdeveloped freeze-dried awareness amid rising disposable incomes.
- Veterinary clinic channel integration:Prescription-aligned formulations bypass retail margin compression through practitioner endorsement.
- Solar-powered sublimation:Renewable energy convergence with freeze-dry operations addresses ESG procurement criteria in California and Germany.
Industry Challenges
- Pathogen validation protocols:FDA Center for Veterinary Medicine raw food testing timelines extend product launch cycles.
- Cold-chain technician scarcity:Specialized refrigeration maintenance skills command wage premiums in Wisconsin and California manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Freeze-Dried Pet Food Market |
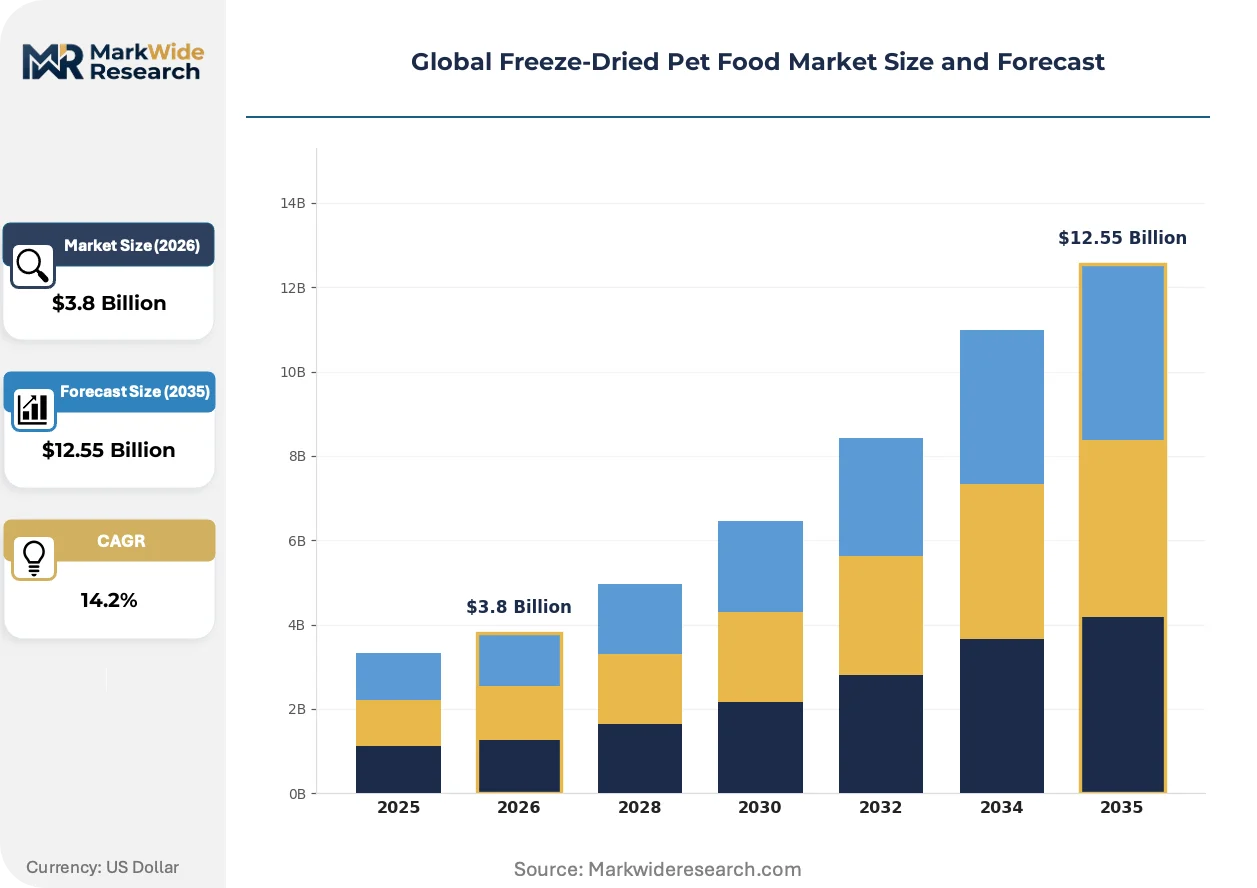
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dog Food, Cat Food, Treats, Supplements Ingredient: Meat, Vegetables, Fruits, Grains Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Stores Packaging Type: Bags, Pouches, Cans, Tubs |
| Companies Covered | Stella & Chewy's, Primal Pet Foods, Vital Essentials, Champion Petfoods, Steve's Real Food, Wisconsin Freeze Dried, Bravo Pet Foods, K9 Natural, Nature’s Variety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Freeze-Dried Pet Food Market Emerging Trajectories
Active freeze-drying process optimization and regulatory disclosure mandates are compressing traditional ingredient sourcing models while opening veterinary-channel distribution pathways previously dominated by pharmaceutical incumbents.
Radio-frequency assisted sublimation is expanding into high-moisture meat matrices previously excluded from freeze-dry processing due to ice crystal damage. Premium raw-food brands in the United States and Germany are adopting hybrid thermal systems to reduce batch times by one-third without protein denaturation. This acceleration is expanding into contract manufacturing segments where private-label entrants demand throughput parity with branded volume leaders.
China's SAMR enforcement of GB standards for imported pet food labeling is forcing reformulation of additive portfolios and origin documentation for cross-border entrants. Domestic manufacturers in Shandong and Zhejiang provinces are building captive testing laboratories to preempt certification delays. The regulatory friction most affects meat-based imports targeting tier-one cities where consumer litigation awareness is highest.
Subscription-based replenishment models are displacing bulk pantry stocking among millennial dog owners in Austin, Toronto, and Sydney. Direct-to-consumer platforms capture recurring revenue through algorithmic portion sizing tied to breed weight trajectories. This behavioral pivot is most visible in single-pet households where convenience premiums override per-unit cost sensitivity.
Global Freeze-Dried Pet Food Market Segmentation
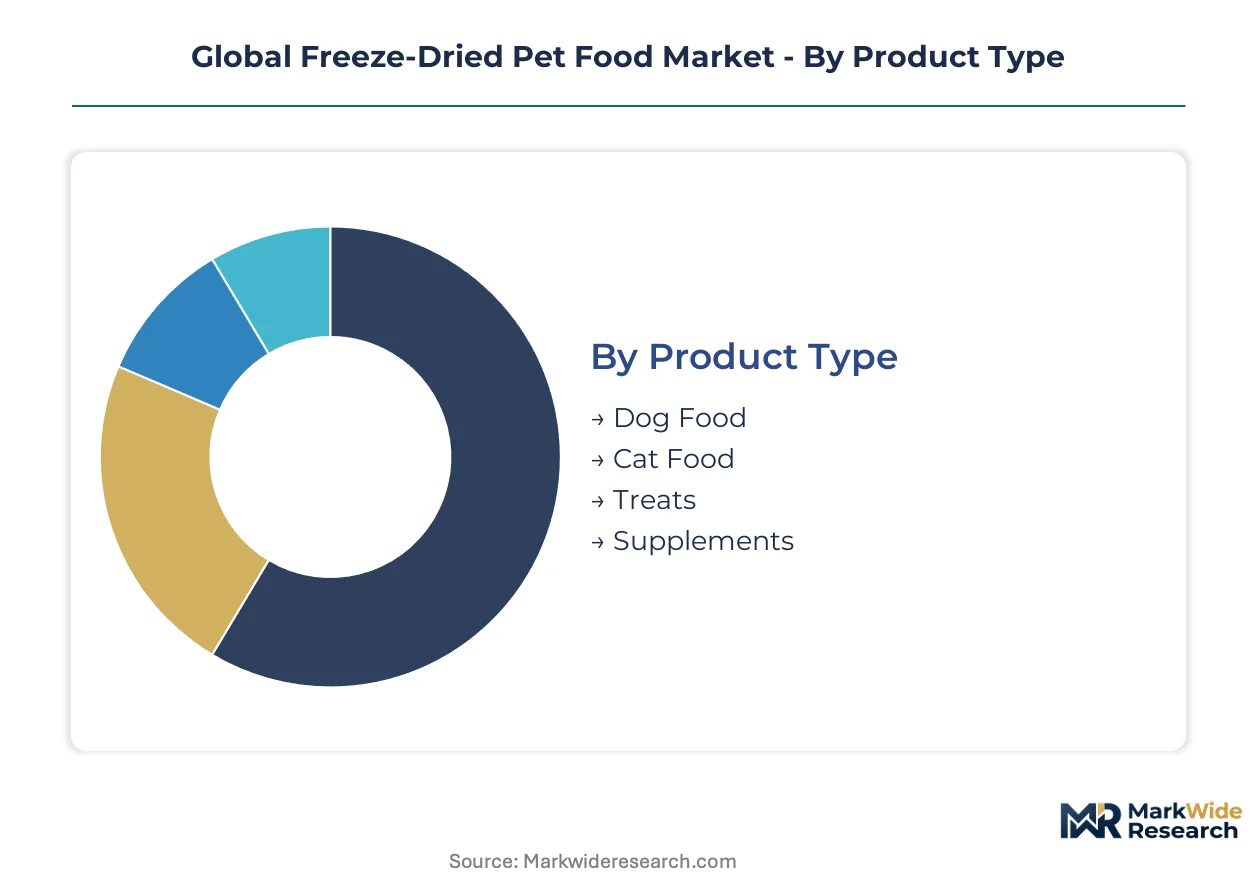
Freeze-dried pet food segmentation reflects divergent margin profiles across protein sourcing intensity and channel infrastructure requirements. Supply concentration in meat-based formulations and online fulfillment networks shapes competitive positioning across each dimension.
Product Type:
Supply concentration in freeze-drying capacity favors formulations with the highest throughput and veterinary endorsement density.
- Dog Food:Breed-size formulation diversity drives batch complexity, from Chihuahua-appropriate nuggets to Great Dane meal volumes. Demand concentrates in United States metropolitan households where veterinary endorsement of raw-aligned diets sustains premium pricing. Protein digestibility claims and cold-chain traceability requirements elevate manufacturing standards.
- Cat Food:Taurine preservation through sublimation protocols differentiates feline formulations from canine equivalents. Demand clusters in German and Japanese urban apartments where obligate carnivore nutrition awareness is highest. Smaller batch sizes per SKU compress margin structures relative to dog food scale.
- Treats:Training-reward formats dominate volume in China and Australia.
- Supplements:Joint and coat formulations target aging pet demographics in California and Florida.
Dog Food absorbs the bulk of installed capacity; Cat Food is expanding most quickly.
Ingredient:
Cost tier stratification separates protein-dominant formulations from carbohydrate-inclusive alternatives.
- Meat:New Zealand lamb and venison supply networks anchor premium positioning through pastoral land constraints. Demand concentrates in tier-one Chinese cities and German metropolitan zones where origin disclosure mandates from EU Farm to Fork strategy accelerate traceability investment. Sublimation preserves myofibrillar structure for digestibility claims.
- Vegetables:Sweet potato and pumpkin matrices serve carbohydrate-tolerant formulations in North American markets. Demand clusters in Austin and Toronto where grain-free positioning retains consumer resonance despite veterinary skepticism.
- Fruits:Blueberry and cranberry inclusion targets antioxidant claims in premium treat segments.
- Grains:Oat and rice formulations occupy economy positioning in price-sensitive Indian and Brazilian markets.
Meat commands the highest margin tier; Vegetables are climbing the fastest as formulation diversity expands.
Distribution Channel:
Volume concentration in traditional retail contrasts with customer acquisition economics in direct channels.
- Online Retail:Algorithmic replenishment models capture recurring revenue through breed-weight trajectory matching. Demand concentrates in single-pet millennial households across Sydney, London, and New York where convenience premiums override per-unit cost sensitivity. Subscription infrastructure requires predictive logistics investment.
- Pet Stores:Staff-guided purchasing sustains higher basket values through nutritional consultation. Demand clusters in Wisconsin and California manufacturing corridors where trained personnel convert premium positioning.
- Supermarkets:Mass-market penetration in France and Italy depends on shelf-stable format acceptance.
- Specialty Stores:Boutique channels in Tokyo and Seoul emphasize exotic protein provenance.
Pet Stores retain the highest transaction values; Online Retail is gaining share fastest through subscription lock-in.
Packaging Type:
Customer type differentiation separates bulk pantry stocking from portion-controlled convenience.
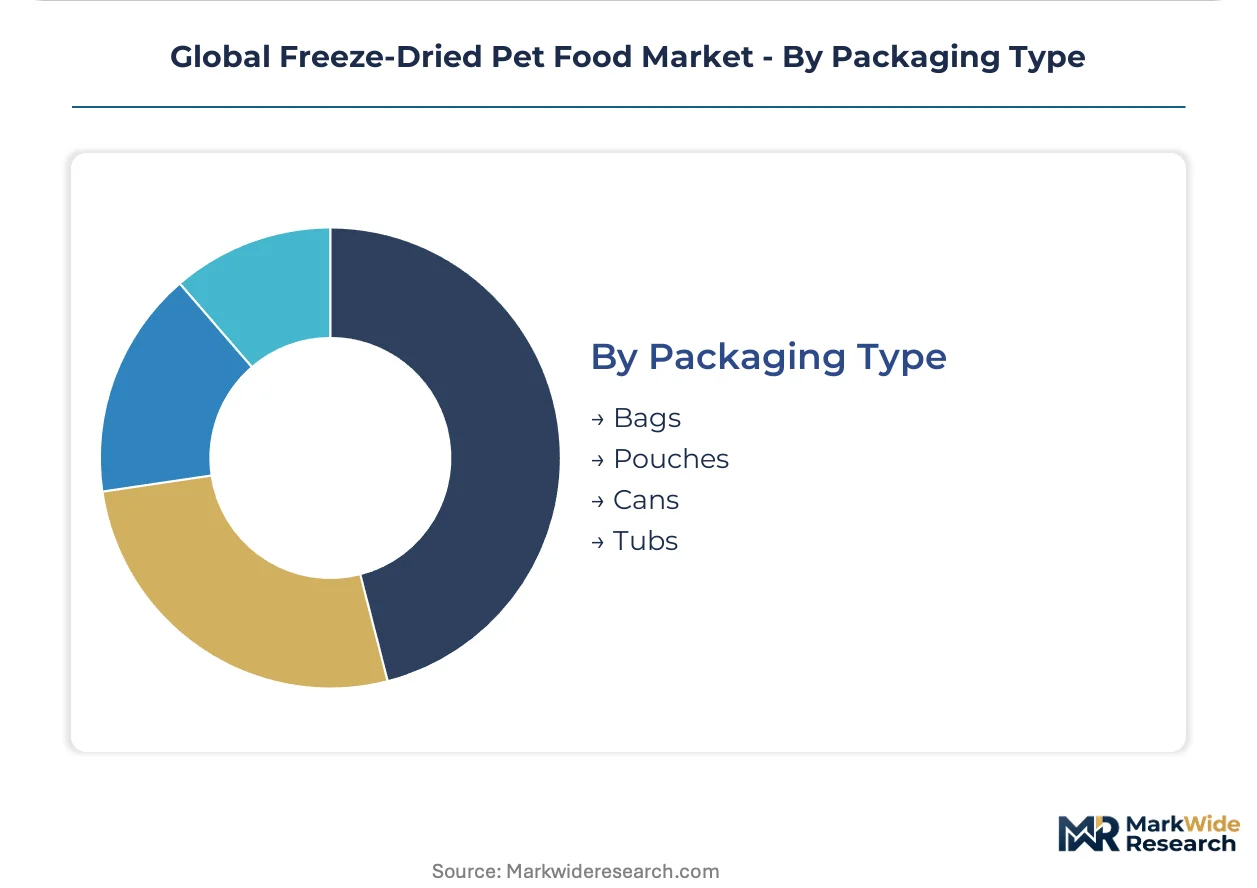
- Bags:Multi-serve formats dominate household penetration in suburban United States markets. Demand concentrates in multi-pet households across Texas and Ohio where volume purchasing reduces per-meal cost. Resealability requirements drive film lamination technology.
- Pouches:Single-serve portability targets urban dog owners in Shanghai and Mumbai with limited storage space. Demand clusters in apartment-dwelling demographics where freshness sealing justifies unit premium.
- Cans:Hybrid wet-dry positioning occupies transitional segments in Brazilian retail.
- Tubs:Bulk institutional formats serve breeding kennel and veterinary clinic channels.
Bags absorb the bulk of polymer packaging volume; Pouches are expanding most quickly through urban convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand pastoral networks anchor protein sourcing for freeze-dried formulations, with sublimation capacity concentrating in manufacturing clusters across five demand centers.
United States
Metropolitan dog ownership in New York and Austin drives subscription-based replenishment models. FDA Center for Veterinary Medicine guidelines govern raw pet food pathogen controls, extending product launch timelines. Wisconsin hosts contract manufacturing clusters where specialized refrigeration maintenance skills command wage premiums.
China
Tier-one cities including Shanghai and Beijing concentrate demand for premium meat-based formulations with traceable origin documentation. SAMR enforces GB standards for imported pet food labeling and additive restrictions. Domestic manufacturers in Shandong and Zhejiang provinces build captive testing laboratories to preempt certification delays.
Germany
Urban apartment demographics in Berlin and Munich sustain cat food demand with high taurine preservation requirements. EU Regulation 183/2005 on feed hygiene mandates HACCP implementation across ingredient sourcing. The EU Farm to Fork strategy tightens traceability mandates, accelerating investment in vertically controlled sourcing networks.
India
Mumbai and Bangalore present underdeveloped freeze-dried awareness amid rising disposable incomes and urban pet penetration. The country's national food safety regulator enforces labeling standards for imported pet food products. Western Maharashtra manufacturing corridors develop cold-chain infrastructure to serve emerging metropolitan demand.
Australia
Sydney single-pet millennial households drive online retail expansion through algorithmic portion sizing tied to breed weight trajectories. The country's national agricultural regulator oversees biosecurity protocols for imported protein sources. Melbourne-based distribution networks invest in predictive logistics infrastructure for subscription fulfillment.
Global Freeze-Dried Pet Food Market Vendor Landscape
Global majors compete with regional champions across captive sourcing and sublimation capacity. The vendor base clusters around three tiers: vertically integrated protein owners, contract manufacturing specialists, and direct-to-consumer platform operators. Strategic archetypes include captive traceability leaders, cold-chain infrastructure anchors, and private-label contract manufacturers. Competitive moves concentrate on backward integration into New Zealand pastoral networks and renewable energy convergence with freeze-dry operations.
Within the captive sourcing tier, Stella & Chewy's represents protein traceability leadership through raw-material relationship control. Wisconsin Freeze Dried exemplifies contract manufacturing scale for private-label entrants. Primal Pet Foods occupies a position anchored through California-based cold-chain infrastructure. These three company structures illustrate the strategic divergence between protein ownership, manufacturing scale, and distribution integration.
| Leading Market Players |
|---|
| Stella & Chewy's |
| Primal Pet Foods |
| Vital Essentials |
| Champion Petfoods |
| Steve's Real Food |
| Wisconsin Freeze Dried |
| Bravo Pet Foods |
| K9 Natural |
| Nature's Variety |
| Others |
Supply Flow & Price Mechanics
EU Farm to Fork traceability mandates for ingredient origin disclosure force brands to absorb cold-chain infrastructure costs that compress margin structures at the premium tier. This procurement specification shift elevates pricing for meat-based formulations with verified New Zealand lamb and venison provenance while squeezing vegetable-inclusive alternatives.
Pricing Analysis
Subscription bundling with algorithmic portion sizing and veterinary consultation credits separates premium pricing tiers from transactional per-unit sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein traceability depth and cold-chain certification grade. Pricing pressure stems from renewable energy convergence requirements in California and Germany manufacturing clusters. Economy grain-inclusive formulations in Indian and Brazilian markets exhibit highest price sensitivity; premium meat-based SKUs in Shanghai and New York maintain inelastic demand.
Supply Chain Analysis
New Zealand pastoral networks for lamb and venison rest on land-constrained protein sourcing that limits raw material expansion for premium lines. Wisconsin and California manufacturing clusters draw from captive cold-chain infrastructure with specialized refrigeration maintenance skill premiums. Single-source vulnerability concentrates in New Zealand protein origins facing biosecurity protocol disruptions. Distribution runs through direct-to-consumer subscription platforms and pet store networks with staff-guided consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radio-frequency assisted sublimation is displacing conventional vacuum chamber batch processing, compressing cycle times by one-third without protein denaturation and reshaping competitive economics for legacy equipment operators.
For Market Incumbents: Anchor California and Wisconsin cold-chain infrastructure against renewable energy cost trajectories by securing solar-powered sublimation partnerships. Defend against private-label contract manufacturing erosion through captive New Zealand protein sourcing relationships and FDA pathogen validation protocol pre-certification investments. For New Entrants and Emerging Players: Launch via veterinary clinic channel integration in Mumbai and Bangalore where freeze-dried awareness remains underdeveloped and practitioner endorsement unlocks prescription-aligned pricing. Target single-serve pouch formats for urban apartment demographics in tier-one Chinese cities with limited storage space and freshness-sealing willingness-to-pay premiums. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing specialists with installed sublimation capacity and renewable energy site control. Long-term viability hinges on backward integration into traceable protein sourcing networks rather than spot-market ingredient dependency. Watch EU Emissions Trading System phase-in acceleration as margin inflection trigger for carbon-intensive freeze-dry operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into New Zealand Pastoral Networks | Captive lamb and venison sourcing secures EU Farm to Fork traceability compliance and premium pricing tier access. |
| Solar-Powered Sublimation Capacity Buildout | Renewable energy convergence addresses ESG procurement criteria in California and Germany manufacturing corridors. |
| Veterinary Clinic Channel Partnership | Practitioner endorsement bypasses retail margin compression and locks in recurring prescription-aligned revenue streams. |
| Algorithmic Subscription Platform Launch | Breed-weight trajectory matching captures recurring revenue from millennial single-pet households in Sydney and London. |
| Captive Testing Laboratory Investment | Shandong and Zhejiang facilities preempt China's SAMR certification delays for cross-border meat-based entrants. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with freeze-dry equipment manufacturers, pet food brand procurement directors, and veterinary clinic channel managers. FDA Center for Veterinary Medicine guidance documents, EU Regulation 183/2005 feed hygiene implementations, and China's SAMR GB standards enforcement records supplied regulatory trajectory validation. Bottom-up volume modeling across protein sourcing intensity and channel infrastructure requirements triangulated against top-down expenditure flow analysis from metropolitan household pet ownership surveys.
Data-stream reconciliation across production capacity databases, cold-chain infrastructure investment disclosures, and subscription platform transaction patterns informed the analytical framework. Segmentation dimensions spanned product type, ingredient sourcing tier, distribution channel, and packaging format across the projection horizon. CAGRs derived from fitted growth curves applied to protein digestibility claim penetration rates and urban pet ownership density trajectories. Forecast inputs incorporated EU Emissions Trading System carbon pricing phase-in assumptions and radio-frequency sublimation technology adoption curves.
The model assumes a particular technology adoption path for radio-frequency assisted sublimation; alternative pathways for vacuum chamber throughput optimization would alter the outlook for batch cycle compression and capital expenditure requirements. Forecasts reflect assumptions regarding EU Farm to Fork traceability mandate enforcement timing and New Zealand pastoral land constraint persistence. Alternative protein sourcing from Australian or North American venison networks, accelerated FDA pathogen validation timelines, or wet food substitution elasticity shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Foie Gras Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Brahmi Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Vegetarian Taquitos Market