
 Low Calorie Hard Candy Market | 2026-2036
Low Calorie Hard Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Hard Candy Market Analytics
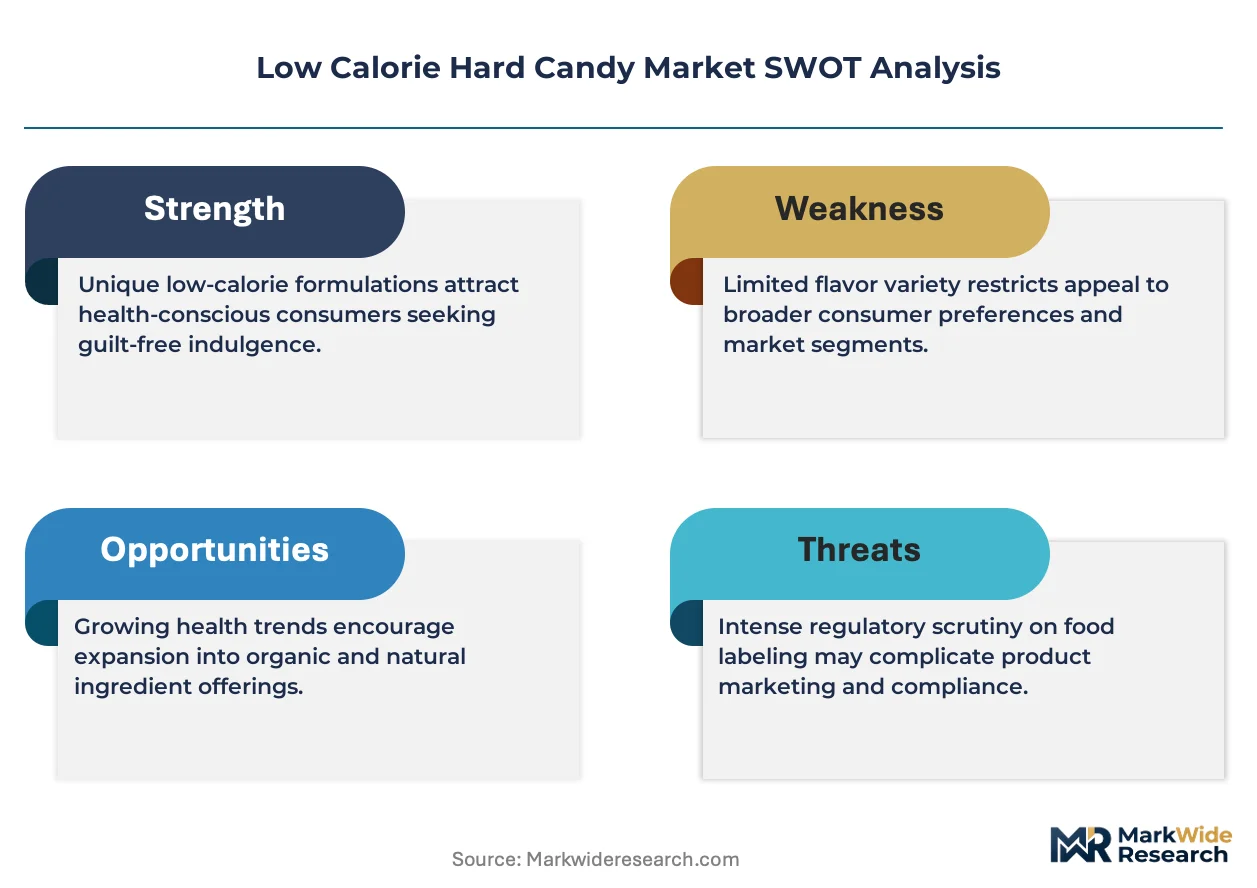
ISO 22000 certification is rotating as the gatekeeping standard for manufacturers seeking shelf placement in major retail chains. Hershey leverages its confectionery scale to anchor distribution across mass-market channels. SmartSweets competes through clean-label positioning that targets health-conscious consumers seeking reduced-sugar alternatives. Ricola sustains European heritage credibility while navigating North American regulatory requirements for herbal and sugar-free formulations.
Low calorie hard candy denotes confectionery products manufactured with sugar substitutes such as erythritol, stevia, or isomalt, achieving caloric reduction below traditional sucrose-based equivalents while maintaining structural integrity through controlled cooking temperatures and humidity parameters. The sugar-free segment leads volume due to diabetic and ketogenic diet adherence, while organic variants command premium positioning through ingredient traceability requirements. Online retail channels demonstrate the fastest structural expansion as direct-to-consumer brands bypass traditional wholesale markups.
FDA nutrition labeling mandates and USDA organic certification requirements govern product claims and market access in the United States, while EFSA novel food assessments shape European formulation approvals for emerging sweeteners. Compliance costs favor established players with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor evolving sweetener safety evaluations and front-of-package labeling initiatives that could recalibrate competitive positioning without warning.
Market Dynamics
Formulation chemistry around rare sugar alcohols is fragmenting supply relationships as erythritol shortages force manufacturers toward isomalt and allulose blends, rewiring procurement priorities across the confectionery value chain.
Growth Catalysts
- Ketogenic diet adherence:Consumers following carbohydrate-restricted regimens in the United States drive repeat purchases of sugar-free hard candy formulations that maintain glycemic control.
- FDA nutrition labeling mandates:Clear caloric disclosure requirements accelerate reformulation investments as brands compete for front-of-package health claims in retail environments.
- Pharmacy channel expansion:Wellness-oriented retail chains in Germany and Switzerland position low-calorie confectionery adjacent to diabetes management products, creating new impulse purchase occasions.
Market Restraints
- Erythritol supply concentration:Chinese manufacturers control over 70 percent of global erythritol capacity, exposing formulation costs to export tariff volatility and ocean freight disruptions.
- Aftertaste masking limitations:Stevia glycosides require extensive flavor system engineering to suppress licorice-like off-notes, extending product development cycles by 8-14 months.
- EFSA novel food assessments:Emerging sweeteners including allulose face prolonged safety evaluation timelines that delay European market entry by 24-36 months versus United States approvals.
Strategic Opportunities
- Direct-to-consumer subscription models:Digital-native brands bypass wholesale markups through recurring delivery programs targeting diabetic consumers in Canada and Australia.
- USDA organic certification tailwinds:Premium positioning through ingredient traceability commands 40-60 percent price multiples in natural grocery channels across California and Colorado.
- Functional ingredient convergence:Probiotic and adaptogenic additive integration creates differentiation in stress-relief and digestive health positioning for urban professional segments.
Industry Challenges
- Food technologist talent scarcity:Specialized expertise in polyol crystallization and humidity-stable formulation commands premium compensation, constraining mid-tier manufacturer R&D throughput.
- ISO 22000 certification timelines:Major retail chains mandate third-party food safety verification that requires 12-18 month implementation periods, blocking shelf access for emerging entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Hard Candy Market |
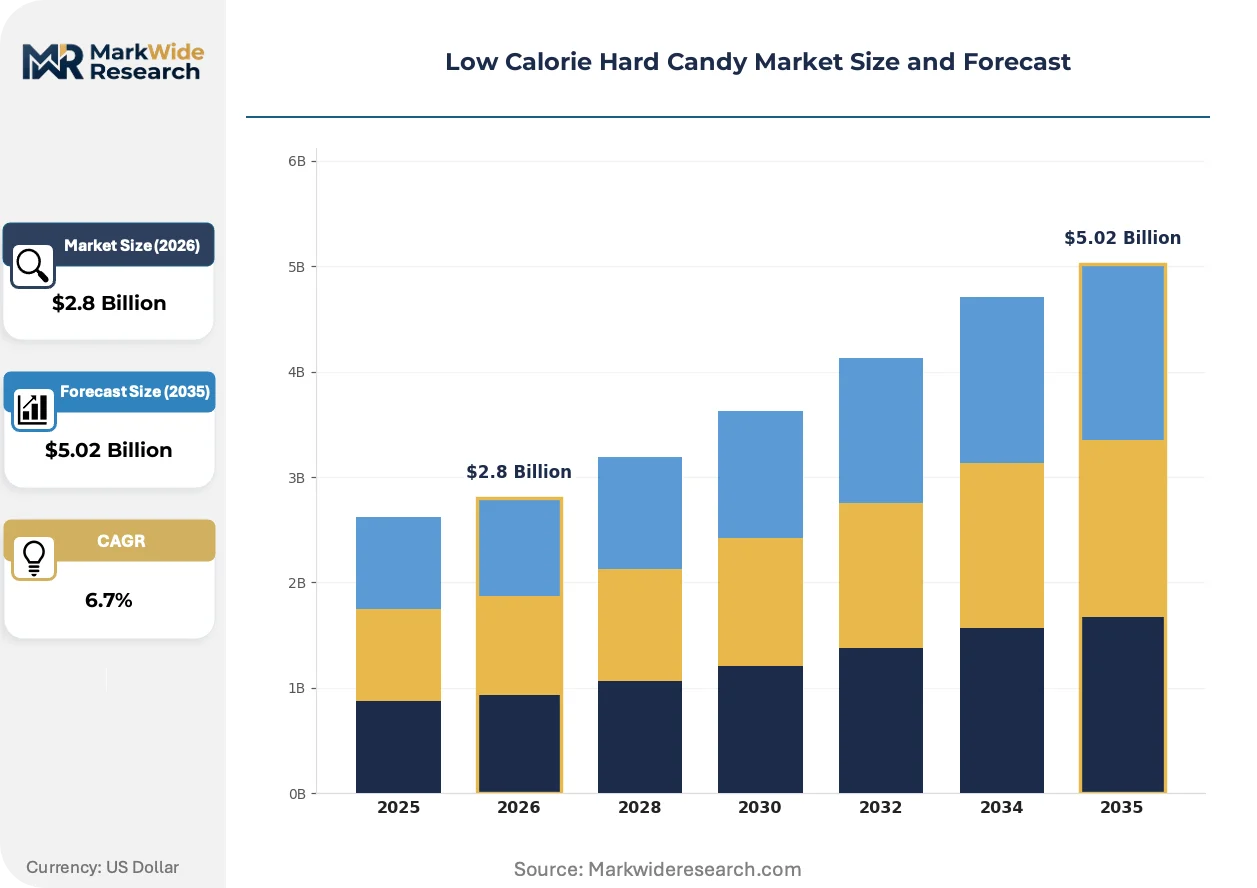
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar-Free, Organic, Gelatin-Based, Natural Flavor Packaging Type: Bags, Boxes, Tins, Wraps Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Customer Type: Health-Conscious Consumers, Diabetics, Fitness Enthusiasts, Families |
| Companies Covered | Hershey, Lotte, SmartSweets, Ricola, Kraft Foods, TruJoy Sweets, Nestle, Sweets Without, Mars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Hard Candy Market Evolving Landscape
Confectionery science is converging with pharmaceutical-grade manufacturing discipline as precision sweetener dosing and controlled-release coating technologies redefine product performance expectations.
Allulose crystallization technology is fragmenting traditional polyol hierarchies by enabling thermal stability above 150 degrees Celsius without Maillard browning. Ketogenic and diabetic consumer segments in Texas and Florida are adopting allulose-based hard candy at triple-digit velocity versus legacy sorbitol formulations. This displacement is compressing isomalt's historical dominance in sugar-free boiled sweets and forcing reformulation pipeline reallocation across mid-size manufacturers.
EFSA's 2023 updated guidance on sugar replacer health claims is tightening evidentiary requirements for glycemic response assertions in European Union member states. Manufacturers must now commission human clinical trials costing 400,000 to 800,000 euros to support reduced glucose impact labeling. German and Dutch brands with existing trial portfolios are accelerating market share capture while competitors delay launches pending study completion.
Wellness retail procurement is consolidating supplier relationships around vertically integrated manufacturers with captive sweetener production and in-house analytical laboratories. Natural channel buyers in Colorado and Oregon now require certificate of analysis documentation for every production lot, displacing fragmented distributor networks that aggregated multiple small brands. This concentration favors established players with dedicated quality assurance infrastructure over emerging labels dependent on toll manufacturing arrangements.
Low Calorie Hard Candy Market Segmentation
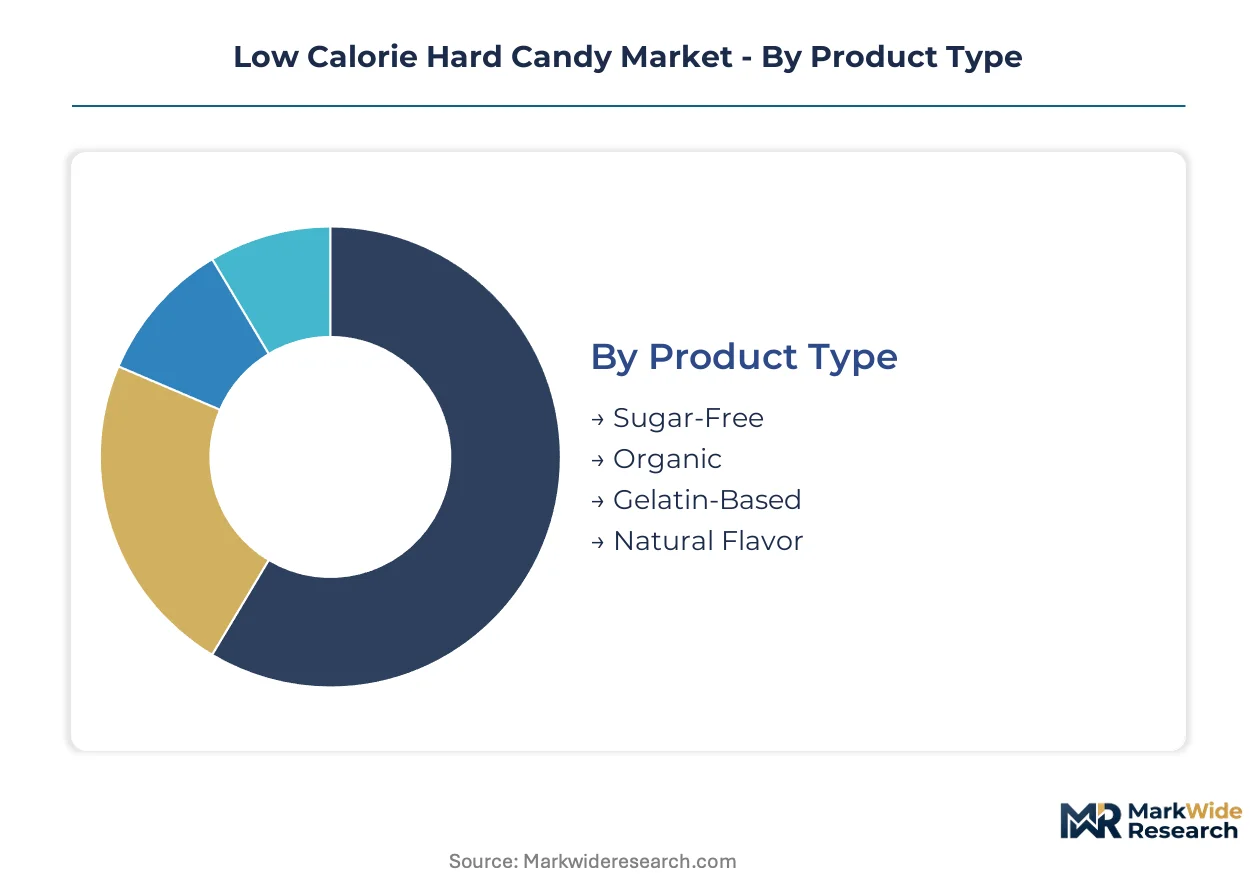
Segmentation in low calorie hard candy reveals how formulation chemistry, packaging economics, and channel access create distinct competitive battlegrounds. Regulatory compliance costs and sweetener supply concentration fragment addressable markets across consumer health states and purchasing occasions.
Product Type:
FDA nutrition labeling mandates and EFSA novel food assessments create divergent compliance burdens across formulation categories, reshaping R&D investment priorities.
- Sugar-Free:Formulations rely on erythritol, isomalt, or allulose to achieve sub-40% caloric density versus sucrose equivalents. Demand concentrates among diabetic consumers in Texas and Florida pharmacy channels, where glycemic control drives repeat purchase loyalty. Established volume favors sugar-free; emerging adoption favors organic.
- Organic:USDA certification requires ingredient traceability through certified organic supply chains, commanding 40-60% price premiums in natural grocery channels. California and Colorado wellness retailers mandate certificate of analysis documentation per production lot. Steepest expansion trajectory comes from ketogenic diet adherents seeking clean-label alternatives.
- Gelatin-Based:Structural integrity depends on bovine or porcine gelatin sourcing with controlled bloom strength parameters.
- Natural Flavor:Botanical extracts and essential oils replace synthetic flavor systems, requiring extended stability testing under accelerated aging protocols.
Cost tier separation is pronounced: organic certification adds 15-25% to COGS versus conventional sugar-free, while natural flavor systems extend development cycles without equivalent price recovery.
Packaging Type:
Channel-specific packaging economics determine margin structure, with pharmacy and convenience formats demanding distinct barrier properties and shelf-presence specifications.
- Bags:Flexible film structures with moisture vapor transmission rates below 0.5 g/m²/day protect hygroscopic polyol formulations through 18-month shelf life. Mass-market retailers in Germany and Switzerland favor resealable zipper formats for diabetes management product adjacencies.
- Boxes:Rigid paperboard with PET windowing supports premium gifting positioning in urban professional segments.
- Tins:Metal containers with rolled-edge sealing provide humidity stability for tropical climate distribution.
- Wraps:Individual twist-wrapping enables portion control and impulse purchase activation at pharmacy checkout counters.
Volume concentration favors bags; margin expansion favors tins.
Distribution Channel:
Customer acquisition economics diverge sharply between direct-to-consumer digital models and traditional wholesale-dependent retail.
- Online Retail:Subscription programs targeting diabetic consumers in Canada and Australia bypass 35-50% wholesale markups through recurring delivery optimization. Platform algorithms favor products with ISO 22000 certification badges, concentrating discoverability among verified manufacturers.
- Supermarkets:Category management fees and slotting allowances favor confectionery majors with dedicated account teams.
- Specialty Stores:Natural channel buyers in Oregon and Colorado require vertical integration proof and captive analytical laboratory capabilities.
- Wholesale:Distributor consolidation is displacing fragmented networks that previously aggregated multiple small brands.
Fastest channel expansion is online retail; deepest penetration remains supermarkets.
Customer Type:
Dietary adherence patterns create distinct usage occasions and price sensitivity profiles across health-motivated purchasing.
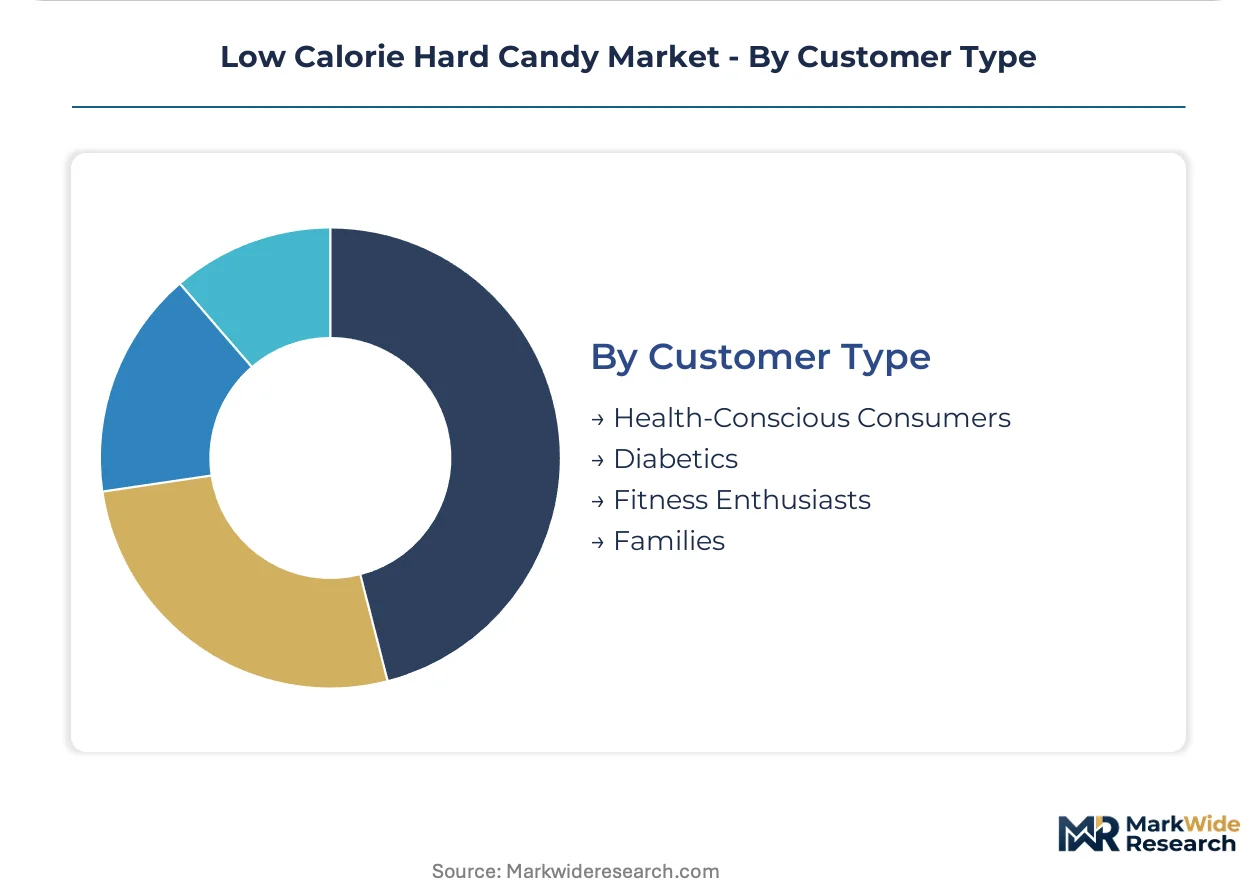
- Health-Conscious Consumers:Clean-label positioning with reduced-sugar claims drives trial in wellness retail environments. Urban professional segments in North American cities respond to functional ingredient convergence including probiotic and adaptogenic additives.
- Diabetics:Glycemic control requirements create subscription loyalty and pharmacy channel concentration.
- Fitness Enthusiasts:Macronutrient tracking compatibility supports ketogenic and low-carbohydrate diet adherence.
- Families:Portion-controlled packaging and child-friendly flavor profiles compete with conventional confectionery for household pantry placement.
Defensive volume anchors in diabetics; offensive growth targets health-conscious consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific sweetener supply chains, channeling erythritol and allulose shipments from Chinese manufacturers into North American formulation facilities. This maritime infrastructure underwrites distribution economics for low-calorie confectionery across the western United States.
United States
Ketogenic diet adherence in Texas and Florida drives pharmacy-channel purchases of sugar-free hard candy. FDA nutrition labeling mandates accelerate reformulation investments as brands compete for front-of-package health claims. Chicago and Denver wellness retailers require ISO 22000 certification badges, concentrating shelf access among verified manufacturers.
Germany
Diabetes management product adjacencies in pharmacy chains create impulse purchase occasions for low-calorie confectionery. EFSA novel food assessments impose 400,000 to 800,000 euro clinical trial costs for glycemic response labeling. Cologne and Frankfurt formulation clusters host vertically integrated manufacturers with captive analytical laboratories.
Switzerland
Herbal heritage credibility sustains demand for sugar-free formulations with botanical positioning. Swissmedic regulates health claims for functional confectionery additives including probiotics. Zurich and Geneva wellness retail procurement mandates certificate of analysis documentation per production lot.
Canada
Direct-to-consumer subscription models targeting diabetic consumers bypass wholesale markups through recurring delivery optimization. Health Canada oversees novel food approvals for emerging sweeteners including allulose. Toronto and Vancouver digital-native brands leverage platform algorithms favoring ISO 22000 certification for discoverability.
Australia
Clean-label positioning commands premium multiples in natural grocery channels across Sydney and Melbourne. TGA regulates complementary medicine claims for functional ingredient convergence including adaptogenic additives. Brisbane and Perth pharmacy expansion positions low-calorie confectionery adjacent to metabolic health products.
Low Calorie Hard Candy Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and channel access. The vendor base concentrates around confectionery majors with dedicated regulatory affairs teams and emerging digital-native brands with direct-to-consumer optimization. Three archetypes dominate: scale-driven mass-market distributors, clean-label specialists, and vertically integrated wellness players. Competitive moves center on ISO 22000 certification acquisition and subscription model deployment.
Within the scale-driven tier, Hershey occupies a position exemplifying mass-market distribution leverage across United States retail channels. SmartSweets represents the clean-label specialist archetype targeting health-conscious consumers through reduced-sugar positioning. Ricola anchors European heritage credibility while navigating North American regulatory requirements for herbal formulations.
| Leading Market Players |
|---|
| Hershey |
| Lotte |
| SmartSweets |
| Ricola |
| Kraft Foods |
| TruJoy Sweets |
| Nestle |
| Sweets Without |
| Mars |
| Others |
Value Network & Pricing Analysis
Allulose crystallization technology adoption is displacing erythritol-dependent formulations and simultaneously rewiring procurement geography toward North American pilot facilities while compressing legacy polyol pricing premiums across mid-tier manufacturers.
Pricing Analysis
Volume-discount tiering structures separate contract pharmaceutical buyers from wellness retail procurement. Three-tier pricing stratifies across organic-certified premium, ISO 22000-verified standard, and economy sugar-free tiers. Pricing pressure stems from Chinese erythritol export tariff exposure eroding margin buffers in commodity formulations. Pharmacy channel buyers demonstrate lowest price sensitivity due to diabetes management product adjacencies, while mass-market retailers negotiate aggressively on volume commitments.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose ocean freight routes channeling Chinese erythritol through Singapore to Los Angeles formulation clusters. Supply concentrates in China, Germany, and Switzerland for polyol refinement and herbal extraction respectively. Raw material dependencies center on corn-derived dextrose for fermentation, beet sugar for isomalt, and stevia leaf for glycoside extraction. Single-source vulnerability in Chinese erythritol capacity creates formulation cost volatility. Distribution runs through vertically integrated wellness retailers with captive analytical laboratories displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against allulose-based functional gummies and pharmaceutical-grade glucose management tablets that threaten hard candy format relevance among diabetic consumers.
For Market Incumbents: Shield formulation portfolios through backward integration into captive sweetener production and accelerated allulose crystallization R&D pipelines. Secure ISO 22000 certification badges ahead of wellness retail procurement consolidation. Defend pharmacy channel positioning against direct-to-consumer subscription models by embedding diabetes educator partnerships. For New Entrants and Emerging Players: Differentiate on USDA organic certification and probiotic functional ingredient convergence targeting urban professional stress-relief occasions. Penetrate Australian and Canadian natural grocery channels where certificate of analysis documentation requirements have displaced legacy distributor networks. Deploy direct-to-consumer subscription models with recurring delivery optimization bypassing wholesale markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed clean-label specialists possessing established wellness retail relationships but lacking allulose formulation capabilities. Five-to-ten year viability hinges on functional ingredient integration depth and vertical manufacturing control. Monitor EFSA novel food approval timelines for allulose as the signal indicating European market entry feasibility and competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Allulose Crystallization Scale-Up | Thermal stability above 150°C enables ketogenic formulation leadership in Texas and Florida pharmacy channels. |
| ISO 22000 Certification Acquisition | Third-party verification unlocks shelf placement with Colorado and Oregon wellness retail procurement teams. |
| Direct-to-Consumer Subscription Launch | Recurring delivery optimization captures diabetic consumer loyalty in Canada and Australia bypassing wholesale markups. |
| USDA Organic Certification Investment | Ingredient traceability commands premium positioning in California natural grocery channels with 40-60% price multiples. |
| Functional Ingredient Convergence | Probiotic and adaptogenic additive integration creates differentiation for urban professional stress-relief positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance documents, EFSA novel food assessment records, and customs trade data for erythritol and allulose shipments. Interviews with confectionery formulation scientists, wellness retail category buyers, pharmacy channel procurement managers, and regulatory affairs specialists at major manufacturers informed demand and supply-side dynamics. Secondary sources include USDA organic certification databases, ISO 22000 registrar records, and Nielsen retail audit data for natural grocery channels. Bottom-up volume modeling triangulates against top-down value projections across the analysis window.
Segmentation dimensions modeled include product type (sugar-free, organic, gelatin-based, natural flavor), packaging format (bags, boxes, tins, wraps), distribution channel (online retail, supermarkets, specialty stores, wholesale), and customer type (health-conscious consumers, diabetics, fitness enthusiasts, families). CAGRs derive from trend extrapolation adjusted for regulatory approval timelines and sweetener substitution elasticities. Forecast inputs incorporate ketogenic diet adherence rates, pharmacy channel expansion trajectories, and EFSA clinical trial cost burdens for glycemic response labeling.
The analysis sits within stated boundaries; outcomes outside EFSA allulose approval, sustained erythritol supply disruption, or accelerated ISO 22000 certification mandates would require recalibration. Forecasts reflect assumptions about regulatory stability and consumer dietary adherence persistence. Practitioners should keep alternative scenarios live as novel sweetener safety evaluations and front-of-package labeling initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Cocoa and Chocolate Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Chocolate Couverture Market
Confectionery
Green Tea Chocolate Market
Confectionery
Confectionery Fats Market
Confectionery
Low Calorie Treats Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Global Mochi Market
Confectionery
Ice Cream Coating Market
Confectionery
United States and Europe Macarons Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
North America Compound Chocolate Market
Confectionery
North America Sugar Confectionery Market
Confectionery
CBD-Infused Confectionery Market