
 Coconut Butter Market | 2026-2036
Coconut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Butter Market Analysis
Clean-label bakery and confectionery buyers is redrawing procurement priorities across the coconut butter supply base. Nutiva, Inc. leverages its USDA organic certification network to secure shelf placement in premium retail channels. Artisana Organics, Inc. specializes in raw, stone-ground production methods that appeal to minimally processed food segments. Dr. Bronner's, LLC anchors its sourcing through fair trade cooperatives in Sri Lanka, reinforcing supply chain transparency as a competitive differentiator.
Coconut butter is a semi-solid emulsion produced by grinding dried coconut kernel (copra) into a paste containing approximately 60-70% fat, with the balance comprising fiber, protein, and natural sugars; manufacturers typically employ stone grinding or expeller pressing at temperatures below 46°C to preserve enzymatic activity in raw grades. Organic coconut butter commands premium positioning in North American and European retail due to stringent USDA and EU organic compliance costs that smaller processors struggle to absorb. Spreadable form factors dominate household penetration, while powdered variants are gaining traction among nutritional supplement manufacturers seeking clean-label lipid fortification without liquid handling complexity.
FDA food labeling rules and USDA National Organic Program standards govern ingredient declarations and certification eligibility for coconut butter sold in the United States, while EU organic regulations and EFSA novel food assessments shape market access across European member states. These frameworks elevate compliance costs for new entrants but simultaneously reward established operators with validated traceability systems. Stakeholders must monitor evolving allergen labeling requirements and origin-certification protocols as retail buyers intensify supplier audit frequency.
Market Dynamics
Clean-label procurement mandates from North American bakery chains are compressing supplier qualification timelines while tightening organic traceability requirements across Sri Lankan and Philippine origin markets.
Growth Catalysts
- USDA National Organic Program certification:Retail buyers in the United States now require validated organic chain-of-custody documentation, accelerating facility upgrades among processors seeking premium channel access.
- Stone-ground raw processing:Minimally processed food segments are specifying sub-46°C grinding temperatures to preserve enzymatic activity, creating technical differentiation for equipped manufacturers.
- Sri Lankan origin concentration:Premium-grade copra sourcing is consolidating around Sri Lankan estates with established fair trade cooperative relationships, rewarding early direct-sourcing investments.
Market Restraints
- Copra price volatility:Dried coconut kernel input costs fluctuate with Philippine and Indonesian harvest cycles, squeezing processor margins during El Niño-drought periods.
- Dual certification burden:Simultaneous USDA organic and EU organic compliance requires parallel audit streams, elevating fixed costs for export-oriented operators.
- Almond and cashew butter substitution:Alternative tree-nut spreads compete for shelf space in natural food channels, particularly where coconut allergen labeling creates consumer hesitation.
Strategic Opportunities
- Powdered form factor expansion:Nutritional supplement manufacturers are adopting spray-dried coconut butter for clean-label lipid fortification, bypassing liquid handling complexity in powder-based formulations.
- Fair trade cooperative anchoring:Direct sourcing partnerships in Sri Lanka's Southern Province enable supply chain transparency narratives that command retail placement premiums.
- EFSA novel food pathway:European entrants can leverage existing copra safety data to accelerate approved status for innovative coconut butter applications in functional foods.
Industry Challenges
- Organic inspector capacity constraints:Accredited certification bodies face audit backlog, extending qualification timelines for new processing facilities by six to twelve months.
- Legacy ERP traceability gaps:Smaller processors lack integrated lot-tracking systems capable of generating real-time origin documentation demanded by retail audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Butter Market |
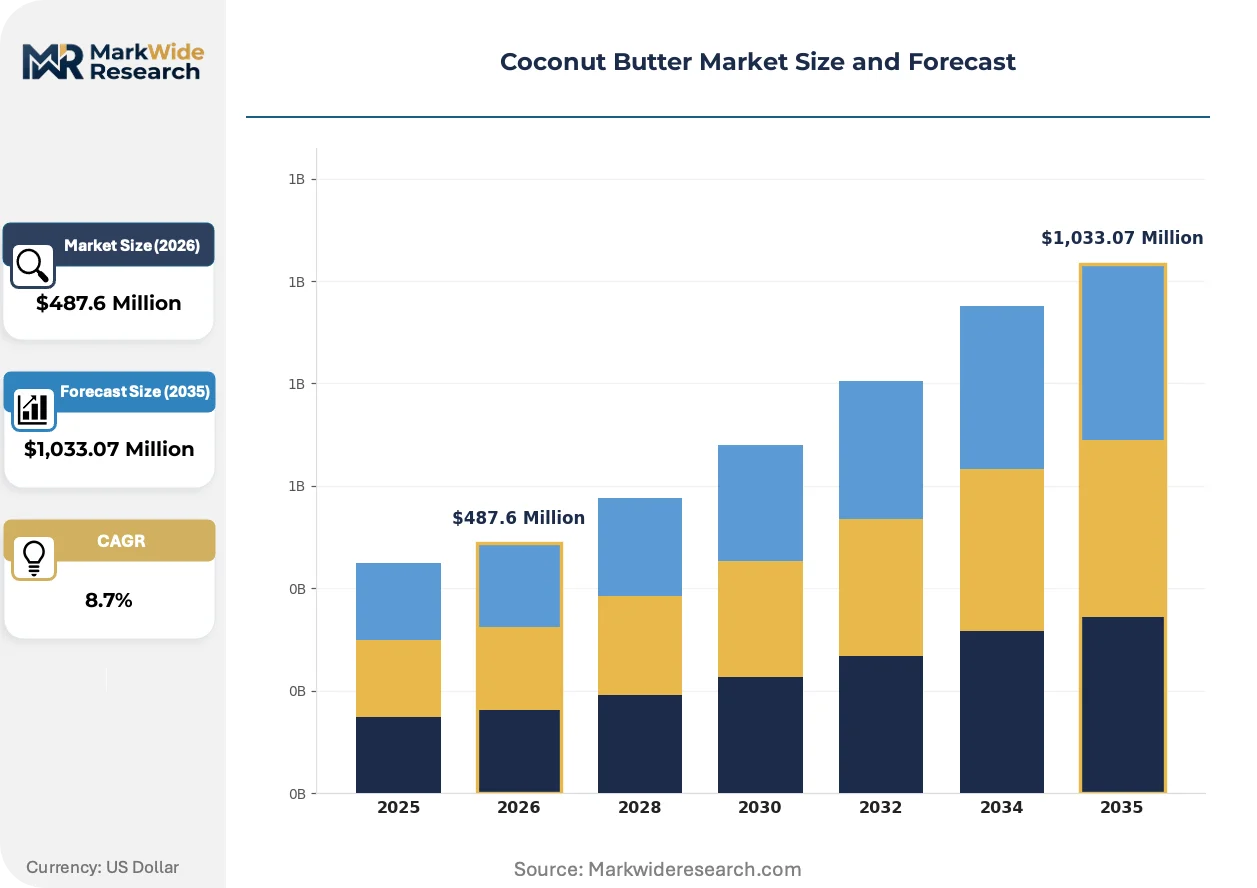
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Coconut Butter, Refined Coconut Butter, Organic Coconut Butter, Flavored Coconut Butter Form: Spreadable, Liquid, Solid, Powdered Application: Baking, Cooking, Skincare, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Ceylon Coconut Company Ltd., MaraNatha Natural Foods, Inc., Nutiva, Inc., The Coconut Company Ltd., Dr. Bronner’s, LLC, Artisana Organics, Inc., Bali Nutra Ltd., Andy Albao Corporation, Tropical Traditions LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Butter Market Emerging Trajectories
Processing technology and procurement specifications are diverging sharply between raw-grade premium positioning and commodity-scale efficiency plays.
Cold-press expeller technology is bifurcating the equipment supply base. High-end stone-grinding systems capable of sub-46°C operation are securing placement in minimally processed food segments. Volume processors are adopting continuous expeller configurations that sacrifice enzymatic preservation for throughput. The market is separating into premium raw-grade and standard refined tiers with limited middle-ground equipment demand.
EU organic regulations are tightening residue testing protocols for coconut butter imports. Maximum pesticide residue limits now require third-party laboratory verification at port of entry. German and Dutch importers are consolidating supplier bases around processors with in-house testing capabilities, displacing smaller traders lacking analytical infrastructure.
Direct-to-manufacturer sourcing is displacing traditional commodity brokers in North American procurement. Nutritional supplement formulators are establishing bilateral contracts with Sri Lankan processors, bypassing layered distribution. This channel compression is most visible in California and Oregon, where clean-label contract manufacturers specify origin-verified inputs with single-source documentation.
Coconut Butter Market Segmentation
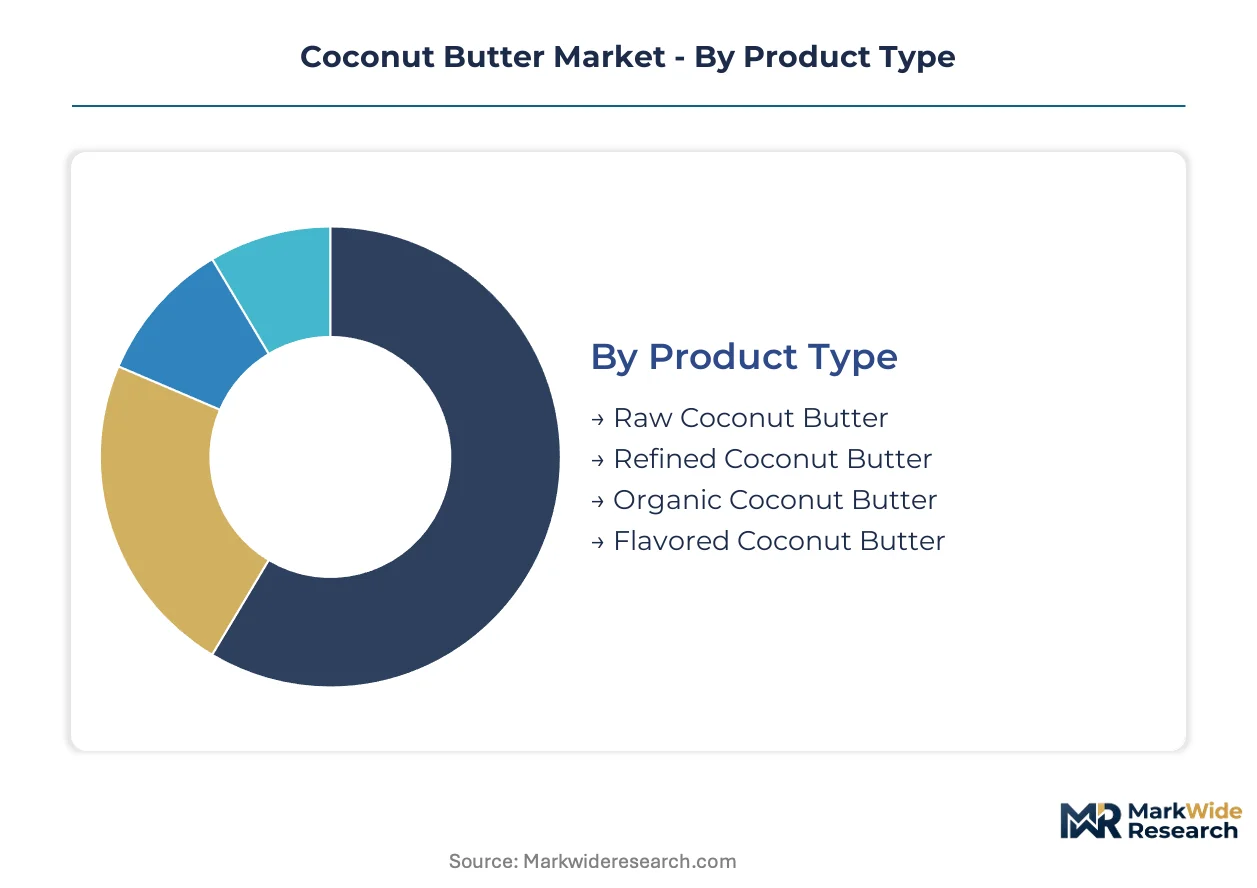
Coconut butter segmentation reflects divergent compliance burdens and processing intensities across the value chain. Regulatory differentiation between USDA organic, EU organic, and conventional grades creates distinct cost structures that reshape competitive positioning in each category.
Product Type:
USDA National Organic Program and EU organic regulations impose parallel audit streams that segment the market into four distinct certification and processing tiers.
- Raw Coconut Butter:Stone-ground at sub-46°C temperatures to preserve enzymatic activity and native protein structures. Clean-label bakery chains in the United States specify this grade for minimally processed positioning, though stone-grinding equipment constraints limit supplier qualification timelines.
- Organic Coconut Butter:Requires validated chain-of-custody documentation from Sri Lankan or Philippine estates through final packaging. Dual USDA-EU certification elevates fixed costs, concentrating supply among processors with in-house testing capabilities and established fair trade cooperative relationships.
- Refined Coconut Butter:High-temperature processing neutralizes flavor variance and extends shelf stability. Commodity-scale manufacturers favor this grade for confectionery applications where enzymatic preservation is not specified.
- Flavored Coconut Butter:Incorporates vanilla, cacao, or spice inclusions targeting premium retail channels. California and Oregon natural food stores represent the primary demand concentration for value-added positioning.
Refined coconut butter handles the majority of throughput; organic coconut butter is expanding most quickly on share.
Form:
Handling characteristics and formulation compatibility drive form factor selection across end-use applications.
- Spreadable:Semi-solid emulsion at ambient temperature dominates household penetration. North American retail buyers specify this form for dairy replacement positioning in clean-label bakery chains.
- Powdered:Spray-dried lipid matrix enables clean-label fortification in nutritional supplement formulations. California contract manufacturers are bypassing liquid handling complexity through bilateral sourcing agreements with Sri Lankan processors.
- Liquid:Decanted oil phase separated from fiber and protein fractions. Industrial confectionery applications specify this grade for precise dosing in continuous production lines.
- Solid:Chilled and block-form for foodservice and industrial bulk handling. Philippine copra processors favor this form for ocean freight efficiency to North American manufacturing clusters.
Spreadable form maintains volume leadership; powdered form is climbing the fastest as supplement manufacturers consolidate procurement.
Application:
End-use specifications diverge sharply between food-grade enzymatic preservation requirements and cosmetic-grade stability demands.
- Baking:Clean-label bakery chains specify organic, raw-grade coconut butter for dairy replacement in laminated doughs and fillings. FDA food labeling rules govern allergen declarations that influence consumer hesitation at point of purchase.
- Nutritional Supplements:Powdered coconut butter enables MCT lipid fortification in protein blends and meal replacements. Direct-to-manufacturer sourcing from Sri Lanka's Southern Province is displacing traditional commodity brokers in this channel.
- Cooking:Refined grades with high smoke points serve sauté and frying applications where flavor neutrality is preferred. Philippine and Indonesian harvest cycles introduce input cost volatility that squeezes processor margins.
- Skincare:Cosmetic formulators specify raw or minimally processed grades for emollient properties in balms and body butters. EFSA novel food assessments do not apply, though EU cosmetic regulation governs ingredient safety documentation.
Baking commands the largest demand share; nutritional supplements show the steepest expansion trajectory.
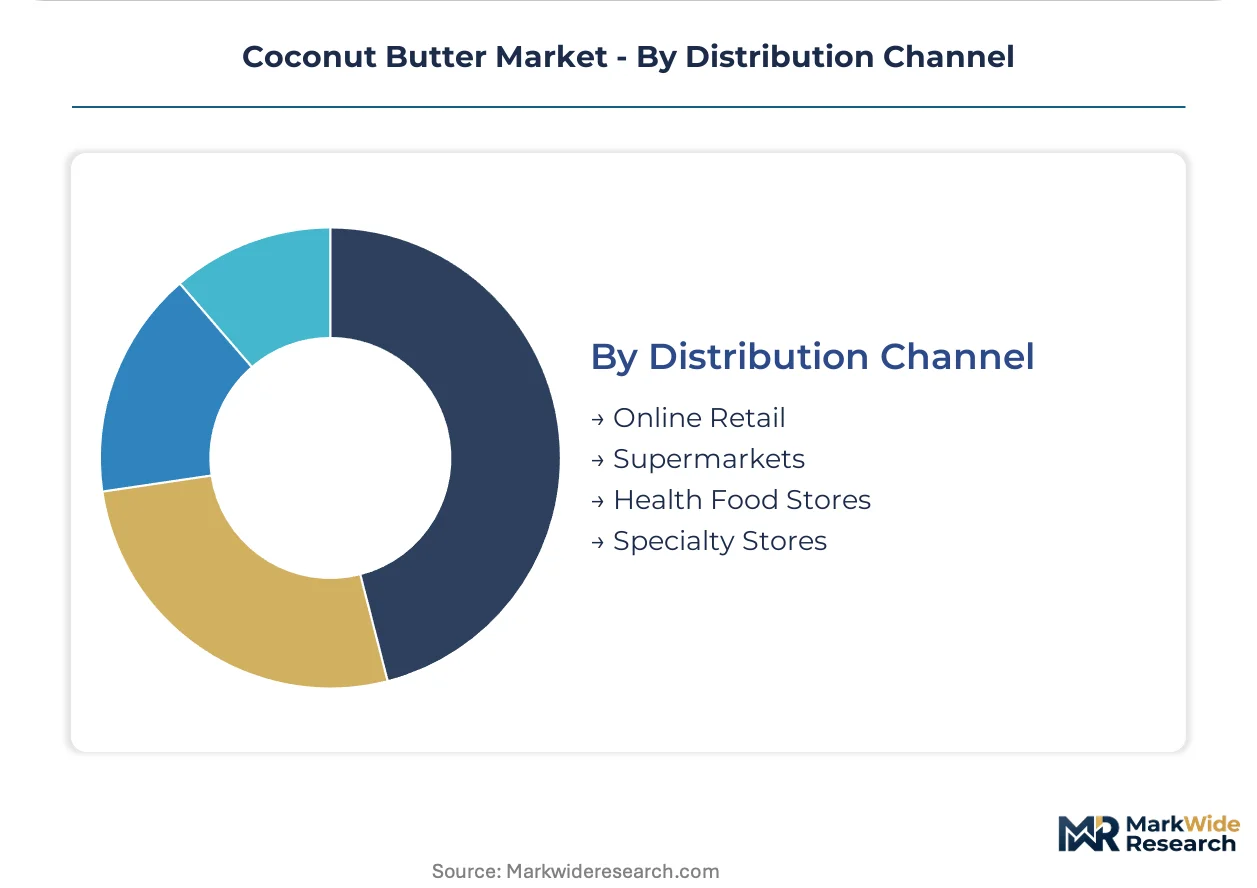
Distribution Channel:
Channel selection determines documentation depth and audit frequency required for market access.
- Health Food Stores:Independent retailers in California and Oregon specify origin-verified inputs with single-source documentation. These outlets reward fair trade cooperative anchoring with premium shelf placement.
- Online Retail:Direct-to-consumer platforms enable traceability narrative marketing that commands price premiums. USDA organic certification badges reduce consumer search friction in digital channels.
- Supermarkets:Mass retail placement requires validated organic chain-of-custody documentation and integrated lot-tracking systems capable of generating real-time origin documentation.
- Specialty Stores:Gourmet and ethnic food retailers stock flavored and premium-grade variants targeting experiential purchase occasions.
Health food stores anchor premium positioning; online retail is gaining share fastest through direct sourcing narratives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Colombo anchors Sri Lanka's coconut butter export infrastructure, handling containerized shipments of organic-grade copra to North American and European manufacturing clusters. Philippine facilities rely on the Port of Manila for bulk copra movements to industrial processors. These maritime gateways determine origin-market access for premium-grade raw material.
United States
Clean-label bakery chains in California and Oregon specify USDA organic coconut butter for dairy replacement formulations. FDA food labeling rules govern allergen declarations that influence retail placement decisions. Los Angeles and Portland manufacturing clusters host contract manufacturers establishing bilateral sourcing agreements with Sri Lankan processors.
Germany
EFSA novel food assessments shape market access for innovative coconut butter applications in functional foods. REACH compliance and EU organic regulations impose residue testing protocols requiring third-party laboratory verification. Hamburg and Rotterdam port complexes consolidate supplier bases around processors with in-house analytical capabilities.
Philippines
Copra price volatility tracks harvest cycles across Mindanao and Quezon Province estates. The country's national food safety regulator enforces export certification standards for dried coconut kernel shipments. Davao City processing facilities supply refined grades to North American confectionery manufacturers seeking volume throughput.
Sri Lanka
Fair trade cooperative relationships in the Southern Province enable supply chain transparency narratives commanding retail placement premiums. USDA National Organic Program and EU organic dual certification requirements concentrate supply among established estate operators. Galle and Matara districts anchor premium-grade raw material sourcing for stone-ground raw processing.
Netherlands
Amsterdam and Rotterdam distribution hubs re-export organic coconut butter to German and French retail channels. EU organic regulations and EFSA residue limits require validated chain-of-custody documentation at port of entry. Dutch importers are consolidating procurement around processors with integrated lot-tracking systems.
Coconut Butter Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and origin-verification capabilities. The supplier base concentrates around three tiers: multinational organic brands with dual USDA-EU certification, regional estate-integrated processors, and private-label contract manufacturers serving nutritional supplement channels. Competitive moves center on direct sourcing partnerships in Sri Lanka's Southern Province and facility upgrades to achieve sub-46°C stone-grinding specifications.
Within the estate-integrated tier, Ceylon Coconut Company Ltd. and The Coconut Company Ltd. represent archetypes of origin-anchored supply chain control. Among North American organic specialists, Nutiva, Inc. and Dr. Bronner's, LLC occupy positions defined by USDA certification network scale and fair trade cooperative anchoring respectively. These groupings illustrate how certification infrastructure and sourcing geography stratify competitive positioning.
| Leading Market Players |
|---|
| Ceylon Coconut Company Ltd. |
| MaraNatha Natural Foods, Inc. |
| Nutiva, Inc. |
| The Coconut Company Ltd. |
| Dr. Bronner's, LLC |
| Artisana Organics, Inc. |
| Bali Nutra Ltd. |
| Andy Albao Corporation |
| Tropical Traditions LLC |
| Others |
Supply Flow & Price Mechanics
Ninety-day ocean freight lead times from Colombo to Los Angeles bind Sri Lankan estate processors to North American buyers through long-term offtake agreements, concentrating pricing power among operators with validated USDA organic chain-of-custody documentation and in-house testing capabilities.
Pricing Analysis
Volume-discount tiering separates raw stone-ground grades from refined commodity tiers, with premium-mid-economy pricing differentiation anchored in certification depth and enzymatic preservation specifications. Price differentiation stems from dual USDA-EU compliance costs and sub-46°C processing equipment investments. Cost compression in refined grades is intensifying because Philippine harvest volatility squeezes processor margins. Nutritional supplement manufacturers show lowest price sensitivity due to clean-label fortification premiums, while industrial confectionery buyers negotiate aggressively on volume.
Supply Chain Analysis
The Port of Colombo transit underwrites premium-grade organic flows to North American manufacturing clusters, while the Port of Manila handles bulk refined movements. Raw material sourcing draws from Sri Lankan Southern Province estates and Philippine Mindanao copra processors. Single-source vulnerability concentrates in fair trade cooperative relationships that anchor transparency narratives. Distribution runs through bilateral direct-to-manufacturer contracts displacing layered commodity brokers, particularly in California and Oregon contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings represent a faster-expanding recurring layer than base ingredient supply, as retail audit protocols demand continuous origin documentation and real-time lot-tracking subscriptions.
For Market Incumbents: Consolidate procurement relationships in Sri Lanka's Galle and Matara districts through exclusive fair trade cooperative anchoring, defending against almond and cashew butter substitution in natural food channels. Expand in-house analytical capabilities to capture residue testing revenue from smaller traders lacking EU port-of-entry compliance infrastructure. For New Entrants and Emerging Players: Lead with powdered coconut butter formulations targeting California nutritional supplement contract manufacturers, the most penetrable segment due to direct sourcing channel compression. Establish bilateral sourcing agreements bypassing traditional commodity brokers, leveraging spray-dried lipid matrix specifications that eliminate liquid handling complexity for powder-based formulators. For Investors and Strategic Acquirers: Long-term, this sits as a certification-infrastructure play because dual USDA-EU compliance barriers concentrate supply among operators with validated traceability systems and audit-ready documentation platforms. Target estate-integrated processors with established Southern Province cooperative networks. Monitor organic inspector capacity constraints as the signal indicating qualification timeline bottlenecks that favor incumbents with existing certification relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA-EU parallel audit streams unlock premium retail channel placement in California and Oregon. |
| Direct Sourcing Partnership | Fair trade cooperative anchoring in Sri Lanka's Southern Province commands supply chain transparency premiums. |
| Powdered Form Factor Expansion | Spray-dried lipid matrices bypass liquid handling complexity for nutritional supplement manufacturers. |
| In-House Analytical Capability | Residue testing infrastructure satisfies EU port-of-entry verification displacing smaller traders. |
| Stone-Grinding Equipment Upgrade | Sub-46°C processing preserves enzymatic activity for minimally processed food segment specifications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food labeling guidance, USDA National Organic Program standards documentation, EU organic regulations, and EFSA novel food assessment records. Interviews with organic certification body auditors, Sri Lankan estate operations managers, North American clean-label bakery procurement directors, and nutritional supplement formulators informed supply chain dynamics and pricing pressure points. Secondary validation drew from customs trade data, organic certification registry filings, and port authority container movement records. Bottom-up processor capacity assessments and top-down retail channel demand estimates were cross-referenced for triangulation.
Segmentation dimensions modeled include product type across raw, organic, refined, and flavored grades; form factor across spreadable, powdered, liquid, and solid; application across baking, nutritional supplements, cooking, and skincare; and distribution channel across health food stores, online retail, supermarkets, and specialty stores. CAGRs were derived from regression analysis against organic food penetration rates and clean-label procurement mandate adoption curves. Forecast inputs incorporated copra price volatility indices and El Niño-drought frequency patterns affecting Philippine and Indonesian harvest cycles.
Forecasts assume regulatory continuity in FDA food labeling rules, USDA National Organic Program standards, and EU organic regulations; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as organic inspector capacity constraints and evolving allergen labeling requirements reshape supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Bee Products Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Cultures Market
Specialty Foods
Dong Quai Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Global Truffle Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Grain-Free Pet Food Market