
 Long Term Data Retention Solutions Market | 2026-2036
Long Term Data Retention Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Long Term Data Retention Solutions Market Foresight
The divergence between premium and commodity tiers is hardening as enterprises separate mission-critical immutable archives from routine backup repositories. Veritas Technologies dominates enterprise-grade compliance archiving through deep policy engine integration. Cohesity leverages web-scale file systems to consolidate secondary storage workloads at lower cost per terabyte.
Long term data retention solutions encompass hardware, software, and services engineered to preserve digital assets for multi-decade durations with guaranteed recoverability, typically employing WORM (Write Once Read Many) media, cryptographic checksums, and geographic dispersion to satisfy legal hold and audit requirements. Cloud storage solutions capture the fastest expansion as hyperscalers introduce locked vault tiers with automated legal-hold policies, while on-premises storage sustains margin concentration among financial institutions subject to SEC 17a-4 and FINRA retention rules. Regulatory compliance use cases anchor enterprise spending, though disaster recovery segments accelerate as ransomware frequency elevates offline recovery to board-level priority.
FDA 21 CFR Part 11, SEC Rule 17a-4, and GDPR Article 5 retention limitations collectively shape product roadmaps by mandating tamper-evident logs, indexed searchability, and documented chain-of-custody protocols. The EU AI Act adds emerging pressure for training data provenance tracking that extends retention obligations into machine learning pipelines. Stakeholders must weigh sovereign data localization mandates against cloud economies of scale when architecting multi-jurisdiction retention frameworks.
Market Dynamics
Immutable storage architectures are forcing infrastructure decisions across financial services, healthcare, and government sectors as ransomware attacks and regulatory mandates harden requirements for tamper-proof, air-gapped data preservation. This structural shift separates mission-critical archives from routine backup tiers.
Growth Catalysts
- SEC 17a-4 and FINRA Retention Mandates:US broker-dealers must preserve electronic records in non-rewriteable, non-erasable formats for specified durations, driving demand for WORM-enabled storage systems with indexed search capabilities.
- Healthcare Digitization:HIPAA Security Rule requirements for electronic protected health information backup and disaster recovery are accelerating hospital system investments in long-term clinical data archives with guaranteed recoverability.
- Ransomware Frequency:Board-level prioritization of offline recovery capabilities is elevating immutable tape and air-gapped vault architectures from IT preference to executive mandate.
Market Restraints
- Input Cost Volatility:Rare earth elements and specialized magnetic tape substrate supply concentration in Japan and limited semiconductor fabrication for storage controllers create pricing pressure on hardware procurement.
- Technical Obsolescence Risk:Multi-decade retention obligations outpace media format lifecycles, forcing costly migration projects and format-agnostic abstraction layer investments.
- Substitution from Hyperscale Cloud:Locked vault tiers with automated legal-hold policies from AWS, Azure, and Google Cloud are capturing mid-market segments that previously defaulted to on-premises tape infrastructure.
Strategic Opportunities
- EU AI Act Provenance Tracking:Emerging requirements for training data lineage documentation extend retention obligations into machine learning pipelines, creating new compliance service revenue streams.
- Underpenetrated German Mittelstand:Mid-sized manufacturers subject to CSRD sustainability reporting and product lifecycle documentation mandates represent a greenfield segment for managed archive services.
- Technology Convergence:Blockchain-anchored cryptographic checksums combined with quantum-resistant encryption are enabling next-generation tamper-evident logging for high-stakes litigation hold scenarios.
Industry Challenges
- Specialized Talent Scarcity:Expertise in legacy tape format migration, cryptographic key lifecycle management, and cross-jurisdiction compliance engineering commands premium compensation and constrains implementation velocity.
- Integration Complexity:Enterprise content management systems, electronic health record platforms, and trading surveillance applications each demand custom connector development for seamless archival workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Term Data Retention Solutions Market |
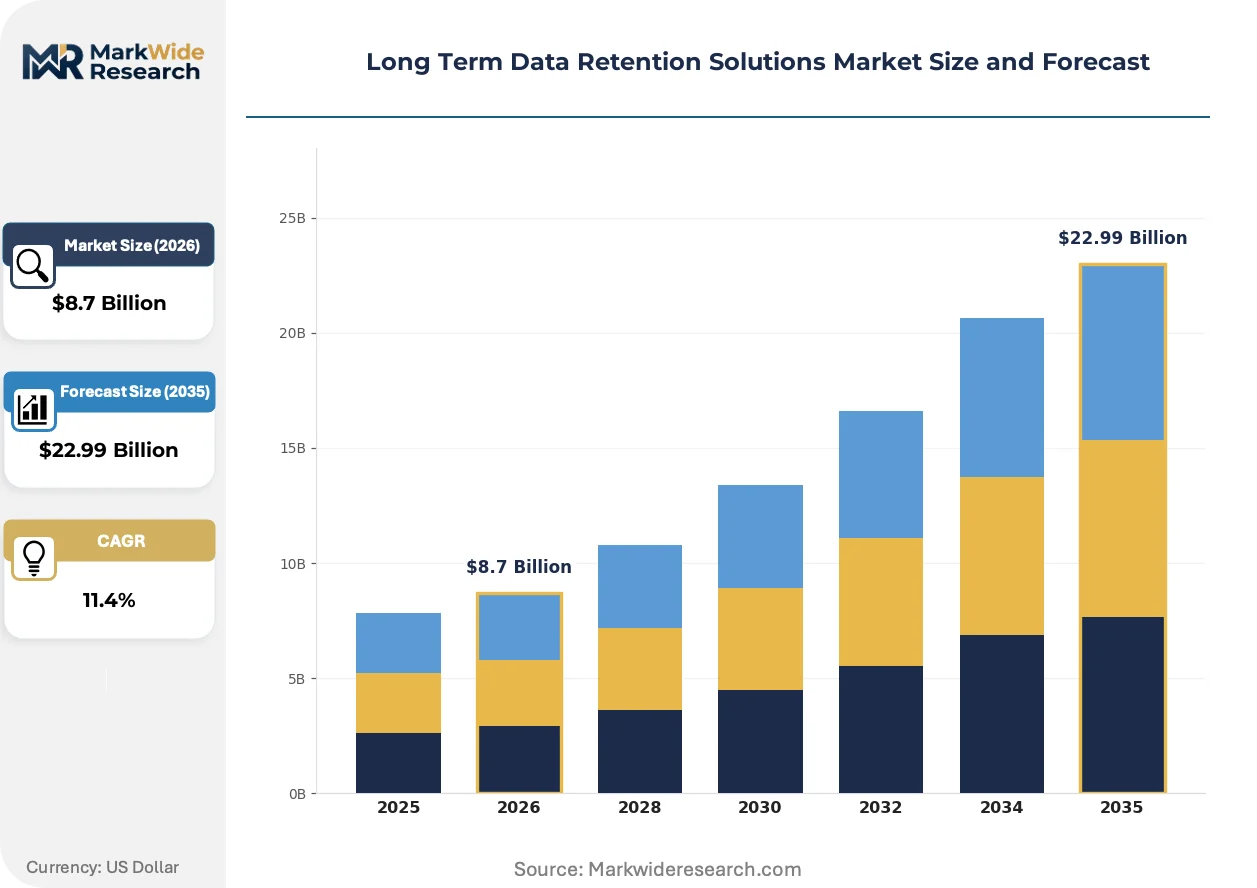
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud Storage, On-Premises Storage, Hybrid Storage, Archiving Solutions Data Type: Structured Data, Unstructured Data, Semi-Structured Data, Backup Data Use Case: Regulatory Compliance, Disaster Recovery, Data Archiving, Operational Continuity End User: Healthcare Organizations, Financial Institutions, Government Agencies, Educational Institutions |
| Companies Covered | Veeam Software, Cohesity, Zerto, Veritas Technologies, Microsoft, Google, Iron Mountain, Solix Technologies, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Term Data Retention Solutions Market Shifts & Advancements
Storage vendors are embedding policy engines directly into hardware controllers to automate legal-hold enforcement and chain-of-custody documentation. This convergence of software-defined governance with physical media is compressing procurement cycles and reshaping vendor selection criteria.
Object storage software is integrating immutable versioning, automated tiering to tape libraries, and cryptographic integrity verification into unified namespaces. Financial institutions in the United States are deploying these stacks to satisfy SEC Rule 17a-4(f) requirements while reducing operational overhead. The technology is integrating compliance automation directly into the data path, eliminating separate workflow orchestration layers.
GDPR Article 5 retention limitations and the EU AI Act are mandating documented erasure procedures alongside preservation obligations, creating demand for policy engines that govern both retention and destruction. European data protection authorities are auditing proof-of-deletion capabilities with the same rigor applied to recovery testing. Healthcare and AI development organizations in Germany and France are restructuring their retention frameworks to accommodate these dual mandates.
Consumption-based procurement of archive capacity is displacing capital-intensive tape library purchases among mid-market enterprises. Managed service providers in Japan and the United States are offering petabyte-scale vaulting with guaranteed retrieval SLAs, transferring operational risk from customer to vendor. This model is accelerating fastest among pharmaceutical companies subject to FDA 21 CFR Part 11 clinical data retention requirements.
Long Term Data Retention Solutions Market Segmentation
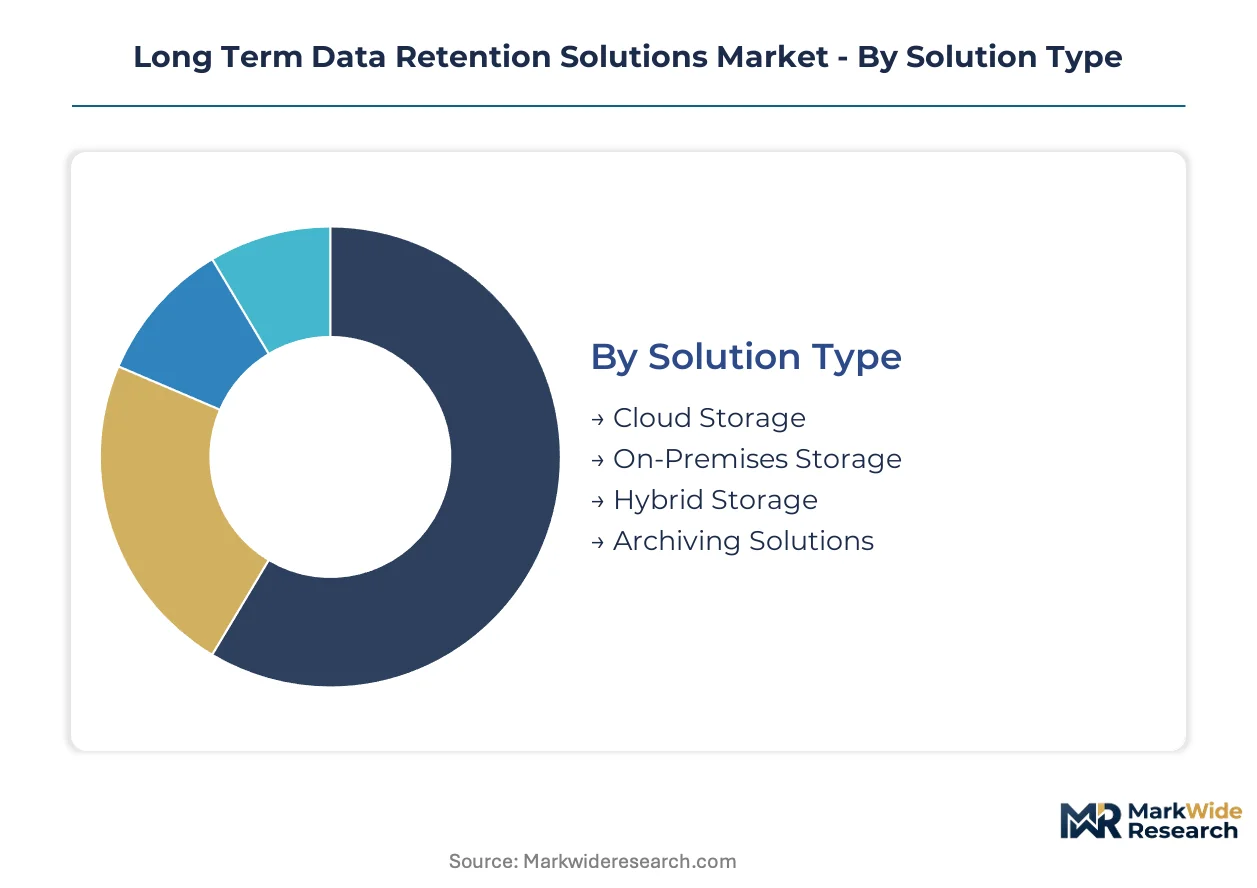
Long term data retention solutions fragment across four dimensions that determine compliance architecture and procurement economics. Solution type dictates capital intensity and operational control. Data type shapes indexing requirements and retrieval latency. Use case separates mission-critical archives from routine backup tiers. End user verticals impose distinct regulatory frameworks that reshape vendor selection criteria.
Solution Type:
Cloud storage vaults demand SOC 2 Type II and ISO 27001 certifications. On-premises tape libraries require SEC 17a-4(f) and FINRA compliance attestations. Hybrid architectures must satisfy both sets simultaneously.
- Cloud Storage:Hyperscaler-locked vault tiers with automated legal-hold policies and geographic redundancy. Financial services firms in the United States are migrating petabyte-scale archives to AWS Glacier and Azure Archive to satisfy retention mandates while eliminating tape library maintenance.
- On-Premises Storage:Physical tape libraries and WORM-enabled disk arrays with air-gapped isolation. German banks and Japanese insurers retain these configurations to satisfy sovereign data localization requirements and ransomware recovery SLAs.
- Hybrid Storage:Policy-driven tiering between hot cloud tiers and cold on-premises archives. Healthcare organizations deploy these architectures to balance HIPAA disaster recovery speed with long-term cost containment.
- Archiving Solutions:Software-defined governance layers with automated chain-of-custody documentation. Pharmaceutical companies subject to FDA 21 CFR Part 11 requirements drive specialized demand for tamper-evident logging capabilities.
Leading the category by volume: On-Premises Storage. Growing fastest: Cloud Storage.
Data Type:
Structured data archives require schema preservation and queryable indexes. Unstructured repositories demand content-aware classification engines. Backup data carries distinct recovery point objective requirements.
- Structured Data:Relational database snapshots and transactional logs with enforced referential integrity. Financial trading surveillance systems in the United States generate the highest ingestion volumes for SEC-mandated retention.
- Unstructured Data:Email archives, medical imaging, and document repositories without predefined schemas. HIPAA-covered entities in Germany and France invest heavily here for clinical record discoverability.
- Semi-Structured Data:JSON logs, XML configuration files, and machine-generated telemetry with partial schema. IoT device manufacturers in Japan use these archives for product liability defense.
- Backup Data:Full system images and incremental snapshots optimized for rapid recovery. Ransomware frequency has elevated this segment to board-level priority across all regulated verticals.
Structured Data commands the largest share of compliance-driven spending. Unstructured Data is climbing the fastest as AI training data provenance requirements expand.
Use Case:
Regulatory compliance anchors enterprise budgets with non-negotiable retention statutes. Disaster recovery has shifted from IT preference to executive mandate. Data archiving separates active discovery repositories from deep cold storage.
- Regulatory Compliance:Mandated preservation with indexed searchability and legal-hold automation. SEC 17a-4, HIPAA Security Rule, and GDPR Article 5 collectively shape product roadmaps across vendor portfolios.
- Disaster Recovery:Offline recovery capabilities with guaranteed retrieval SLAs and air-gapped isolation. Immutable tape formats are displacing disk-based backup in ransomware-conscious organizations.
- Data Archiving:Long-term preservation for reference, research, and litigation readiness. Academic medical centers in the United States and Germany maintain multi-decade clinical trial archives here.
- Operational Continuity:Business process resumption with defined recovery time objectives. Manufacturing firms in Japan deploy these solutions for supply chain documentation continuity.
Regulatory Compliance leads by committed spend. Disaster Recovery is gaining share fastest as offline recovery becomes a board-level priority.
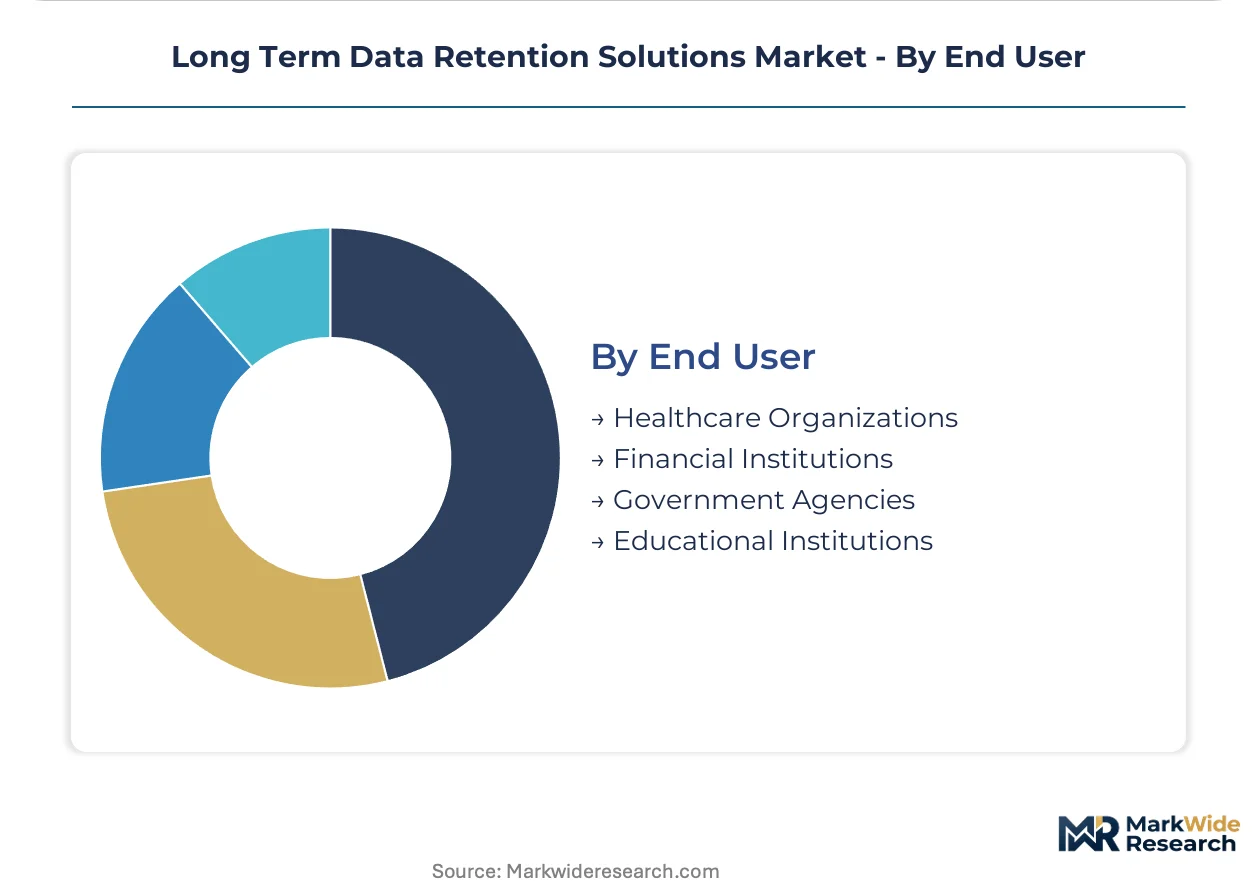
End User:
Healthcare organizations face HIPAA Security Rule and FDA 21 CFR Part 11 dual mandates. Financial institutions navigate SEC, FINRA, and state insurance commissioner requirements. Government agencies impose sovereign data localization.
- Healthcare Organizations:Hospital systems and pharmaceutical manufacturers with electronic health record and clinical data retention obligations. HIPAA mandates and digitization initiatives are accelerating archive modernization.
- Financial Institutions:Broker-dealers, banks, and insurers subject to SEC 17a-4 and FINRA retention rules. These organizations drive demand for WORM-enabled systems with indexed search capabilities.
- Government Agencies:Federal, state, and municipal entities with classified and unclassified record preservation mandates. Sovereign data localization requirements favor on-premises or in-country cloud deployments.
- Educational Institutions:Universities and research organizations with grant-funded data management plans. NIH and NSF retention requirements shape procurement for federally funded research.
Healthcare Organizations lead by committed archive capacity. Financial Institutions are expanding fastest as ransomware recovery elevates immutable storage to executive mandate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district anchors European demand for immutable storage vaults as German banks consolidate petabyte-scale archives under CSRD and GDPR dual mandates. Tokyo's Kanto corridor and Boston's healthcare cluster drive comparable infrastructure investments across their respective regulatory environments.
United States
SEC 17a-4 and FINRA retention rules compel broker-dealers in Manhattan and Chicago to maintain WORM-enabled archives with indexed search capabilities. HIPAA Security Rule enforcement accelerates hospital system modernization across the Boston-Cambridge corridor. Financial institutions in Charlotte and San Francisco are migrating legacy tape infrastructure to hybrid cloud architectures.
Germany
CSRD sustainability reporting and product lifecycle documentation mandates activate demand among mid-sized manufacturers in Bavaria and Baden-Württemberg. GDPR Article 5 retention limitations require documented erasure procedures alongside preservation obligations. Industrial clusters around Stuttgart and Munich are restructuring retention frameworks for dual compliance.
Japan
METI guidelines and sovereign data localization requirements preserve on-premises tape library deployments among Tokyo and Osaka financial institutions. Rare earth element supply concentration for magnetic tape substrates creates procurement leverage for domestic manufacturers. Pharmaceutical companies in Kobe and Nagoya maintain FDA 21 CFR Part 11 compliant clinical data archives.
United Kingdom
FCA conduct rules and emerging AI Act alignment pressure drive archive modernization among London-based asset managers and insurers. NHS digitization initiatives accelerate long-term clinical data preservation investments across the Greater Southeast. Research institutions in Cambridge and Oxford restructure retention frameworks for grant-funded data management plans.
France
CNIL enforcement of GDPR retention limitations and ANSM pharmaceutical documentation requirements shape hospital and manufacturer procurement in Île-de-France. EU AI Act provenance tracking obligations extend retention into machine learning pipelines for Paris-based AI developers. Healthcare clusters in Lyon and Toulouse invest in policy engines governing both retention and destruction.
Long Term Data Retention Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and policy engine sophistication. Enterprise-grade vendors command pricing power through deep regulatory integration while mid-market specialists compete on cost per terabyte. Three archetypes dominate: legacy infrastructure incumbents with tape library installed bases, web-scale software-defined platforms, and hyperscaler-locked vault operators. Consolidation through strategic acquisitions and technology licensing partnerships represents the primary competitive vector.
Within the enterprise compliance tier, Veritas Technologies and Cohesity occupy positions defined by policy engine depth and web-scale consolidation capabilities respectively. Veeam Software exemplifies the backup-to-archive convergence archetype. Microsoft and Google sit within the hyperscaler vault tier, leveraging cloud-native locked storage tiers with automated legal-hold automation. These five anchors span the full spectrum from on-premises WORM systems to consumption-based cloud archival.
| Leading Market Players |
|---|
| Veeam Software |
| Cohesity |
| Zerto |
| Veritas Technologies |
| Microsoft |
| Iron Mountain |
| Solix Technologies |
| NetApp |
| Others |
Supply & Pricing Matrix
Captive integration into rare earth element refining and magnetic tape substrate production anchors supply position and pricing power for Japanese manufacturers serving financial institutions under METI localization mandates. This vertical control over specialized inputs insulates premium-tier vendors from commodity cost swings while forcing mid-market competitors toward outsourced cloud vault partnerships.
Pricing Analysis
Outcome-based pricing tied to guaranteed retrieval SLAs and legal-hold automation anchors enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels separates WORM-certified immutable archives from routine backup tiers. Cost compression in the standard tier intensifies as hyperscaler locked-vault services capture mid-market volume previously served by on-premises tape libraries. Healthcare organizations subject to HIPAA Security Rule mandates exhibit highest price sensitivity due to constrained capital budgets, while financial institutions facing SEC 17a-4 enforcement show lowest sensitivity to secure compliance-grade solutions.
Supply Chain Analysis
Regional distribution centers in Japan, the United States, and Germany maintain hub-and-spoke patterns for magnetic tape media and specialized storage controllers. Manufacturing draws from concentrated rare earth element deposits and semiconductor fabrication facilities concentrated in East Asia. Single-source vulnerability for advanced tape substrates creates procurement risk for European and North American system integrators. Distribution runs through authorized value-added resellers and direct enterprise sales teams, with managed service providers emerging as a secondary channel for consumption-based archive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
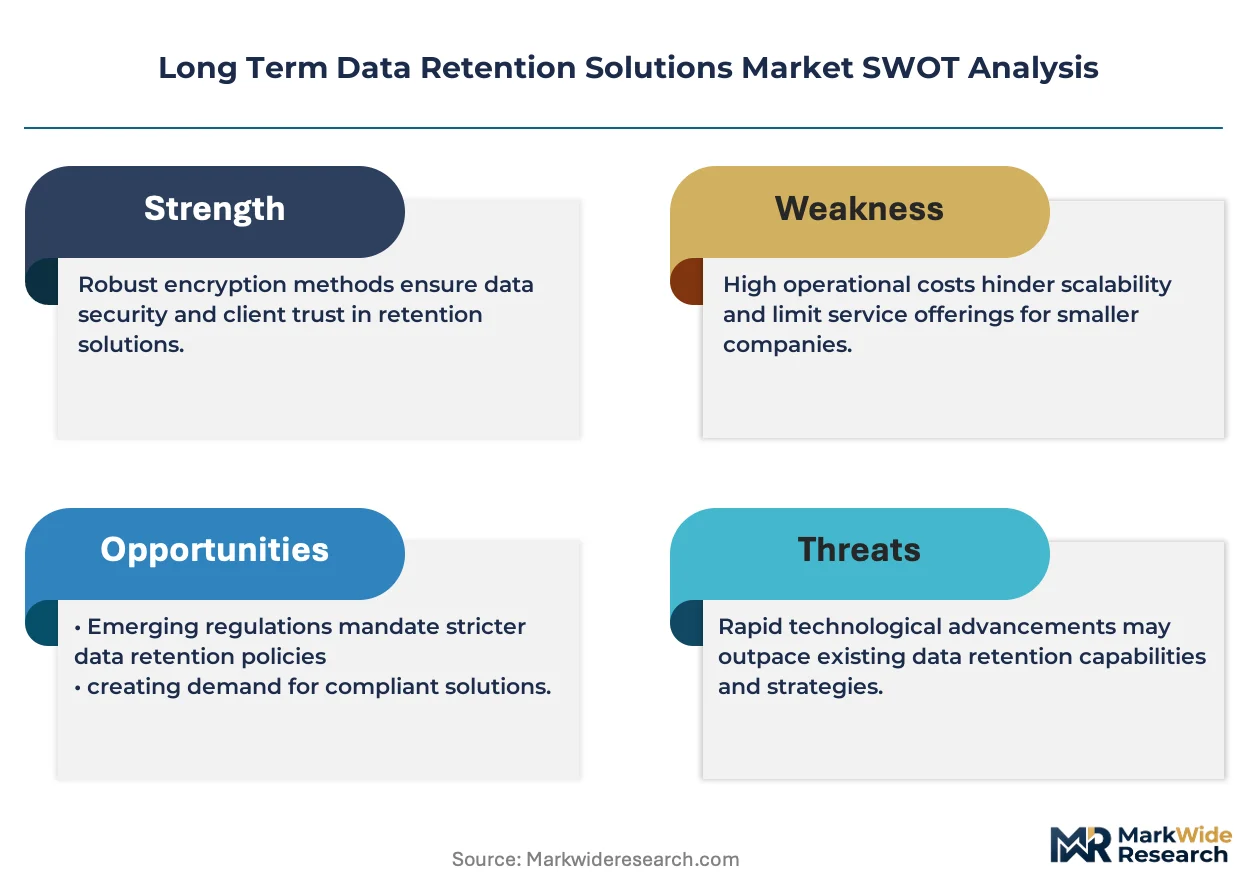
This market reads as a cost-of-compliance story where SEC 17a-4 and FINRA retention mandates create a barrier-to-entry moat for vendors with certified WORM capabilities and indexed search infrastructure.
For Market Incumbents: Hedge against hyperscaler substitution by deepening policy engine integration with electronic health record platforms and trading surveillance applications. Secure tape format migration expertise through targeted hiring in Japan and Germany, where legacy archive volumes concentrate. Capacity expansion in sovereign data localization jurisdictions preserves positioning among government agencies and regulated financial institutions.
For New Entrants and Emerging Players: The mid-market price-point gap between premium enterprise compliance suites and basic cloud backup services offers white-space opportunity. Target pharmaceutical manufacturers subject to FDA 21 CFR Part 11 clinical data requirements in the United States and Japan, where specialized tamper-evident logging commands premium pricing. A managed service wrapper around hyperscaler vault infrastructure provides the fastest go-to-market path without capital-intensive hardware development.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking compliance certification depth and by legacy infrastructure vendors pursuing software-defined consolidation. Long-term viability hinges on quantum-resistant encryption and blockchain-anchored checksum capabilities across the projection horizon. Monitor EU AI Act provenance tracking enforcement as the inflection signal for training data lineage service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Policy Engine Integration | Embedded governance automation satisfies SEC 17a-4(f) without separate workflow layers. |
| Quantum-Resistant Encryption Development | Cryptographic upgrades address emerging threats to multi-decade archive integrity. |
| Managed Archive Service Launch | Consumption-based models transfer operational risk from healthcare providers to vendors. |
| Tape Format Migration Services | Technical obsolescence risk creates recurring revenue from legacy archive modernization. |
| EU AI Act Compliance Module | Training data provenance tracking extends retention obligations into machine learning pipelines. |
Research Methodology
Multi-period observation of regulatory enforcement patterns, hyperscaler vault tier introductions, and ransomware incident frequencies anchored the trend analysis, supplemented by interviews with compliance officers at broker-dealers, HIPAA security officers at hospital systems, procurement leads at pharmaceutical manufacturers, and archive infrastructure specialists at systems integrators. Secondary validation drew from SEC enforcement actions, FDA 483 inspection observations, GDPR Article 5 guidance documents, and hyperscaler service launch announcements. Bottom-up segmentation modeling triangulated against top-down regulatory mandate sizing.
Input-output matrices mapped solution type, data type, use case, and end user vertical against geographic regulatory clusters across the projection horizon. CAGRs were derived from segment-level demand curves weighted by compliance mandate enforcement intensity. Forecast inputs included electronic health record adoption trajectories, SEC examination priority shifts, and cloud storage price decline curves.
Inputs from regulatory filing databases and vendor service documentation were available through the study window; gaps in private contract pricing and actual recovery test frequencies introduce uncertainty bands around penetration rate assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
South Africa Data Center Power Market