
 Europe Automated Storage and Retrieval System Market | 2026-2036
Europe Automated Storage and Retrieval System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automated Storage and Retrieval System Market Foresight
E-commerce fulfillment centers is reorganizing demand patterns across the European ASRS landscape, pulling investment away from traditional retail distribution models. SSI Schaefer AG leverages its vertical integration in software and hardware to dominate complex multi-site installations. KION Group AG anchors its position through manufacturing scale across German production facilities. Knapp AG specializes in pharmaceutical-grade automation, sustaining premium positioning in regulated cold-chain environments.
An automated storage and retrieval system comprises computer-controlled racks, cranes, shuttles, and conveyors that store and retrieve materials with minimal human intervention, typically operating in aisles under 1.5 meters wide and reaching heights exceeding 40 meters in high-bay configurations. Unit Load systems lead European installed base due to pallet-handling dominance in manufacturing and bulk distribution, while Vertical Lift Module installations are expanding fastest in spare-parts logistics and micro-fulfillment where floor-space constraints dominate. Robotics technology within the technology dimension commands attention as labor shortages intensify across Central European warehousing clusters.
CE marking requirements under the EU Machinery Directive establish baseline safety and interoperability standards for ASRS deployment across member states, while the EU Green Deal's energy-efficiency frameworks shape procurement criteria for new installations. Germany's KBA and France's national labor inspectorates enforce workplace automation safety protocols that influence system design specifications. Stakeholders must monitor how the EU AI Act's risk-classification rules will apply to autonomous decision-making in robotic storage systems.
Market Dynamics
The EU Green Deal's decarbonization mandates are compressing warehouse operators' technology refresh cycles, forcing capital reallocation toward energy-efficient automation before legacy equipment reaches end-of-life. This regulatory pressure layer stacks atop labor scarcity in Central European logistics clusters, creating compound urgency for system modernization.
Growth Catalysts
- E-commerce fulfillment density:Germany's automotive and pharmaceutical distribution hubs are modernizing legacy infrastructure to handle SKU proliferation and same-day delivery windows. Multi-tier racking configurations now dominate new build specifications.
- REACH and RoHS compliance:Material handling equipment manufacturers face restricted substance mandates that favor modular, upgradeable system architectures over welded, disposable designs. Component standardization accelerates retrofit economics.
- Robotics convergence:Autonomous mobile robots are integrating with fixed-rack ASRS infrastructure in French and Dutch fulfillment centers, extending system flexibility without aisle reconfiguration.
Market Restraints
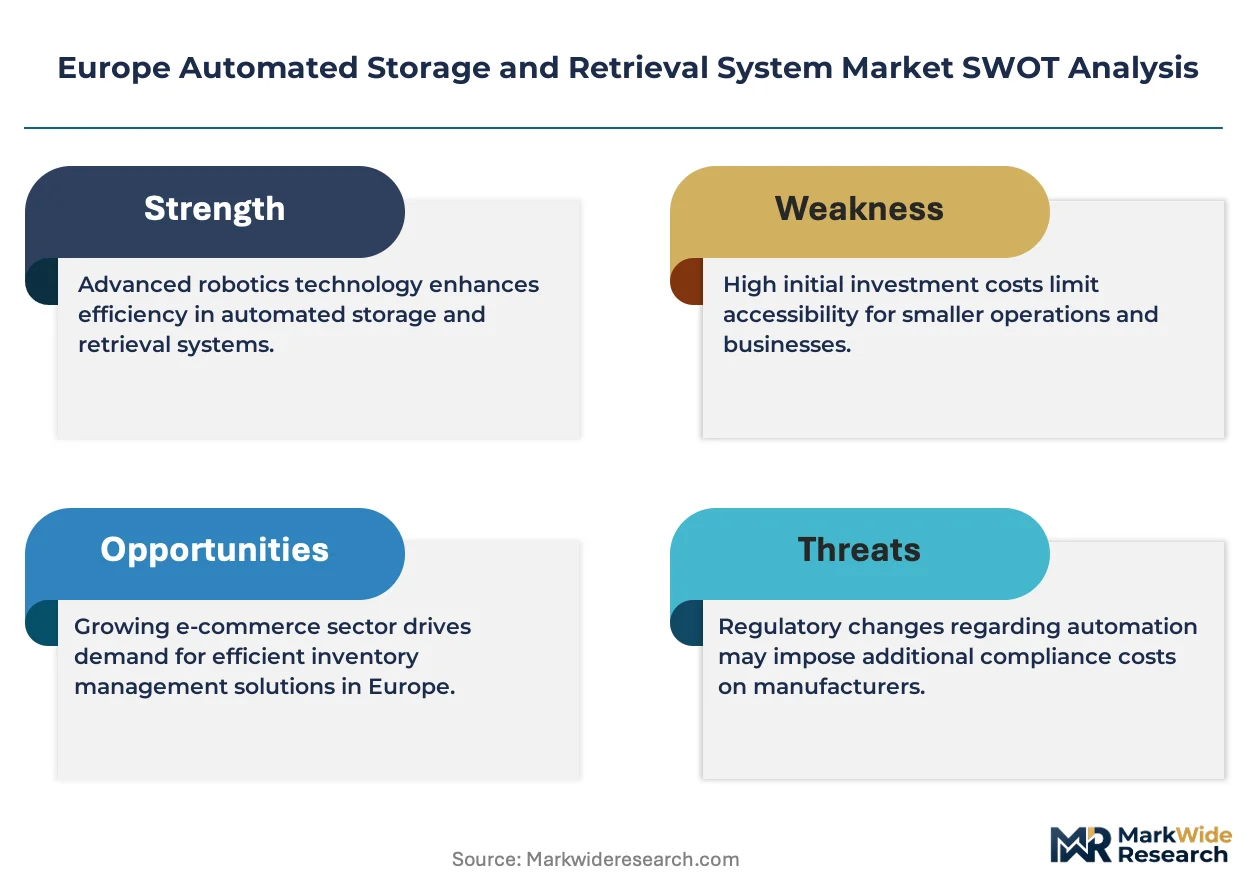
- Steel input volatility:High-bay rack fabrication depends on structural steel pricing that fluctuates with energy-intensive European smelter output. German fabricators pass through 60-90 day lagged adjustments.
- Control system supplier concentration:PLC and warehouse management software layers concentrate among a handful of vendors, creating integration bottlenecks for mid-market warehouse operators seeking multi-site standardization.
- CE marking timeline friction:The EU Machinery Directive's conformity assessment procedures extend deployment schedules by 4-8 months for novel shuttle configurations, compressing ROI realization windows.
Strategic Opportunities
- Polish and Czech manufacturing corridors:Greenfield industrial parks in these markets remain underpenetrated by high-bay automation, offering first-mover positioning before labor cost convergence accelerates.
- Cold-chain pharmaceutical grade:EMA's Good Distribution Practice requirements for temperature-verified storage create premium segmentation for validated systems with continuous monitoring documentation.
- EU AI Act risk classification:Autonomous decision-making in robotic storage systems will face new conformity obligations, favoring vendors with pre-positioned algorithmic transparency and human oversight architectures.
Industry Challenges
- Mechatronics technician scarcity:Germany's KBA and industrial employer federations report unfilled vacancies for crane maintenance and control system diagnostics that outstrip vocational training pipeline output.
- Legacy WMS integration:Proprietary data protocols in 1990s-era warehouse management systems require expensive middleware development for real-time ASRS coordination, delaying unified inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automated Storage and Retrieval System Market |
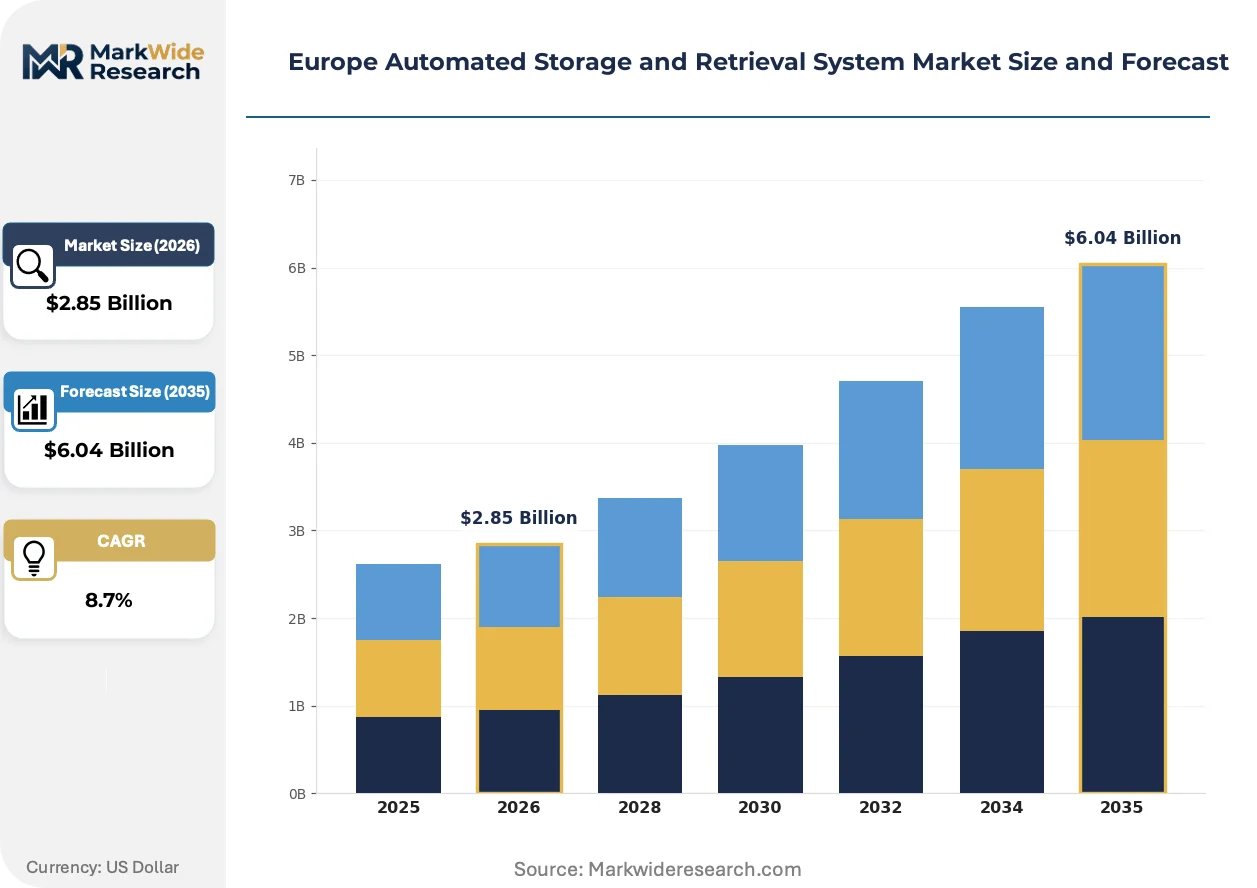
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load, Mini Load, Vertical Lift Module, Automated Tote System End User: Retail, E-Commerce, Manufacturing, Automotive Technology: Artificial Intelligence, Robotics, IoT, Barcode Scanning Installation: Fixed, Mobile, Modular, Custom |
| Companies Covered | SSI Schaefer AG, KION Group AG, Knapp AG, Swisslog AG, Daifuku Co. Ltd, Jungheinrich AG, Kardex Holding AG, Mecalux SA, TGW Logistics Group GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automated Storage and Retrieval System Market Shifts & Advancements
Shuttle-based storage architectures are compressing the viable footprint for automated fulfillment, enabling micro-fulfillment penetration into urban logistics constraints previously reserved for manual operations.
Three-dimensional shuttle systems with aisle-changing capability are displacing traditional crane-based unit load handling in mid-rise configurations between 12 and 25 meters. German automotive spare parts distributors are adopting these for 24-hour service level commitments. The technology is displacing fixed-aisle crane investments that require 3-5 year capacity commitment horizons.
The EU AI Act's risk-classification framework for autonomous industrial systems is mandating algorithmic audit trails and human-in-the-loop protocols for robotic storage decisions. System vendors must reengineer control architectures to document decision logic and enable operator override. Pharmaceutical and food-grade cold storage facilities in France and the Netherlands face the earliest compliance deadlines given product safety criticality.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Dutch e-commerce operators now procure crane maintenance, software updates, and spare parts logistics through separate specialist vendors rather than single-source OEM agreements. This procurement pattern is most visible in multi-site operators with internal technical capabilities that can coordinate fragmented service layers.
Europe Automated Storage and Retrieval System Market Segmentation
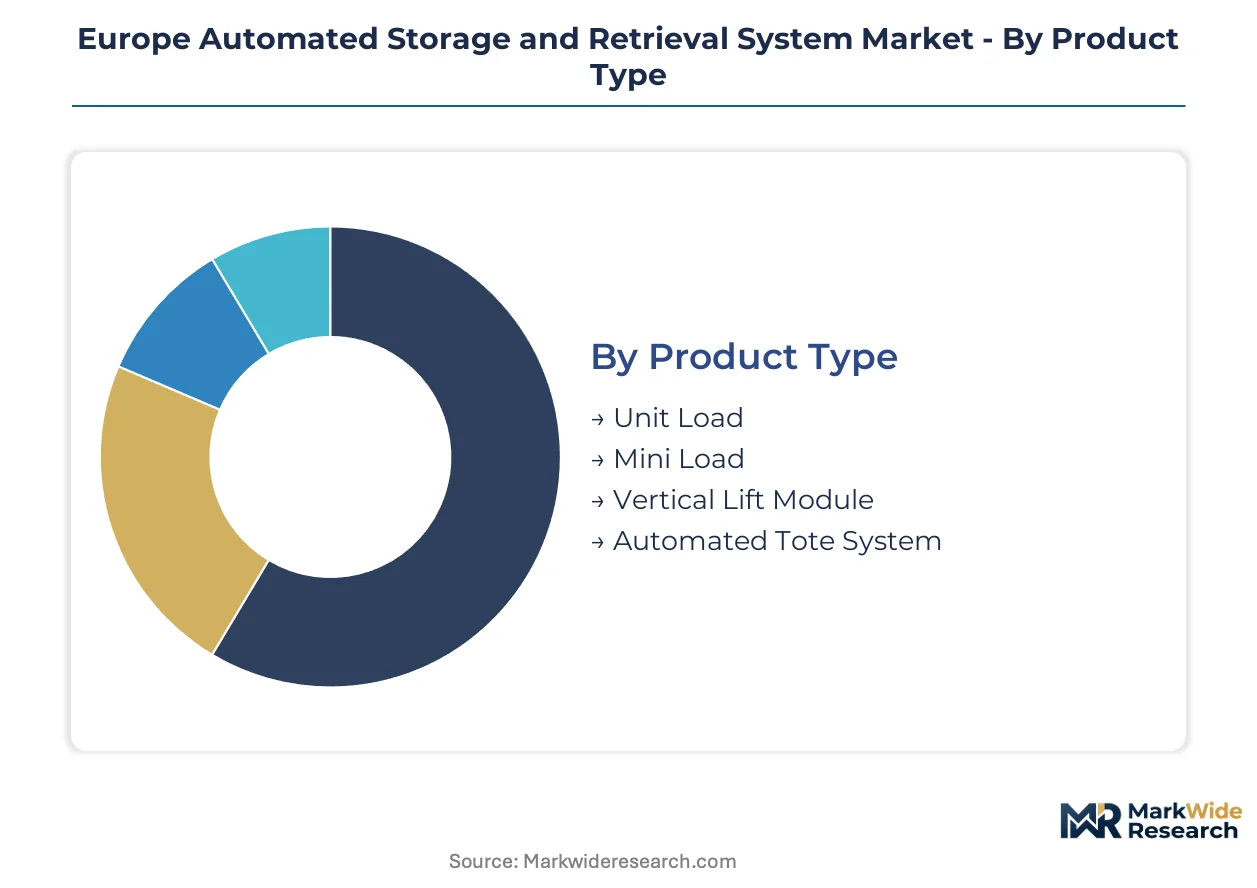
ASRS procurement patterns diverge sharply across European industrial corridors. German automotive clusters favor high-bay unit load systems, while Dutch e-commerce operators prioritize modular shuttle configurations for rapid reconfiguration.
Product Type:
German and French demand concentrates in pallet-handling systems for manufacturing integration, while Benelux fulfillment centers drive tote-based and vertical lift adoption for SKU density.
- Unit Load:Pallet-based crane and shuttle systems handle loads exceeding 1,000 kilograms in high-bay configurations exceeding 30 meters. German automotive spare parts distributors in Stuttgart and Wolfsburg corridors deploy these for 24-hour service commitments, with rack structures fabricated from European structural steel subject to REACH substance restrictions.
- Vertical Lift Module:Enclosed column systems with extractor mechanisms retrieve totes within compact footprints under 15 square meters. French pharmaceutical distributors in Lyon and Strasbourg clusters install these for temperature-controlled API storage, complying with EMA Good Distribution Practice documentation requirements.
- Mini Load:Bin-handling shuttles serve totes and cartons in mid-rise configurations between 8 and 18 meters. Dutch third-party logistics operators favor these for e-commerce returns processing.
- Automated Tote System:Conveyor-integrated buffer systems sequence individual totes for picking station replenishment. Polish greenfield fulfillment centers adopt these for same-day delivery density.
Unit Load commands the established base. The steepest expansion runs through Vertical Lift Module.
End User:
Cost tier segmentation separates capital-intensive manufacturing integration from fulfillment operators seeking payback horizons under four years.
- Manufacturing:Production-integrated ASRS synchronize with assembly line takt times, requiring PLC coordination with MES layers. German automotive OEMs in Bavaria and Baden-Württemberg specify these for sequenced parts delivery to final assembly, with CE marking under the EU Machinery Directive governing safety interlocks.
- E-Commerce:Fulfillment-oriented systems prioritize throughput velocity over storage density, with shuttle-based architectures enabling same-day cutoffs. Dutch operators around Rotterdam and Venlo logistics parks drive adoption of aisle-changing shuttles for SKU proliferation management.
- Automotive:Tier-one suppliers deploy high-bay systems for sequenced delivery to OEM assembly plants. French suppliers in the Hauts-de-France automotive belt favor these for just-in-sequence contracts.
- Retail:Regional distribution centers consolidate store replenishment with case-pick automation. Italian fashion retailers in Milan-Turin corridor adopt these for seasonal inventory surges.
Manufacturing absorbs the highest capital intensity. E-Commerce is gaining share fastest through fulfillment densification.
Technology:
Application criticality determines technology stack depth, with pharmaceutical cold chain demanding full sensor integration while bulk distribution runs on simpler barcode infrastructure.
- Robotics:Autonomous mobile robots integrate with fixed-rack ASRS for flexible goods-to-person fulfillment. French and Dutch e-commerce operators deploy these to extend system flexibility without aisle reconfiguration, though EU AI Act risk classification will mandate algorithmic audit trails for autonomous decision-making.
- Artificial Intelligence:Predictive analytics optimize slotting algorithms and maintenance scheduling based on throughput patterns. German pharmaceutical distributors adopt these for batch prioritization in validated environments.
- IoT:Sensor networks monitor rack structural integrity, crane vibration, and energy consumption in real time. Spanish perishables operators use these for continuous cold chain verification.
- Barcode Scanning:Linear and 2D code reading provides baseline inventory tracking at lower capital cost. Eastern European manufacturing corridors favor these for proven reliability.
Robotics anchors current investment. AI is climbing the fastest as labor scarcity intensifies predictive automation requirements.
Installation:
Customer technical capabilities and site constraints determine installation architecture, with multi-site operators favoring standardization while urban fulfillment demands custom footprints.
- Modular:Prefabricated rack and crane components enable phased capacity expansion without operational shutdown. Polish and Czech greenfield industrial parks favor these for demand uncertainty management.
- Fixed:Welded rack structures with dedicated aisle cranes maximize density for stable SKU portfolios. German bulk distributors specify these for 20-year asset lifecycles.
- Mobile:Rack systems mounted on guided vehicles eliminate fixed aisle requirements, enabling footprint reconfiguration. Benelux operators test these for seasonal demand fluctuation.
- Custom:Engineered-to-order configurations address constrained urban sites or unusual load profiles. Paris and London micro-fulfillment centers require these for basement and multi-story installations.
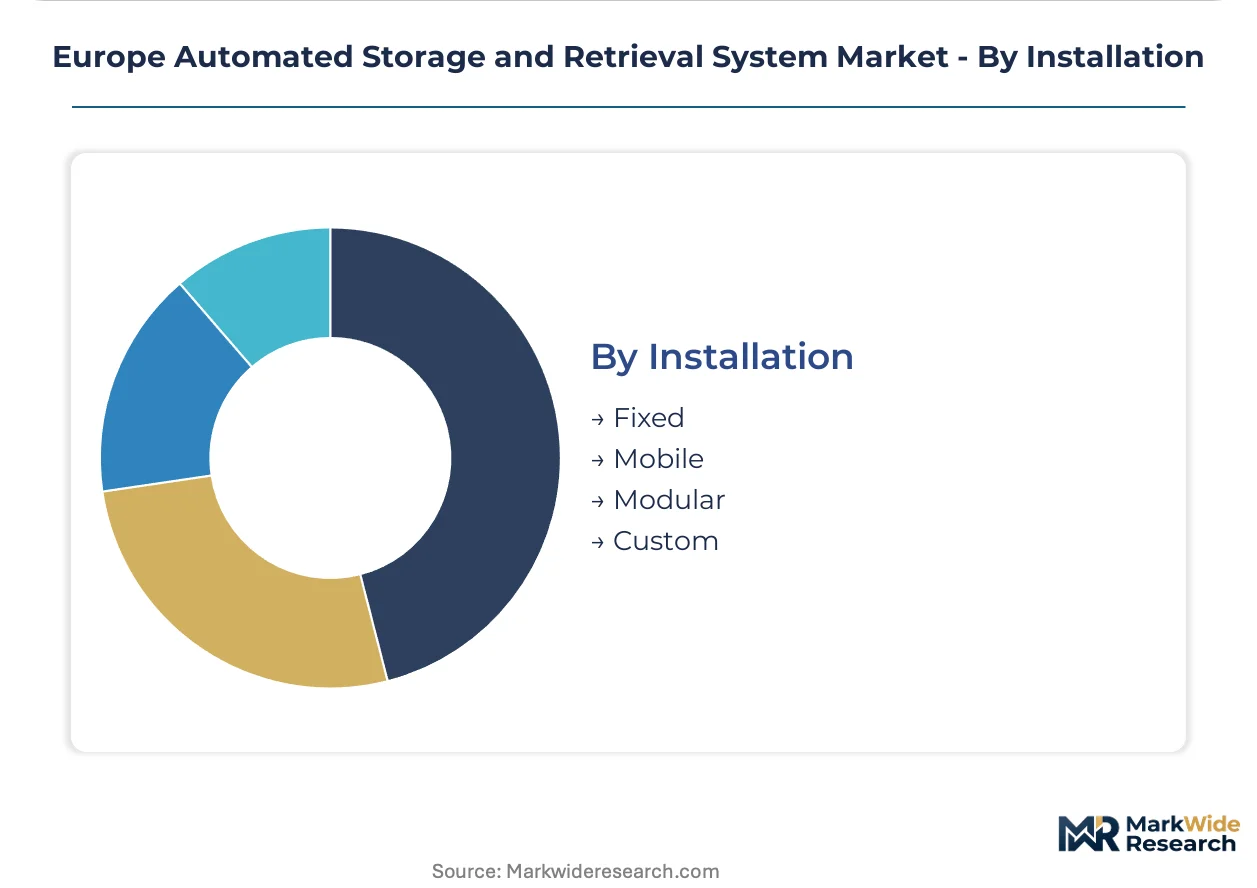
Fixed installations retain the largest installed base. Modular is expanding most quickly through greenfield uncertainty hedging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor's freight rail network underwrites Germany's dominance in European logistics automation, while Rotterdam's deep-water port infrastructure anchors Dutch distribution density.
Germany
Automotive sequenced parts delivery and pharmaceutical cold-chain modernization drive capital deployment. The KBA enforces workplace automation safety protocols that shape crane and shuttle system specifications. Stuttgart and Wolfsburg corridors host tier-one suppliers installing high-bay unit load systems for 24-hour OEM service commitments.
Netherlands
E-commerce fulfillment density and perishables distribution concentrate procurement around modular shuttle architectures. REACH substance restrictions favor upgradeable rack designs over welded structures. Rotterdam and Venlo logistics parks host third-party operators testing aisle-changing shuttles for SKU proliferation management.
France
Pharmaceutical-grade automation and automotive just-in-sequence contracts dominate demand patterns. EMA Good Distribution Practice requirements mandate temperature-verified storage with continuous monitoring documentation. Lyon and Strasbourg clusters install vertical lift modules for API storage, while Hauts-de-France automotive belt suppliers deploy high-bay systems.
Poland
Greenfield industrial parks and manufacturing corridor expansion create first-mover positioning opportunities before labor cost convergence accelerates. EU Green Deal decarbonization mandates compress technology refresh cycles for warehouse operators. Warsaw and Łódź logistics zones adopt automated tote systems for same-day delivery density.
Belgium
Pharmaceutical distribution hubs and port-connected fulfillment centers drive mid-rise automation adoption. CE marking under the EU Machinery Directive extends deployment timelines for novel shuttle configurations. Antwerp's chemical and logistics cluster integrates ASRS with port-centric supply chains.
Europe Automated Storage and Retrieval System Market Competitive Landscape
Listed leaders compete with private specialists across hardware fabrication and software integration dimensions. The vendor base concentrates among German and Swiss engineering groups with captive manufacturing assets, while mid-market operators face integration bottlenecks from concentrated PLC and WMS suppliers. Strategic archetypes span vertically integrated system architects, component-specialist fabricators, and software-centric integrators. Competitive moves center on multi-site standardization contracts and service contract unbundling.
Among German-based engineering groups, SSI Schaefer AG and KION Group AG exemplify scale-driven system architects with manufacturing depth. Swisslog AG represents the cross-border specialist tier with logistics automation heritage. Knapp AG occupies a position within the pharmaceutical-grade segment, reflecting premium positioning in regulated cold-chain environments. These anchors demonstrate how geographic concentration in German-speaking industrial corridors shapes competitive positioning.
| Leading Market Players |
|---|
| SSI Schaefer AG |
| KION Group AG |
| Knapp AG |
| Swisslog AG |
| Daifuku Co. Ltd |
| Jungheinrich AG |
| Kardex Holding AG |
| Mecalux SA |
| TGW Logistics Group GmbH |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with German steel fabricators lock in rack structure pricing visibility for warehouse operators committing to multi-site rollouts, insulating procurement teams from energy-intensive smelter output volatility while constraining supplier switching flexibility under REACH substance compliance timelines.
Pricing Analysis
Three-tier pricing structure across premium pharmaceutical-grade, standard manufacturing-integrated, and economy modular configurations separates validated cold-chain systems with EMA documentation from bulk distribution equipment. Price differentiation hinges on CE marking complexity and software integration depth. Cost compression in standard tiers is intensifying because mid-market operators fragment procurement across specialist vendors. E-commerce fulfillment operators exhibit highest price sensitivity due to four-year payback mandates, while pharmaceutical distributors accept premium positioning for regulatory risk mitigation.
Supply Chain Analysis
Strait of Hormuz transit exposure for specialty steel alloys from East Asian refiners concentrates raw material risk for European high-bay rack fabricators. Structural steel supply centers on German, Polish, and Czech rolling mills. Control system production draws from German and Swiss PLC specialists. Single-source vulnerability runs through concentrated warehouse management software vendors. Distribution feeds from captive manufacturing facilities through regional system integrators to end-user sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European ASRS penetration sits at early-cycle expansion with greenfield industrial parks in Central Europe driving first-mover positioning before labor cost convergence accelerates adoption curves.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into control system software layers, neutralizing integration bottlenecks from concentrated PLC suppliers. Deepen captive service capabilities to counter unbundling trends among Dutch e-commerce operators. Anchor multi-site standardization contracts before mid-market competitors fragment procurement patterns. For New Entrants and Emerging Players: Aftermarket service fragmentation creates entry points for specialist crane maintenance and spare parts logistics vendors serving multi-site operators with internal technical coordination capabilities. Polish and Czech greenfield corridors offer lowest competitive density for modular system penetration. Pursue software-centric integration partnerships to bypass hardware fabrication capital requirements. For Investors and Strategic Acquirers: Component-specialist fabricators with REACH-compliant upgradeable architectures represent acquisition targets positioned for EU Green Deal-driven refresh cycles. Long-term viability rests on algorithmic transparency capabilities ahead of EU AI Act risk classification enforcement. Watch EMA cold-chain validation backlogs as inflection indicator for pharmaceutical-grade system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Reduces PLC supplier concentration risk for German system architects. |
| Modular Rack Architecture Development | Enables REACH-compliant upgrade paths without full system replacement. |
| Algorithmic Audit Trail Implementation | Positions vendors for EU AI Act conformity obligations in robotic storage. |
| Multi-Site Service Contract Unbundling | Captures fragmented procurement patterns among Dutch e-commerce operators. |
| Polish Greenfield Corridor Expansion | Secures first-mover positioning before labor cost convergence accelerates. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse operations directors, mechatronics maintenance managers, OEM procurement leads, and system integrators, and refined through secondary validation against EU Machinery Directive filings, EMA Good Distribution Practice documentation, customs trade data for steel inputs, and SEC disclosures from listed automation vendors. Bottom-up installation tracking triangulates with top-down market sizing across member state industrial corridors.
Variance decomposition across product type, end-user vertical, technology stack, and installation architecture dimensions structures the analytical framework. CAGRs derive from modeled deployment trajectories incorporating EU Green Deal compliance deadlines and labor scarcity indices. Industry-specific inputs include KBA safety protocol evolution and EMA validation timeline data.
Underlying assumptions cover stable REACH enforcement intensity and linear steel price normalization, with deviation risk concentrated in EU AI Act implementation timing and Central European wage convergence velocity. Practitioners should keep alternative scenarios live as EMA cold-chain documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Brazil Data Center Rack Market