
 France Data Center Power Market | 2026-2036
France Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Power Market Insights
A shortage of certified electrical engineers specialized in high-voltage DC distribution is unwinding project timelines for hyperscale builds across France. Schneider Electric leverages its Grenoble R&D campus to sustain domestic manufacturing of modular power skids. Legrand Group anchors its position through channel control across electrical distribution networks serving colocation campuses. Cummins Inc competes on backup power specialization with natural-gas and diesel genset configurations tailored to French grid reliability profiles.
France data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers continuous electrical energy to server halls, typically operating at 400/230 V AC or 380 V DC with redundancy tiers from N+1 to 2N. Uninterruptible power supply systems dominate capital allocation among product types due to their critical role in bridging millisecond-scale grid interruptions. Liquid cooling technology is displacing legacy air cooling in facilities above 10 MW capacity as heat densities from AI training clusters exceed 50 kW per rack. Cloud service providers represent the fastest-growing end user segment, though government agencies maintain stable procurement through sovereign cloud mandates.
France's national energy regulator and grid operator enforce connection standards that shape data center power architecture, while EU CSRD disclosure rules and the F-Gas Regulation constrain cooling system selection and refrigerant choices. Stakeholders must monitor how forthcoming building efficiency codes and nuclear energy dispatch priorities reshape baseload cost structures for new capacity additions.
Market Dynamics
High-voltage direct current distribution architecture is recalibrating power infrastructure procurement across French hyperscale campuses, compressing legacy AC-centric engineering cycles and rewiring vendor qualification protocols.
Growth Catalysts
- EU Green Deal carbon intensity benchmarks:The framework mandates measurable emissions reductions for digital infrastructure, compelling facility operators to accelerate renewable energy procurement and liquid cooling retrofits.
- Cloud service provider facility buildouts:Hyperscale operators are expanding server hall footprints across Greater Paris, generating concentrated demand for modular uninterruptible power supply systems and high-capacity busway distribution.
- Sovereign cloud procurement mandates:French government agencies are directing stable capital allocation toward domestic colocation capacity, insulating public-sector demand from private-market volatility.
Market Restraints
- Certified electrical engineer scarcity:Specialized high-voltage DC expertise concentrates within Grenoble and Paris engineering clusters, elongating project timelines for hyperscale builds outside these hubs.
- Grid connection queuing protocols:France's national energy regulator enforces sequential interconnection studies that delay energization schedules for facilities above 20 MW capacity.
- F-Gas Regulation refrigerant constraints:The framework limits hydrofluorocarbon deployment in precision cooling systems, restricting equipment sourcing for legacy air-cooled facilities.
Strategic Opportunities
- Marseille submarine cable landing zone expansion:Secondary hub development is attracting edge computing investments, creating demand for distributed power modules with sub-10 MW footprints.
- Lyon pharmaceutical and biotech data residency requirements:Emerging compliance-driven demand is opening colocation niches for mission-critical backup power configurations.
- EU CSRD disclosure alignment services:The mandate is generating advisory revenue streams around Scope 2 emissions verification and power usage effectiveness optimization.
Industry Challenges
- 2N redundancy tier engineering complexity:Dual-path electrical architectures demand synchronized commissioning of independent utility feeds, complicating project handoff protocols.
- Liquid cooling infrastructure retrofit integration:Existing air-cooled facilities face mechanical room reconfiguration costs and floor loading recertification when accommodating AI training clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Power Market |
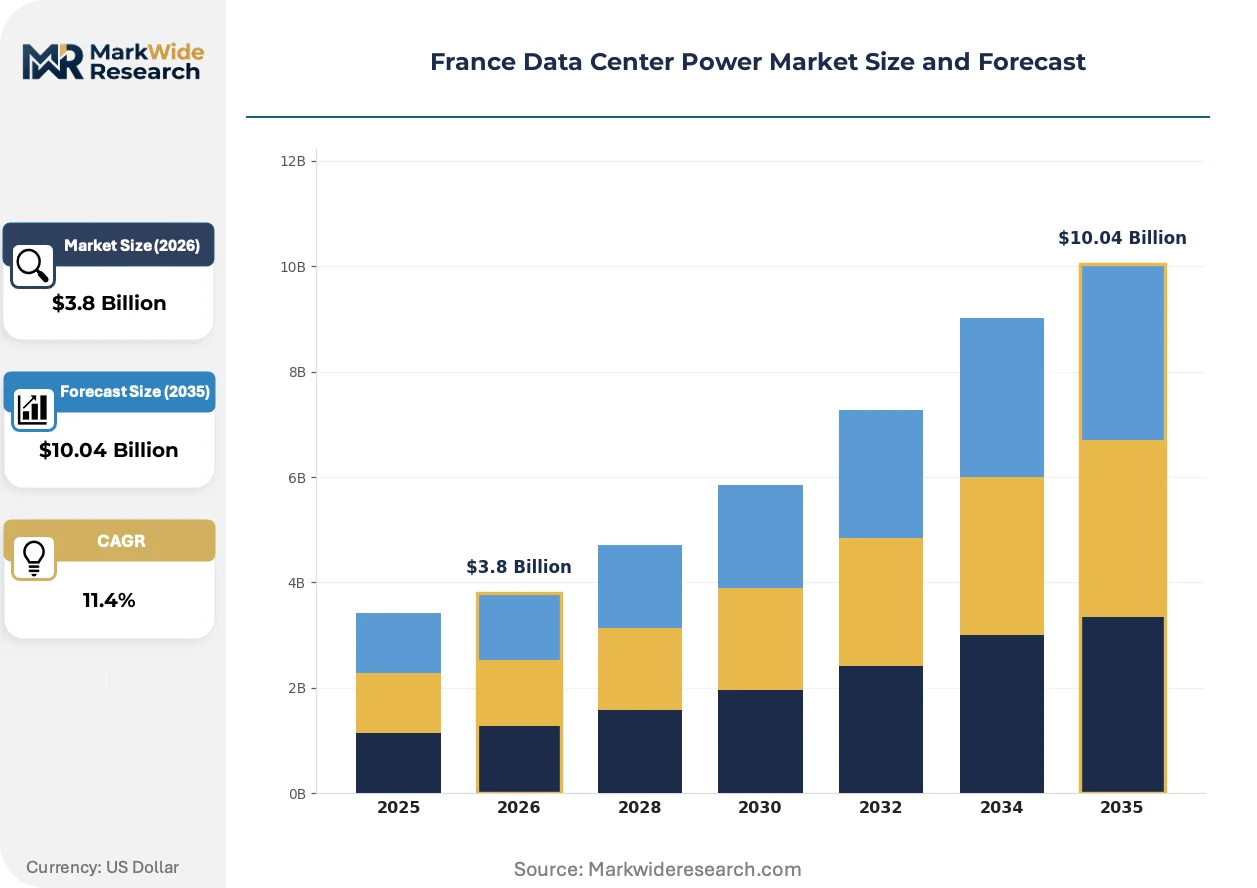
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backup Power Solutions, Cooling Systems, Power Distribution Units, Uninterruptible Power Supply End User: Colocation Providers, Cloud Service Providers, Enterprises, Government Agencies Technology: Hybrid Cooling, Liquid Cooling, Air Cooling, DC Power Systems Capacity: 1-5 MW, 5-10 MW, 10-20 MW, Above 20 MW |
| Companies Covered | Schneider Electric, ABB Ltd, Eaton Corporation, Vertiv Group, Cummins Inc, Legrand Group, Caterpillar Inc, Delta Electronics, Generac Holdings Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Power Market Trends and Innovations
Power distribution topology is undergoing fundamental restructuring as heat densities from accelerated computing workloads exceed legacy thermal management thresholds.
380 V DC bus architecture is supplanting conventional 400/230 V AC distribution in facilities above 10 MW capacity. Cloud service providers are specifying native DC rack power supplies for new builds, eliminating double-conversion losses and reducing copper conductor mass. This voltage standardization is compressing uninterruptible power supply footprint requirements and enabling direct battery coupling to server loads.
The EU F-Gas Regulation is prohibiting high-global-warming-potential refrigerants in new precision cooling installations from 2025. Equipment manufacturers are reformulating product portfolios around natural refrigerants and liquid-cooled rear-door heat exchangers. French colocation operators are prioritizing cooling system procurement from vendors with verified refrigerant transition roadmaps.
Buyers are consolidating electrical infrastructure procurement under single-source engineering-procure-construct contracts. Hyperscale operators are bypassing traditional multi-vendor integration models, instead specifying integrated power skid packages with unified warranty coverage. This bundling pattern concentrates vendor qualification activity within Ile-de-France and compresses commissioning timelines for repeat facility designs.
France Data Center Power Market Segmentation
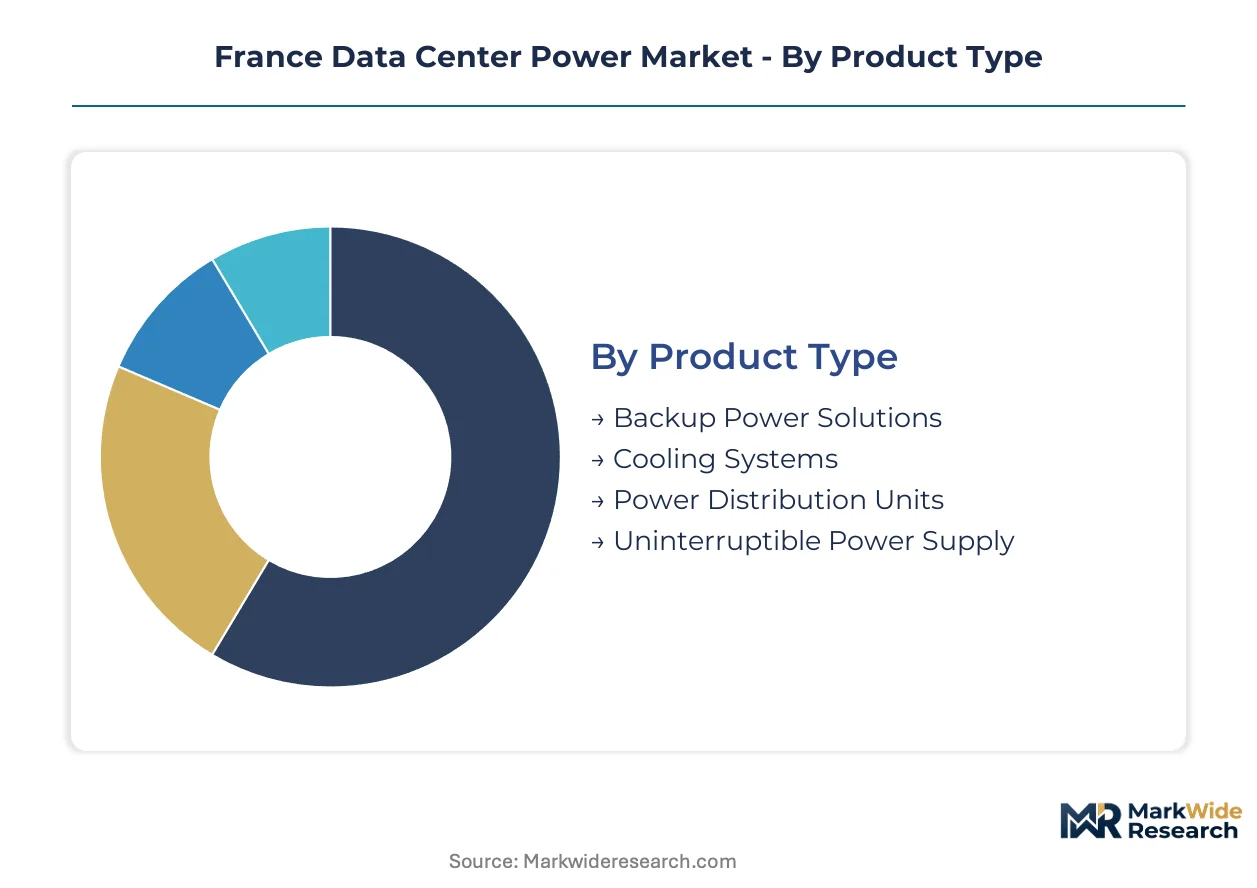
Segmentation in the France data center power market reveals how procurement patterns diverge across facility scales and operator types. Understanding these divides helps vendors align product development with the specific technical and regulatory pressures shaping each buyer category.
Product Type:
Domestic manufacturing clusters around Grenoble and Paris supply modular power infrastructure for hyperscale campuses, while import-dependent cooling systems face F-Gas Regulation compliance hurdles.
- Uninterruptible Power Supply:Double-conversion and line-interactive configurations dominate capital allocation due to their millisecond-scale bridging capability during grid interruptions. Demand concentrates among cloud service providers building N+1 and 2N redundant facilities across Greater Paris, where uptime guarantees drive premium procurement specifications.
- Backup Power Solutions:Natural-gas and diesel genset configurations anchor mission-critical resilience, with Cummins Inc and domestic manufacturers competing on French grid reliability profiles. Procurement from colocation providers is accelerating as sovereign cloud mandates expand government agency capacity requirements.
- Power Distribution Units:Busway and rack-level PDUs manage final-mile power delivery to server loads.
- Cooling Systems:Precision air handlers and liquid-cooled rear-door heat exchangers face refrigerant transition pressures under EU F-Gas Regulation constraints.
Uninterruptible power supply holds the largest share; momentum sits with backup power solutions as natural-gas configurations gain regulatory preference over diesel.
End User:
Procurement scale and redundancy tier requirements create sharp segmentation between hyperscale operators and compliance-driven public sector buyers.
- Cloud Service Providers:Hyperscale operators specify native 380 V DC rack power supplies and integrated power skid packages, compressing commissioning timelines through single-source EPC contracts. Facility buildouts across Greater Paris and Marseille submarine cable landing zones are generating concentrated demand for modular infrastructure with unified warranty coverage.
- Government Agencies:Sovereign cloud procurement mandates direct stable capital allocation toward domestic colocation capacity, insulating public-sector demand from private-market volatility. ANSM and CNIL data residency requirements shape backup power specifications for sensitive workloads.
- Colocation Providers:Multi-tenant facilities balance diverse tenant redundancy requirements across shared infrastructure.
- Enterprises:Pharmaceutical and biotech firms in Lyon drive niche demand for mission-critical configurations.
Cloud service providers hold the largest share; government agencies provide the steadiest revenue visibility through mandate-backed procurement cycles.
Technology:
Heat density thresholds from AI training clusters are forcing rapid infrastructure transitions across facilities above 10 MW capacity.
- Liquid Cooling:Direct-to-chip and immersion configurations displace legacy air cooling as rack densities exceed 50 kW, requiring mechanical room reconfiguration and floor loading recertification. Cloud service providers building AI training clusters across Ile-de-France are specifying liquid-cooled rear-door heat exchangers to manage thermal loads without expanding facility footprints.
- DC Power Systems:380 V DC bus architecture eliminates double-conversion losses and reduces copper conductor mass compared to 400/230 V AC distribution. Hyperscale campuses are specifying native DC rack power supplies for new builds, compressing uninterruptible power supply footprint requirements and enabling direct battery coupling.
- Air Cooling:Legacy precision air handlers face refrigerant constraints and density limitations.
- Hybrid Cooling:Combined liquid-air configurations bridge transition periods for mixed-density workloads.
Air cooling holds the largest installed base; liquid cooling is climbing the fastest as AI training cluster deployments accelerate.
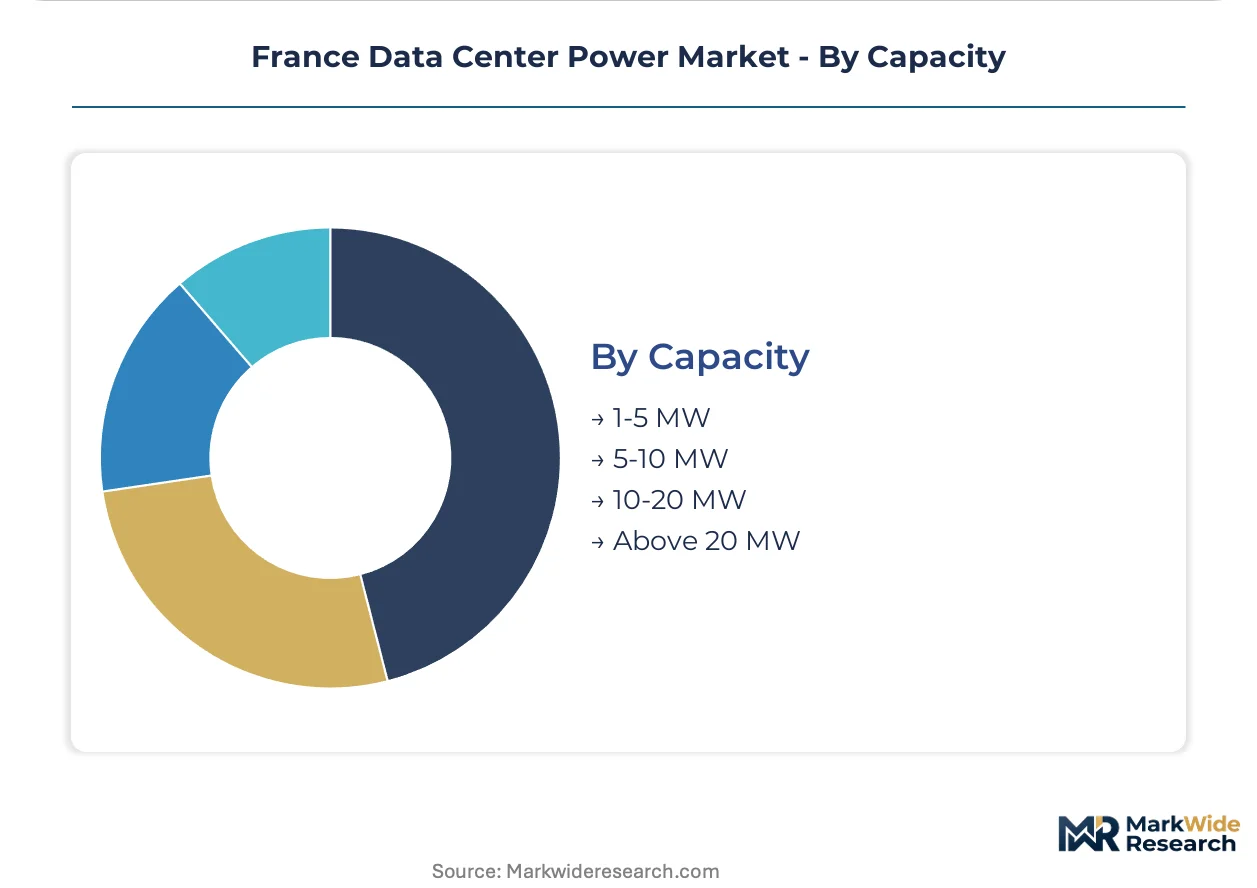
Capacity:
Grid connection queuing protocols from France's national energy regulator create distinct procurement timelines across facility scale tiers.
- Above 20 MW:Hyperscale campuses face sequential interconnection studies that delay energization schedules, concentrating vendor qualification activity within Ile-de-France where engineering expertise clusters. Cloud service providers are consolidating procurement under integrated power skid packages to compress commissioning timelines for repeat facility designs.
- 10-20 MW:Mid-scale facilities balance density economics with connection feasibility, often locating in secondary hubs near Marseille and Lyon.
- 5-10 MW:Edge computing investments in Marseille submarine cable landing zones are creating demand for distributed power modules.
- 1-5 MW:Smaller footprints serve enterprise data residency requirements and regional edge workloads.
Facilities above 20 MW hold the largest share; sub-10 MW distributed modules are gaining share fastest as edge computing investments expand beyond Greater Paris.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's national energy regulator and grid operator anchor the domestic market through connection standards that shape data center power architecture across metropolitan clusters.
Île-de-France
Hyperscale cloud operators concentrate server hall investments across Greater Paris, generating demand for modular uninterruptible power supply systems and high-capacity busway distribution. The EU Green Deal carbon intensity benchmarks compel facility operators to accelerate renewable energy procurement and liquid cooling retrofits. Engineering expertise clusters around Paris, compressing vendor qualification timelines for repeat facility designs.
Auvergne-Rhône-Alpes
Lyon's pharmaceutical and biotech sectors drive niche demand for mission-critical backup power configurations under ANSM data residency requirements. The F-Gas Regulation constrains refrigerant choices for precision cooling systems serving compliance-driven workloads. Grenoble anchors domestic manufacturing of modular power skids through specialized R&D campuses.
Provence-Alpes-Côte d'Azur
Marseille's submarine cable landing zones attract edge computing investments, creating demand for distributed power modules with sub-10 MW footprints. Grid connection queuing protocols from the national energy regulator delay energization schedules for facilities above 20 MW capacity. Secondary hub development is accelerating procurement of natural-gas genset configurations tailored to regional grid reliability profiles.
Hauts-de-France
Northern corridor facilities balance proximity to submarine cable interconnects with land availability for hyperscale campus expansion. EU CSRD disclosure rules generate advisory revenue streams around Scope 2 emissions verification for operators in this emerging cluster. Lille's logistics infrastructure supports just-in-time delivery of electrical distribution components for multi-tenant colocation builds.
France Data Center Power Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on backup power configurations and cooling system transitions. The market structure reflects consolidation around electrical infrastructure bundling, with repeat facility designs compressing commissioning timelines. Two strategic archetypes dominate: integrated power skid packagers and precision cooling specialists. Competitive moves center on single-source engineering-procure-construct contract capture and refrigerant transition roadmap verification.
Among France-based electrical distribution specialists, Legrand Group and Schneider Electric exemplify contrasting approaches to channel control and domestic manufacturing anchoring. Schneider Electric occupies a position representing integrated power infrastructure packaging through its Grenoble R&D campus concentration. Cummins Inc sits within the backup power specialization tier, anchoring natural-gas and diesel genset competition tailored to French grid reliability profiles.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB Ltd |
| Eaton Corporation |
| Vertiv Group |
| Cummins Inc |
| Legrand Group |
| Caterpillar Inc |
| Delta Electronics |
| Generac Holdings Inc |
| Others |
Pricing and Supply Chain Analysis
Engineering-procure-construct bundling locks in supply access for hyperscale operators while compressing price visibility across multi-year facility rollouts. This contract structure concentrates procurement leverage within Ile-de-France engineering clusters and anchors cost predictability for repeat modular power skid designs.
Pricing Analysis
Île-de-France commands pricing premiums over Marseille and Lyon secondary hubs due to engineering scarcity and grid connection queuing advantages. Project-based contracting dominates, with price differentiation driven by certification tier for high-voltage DC systems and volume scale across hyperscale campuses. Cost compression in standard AC infrastructure is intensifying because 380 V DC displacement eliminates double-conversion equipment layers. Cloud service providers exhibit lowest price sensitivity due to uptime guarantee requirements, while enterprise colocation tenants in Lyon show highest sensitivity to backup power configuration costs.
Supply Chain Analysis
France and Germany anchor domestic manufacturing of modular power skids and electrical distribution components, while China and Taiwan supply precision cooling subassemblies and power semiconductor modules. Copper busbar, lithium-ion battery cells, and natural-gas genset engines constitute critical input dependencies. Single-source vulnerability concentrates in high-voltage DC engineering talent pools centered on Grenoble and Paris. Distribution runs through direct OEM relationships with hyperscale operators and channel partnerships serving multi-tenant colocation providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized high-voltage DC expertise concentrates so narrowly that facility buildouts outside Paris and Grenoble face elongated commissioning timelines, compressing competitive advantage toward engineering-captive vendors.
For Market Incumbents: Fortify channel control across electrical distribution networks serving sovereign cloud mandates by deepening backward integration into modular power skid manufacturing. Expand capacity reservation agreements with France's national energy regulator to secure preferential grid connection slots ahead of hyperscale competitors. Anchor R&D investment in liquid-cooled rear-door heat exchanger roadmaps that satisfy F-Gas Regulation refrigerant transition deadlines. For New Entrants and Emerging Players: Differentiate on Marseille submarine cable landing zone edge computing deployments by offering sub-10 MW distributed power modules with native 380 V DC architecture. Target pharmaceutical and biotech data residency requirements in Lyon with mission-critical backup power configurations certified under ANSM protocols. Pursue engineering-procure-construct partnerships with regional developers lacking in-house high-voltage DC commissioning expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation providers with sovereign cloud tenant exposure and long-term power purchase agreements. Long-term viability hinges on refrigerant transition compliance and liquid cooling retrofit capability rather than legacy air-cooled installed base. Monitor France's national energy regulator dispatch priority announcements for nuclear baseload cost structure inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Power Skid Standardization | Compresses commissioning timelines for repeat hyperscale facility designs across Greater Paris. |
| Liquid Cooling Retrofit Partnership | Enables AI training cluster accommodation without mechanical room footprint expansion. |
| Sovereign Cloud Certification Investment | Unlocks stable government agency procurement insulated from private-market volatility. |
| Natural-Gas Genset Configuration Expansion | Aligns backup power portfolios with EU Green Deal carbon intensity benchmark preferences. |
| High-Voltage DC Engineering Talent Acquisition | Secures scarce expertise for 380 V DC bus architecture deployment outside Ile-de-France. |
Research Methodology
Initial hypotheses were tested against primary input from data center facility engineers, EPC contractors, cloud service provider infrastructure planners, and national energy regulator interconnection specialists and refined through secondary validation against SEC filings from hyperscale operators, EU CSRD disclosure submissions, F-Gas Regulation compliance databases, and France grid operator connection queue records. Bottom-up facility-level capacity tracking and top-down national energy demand projections were triangulated to anchor market sizing.
Variance decomposition across product type, end user, technology, and capacity tier segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Nuclear energy dispatch priority scenarios and AI training cluster density trajectories constituted industry-specific forecast inputs.
Material uncertainties — grid connection study delays, refrigerant supply disruptions, certified engineer availability shocks — sit outside the modeled envelope. Forecasts reflect assumptions around EU Green Deal implementation pace and sovereign cloud mandate durability. Recalibration cycles align with material shifts in national energy regulator interconnection protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
India Data Center Server Market