
 Indonesia Data Center Rack Market | 2026-2036
Indonesia Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Rack Market Insights
Modular rack configurations bundled with integrated power and cooling units is repositioning procurement patterns for Indonesian colocation operators. Schneider Electric SE leverages its prefabricated modular data center portfolio to capture hyperscale contracts in Greater Jakarta. Rittal GMBH & Co.KG anchors its position through localized assembly capabilities and channel partnerships with Indonesian systems integrators. Vertiv Group Corp. differentiates via thermal management integration that reduces field commissioning time for tropical climates.
A data center rack is a standardized frame structure, typically 19 inches wide with vertical mounting rails in rack unit increments, designed to house servers, networking equipment, and power distribution units in organized, scalable configurations. Steel construction dominates Indonesian supply chains due to cost efficiency and load-bearing requirements for dense IT deployments. Enclosed rack and hyper-rack variants are capturing margin pools as tropical humidity drives demand for sealed environments with active airflow management. Wall-mount rack demand from edge computing sites in secondary Indonesian cities is expanding faster than traditional enterprise floor-standing units.
Indonesia's Ministry of Communication and Informatics enforces data localization rules that mandate domestic storage for public sector and financial data, directly stimulating rack procurement from local facility operators. BIS-equivalent electrical safety standards and PLN grid codes shape power distribution specifications for rack-integrated PDUs across the archipelago. Stakeholders must monitor permitting velocity in Batam and Surabaya special economic zones against Jakarta saturation to optimize deployment sequencing.
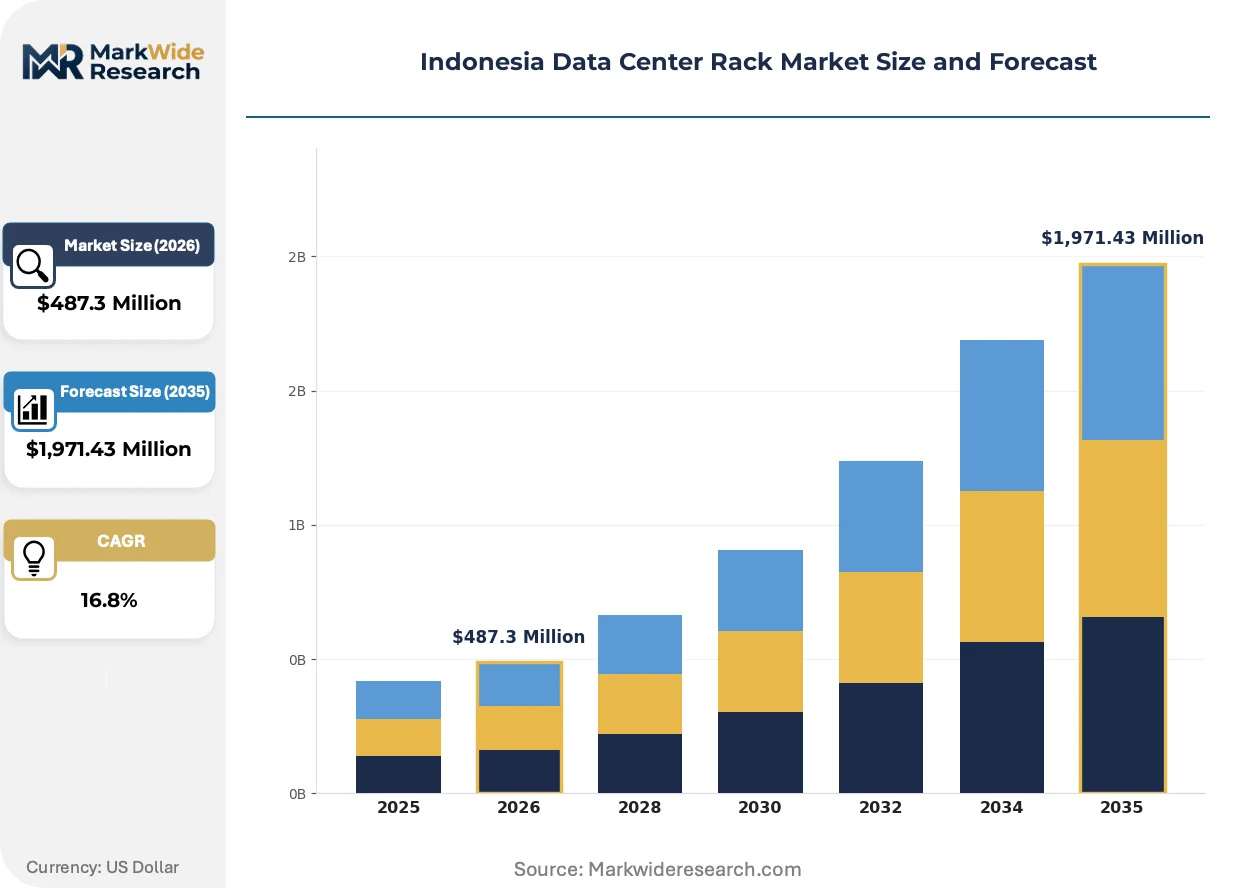
Market Dynamics
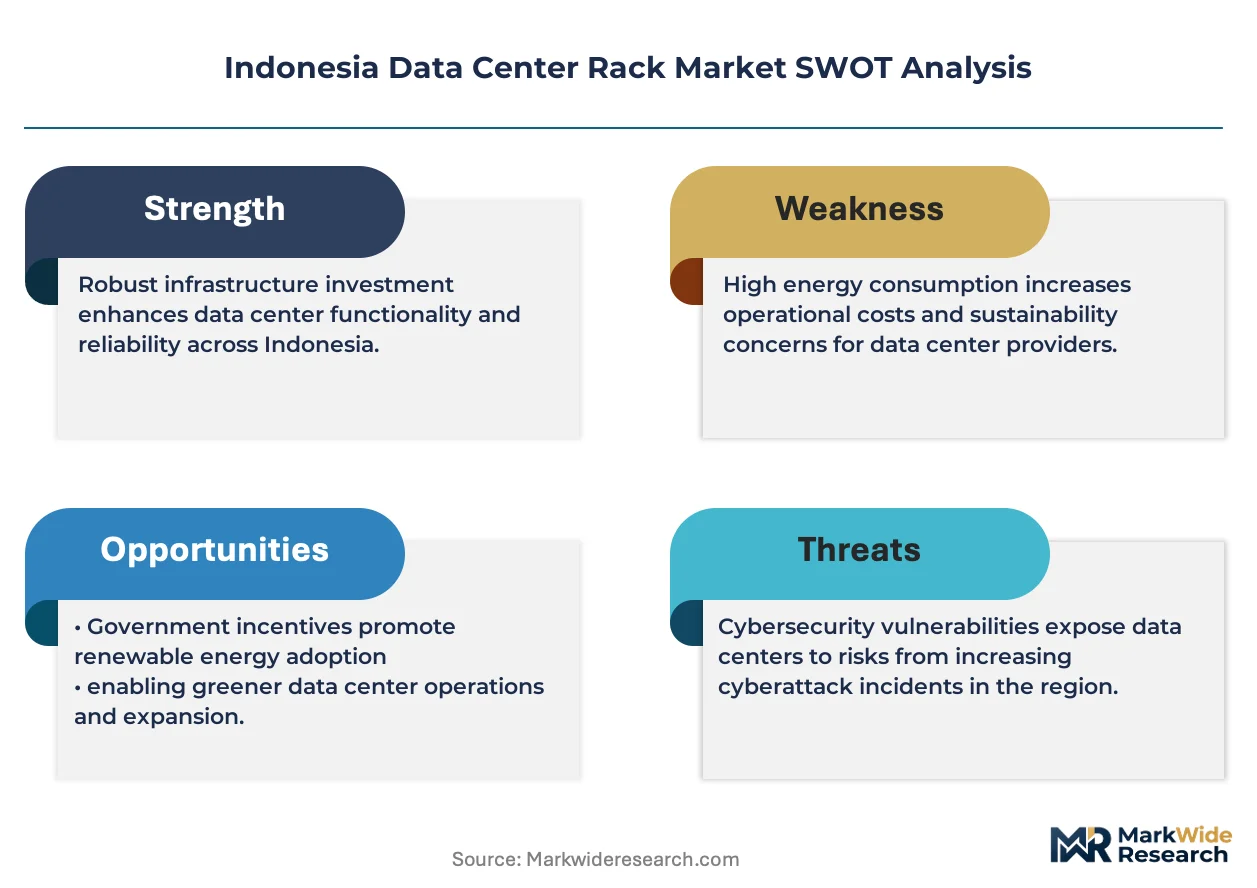
Indonesia's data localization mandates from the Ministry of Communication and Informatics are forcing foreign cloud operators to build domestic rack infrastructure rather than serving Indonesian users from Singapore or Hong Kong facilities.
Growth Catalysts
- Financial sector compliance:Indonesia's central bank requires domestic data storage for payment systems and banking records, compelling rack procurement from local colocation providers.
- PLN grid expansion:Perusahaan Listrik Negara is extending reliable power to industrial zones in Bekasi and Cibitung, enabling hyperscale campus development.
- Tropical climate engineering:Active airflow management and sealed rack designs are unlocking deployment density previously limited by humidity-induced corrosion risks.
Market Restraints
- Steel input volatility:Cold-rolled steel prices fluctuate with global commodity cycles, compressing margin visibility for rack manufacturers serving Indonesian projects.
- Specialized fabricator concentration:Precision sheet metal capabilities for 19-inch rack frames concentrate in Greater Jakarta, creating geographic supply risk for outer island deployments.
- Skilled commissioning technicians:Field teams capable of integrating power distribution units with tropical-rated cooling systems remain scarce outside Java.
Strategic Opportunities
- Surabaya corridor development:East Java's special economic zone incentives are attracting secondary hyperscale investments beyond saturated Greater Jakarta markets.
- Edge computing integration:Wall-mount rack configurations for telecommunications nodes in Medan, Makassar, and Denpasar represent underpenetrated demand.
- BIS-equivalent certification harmonization:Streamlined electrical safety approvals for rack-integrated PDUs would accelerate deployment timelines for foreign operators.
Industry Challenges
- Thermal commissioning complexity:Integrating active airflow management with legacy raised-floor data centers requires specialized retrofit expertise rarely available in Indonesian systems integrator networks.
- Permitting velocity variance:Batam and Surabaya special economic zones process facility approvals faster than Jakarta, forcing operators to sequence construction across disparate regulatory environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Rack Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,971.43 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mount Rack, Hyper-Rack End User: Telecommunications, Enterprises, Government, Healthcare Application: Cloud Computing, Big Data, IT Infrastructure, Virtualization Material: Steel, Aluminum, Plastic, Others |
| Companies Covered | Schneider Electric SE, Rittal GMBH & Co.KG, Vertiv Group Corp., Dell Inc., Hewlett Packard Enterprise, Legrand SA, Eaton Corporation, Cisco Systems, Inc., Tri Data Racks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Rack Market Trends and Innovations
Modular rack systems with factory-integrated power and cooling are compressing field deployment timelines for Indonesian hyperscale projects. This shift is reshaping supplier relationships and procurement specifications across the archipelago.
Prefabricated modular rack configurations are consolidating procurement decisions for Indonesian colocation operators. Hyperscale buyers in Cibitung and Bekasi now specify complete power-thermal-rack units rather than sourcing components separately. This consolidation is compressing vendor lists and favoring suppliers with integrated manufacturing capabilities.
Indonesia's Ministry of Communication and Informatics data localization enforcement is tightening compliance timelines for foreign cloud providers. Operators must now demonstrate domestic rack deployment before receiving operational licenses for public sector and financial data services. Financial services and government cloud segments are responding by accelerating facility construction in Greater Jakarta despite land scarcity.
Hyperscale buyers are consolidating procurement authority at the campus level rather than distributing rack decisions across individual facility managers. This concentration is displacing traditional channel relationships with Indonesian systems integrators in favor of direct manufacturer engagement. The shift is most visible in Greater Jakarta where cloud operators standardize on single-supplier rack specifications across multi-building campuses.
Indonesia Data Center Rack Market Segmentation
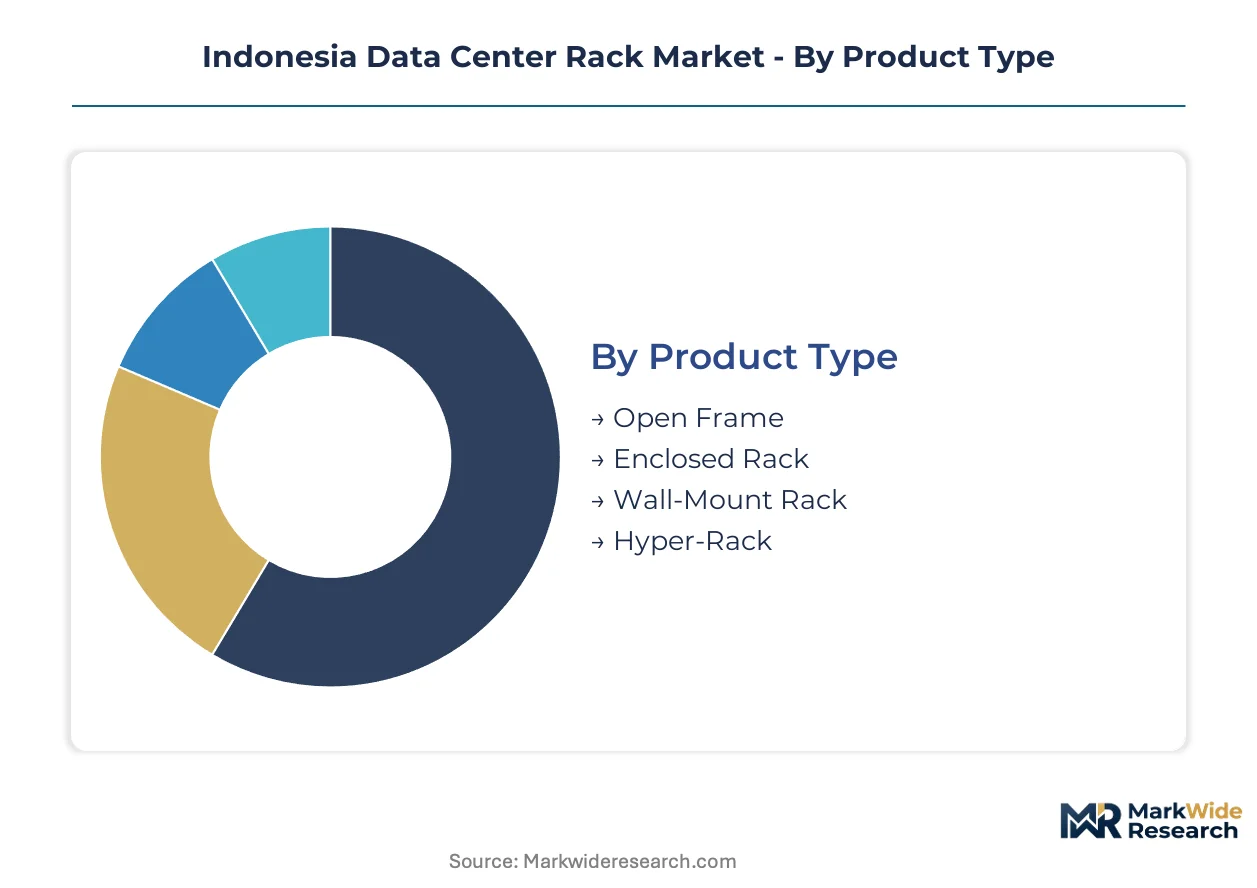
Indonesian operators configure rack procurement around tropical climate resilience, regulatory compliance, and deployment velocity. Segmentation reveals how capital allocation shifts between hyperscale campuses in Greater Jakarta and edge nodes across the archipelago.
Product Type:
Capital intensity varies sharply across frame architectures, with sealed environments demanding integrated power and cooling investments that open frames avoid.
- Enclosed Rack:Sealed steel housings with active airflow management protect equipment from Jakarta's humidity. Hyperscale buyers in Cibitung specify these for density levels exceeding standard corrosion thresholds.
- Hyper-Rack:Factory-integrated power distribution and thermal units compress field commissioning timelines. Cloud operators deploying across Bekasi campuses favor these for standardized multi-building rollouts.
- Open Frame:Four-post steel structures without side panels suit cost-sensitive enterprise deployments in secondary cities where environmental control is handled at facility level.
- Wall-Mount Rack:Compact enclosures for telecommunications nodes in Medan and Makassar edge locations where floor space constraints dominate procurement decisions.
Most installed capacity flows through Enclosed Rack configurations. Expansion is steepest in Hyper-Rack as hyperscale buyers consolidate procurement authority.
End User:
Customer procurement sophistication determines specification complexity, with regulated sectors driving premium rack configurations.
- Telecommunications:National carriers deploy wall-mount and enclosed racks across base transceiver stations and core network facilities. Tower companies in Surabaya corridor accelerate edge infrastructure buildouts.
- Enterprises:Banking and manufacturing buyers prioritize BIS-equivalent electrical compliance in rack-integrated PDUs. Domestic conglomerates expanding digital operations drive replacement cycles in Greater Jakarta.
- Government:Ministry of Communication and Informatics data localization mandates compel state agencies to procure domestically installed racks for public sector cloud services.
- Healthcare:Hospital networks require sealed rack environments for patient data systems, with demand concentrating in Java's tertiary medical centers.
Telecommunications accounts for the largest installed base. Healthcare is gaining share fastest as hospital digitization accelerates post-pandemic.
Application:
Workload characteristics dictate thermal and power density requirements, with cloud-native applications pushing rack specifications toward integrated cooling.
- Cloud Computing:Hyperscale providers specify hyper-rack configurations with factory-integrated thermal management for Cibitung and Bekasi campuses serving financial services clients.
- Big Data:Analytics workloads drive high-density deployments requiring active airflow racks that maintain thermal stability during sustained compute cycles.
- IT Infrastructure:General enterprise workloads favor enclosed racks with standardized power distribution across mixed server and networking equipment.
- Virtualization:Consolidated server environments in Jakarta-based colocation facilities employ open frame racks where facility-level cooling suffices.
Cloud Computing dominates capital deployment. Big Data is climbing the fastest as Indonesian enterprises invest in analytics infrastructure.
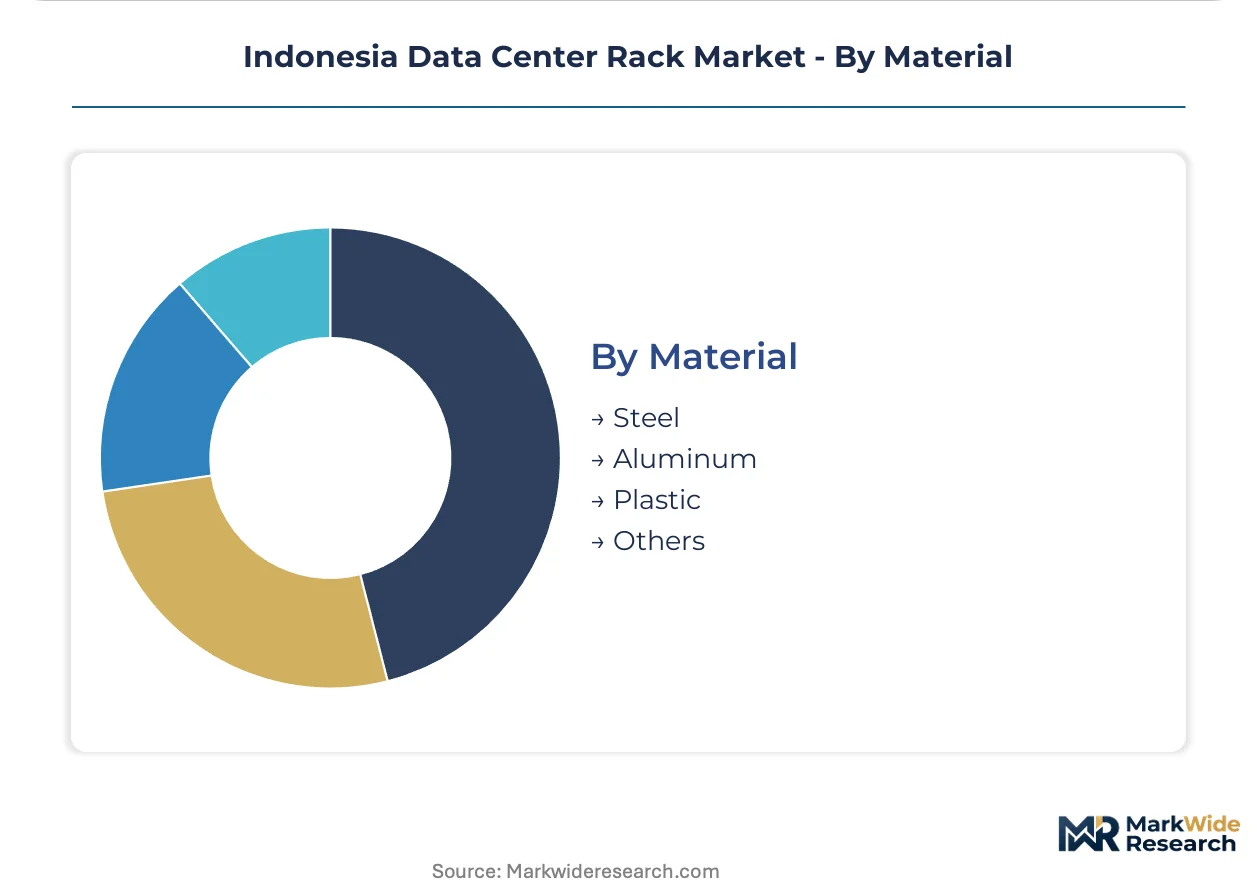
Material:
Supply chain geography and load-bearing requirements shape material selection, with local fabrication capabilities favoring certain inputs.
- Steel:Cold-rolled carbon steel dominates Indonesian manufacturing due to established local sheet metal fabrication and cost efficiency for standard 19-inch frames.
- Aluminum:Lightweight alloys serve wall-mount and transportable edge deployments where reduced structural load matters more than absolute material cost.
- Plastic:Non-conductive housings for specialized low-power telecommunications equipment in humid coastal environments where corrosion resistance outweighs mechanical strength.
- Others:Composite and stainless steel variants for niche applications requiring specific thermal or electromagnetic properties.
Steel commands the volume position. Aluminum is expanding most quickly as edge computing multiplies lightweight rack deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's data center rack industry traces its scaling momentum to the Ministry of Communication and Informatics data localization mandates first enforced in the mid-2010s, which redirected foreign cloud investment from regional hubs toward domestic facility construction across Java and Sumatra.
Greater Jakarta
Cibitung and Bekasi industrial zones concentrate hyperscale campus development driven by PLN grid expansion and land availability. Bank Indonesia's domestic data storage requirements for payment systems accelerate rack procurement from local colocation providers. Cloud operators standardize on hyper-rack configurations across multi-building campuses to compress commissioning timelines.
East Java
Surabaya's special economic zone incentives attract secondary hyperscale investments beyond saturated Jakarta markets. Faster permitting velocity compared to the capital enables operators to sequence construction strategically. Tower companies accelerate edge infrastructure buildouts across the corridor to serve telecommunications nodes.
North Sumatra
Medan emerges as a telecommunications edge computing hub where wall-mount rack demand expands faster than traditional enterprise floor-standing units. Humid tropical conditions drive specification toward sealed rack environments with active airflow management. National carriers deploy compact enclosures across base transceiver stations serving secondary cities.
South Sulawesi
Makassar anchors eastern Indonesia's edge computing expansion with floor space constraints dominating procurement decisions for telecommunications nodes. Skilled commissioning technicians capable of integrating power distribution units with tropical-rated cooling systems remain scarce outside Java. Local systems integrators partner with foreign suppliers to bridge capability gaps.
Bali and Nusa Tenggara
Denpasar represents underpenetrated demand for wall-mount rack configurations serving tourism and hospitality digital infrastructure. Ministry of Communication and Informatics regulations extend data localization requirements to provincial government services. Hospital networks in tertiary medical centers drive sealed rack procurement for patient data systems.
Indonesia Data Center Rack Market Competitive Landscape
The competitive structure tilts toward integrated solution providers with manufacturing scale and tropical climate engineering capabilities. Vendor relationships concentrate around direct manufacturer engagement rather than distributed channel partnerships as hyperscale buyers consolidate procurement authority at the campus level. Two strategic archetypes dominate: multinational industrial conglomerates with prefabricated modular portfolios, and precision sheet metal specialists with localized assembly capabilities. Capacity expansion and strategic partnerships with Indonesian systems integrators constitute the dominant competitive moves.
Among European-based industrial groups, Schneider Electric SE exemplifies the integrated solution archetype through its prefabricated modular data center portfolio. Rittal GMBH & Co.KG anchors the precision fabrication tier with localized assembly capabilities and channel partnerships. Vertiv Group Corp. occupies a position emphasizing thermal management integration for tropical deployment conditions. These three represent distinct strategic vectors within a market where procurement consolidation favors suppliers with complete power-thermal-rack manufacturing capabilities.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GMBH & Co.KG |
| Vertiv Group Corp. |
| Dell Inc. |
| Hewlett Packard Enterprise |
| Legrand SA |
| Eaton Corporation |
| Cisco Systems, Inc. |
| Tri Data Racks |
| Others |
Pricing and Supply Chain Analysis
Hyperscale campus procurement consolidation in Greater Jakarta compresses vendor lists and concentrates pricing power among integrated manufacturers with complete power-thermal-rack capabilities. This buyer concentration tilts negotiations toward volume-based contract structures that reward scale and penalize fragmented component suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Indonesian market by certification grade and volume scale. Premium tiers command markup for BIS-equivalent electrical compliance and factory-integrated thermal management, while economy configurations serve cost-sensitive edge deployments in secondary cities. Cost compression in standard-tier open-frame racks is intensifying because cold-rolled steel input volatility squeezes margin visibility. Telecommunications carriers exhibit highest price sensitivity due to distributed procurement across thousands of base transceiver stations, whereas financial services buyers prioritize compliance over unit cost.
Supply Chain Analysis
Indonesia's domestic-content momentum draws from localized assembly mandates and Ministry of Communication and Informatics procurement preferences for domestically installed infrastructure. Precision sheet metal fabrication concentrates in Greater Jakarta, with secondary capabilities emerging in Surabaya and Batam special economic zones. Supply chains rest on cold-rolled carbon steel from regional mills, power distribution components from ASEAN manufacturing hubs, and specialized cooling elements from tropical-climate engineering specialists. Single-source vulnerability concentrates in precision rack frame fabrication, where 19-inch standards require capabilities limited to Java-based fabricators. Distribution runs through direct manufacturer engagement with hyperscale operators, displacing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's data center rack market functions as a geographic-arbitrage play where operators exploit faster permitting velocity in Surabaya and Batam against land-scarce Greater Jakarta, capturing cost differentials of 15-25% in facility construction timelines.
For Market Incumbents: Cement dominance in Cibitung and Bekasi hyperscale corridors through captive assembly capacity expansion and BIS-equivalent certification pre-approval for rack-integrated PDUs. Threat from modular prefabrication specialists demands backward integration into tropical-rated thermal management components. Channel control over Indonesian systems integrators remains the critical defensive lever against direct manufacturer engagement by cloud operators. For New Entrants and Emerging Players: The 40-60% price gap between premium hyper-rack configurations and economy wall-mount units opens white-space opportunity in Surabaya corridor edge infrastructure and Medan telecommunications nodes. East Java's special economic zone incentives create the most penetrable geographic entry point. Go-to-market through tower company partnerships bypasses hyperscale vendor consolidation. For Investors and Strategic Acquirers: Cloud operators and hyperscale developers are the most active acquirers in this space, seeking captive supply security for tropical-climate rack infrastructure. Long-term viability hinges on localization depth and permitting relationships across Indonesian special economic zones. Acquisition targets should demonstrate precision sheet metal capabilities with existing Ministry of Communication and Informatics compliance track records. Watch PLN grid expansion announcements in outer island industrial zones as inflection signals for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Modular Manufacturing Scale-Up | Factory-integrated power-thermal-rack units compress field commissioning timelines for Bekasi hyperscale campuses. |
| Localized Assembly Joint Venture | Partnerships with Indonesian systems integrators satisfy domestic-content preferences while bridging precision fabrication gaps. |
| BIS-Equivalent Certification Pre-Approval | Pre-certified rack-integrated PDUs accelerate deployment timelines for foreign cloud operators facing compliance deadlines. |
| Surabaya Corridor Geographic Expansion | Faster permitting velocity in East Java special economic zone enables construction sequencing against Jakarta saturation. |
| Tropical Climate Engineering Partnership | Collaboration with humidity-rated cooling specialists differentiates sealed rack offerings for corrosion-prone deployments. |
Research Methodology
Multiple input streams — hyperscale facility development tracking, PLN grid expansion monitoring, and Ministry of Communication and Informatics regulatory filing analysis — were reconciled against primary interviews with data center construction directors, colocation procurement managers, and tropical HVAC engineering specialists. Secondary validation drew from PLN infrastructure disclosures, special economic zone authority permitting records, and BIS-equivalent standards documentation. Bottom-up rack deployment counts across Cibitung, Bekasi, Surabaya, and Medan clusters were triangulated against top-down capital expenditure estimates from cloud operator facility announcements.
Historical deployment patterns were cross-referenced against panel input from equipment suppliers and systems integrators to construct analytical frameworks across product type, end user, application, and material segmentation dimensions. CAGRs were derived from installed base growth trajectories and replacement cycle analysis rather than simple trend extrapolation. Forecast inputs incorporated PLN grid reliability projections, data localization enforcement intensity, and tropical climate engineering adoption curves for active airflow management systems.
The model assumes a particular technology adoption path; alternative pathways for liquid cooling integration would alter the outlook for sealed rack specifications and power density assumptions. Forecasts reflect assumptions about Ministry of Communication and Informatics enforcement consistency and PLN infrastructure delivery schedules. Regulatory delay, commodity price spikes, or skilled technician scarcity could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Chile Data Center Rack Market