
 Europe Data Center Construction Market | 2026-2036
Europe Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Construction Market Insights
The gap between hyperscale builds and legacy facility retrofits is expanding across Europe. AECOM leverages its engineering scale to secure complex hyperscale campus contracts in Frankfurt and Amsterdam. Bouygues Construction anchors French market share through integrated design-build delivery for sovereign cloud operators. Arup differentiates via advanced thermal modeling and low-carbon structural solutions that meet tightening EU building codes.
Europe data center construction encompasses the civil, mechanical, electrical, and structural build-out of facilities housing compute, storage, and network infrastructure, typically requiring power densities exceeding 20 kW per rack and precision cooling within ±1°C tolerance to sustain 99.999% uptime. Hyperscale facility types dominate capital deployment as cloud operators commission multi-hundred-megawatt campuses. Edge deployments represent the fastest-growing facility category, driven by latency-sensitive gaming and autonomous systems workloads. Design services capture premium margins where thermal and power optimization complexity escalates.
EMA efficiency directives, EU Green Deal carbon benchmarks, and national building energy codes collectively mandate liquid cooling readiness and renewable power sourcing for new approvals. CSRD disclosure rules now require operational carbon reporting across facility lifecycles, shifting procurement criteria toward embodied carbon metrics. Stakeholders must monitor how upcoming F-Gas Regulation amendments restrict synthetic refrigerant use in precision cooling systems.
Market Dynamics
The EU Green Deal's carbon-neutrality mandates are compressing construction timelines while forcing liquid cooling retrofits into legacy specifications. This regulatory pressure is widening the capability gap between hyperscale-ready contractors and regional specialists.
Growth Catalysts
- EMA Efficiency Directives:Mandates for liquid cooling readiness in new facilities are pulling forward capital deployment from cloud operators seeking pre-certification advantages.
- Autonomous Systems Workloads:Latency-sensitive edge computing for automotive and robotics applications is generating demand for sub-10ms proximity infrastructure across Northern European clusters.
- Frankfurt-Amsterdam-Dublin Triangle:Concentrated fiber interconnectivity and renewable power availability is concentrating hyperscale campus commitments in these three metropolitan zones.
Market Restraints
- Copper and Electrical Steel Volatility:Transformer and busbar input costs swing with commodity markets, compressing fixed-price contract margins for electrical contractors.
- Nordic Cooling Equipment Concentration:Precision cooling system manufacturing concentrates among Finnish and Swedish suppliers, creating single-source vulnerability for southern European projects.
- F-Gas Regulation Amendments:Pending restrictions on synthetic refrigerants are freezing procurement decisions for mechanical contractors awaiting compliance clarity.
Strategic Opportunities
- Spanish Edge Market:Underpenetrated secondary cities like Barcelona and Bilbao offer first-mover positioning for latency-optimized gaming infrastructure.
- CSRD Carbon Disclosure:Mandatory operational carbon reporting is creating premium service tiers for contractors offering embodied carbon tracking across facility lifecycles.
- Direct Liquid Cooling Convergence:Integration of immersion cooling with high-density GPU racks enables 50+ kW per rack configurations for AI training clusters.
Industry Challenges
- Commissioning Engineer Scarcity:Specialized talent for 99.999% uptime validation commands 40% wage premiums, stretching project staffing timelines.
- Legacy Grid Integration:Brownfield sites in Paris and London require substation upgrades that add 18-24 months to energization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Construction Market |
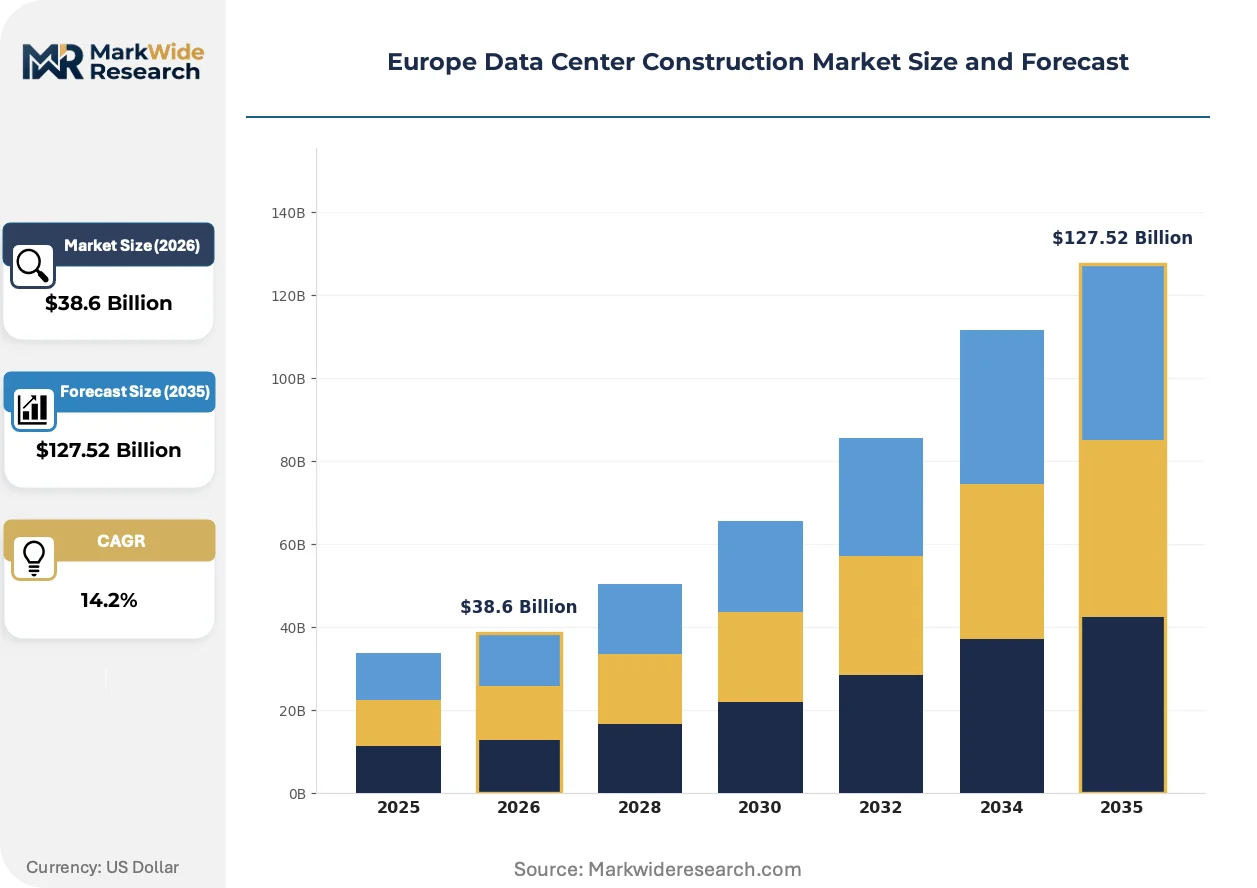
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Management, Maintenance Facility Type: Colocation, Hyperscale, Edge, Modular Deployment Model: Private, Public, Hybrid, Multi-tenant End User: IT Companies, Gaming, Healthcare, Financial Services |
| Companies Covered | AECOM, Arup, DPR Construction, Artelia, Bouygues Construction, NTT Ltd., CBRE Group Inc., Bouygues Energies and Services SAS, ISG plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Construction Market Trends and Innovations
Modular prefabrication is compressing on-site construction duration while thermal design software is embedding carbon optimization into early-stage engineering decisions. These shifts are redistributing value capture toward design-phase specialists.
Immersion cooling systems using dielectric fluids are decentralizing thermal management from centralized chillers to rack-level containment. Hyperscale operators in Amsterdam and Frankfurt are piloting two-phase immersion for AI training clusters. This topology is decentralizing mechanical infrastructure investment decisions from campus-wide to individual hall configurations.
The EU Green Deal's building energy codes are mandating real-time carbon intensity disclosure for operational power. CSRD rules now require facility-level Scope 1 and 2 reporting across asset portfolios. Data center operators in France and Germany are responding by procuring renewable energy through 15-20 year power purchase agreements to lock in compliance trajectories.
Enterprise buyers are consolidating vendor relationships around design-build contractors offering integrated MEP and structural delivery. This concentration is displacing fragmented general contractor-subcontractor hierarchies in the Netherlands and Ireland. Sovereign cloud operators in Paris and Munich are driving this pattern, seeking single-accountability partners for security-cleared facilities.
Europe Data Center Construction Market Segmentation
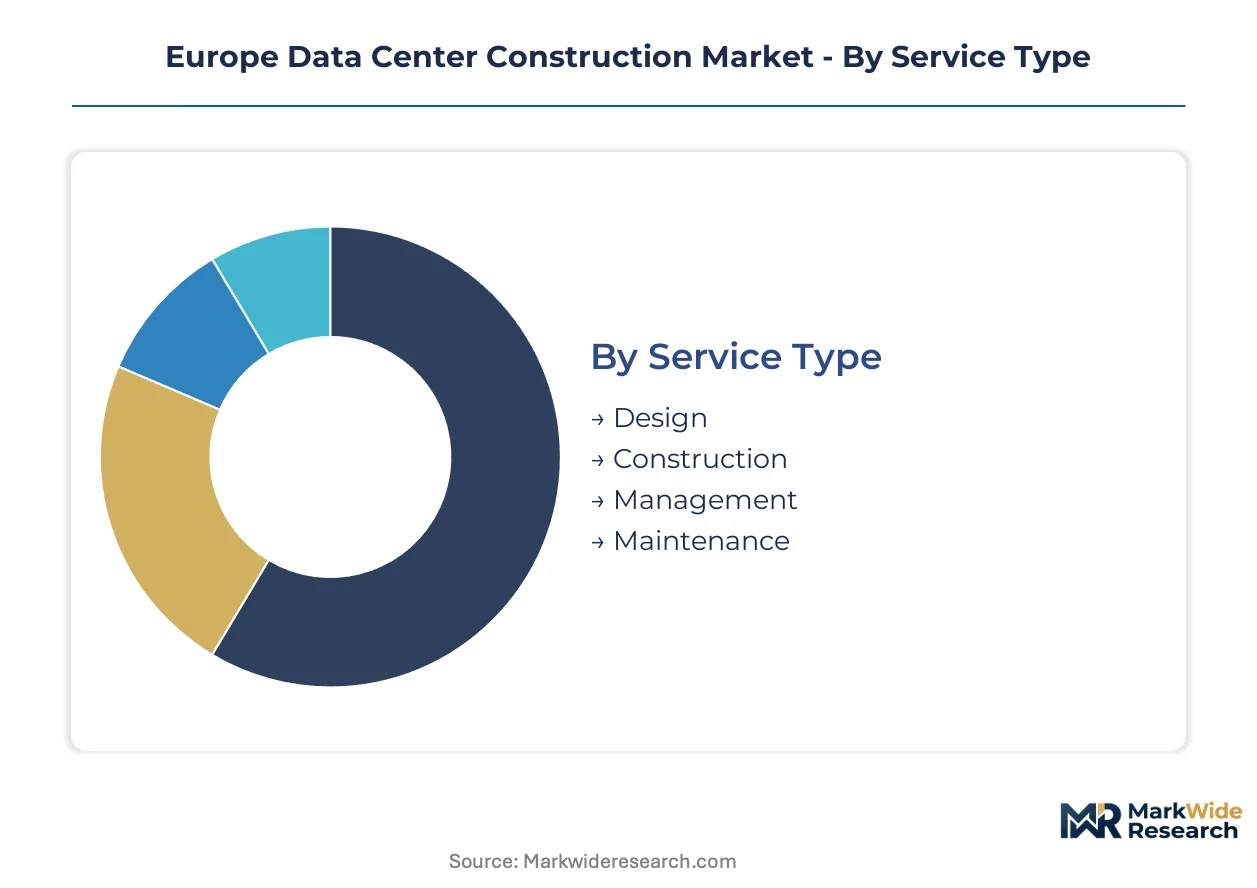
Segmentation reveals where capital deployment concentrates and where capability gaps create margin premiums. Construction contractors must align service portfolios against facility type evolution and deployment model complexity to capture value.
Service Type:
Engineering talent pools concentrate unevenly across service tiers, with specialized commissioning expertise commanding scarcity premiums.
- Design:Advanced thermal modeling and power optimization services capture premium margins as EU Green Deal codes tighten. German hyperscale campuses in Frankfurt drive demand for liquid-cooling-ready engineering specifications.
- Construction:Integrated civil, mechanical, and electrical build-out dominates capital allocation. Amsterdam and Dublin hyperscale projects pull capacity from regional contractors seeking scale credentials.
- Management:Project oversight spans scheduling, cost control, and vendor coordination for multi-hundred-megawatt campuses. French sovereign cloud operators favor single-accountability construction management structures.
- Maintenance:Lifecycle service contracts extend revenue visibility post-commissioning. Dutch colocation facilities prioritize predictive maintenance for 99.999% uptime guarantees.
Today's leader: Construction. Tomorrow's challenger: Design.
Facility Type:
Capital deployment intensity varies sharply by facility scale and power density requirements.
- Hyperscale:Multi-hundred-megawatt campuses require specialized civil foundations and substation integration. Northern European fiber interconnectivity clusters in Frankfurt, Amsterdam, and Dublin concentrate commitments from cloud operators.
- Edge:Sub-10ms latency infrastructure for gaming and autonomous systems workloads expands most quickly. Spanish secondary cities including Barcelona and Bilbao present first-mover positioning for latency-optimized builds.
- Colocation:Multi-tenant facilities balance standardized specifications against tenant customization demands. Paris and London brownfield retrofits face 18-24 month grid integration delays.
- Modular:Prefabricated mechanical and electrical components compress on-site construction duration. Nordic manufacturing concentration for precision cooling modules creates sourcing vulnerability for southern European projects.
Hyperscale commands current capital volumes. Edge deployments offer the steepest expansion trajectory.
Deployment Model:
Procurement complexity escalates with tenant count and security classification layering.
- Private:Single-entity facilities for sovereign cloud and defense applications demand security-cleared construction teams. German and French national cloud operators drive single-tenant specifications.
- Public:Government and municipal data centers prioritize renewable power sourcing and CSRD carbon disclosure compliance. EU Green Deal benchmarks shape public sector procurement criteria.
- Hybrid:Split workload architectures require segmented physical infrastructure with differentiated cooling and power redundancy. Financial services firms in Frankfurt and London favor hybrid configurations for regulatory compliance.
- Multi-tenant:Shared facilities maximize power utilization efficiency through diverse tenant load profiles. Dutch and Irish markets concentrate multi-tenant development for interconnection density.
Private deployments anchor premium pricing. Hybrid models gain share fastest among regulated industries.
End User:
Latency sensitivity and compliance intensity reshape facility specifications across verticals.
- IT Companies:Cloud and software providers dominate hyperscale commissioning with 20+ kW per rack density requirements. Northern European renewable power availability aligns with sustainability commitments.
- Gaming:Real-time multiplayer and cloud gaming infrastructure demands sub-10ms edge proximity. Nordic and Iberian markets attract latency-optimized investments from gaming platforms.
- Healthcare:Patient data sovereignty mandates localize infrastructure within national borders. German and French healthcare data residency rules restrict cross-border facility options.
- Financial Services:Trading and risk analytics workloads require microsecond-level latency to exchange infrastructure. Frankfurt and London financial districts concentrate specialized low-latency builds.
IT companies drive current capacity expansion. Gaming represents the fastest-climbing vertical for edge infrastructure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commissioning engineers with liquid cooling expertise concentrate in the Frankfurt-Amsterdam-Dublin corridor, anchoring Europe's hyperscale construction capacity. This talent pool shapes where cloud operators commit capital.
Germany
Frankfurt's fiber density and renewable power access attract multi-hundred-megawatt campus investments from sovereign cloud operators. The country's national building energy codes mandate liquid cooling readiness for new facility approvals. Hesse's Rhine-Main cluster hosts specialized contractors serving 50+ kW per rack AI training configurations.
Netherlands
Amsterdam's interconnection hubs and North Sea wind power availability concentrate hyperscale commitments from international cloud providers. The EU Green Deal's carbon benchmarks drive 15-20 year renewable power purchase agreements. Eemshaven and Schiphol-Rijk industrial zones anchor modular prefabrication supply chains for precision cooling components.
France
Sovereign cloud operators in Paris and Marseille demand security-cleared construction teams for single-tenant defense facilities. The CSRD disclosure rules require operational carbon reporting across facility lifecycles. Île-de-France's brownfield retrofit projects face 18-24 month grid integration delays at legacy substations.
Ireland
Dublin's low corporate tax regime and transatlantic cable landing points concentrate hyperscale data center investment from US technology companies. The country's national planning authority enforces renewable power sourcing mandates for new construction permits. Greater Dublin's power grid constraints are shifting development toward Cork and Limerick secondary clusters.
Spain
Barcelona and Bilbao's underpenetrated edge markets attract latency-optimized gaming infrastructure investments. The country's national energy efficiency directives align with EU Green Deal thermal performance standards. Catalonia's secondary metro zones offer first-mover positioning for sub-10ms autonomous systems workloads.
Europe Data Center Construction Market Competitive Landscape
Capital-heavy integrated contractors compete with specialized engineering designers for premium-margin hyperscale contracts. The market structures around three tiers: global AEC firms with multi-country delivery capability, national champions anchored in domestic sovereign cloud relationships, and regional specialists focused on colocation retrofits. Strategic moves concentrate on design-build integration to capture single-accountability procurement preferences and thermal engineering talent acquisition to meet liquid cooling specification complexity.
Within the integrated delivery tier, AECOM and Bouygues Construction exemplify scale-driven positioning across Northern European hyperscale corridors. Arup occupies a specialist position anchored in advanced thermal modeling and low-carbon structural solutions. These three entities represent contrasting archetypes: the engineering conglomerate with civil-mechanical-electrical breadth, the construction group with national sovereign cloud relationships, and the design consultancy with carbon-optimized building physics expertise.
| Leading Market Players |
|---|
| AECOM |
| Arup |
| DPR Construction |
| Artelia |
| Bouygues Construction |
| NTT Ltd. |
| CBRE Group Inc. |
| Bouygues Energies and Services SAS |
| ISG plc |
| Others |
Pricing and Supply Chain Analysis
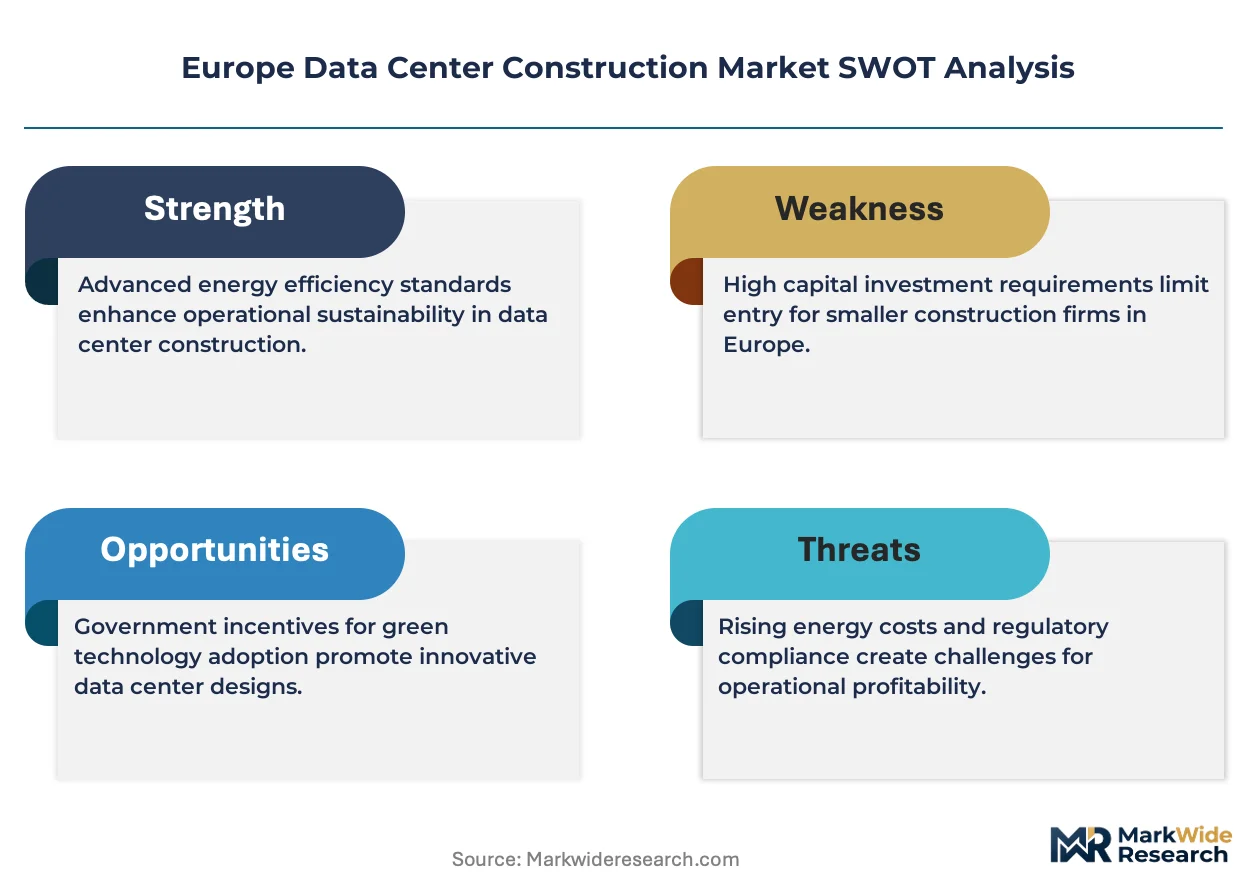
Hyperscale cloud operators concentrate procurement decisions across the Frankfurt-Amsterdam-Dublin corridor, anchoring project-based contract pricing for integrated design-build delivery. This buyer concentration compresses margins for electrical contractors facing volatile copper and electrical steel input costs while rewarding thermal engineering specialists with scarcity premiums for liquid-cooling-ready specifications.
Pricing Analysis
Design services versus construction execution splits the pricing architecture across unbundled engineering fees and bundled turnkey contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies around thermal modeling complexity, with advanced carbon-optimized specifications commanding 40% wage premiums for commissioning engineers. Cost compression in fixed-price electrical installation contracts is intensifying because commodity volatility erodes contractor margins. Regional specialists serving brownfield retrofits exhibit highest price sensitivity, while sovereign cloud operators in France and Germany demonstrate lowest sensitivity due to security-cleared delivery requirements.
Supply Chain Analysis
Direct-to-hyperscale channels handle multi-hundred-megawatt campus demand through integrated contractor relationships in Germany, the Netherlands, and Ireland. Precision cooling module manufacturing concentrates in Finland and Sweden, while electrical steel and copper processing feeds from German and Belgian metallurgical suppliers. Single-source vulnerability for dielectric fluid immersion systems creates procurement risk for AI training cluster deployments. Distribution runs through design-build contractors displacing fragmented general contractor-subcontractor hierarchies in the Netherlands and Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe data center construction market represents a late-cycle quality story as EU Green Deal carbon benchmarks and CSRD disclosure rules shift procurement criteria toward embodied carbon tracking and liquid cooling readiness. Cloud operators now prioritize contractors with integrated thermal engineering capabilities over pure construction scale.
For Market Incumbents: Lock in commissioning engineer talent pools through specialized training partnerships with German technical universities, defending against hyperscale-ready contractor scarcity. Deepen backward integration into modular prefabrication supply chains for precision cooling components to capture value migrating from on-site construction to factory assembly. Anchor relationships with sovereign cloud operators in Paris and Munich through security-cleared delivery capabilities that emerging competitors cannot replicate quickly.
For New Entrants and Emerging Players: Launch via specialized edge infrastructure delivery in Spanish secondary cities including Barcelona and Bilbao, where latency-optimized gaming demand outpaces established contractor presence. Target predictive maintenance service contracts for Dutch colocation facilities seeking 99.999% uptime guarantees, penetrating through lifecycle revenue visibility rather than capital-heavy construction competition. Differentiate through CSRD-compliant embodied carbon tracking software that incumbent contractors lack across facility lifecycles.
For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space, seeking design-build integration capabilities to secure single-accountability procurement preferences. Long-term viability centers on contractors with liquid cooling engineering talent and renewable power sourcing relationships across the analysis window. Acquisition target archetypes include thermal modeling specialists with low-carbon structural solutions and regional contractors holding security clearances for sovereign cloud work. Watch F-Gas Regulation amendment clarity as inflection indicator for mechanical contractor procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Engineering Talent Acquisition | Liquid cooling expertise commands 40% wage premiums in Frankfurt and Amsterdam clusters. |
| Modular Prefabrication Scale-Up | Factory-assembled mechanical components compress on-site construction duration for hyperscale campuses. |
| Renewable Power Purchase Agreements | 15-20 year contracts lock in CSRD compliance trajectories for German and Dutch operators. |
| Security-Cleared Delivery Certification | French sovereign cloud operators require single-accountability partners for defense facilities. |
| Predictive Maintenance Platform Launch | Dutch colocation providers prioritize uptime guarantees through lifecycle service contracts. |
Research Methodology
Direct dialogue with data center project developers, EPC contractors, commissioning engineers, and hyperscale facility operators grounded the qualitative foundation for this analysis. Primary insights were cross-validated against secondary sources including EU regulatory filings for CSRD and F-Gas Regulation amendments, national building energy code documentation from Germany and France, and power purchase agreement disclosure databases. Customs records tracking copper and electrical steel trade flows, alongside EPC contractor procurement announcements, provided input cost visibility. Bottom-up project pipeline aggregation was triangulated with top-down capital expenditure tracking from cloud operator disclosures.
Segmented outputs across service type, facility type, deployment model, and end user vertical were generated through the analytical framework. Modeled dimensions included power density tier, cooling topology, and renewable power sourcing status across the projection horizon. CAGRs were derived from facility commissioning schedules, grid interconnection timelines, and regulatory approval trajectories. Forecast inputs incorporated EU Green Deal carbon benchmark evolution, F-Gas Regulation amendment scenarios, and hyperscale cloud operator capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated F-Gas Regulation restrictions or prolonged grid integration delays at legacy Paris and London substations. Projections reflect assumptions regarding cloud operator capital commitment continuity, renewable power sourcing availability, and commissioning engineer supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Jakarta Data Center Market