
 Italy Data Center Market | 2026-2036
Italy Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Market Insights
Italian enterprise demand is broadening beyond traditional telecom hosting as automotive manufacturers and pharmaceutical groups adopt cloud-adjacent colocation for latency-sensitive applications. IRIDEOS leverages its nationwide fiber footprint to anchor edge deployments across Northern industrial corridors. Telecom Italia sustains legacy enterprise relationships through integrated network-facility bundles. Aruba SpA competes on sovereign data guarantees that appeal to public-sector buyers.
Italy data centers constitute dedicated facilities housing servers, storage systems, and networking equipment with redundant power supplies, precision cooling maintaining temperatures between 18°C and 27°C, and physical security controls for continuous digital service delivery. Colocation services capture the largest revenue pool as enterprises divest owned assets, while hyperscale construction accelerates near Milan to serve cloud platform demand. Liquid cooling penetration rises in high-density deployments where air systems face thermal limits, and disaster recovery services gain traction among BFSI clients confronting operational resilience mandates.
Italy's data center operators navigate oversight from the national cybersecurity agency under EU NIS2 transposition, alongside AGCOM regulations governing interconnection and BIS-adjacent standards for critical infrastructure certification. The EU AI Act imposes new documentation and risk-management obligations on facilities hosting training workloads for high-risk systems. Stakeholders must monitor whether proposed national data localization amendments alter cross-border service economics.
Market Dynamics
Italian data center operators confront a structural squeeze between EU AI Act compliance mandates and localized power grid constraints that favor facilities with secured renewable energy offtake agreements.
Growth Catalysts
- EU AI Act documentation requirements:Facilities hosting high-risk AI training workloads must maintain risk-management records, creating premium service tiers for compliant colocation.
- Automotive edge computing:Northern Italy's automotive manufacturers demand sub-10ms latency for connected vehicle platforms, pulling compute closer to manufacturing corridors.
- Milan fiber density:The metropolitan area's intersection of terrestrial fiber routes and trans-Mediterranean subsea cables anchors hyperscale construction decisions.
Market Restraints
- Power interconnection queues:Terna, Italy's transmission system operator, faces 18-24 month backlogs for new high-voltage connections, freezing greenfield site development.
- Limited domestic server manufacturing:Italy lacks indigenous rack-scale server production, forcing dependence on Taiwanese and Chinese OEM supply chains with extended lead times.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon quota reductions constrain conventional precision cooling expansion, raising retrofit costs for legacy facilities.
Strategic Opportunities
- Southern Italy latency arbitrage:Underdeveloped data center infrastructure in Sicily and Calabria offers first-mover positioning for submarine cable landing stations serving North African and Middle Eastern traffic.
- Liquid cooling convergence:Integration of direct-to-chip cooling with waste heat recovery systems enables district heating partnerships with municipal utilities.
- NIS2 transposition incentives:Italy's cybersecurity framework implementation creates certified facility demand from critical infrastructure operators seeking audit-ready environments.
Industry Challenges
- Electrical trades specialization:Shortage of certified high-voltage technicians delays commissioning schedules and inflates contractor rates for 132kV substation work.
- Legacy banking core migration:Italian financial institutions operate decades-old mainframe architectures that resist cloud-native refactoring, complicating hybrid deployment roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Market |
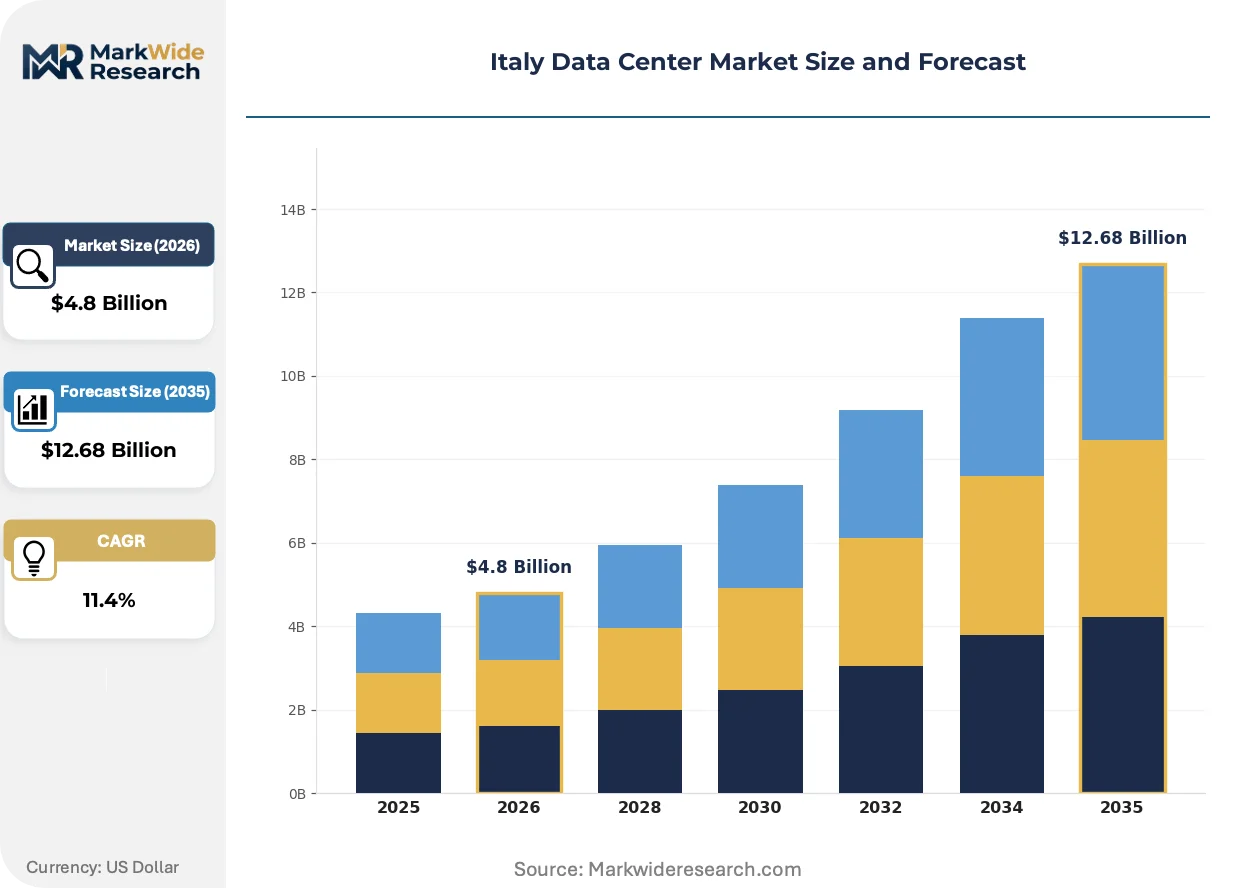
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Center Type: Colocation, Hyperscale, Edge, Managed Service Type: Infrastructure as a Service, Disaster Recovery, Data Backup, Network Services Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Free Cooling End User: BFSI, Healthcare, Telecom, IT Services |
| Companies Covered | IRIDEOS, Telecom Italia (TIM), Aruba SpA, Digital Realty, STACK Infrastructure, Equinix, Vantage Data Centers, BT Italia, Data4, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Market Trends and Innovations
Italian data center architecture is pivoting from air-dominated thermal management toward integrated infrastructure platforms that collapse networking, compute, and storage silos into unified operational layers.
Software-defined power distribution is unifying rack-level energy monitoring with grid-responsive load balancing. Hyperscale operators in Lombardy deploy these systems to participate in demand-response programs managed by Terna. This convergence is unifying facility operations with regional grid stability objectives, compressing the traditional separation between data center engineering and utility interaction.
The EU AI Act's risk classification system imposes documentation burdens on facilities hosting training infrastructure for high-risk AI systems. Italian operators must maintain technical logs and human oversight protocols for tenant workloads. Financial services and healthcare data centers face the steepest compliance ramps, with several Milan facilities pursuing third-party certification to preempt regulatory scrutiny.
Enterprise procurement of data center services is fragmenting from monolithic colocation contracts toward modular capacity subscriptions. Italian pharmaceutical and automotive buyers now procure compute, storage, and networking as separate metered services rather than fixed cage commitments. This unbundling is most pronounced among Milan-headquartered multinationals with variable workload patterns tied to seasonal research cycles.
Italy Data Center Market Segmentation
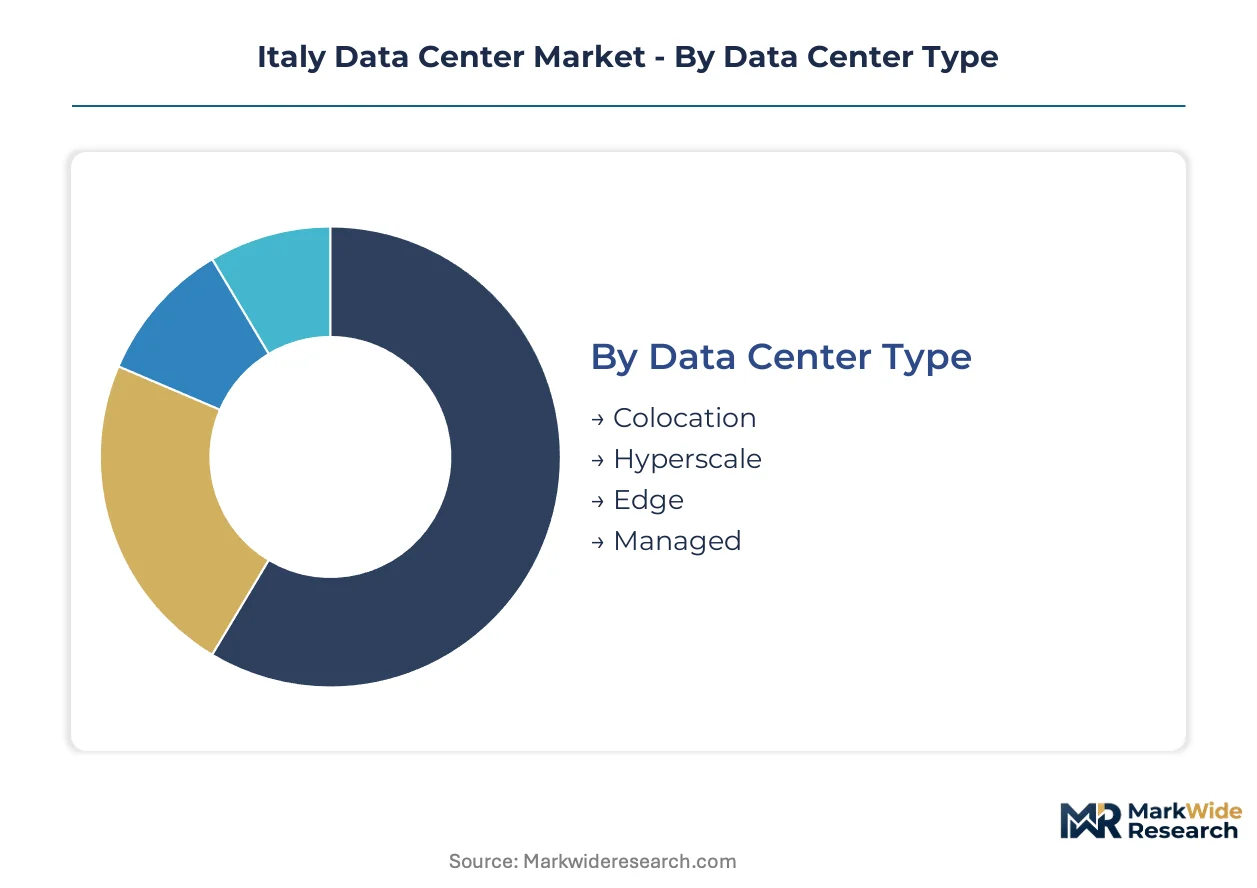
Italian data center procurement fragments across facility architectures, service models, thermal systems, and vertical demand patterns. Each segmentation axis reveals distinct investment priorities shaped by Milan's hyperscale concentration, EU regulatory mandates, and Northern Italy's industrial computing requirements.
Data Center Type:
Facility scale and ownership structure determine power density, interconnection economics, and tenant control levels across the Italian footprint.
- Colocation:Multi-tenant facilities where enterprises lease rack, cage, or suite space with shared power and cooling infrastructure. Milan-headquartered financial institutions dominate demand as they divest owned assets under operational resilience mandates from the national cybersecurity agency.
- Hyperscale:Single-tenant campuses exceeding 15MW designed for cloud platform operators. Construction concentrates near Milan where Terna's transmission grid and trans-Mediterranean fiber landing stations intersect.
- Edge:Distributed micro-facilities positioned for sub-10ms latency to manufacturing and connected vehicle platforms. Northern automotive corridors around Turin and Modena anchor initial deployment.
- Managed:Fully outsourced infrastructure where operators assume hardware lifecycle and platform management. Public-sector buyers favor this model for sovereign data compliance under NIS2 transposition.
Mature deployment sits with Colocation. Newer deployment is concentrated in Hyperscale.
Service Type:
Commercial models diverge between capital-intensive infrastructure rental and value-added operational services.
- Infrastructure as a Service:Metered compute, storage, and networking resources provisioned on demand. Pharmaceutical groups in Lombardy adopt this for variable R&D workloads tied to seasonal trial cycles.
- Disaster Recovery:Secondary site replication and failover orchestration for business continuity. BFSI clients drive adoption as EU DORA requirements harden operational resilience obligations.
- Data Backup:Immutable storage tiers for compliance retention and ransomware recovery. Healthcare providers leverage this for patient record archiving under national data protection frameworks.
- Network Services:Cross-connects, internet exchange access, and private backbone integration. Telecom operators bundle these with facility commitments to defend enterprise relationships.
Revenue concentration favors Infrastructure as a Service. Steepest expansion trajectory belongs to Disaster Recovery.
Cooling Technology:
Thermal management systems face F-Gas quota constraints and rising power density thresholds that favor mechanical innovation.
- Air Cooling:Conventional precision HVAC maintaining 18-27°C through raised-floor distribution. Legacy facilities across Rome and Milan rely on this, though retrofit costs climb under hydrofluorocarbon phase-down schedules.
- Liquid Cooling:Direct-to-chip or rear-door heat exchangers targeting 50kW+ racks. Hyperscale builds near Milan adopt this for AI training clusters where air systems hit thermal limits.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies. Experimental deployments emerge in high-performance computing environments seeking extreme density without mechanical refrigeration.
- Free Cooling:Economizer systems leveraging Northern Italy's temperate climate for partial-year compressor bypass. Alpine-adjacent facilities capture operating cost advantages from seasonal temperature differentials.
Installed base dominance rests with Air Cooling. Technology transition is accelerating fastest in Liquid Cooling.
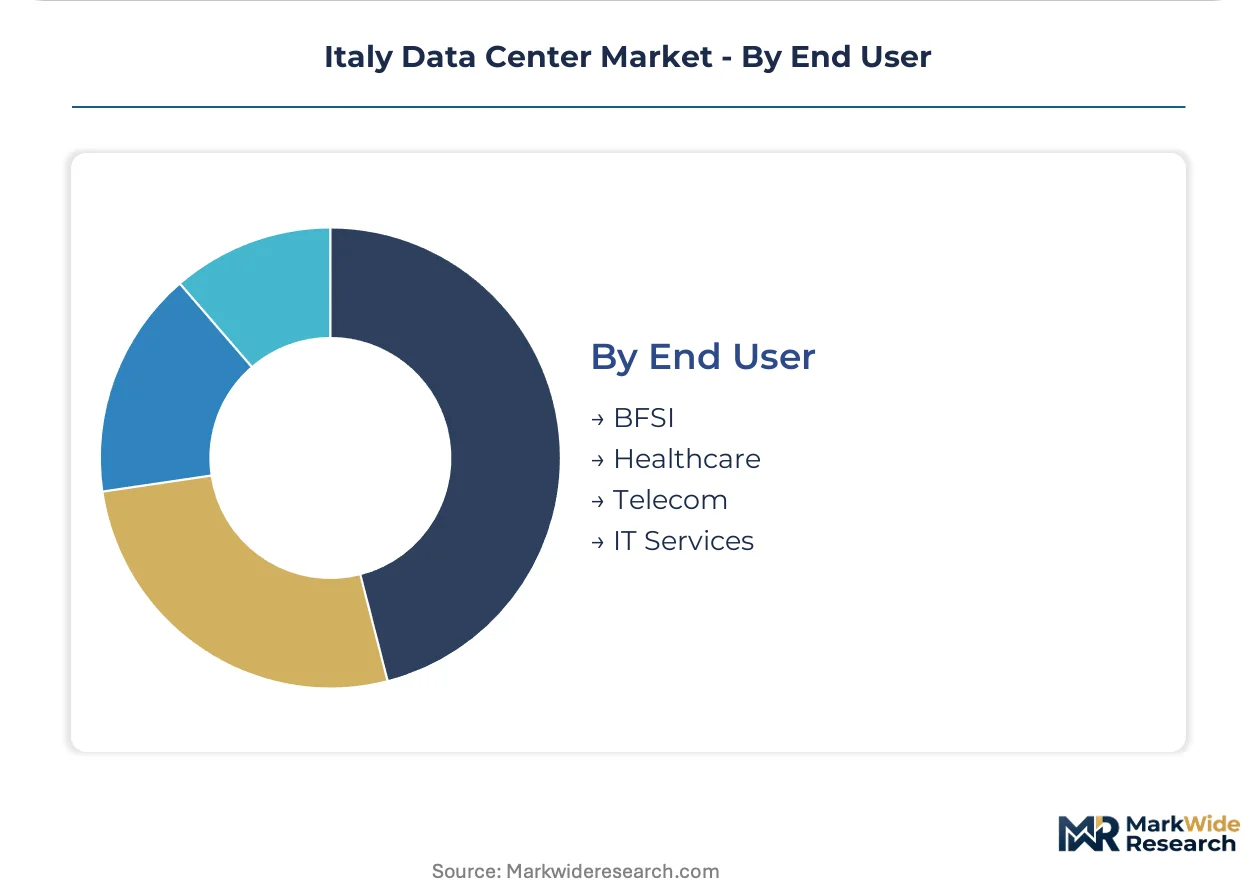
End User:
Vertical demand patterns reflect regulatory exposure, latency sensitivity, and data sovereignty requirements across the Italian economy.
- BFSI:Banks, insurers, and payment processors migrating core systems from mainframe estates. Core banking modernization resists cloud-native refactoring, prolonging hybrid deployment timelines.
- Healthcare:Hospital networks and pharmaceutical manufacturers managing patient data and research compute. EU AI Act documentation requirements impose new burdens on facilities hosting medical imaging AI training.
- Telecom:Mobile and fixed-line operators housing subscriber databases and edge computing infrastructure. 5G core network functions pull compute toward distributed facilities beyond Milan.
- IT Services:Systems integrators and managed service providers reselling capacity to mid-market enterprises. Procurement fragmentation toward modular subscriptions reshapes their sourcing economics.
Contract value leadership belongs to BFSI. Volume expansion is shifting most quickly toward Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's tax-advantaged industrial zones accelerate Milan's hyperscale concentration, pulling investment toward Northern Italy's fiber-dense corridors while regulatory frameworks reshape facility economics nationwide.
Lombardy
Milan's intersection of trans-Mediterranean subsea cables and Terna's high-voltage grid anchors hyperscale construction decisions. The EU AI Act imposes documentation burdens on facilities hosting high-risk AI training workloads. Cloud operators expand campus footprints around the Milan metropolitan area to capture enterprise demand from financial institutions modernizing core banking systems.
Piedmont
Turin's automotive manufacturers demand sub-10ms latency for connected vehicle platforms, pulling edge compute toward manufacturing corridors. NIS2 transposition creates certified facility demand from critical infrastructure operators. Edge micro-facilities cluster along the Torino-Alessandria industrial axis to serve Stellantis and supplier networks.
Veneto
Padua and Verona pharmaceutical groups procure modular capacity subscriptions for variable R&D workloads tied to seasonal trial cycles. The national cybersecurity agency mandates operational resilience standards for healthcare data hosting. Alpine-adjacent facilities near Belluno capture free cooling advantages from seasonal temperature differentials.
Emilia-Romagna
Modena's automotive suppliers and Bologna's industrial automation sector drive latency-sensitive computing requirements. F-Gas Regulation phase-down constrains conventional precision cooling expansion, raising retrofit costs for legacy facilities. Data center development concentrates along the A1 motorway corridor connecting Milan to Florence.
Lazio
Rome's public-sector buyers favor managed infrastructure models for sovereign data compliance under NIS2 transposition. AGCOM regulations governing interconnection shape facility siting decisions. State-owned enterprises and government agencies consolidate workloads in certified colocation environments around the capital.
Italy Data Center Market Competitive Landscape
Top-tier vendors anchor hyperscale construction, while regional specialists defend enterprise relationships through integrated network-facility bundles. The vendor base stratifies across three tiers: global platform operators with multi-country footprints, national telecom incumbents leveraging fiber assets, and pure-play colocation providers competing on compliance certification. Dominant competitive moves include capacity expansion near Milan's fiber intersections and strategic partnerships with renewable energy developers to secure power offtake.
Within the national incumbent tier, Telecom Italia and IRIDEOS exemplify divergent strategies for enterprise retention. Telecom Italia bundles legacy network services with facility commitments to defend relationships with financial institutions undergoing mainframe modernization. IRIDEOS leverages its nationwide fiber footprint to anchor edge deployments across Northern industrial corridors. Aruba SpA occupies a distinct position competing on sovereign data guarantees that appeal to public-sector buyers confronting NIS2 compliance requirements.
| Leading Market Players |
|---|
| IRIDEOS |
| Telecom Italia (TIM) |
| Aruba SpA |
| Digital Realty |
| STACK Infrastructure |
| Equinix |
| Vantage Data Centers |
| BT Italia |
| Data4 |
| Others |
Pricing and Supply Chain Analysis
Base metals price indices for copper and aluminum, critical to electrical infrastructure, cascade through Italian data center construction costs into three distinct procurement tiers. Premium facilities near Milan command elevated rates reflecting secured power interconnection timelines, while secondary markets absorb spot-price volatility through shorter contract structures.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to rack-scale deployments requiring sub-six-month commissioning, while spot inventory of pre-certified cooling equipment trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates NIS2-certified environments from uncertified legacy facilities and basic colocation. Cost compression in standard-tier colocation is intensifying because hyperscale operators are absorbing interconnection premiums into bundled offerings. Public-sector buyers demonstrate lowest price sensitivity, prioritizing sovereign data guarantees over per-kilowatt economics.
Supply Chain Analysis
Dual-sourcing requirements from Terna and major Italian utilities mandate multi-supplier qualification for critical power infrastructure, extending procurement cycles. Taiwan, China, and Germany anchor server and switchgear supply, while domestic electrical trades draw from regional contractor pools. The supply chain rests on Taiwanese OEM lead times stretching 20-28 weeks for liquid-cooled rack systems. Single-source vulnerability concentrates in precision cooling compressors subject to F-Gas quota restrictions. Distribution runs through systems integrators and direct hyperscale procurement channels, with mid-market enterprises accessing capacity via telecom-bundled offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy data center market functions as a cost-of-compliance story where EU AI Act documentation mandates create barrier-to-entry moats favoring certified incumbents. NIS2 transposition hardens this dynamic by requiring audit-ready environments that smaller operators cannot provision economically.
For Market Incumbents: Deploy liquid cooling convergence as a defensive lever against thermal density limits in legacy Milan facilities. Secure renewable energy offtake agreements with Terna-registered developers to lock in power pricing ahead of interconnection queue backlogs. Vertical integration into district heating partnerships monetizes waste heat recovery, offsetting F-Gas retrofit costs while differentiating against pure-play colocation competitors. For New Entrants and Emerging Players: Launch via submarine cable landing station partnerships in Sicily and Calabria, targeting latency arbitrage for North African and Middle Eastern traffic. Southern Italy's underdeveloped infrastructure offers first-mover positioning absent hyperscale saturation. Edge micro-facilities along Turin-Modena automotive corridors penetrate the fastest-expanding latency-sensitive segment with sub-10ms value propositions. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fiber-facility operators with NIS2 pre-certification. Long-term viability hinges on power interconnection securedness rather than pure location. The signal to watch is Terna's queue clearance velocity for 132kV substations, which would unlock greenfield development economics and compress acquisition premiums for shovel-ready sites.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems enable AI training cluster hosting under EU AI Act thermal documentation requirements. |
| Renewable Energy Offtake Securement | Long-term PPAs with Terna-registered developers insulate against power interconnection queue delays. |
| NIS2 Certification Pre-Investment | Audit-ready environments capture public-sector procurement migrating from legacy Telecom Italia bundles. |
| Submarine Cable Landing Partnership | Sicily-adjacent positioning intercepts trans-Mediterranean traffic seeking low-latency European termination. |
| District Heating Integration | Waste heat recovery partnerships with municipal utilities monetize thermal output and differentiate facility economics. |
Research Methodology
Regulatory filings from AGCOM, Terna grid interconnection databases, and EU NIS2 implementation guidance formed the secondary backbone of this analysis. Primary interviews with data center engineering directors, utility procurement officers at Terna, and enterprise IT infrastructure heads at Milan-headquartered financial institutions validated demand assumptions. Bottom-up facility capacity tracking and top-down cloud capex allocation modeling were triangulated against hyperscale construction permits in Lombardy.
Bottom-up modeling aggregated individual facility power commitments and tenant expansion schedules, while top-down analysis cross-referenced cloud operator European investment disclosures. Segmentation across facility type, cooling technology, service model, and vertical end-use shaped volume and value outputs across the projection horizon. CAGRs were derived from facility commissioning pipelines and power grid expansion timelines, with AI training workload growth rates applied as a demand-side modifier.
Power grid interconnection delays, F-Gas quota allocation volatility, and EU AI Act enforcement variance are the dominant revision risks to these projections. Deviation in Terna's queue clearance velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
North America Hyperscale Data Center Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market