
 Global Hyper-Converged Infrastructure Market | 2026-2036
Global Hyper-Converged Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyper-Converged Infrastructure Market Foresight
Healthcare provider IT modernization is restructuring procurement patterns across the hyper-converged infrastructure landscape. Dell Technologies leverages its integrated server-storage portfolio to dominate enterprise data center consolidation projects. Nutanix anchors its position through software-defined architecture that spans on-premises and hybrid cloud deployments. Hewlett Packard Enterprise competes through GreenLake as-a-service models that reduce capital intensity for mid-market buyers.
Hyper-converged infrastructure integrates compute, storage, and networking into a single software-defined platform managed through a unified control plane, typically deployed on commodity x86 servers with NVMe flash tiers and 25/100GbE fabric connectivity. Its primary purpose is to collapse legacy three-tier data center architectures into scalable building blocks that reduce operational overhead and accelerate workload provisioning. The solution type dimension shows compute and storage combinations capturing the deepest margin pools, while data protection and security layers are expanding fastest as ransomware resilience becomes a board-level priority. Deployment mode insights reveal hybrid cloud configurations leading new installations, though managed services and colocation options are gaining traction among organizations lacking internal platform engineering expertise.
The U.S. Federal Risk and Authorization Management Program and the EU Cybersecurity Act are tightening certification requirements for infrastructure deployed in government and regulated industries, directly shaping vendor product roadmaps and market access conditions. China's MIIT cloud computing standards and data localization rules are fragmenting architecture choices for multinational enterprises operating across jurisdictions. ISO 27001 and SOC 2 Type II frameworks now serve as baseline procurement filters rather than differentiators, compressing competitive space to implementation velocity and interoperability breadth. Stakeholders must monitor evolving sovereign cloud mandates and edge computing regulations that will determine where infrastructure control planes must physically reside.
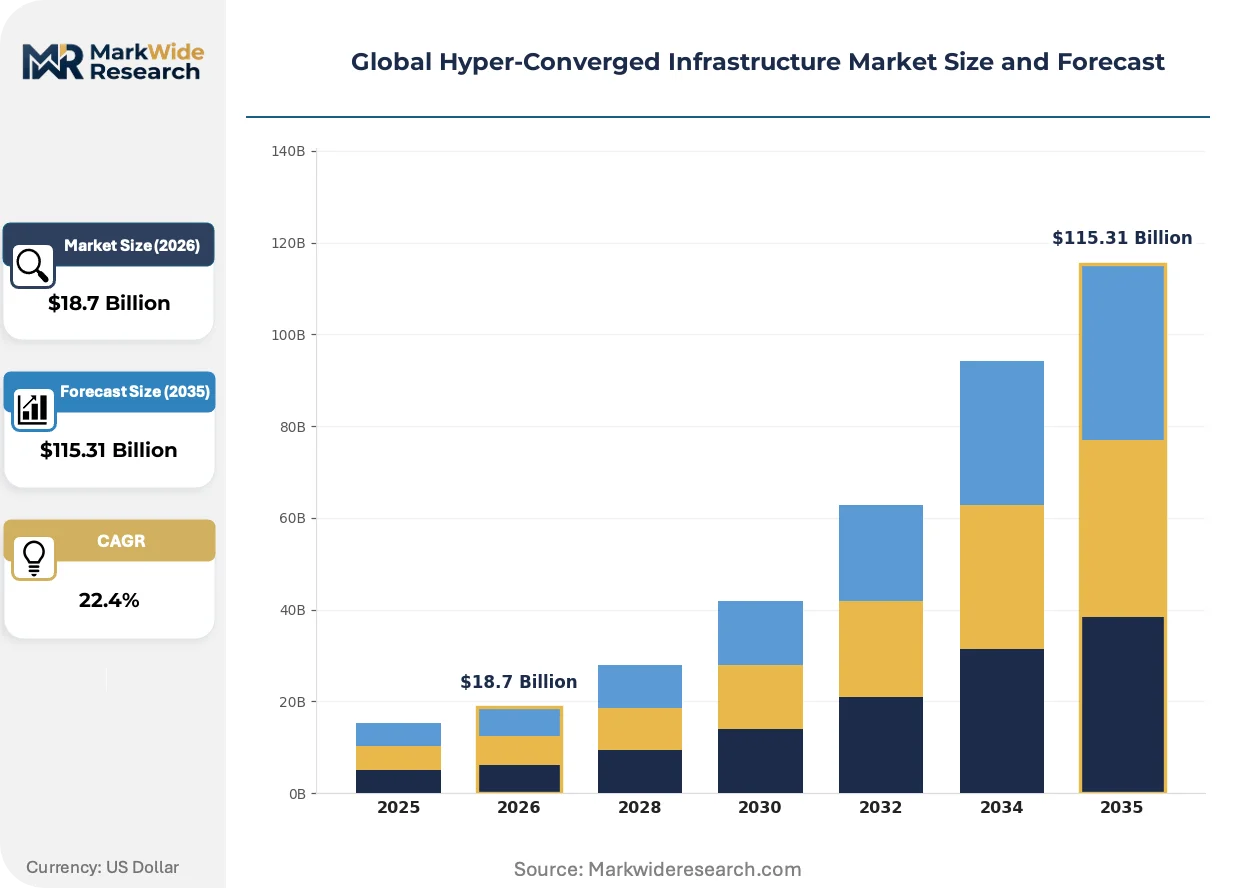
Market Dynamics
Data sovereignty mandates are fragmenting infrastructure deployment patterns as enterprises must physically locate control planes within jurisdictional boundaries, forcing vendors to engineer multi-instance architectures rather than centralized cloud management.
Growth Catalysts
- EU AI Act compliance:Automated governance requirements are accelerating procurement of HCI platforms with embedded policy enforcement and audit logging capabilities across European financial services.
- Edge computing proliferation:Manufacturing and logistics operators are deploying modular HCI nodes at plant floors to process machine vision and predictive maintenance workloads locally.
- India's sovereign cloud buildout:National data localization directives under RBI and SEBI guidelines are driving state-owned enterprises toward on-premises HCI deployments over hyperscaler alternatives.
Market Restraints
- NVMe flash supply concentration:Memory controller fabrication depends on Taiwan and South Korea foundry capacity, exposing infrastructure vendors to input cost volatility and allocation constraints.
- China MIIT certification delays:Multinational enterprises face 12-18 month approval timelines for HCI deployments, fragmenting architecture standardization across their operating regions.
- Hyperscaler bare-metal substitution:AWS Outposts, Azure Stack, and Google Distributed Cloud are capturing workloads that previously defaulted to third-party HCI stacks.
Strategic Opportunities
- Germany industrial edge:Automotive and precision engineering clusters in Baden-Württemberg and Bavaria are underpenetrated for shop-floor HCI despite advanced automation adoption.
- Healthcare data protection layers:HIPAA-driven encryption and immutable backup requirements are creating attach-rate expansion for security-integrated HCI configurations in US provider networks.
- Disaggregated composable infrastructure:Convergence of software-defined storage with CXL memory pooling is enabling new rack-scale architectures that blur traditional HCI boundaries.
Industry Challenges
- Platform engineering talent scarcity:Enterprise IT organizations lack staff fluent in Kubernetes orchestration atop HCI substrates, slowing production deployments and increasing professional services dependency.
- Three-tier legacy integration friction:Mainframe and traditional SAN environments resist seamless HCI assimilation, forcing costly parallel operations during multi-year migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyper-Converged Infrastructure Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid Cloud, Managed Services, Colocation Solution Type: Compute, Storage, Networking, Data Protection, Analytics, Security Application: Data Center Consolidation, Virtual Desktop Infrastructure, Disaster Recovery, Edge Computing, Cloud Computing End User: Telecommunications Providers, Financial Services Firms, Manufacturing Enterprises, Educational Institutions, Government Agencies |
| Companies Covered | Dell Technologies, Nutanix, Hewlett Packard Enterprise, VMware, Cisco Systems, Huawei Technologies, NetApp, IBM, Hitachi Vantara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyper-Converged Infrastructure Market Shifts & Advancements
Workload portability requirements are dissolving the boundary between on-premises infrastructure and public cloud control planes, forcing vendors to engineer unified management layers that span both substrates without operational discontinuity.
NVMe-oF (NVMe over Fabrics) is overtaking iSCSI and traditional SAN protocols as the dominant storage interconnect in enterprise data centers. Financial services trading floors and electronic health record systems are adopting RDMA-capable 100GbE fabrics to achieve sub-100 microsecond latency. This protocol shift is compressing the performance differentiation between all-flash arrays and integrated HCI storage tiers.
The EU Cybersecurity Act and its Common Criteria certification schemes are mandating formal security evaluation for infrastructure deployed in government and critical national infrastructure sectors. Vendors must now maintain parallel product lines: standard commercial releases and evaluated configurations with hardened firmware. German federal procurement and French healthcare networks are most affected, with tenders now specifying EAL4+ assurance levels.
Consumption-based financing models are displacing traditional capital purchase cycles for mid-market buyers. HPE GreenLake, Dell APEX, and Nutanix Clusters are capturing workloads through opex-aligned contracts that bundle hardware, software, and managed services. This pattern is most visible in United States healthcare systems and United Kingdom local government, where budget constraints favor predictable monthly payments over three-year depreciation schedules.
Global Hyper-Converged Infrastructure Market Segmentation
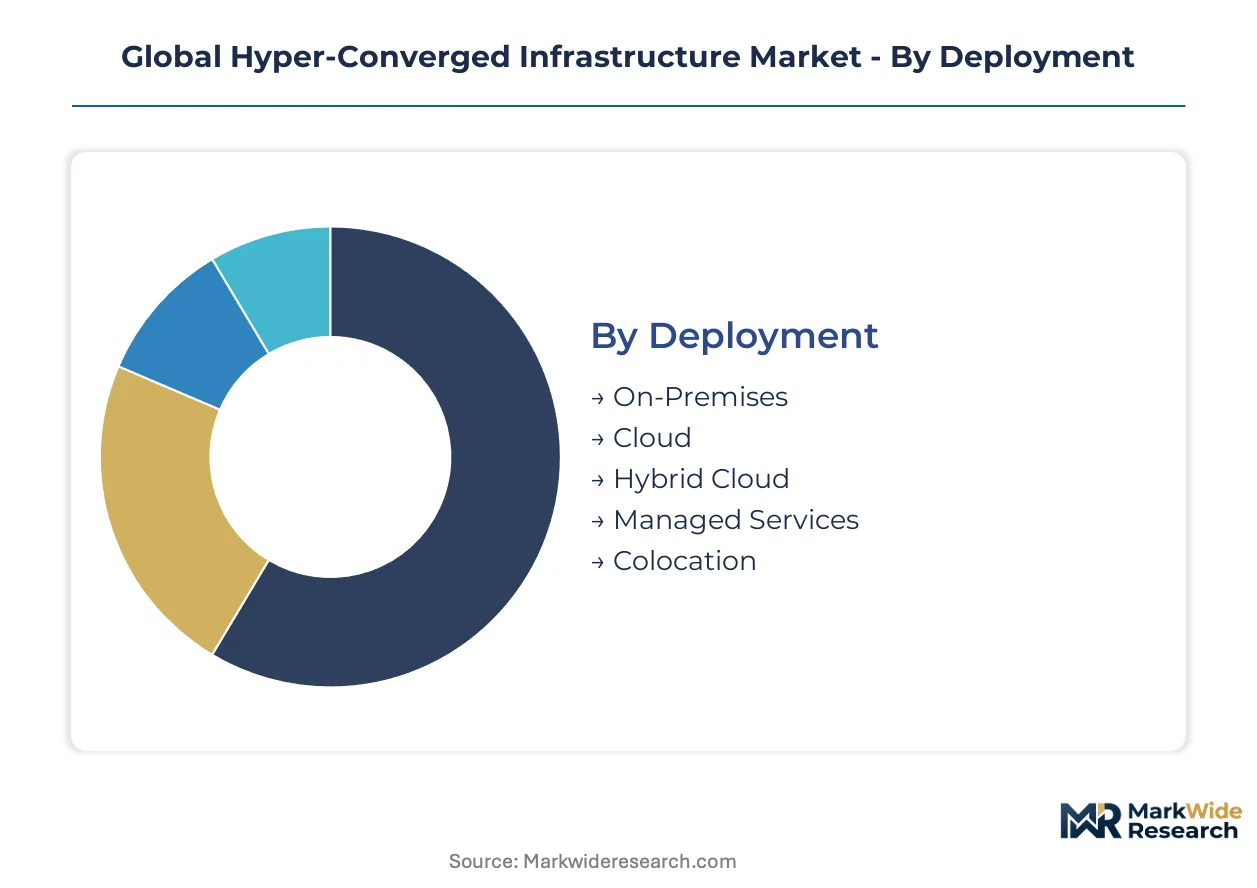
Hyper-converged infrastructure procurement patterns diverge sharply across deployment models, solution architectures, and regulatory exposure profiles. Understanding these segment boundaries reveals where vendor R&D investments concentrate and which customer verticals command premium pricing.
Deployment:
NVMe flash density and control plane location determine architectural choices across installation modes.
- On-Premises:Full hardware ownership with dedicated rack-scale deployments using 25/100GbE fabrics and NVMe flash tiers. Financial services firms in Germany and India favor this mode for RBI and BaFin data localization mandates that prohibit cross-border control plane access.
- Cloud:Hyperscaler-hosted HCI stacks with subscription licensing. Manufacturing enterprises in the United States are retreating from this mode as egress costs accumulate and sovereign cloud requirements harden.
- Hybrid Cloud:Unified management layers spanning owned infrastructure and hyperscaler capacity. Telecommunications providers across the United States, Germany, and India are standardizing on this architecture to arbitrage latency-sensitive versus batch workloads.
- Managed Services:Third-party operation of customer-owned or leased hardware. Educational institutions lacking platform engineering staff are outsourcing lifecycle management to specialist providers.
- Colocation:Customer-owned equipment in multi-tenant facilities with shared power and network infrastructure. Government agencies seeking FedRAMP or EU Cybersecurity Act certification without capital construction are migrating here.
Hybrid Cloud leads on scale; Managed Services leads on momentum.
Solution Type:
Margin pools concentrate where software-defined abstraction layers replace discrete hardware appliances.
- Compute:Virtualized x86 server resources with Kubernetes orchestration substrates. Virtual Desktop Infrastructure deployments in United States healthcare systems and German automotive engineering clusters consume the densest compute configurations.
- Storage:Software-defined pools with erasure coding and deduplication. This layer commands the deepest margin pools as all-flash tiers displace hybrid configurations in financial services risk analytics workloads.
- Networking:Virtual switching and microsegmentation embedded in the hypervisor. Demand concentrates in telecommunications provider edge nodes requiring 5G core user plane function hosting.
- Data Protection:Immutable snapshots, replication, and ransomware recovery orchestration. United States hospital networks facing HIPAA enforcement are expanding attach rates for integrated backup layers.
- Analytics:In-place query processing without data movement to external warehouses. Manufacturing enterprises in Bavaria are deploying this for predictive maintenance on shop-floor HCI nodes.
- Security:Encryption, key management, and zero-trust policy enforcement. EU AI Act compliance requirements are accelerating procurement of platforms with embedded audit logging across French and German financial services.
Storage dominates revenue contribution; Security is climbing the fastest.
Application:
Workload characteristics dictate node sizing, fabric bandwidth, and data services requirements.
- Data Center Consolidation:Migration from three-tier architectures to unified building blocks. United States federal agencies under data center optimization mandates are retiring legacy SAN environments through this application.
- Virtual Desktop Infrastructure:Persistent and non-persistent desktop hosting with GPU passthrough. Educational institutions in India are scaling VDI for remote learning infrastructure under national digital education initiatives.
- Disaster Recovery:Synchronous and asynchronous replication with automated failover. Financial services firms in Germany are mandating sub-15-minute recovery point objectives that HCI replication satisfies.
- Edge Computing:Modular nodes for plant-floor, retail, and cell-tower deployment. Automotive manufacturers in Baden-Württemberg are processing machine vision workloads locally to minimize cloud latency.
- Cloud Computing:Self-service workload provisioning with chargeback metering. Government agencies in the United States are deploying this for inter-agency resource sharing while maintaining CJIS compliance.
Data Center Consolidation anchors installed base; Edge Computing shows steepest expansion trajectory.
End User:
Procurement authority and compliance exposure shape vendor engagement models and contract structures.
- Telecommunications Providers:5G core and edge computing infrastructure at national scale. Indian operators under TRAI localization rules are building sovereign cloud capacity through on-premises HCI rather than hyperscaler alternatives.
- Financial Services Firms:Real-time risk analytics and trading infrastructure with sub-millisecond latency requirements. EU AI Act automated governance mandates are reshaping European procurement toward platforms with embedded policy enforcement.
- Manufacturing Enterprises:Predictive maintenance and digital twin workloads at production facilities. Precision engineering clusters in Germany remain underpenetrated despite advanced automation adoption.
- Educational Institutions:Research computing and administrative system consolidation. Budget constraints in United Kingdom universities are favoring consumption-based financing over capital purchase cycles.
- Government Agencies:Classified and unclassified workloads with certification requirements. FedRAMP and EU Cybersecurity Act Common Criteria schemes are filtering vendor participation to evaluated product lines.
Telecommunications Providers represent the largest addressable spend; Financial Services Firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering clusters anchor infrastructure demand as German automotive manufacturers deploy edge nodes for real-time quality control. Sovereign cloud mandates and data localization rules are fragmenting procurement patterns across major economies. Regulatory divergence between jurisdictions forces vendors to engineer multi-instance architectures rather than centralized management planes.
United States
Federal agencies under data center optimization mandates drive consolidation from legacy SAN environments to unified building blocks. FedRAMP certification requirements filter vendor participation to evaluated product lines for government workloads. Healthcare systems in Texas and California favor consumption-based financing models that bundle hardware with managed services.
Germany
BaFin data localization mandates prohibit cross-border control plane access for financial services trading infrastructure. EU Cybersecurity Act Common Criteria schemes mandate EAL4+ assurance levels for federal procurement and French healthcare network tenders. Bavarian automotive clusters remain underpenetrated for shop-floor HCI despite advanced automation adoption.
India
RBI and SEBI national data localization directives steer state-owned enterprises toward on-premises deployments over hyperscaler alternatives. TRAI localization rules push telecommunications operators to build sovereign cloud capacity through owned infrastructure. Educational institutions in Maharashtra and Karnataka scale virtual desktop infrastructure under national digital education initiatives.
China
MIIT cloud computing standards and certification delays fragment architecture standardization for multinational enterprises operating across jurisdictions. Data localization rules under national cybersecurity law mandate physical control plane residence within territorial boundaries. Manufacturing enterprises in Yangtze River Delta clusters process predictive maintenance workloads locally to minimize latency.
United Kingdom
Budget constraints in universities favor predictable monthly payments over three-year capital depreciation schedules for research computing consolidation. Local government procurement patterns shift toward managed services models that outsource lifecycle management to specialist providers. Healthcare networks in England expand attach rates for security-integrated configurations facing enforcement pressure.
Global Hyper-Converged Infrastructure Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors align to bridge software-defined storage with emerging memory pooling technologies. The vendor base clusters around three distinct archetypes: integrated server-storage portfolio providers, software-defined architecture specialists, and as-a-service consumption model operators. Tiered competitive positioning separates premium-tier evaluated configurations from standard commercial releases. Portfolio diversification and geographic expansion represent the dominant competitive moves as vendors engineer parallel product lines for regulated and unregulated market segments.
Within the integrated infrastructure tier, Dell Technologies exemplifies the server-storage convergence archetype through its rack-scale deployment capabilities. Nutanix occupies a position as the software-defined architecture anchor spanning on-premises and hybrid cloud substrates. Hewlett Packard Enterprise represents the as-a-service consumption model through opex-aligned contract structures that reduce capital intensity for mid-market buyers.
| Leading Market Players |
|---|
| Dell Technologies |
| Nutanix |
| Hewlett Packard Enterprise |
| VMware |
| Cisco Systems |
| Huawei Technologies |
| NetApp |
| IBM |
| Hitachi Vantara |
| Others |
Supply & Pricing Matrix
Platform engineering talent scarcity in India and Eastern Europe widens pricing-tier spreads as labor-cost differentials between certified integration specialists and commodity hardware technicians stratify procurement budgets across enterprise and mid-market segments.
Pricing Analysis
Input-cost pass-through from NVMe flash memory controllers anchors pricing volatility across hardware tiers. Three-tier pricing structure across premium, standard, and economy levels separates EAL4+ certified configurations for German federal procurement from commercial releases. Cost compression in standard tiers intensifies because Taiwan and South Korea foundry allocation constraints squeeze component availability. Mid-market buyers in United Kingdom local government exhibit highest price sensitivity, while financial services firms in Germany accept premium positioning for compliance-integrated stacks.
Supply Chain Analysis
Reverse-logistics flows for rack-scale server refreshes concentrate refurbishment activity in Singapore and Netherlands distribution hubs before redeployment to Indian educational institutions and Southeast Asian colocation facilities. Memory controller fabrication draws from Taiwan and South Korea, while x86 server assembly centers on China and Mexico. Single-source vulnerability in advanced node semiconductor production exposes lead times to geopolitical disruption. Distribution runs through direct vendor channels for enterprise accounts and value-added resellers serving mid-market buyers lacking platform engineering staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act compounds infrastructure demand as automated governance mandates force European financial services toward embedded policy enforcement platforms.
For Market Incumbents: Deepen software-defined storage integration with CXL memory pooling to defend against hyperscaler bare-metal substitution. Expand EAL4+ certification maintenance for German federal and French healthcare tenders. Prioritize backward integration into NVMe flash controller supply relationships to mitigate Taiwan and South Korea foundry allocation risk. For New Entrants and Emerging Players: EU AI Act in Germany and France opens a window for security-integrated HCI configurations with embedded audit logging. Target Baden-Württemberg precision engineering clusters where shop-floor edge penetration remains underdeveloped. Lead with managed services wrapping to bypass internal platform engineering talent scarcity among mid-market manufacturing enterprises. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, seeking on-premises bridge technologies for hybrid cloud arbitrage. Focus on software-defined architecture specialists with Kubernetes-native orchestration substrates. Monitor CXL ecosystem maturation as inflection indicator for rack-scale composable infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Investment | EAL4+ assurance levels unlock German federal procurement and French healthcare network tenders under EU Cybersecurity Act mandates. |
| Managed Services Capability Buildout | Opex-aligned contracts capture United Kingdom universities and local government buyers facing capital budget constraints. |
| Edge Node Miniaturization | Modular HCI form factors penetrate Baden-Württemberg automotive plant floors for machine vision workload localization. |
| Hyperscaler Interoperability Layer | Unified management planes spanning owned infrastructure and AWS Outposts satisfy United States telecommunications provider hybrid requirements. |
| Memory Pooling Technology Integration | CXL-enabled disaggregated architectures blur traditional HCI boundaries for Bavarian predictive maintenance deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center architects, platform engineers, procurement officers at financial services firms, and managed services providers with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory implementation guidance. Bottom-up sizing of node shipments and top-down cross-check against vendor revenue disclosures ensured triangulation integrity.
Segment-weighting approaches distributed value across deployment modes, solution architectures, and end-user verticals with India sovereign cloud buildout and Germany industrial edge penetration treated as distinct regional growth vectors. CAGRs derived from logistic curve fitting to adoption saturation levels incorporated NVMe-oF protocol transition timelines and EAL4+ certification pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under China MIIT certification delay extensions or Taiwan semiconductor supply disruption. Practitioners should monitor EU AI Act implementation timelines and CXL ecosystem commercialization milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Brazil Data Center Physical Security Market