
 Global Software-Defined Data Center Market | 2026-2036
Global Software-Defined Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software-Defined Data Center Market Foresight
Enterprise buyers are bifurcating from traditional capital-intensive data center operators toward cloud-native financial services and telecommunications providers seeking programmable infrastructure. VMware, Inc. leverages its virtualization stack to anchor private cloud deployments among regulated industries. Microsoft Corporation sustains hybrid cloud momentum through deep integration between Azure Stack and enterprise Windows environments. Cisco Systems, Inc. competes on network virtualization, extending its switching dominance into software-defined fabrics for multi-tenant facilities.
Software-Defined Data Center refers to an architecture where compute, storage, networking, and security resources are abstracted from physical hardware and provisioned through policy-driven automation, typically using hypervisors, software-defined networking controllers, and API-orchestrated storage pools to deliver infrastructure-as-code capabilities. Its primary commercial purpose is enabling elastic capacity scaling, automated workload placement, and reduced operational expenditure for organizations operating at cloud scale. Hybrid Cloud deployments now generate the largest revenue pool as enterprises retain sensitive workloads on-premises while bursting to public infrastructure. Compute Virtualization remains the most mature solution category with established margin compression, while Security Orchestration is expanding fastest as zero-trust mandates proliferate across regulated verticals.
The EU AI Act and GDPR impose automated data governance requirements that directly shape European procurement criteria for policy-enforced virtualization platforms. In the United States, NIST cybersecurity frameworks and SEC disclosure rules for material incident reporting are driving financial services toward auditable, software-defined infrastructure with immutable logging. China MIIT standards on data localization and GB compliance for critical information infrastructure add complexity for multinational deployments. Stakeholders must evaluate whether their automation stacks can satisfy divergent jurisdictional compliance without fragmenting operational consistency.
Market Dynamics
Financial services firms are demanding programmable infrastructure that can enforce compliance policies automatically across distributed compute environments, compressing procurement cycles from hardware-centric to API-driven provisioning models.
Growth Catalysts
- GDPR automated enforcement mandates:European data protection authorities require auditable data lineage and automated deletion protocols, pushing enterprises toward policy-driven virtualization platforms with immutable logging capabilities.
- Hyperscale cloud campus expansion:Northern Virginia and Oregon data center clusters are absorbing enterprise workload migrations, creating concentrated demand for software-defined networking fabrics that span multi-tenant facilities.
- Real-time transaction processing requirements:Payment networks and securities exchanges require sub-millisecond workload placement, driving adoption of compute virtualization with predictive resource orchestration.
Market Restraints
- Specialized engineering talent scarcity:Kubernetes and SDN controller expertise commands premium compensation, constraining deployment velocity for mid-market enterprises without captive technical workforces.
- Critical component supply concentration:Merchant silicon for programmable switches concentrates among Taiwan-based foundries, exposing infrastructure timelines to geopolitical friction and export control uncertainty.
- Legacy hardware sunk costs:Enterprises with depreciated but functional physical infrastructure face internal resistance to full-stack virtualization despite operational efficiency gains.
Strategic Opportunities
- India's data localization requirements:RBI and SEBI mandates for domestic financial data storage are creating greenfield demand for software-defined private cloud deployments among multinational banks.
- Security orchestration convergence:Zero-trust network access and microsegmentation are merging into unified policy engines, opening white space for platforms that integrate identity-aware networking with workload isolation.
- Edge computing distribution models:Telecommunications providers are deploying software-defined infrastructure at cell tower aggregation points, enabling new consumption-based pricing for distributed compute.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent policy enforcement across VMware, Azure Stack, and native public cloud control planes without operational fragmentation.
- Compliance certification timelines:FedRAMP and ISO 27001 attestation processes for software-defined platforms extend 12-18 months, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software-Defined Data Center Market |
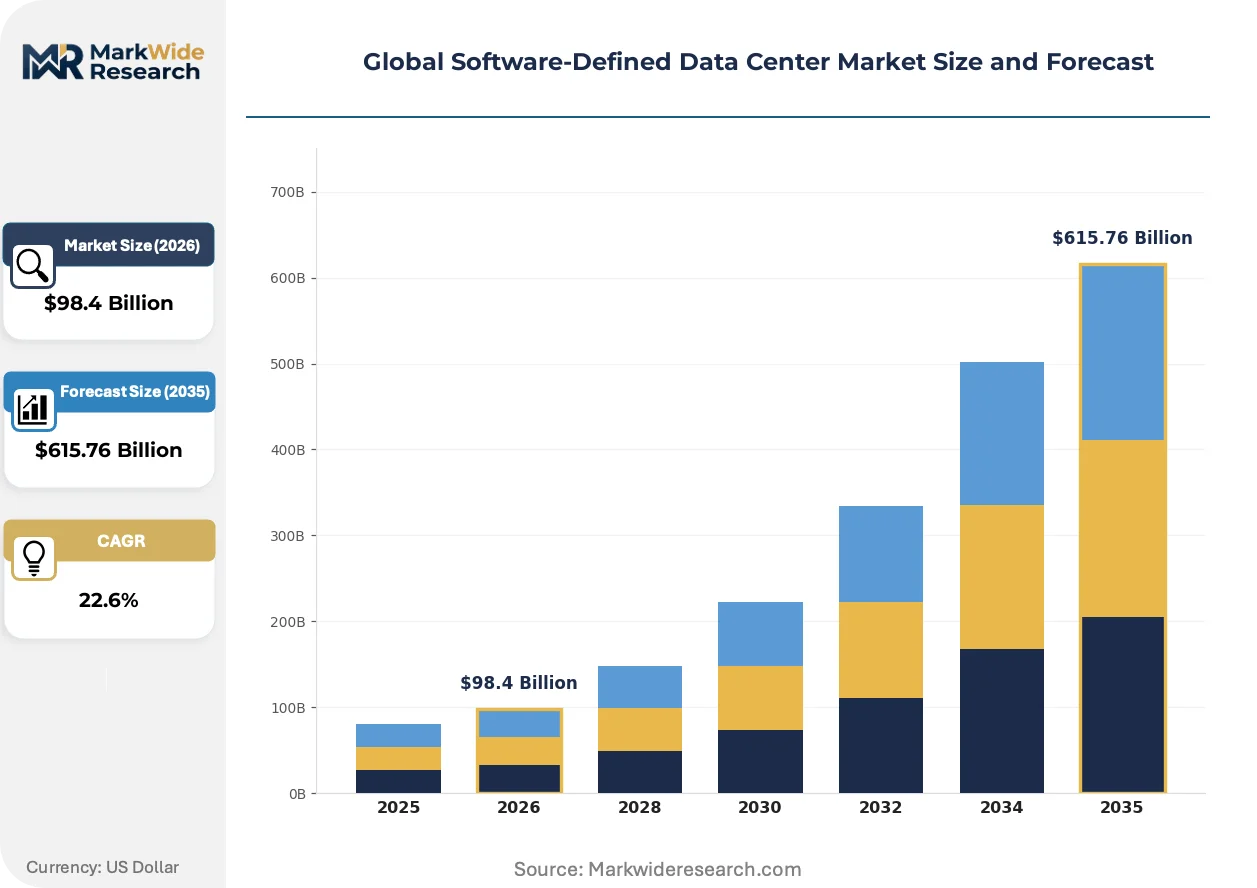
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $615.76 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Offering: Compute Virtualization, Network Virtualization, Storage Virtualization, Security Orchestration, Automation Tools Use Case: Disaster Recovery, Application Development, Testing & QA, Big Data Analytics, Cloud Migration End User Industry: Telecommunications, Financial Services, Education Providers, Government Agencies, Media & Entertainment |
| Companies Covered | VMware, Inc., Microsoft Corporation, Dell Technologies, IBM Corporation, Cisco Systems, Inc., Hewlett Packard Enterprise Development LP, Nutanix, Inc., Oracle Corporation, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software-Defined Data Center Market Shifts & Advancements
Container-native virtualization is compressing the boundary between traditional hypervisors and orchestration layers, forcing infrastructure vendors to reposition around Kubernetes-centric control planes rather than legacy VM management.
Infrastructure-as-code declarative provisioning is supplanting manual configuration workflows in regulated industries. Financial services DevOps teams are adopting GitOps patterns for network and storage policy management, cutting provisioning time from weeks to hours. This shift is compressing margins for professional services-dependent vendors while rewarding API-first platform providers.
The EU AI Act risk classification framework is mandating automated logging and audit trails for high-risk AI workloads. European enterprises must deploy immutable infrastructure telemetry by mid-decade, driving procurement criteria toward software-defined platforms with built-in compliance instrumentation. German automotive and French healthcare providers are piloting these capabilities first.
Consumption-based infrastructure procurement is displacing traditional capital lease arrangements among mid-market enterprises. Managed service providers are offering software-defined data center stacks as operational expenditures, transferring hardware lifecycle risk from buyers to vendors. This pattern is most visible in the United Kingdom and Netherlands, where CFOs prioritize balance-sheet flexibility over ownership.
Global Software-Defined Data Center Market Segmentation
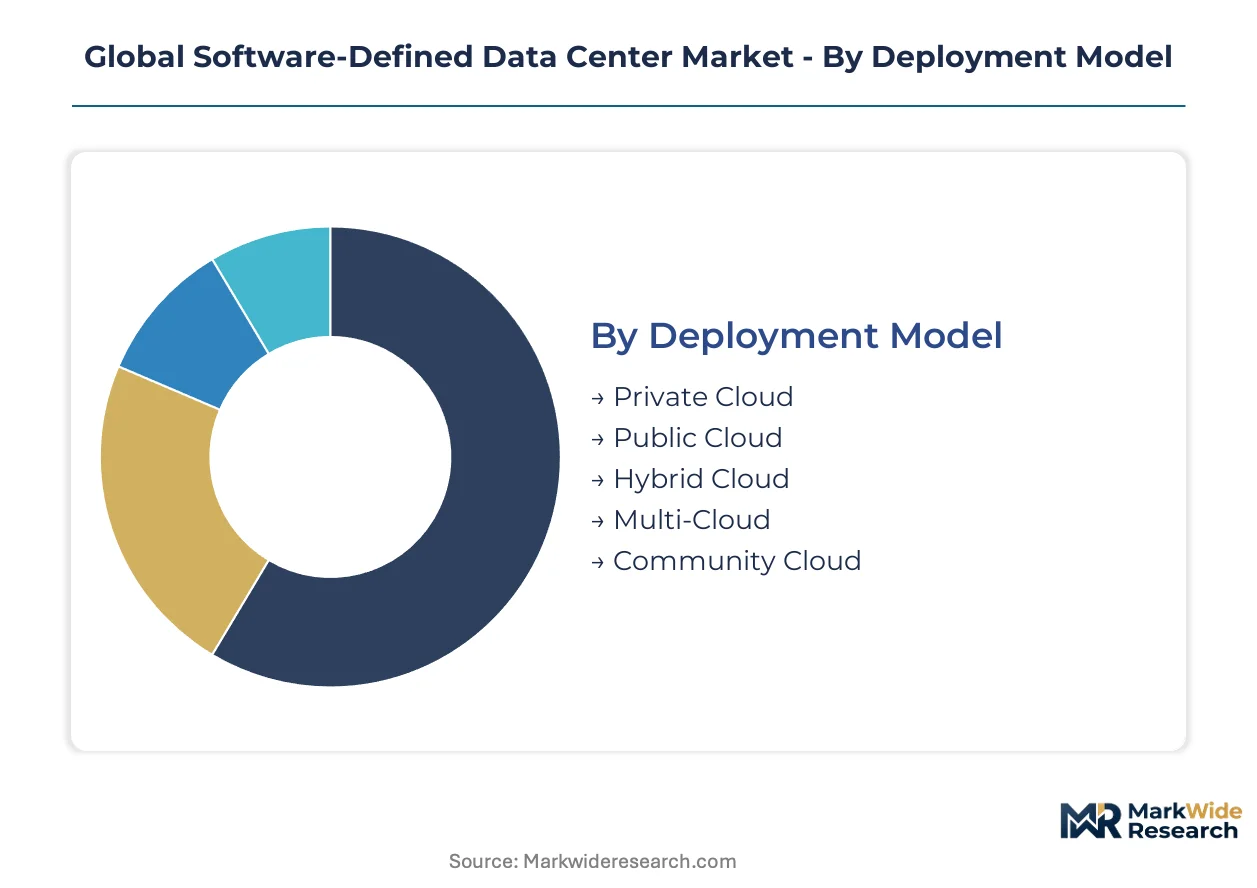
Segmentation in the Software-Defined Data Center market reveals how procurement channels diverge between capital-intensive private deployments and consumption-based public arrangements. Each dimension exposes distinct margin structures, compliance requirements, and vendor competitive positioning.
Deployment Model:
Channel economics split sharply between perpetual-license private infrastructure and metered public consumption, with hybrid deployments commanding premium integration services.
- Private Cloud:Dedicated virtualized infrastructure deployed within enterprise-controlled facilities, governed by VMware vSphere or OpenStack control planes. Financial services firms in Frankfurt and Singapore deploy these for PCI-DSS workloads requiring air-gapped environments. Procurement flows through systems integrators with multi-year maintenance contracts.
- Hybrid Cloud:Unified management planes spanning on-premises VMware or Azure Stack with burst capacity to AWS or Azure public regions. Northern Virginia enterprises favor this model for SEC-compliant workload portability with immutable audit logging across boundaries. This is where expansion concentrates most quickly among regulated verticals.
- Public Cloud:Fully abstracted infrastructure delivered via API without hardware ownership, dominated by hyperscale providers with proprietary SDN fabrics.
- Multi-Cloud:Orchestration layers abstracting VMware, Azure, AWS, and GCP control planes through Kubernetes-centric management.
- Community Cloud:Shared infrastructure serving specific industry verticals with mutualized compliance costs, common among German automotive suppliers.
Private Cloud dominates installed base. Hybrid Cloud is where expansion concentrates.
Solution Offering:
Margin profiles vary from commoditized compute hypervisors to emerging security orchestration platforms commanding 40-60% software gross margins.
- Compute Virtualization:Hypervisor layer abstracting CPU, memory, and I/O resources from physical servers, dominated by x86-64 architectures with ARM emerging at edge locations. Established price compression limits differentiation to management tooling rather than core virtualization engines.
- Security Orchestration:Policy-driven microsegmentation, zero-trust network access, and automated threat response integrated with identity providers. EU AI Act mandates for immutable logging drive procurement among French healthcare and German automotive providers, with steepest expansion trajectory across all solution categories.
- Network Virtualization:SDN controllers decoupling data and control planes, enabling multi-tenant fabric management across distributed facilities.
- Storage Virtualization:Software-defined pools aggregating NVMe, SSD, and HDD tiers through API-provisioned volumes.
- Automation Tools:Infrastructure-as-code frameworks enabling GitOps workflows for network and storage policy management.
Compute Virtualization saturates mature accounts. Security Orchestration is where expansion concentrates.
Use Case:
Workload characteristics determine orchestration complexity, with stateful applications demanding persistent storage fabrics while ephemeral workloads prioritize rapid provisioning velocity.
- Cloud Migration:Systematic relocation of legacy workloads from physical or virtualized infrastructure to software-defined environments with dependency mapping and rollback capabilities. US federal agencies executing FedRAMP-authorized migrations drive specialized procurement through approved system integrators.
- Big Data Analytics:Distributed compute frameworks requiring software-defined storage with locality-aware placement and GPU-accelerated virtualization. Indian IT services providers deploy these for RBI-compliant financial data processing within domestic boundaries.
- Disaster Recovery:Automated failover orchestration with RPO/RTO guarantees through stretched clusters and synchronous replication.
- Application Development:Self-service provisioning for DevOps pipelines with policy-governed resource quotas and chargeback mechanisms.
- Testing & QA:Ephemeral environment instantiation with synthetic data generation and automated teardown for compliance.
Cloud Migration dominates near-term project volume. Big Data Analytics is where expansion concentrates.
End User Industry:
Regulatory intensity varies dramatically, with financial services and government agencies mandating immutable logging while media and education prioritize cost optimization over compliance instrumentation.
- Financial Services:Payment networks, securities exchanges, and banking groups requiring sub-millisecond transaction processing with automated GDPR and SEC compliance enforcement. JPMorgan Chase and Deutsche Bank deploy predictive resource orchestration for real-time risk calculations.
- Telecommunications:5G core network functions and edge computing infrastructure at cell tower aggregation points. Verizon and Vodafone distribute software-defined infrastructure for network slicing and ultra-reliable low-latency services.
- Government Agencies:FedRAMP, ISO 27001, and NIST framework compliance with sovereign data localization requirements.
- Media & Entertainment:Render farms and content delivery infrastructure with burst capacity for production workloads.
- Education Providers:Cost-optimized virtual desktop infrastructure and research computing with grant-funded procurement cycles.
Financial Services dominates premium pricing. Telecommunications is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant silicon for programmable switches concentrates among Taiwan-based foundries, exposing infrastructure timelines to geopolitical friction. Demand clusters in the United States, Germany, India, China, and the United Kingdom where regulatory mandates and hyperscale expansion intersect.
United States
Financial services firms in Northern Virginia and Oregon demand sub-millisecond workload placement for real-time transaction processing. SEC disclosure rules for material incident reporting push JPMorgan Chase and similar institutions toward auditable, software-defined infrastructure with immutable logging. Northern Virginia's hyperscale cloud campuses absorb the bulk of enterprise workload migrations.
Germany
Automotive suppliers and healthcare providers pilot EU AI Act-mandated immutable infrastructure telemetry ahead of mid-decade deadlines. GDPR automated enforcement mandates from data protection authorities require auditable data lineage and automated deletion protocols. Frankfurt hosts dedicated private cloud deployments for PCI-DSS workloads requiring air-gapped environments.
India
RBI and SEBI data localization mandates for domestic financial data storage create greenfield demand among multinational banks. The country's central bank requirements force IT services providers to deploy software-defined private clouds within domestic boundaries. Mumbai and Bangalore financial districts concentrate procurement for Big Data Analytics workloads.
China
MIIT standards on data localization and GB compliance for critical information infrastructure add complexity for multinational deployments. The country's dual carbon goals intersect with software-defined efficiency mandates in state-owned enterprise procurement. Beijing-Tianjin-Hebei corridor anchors domestic cloud provider expansion.
United Kingdom
CFOs in London and the Netherlands prioritize balance-sheet flexibility, accelerating consumption-based infrastructure procurement over capital leases. Managed service providers transfer hardware lifecycle risk from buyers to vendors through operational expenditure models. The City of London's financial institutions drive hybrid cloud adoption for workload portability with immutable audit logging.
Global Software-Defined Data Center Market Competitive Landscape
Concentration sits with virtualization stack incumbents and hyperscale cloud providers that anchor private and hybrid deployments. The vendor base spans three tiers: established platform vendors with decades-long enterprise relationships, cloud-native challengers betting on Kubernetes-centric control planes, and telecommunications operators building edge computing distribution models. Dominant competitive moves include strategic partnerships between hardware OEMs and software orchestration vendors, plus vertical integration into merchant silicon for programmable networking fabrics.
Within the established platform tier, VMware, Inc. and Microsoft Corporation occupy positions as archetypal anchors for regulated industry deployments. Cisco Systems, Inc. sits within the networking-centric specialization vector. These three exemplify how incumbent vendors leverage existing enterprise relationships to defend position against cloud-native challengers, with each representing a distinct strategic archetype: virtualization-native, cloud-extended, and network-originated.
| Leading Market Players |
|---|
| VMware, Inc. |
| Microsoft Corporation |
| Dell Technologies |
| IBM Corporation |
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Development LP |
| Nutanix, Inc. |
| Oracle Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with Taiwan-based foundries lock in merchant silicon access and stabilize compute virtualization licensing costs for hyperscale deployers. These arrangements bind Northern Virginia cloud campuses to fixed-price tiers while exposing mid-market buyers to spot-market volatility in programmable networking hardware.
Pricing Analysis
FedRAMP authorization dictates the pricing tier structure across software-defined infrastructure procurement, separating FedRAMP-authorized platforms from standard enterprise licenses from uncertified alternatives. Price differentiation hinges on compliance certification grade and geographic delivery cost, with air-gapped private cloud deployments in Frankfurt and Singapore commanding substantial premiums. Cost compression in compute virtualization is intensifying because ARM-based alternatives are eroding x86-64 hypervisor margins. Mid-market enterprises without captive technical workforces exhibit highest price sensitivity, while financial services firms in Northern Virginia demonstrate lowest sensitivity due to SEC-mandated audit requirements.
Supply Chain Analysis
Taiwan anchors merchant silicon fabrication for programmable switches while South Korea dominates high-bandwidth memory production for virtualization-optimized servers. The supply chain draws from advanced node wafers, NVMe controller ASICs, and optical transceiver components. Single-source vulnerability concentrates in Taiwan-based foundry capacity, exposing infrastructure timelines to export control friction. Distribution runs through systems integrators with multi-year maintenance contracts for private cloud deployments, shifting toward consumption-based managed service arrangements in the United Kingdom and Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Kubernetes-centric control planes are displacing legacy hypervisor management, forcing interoperability investments around container-native virtualization standards.
For Market Incumbents: Shield installed-base relationships through backward integration into ARM-based server silicon and captive supply of programmable networking ASICs. VMware and Microsoft must accelerate certification investment for FedRAMP and EU AI Act compliance to defend against cloud-native challengers. Channel control through systems integrator exclusivity represents the critical lever for private cloud retention.
For New Entrants and Emerging Players: Anchor in India's greenfield data localization market where RBI and SEBI mandates force multinational banks toward domestic software-defined private cloud deployments. Security orchestration platforms with built-in GDPR automated enforcement offer the most penetrable white space. A GitOps-native go-to-market angle targeting financial services DevOps teams bypasses incumbent professional services dependencies.
For Investors and Strategic Acquirers: Capital is best deployed toward Kubernetes-centric orchestration specialists with established hyperscaler partnerships and zero-trust networking integration. Long-term viability over the next decade rests on platform consolidation around unified policy engines spanning compute, network, and security layers. The signal to watch is hyperscaler capex allocation toward software-defined networking fabrics versus proprietary hardware acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-centric control plane consolidation merges hypervisor and container orchestration for financial services workloads. |
| Strategic Partnership | Systems integrator alliances with FedRAMP-authorized vendors accelerate compliance certification for government agency procurement. |
| Acquisition of Specialist Firm | Security orchestration platforms with EU AI Act-compliant immutable logging command premium positioning in German automotive. |
| Geographic Expansion | Domestic cloud deployments in Mumbai and Bangalore capture RBI-mandated financial data localization requirements. |
| Product Launch | GitOps-native infrastructure-as-code frameworks cut provisioning time from weeks to hours for regulated DevOps teams. |
Research Methodology
A standing panel of cloud infrastructure architects, enterprise IT procurement officers, platform engineers, and systems integrator executives provided ongoing calibration against deployment velocity metrics and compliance certification timelines. Primary interviews with CTOs at financial services firms and telecommunications operators combined with secondary validation from SEC filings, hyperscaler capex disclosures, EMA regulatory submissions, and EU AI Act implementation guidance. Bottom-up triangulation across solution segment adoption curves and top-down reconciliation against aggregate infrastructure spending established market sizing consistency.
Cross-checking against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment model, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating real-time transaction processing requirements, automated policy enforcement mandates, and edge computing distribution expansion. Forecast inputs included hyperscaler facility buildout pipelines and compliance certification backlog data.
Decision-makers should treat outputs as directional under sustained hyperscale cloud campus expansion and stable geopolitical access to Taiwan-based foundry capacity; material deviation would warrant model refresh. Specific risk factors include export control escalation affecting merchant silicon supply, accelerated ARM-based server adoption disrupting x86-64 licensing models, and divergent jurisdictional compliance fragmentation. Recalibration cycles align with material shifts in hyperscaler capex allocation, regulatory enforcement precedent, and container-native virtualization penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
China Data Center Server Market