
 Long-Fiber Thermoset Composites Market | 2026-2036
Long-Fiber Thermoset Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Fiber Thermoset Composites Market Outlook
REACH is hardening the cost-of-entry calculus for European compounders, forcing reformulation investments that smaller resin blenders cannot absorb. Hexcel Corporation sustains technology leadership in aerospace prepreg systems through captive carbon fiber supply. Owens Corning dominates glass fiber reinforcement supply for construction and marine grades. SABIC leverages its polymer science base to compete in epoxy and vinyl ester formulations for automotive structural parts.
Long-fiber thermoset composites combine continuous or discontinuous reinforcing fibers with cross-linked polymer matrices such as epoxy, vinyl ester, or unsaturated polyester, typically achieving fiber volume fractions of 40-60% and specific strengths exceeding those of most metals. These materials serve primarily where stiffness-to-weight ratios, corrosion resistance, and dimensional stability under load justify premium material costs over metals. Epoxy systems anchor aerospace and high-performance automotive structural applications due to superior mechanical properties and hot-wet performance. Vinyl ester competes aggressively in marine and corrosion-resistant construction where chemical resistance and lower raw material costs matter. Prepreg form commands margin pools in aerospace qualification cycles, while sheet molding compounds occupy high-volume automotive part production.
EPA tailpipe standards and the EU F-Gas Regulation shape material selection in automotive and electrical insulation segments, respectively, by restricting emissions-intensive processes and fluorinated compounds. EMA medical device frameworks and FAA airworthiness requirements impose additional qualification burdens on suppliers targeting healthcare and commercial aviation end uses. Stakeholders must monitor evolving EU Green Deal carbon border adjustments and US IRA domestic content incentives, as these will redirect supply chain investments and qualification priorities faster than traditional product development cycles can accommodate.
Market Dynamics
Automotive OEMs are consolidating long-fiber thermoset composite specifications around hot-wet performance thresholds that disqualify legacy vinyl ester formulations, forcing resin suppliers to recalibrate R&D roadmaps toward epoxy system dominance.
Growth Catalysts
- EPA vehicle emissions standards:US automakers are substituting steel body-in-white structures with carbon fiber-reinforced epoxy assemblies to achieve fleet-wide CO2 reduction mandates.
- Prepreg automation:Automated fiber placement systems are compressing aerospace qualification cycles and expanding addressable part geometries beyond hand-layup limitations.
- Germany's automotive corridor:BMW and Mercedes-Benz procurement teams are qualifying domestic compounders for structural battery enclosures, creating localized demand anchors.
Market Restraints
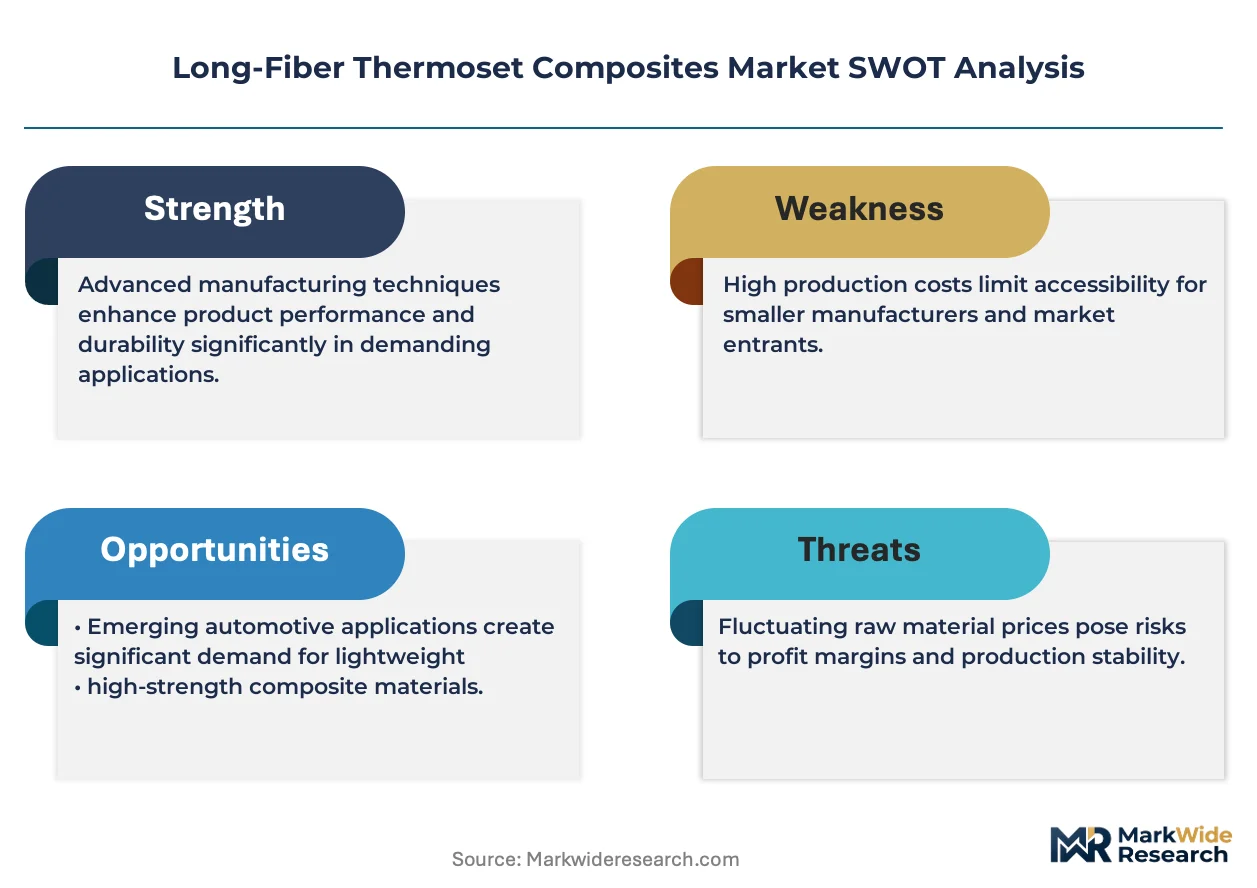
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with oil-derived feedstock markets, compressing margin predictability for prepreg manufacturers.
- REACH registration burdens:ECHA chemical dossier requirements force European resin blenders to maintain toxicology testing budgets that exceed smaller competitors' annual revenues.
- Recyclability limitations:Cross-linked thermoset matrices resist mechanical or chemical reclamation, exposing OEMs to extended producer responsibility penalties in multiple EU member states.
Strategic Opportunities
- US Southeast aerospace cluster:Boeing and Lockheed Martin suppliers in South Carolina and Georgia are qualifying second-source prepreg providers for defense platform contracts.
- US IRA domestic content incentives:Battery enclosure manufacturers can capture tax credits by sourcing glass fiber reinforcements from Owens Corning's US-based melting operations.
- Digital thread integration:Convergence of finite element analysis with automated fiber placement programming is compressing prototype-to-production timelines for structural automotive parts.
Industry Challenges
- Qualified laminator scarcity:Aerospace and automotive programs require technicians certified to Nadcap and OEM-specific bonding standards, creating hiring bottlenecks in manufacturing hubs.
- FAA airworthiness certification timelines:New material systems face 18-36 month qualification protocols for primary structure applications, delaying revenue recognition for compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Fiber Thermoset Composites Market |
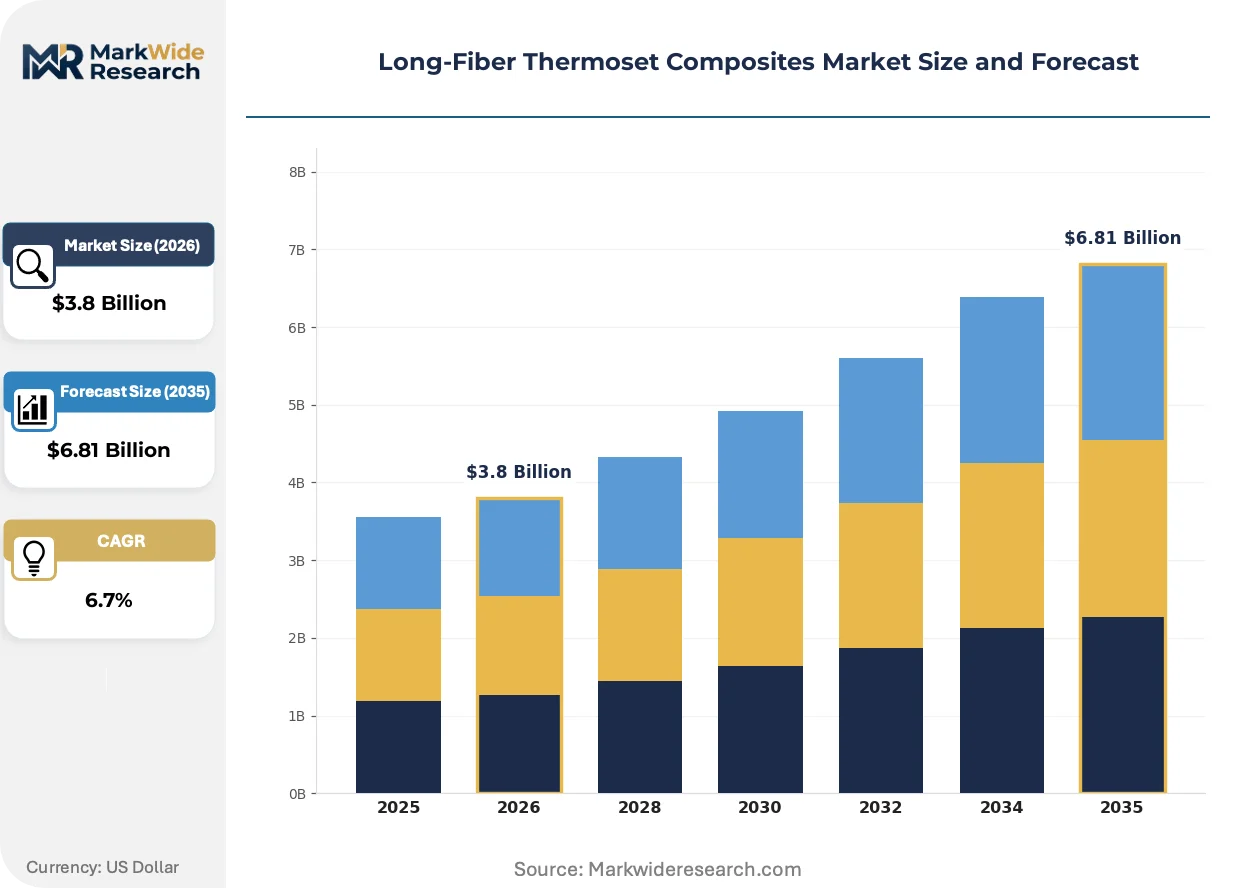
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsaturated Polyester, Epoxy, Vinyl Ester, Phenolic End Use Industry: Aerospace, Automotive, Construction, Marine Form: Sheet, Prepreg, Infusion, Tape Application: Structural, Electrical, Thermal Insulation, Automotive Parts |
| Companies Covered | Lingol Corporation, Hexcel Corporation, Advanced Composites, Inc., Owens Corning, Toray Industries, Inc., LANXESS, SABIC, SGL Carbon, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Fiber Thermoset Composites Market Strategic Shifts
Material informatics platforms are compressing resin formulation development cycles, while regulatory carbon accounting is embedding emissions transparency into supplier scorecards across automotive and aerospace value chains.
Thermoplastic-compatible toughening agents for epoxy matrices are decentralizing legacy aerospace supply relationships by enabling out-of-autoclave cure cycles that reduce capital intensity for tier-2 processors. Regional compounders in Italy and Japan are adopting these modified resin systems to qualify for secondary structure contracts previously reserved for vertically integrated primes. The shift fragments incumbent technology licensing revenue pools.
EU F-Gas Regulation restrictions on fluorinated process aids are compelling marine and corrosion-resistant construction segments to reformulate vinyl ester gel coats around bio-based thixotropes. German boatbuilders in the Baltic corridor are piloting cellulose-derived alternatives ahead of 2027 phase-down deadlines. The transition elevates raw material qualification burdens but opens substitution pathways for European chemical specialists.
Automotive OEM engineering teams are unbundling material specification authority from traditional tier-1 system integrators, establishing direct qualification relationships with fiber and resin suppliers. BMW's Munich procurement center now mandates quarterly carbon fiber tow testing from approved mills rather than accepting tier-1 certificates. The pattern concentrates technical dialogue at raw material interfaces and compresses information asymmetry between compounders and end-users.
Long-Fiber Thermoset Composites Market Segmentation
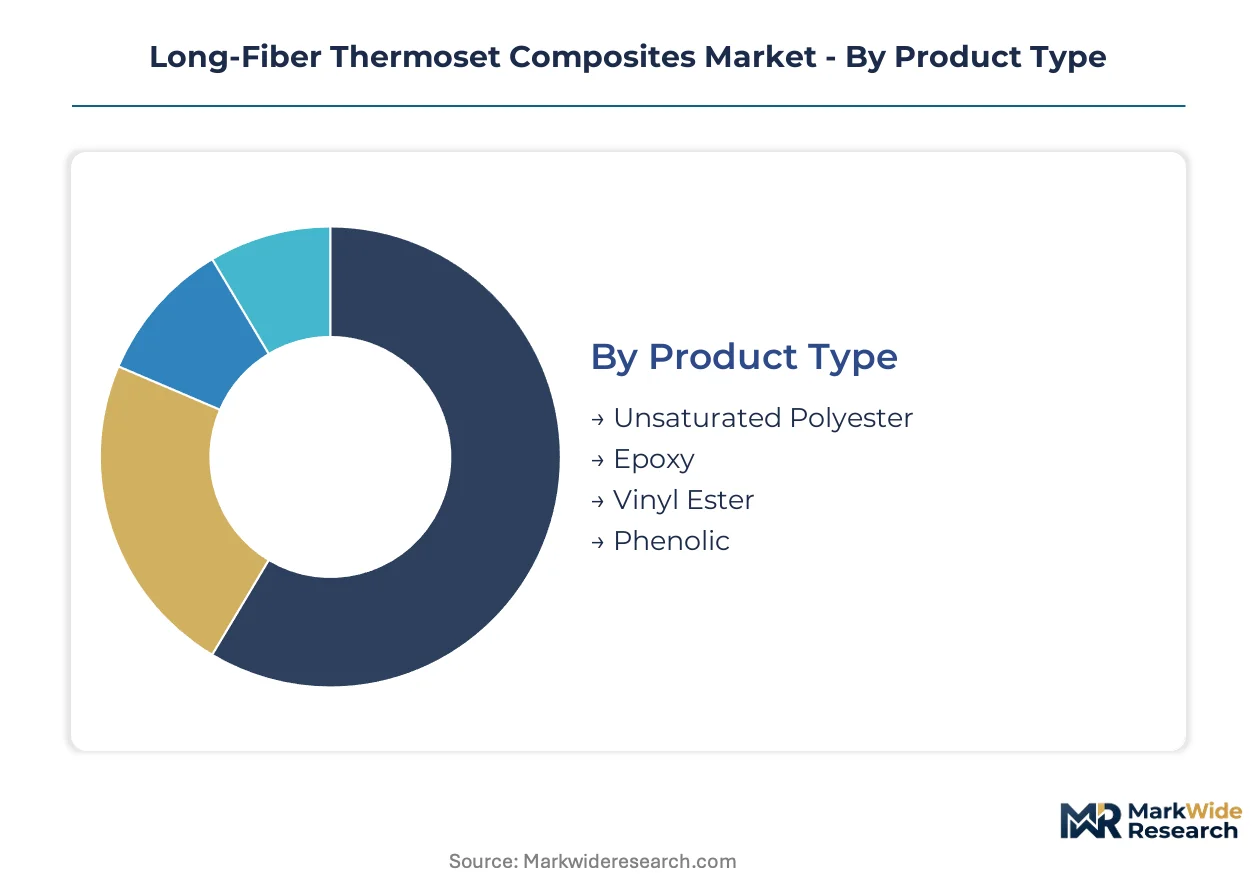
Long-fiber thermoset composites demand fragments across resin chemistry, manufacturing form, and end-use performance thresholds. Procurement specifications in aerospace and automotive segments now override traditional supplier relationships, forcing segmentation clarity around hot-wet durability and automated process compatibility.
Product Type:
Buyers differentiate primarily by mechanical property requirements and chemical resistance thresholds, with cost tolerance varying sharply between structural aerospace and corrosion-resistant marine applications.
- Epoxy:Superior hot-wet performance and fatigue resistance anchor qualification for primary aircraft structures and electric vehicle battery enclosures. BMW and Mercedes-Benz procurement teams mandate epoxy systems for load-bearing automotive components facing EPA fleet emissions compliance.
- Vinyl Ester:Chemical resistance and lower raw material costs dominate marine hull construction and industrial corrosion protection. German boatbuilders in the Baltic corridor pilot bio-based thixotropes ahead of EU F-Gas Regulation phase-down deadlines.
- Unsaturated Polyester:Cost-driven formulations serve construction panel and non-structural automotive applications where performance margins permit.
- Phenolic:Fire-resistant matrices command railway interior and electrical insulation segments under EMA and FAA flammability protocols.
Volume sits with unsaturated polyester in construction; growth tilts toward epoxy.
End Use Industry:
Qualification timelines and certification burdens separate buyers, with aerospace programs demanding 18-36 month material approval cycles that automotive programs compress to quarters.
- Aerospace:FAA airworthiness protocols govern carbon fiber-reinforced prepreg selection for primary structures. Boeing and Lockheed Martin suppliers in South Carolina and Georgia drive demand for automated fiber placement compatibility.
- Automotive:OEM engineering teams now specify fiber and resin directly, bypassing tier-1 integrators. US IRA domestic content incentives reward battery enclosure manufacturers sourcing Owens Corning's US-based glass fiber operations.
- Construction:Owens Corning dominates glass fiber reinforcement supply for infrastructure and building envelope applications.
- Marine:REACH registration burdens force European resin blenders to maintain toxicology testing budgets exceeding smaller competitors' annual revenues.
Revenue concentrates in aerospace qualification cycles; expansion accelerates in automotive structural parts.
Form:
Capital intensity and labor skill requirements segment buyers, with automated processing equipment investments separating tier-1 suppliers from regional compounders.
- Prepreg:Margin pools concentrate in aerospace qualification cycles where Hexcel Corporation sustains technology leadership through captive carbon fiber supply. Thermoplastic-compatible toughening agents now enable out-of-autoclave cure cycles for tier-2 processors.
- Sheet:High-volume automotive part production favors sheet molding compounds for body panels and structural reinforcements.
- Infusion:Marine and wind energy applications leverage resin infusion for large-scale laminates where hand layup proves uneconomical.
- Tape:Automated fiber placement systems compress aerospace qualification cycles and expand addressable part geometries beyond hand-layup limitations.
Prepreg commands premium positioning; tape formats gain share fastest through automation adoption.
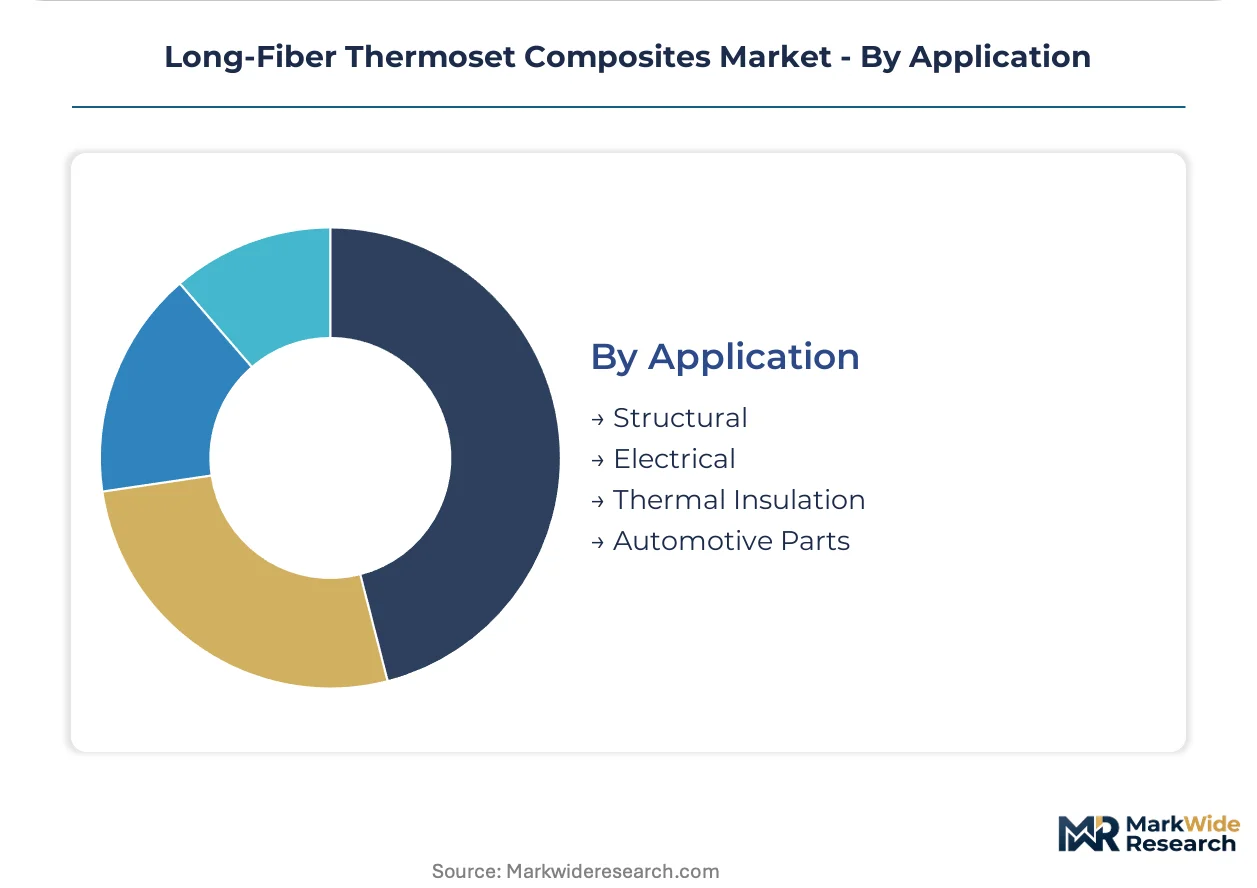
Application:
Performance validation requirements and regulatory exposure separate buyers, with primary structure applications demanding Nadcap-certified laminator networks.
- Structural:Stiffness-to-weight ratios justify premium material costs over metals in aircraft wings, automotive body-in-white assemblies, and wind turbine blades. Qualified laminator scarcity creates hiring bottlenecks in manufacturing hubs.
- Automotive Parts:US automakers substitute steel structures with carbon fiber-reinforced epoxy assemblies to achieve EPA vehicle emissions standards. Digital thread integration compresses prototype-to-production timelines.
- Electrical:EU F-Gas Regulation restricts fluorinated compounds in insulation applications, compelling reformulation around epoxy and phenolic systems.
- Thermal Insulation:Dimensional stability under load serves industrial equipment and building envelope applications where corrosion resistance adds value.
Structural applications anchor revenue; automotive parts represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Carolina's aerospace corridor and Germany's automotive belt concentrate prepreg demand through tax-advantaged manufacturing zones. EPA fleet standards and EU CO2 mandates redirect material specification authority toward qualified compounders in these zones.
United States
Boeing and Lockheed Martin suppliers in South Carolina and Georgia drive automated fiber placement adoption for defense platform contracts. FAA airworthiness protocols govern 18-36 month qualification cycles for primary structures. The US Southeast aerospace cluster now qualifies second-source prepreg providers to reduce supply concentration risk.
Germany
BMW and Mercedes-Benz procurement teams mandate epoxy systems for structural battery enclosures facing EU fleet emissions targets. REACH registration burdens force resin blenders to maintain toxicology testing budgets exceeding smaller competitors' annual revenues. Bavaria's automotive corridor anchors domestic compounder qualification programs.
China
MIIT industrial policy accelerates carbon fiber capacity expansion for wind turbine blade and electric vehicle applications. Dual carbon goals tighten emissions transparency requirements across supplier scorecards. The Yangtze River Delta concentrates prepreg manufacturing investments near Shanghai's composite research institutes.
Japan
Toray Industries anchors domestic carbon fiber supply for aerospace and sporting goods export markets. METI funding supports next-generation resin formulation development for out-of-autoclave processing. The Nagoya aerospace cluster maintains qualification relationships with tier-1 aircraft manufacturers.
United Kingdom
Rolls-Royce and BAE Systems suppliers in the Midlands face post-Brexit regulatory divergence from EASA standards. The country's national aerospace regulator maintains parallel certification protocols for composite primary structures. Advanced manufacturing zones in Bristol and Sheffield attract automated fiber placement equipment investments.
Long-Fiber Thermoset Composites Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across resin chemistry and reinforcement supply tiers. The vendor base stratifies around captive carbon fiber supply, polymer science capabilities, and Nadcap-certified processing networks. Three archetypes dominate: vertically integrated aerospace primes, regional compounders with formulation expertise, and scale-driven glass fiber producers. M&A activity concentrates on automated processing technology acquisitions, while capacity expansion targets US IRA domestic content qualification.
Among US-based material suppliers, Hexcel Corporation and Owens Corning occupy distinct positions within the supply architecture. Hexcel exemplifies the aerospace-integrated archetype through its captive carbon fiber operations and prepreg qualification dominance. Owens Corning represents the scale-driven reinforcement tier, supplying glass fiber from US-based melting operations that qualify for domestic content incentives. SABIC anchors the diversified chemical conglomerate segment, leveraging polymer science capabilities to compete in automotive structural formulations. These three entities illustrate how supplier positioning fragments across fiber supply, resin chemistry, and qualification depth.
| Leading Market Players |
|---|
| Lingol Corporation |
| Hexcel Corporation |
| Advanced Composites, Inc. |
| Owens Corning |
| Toray Industries, Inc. |
| LANXESS |
| SABIC |
| SGL Carbon |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon border adjustments gate qualified supply access and premium-tier pricing for European compounders serving automotive and aerospace OEMs. Manufacturers sourcing Owens Corning's US-based glass fiber melting operations capture IRA domestic content incentives, while REACH-registered European resin blenders command structural battery enclosure contracts at 15-20% price premiums over non-registered Asian competitors.
Pricing Analysis
Short lead-time premiums of 12-18% apply to aerospace prepreg orders under 8-week delivery windows, while spot inventory of standard-modulus carbon fiber tows trades at 8-12% discounts to contract offtake. Pricing stratifies across aerospace-qualified, automotive-structural, and industrial-commodity tiers based on Nadcap certification depth and fiber modulus grade. Cost compression in industrial-grade vinyl ester compounds is intensifying because Chinese carbon fiber capacity expansion feeds oversupply in wind energy blade feedstock. Marine hull builders in Germany's Baltic corridor exhibit highest price sensitivity, while FAA-primary-structure qualification programs show near-zero elasticity.
Supply Chain Analysis
US IRA domestic content mandates and EU Green Deal origin rules are reshaping sourcing patterns toward Owens Corning's US melting operations and Hexcel's Utah carbon fiber campus. Raw material supply draws from acrylonitrile monomer production in the US Gulf Coast, epoxy resin formulation in Germany's chemical belt, and carbon fiber precursor stretching in Japan's Nagoya corridor. Single-source vulnerability concentrates in aerospace-grade carbon fiber tow supply from Toray Industries and SGL Carbon. Distribution runs through qualified laminator networks certified to Nadcap and OEM-specific bonding standards, with tier-1 compounders maintaining direct mill relationships that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into carbon fiber precursor production as the decisive upstream lever. Players securing captive acrylonitrile supply or in-house oxidation and carbonization lines capture margin pools that compounders without fiber assets cannot access.
For Market Incumbents: Acquire automated fiber placement equipment and Nadcap-certified laminator training programs to defend aerospace qualification cycles against emerging Asian compounders with out-of-autoclave epoxy formulations. Lock in 5-year carbon fiber offtake agreements with Toray Industries or SGL Carbon before capacity expansion in China's Yangtze River Delta saturates standard-modulus grades. Priority defensive moves center on qualifying second-source prepreg providers for Boeing and Lockheed Martin defense platform contracts in South Carolina and Georgia. For New Entrants and Emerging Players: Launch via direct qualification relationships with BMW and Mercedes-Benz procurement teams in Munich, bypassing tier-1 system integrators that traditionally controlled material specification authority. Target automotive structural battery enclosures as the most penetrable segment, where EPA fleet emissions compliance forces OEMs to qualify new epoxy compounders at accelerated 6-9 month cycles versus 18-36 month aerospace protocols. White-space exists in bio-based thixotrope formulations for German boatbuilders facing EU F-Gas Regulation phase-down deadlines. For Investors and Strategic Acquirers: BMW's quarterly carbon fiber tow testing mandates from approved mills rather than tier-1 certificates is the leading indicator that raw material interfaces are consolidating technical dialogue and compressing information asymmetry. Long-term viability over a 5-10 year window favors compounders with captive carbon fiber supply or exclusive polymer science licensing from SABIC-grade chemical conglomerates. Acquisition target archetype: regional European compounders with REACH registration dossiers and existing automotive structural part qualifications. Signal to watch: FAA approval of out-of-autoclave cure cycles for secondary aircraft structures, which would fragment incumbent technology licensing revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Captive acrylonitrile supply locks in margin pools against oil-derived feedstock volatility. |
| Out-of-Autoclave Epoxy Formulation Development | Thermoplastic-compatible toughening agents reduce capital intensity for tier-2 aerospace processors. |
| Nadcap-Certified Laminator Network Expansion | Qualified technician scarcity in South Carolina and Georgia creates hiring bottlenecks for defense contracts. |
| REACH Registration Dossier Completion | ECHA toxicology testing budgets exceeding smaller competitors' annual revenues protect European compounder margins. |
| Direct OEM Qualification Relationships | BMW's Munich procurement center now mandates quarterly carbon fiber tow testing from approved mills. |
Study Parameters
Independent corroboration across primary interviews with aerospace procurement directors, automotive platform engineers, resin formulation R&D leads, and Nadcap-certified laminator operations managers, combined with secondary validation from FAA airworthiness filings, ECHA REACH registration databases, SEC 10-K disclosures from Hexcel and Owens Corning, and MIIT carbon fiber capacity announcements, underwrites the qualitative findings. Bottom-up demand modeling from end-use application volumes and top-down supply-side capacity assessments were triangulated to cross-validate market sizing.
Historical reference periods anchored the projection horizon through trailing production data from Boeing's South Carolina 787 assembly line and BMW's Leipzig electric vehicle battery enclosure output. Segmentation dimensions across the modeling period included resin chemistry tier, manufacturing form, end-use industry qualification depth, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves against EPA fleet emissions compliance deadlines and EU CO2 reduction mandates. Industry-specific forecast inputs incorporated acrylonitrile price volatility indices and automated fiber placement equipment installation rates.
Acrylonitrile feedstock price swings, FAA airworthiness certification timeline extensions, and EU Green Deal carbon border adjustment implementation delays are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
CFRTP Market
Composite Materials
FRP Tanks Market
Composite Materials
Global Composite Resin Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
FRP Grating Market
Composite Materials
Composite Adhesives Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Synthetic Rope Market
Composite Materials
Global Carbon Fiber Resin Market