
 Global Composite Resin Market | 2026-2036
Global Composite Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Composite Resin Market Analysis
The capital-intensity divergence between integrated petrochemical conglomerates and specialized resin compounders is collapsing as feedstock volatility compresses margin buffers across both tiers. Huntsman Corporation leverages its upstream amine and anhydride chemistry to sustain captive epoxy hardener supply chains. Toray Industries anchors premium aerospace prepreg demand through carbon fiber-resin co-development programs. Owens Corning competes in glass-reinforced polyester systems for construction and marine applications, where scale economics dominate procurement decisions.
Composite resin denotes thermoset or thermoplastic polymer matrices—epoxy, polyester, vinyl ester, or phenolic—formulated with curing agents to impregnate or bond reinforcement fibers, typically achieving tensile moduli from 2.5 to 4.5 GPa in cured laminates. These matrices transfer load between fibers, protect reinforcements from environmental degradation, and enable net-shape manufacturing through resin transfer molding, filament winding, or autoclave cure cycles. Epoxy formulations command the dominant value share in aerospace and wind turbine blade applications, where fatigue resistance and fiber adhesion justify premium positioning. Polyester resins retain volume leadership in construction and marine sectors, where cost sensitivity and ambient-temperature cure requirements favor unsaturated formulations. Phenolic systems occupy a specialized niche in rail and mass transit interiors, where flame-smoke-toxicity regulations drive demand for low-fire-hazard matrices despite processing complexity and brittleness trade-offs.
The EPA enforces National Emission Standards for Hazardous Air Pollutants on open molding operations, compelling polyester and vinyl ester processors to adopt closed-mold techniques or vapor recovery systems. REACH registration requirements in Europe restrict certain styrene-based formulations, redirecting formulation investment toward low-V vinyl ester and bio-derived epoxy alternatives. China's Ministry of Ecology and Environment implements dual carbon goals that tighten energy intensity benchmarks for resin synthesis plants. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated release agents face scrutiny under emerging chemical management frameworks across multiple jurisdictions.
Market Dynamics
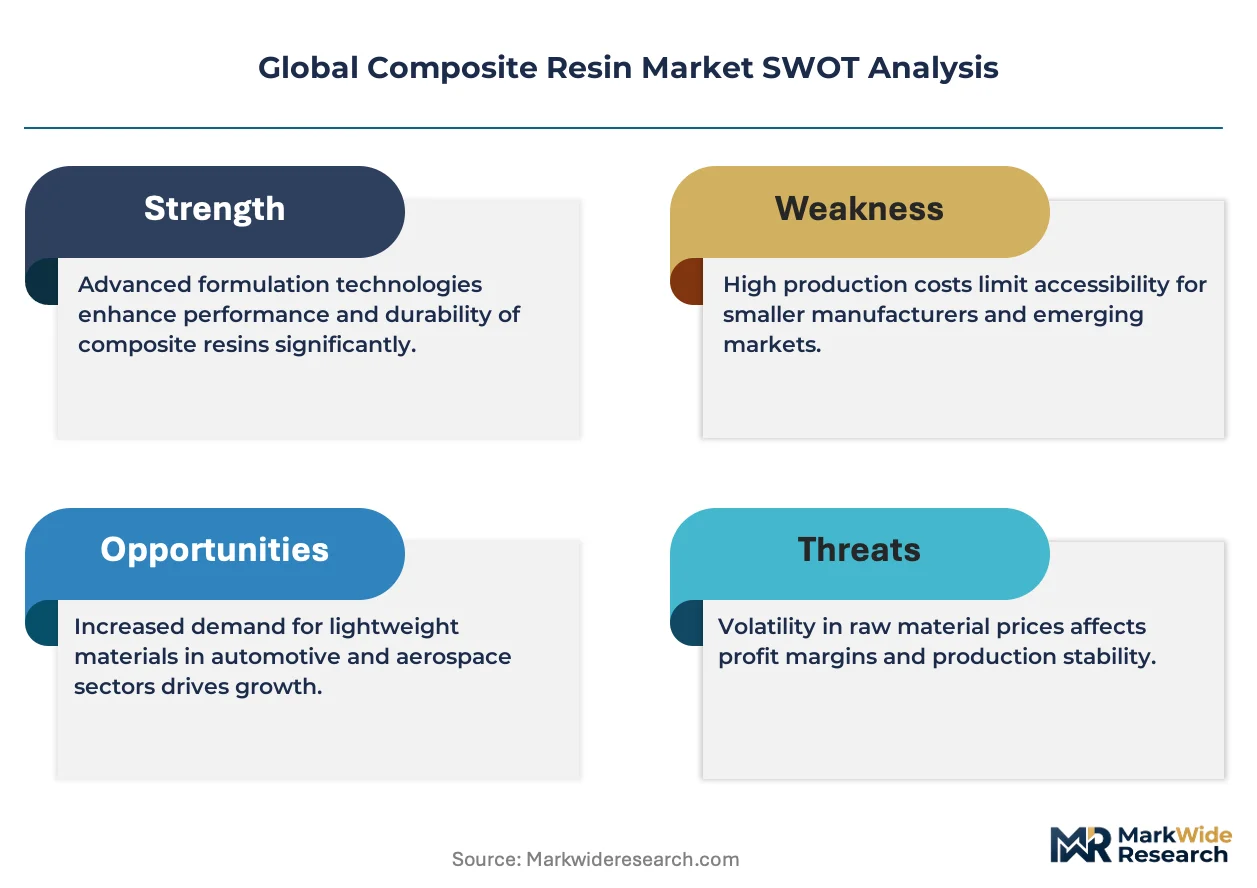
Feedstock volatility and regulatory tightening on styrene emissions are compressing margin buffers across polyester and vinyl ester supply chains, forcing compounders to reconfigure formulation chemistry and captive raw material positions.
Growth Catalysts
- Wind blade scaling:China's wind energy corridor is scaling domestic prepreg consumption as blade manufacturers expand rotor diameters beyond 100 meters, demanding higher-modulus epoxy systems.
- REACH compliance redirection:ECHA restrictions on styrene-based formulations in Europe are redirecting R&D investment toward low-V vinyl ester and bio-derived epoxy alternatives with equivalent mechanical performance.
- Aerospace lightweighting mandates:FAA certification pathways for thermoset primary structures are accelerating thermoplastic resin adoption in next-generation narrowbody programs.
Market Restraints
- Bisphenol-A feedstock concentration:Epoxy resin synthesis depends on concentrated petrochemical supply from Gulf Coast crackers, exposing formulators to ethylene and propylene price swings.
- Autoclave cure bottlenecks:Aerospace prepreg processing requires capital-intensive autoclave infrastructure with 8-12 hour cure cycles, constraining throughput for tier-two suppliers.
- Fluorinated release agent phaseout:Emerging PFAS restrictions under EPA and state-level frameworks are eliminating conventional mold release chemistries before qualified alternatives achieve scale.
Strategic Opportunities
- India infrastructure buildout:National highway and rail corridor expansion is creating addressable demand for glass-reinforced polyester composites in bridge decking and station construction.
- Out-of-autoclave processing convergence:Oven-curable epoxy prepregs combined with resin transfer molding are opening aerospace-qualified material supply to non-autoclave fabricators.
- EU Green Deal chemistry incentives:Horizon Europe funding streams and carbon border adjustment mechanisms are favoring bio-epoxy and recycled carbon fiber resin systems with verified lifecycle credentials.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in thermoset kinetics and fiber-matrix interface engineering is concentrated among retiring technical staff at legacy resin houses.
- Multi-jurisdiction certification timelines:Simultaneous FAA, EASA, and CAAC qualification for aerospace prepreg grades extends product launch cycles by 18-36 months.
- Legacy polyester inventory integration:Marine and construction fabricators maintain substantial unsaturated polyester stockpiles, creating resistance to vinyl ester conversion despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Composite Resin Market |
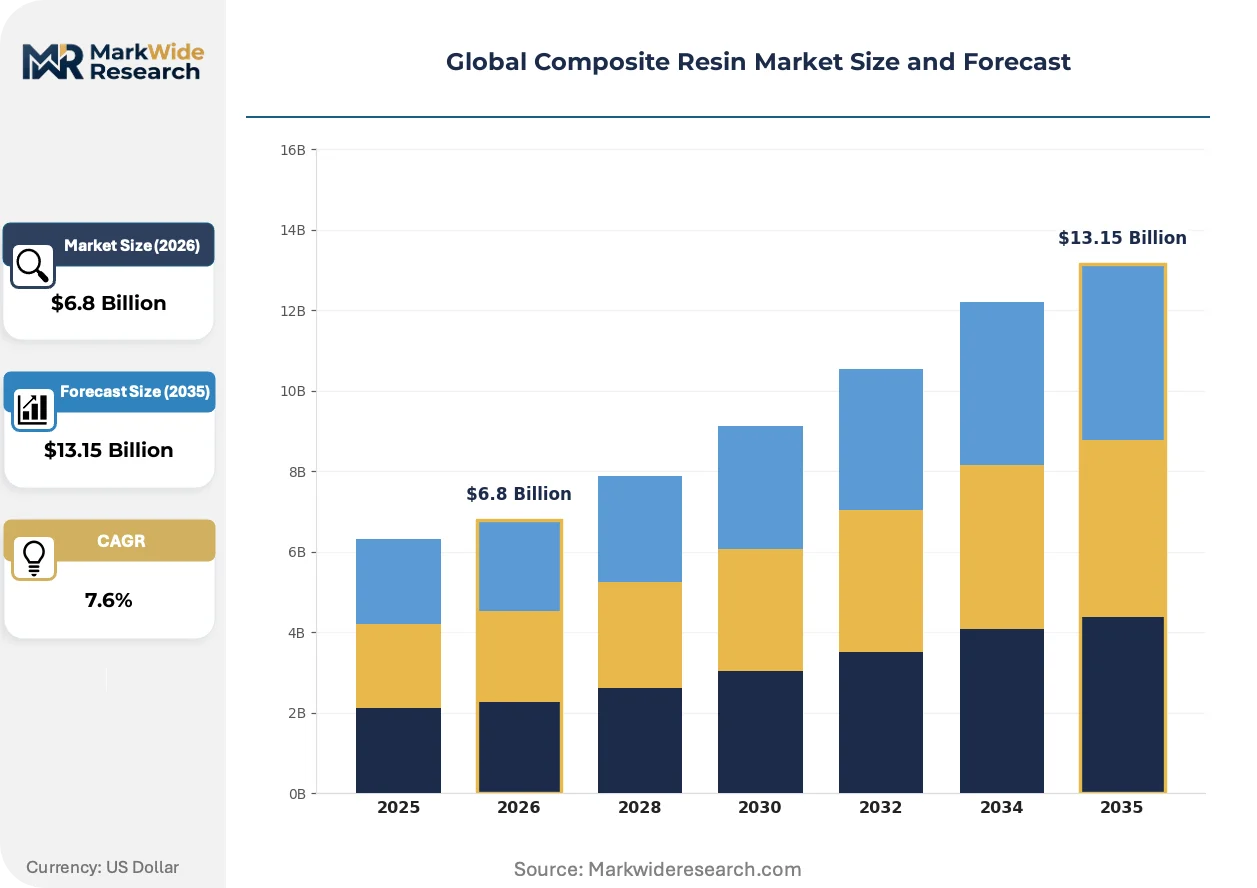
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Vinyl Ester, Phenolic Application: Aerospace, Automotive, Construction, Marine End User: OEMs, Tier-1 Suppliers, Contractors, Manufacturers Form: Prepregs, SMC, BMC, Laminates |
| Companies Covered | Toray Industries, Owens Corning, Hexcel Corporation, Huntsman Corporation, Teijin Limited, Mitsubishi Chemical Group Corporation, Solvay, Hexion Inc, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Composite Resin Market Emerging Trajectories
Formulation chemistry, regulatory chemistry standards, and manufacturing process architectures are diverging simultaneously, creating multiple parallel innovation tracks without dominant design consolidation.
Thermoplastic resin systems are fragmenting the aerospace secondary structures market. PEEK and PEKK matrices offer weldability and recyclability advantages over thermosets. Boeing and Airbus tier-one suppliers are qualifying these materials for interior panels and ducting. The technology is fragmenting what was a consolidated epoxy prepreg supply base into specialty polymer compounders with distinct processing equipment requirements.
EPA National Emission Standards for Hazardous Air Pollutants are compelling open-molding operations to adopt closed-mold resin transfer or light RTM techniques. Polyester and vinyl ester processors in marine and construction sectors face capital expenditure thresholds for vapor recovery infrastructure. Smaller fabricators in Florida and Gulf Coast states are consolidating or exiting rather than retrofitting.
Certification-driven procurement is compressing supplier qualification cycles. Wind turbine OEMs are unbundling blade material specifications from integrated blade manufacturing contracts. Vestas and Siemens Gamesa are establishing approved resin supplier lists with direct purchasing relationships. This pattern is most visible in Denmark and northern Germany, where blade engineering centers maintain proximity to carbon fiber and resin R&D facilities.
Global Composite Resin Market Segmentation
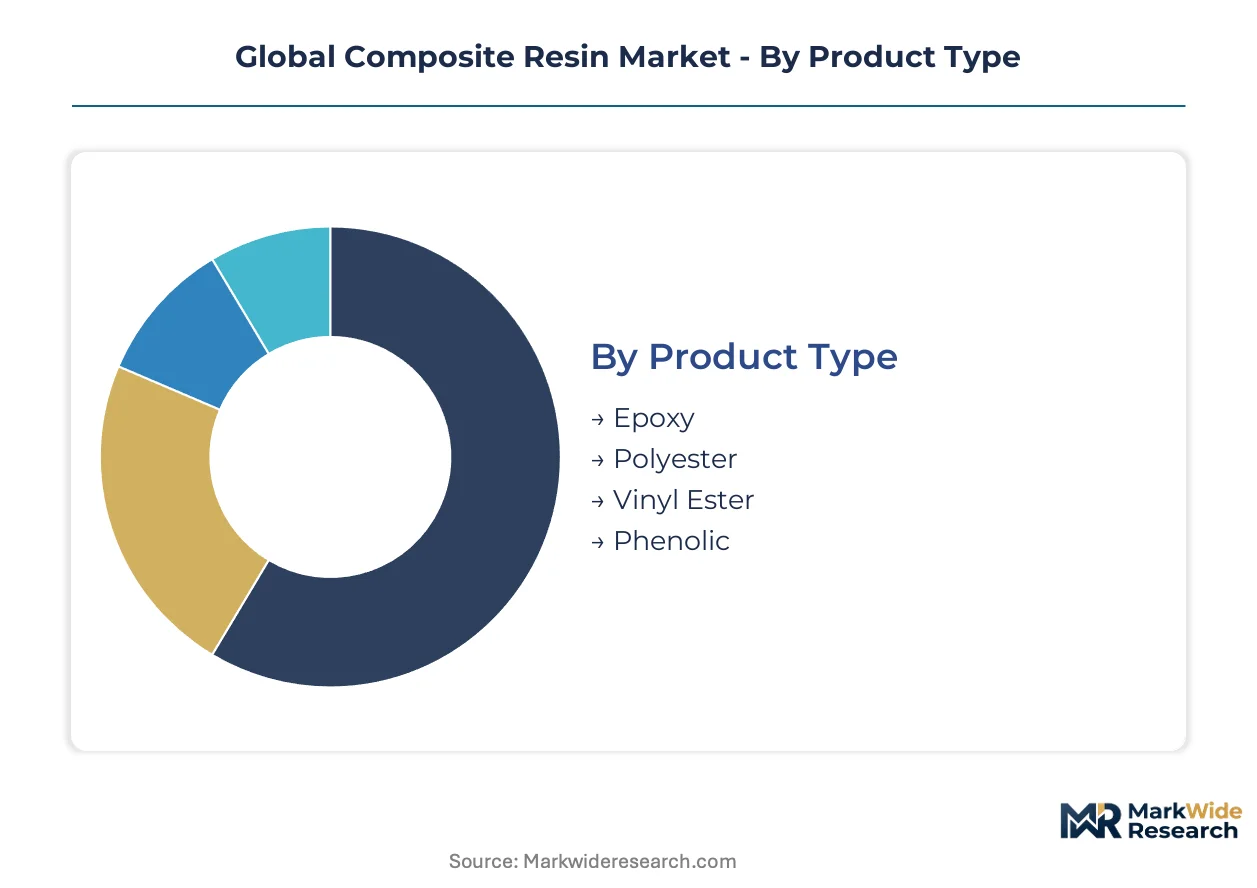
Composite resin segmentation reveals how formulation chemistry, processing form, and end-use certification requirements create distinct competitive arenas with divergent margin profiles and technical barriers. Understanding these boundaries clarifies where substitution threats concentrate and where captive demand insulates pricing power.
Product Type:
Polyester formulations face the most acute substitution pressure as bio-based alternatives and vinyl ester upgrades erode their cost advantage in open-molding applications.
- Epoxy:Thermoset matrices built from bisphenol-A and epichlorohydrin precursors achieve superior fiber adhesion and fatigue resistance. Demand concentrates in wind turbine blade roots and aerospace primary structures, where Siemens Gamesa and Boeing tier-one suppliers mandate certified prepreg systems despite premium positioning.
- Polyester:Unsaturated formulations using maleic anhydride and styrene monomers enable ambient-temperature cure for large marine hulls and construction panels. China's construction boom and Florida boat builders sustain volume, though EPA NESHAP compliance costs are forcing smaller fabricators toward closed-mold conversion or exit.
- Vinyl Ester:Hybrid chemistry combining epoxy backbone with polyester cure kinetics delivers corrosion resistance for chemical storage tanks and offshore platforms.
- Phenolic:Formaldehyde-based thermosets with low smoke-toxicity profiles serve rail interior applications under EN 45545 fire safety mandates.
Polyester retains volume leadership; epoxy holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-driven aerospace procurement from price-sensitive construction bidding.
- Aerospace:Primary and secondary structures require FAA-certified prepregs with documented mechanical property databases. Boeing and Airbus qualification protocols extend supplier development cycles, concentrating demand among resin houses with captive carbon fiber partnerships.
- Automotive:Sheet molding compound and structural reaction injection molding enable high-volume Class A body panels and underhood components. BMW and Porsche motorsport programs drive carbon fiber-epoxy adoption, though mass-market electric vehicle platforms favor glass-reinforced thermoplastics for cost scalability.
- Construction:Glass-reinforced polyester dominates bridge decking, rebar, and architectural cladding where India infrastructure buildout and US highway rehabilitation create project-based demand.
- Marine:Recreational boat hulls and superyacht components rely on hand-layup polyester, though larger vessels shift to vinyl ester for blister resistance.
Construction commands the largest unit volume; aerospace delivers the highest value per kilogram.
End User:
Procurement centralization varies sharply across tiers, with OEMs consolidating resin purchasing while fragmented contractors resist specification changes.
- OEMs:Vestas, Siemens Gamesa, and Boeing direct material qualification and establish approved supplier lists, unbundling resin procurement from integrated manufacturing contracts.
- Tier-1 Suppliers:GKN Aerospace and Spirit AeroSystems manage prepreg inventory and autoclave capacity, intermediating between resin formulators and airframe assembly.
- Contractors:Marine and construction fabricators maintain legacy polyester stockpiles, creating inertia against vinyl ester conversion despite performance advantages.
- Manufacturers:Wind blade producers in China's Jiangsu and Guangdong provinces scale domestic prepreg consumption as rotor diameters exceed 100 meters.
OEMs drive specification change; contractors represent the most price-elastic demand pool.
Form:
Processing technology maturity determines capital barriers and geographic distribution of fabrication capacity.
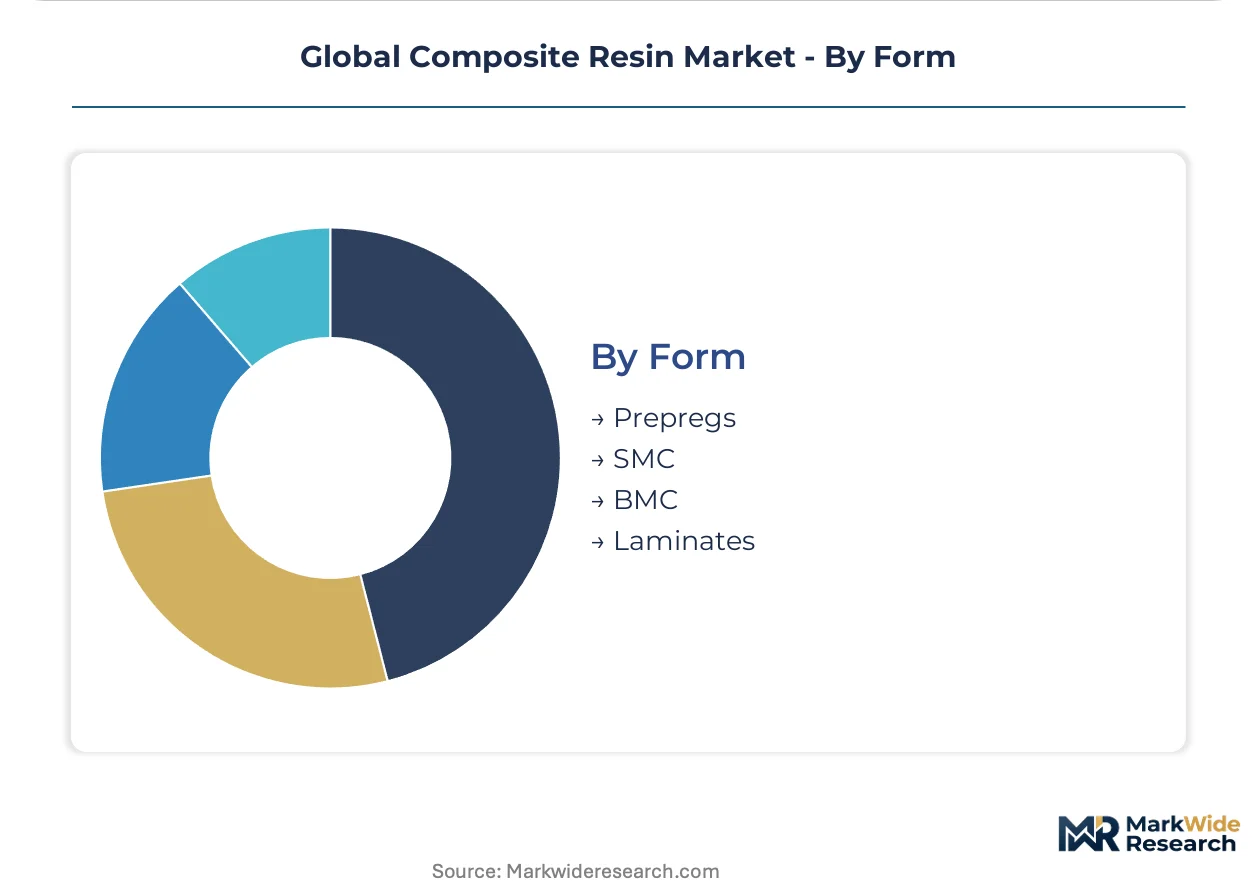
- Prepregs:Fiber-resin combinations with controlled tack and drape properties require cold storage and autoclave cure cycles. Aerospace qualification protocols limit qualified suppliers, though out-of-autoclave epoxy variants are opening non-autoclave fabrication.
- SMC:Sheet molding compounds with chopped glass and thickened polyester enable compression molding of automotive body panels at 60-second cycle times.
- BMC:Bulk molding compounds suit intricate electrical housings and appliance components where flow characteristics and flame retardancy converge.
- Laminates:Hand-layup and filament-wound constructions serve marine, corrosion, and infrastructure applications with minimal tooling investment.
Laminates retain broadest geographic penetration; prepregs concentrate value in certified supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes composite resins primarily for wind energy infrastructure, while the United States directs volumes toward aerospace and defense applications, and Germany anchors European demand through automotive and industrial equipment manufacturing.
China
Wind turbine blade manufacturers in Jiangsu and Guangdong provinces scale domestic prepreg consumption as rotor diameters exceed 100 meters. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy intensity benchmarks for resin synthesis plants. Tianjin and Shanghai host integrated carbon fiber-resin R&D clusters where blade engineering centers maintain proximity to material suppliers.
United States
Boeing tier-one suppliers and defense contractors drive specification-grade epoxy demand for primary airframe structures and unmanned aerial systems. The EPA enforces National Emission Standards for Hazardous Air Pollutants on open molding operations, compelling polyester processors toward closed-mold conversion. Gulf Coast petrochemical corridors supply concentrated bisphenol-A and epichlorohydrin feedstock, exposing formulators to ethylene price volatility.
Germany
Vestas and Siemens Gamesa engineering centers in Hamburg and Munich establish approved resin supplier lists with direct purchasing relationships, unbundling procurement from integrated blade contracts. REACH registration requirements restrict certain styrene-based formulations, redirecting investment toward low-V vinyl ester alternatives. Bavaria and North Rhine-Westphalia concentrate automotive composites development for BMW and Porsche motorsport programs.
India
National highway and rail corridor expansion creates project-based demand for glass-reinforced polyester in bridge decking and station construction. The Bureau of Indian Standards implements construction material certification protocols that favor qualified laminates over unregulated imports. Gujarat and Maharashtra host marine fabricators scaling hand-layup polyester production for domestic boat builders.
Japan
Teijin and Toray anchor premium aerospace prepreg supply through carbon fiber-resin co-development programs serving Boeing and Airbus tier-one suppliers. METI funding streams support next-generation thermoplastic matrix qualification for interior panels and ducting. Nagoya and Osaka industrial corridors concentrate autoclave capacity for commercial aircraft secondary structures.
Global Composite Resin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with petrochemical conglomerates controlling upstream amine and anhydride chemistry while specialized compounders focus on formulation kinetics and fiber-matrix interface engineering. Three archetypes dominate: upstream-integrated resin houses with captive hardener supply, carbon fiber-resin co-developers serving aerospace qualification protocols, and scale-driven glass-reinforced polyester suppliers competing on construction and marine volume. Competitive moves concentrate on backward integration into feedstock positions and strategic partnerships with wind turbine OEMs to secure approved supplier status.
Among integrated chemical conglomerates, Huntsman Corporation exemplifies the upstream-captive archetype through in-house production of epoxy hardener systems. Toray Industries occupies a position within the carbon fiber-resin co-development tier, anchoring premium aerospace prepreg demand through integrated material qualification pathways. Owens Corning represents scale-driven competition in glass-reinforced polyester systems, where procurement decisions hinge on volume economics and construction sector relationships.
| Leading Market Players |
|---|
| Toray Industries |
| Owens Corning |
| Hexcel Corporation |
| Huntsman Corporation |
| Teijin Limited |
| Mitsubishi Chemical Group Corporation |
| Solvay |
| Hexion Inc |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Sixty-day epoxy hardener inventory buffers at Gulf Coast formulators compress when ethylene cracker outages strike, concentrating pricing power among integrated producers with captive amine supply while forcing compounders toward long-term offtake contracts or spot market exposure. This lead-time vulnerability shapes how procurement teams structure resin supply agreements across aerospace and wind energy tiers.
Pricing Analysis
Long-term offtake agreements dominate aerospace prepreg procurement, where Boeing and Airbus tier-one suppliers lock in multi-year epoxy contracts to secure autoclave-qualified material streams. Price differentiation rests on certification grade—FAA-primary versus secondary structure tiers—and volume scale, with rotor blade manufacturers above 100 meters commanding standard-tier pricing while smaller marine fabricators absorb premium spot rates. Cost compression in polyester laminates is intensifying because EPA NESHAP compliance forces open-molding converters toward capital-intensive closed-mold retrofit or exit. Marine contractors represent the most price-elastic demand pool, resisting vinyl ester conversion despite performance advantages, while aerospace OEMs exhibit least sensitivity given qualification lock-in.
Supply Chain Analysis
China, the United States, and Germany anchor global composite resin production, with Jiangsu and Guangdong provinces scaling domestic prepreg consumption for wind blade manufacturing while Gulf Coast petrochemical corridors feed bisphenol-A and epichlorohydrin into epoxy synthesis chains. Raw material dependencies rest on concentrated ethylene and propylene supply from crackers, styrene monomer for polyester cure kinetics, and amine hardeners for epoxy cross-linking. Single-source vulnerability concentrates in carbon fiber-resin co-development programs, where Toray and Teijin captive partnerships limit qualified supplier alternatives for aerospace primary structures. Distribution runs through approved supplier lists established by Vestas and Siemens Gamesa, unbundling resin procurement from integrated blade manufacturing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across formulation chemistry, processing form, and end-use certification creates multiple parallel competitive arenas, with out-of-autoclave processing and bio-derived epoxy alternatives opening niches where integrated petrochemical conglomerates lack agility.
For Market Incumbents: Secure captive hardener supply positions through backward integration into amine and anhydride chemistry, mirroring Huntsman Corporation's upstream model, while accelerating certification investment for low-V vinyl ester formulations to preempt REACH-driven substitution. Capacity addition in China's Jiangsu province captures wind blade scaling demand before domestic compounders consolidate approved supplier status. Channel control through direct OEM relationships insulates margin buffers against spot feedstock volatility.
For New Entrants and Emerging Players: Out-of-autoclave epoxy formulation services represent the most penetrable white space, as incumbent prepreg suppliers prioritize autoclave-qualified aerospace tiers and under-serve non-autoclave fabricators seeking oven-curable alternatives. India's glass-reinforced polyester infrastructure buildout offers geographic entry with lower certification barriers than aerospace or wind energy segments. A technical service-led go-to-market model—embedding formulation chemists at contractor sites—overcomes legacy polyester inventory inertia.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because feedstock volatility and regulatory tightening are collapsing margin buffers across specialist compounders, creating distressed acquisition targets with qualified customer relationships and formulation IP. Mid-cap resin houses with wind energy approved supplier status and bio-epoxy R&D pipelines represent priority acquisition archetypes. The signal to watch is unbundling acceleration—when Siemens Gamesa or Vestas expands direct resin purchasing relationships beyond current approved lists, qualifying timelines compress and target valuations shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardener Chemistry | Huntsman Corporation's captive amine supply insulates margin buffers against ethylene price swings. |
| Out-of-Autoclave Prepreg Qualification | Oven-curable epoxy variants open aerospace material supply to non-autoclave fabricators without capital-intensive infrastructure. |
| Bio-Derived Epoxy R&D Investment | Horizon Europe funding streams favor resin systems with verified lifecycle credentials under EU Green Deal chemistry incentives. |
| Approved Supplier List Expansion | Vestas and Siemens Gamesa unbundling blade material specifications creates direct purchasing relationships outside integrated contracts. |
| Closed-Mold Processing Conversion | EPA NESHAP enforcement compels polyester processors toward vapor recovery infrastructure or market exit. |
Methodological Framework
A spread of perspectives from resin formulation chemists, wind blade procurement leads at OEMs, aerospace tier-one supplier material engineers, and marine fabricator operations managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and REACH registration databases. Bottom-up resin consumption estimates by end-use application triangulated against top-down petrochemical feedstock demand models.
Segmentation dimensions modeled include formulation chemistry tier, processing form, end-use certification requirement, and regional production hub concentration across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating wind turbine blade scaling parameters, aerospace build rate assumptions, and infrastructure investment cycles. Industry-specific forecast inputs encompassed dual carbon goal implementation timelines from China's Ministry of Ecology and Environment and FAA certification pathway evolution for thermoplastic primary structures.
Underlying assumptions cover sustained wind energy capacity expansion, REACH compliance redirection toward low-V alternatives, and epoxy feedstock supply continuity from Gulf Coast crackers, with deviation risk concentrated in ethylene price volatility, PFAS restriction acceleration, and multi-jurisdiction qualification timeline extensions. Recalibration cycles align with material shifts in regulatory enforcement intensity and OEM procurement unbundling patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Composite Materials Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
CFRTP Market
Composite Materials
Tow Prepreg Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Composite Cans Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
PCR Laminates Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Ultra-Lightweight Cement Composites Market