
 Long-Duration Energy Storage Market | 2026-2036
Long-Duration Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Duration Energy Storage Market Insights
Utility procurement is realigning toward eight-to-one-hundred-hour discharge systems as grid operators confront renewable curtailment and seasonal mismatch. Form Energy leverages iron-air chemistry to target hundred-hour economics at utility scale. Energy Vault sustains gravity-based mechanical storage deployments with composite block engineering. ESS Tech specializes in aqueous iron flow batteries for commercial and industrial microgrids.
Long-duration energy storage encompasses electrochemical, mechanical, and thermal systems engineered to discharge electricity over durations exceeding four hours, with round-trip efficiencies ranging from fifty to eighty percent depending on technology pathway. These systems buffer intermittency from wind and solar assets, defer transmission upgrades, and provide capacity value during extended weather events. Flow batteries dominate installed capacity in grid management applications due to scalable power-to-energy ratios and minimal capacity degradation. Compressed air energy storage occupies a narrower niche where underground cavern geology permits, though above-ground variants are gaining traction. Thermal storage competes in renewable integration by capturing excess solar generation as industrial process heat.
The Federal Energy Regulatory Commission in the United States shapes market access through Order 841, which mandates wholesale market participation for storage resources, while the EU Green Deal and F-Gas Regulation constrain fluorinated working fluids in certain thermal and compressed air designs. China's dual carbon goals and GB standards for electrochemical safety create parallel compliance layers for equipment imports. Stakeholders must monitor how capacity market redesigns in multiple jurisdictions value duration-specific attributes versus energy-only arbitrage.
Market Dynamics
Utility procurement is pivoting toward multi-day discharge systems as grid operators confront renewable curtailment and seasonal mismatch. This structural shift compresses project timelines and rewards technologies with extended duration economics.
Growth Catalysts
- Clean Energy Mandates:California and New York state-level mandates accelerate project pipelines by requiring renewable-plus-storage configurations. These frameworks create guaranteed offtake channels.
- Iron-Air Chemistry:Aqueous iron flow batteries achieve hundred-hour discharge at utility scale without rare earth dependencies. This pathway sidesteps lithium-ion supply constraints.
- FERC Order 841:The United States wholesale market participation mandate enables storage resources to bid into capacity, energy, and ancillary service markets simultaneously.
Market Restraints
- Underground Geology Constraints:Compressed air energy storage requires specific salt dome or aquifer formations, limiting deployable sites to Texas, Germany, and select Australian regions.
- Round-Trip Efficiency Gap:Mechanical and thermal systems achieve fifty to seventy percent efficiency versus lithium-ion's ninety percent, eroding arbitrage margins in energy-only markets.
- EU F-Gas Regulation:Fluorinated working fluid restrictions constrain certain thermal storage and compressed air designs, forcing refrigerant substitutions that extend engineering cycles.
Strategic Opportunities
- Industrial Process Heat:Thermal storage capturing excess solar generation for cement and chemical plants opens a gigawatt-scale application underserved by electrochemical alternatives.
- Transmission Deferral:Siting long-duration systems at renewable generation clusters enables utilities to defer multi-billion-dollar transmission upgrades in congested corridors.
- Australia's NEM Reforms:The National Electricity Market capacity mechanism redesign values duration-specific attributes, creating premium revenue streams for eight-plus-hour systems.
Industry Challenges
- Interconnection Queues:Grid connection studies for novel storage technologies face eighteen-to-thirty-six-month backlogs at ISOs and RTOs, delaying commercial operation dates.
- Bankability Standards:Project finance requires multi-year operational track records that emerging chemistries lack, constraining non-lithium technologies to strategic investor or utility balance-sheet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Duration Energy Storage Market |
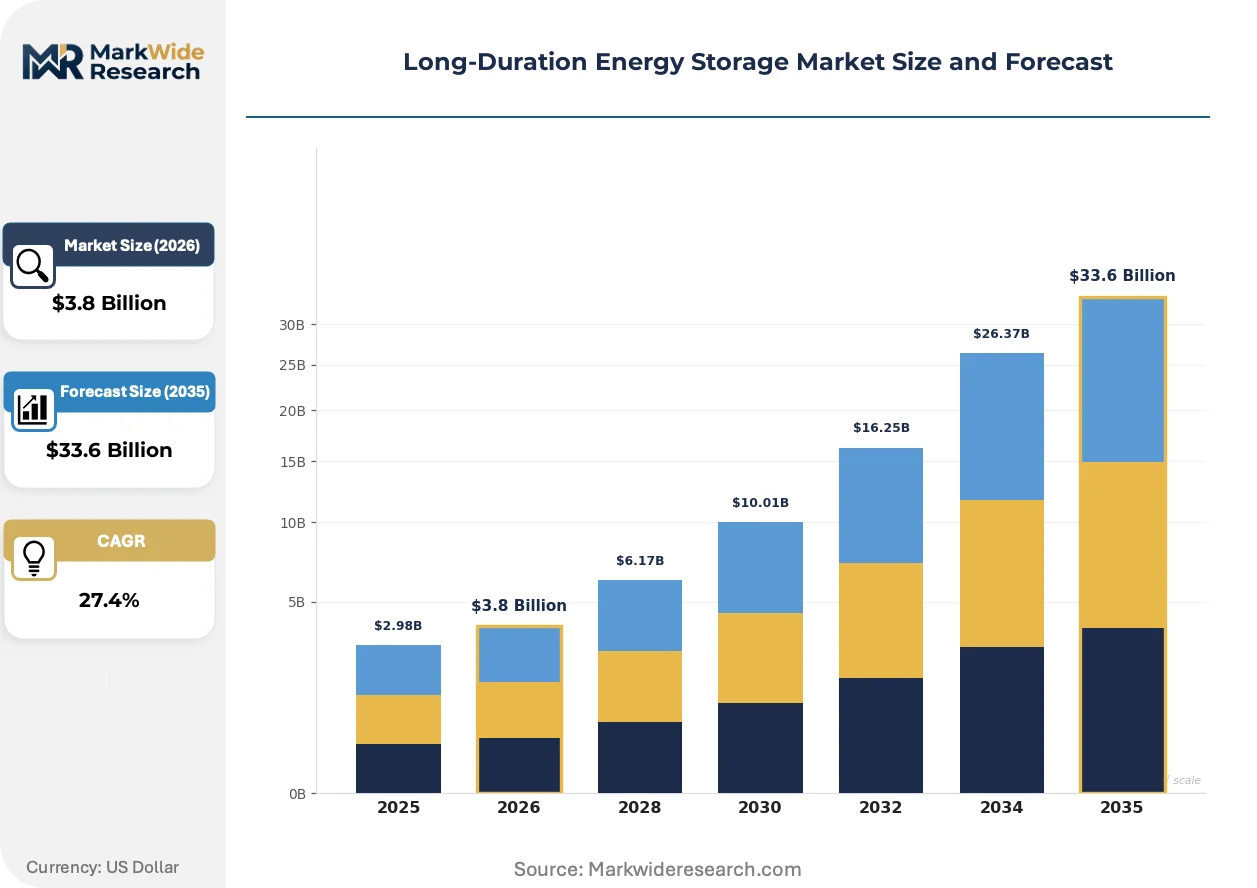
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $33.6 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Technology: Pumped Hydro, Flow Batteries, Compressed Air, Thermal Storage End User: Utilities, Industrial, Commercial, Residential Application: Grid Management, Renewable Integration, Backup Power, Frequency Regulation Distribution Channel: Direct Sales, Online, Wholesale, Partnerships |
| Companies Covered | Sumitomo Electric Industries, ESS Tech, Energy Vault, Form Energy, Invinity Energy Systems, Highview Power, Eos Energy Enterprises, GE Vernova, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Duration Energy Storage Market Trends and Innovations
Technology convergence and procurement model evolution are compressing development timelines for novel storage chemistries. Vectors span unified control architectures, regulatory redefinitions of storage asset class, and buyer-side restructuring of offtake structures.
Iron-air battery systems are unifying power conversion and energy storage into single-footprint installations. Grid operators in the United States Midwest are piloting these configurations for seasonal shifting. This convergence eliminates separate inverter and battery procurement, compressing balance-of-plant costs and project development cycles.
The EU Green Deal's storage-specific targets are reshaping member state auction designs. Capacity mechanisms in Germany and Spain now include duration floors that exclude four-hour lithium-ion bids. Developers are responding with hybrid proposals combining electrochemical front-haul with mechanical or thermal back-end duration.
Corporate offtake structures are fragmenting as data center operators and heavy manufacturers pursue direct bilateral contracts. These buyers bypass traditional utility intermediaries to secure dedicated renewable-plus-storage capacity. The pattern concentrates in California and Texas where retail choice frameworks permit such arrangements.
Long-Duration Energy Storage Market Segmentation
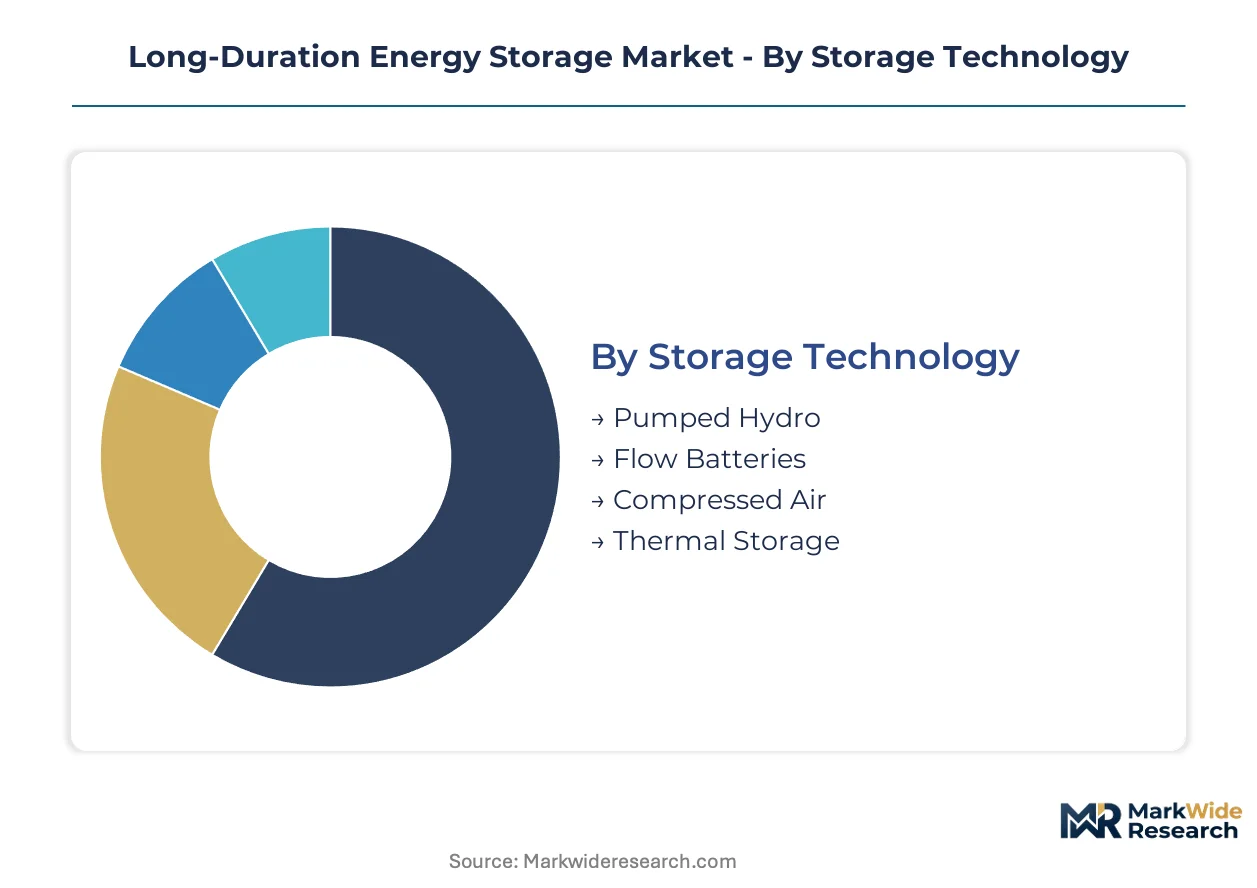
Technology pathways in long-duration storage diverge sharply in capital intensity, site requirements, and operational flexibility. Procurement decisions hinge on discharge duration targets, grid service requirements, and local geological or thermal resource availability.
Storage Technology:
Volume deployment concentrates in established electrochemical and mechanical systems, while premium economics accrue to novel chemistries with extended duration capabilities.
- Pumped Hydro:Gravity-fed water reservoirs deliver multi-gigawatt discharge capacity with seventy to eighty-five percent round-trip efficiency. Demand clusters in Norway, Switzerland, and Austria where alpine topography supports upper and lower reservoir configurations.
- Flow Batteries:Aqueous electrolyte systems achieve scalable power-to-energy ratios with minimal capacity fade over decades. Vanadium redox installations dominate grid management applications in Germany and Australia where daily cycling requirements exceed lithium-ion economics.
- Compressed Air:Underground cavern storage releases pressurized air through turbines for discharge durations spanning four to twenty-four hours. Deployable sites concentrate in Texas, Germany, and select Australian salt dome formations.
- Thermal Storage:Molten salt and solid-state media capture excess renewable generation as industrial process heat. Cement and chemical plants in Spain and California pilot these systems for gigawatt-hour scale shifting.
Mature deployment sits with pumped hydro. Newer deployment is concentrated in flow batteries and thermal systems.
End User:
Customer type determines procurement scale, contract structure, and regulatory compliance burden across the value chain.
- Utilities:Vertically integrated grid operators procure hundred-megawatt systems through competitive solicitations. FERC Order 841 compliance drives wholesale market participation requirements in United States ISO territories.
- Industrial:Heavy manufacturers and data center operators negotiate bilateral renewable-plus-storage contracts. These offtakers prioritize reliability over energy arbitrage in California and Texas retail choice markets.
- Commercial:Mid-scale enterprises deploy behind-the-meter flow batteries for demand charge management. Aqueous iron systems from ESS Tech serve microgrid configurations at manufacturing campuses.
- Residential:Single-home installations remain marginal due to capital cost barriers. Thermal storage for solar water heating captures niche demand in Australian suburban developments.
Contract sophistication peaks with utilities. Procurement velocity is climbing fastest among industrial offtakers.
Application:
Use case specificity dictates technology selection, with grid services favoring rapid response and renewable integration demanding extended discharge.
- Grid Management:Ancillary service provision requires sub-second response times for voltage support and black start capability. Flow batteries dominate this segment due to independent power and energy scaling.
- Renewable Integration:Solar and wind curtailment mitigation favors eight-to-hundred-hour discharge durations. Iron-air chemistry from Form Energy targets seasonal mismatch in United States Midwest wind corridors.
- Backup Power:Critical facility resilience drives procurement at hospitals and military installations. Thermal storage competes where combined heat and power integration reduces total cost of ownership.
- Frequency Regulation:Fast-ramping resources stabilize grid frequency deviations from renewable intermittency. Compressed air systems with advanced turbine controls penetrate this service in German balancing markets.
Revenue stack depth is greatest in grid management. Capacity expansion is steepest in renewable integration.
Distribution Channel:
Channel structure reflects project scale complexity and buyer sophistication, with direct engagement dominating utility-scale deployment.
- Direct Sales:Original equipment manufacturers negotiate engineering-procurement-construction contracts with utilities and industrial offtakers. Form Energy and Energy Vault pursue this channel for hundred-megawatt-plus installations.
- Online:Digital procurement platforms serve commercial and small-scale industrial buyers with standardized flow battery configurations. Configuration tools reduce sales cycle duration for repeat customers.
- Wholesale:Distributors aggregate thermal storage components for regional construction markets. European HVAC wholesalers stock molten salt tanks for solar thermal integration.
- Partnerships:Technology developers ally with EPC firms and renewable developers for integrated project delivery. Joint ventures compress development timelines in Australia's National Electricity Market.
Transaction concentration rests with direct sales. Channel experimentation is most active in partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while deployment concentrates in markets with high renewable penetration. Consumption patterns diverge between mature grid systems seeking seasonal storage and emerging markets building flexible generation from inception.
United States
Utility procurement drives demand as grid operators confront curtailment from Midwest wind and California solar assets. FERC Order 841 mandates wholesale market participation for storage resources, enabling simultaneous bidding into capacity, energy, and ancillary service markets. Project development concentrates in Texas ERCOT territory and California ISO zones where interconnection queues for multi-day systems stretch eighteen to thirty-six months.
Germany
Industrial load centers and balancing market requirements anchor deployment for vanadium flow and compressed air configurations. The EU Green Deal's storage-specific targets reshape federal auction designs with duration floors that exclude four-hour lithium-ion bids. Salt dome formations in Lower Saxony host underground cavern pilots while Bavarian manufacturing clusters pilot thermal storage for cement process heat.
Australia
National Electricity Market reforms value duration-specific attributes, creating premium revenue streams for eight-plus-hour systems. State-level renewable targets in Victoria and South Australia accelerate project pipelines for grid-scale storage. Remote mining operations in Western Australia deploy containerized flow batteries to displace diesel generation at off-grid sites.
China
Dual carbon goals and GB standards for electrochemical safety create parallel compliance layers for domestic and imported equipment. Provincial governments in Gansu and Xinjiang integrate long-duration systems with wind and solar bases to reduce curtailment rates. State Grid Corporation pilots compressed air and gravity storage in regions with favorable geology.
United Kingdom
Capacity market redesigns and net-zero commitments drive utility procurement for grid stability services. The Contracts for Difference mechanism increasingly accommodates storage duration tiers beyond four hours. Scottish wind corridors and North Sea interconnectors create demand for multi-day shifting to manage seasonal generation variability.
Long-Duration Energy Storage Market Competitive Landscape
Top-tier vendors anchor utility-scale deployments, while mid-tier specialists occupy technology-specific niches and regional integrators serve project development functions. The vendor base stratifies across chemistry developers, mechanical system fabricators, and full-stack solution providers. Strategic archetypes include duration-focused chemists, gravity-mechanical engineers, and thermal media specialists. Competitive moves center on strategic partnerships with EPC firms and technology licensing to compress development timelines.
Among chemistry-focused developers, Form Energy and ESS Tech occupy positions exemplifying the iron-based electrochemical archetype, while Energy Vault anchors the gravity-mechanical tier with composite block engineering. Sumitomo Electric Industries represents the established industrial conglomerate model, leveraging manufacturing scale and grid integration expertise. These entities collectively illustrate how competitive positioning diverges between novel chemistry ventures seeking bankability and incumbent industrial players extending existing capabilities into storage applications.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| ESS Tech |
| Energy Vault |
| Form Energy |
| Invinity Energy Systems |
| Highview Power |
| Eos Energy Enterprises |
| GE Vernova |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
Duration-tier bifurcation between hundred-hour iron-air systems and four-hour lithium-ion alternatives manifests in divergent pricing architectures and supply chain configurations across utility procurement channels. Premium economics accrue to extended-duration chemistries with multi-year development cycles, while commodity pricing pressures compress margins in shorter-duration electrochemical segments.
Pricing Analysis
Lead-time premiums for iron-air battery systems with thirty-six-month delivery horizons command fifteen to twenty percent pricing advantages over spot-available lithium-ion configurations in competitive solicitations. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation anchored in duration guarantees and round-trip efficiency certifications. Cost compression in lithium-ion tiers is intensifying because of cathode material oversupply from Chinese manufacturing expansion. Industrial offtakers exhibit highest price sensitivity, while vertically integrated utilities absorb premium durations for transmission deferral value.
Supply Chain Analysis
Dual-sourcing mandates from FERC-jurisdictional utilities require iron electrolyte qualification from at least two independent chemical suppliers, compressing vendor consolidation strategies. Manufacturing concentration centers on China for vanadium electrolyte processing, Germany for precision mechanical components in gravity systems, and the United States for iron-air battery assembly. Raw material dependencies span high-purity iron feedstock, fluorinated membrane materials, and composite block polymers. Single-source vulnerability in vanadium pentoxide supply from South African mining operations poses structural risk. Distribution runs through engineering-procurement-construction consortia for utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bankability requirements for project finance are consolidating vendor tiers, forcing emerging chemistry developers toward strategic investor backing or utility balance-sheet partnerships.
For Market Incumbents: To counter lithium-ion cost erosion from Chinese cathode oversupply, Sumitomo Electric and Siemens Energy should deepen backward integration into iron electrolyte production and secure captive vanadium processing capacity in Australian mining corridors. Certification investment in UL 9540A thermal runaway testing for flow battery configurations creates switching costs against emerging entrants. For New Entrants and Emerging Players: The price-point gap between premium iron-air seasonal storage and economy lithium-ion peaking systems creates white-space opportunity for aqueous iron flow batteries targeting eight-to-twenty-hour commercial microgrids. Victoria and South Australia present the most penetrable geographies given NEM capacity mechanism reforms. Direct bilateral contracting with data center operators bypasses utility procurement friction. For Investors and Strategic Acquirers: Re-rating potential sits with iron-air chemistry developers given FERC Order 841 capacity market participation catalysts across Midwest ISO territories. Five-to-ten-year viability framing favors ventures with demonstrated multi-hundred-megawatt manufacturing partnerships over laboratory-stage alternatives. The signal to watch is utility interconnection queue priority for non-lithium technologies in California and Texas.| Strategic Initiative | Industry Significance |
|---|---|
| Duration-Specific Capacity Buildout | Hundred-hour iron-air deployments in ERCOT and CAISO zones capture seasonal arbitrage premiums. |
| Backward Integration into Electrolyte Supply | Captive iron processing capacity insulates Form Energy and ESS Tech from commodity volatility. |
| Technology Licensing to EPC Partners | Energy Vault's composite block engineering licenses compress deployment timelines in Australian NEM projects. |
| Power Purchase Agreement Restructuring | Corporate offtakers in California retail choice markets bypass utility intermediaries for dedicated storage capacity. |
| Green Certification Program | EU Green Deal compliance positioning opens German and Spanish auction participation for non-lithium chemistries. |
Research Methodology
Trade databases, FERC interconnection filings, and IEA technology roadmaps formed the secondary backbone, cross-referenced with primary interviews involving utility planning officers, independent power producer project developers, EPC contractors, and grid operators across United States ISO territories and European balancing markets. Bottom-up project pipeline aggregation and top-down policy impact modeling enabled triangulation across deployment forecasts.
Bottom-up volume estimates derived from announced project capacities, while top-down constraints incorporated renewable penetration thresholds and grid flexibility requirements across the analysis window. Segmentation dimensions encompassed discharge duration tiers, technology chemistry families, end-user contract structures, and regional regulatory frameworks. CAGRs were synthesized from utility procurement trajectory modeling and learning curve assumptions for emerging chemistries.
Inputs from utility interconnection queues and state-level mandate announcements were available through the study window; gaps in commercial operational date realization for pilot projects introduce uncertainty bands around deployment timing. Deviation in FERC capacity market redesign timing or EU Green Deal implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Solar Storage System Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
South America Energy Storage Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Ultracapacitors Market
Energy Storage
Battery Storage Boxes Market