
 Latin America Stevedoring and Marine Cargo Handling Market | 2026-2036
Latin America Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Stevedoring and Marine Cargo Handling Market Foresight
Port automation mandates across Brazil and Colombia are broadening the capital threshold for terminal operators seeking concession renewals. A.P. Moller - Maersk leverages its integrated logistics footprint to control transshipment flows through Colombian and Mexican hubs. CMA CGM Group anchors regional capacity through dedicated terminal investments along the Pacific corridor. Navios South American Logistics Inc specializes in bulk and breakbulk infrastructure serving Argentina's grain belt and Paraguay's riverine access.
Stevedoring and marine cargo handling encompasses the physical transfer, stowage, and discharge of vessel-borne freight using shore-based cranes, mobile equipment, and labor coordination, with throughput capacity measured in twenty-foot equivalent units per hour and deadweight tonnage per berth cycle. The primary commercial purpose centers on minimizing vessel port stay duration while preserving cargo integrity across containerized, bulk, and breakbulk modalities. Container handling dominates value capture given reefer specialization and transshipment premiums, while bulk cargo handling sustains volume leadership through iron ore, grain, and petroleum flows across Atlantic and Pacific basins. Breakbulk operations retain structural importance in project cargo serving energy and mining developments, though margin pools concentrate in automated container terminals with digital platform integration.
Brazil's ANTAQ port regulatory framework, Colombia's national infrastructure agency ANI concession standards, and Chile's SUBPESCA environmental compliance protocols collectively elevate operational certification requirements for market access. These bodies enforce equipment modernization timelines, labor safety benchmarks, and emissions controls that filter terminal operator eligibility. Stakeholders must weigh concession tenure security against automation capital commitments as regulatory compliance becomes inseparable from competitive viability.
Market Dynamics
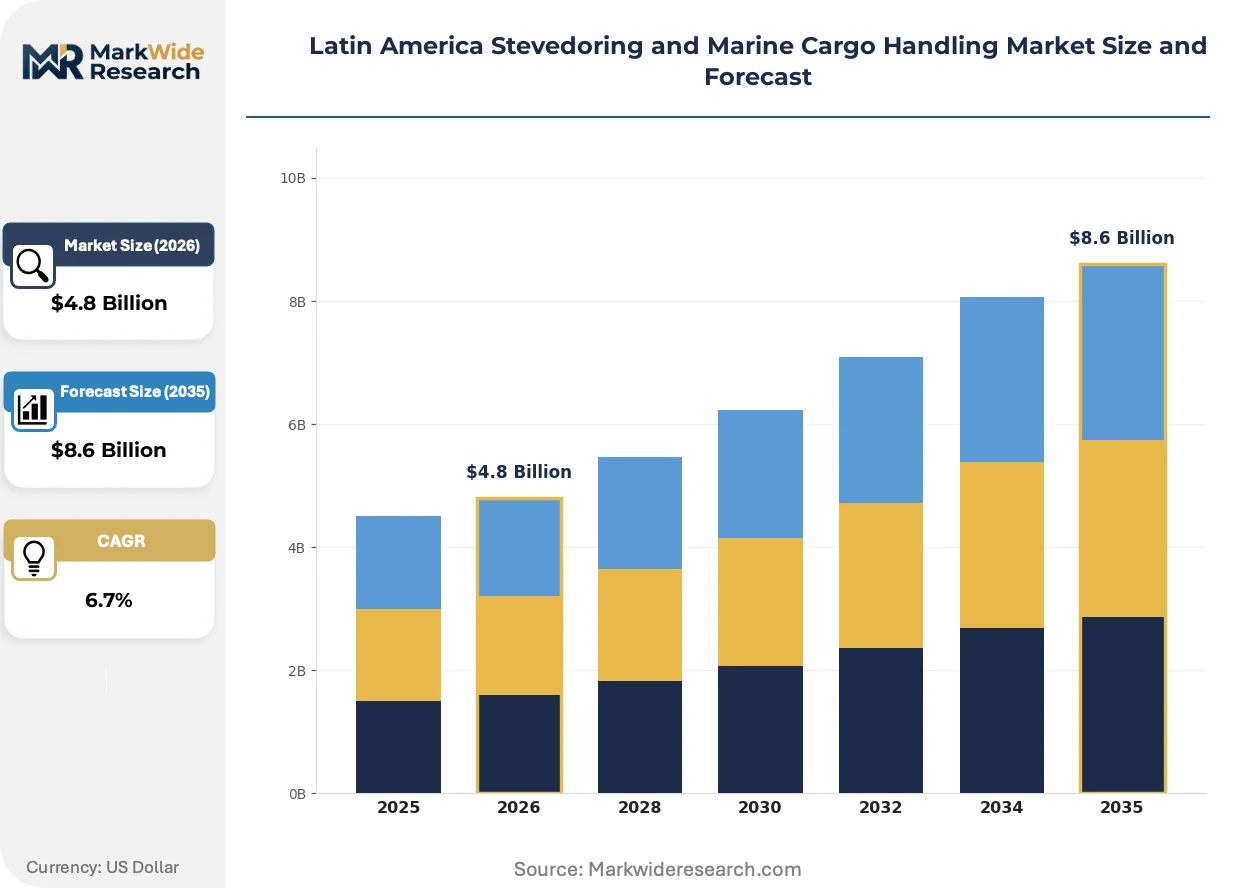
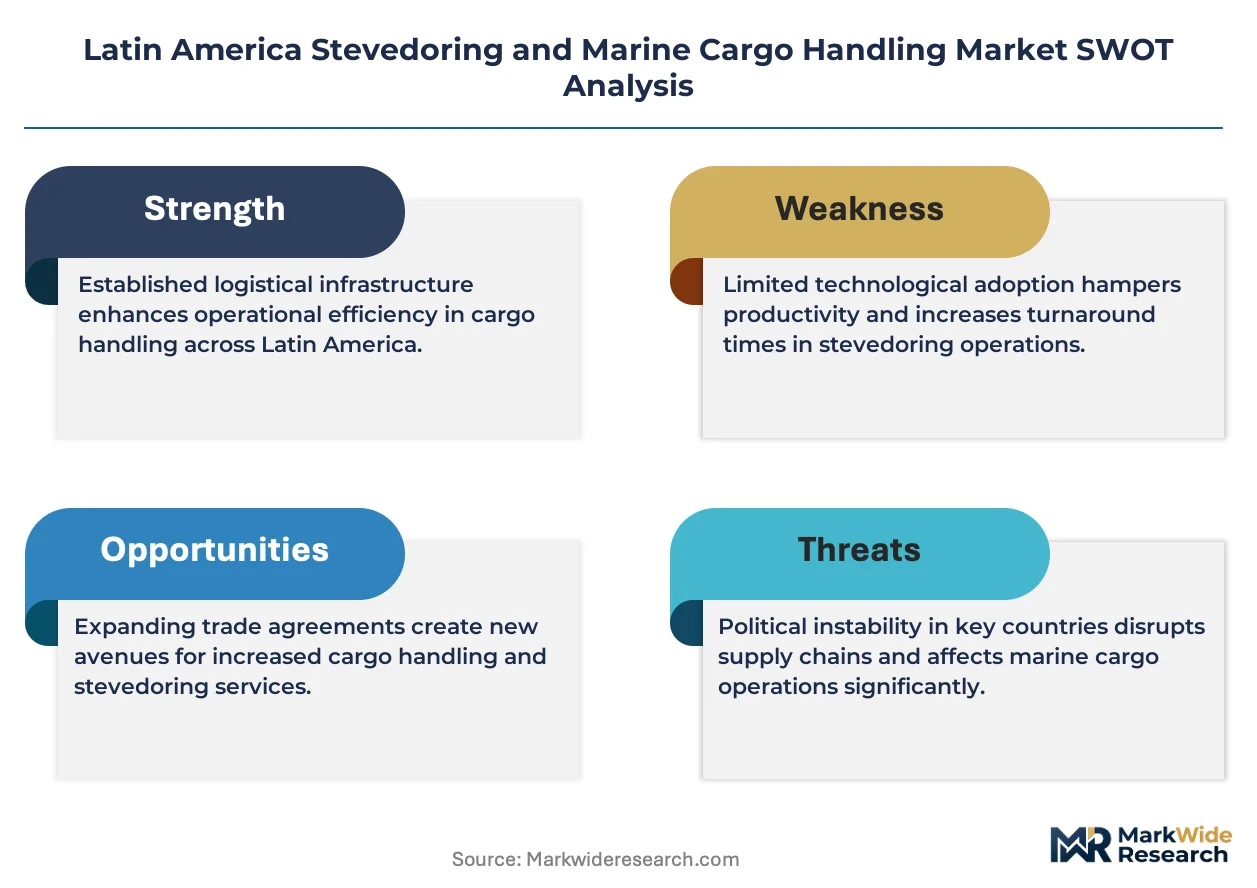
Port automation mandates and concession renewal frameworks across Brazil, Colombia, and Chile are forcing terminal operators to commit capital-intensive crane and yard management upgrades before securing tenure extensions, fundamentally restructuring competitive entry barriers.
Growth Catalysts
- ANTAQ Equipment Modernization Timelines:Brazil's port regulator mandates automated stacking cranes and vessel-to-shore electrification at Santos and Paranaguá, compelling incumbent operators to expand berth productivity metrics.
- Soybean Export Surge:Agricultural shippers across Mato Grosso and Rio Grande do Sul are routing record refrigerated container volumes through Atlantic corridor terminals, stretching existing reefer plug capacity.
- Panama Canal Expansion Protocols:New vessel class accommodation rules are drawing post-Panamax boxships into Colombian and Mexican transshipment hubs, redistributing cargo flows across Pacific basin facilities.
Market Restraints
- Concession Capital Lock-in:ANI standards in Colombia require upfront automation investment before bid award, filtering out mid-tier terminal operators lacking balance sheet depth for crane procurement.
- Specialized Labor Scarcity:Remote equipment operator certification programs across Chile and Peru cannot match deployment timelines for automated yard blocks, extending commissioning schedules.
- Grid Electrification Gaps:Shore power infrastructure at Brazilian bulk terminals remains incomplete, forcing dual-fuel dependency that elevates operating cost volatility against fully electrified competitors.
Strategic Opportunities
- Paraguay Riverine Access:Breakbulk and project cargo terminals serving Asunción and Villeta remain underdeveloped, offering first-mover positioning for barge-feeder integration with Argentine grain belt exporters.
- SUBPESCA Emissions Compliance:Chile's environmental protocols create premium berth access for terminals demonstrating carbon capture integration or renewable-powered cargo handling, attracting ESG-linked shipping lines.
- Reefer-Transshipment Convergence:Pacific coast facilities in Buenaventura and Manzanillo can capture value from cold chain platform integration, linking Central American produce exporters with Asian consumer markets.
Industry Challenges
- Automation-Workforce Transition:Dockworker unions across Brazilian ports resist remote crane operator retraining mandates, delaying yard automation commissioning and inflaming labor arbitration costs.
- Legacy System Integration:Terminal operating system upgrades at Paranaguá must interface with customs clearance platforms dating to 2012, fragmenting data visibility across vessel planning and gate operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Stevedoring and Marine Cargo Handling Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bulk Cargo Handling, Container Handling, Breakbulk Operations, Ro-Ro Services End User: Shipping Lines, Freight Forwarders, Port Operators, Logistics Companies Technology: Automated Systems, Manual Processes, Hybrid Solutions, Digital Platforms Equipment: Cranes, Forklifts, Conveyors, Tugboats |
| Companies Covered | A.P. Moller - Maersk, Mediterranean Shipping Co, COSCO Group, CMA CGM Group, Hapag-Lloyd, UWL Inc, Latin American Cargo, Navios South American Logistics Inc, ONE (Ocean Network Express), Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Stevedoring and Marine Cargo Handling Market Shifts & Advancements
Digital platform integration and electrification hardware are compressing vessel turnaround metrics while regulatory compliance frameworks accelerate equipment replacement cycles across the region's major cargo gateways.
Automated rubber-tired gantry cranes with AI-powered container positioning are absorbing manual yard planning functions at Colombian and Chilean terminals. Maersk-controlled facilities in Cartagena deploy these systems to compress dwell times for transshipment cargo. The technology is absorbing traditional stevedoring labor coordination roles, reducing headcount dependencies while elevating throughput per hectare.
ANI concession standards now embed emissions monitoring and shore power readiness as mandatory bid evaluation criteria across Colombian Pacific and Caribbean ports. Terminal operators must demonstrate renewable energy procurement contracts or carbon offset verification to qualify for 20-year tenure awards. Bulk cargo handlers at Barranquilla and Buenaventura face the steepest compliance ramps given diesel-dependent legacy equipment fleets.
Cargo owners across Brazil's agricultural belt now contract directly with terminal operators for integrated inland-to-vessel logistics, bypassing traditional freight forwarder intermediaries. Soybean exporters in Mato Grosso negotiate volume commitments with Santos terminal operators that bundle trucking, storage, and vessel loading under single invoicing. This disintermediation concentrates price negotiation leverage with commodity traders while compressing margin pools for traditional logistics service providers.
Latin America Stevedoring and Marine Cargo Handling Market Segmentation
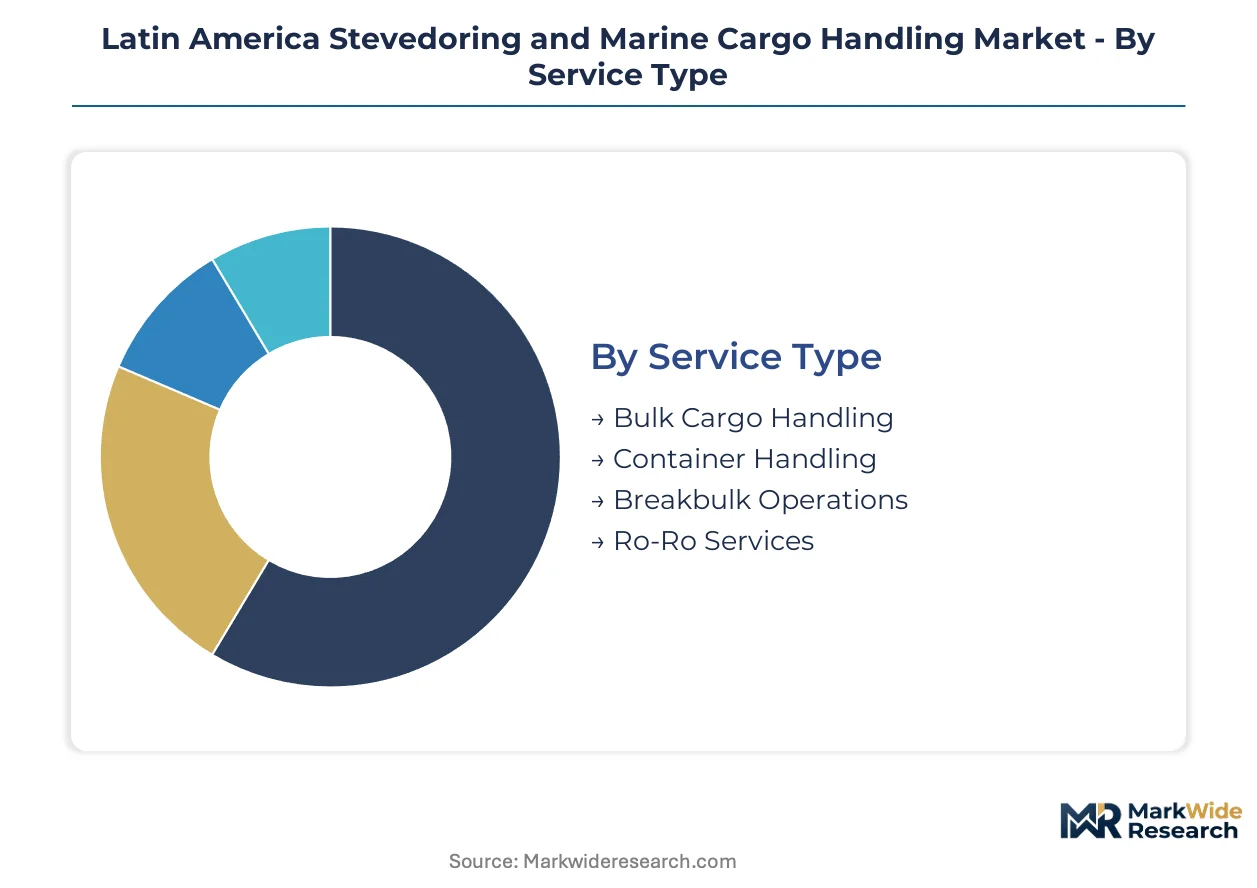
Service modality determines capital intensity and margin structure across Latin American cargo gateways, with automation readiness now filtering concession eligibility. Equipment specialization and technology deployment separate terminal operators competing for soybean, iron ore, and transshipment volumes.
Service Type:
Terminal operators select service portfolios based on berth configuration and hinterland cargo composition.
- Container Handling:Automated stacking cranes and reefer plug infrastructure dominate capital allocation at Santos, Cartagena, and Manzanillo. Soybean exporters across Mato Grosso negotiate direct volume commitments with terminal operators bundling inland logistics and vessel loading.
- Bulk Cargo Handling:Iron ore, grain, and petroleum flows sustain volume leadership through dedicated berth cycles measured in deadweight tonnage. Brazilian Atlantic terminals face incomplete shore power infrastructure, forcing dual-fuel dependency against electrified competitors.
- Breakbulk Operations:Project cargo terminals serving Paraguay's riverine access and Argentine energy developments retain structural importance despite thinner margins.
- Ro-Ro Services:Vehicle and machinery discharge operations concentrate at Brazilian and Mexican Pacific gateways serving automotive supply chains.
Volume sits with Bulk Cargo Handling; growth tilts toward Container Handling.
End User:
Contracting authority shapes pricing leverage and integration depth across the stevedoring value chain.
- Shipping Lines:Ocean carriers with integrated logistics footprints control transshipment flows through Colombian and Mexican hubs, demanding terminal operating system compatibility and emissions compliance documentation. ANI concession standards in Colombia embed renewable energy procurement as mandatory bid criteria.
- Port Operators:Concession holders at Santos and Paranaguá face ANTAQ-mandated equipment modernization timelines before tenure renewal, elevating automation capital thresholds.
- Freight Forwarders:Traditional intermediaries see margin compression as agricultural exporters contract directly with terminal operators for inland-to-vessel logistics.
- Logistics Companies:Regional integrators seek yard automation partnerships to compress dwell times and elevate throughput per hectare.
Negotiating power concentrates with Shipping Lines; Logistics Companies are expanding most quickly through platform integration.
Technology:
Regulatory compliance timelines and labor availability constrain deployment choices.
- Automated Systems:AI-powered rubber-tired gantry cranes with container positioning algorithms absorb manual yard planning functions at Colombian and Chilean terminals. Remote equipment operator certification programs cannot match deployment schedules, extending commissioning timelines.
- Digital Platforms:Terminal operating system upgrades must interface with legacy customs clearance infrastructure, fragmenting data visibility.
- Hybrid Solutions:Transitional configurations bridge electrification gaps at Brazilian bulk terminals with incomplete grid infrastructure.
- Manual Processes:Dockworker unions across Brazilian ports resist retraining mandates, delaying automation commissioning.
Installed base favors Manual Processes; steepest expansion trajectory belongs to Automated Systems.
Equipment:
Berth productivity metrics and vessel class accommodation drive procurement priorities.
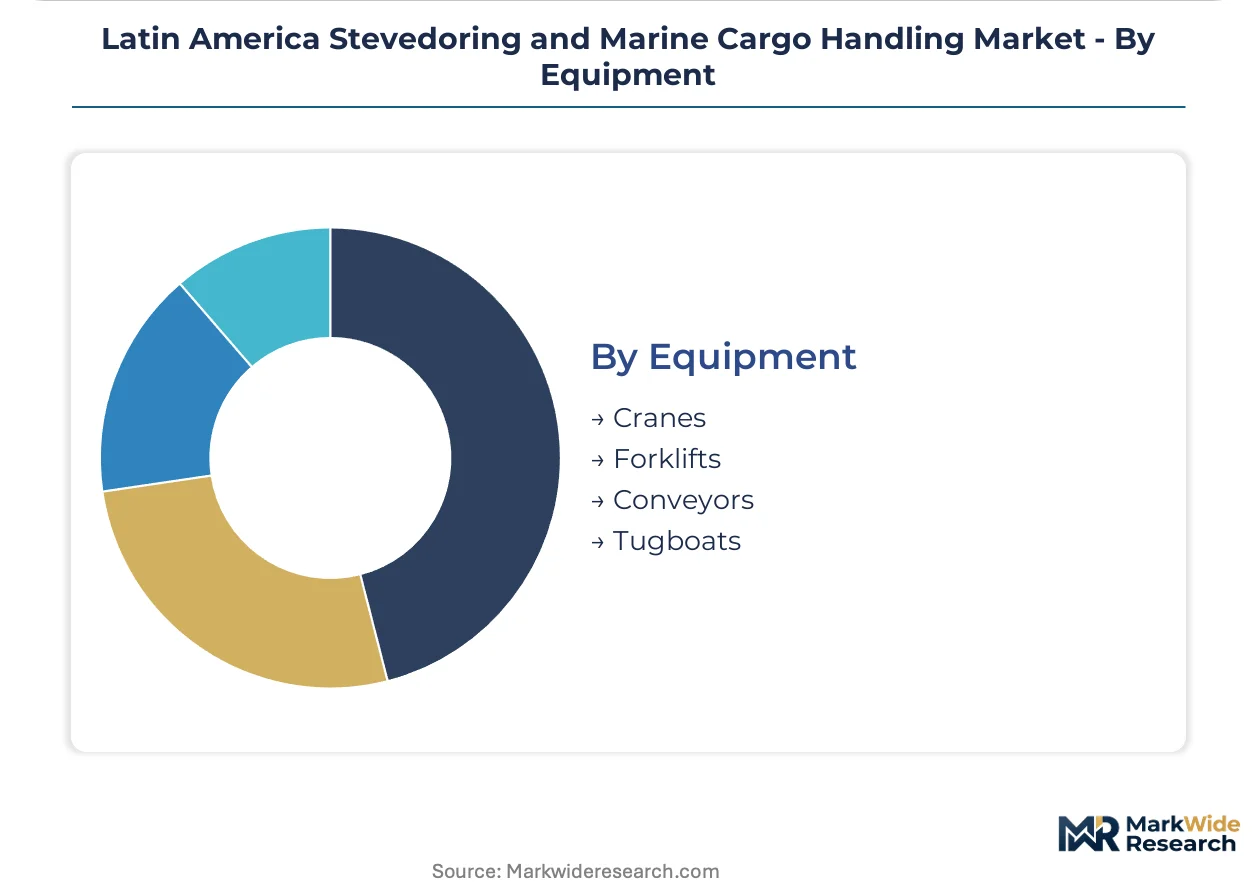
- Cranes:Automated stacking cranes and vessel-to-shore electrification dominate capital commitments at Atlantic corridor ports. ANTAQ mandates filter terminal operator eligibility through equipment replacement timelines.
- Conveyors:Continuous flow systems sustain iron ore and grain throughput at dedicated bulk terminals.
- Forklifts:Yard equipment fleets transition toward electrification under SUBPESCA emissions protocols in Chile.
- Tugboats:Harbor assist and escort services adapt to post-Panamax vessel dimensions through Colombian and Mexican hubs.
Investment concentrates in Cranes; electrification requirements favor Conveyors and Forklifts gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Zona Franca de Manaus tax-incentive regime and Colombia's free trade zones concentrate stevedoring investment along Atlantic and Pacific corridors, with regulatory mandates reshaping terminal operator requirements across the continent.
Brazil
Soybean exporters across Mato Grosso and Rio Grande do Sul are routing record refrigerated container volumes through Santos and Paranaguá terminals. ANTAQ equipment modernization timelines mandate automated stacking cranes and vessel-to-shore electrification before concession renewals. The Santos-Paranaguá axis commands dedicated berth investments as iron ore and grain export volumes strain existing infrastructure.
Colombia
Pacific coast facilities in Buenaventura and Caribbean hubs in Cartagena capture transshipment flows from post-Panamax boxships. ANI concession standards embed emissions monitoring and shore power readiness as mandatory bid evaluation criteria. Cartagena terminals deploy automated yard systems to compress dwell times for transshipment cargo.
Argentina
Grain belt exporters negotiate direct volume commitments with terminal operators bundling trucking, storage, and vessel loading. The country's national port administration enforces labor safety benchmarks and equipment replacement timelines. Rosario and Buenos Aires terminals serve as primary export gateways for agricultural commodities.
Chile
SUBPESCA environmental compliance protocols create premium berth access for terminals demonstrating carbon capture integration or renewable-powered cargo handling. Remote equipment operator certification programs cannot match deployment timelines for automated yard blocks. Valparaíso and San Antonio facilities anchor Pacific corridor capacity.
Mexico
Post-Panamax vessel accommodation rules are drawing boxships into Mexican transshipment hubs at Manzanillo and Lázaro Cárdenas. The country's national communications and transport regulator oversees port modernization standards. Pacific coast terminals link Central American produce exporters with Asian consumer markets through cold chain platform integration.
Latin America Stevedoring and Marine Cargo Handling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin American cargo gateways, creating a tiered structure where capital depth filters concession eligibility. Container handling specialists with integrated logistics footprints control transshipment flows through Colombian and Mexican hubs. Bulk cargo operators anchor regional capacity through dedicated terminal investments along riverine and Atlantic corridors. The dominant competitive moves center on automation capital commitments ahead of concession renewals and direct contracting with agricultural exporters to disintermediate traditional freight forwarders.
Within the integrated logistics tier, A.P. Moller - Maersk and CMA CGM Group occupy positions that exemplify transshipment control through terminal operating system compatibility and emissions compliance documentation. Navios South American Logistics Inc represents the specialized bulk and breakbulk archetype, serving Argentina's grain belt and Paraguay's riverine access with infrastructure focused on commodity export corridors. These three companies illustrate the strategic divergence between containerized transshipment dominance and bulk cargo volume leadership.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| Mediterranean Shipping Co |
| COSCO Group |
| CMA CGM Group |
| Hapag-Lloyd |
| UWL Inc |
| Latin American Cargo |
| Navios South American Logistics Inc |
| ONE (Ocean Network Express) |
| Others |
Supply & Pricing Matrix
Baltic Dry Index fluctuations cascade through Latin American stevedoring contracts, compressing margins at bulk terminals while container operators capture reefer premiums through long-term agricultural offtake agreements with Mato Grosso soybean exporters.
Pricing Analysis
Lead-time contracting structures reward advance volume commitments with berth priority access, while spot market slots trade at premiums during peak harvest windows. Three-tier pricing structure across priority berthing, standard scheduling, and flexible windows separates committed agricultural exporters from opportunistic breakbulk charterers. Cost compression in standard-tier container handling is intensifying because ANTAQ-mandated crane electrification capital must be recovered through throughput gains. Freight forwarders show acute price sensitivity as direct terminal contracting disintermediates their role, while integrated shipping lines absorb premium pricing for emissions-compliant berth access.
Supply Chain Analysis
Empty container repositioning flows from Asian consumer markets back to Brazilian export corridors create structural equipment imbalances that elevate leasing rates during Mato Grosso harvest peaks. Equipment manufacturing concentrates in China, South Korea, and Germany for automated stacking cranes and vessel-to-shore systems. Terminal operating software and remote operator certification programs draw from US, European, and Israeli technology clusters. Single-source vulnerability sits with Chinese crane suppliers facing ANI localization requirements in Colombia. Distribution runs through concession-holder networks at Santos, Cartagena, and Manzanillo, with feeder barge integration extending into Paraguay's riverine system.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal operators are racing to integrate inland logistics capabilities upstream, capturing agricultural exporter relationships before concession renewals force automation capital deployment that locks in competitive positioning for two decades.
For Market Incumbents: Hedge against labor arbitration costs by accelerating remote crane operator certification partnerships with Chilean technical institutes before SUBPESCA mandates widen compliance gaps. Secure concession tenure through early ANTAQ equipment modernization commitments at Paranaguá, converting automation capital into exclusive berth access that filters mid-tier competitors lacking balance sheet depth for electrified crane procurement. For New Entrants and Emerging Players: Begin with underdeveloped breakbulk terminals serving Asunción and Villeta, where barge-feeder integration with Argentine grain belt exporters offers first-mover positioning absent dominant incumbents. Target Paraguay riverine access for project cargo serving energy developments, leveraging lower automation thresholds compared to container gateway requirements. Pursue direct contracting relationships with commodity traders bypassing freight forwarder intermediaries. For Investors and Strategic Acquirers: The window for entry favors specialized bulk operators with captive riverine infrastructure over saturated container gateway plays. Mid-cap terminal operators holding Colombian Pacific concessions face steepest ANI compliance ramps, creating distressed acquisition opportunities for capital-rich buyers capable of shore power infrastructure deployment. Monitor ANTAQ concession renewal timelines for Santos and Paranaguá as inflection indicators for regional consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inland Logistics | Soybean exporters in Mato Grosso negotiate direct volume commitments bundling trucking, storage, and vessel loading. |
| Automated Stacking Crane Deployment | Maersk-controlled Cartagena facilities deploy AI-powered yard systems to compress transshipment cargo dwell times. |
| Shore Power Infrastructure Investment | SUBPESCA emissions protocols create premium berth access for terminals demonstrating renewable-powered cargo handling. |
| Reefer Plug Capacity Expansion | Atlantic corridor terminals stretch existing infrastructure as agricultural shippers route record refrigerated container volumes. |
| Riverine Barge-Feeder Integration | Paraguay's underdeveloped breakbulk terminals offer first-mover positioning linking Argentine grain exports to ocean vessels. |
Research Methodology
Trade publications, customs filings, and ANTAQ regulatory disclosures formed the secondary backbone, cross-referenced with primary interviews involving terminal operations directors, port authority concession managers, agricultural commodity traders, and remote equipment certification program administrators. Bottom-up vessel throughput data from Santos, Cartagena, and Manzanillo combined with top-down macroeconomic trade flow analysis to triangulate market sizing across container, bulk, and breakbulk modalities.
Historical throughput trendlines at major Atlantic and Pacific corridor ports anchored the projection framework, with growth rates derived from regression analysis against agricultural export volumes and Panama Canal vessel class accommodation shifts. Segmentation modeling incorporated service type, end-user contracting authority, technology deployment stage, and equipment specialization dimensions. Forecast inputs included ANI concession award timelines, SUBPESCA emissions compliance phase-ins, and soybean production forecasts from Brazil's agricultural belt.
Underlying measurement precision varies by segment; container handling throughput carries tighter precision than breakbulk project cargo given standardized TEU reporting, while bulk cargo estimates reflect greater uncertainty around commodity price-driven volume swings. Forecasts embed assumptions regarding regulatory enforcement continuity and concession renewal participation rates. Practitioners should monitor ANTAQ equipment modernization deadline extensions and dockworker union arbitration outcomes for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market