
 United States Digital Freight Forwarding Market | 2026-2036
United States Digital Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digital Freight Forwarding Market Analytics
FMC's Ocean Shipping Reform Act certification requirements for non-vessel operating common carriers is unwinding legacy broker networks and forcing digital onboarding. C.H. Robinson Worldwide leverages its proprietary Navisphere platform to sustain control over domestic truckload matching. Flexport competes through integrated customs brokerage and ocean freight digitization. Freightos anchors rate transparency across international air and ocean lanes with its digital marketplace.
Digital freight forwarding encompasses technology-enabled orchestration of cargo movement across multimodal networks, utilizing application programming interfaces, electronic data interchange protocols, and real-time visibility telemetry to replace manual quotation, booking, and documentation workflows. Artificial Intelligence segments command premium pricing through predictive capacity forecasting and dynamic rate optimization, while Blockchain deployments remain nascent due to carrier consortium coordination costs. Cloud-Based deployment dominates new implementations as shippers prioritize API-first integration with existing enterprise resource planning systems over capital-intensive on-premises infrastructure.
The Federal Motor Carrier Safety Administration enforces hours-of-service compliance through mandatory electronic logging devices, directly expanding addressable demand for automated carrier matching. The Federal Maritime Commission's updated detention and demurrage billing rules under OSRA 2022 compel forwarders to deploy timestamp-verification technology. Stakeholders must weigh interoperability investments against platform switching costs as carrier APIs proliferate without universal data standards.
Market Dynamics
The Federal Motor Carrier Safety Administration's electronic logging device mandate continues compressing carrier matching timelines, forcing small fleet operators onto automated freight platforms and eliminating phone-and-fax brokerage workflows across Texas, California, and Illinois freight corridors.
Growth Catalysts
- E-Commerce Density:Midwest and Southeast warehouse clusters are generating platform-native freight procurement demand as shippers abandon annual contracted lanes for spot-market agility.
- FMCSA Hours-of-Service Enforcement:Mandatory electronic logging devices expand the addressable base for digital freight matching by disqualifying manual dispatch compliance methods.
- Port-Rail-Highway Interchanges:Dense shipment origination points in Texas, California, and Illinois create network effects that accelerate platform adoption through carrier-side liquidity.
Market Restraints
- API Proliferation Without Standards:Carrier-specific data formats impose interoperability costs on forwarders attempting multi-platform integration.
- Small Carrier Technology Debt:Owner-operators in rural corridors lack enterprise resource planning infrastructure to consume digital tendering without middleware investment.
- Blockchain Consortium Coordination:Distributed ledger deployments stall due to competing carrier governance models and implementation cost allocation disputes.
Strategic Opportunities
- Customs Brokerage Convergence:Integration of ocean freight digitization with automated customs filing creates stickier shipper relationships in port-adjacent markets.
- AI-Driven Predictive Capacity:Machine learning forecasting models command premium positioning by reducing deadhead miles for asset-light carriers.
- Cloud-Native ERP Integration:API-first deployment models displace on-premises infrastructure as shippers prioritize real-time visibility telemetry over capital expenditure.
Industry Challenges
- Timestamp-Verification Technology Deployment:Federal Maritime Commission detention and demurrage billing rules under OSRA 2022 compel forwarders to rebuild invoice systems for automated audit trails.
- Legacy Broker Network Unwinding:FMC certification requirements for non-vessel operating common carriers force rapid digital onboarding of previously relationship-dependent accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digital Freight Forwarding Market |
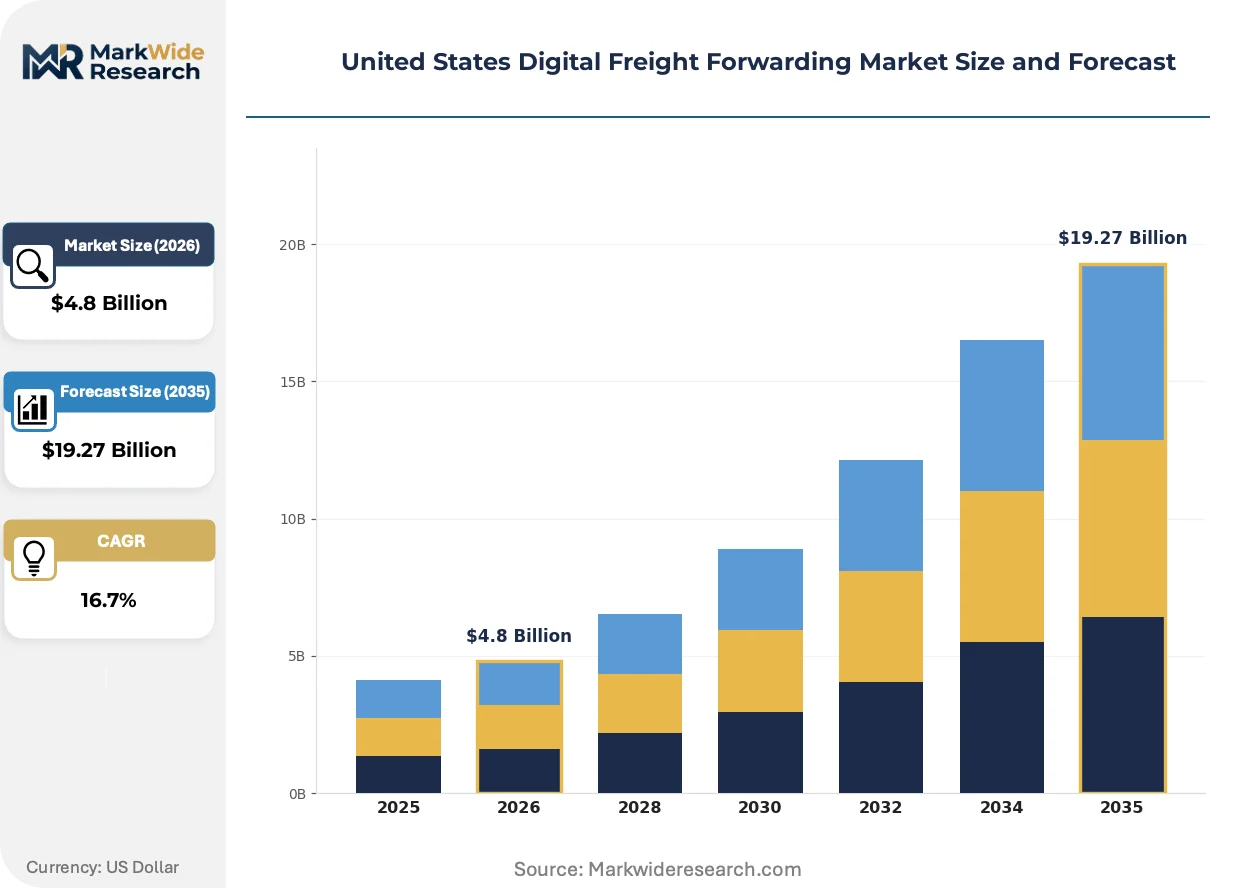
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight Technology: Blockchain, IoT, Automation, Artificial Intelligence End User: E-commerce, Manufacturing, Retail, Logistics Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | UniCargo, SILQ, C.H. Robinson Worldwide, Arrive Logistics, RXO, Uber Freight, Freightos, Echo Global Logistics, Flexport, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digital Freight Forwarding Market Evolving Landscape
Platform-based freight procurement is actively displacing contracted lane relationships as shippers prioritize spot-market responsiveness over annual rate commitments in volatile capacity environments.
Artificial intelligence is bifurcating the competitive landscape between predictive capacity forecasting specialists and static rate-quoting incumbents. Large e-commerce shippers in the Midwest are adopting dynamic rate optimization modules at accelerating pace. This technology compression is eliminating margin capture for forwarders lacking real-time telemetry infrastructure.
The Federal Maritime Commission's updated detention and demurrage billing rules under OSRA 2022 are forcing timestamp-automation investments across NVOCC certification holders. Industrial consequence includes accelerated platform switching as legacy brokers fail compliance audits. Port-adjacent forwarders in California and Texas corridors are responding with dedicated verification technology procurement.
Shipper procurement patterns are fragmenting from annual contracted lanes toward continuous spot-market engagement. The traditional RFP cycle is compressing into weekly or daily tendering decisions as volatility tolerance rises. This behavioral shift is most visible among e-commerce verticals operating Midwest and Southeast distribution networks.
United States Digital Freight Forwarding Market Segmentation
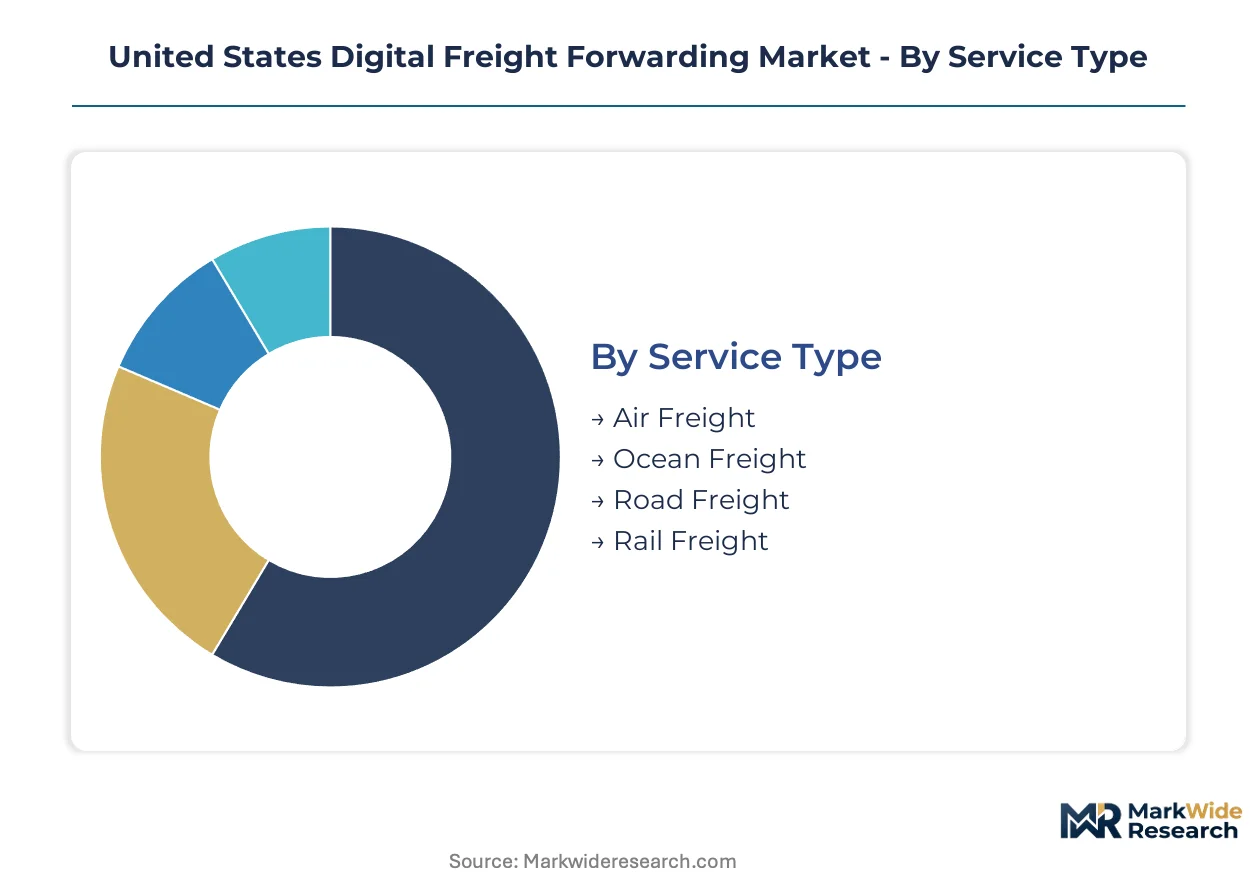
Digital freight forwarding segmentation reveals where technology investments concentrate and which service lines capture premium pricing. Shipper procurement patterns differ sharply across deployment models and end-use verticals, creating distinct margin architectures within each category.
Service Type:
Road freight commands the dominant margin pool due to fragmented carrier bases and high tender frequency, while ocean freight yields lower per-shipment margins at substantially higher contract values.
- Road Freight:Truckload and less-than-truckload digitization dominates platform transaction volumes. Demand clusters along Texas-California-Illinois corridors where FMCSA electronic logging device enforcement has eliminated manual dispatch compliance for small fleet operators.
- Ocean Freight:Container booking automation integrates with customs brokerage workflows. FMC detention and demurrage billing rules under OSRA 2022 force timestamp-verification technology deployment across NVOCC certification holders in port-adjacent markets.
- Air Freight:International lane digitization prioritizes rate transparency over capacity forecasting due to scheduled carrier dominance.
- Rail Freight:Intermodal coordination platforms serve bulk commodity and automotive verticals with lower tender frequency than truckload markets.
Road freight holds installed capacity. Ocean freight is rotating up the share rankings through customs brokerage convergence.
Technology:
Artificial Intelligence applications extract premium pricing through predictive capacity forecasting, while Blockchain deployments stall on carrier consortium governance disputes.
- Artificial Intelligence:Machine learning models forecast lane-level capacity availability and optimize dynamic rate quotations. Midwest e-commerce shippers adopt these modules fastest as spot-market procurement replaces annual contracted lanes.
- Automation:Robotic process automation eliminates manual document processing in quotation and booking workflows. Forwarders deploying automated carrier matching capture margin from phone-and-fax incumbents in California and Texas freight corridors.
- IoT:Real-time visibility telemetry tracks container location and condition across multimodal handoffs.
- Blockchain:Distributed ledger implementations for smart contracts and documentation remain nascent due to competing carrier governance models and implementation cost allocation conflicts.
Automation holds installed capacity. Artificial Intelligence is climbing the fastest as shipper willingness-to-pay for predictive capabilities expands.
End User:
E-commerce verticals drive platform-native procurement adoption, while manufacturing retains legacy annual contracting patterns with slower digitization timelines.
- E-commerce:Spot-market agility requirements force abandonment of annual contracted lanes. Midwest and Southeast warehouse clusters generate dense shipment origination points that accelerate carrier-side liquidity on digital platforms.
- Logistics:Third-party providers integrate digital freight matching as a service layer for shipper clients. These intermediaries prioritize API-first ERP integration over standalone platform interfaces.
- Retail:Seasonal volume volatility creates demand for dynamic capacity sourcing during peak periods.
- Manufacturing:Contractual rate stability preferences slow adoption of spot-market platforms despite inbound supply chain digitization investments.
Logistics holds installed capacity. E-commerce is gaining share fastest through procurement pattern fragmentation.
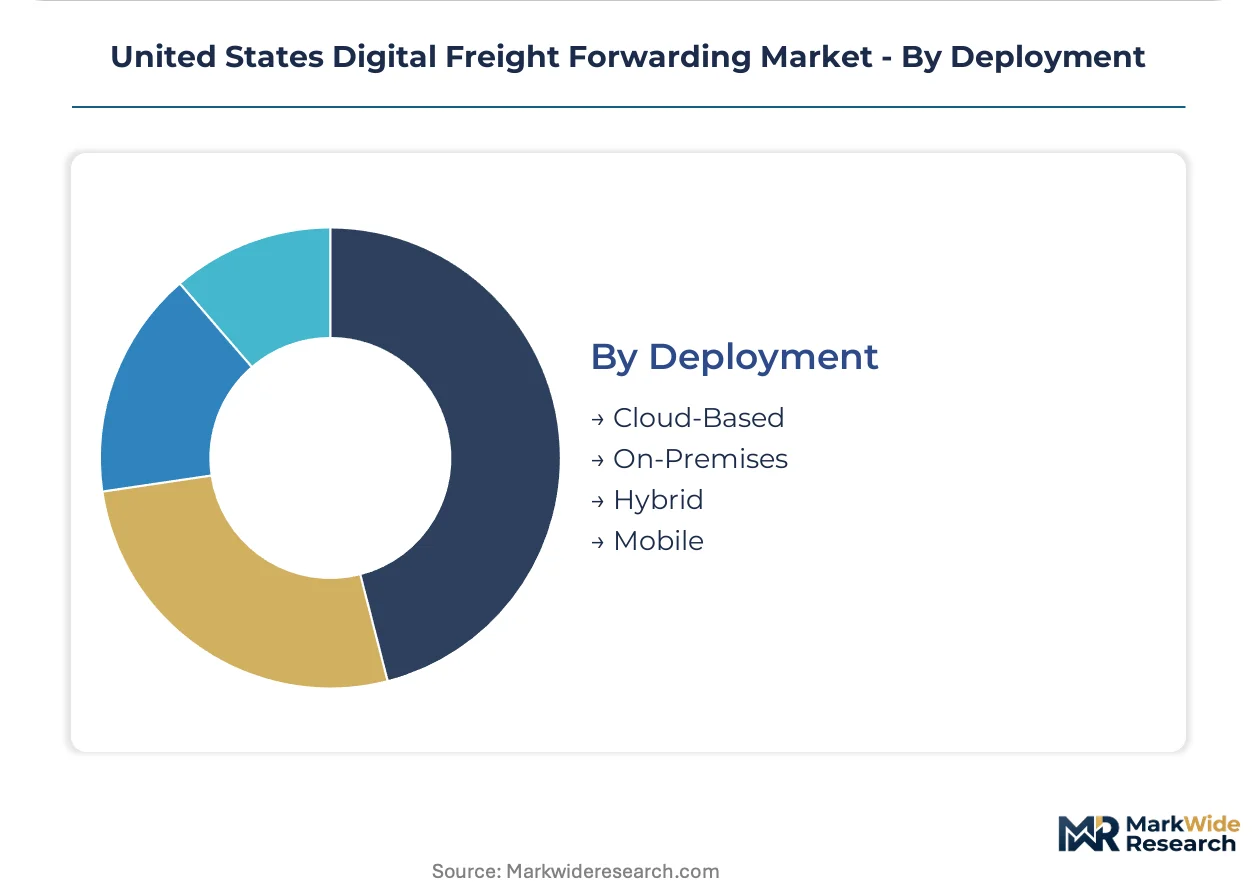
Deployment:
Cloud-based implementations dominate new forwarder investments as shippers prioritize API integration speed over infrastructure control.
- Cloud-Based:API-first deployment models enable real-time visibility telemetry integration with existing enterprise resource planning systems. This architecture displaces capital-intensive on-premises infrastructure across mid-market forwarders.
- Mobile:Driver-facing applications for electronic tender acceptance and document upload extend platform reach to owner-operators lacking enterprise IT infrastructure.
- Hybrid:Mixed cloud-on-premises configurations serve large forwarders with legacy data center investments and compliance-sensitive documentation requirements.
- On-Premises:Declining share reflects capital expenditure burden and slower integration timelines relative to cloud-native alternatives.
Hybrid holds installed capacity. Cloud-Based is expanding most quickly through shipper procurement prioritization of integration velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles rail intermodal complex anchors California's dominance in containerized freight digitization. Texas Gulf Coast petrochemical corridors and Illinois Midwest distribution hubs complete the three-state infrastructure triangle driving platform adoption.
California
E-commerce fulfillment centers in the Inland Empire generate dense truckload demand for digital freight matching. The Federal Maritime Commission's OSRA 2022 detention and demurrage rules force Los Angeles-Long Beach forwarders to deploy timestamp-verification systems. Flexport exemplifies customs brokerage convergence in port-adjacent markets.
Texas
Houston petrochemical exports and Dallas-Fort Worth distribution clusters create multimodal shipment origination density. FMCSA electronic logging device enforcement has eliminated manual dispatch for small fleet operators along Interstate 35 and Interstate 10 corridors. Uber Freight leverages this carrier liquidity in energy and retail verticals.
Illinois
Chicago's rail-highway interchange density produces the highest truckload tender frequency outside California. The FMCSA hours-of-service compliance mandate pushes owner-operators toward automated freight platforms. C.H. Robinson Worldwide sustains platform dominance through Navisphere integration with regional enterprise shippers.
Georgia
Savannah Port expansion and Atlanta distribution hub growth generate Southeast corridor platform demand. The Federal Motor Carrier Safety Administration's ELD mandate compresses carrier matching timelines for Port of Savannah drayage operators. Arrive Logistics captures spot-market procurement shifts among Atlanta-based retail and manufacturing shippers.
Ohio
Columbus and Cleveland distribution clusters anchor Midwest manufacturing supply chain digitization. Ohio's central location creates backhaul optimization demand for AI-driven capacity forecasting. Echo Global Logistics serves automotive and industrial verticals with automated truckload tendering across the I-70 and I-80 corridors.
United States Digital Freight Forwarding Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, creating a tiered structure where scale and specialization coexist. Publicly traded platforms leverage balance sheet capacity for carrier network expansion, while venture-backed specialists prioritize API-first architecture and vertical workflow depth. Three archetypes dominate: asset-light matching platforms, customs brokerage convergers, and rate transparency marketplaces. Competitive intensity centers on carrier liquidity acquisition and shipper ERP integration speed.
Within the customs brokerage convergence archetype, Flexport exemplifies integrated ocean freight digitization with automated customs filing. C.H. Robinson Worldwide anchors the asset-light matching tier through proprietary platform control over domestic truckload liquidity. Freightos occupies the rate transparency position across international air and ocean lanes. These three represent divergent strategic bets on where shipper willingness-to-pay concentrates.
| Leading Market Players |
|---|
| UniCargo |
| SILQ |
| C.H. Robinson Worldwide |
| Arrive Logistics |
| RXO |
| Uber Freight |
| Freightos |
| Echo Global Logistics |
| Flexport |
| Others |
Value Network & Pricing Analysis
FMC Ocean Shipping Reform Act certification requirements gate both NVOCC supply qualification and price differentiation simultaneously, forcing timestamp-verification technology investments that separate compliant forwarders from legacy brokers facing audit failures.
Pricing Analysis
Volume-discount tiering structures dominate platform economics, with enterprise shippers capturing 15-25% rate reductions against spot-market tariffs through annual committed volumes. Price differentiation hinges on API integration depth and real-time visibility telemetry quality, with premium tiers commanding margins for predictive capacity forecasting modules. Cost compression in the mid-market segment is intensifying because carrier liquidity aggregation has commoditized basic matching functionality. Small e-commerce shippers exhibit highest price sensitivity, while Fortune 500 logistics buyers prioritize integration velocity over per-shipment economics.
Supply Chain Analysis
The United States produces domestic truckload capacity through fragmented owner-operator networks concentrated in Texas, California, and Illinois freight corridors. Platform infrastructure draws from cloud computing services, GPS telemetry hardware, and electronic logging device manufacturers. Single-source vulnerability persists in rural carrier coverage where middleware gaps prevent digital tendering adoption. Distribution runs through API-first integrations with shipper enterprise resource planning systems, bypassing traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large e-commerce shippers whose procurement consolidation across Midwest and Southeast distribution networks forces platform price concessions and accelerates spot-market procurement fragmentation.
For Market Incumbents: Compound carrier liquidity advantages through exclusive API partnerships with midsize fleet operators in the I-35 and I-10 corridors, insulating against venture-backed entrants offering subsidized rates. Deepen predictive capacity forecasting R&D to maintain premium positioning as static rate-quoting competitors lose margin. Defensive moves must address the threat of customs brokerage convergence by Flexport and similar integrated platforms. For New Entrants and Emerging Players: Differentiate on rural corridor coverage where owner-operator technology debt has excluded incumbent platforms from penetrating spot agricultural and energy freight markets. Target Ohio and Georgia sub-regions where manufacturing and retail verticals show fastest procurement pattern fragmentation. Go-to-market leverage rests on mobile-first driver applications that eliminate middleware requirements for small carriers lacking enterprise IT infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed logistics intermediaries possessing captive shipper relationships but lacking API-native architecture for ERP integration. Long-term viability favors platforms with demonstrated carrier-side liquidity in port-rail-highway interchange markets. The signal to watch is FMCSA enforcement intensity expanding electronic logging device compliance requirements into additional freight corridors.| Strategic Initiative | Industry Significance |
|---|---|
| API-First ERP Integration | Cloud-native deployment models displace on-premises infrastructure as C.H. Robinson and competitors prioritize integration velocity. |
| Timestamp-Verification Technology Procurement | FMC detention and demurrage billing rules under OSRA 2022 force Los Angeles-Long Beach forwarders into compliance infrastructure investments. |
| Carrier Liquidity Aggregation | Uber Freight and RXO capture Interstate 35 and Interstate 10 corridor density through exclusive small fleet operator partnerships. |
| AI-Driven Predictive Capacity Forecasting | Machine learning modules command premium positioning by reducing deadhead miles for asset-light carriers in volatile spot markets. |
| Customs Brokerage Convergence | Flexport integrates ocean freight digitization with automated customs filing to create stickier shipper relationships in port-adjacent California markets. |
Research Methodology
Initial hypotheses were tested against primary input from freight procurement executives at e-commerce and retail shippers, carrier operations managers at midsize fleet operators, platform product directors at digital forwarders, and customs brokerage compliance officers, then refined through secondary validation against FMCSA enforcement bulletins, FMC OSRA implementation guidance, SEC 10-K filings from listed logistics platforms, and electronic logging device adoption surveys from carrier associations. Bottom-up transaction volume estimates triangulated against top-down market sizing from freight corridor density analysis.
Variance-decomposition framing separated volume growth from pricing mix effects across the projection horizon, with segmentation modeling across service type, technology deployment, end-user vertical, and cloud versus on-premises architecture. CAGRs derived from logistic curve fitting to platform adoption rates, with industry-specific inputs including FMCSA hours-of-service enforcement expansion timelines and e-commerce warehouse cluster development patterns in the Midwest and Southeast.
The analysis sits within stated boundaries; outcomes outside sustained FMCSA electronic logging device enforcement intensity or accelerated e-commerce distribution network expansion would require recalibration. Forecasts reflect documented assumptions about carrier API proliferation rates and shipper willingness-to-pay for predictive capabilities. Recalibration cycles align with material shifts in Federal Maritime Commission detention and demurrage billing rule implementation or Federal Motor Carrier Safety Administration compliance mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Turkey Freight and Logistics Market