
 Colombia Cold Chain Logistics Market | 2026-2036
Colombia Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Cold Chain Logistics Market Outlook
Temperature-controlled warehousing as a subscription service is restructuring how Colombian food processors procure cold storage, shifting capital expenditure into operational contracts. Megafin Logistica Para Alimentos anchors the protein and seafood vertical through dedicated blast-freezing infrastructure in Cartagena. DSV Colombia leverages its pan-Andean network to sustain cross-border refrigerated flows into Ecuador and Peru. Rentafrio differentiates through modular cold-room leasing for seasonal agricultural harvests in the coffee triangle.
Colombia cold chain logistics encompasses the integrated movement and storage of perishable goods under controlled thermal conditions, typically maintaining temperatures between minus twenty-five and fifteen degrees Celsius through mechanical refrigeration, thermal insulation, and real-time telemetry. The primary commercial purpose centers on preserving biochemical stability of food and pharmaceutical products from origin through final delivery. Warehousing commands the largest fixed-asset investment pool due to land and energy costs around major cities, while monitoring technology shows the fastest capability upgrade cycle as INVIMA and export buyers demand continuous data logs. Pharmaceutical product lines carry premium handling fees driven by Good Distribution Practice validation requirements.
INVIMA, Colombia's national food and drug surveillance institute, enforces temperature integrity standards for vaccine and biologic distribution that directly shape fleet investment decisions by logistics providers. The Ministry of Agriculture and Rural Development coordinates with regional health authorities to align cold chain infrastructure with rural food security programs and export certification protocols. Stakeholders must weigh energy cost trajectories against electrification timelines when committing to refrigerated fleet replacement cycles.
Market Dynamics
INVIMA's end-to-end temperature documentation mandates for vaccine shipments are forcing fleet-wide telemetry upgrades across Colombian logistics providers, compressing investment timelines and reshaping competitive capabilities.
Growth Catalysts
- INVIMA Traceability Mandates:Colombia's national pharmaceutical regulator now requires continuous temperature logs for all vaccine distribution, creating immediate demand for real-time monitoring infrastructure.
- Biologics Expansion:Temperature-sensitive pharmaceutical products are commanding dedicated refrigerated capacity as cold-chain-validated handling becomes non-negotiable for export certification.
- Bogotá Savanna Concentration:Perishable export volumes to North American markets are clustering around the capital's logistics corridor, driving fixed-asset investment in that geography.
Market Restraints
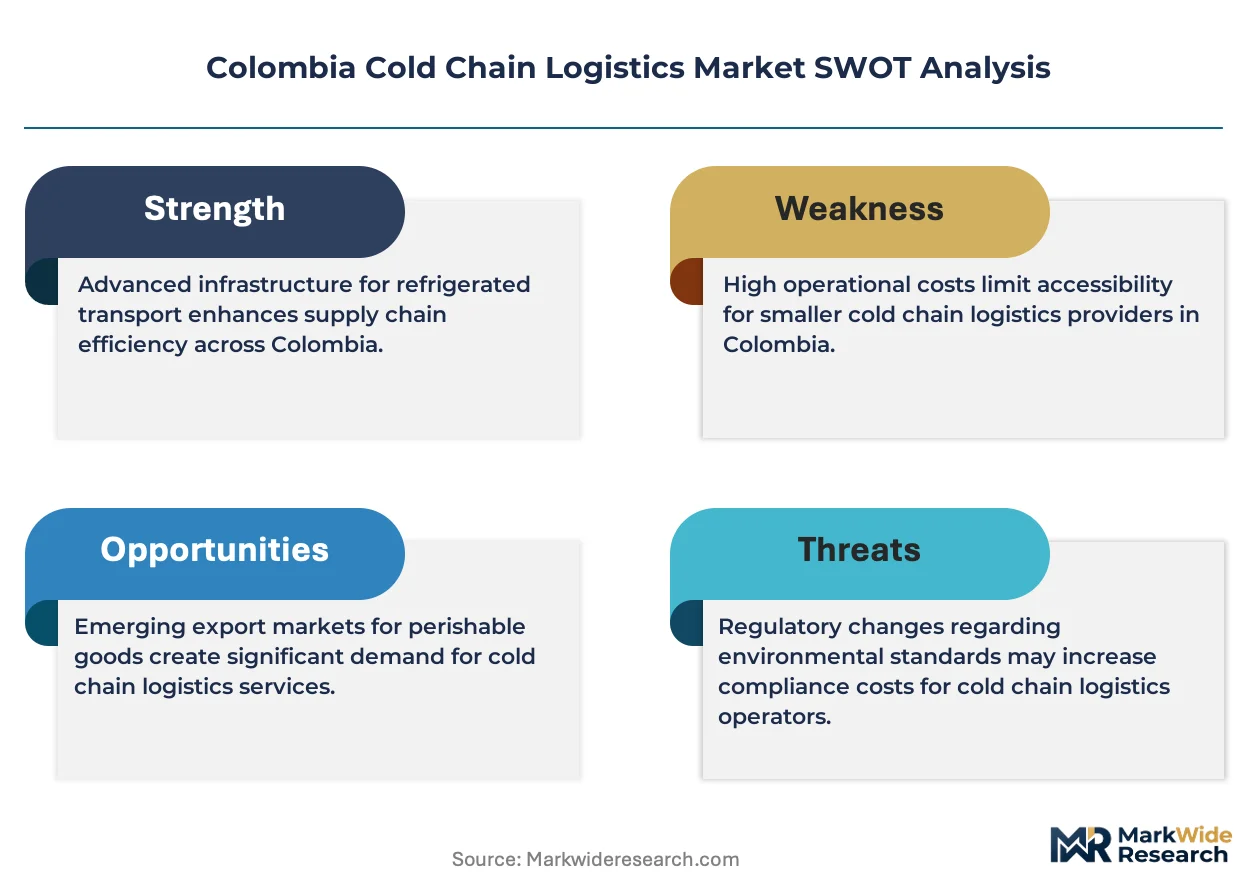
- Energy Cost Volatility:Grid electricity and diesel price swings directly compress margins for refrigerated warehousing operations, particularly in land-constrained urban zones.
- Equipment Supply Concentration:Refrigeration unit manufacturing concentrates among a narrow supplier base, creating lead-time vulnerability for fleet expansion programs.
- Good Distribution Practice Validation:Pharmaceutical handling certification demands specialized facility design that extends project timelines and locks up capital.
Strategic Opportunities
- Coffee Triangle Seasonality:Modular cold-room leasing for agricultural harvest peaks in Caldas, Quindío, and Risaralda offers asset-light revenue capture.
- Cross-Andean Integration:Refrigerated flows into Ecuador and Peru remain underdeveloped relative to trade potential, opening corridor development prospects.
- Subscription Warehousing:Temperature-controlled storage as an operational contract rather than capital expenditure is penetrating mid-sized food processor segments.
Industry Challenges
- Telemetry Integration Complexity:Legacy warehouse management systems require substantial reconfiguration to ingest continuous temperature data streams mandated by regulators.
- Certified Technician Scarcity:Refrigeration mechanics with pharmaceutical-grade validation experience are concentrated in Bogotá, constraining regional expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Cold Chain Logistics Market |
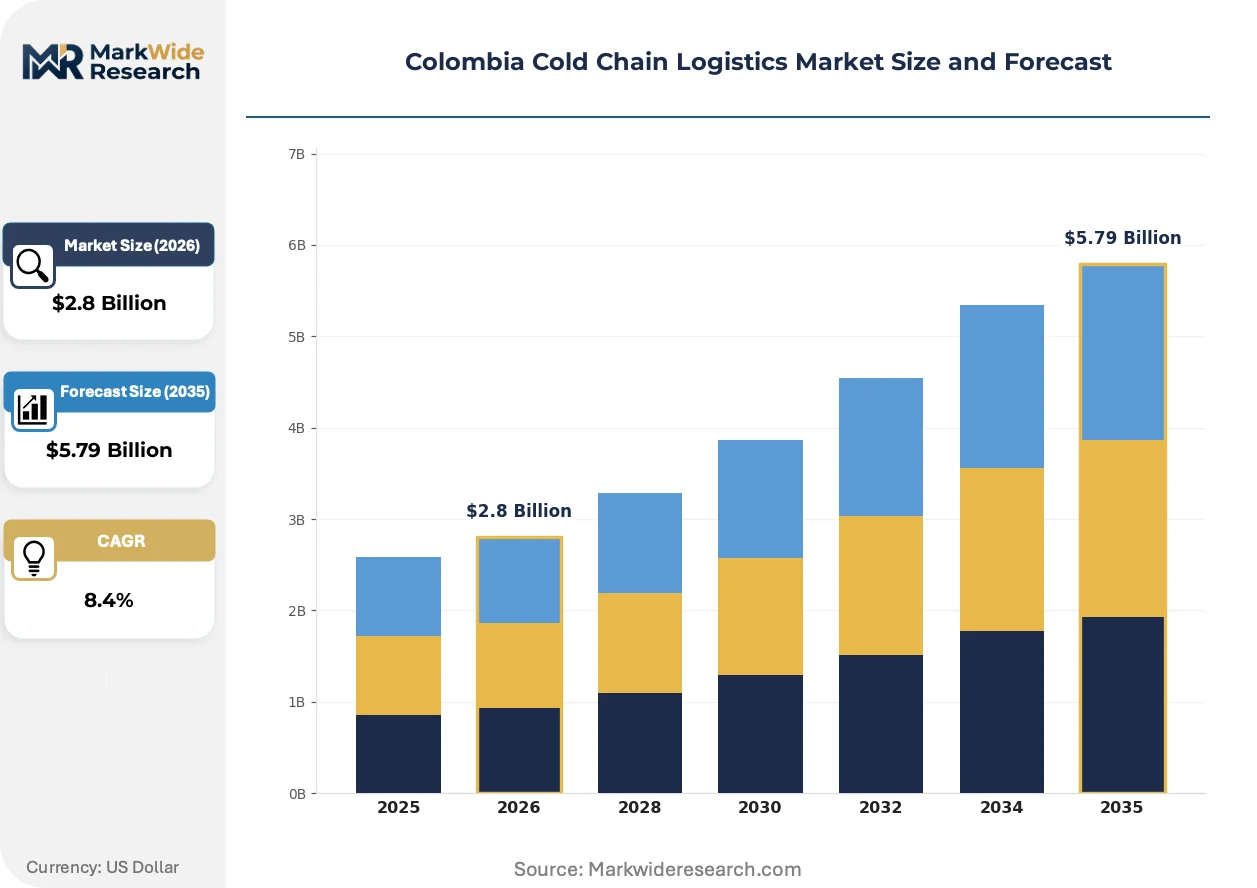
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Monitoring Product Type: Fresh Produce, Pharmaceuticals, Dairy Products, Frozen Foods End User: Food Retailers, Healthcare Providers, Restaurants, Supermarkets Technology: Refrigerated Trucks, Cold Storage Facilities, IoT Sensors, Temperature Control Systems |
| Companies Covered | Megafin Logistica Para Alimentos, Ransa Colombia (Colfrigos), Rentafrio, Frimac, DSV Colombia, Apix Logistica Especializada SAS, DHL Group, Transportes Iceberg De Colombia, GEODIS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Cold Chain Logistics Market Strategic Shifts
Cold chain operations in Colombia are undergoing capability compression as regulatory telemetry requirements, energy transition pressures, and procurement model evolution converge on provider economics.
Modular cold-room systems are modularizing how seasonal agricultural producers access refrigerated capacity. Coffee and avocado growers in the Eje Cafetero are adopting plug-and-play thermal units for harvest peaks rather than committing to year-round fixed infrastructure. This technology is modularizing capital deployment patterns across Colombia's dispersed agricultural zones.
INVIMA's pharmaceutical distribution standards are tightening documentation requirements for temperature-sensitive biologics. Logistics providers must now maintain continuous data logs from origin through final delivery, with audit trails subject to regulatory inspection. Vaccine and biologic shipments face the steepest compliance burden, driving investment in validated cold chain infrastructure.
Food processors are restructuring how they procure cold storage, abandoning owned-asset models in favor of operational contracts with third-party providers. Subscription-based warehousing allows processors to match refrigerated capacity to seasonal production cycles without carrying fixed costs through low-utilization periods. This pattern is most visible among mid-sized protein and seafood handlers in Cartagena and Barranquilla.
Colombia Cold Chain Logistics Market Segmentation
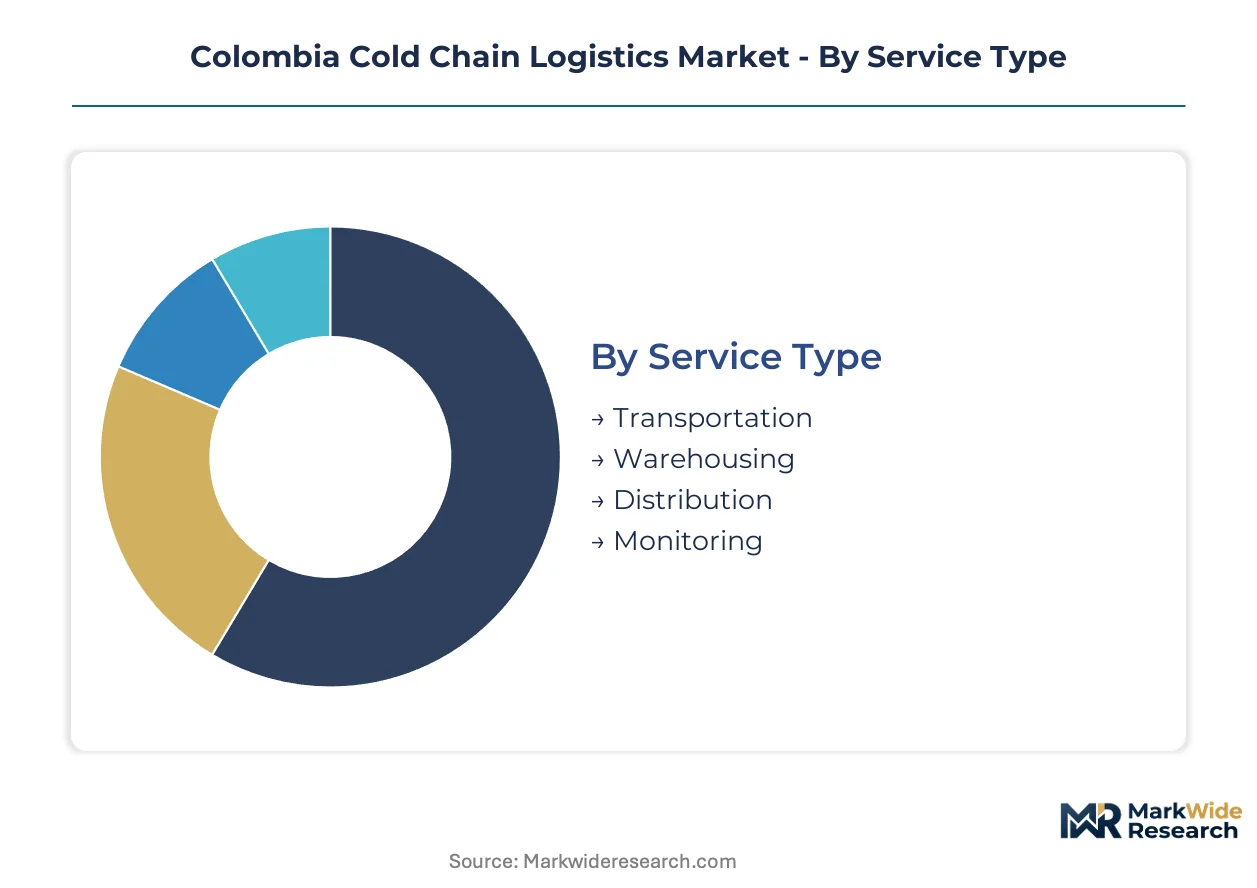
Colombia's cold chain logistics market segments around service delivery modes, product thermal requirements, and customer operational profiles. Each dimension carries distinct margin structures and regulatory burdens that shape provider investment priorities.
Service Type:
Refrigerated fleet and facility upgrade cycles concentrate investment differently across service modalities, with telemetry mandates compressing replacement timelines for monitoring-intensive segments.
- Transportation:Mobile refrigeration units maintain controlled thermal environments across road networks, with diesel-electric hybrid systems gaining traction amid energy cost volatility. Demand clusters around Bogotá's savanna corridor for perishable exports to North American markets, driven by INVIMA-validated handling requirements for pharmaceutical shipments.
- Warehousing:Fixed cold storage infrastructure commands the largest capital deployment pool due to land scarcity and electricity costs around major Colombian cities. Subscription-based procurement models are restructuring how mid-sized food processors access capacity, converting capital expenditure into operational contracts.
- Distribution:Consolidated last-mile delivery networks coordinate multi-temperature loads across urban and rural zones. Cross-border refrigerated flows into Ecuador and Peru remain underdeveloped relative to trade potential.
- Monitoring:Real-time telemetry systems capture continuous temperature data streams for regulatory compliance and quality assurance. INVIMA's end-to-end documentation mandates for vaccine distribution are forcing fleet-wide upgrades.
Warehousing sits at the top of the volume ranking, with monitoring climbing the fastest.
Product Type:
Product thermal profiles determine facility design specifications and handling fee structures, with pharmaceutical-grade validation commanding premium margins over food-grade operations.
- Fresh Produce:Temperature-sensitive fruits and vegetables require rapid cooling and consistent humidity control to arrest respiration and spoilage. Avocado and coffee exporters in the Eje Cafetero drive seasonal demand spikes for modular cold-room capacity.
- Pharmaceuticals:Biologics and vaccines demand validated cold chain infrastructure with continuous data logging and Good Distribution Practice certification. INVIMA traceability mandates now require end-to-end temperature documentation for all vaccine shipments.
- Dairy Products:Chilled milk and derivative products require rapid post-processing cooling and uninterrupted cold chain integrity. Colombian dairy processors concentrate distribution around Bogotá and Medellín metropolitan zones.
- Frozen Foods:Blast-frozen proteins and prepared meals sustain extended shelf life through deep-freeze storage at minus eighteen degrees Celsius or below. Seafood handlers in Cartagena anchor dedicated freezing infrastructure investment.
Pharmaceuticals capture the highest margin tier, with fresh produce expanding most quickly.
End User:
Customer procurement sophistication varies sharply across end-user categories, with healthcare providers demanding validated compliance while food retailers prioritize cost-efficient throughput.
- Food Retailers:Supermarket chains and independent grocers require multi-temperature receiving and storage capacity aligned with promotional cycling and seasonal demand. Modern trade expansion in Colombian urban centers is upgrading cold chain specifications.
- Healthcare Providers:Hospitals and clinics handling vaccines and biologics mandate INVIMA-compliant temperature documentation with audit-ready data trails. This segment absorbs the steepest compliance burden and associated handling premiums.
- Restaurants:Foodservice operators procure refrigerated capacity for protein, dairy, and produce inputs with emphasis on reliability over advanced telemetry. Chain restaurant expansion is consolidating supplier relationships.
- Supermarkets:Large-format retail operators maintain dedicated receiving docks and back-of-house cold rooms with direct supplier integration. Private label growth is extending cold chain control upstream into processor networks.
Healthcare providers impose the most stringent requirements, with food retailers representing the deepest volume base.
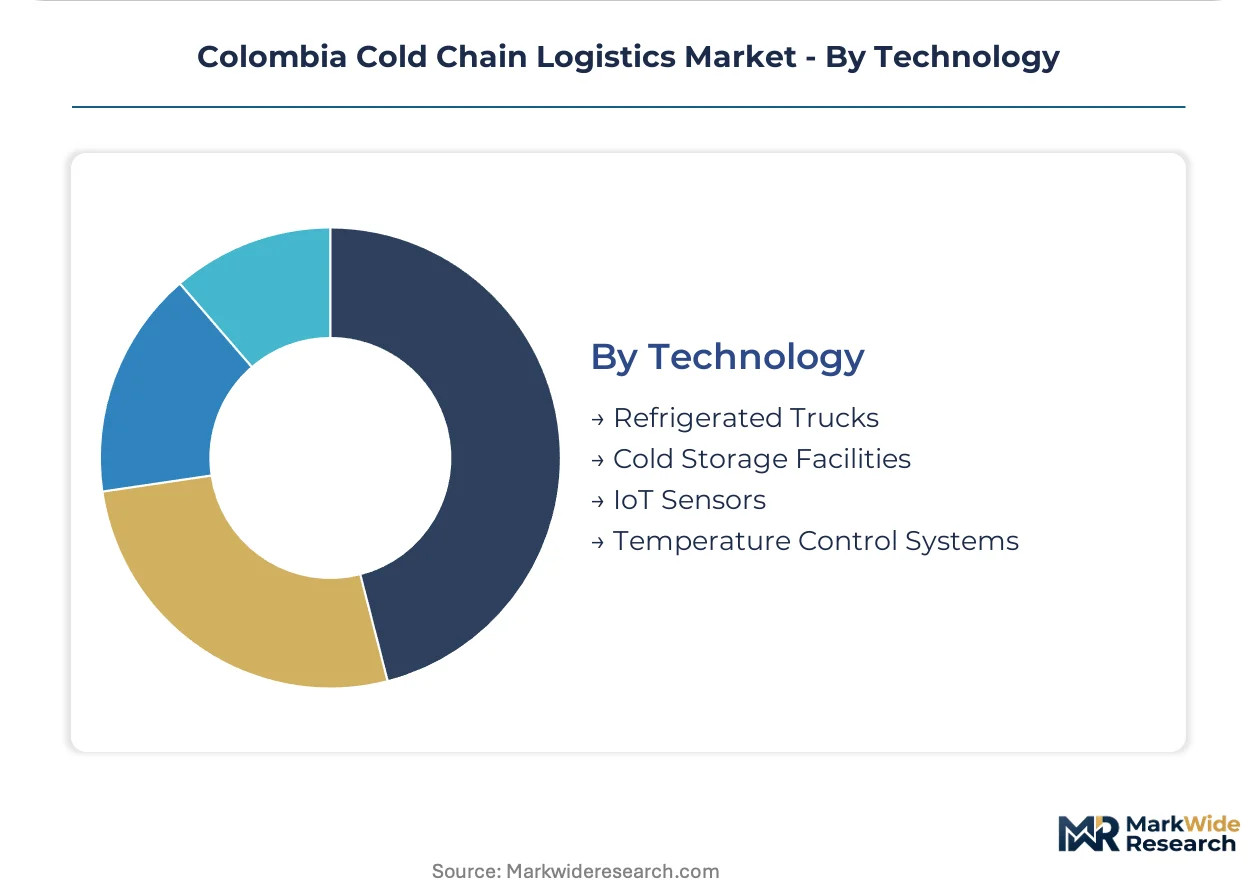
Technology:
Technology deployment patterns reflect a tension between proven mechanical systems and digital monitoring layers, with integration complexity rising as legacy infrastructure meets modern telemetry demands.
- Refrigerated Trucks:Diesel-powered and electric auxiliary transport refrigeration units maintain cargo temperatures across variable ambient conditions. Fleet operators weigh electrification timelines against energy cost trajectories when committing to replacement cycles.
- Cold Storage Facilities:Engineered buildings with high-performance insulation and mechanical refrigeration systems provide static temperature control for inventory holding. Land and electricity costs around Bogotá concentrate fixed-asset investment in that corridor.
- IoT Sensors:Wireless temperature and humidity loggers transmit continuous data to cloud-based monitoring platforms for real-time alerts and regulatory documentation. INVIMA mandates are accelerating adoption across pharmaceutical distribution networks.
- Temperature Control Systems:Programmable logic controllers and building management systems orchestrate cooling equipment operation for energy efficiency and temperature stability. Retrofit complexity constrains upgrade velocity in legacy facilities.
Cold storage facilities anchor capital deployment, with IoT sensors gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's cold chain infrastructure outpaces Ecuador and Peru in pharmaceutical-grade capacity, yet lags Chile in cross-border temperature-controlled corridor density. The Andean region exhibits sharp disparities in regulatory enforcement and fixed-asset investment across national boundaries.
Bogotá Savanna Corridor
Perishable export volumes to North American markets concentrate around Colombia's capital logistics zone, driving refrigerated fleet deployment. INVIMA pharmaceutical traceability mandates force warehouse operators to maintain continuous temperature documentation for vaccine distribution. The savanna corridor anchors the country's deepest pool of Good Distribution Practice-certified facilities.
Cartagena Caribbean Hub
Seafood and protein exporters demand dedicated blast-freezing infrastructure at Colombia's primary Caribbean port. The Ministry of Agriculture coordinates export certification protocols with regional health authorities to align cold chain standards with destination market requirements. Megafin Logistica Para Alimentos maintains specialized freezing capacity for international protein shipments.
Eje Cafetero Coffee Triangle
Seasonal avocado and coffee harvests create acute demand spikes for modular cold-room capacity across Caldas, Quindío, and Risaralda. Rentafrio deploys plug-and-play thermal units that convert capital expenditure into operational contracts for agricultural producers. Harvest peaks strain regional electricity grids and concentrate temporary refrigeration demand.
Medellín Metropolitan Zone
Dairy processors and pharmaceutical distributors cluster around Colombia's second city for chilled distribution to Antioquia's urban population. The national food and drug surveillance institute extends temperature integrity standards to regional vaccine distribution networks. Cold storage facility investment concentrates where land costs remain below Bogotá levels.
Cross-Andean Border Zones
Refrigerated flows into Ecuador and Peru remain underdeveloped relative to bilateral trade potential, creating corridor expansion opportunities. DSV Colombia leverages its pan-Andean network to sustain limited cross-border temperature-controlled shipments. Customs harmonization and regulatory alignment gaps constrain seamless cold chain integration.
Colombia Cold Chain Logistics Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade and export-certified segments, while mid-tier operators compete on seasonal agricultural contracts and subscription warehousing. The market structure concentrates validated cold storage capacity among logistics providers with INVIMA compliance infrastructure, with fragmentation increasing in seasonal and modular service tiers. Three archetypes dominate: integrated protein-seafood specialists, pharmaceutical-validated distributors, and asset-light modular leasing platforms. Competitive moves center on fleet telemetry upgrades for regulatory compliance and subscription model penetration into mid-sized food processor accounts.
Among Colombian cold chain specialists, Megafin Logistica Para Alimentos and Rentafrio exemplify divergent strategic positions. Megafin anchors the protein and seafood vertical through dedicated infrastructure investment, representing the integrated specialist archetype. Rentafrio occupies the asset-light modular tier, converting fixed refrigeration investment into operational contracts for seasonal agricultural producers. DSV Colombia sits within the multinational network category, leveraging cross-border capabilities that most domestic operators cannot replicate.
| Leading Market Players |
|---|
| Megafin Logistica Para Alimentos |
| Ransa Colombia (Colfrigos) |
| Rentafrio |
| Frimac |
| DSV Colombia |
| Apix Logistica Especializada SAS |
| DHL Group |
| Transportes Iceberg De Colombia |
| GEODIS |
| Others |
Value Chain & Pricing Dynamics
Telemetry integration across refrigerated fleets is compressing cost structures for Colombian logistics providers while concentrating pricing power among operators with validated INVIMA compliance infrastructure. Subscription-based warehousing contracts are displacing capital-intensive ownership models, redistributing margin capture toward asset-light platforms that can scale modular capacity seasonally.
Pricing Analysis
Capacity additions in Bogotá's savanna corridor are reshaping price floors for pharmaceutical-grade cold storage as INVIMA-validated facilities compete for biologics contracts. Three-tier pricing structure across premium, standard, and economy levels separates Good Distribution Practice-certified handlers from food-grade operators and seasonal agricultural lessors. Cost compression in standard-tier warehousing is intensifying because electricity volatility erodes fixed-cost absorption rates. Food retailers exhibit the deepest price sensitivity, while healthcare providers absorb premium handling fees for audit-ready temperature documentation.
Supply Chain Analysis
Regional distribution centers around Bogotá and Cartagena anchor hub-and-spoke patterns that concentrate temperature-controlled inventory before last-mile deployment. Equipment manufacturing for transport refrigeration units draws from China, the United States, and Germany, while diesel-electric hybrid systems rest on South Korean and Japanese battery component supply. Single-source vulnerability runs through narrow supplier bases for validated cold chain monitoring systems. Distribution runs through consolidated port-to-warehouse corridors with limited cross-Andean integration into Ecuador and Peru.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's cold chain logistics market functions as a regulatory compounder, with INVIMA's end-to-end temperature documentation mandates for vaccine shipments creating durable demand for validated infrastructure investment.
For Market Incumbents: Acquire modular cold-room assets in the Eje Cafetero to capture seasonal agricultural leasing revenue before asset-light competitors consolidate harvest-cycle relationships. Invest in telemetry integration capabilities that satisfy INVIMA audit requirements, defending against emerging entrants lacking pharmaceutical-grade validation experience. Backward integration into IoT sensor deployment reduces third-party dependency for regulatory compliance data streams. For New Entrants and Emerging Players: Launch via cross-Andean corridor development into Ecuador and Peru, where refrigerated trade flows remain underdeveloped relative to bilateral potential. Target mid-sized protein processors in Cartagena and Barranquilla with subscription warehousing contracts that convert their capital expenditure into operational relationships. Position around seasonal agricultural peaks in Caldas, Quindío, and Risaralda where harvest timing creates acute capacity shortages. For Investors and Strategic Acquirers: Valuations sit cheapest among regional food-grade operators lacking INVIMA certification, presenting consolidation targets for compliance infrastructure overlay. Long-term viability hinges on electrification readiness as diesel cost volatility and grid decarbonization timelines reshape fleet economics. Watch telemetry adoption velocity among second-tier warehousing operators as the inflection signal for regulatory compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| INVIMA Compliance Infrastructure Investment | Validated cold storage capacity captures premium handling fees from biologics distributors. |
| Modular Cold-Room Fleet Expansion | Plug-and-play thermal units convert agricultural capital expenditure into recurring operational contracts. |
| Cross-Andean Corridor Development | Refrigerated flows into Ecuador and Peru unlock underdeveloped bilateral trade potential. |
| Telemetry System Integration | Continuous temperature data streams satisfy regulatory mandates and reduce audit failure risk. |
| Subscription Warehousing Model Penetration | Operational contracts align processor costs with seasonal production cycles. |
Study Parameters
Direct dialogue with cold chain operations directors, pharmaceutical distribution managers, INVIMA regulatory affairs specialists, and agricultural cooperative procurement heads grounded qualitative findings in practitioner experience. Secondary validation drew from customs export records, INVIMA pharmaceutical traceability guidelines, Ministry of Agriculture rural infrastructure reports, and refrigerated fleet registration databases. Bottom-up capacity modeling and top-down trade flow analysis triangulated market sizing across service type, product thermal profile, and regional geography dimensions.
Segmentation outputs across transportation, warehousing, distribution, and monitoring modalities were projected over the analysis window using adoption curve modeling for telemetry integration and electrification timelines. Service-type splits, product thermal requirements, and end-user procurement sophistication formed the core segmentation framework. CAGRs were derived from fixed-asset investment cycles, regulatory compliance deadlines, and export volume trajectories without reliance on single-source projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy price volatility scenarios and refrigeration equipment supply disruption. Projections reflect documented assumptions regarding INVIMA enforcement consistency, cross-Andean customs harmonization progress, and electrification infrastructure deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Myanmar Freight and Logistics Market