
 Manufacturing Logistics Market | 2026-2036
Manufacturing Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Logistics Market Insights
Asset-light leasing models for automated warehousing fleets is reconfiguring competitive entry barriers, allowing mid-scale electronics manufacturers to deploy enterprise-grade logistics infrastructure without capital-heavy balance sheets. Deutsche Post DHL leverages its integrated freight-forwarding network to anchor contract logistics relationships across European automotive corridors. FedEx competes through time-definite manufacturing support services that synchronize inbound material flows with production windows at aerospace fabrication sites.
Manufacturing logistics encompasses the planning, execution, and control of physical material flows, information coordination, and inventory positioning required to feed production lines with specified components at defined intervals, typically operating within tolerance windows measured in hours or minutes for just-in-sequence operations. The discipline integrates automated guided vehicles, conveyor systems, and inventory management software to eliminate line stoppages and reduce work-in-process holding costs across multi-echelon supply networks. Warehousing equipment and automated guided vehicles represent mature, high-volume segments where margin pools have compressed due to equipment commoditization, while cloud-based platforms and real-time data analytics are expanding fastest as manufacturers prioritize predictive visibility over static ERP scheduling. RFID tracking and sensor integration now underpin most new deployments, with robotics adoption accelerating in food processing plants and pharmaceutical fabricators where contamination control and batch traceability requirements exceed manual handling capabilities.
The EPA regulates emissions from logistics fleets and warehousing equipment operating in US manufacturing zones, while OSHA mandates ergonomic and safety standards for automated material handling environments that directly influence robotics deployment specifications. REACH and RoHS frameworks in Europe restrict hazardous substances in conveyor components and battery systems, compelling suppliers to requalify material streams for electronics and consumer goods assemblers. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and digital product passport requirements will reshape supplier qualification criteria and logistics network design decisions.
Market Dynamics
Automotive OEMs are compressing inbound logistics tolerance windows to minutes, forcing warehouse operators to abandon static batch-picking for synchronized sequencing systems that feed assembly lines directly.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain fabricators across Germany and France are retrofitting refrigerant-handling protocols, generating demand for compliant hazardous-material logistics infrastructure.
- Just-in-sequence assembly:Stuttgart industrial clusters require precision inbound scheduling, pulling investment into automated guided vehicle fleets and real-time inventory positioning software.
- RFID-sensor convergence:Pharmaceutical plants are deploying integrated tracking layers to satisfy batch traceability mandates, expanding robotics adoption in contamination-controlled environments.
Market Restraints
- Lithium-ion battery cost volatility:Automated guided vehicle fleets face margin pressure from raw material price swings in cathode supply chains.
- Conveyor equipment commoditization:Standardized warehousing hardware has compressed supplier margins, limiting R&D reinvestment capacity among mid-tier manufacturers.
- REACH substance restrictions:Electronics assemblers must requalify conveyor components and battery systems, extending supplier onboarding timelines.
Strategic Opportunities
- Asset-light leasing models:Mid-scale electronics manufacturers can deploy enterprise-grade automated warehousing without capital-heavy balance sheets.
- Carbon-border adjustment mechanisms:Emerging compliance frameworks will reshape supplier qualification criteria, rewarding logistics providers with verified emissions tracking.
- Cloud-based predictive visibility:Real-time data analytics platforms are displacing static ERP scheduling, opening white space for software-native entrants.
Industry Challenges
- Legacy ERP integration complexity:Manufacturers struggle to overlay predictive analytics onto decades-old scheduling systems without disrupting live production.
- Automation technician scarcity:Deployment of robotic handling systems outpaces availability of certified maintenance personnel in industrial clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Logistics Market |
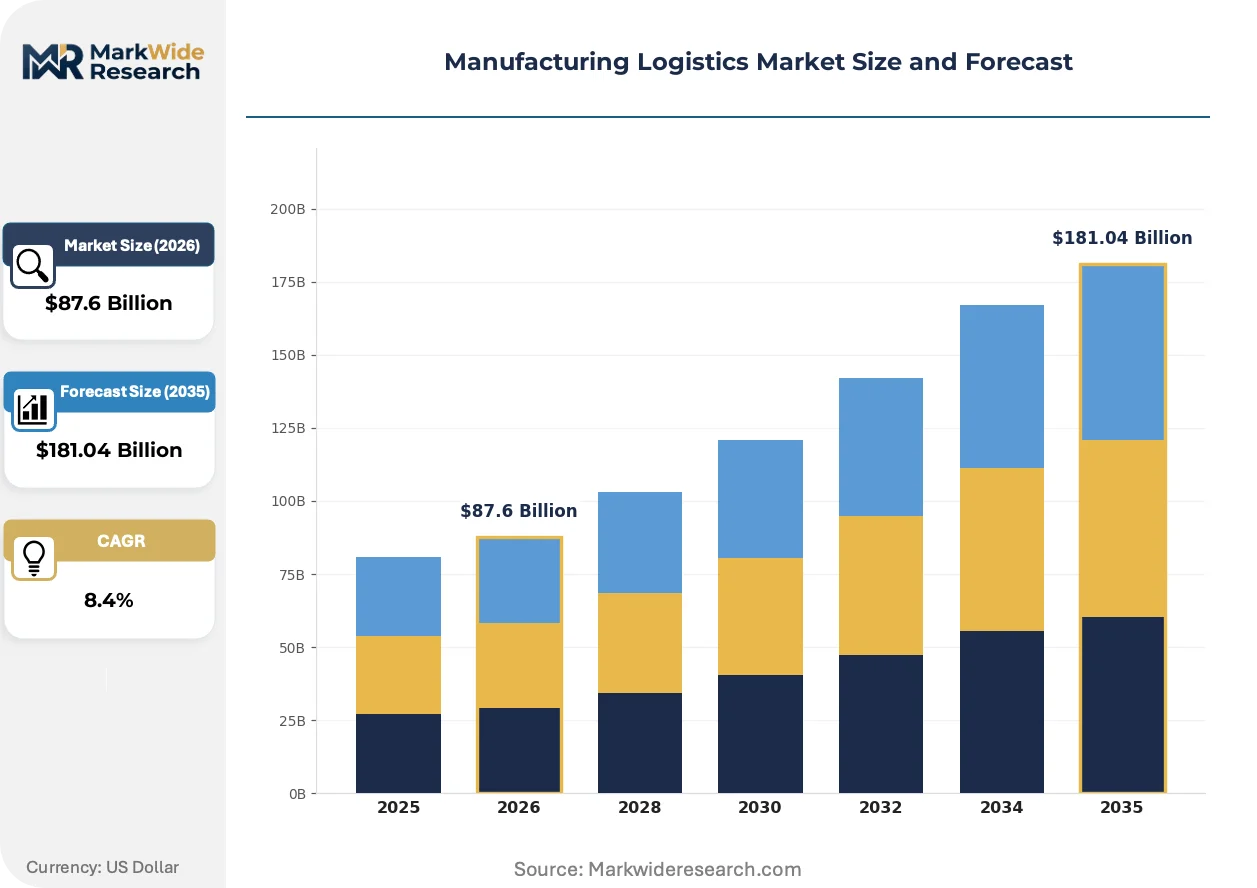
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warehousing Equipment, Automated Guided Vehicles, Conveyor Systems, Inventory Management Software, Sorting Systems Technology: RFID Tracking, Cloud-Based Platforms, Robotics, Real-Time Data Analytics, Sensor Integration Application: Just-In-Time Delivery, Supply Chain Optimization, Material Handling, Order Fulfillment, Production Scheduling End User: Electronics Manufacturers, Aerospace Producers, Food Processing Plants, Pharmaceutical Fabricators, Consumer Goods Assemblers |
| Companies Covered | Deutsche Post DHL, United Parcel Service, FedEx, A.P. Moller - Maersk, DSV, Kuehne + Nagel, DB Schenker, CEVA Logistics, Expeditors International of Washington, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Logistics Market Trends and Innovations
Physical automation is converging with digital orchestration layers, compressing the gap between warehouse execution and production planning into closed-loop systems that self-correct in real time.
Automated guided vehicles now coordinate directly with conveyor networks and robotic picking arms to eliminate manual handoffs in food processing plants. Pharmaceutical fabricators are deploying these integrated cells fastest, driven by contamination control requirements that exceed manual handling capabilities. The technology is migrating from isolated material transport toward fully orchestrated production-floor logistics that synchronize with MES systems.
EPA emissions regulations for logistics fleets and warehousing equipment are tightening operating parameters in US manufacturing zones. OSHA ergonomic mandates for automated material handling environments are influencing robotics deployment specifications directly. Aerospace fabrication sites in the US are responding by prioritizing time-definite inbound services that consolidate regulatory compliance with production window synchronization.
Buyers are unbundling after-sales service from equipment procurement, treating maintenance and software updates as separate subscription decisions. Electronics manufacturers are leading this shift, pressuring traditional vendors to modularize their offerings. Germany's automotive corridors exhibit this pattern most acutely, where OEMs negotiate logistics contracts around uptime guarantees rather than asset ownership.
Manufacturing Logistics Market Segmentation
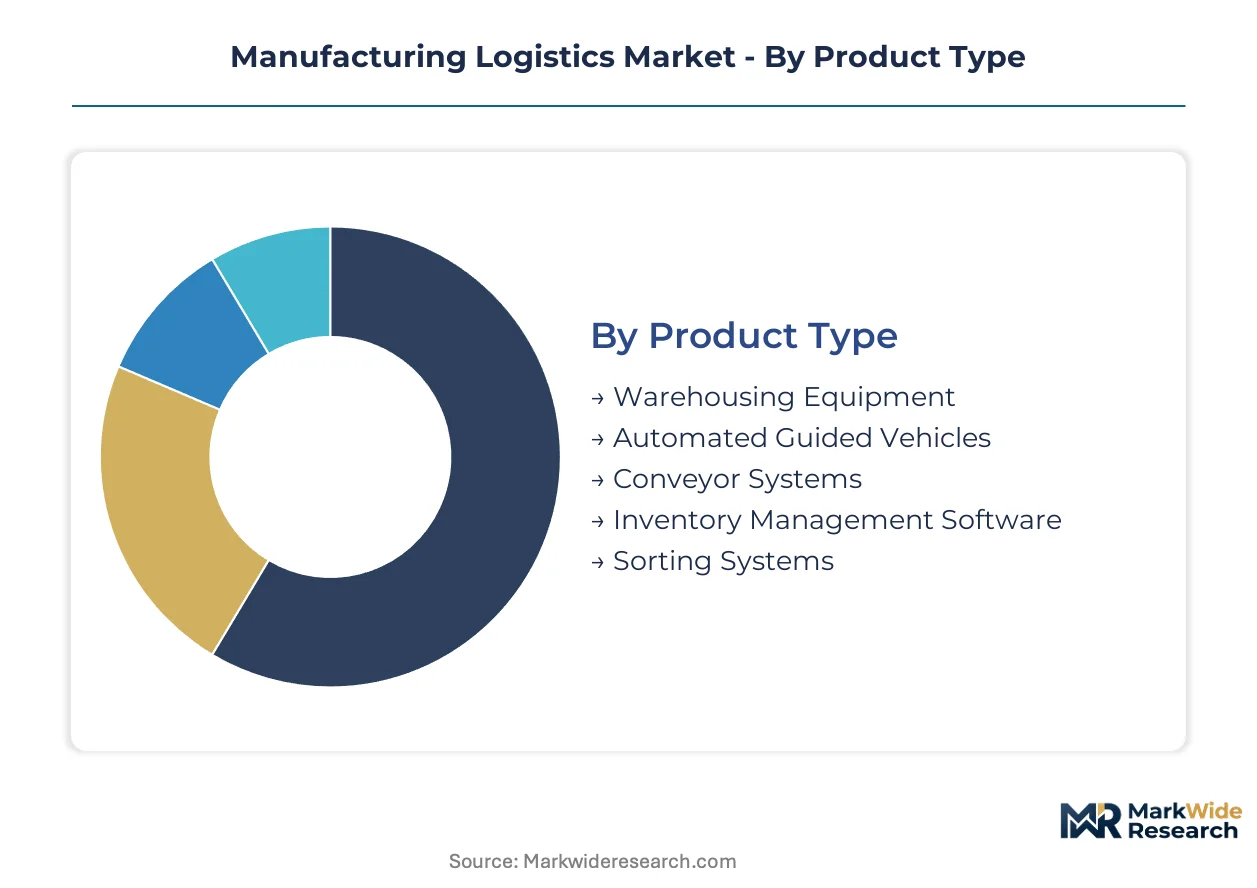
Segmentation in manufacturing logistics reveals how capital intensity, regulatory exposure, and automation maturity fragment procurement patterns across equipment buyers. Understanding these divides exposes where margin pools concentrate and which technology layers command pricing power.
Product Type:
Mature hardware segments compete on scale economies while software-enabled systems capture expanding margin pools through recurring revenue models.
- Warehousing Equipment:Racking systems, pallet jacks, and manual handling infrastructure constitute the installed base across legacy facilities. Electronics manufacturers in Shenzhen and Guadalajara still deploy these assets where labor costs justify manual throughput over automation capex.
- Automated Guided Vehicles:Lithium-ion powered mobile robots execute point-to-point material transport without fixed infrastructure. Stuttgart automotive clusters demand these fleets for just-in-sequence assembly lines where tolerance windows compress to minutes.
- Conveyor Systems:Belt and roller configurations dominate high-volume, predictable flow environments. Food processing plants in the Netherlands deploy stainless steel variants to satisfy EU hygiene mandates.
- Inventory Management Software:Cloud-native platforms displace on-premise ERP modules with predictive positioning algorithms. Pharmaceutical fabricators prioritize these systems for batch traceability compliance under FDA and EMA frameworks.
- Sorting Systems:Automated parcel and component segregation equipment handles high-mix, high-velocity distribution. E-commerce fulfillment centers in Poland and Ohio represent concentrated demand nodes.
Warehousing equipment handles the majority of throughput; inventory management software is the fastest mover on share.
Technology:
Adoption intensity correlates with regulatory pressure and contamination control requirements, creating divergent deployment timelines across end-use verticals.
- RFID Tracking:Passive and active radio-frequency identification tags enable item-level visibility without line-of-sight scanning. Aerospace producers in Toulouse and Seattle embed these in component containers to satisfy traceability mandates from EASA and FAA.
- Cloud-Based Platforms:Distributed computing architectures centralize logistics orchestration across multi-site manufacturing networks. Mid-scale electronics manufacturers in Vietnam leverage these to avoid capital-heavy infrastructure investments.
- Robotics:Articulated arms and collaborative robots execute picking, packing, and palletizing in contamination-controlled environments. Pharmaceutical fabricators in Basel and Boston deploy these fastest where batch integrity requirements exceed manual handling capabilities.
- Real-Time Data Analytics:Stream processing engines convert sensor feeds into actionable positioning decisions. Automotive OEMs in Wolfsburg use these to synchronize inbound supplier flows with assembly line takt times.
- Sensor Integration:Temperature, vibration, and proximity detectors feed closed-loop control systems. Cold-chain operators across Germany retrofit these to comply with EU F-Gas Regulation refrigerant monitoring requirements.
RFID tracking commands the widest installed base; robotics is climbing the fastest as contamination control mandates harden.
Application:
Operational priorities shift from cost minimization toward synchronization precision as production windows tighten and penalty clauses for line stoppages escalate.
- Just-In-Time Delivery:Synchronized inbound logistics eliminate buffer inventory through precisely timed supplier shipments. Toyota-derived methodologies dominate automotive corridors in Kentucky and Aichi Prefecture.
- Supply Chain Optimization:Network design and inventory positioning algorithms minimize total landed cost across multi-echelon distribution. Consumer goods assemblers in São Paulo deploy these to navigate Brazil's complex interstate tax regimes.
- Material Handling:Physical movement, storage, and protection of goods throughout manufacturing processes. Food processing plants in Denmark prioritize hygienic handling protocols under EFSA guidelines.
- Order Fulfillment:Pick, pack, and ship operations connecting finished goods to downstream distribution channels. Electronics manufacturers in Malaysia specialize these flows for high-velocity smartphone exports.
- Production Scheduling:Algorithms aligning material availability with capacity constraints and demand forecasts. Aerospace fabricators in Broughton and Charleston depend on these to manage long-lead composite component flows.
Material handling absorbs the largest operational spend; just-in-time delivery is gaining share fastest as tolerance windows compress.
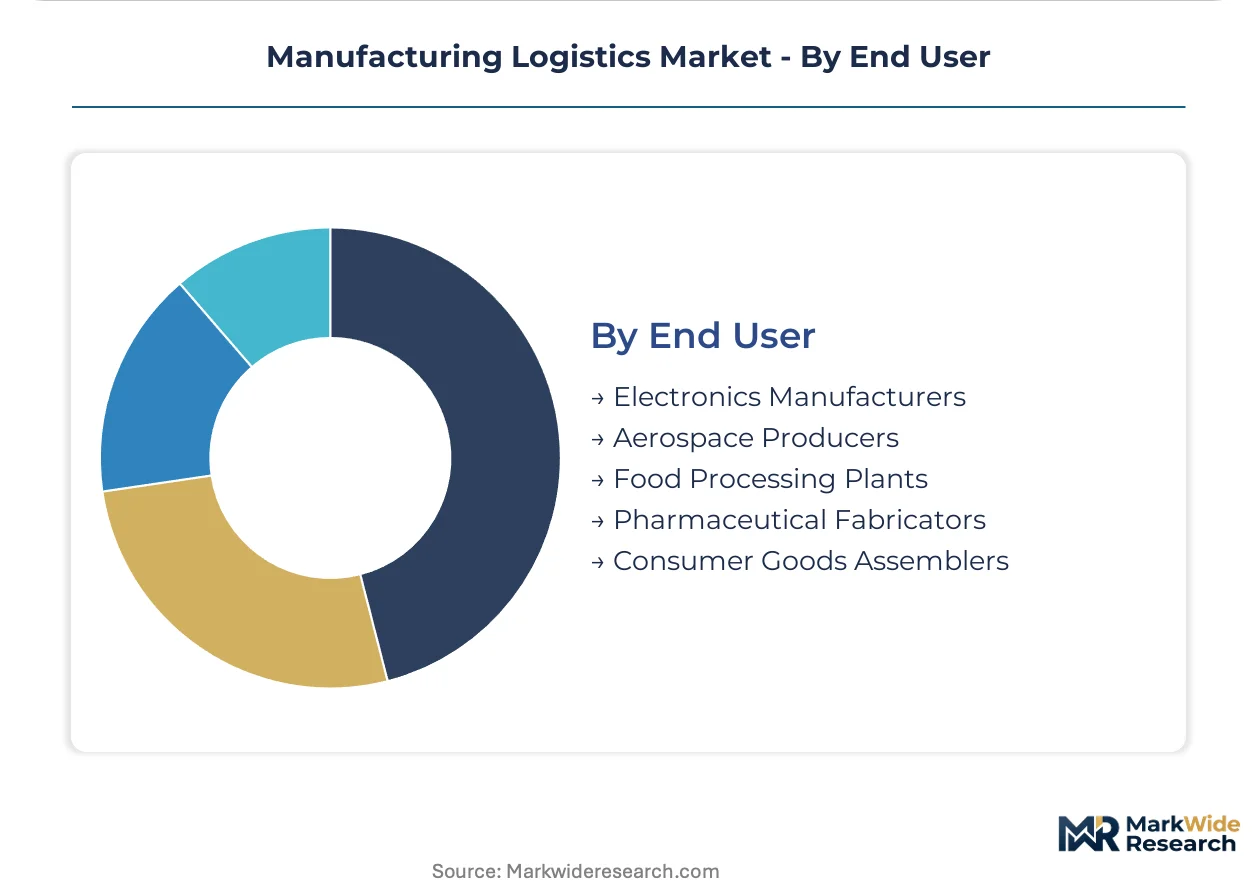
End User:
Vertical-specific regulatory burdens and contamination thresholds create divergent technology requirements that fragment vendor competitive positioning.
- Electronics Manufacturers:High-mix, high-velocity assembly operations demanding rapid changeover capabilities. Facilities in Penang and Monterrey prioritize automated storage and retrieval systems for component proliferation management.
- Aerospace Producers:Long-lead fabrication cycles with stringent traceability and certification requirements. Boeing and Airbus supplier networks in Wichita and Hamburg deploy time-definite logistics services synchronized with fabrication windows.
- Food Processing Plants:Hygiene-mandated environments requiring washdown-capable equipment and temperature-controlled flows. EU operators face escalating compliance costs under EFSA and national veterinary inspection regimes.
- Pharmaceutical Fabricators:Contamination-controlled cleanrooms with batch-level serialization mandates. FDA and EMA good manufacturing practice rules drive robotics adoption exceeding manual handling capabilities.
- Consumer Goods Assemblers:High-volume, seasonal demand patterns with compressed fulfillment windows. Procter & Gamble and Unilever operations in Ohio and Rotterdam optimize these flows through predictive inventory positioning.
Electronics manufacturers represent the largest addressable base; pharmaceutical fabricators are expanding most quickly on compliance-driven automation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in precision components and finished vehicles are redrawing logistics network configurations across major manufacturing hubs. Countries with trade surpluses in automotive and electronics are expanding outbound cold-chain and hazardous-material handling capacity, while deficit markets prioritize inbound synchronization infrastructure.
Germany
Stuttgart and Wolfsburg automotive clusters demand minute-level inbound sequencing for just-in-time assembly lines. The EU F-Gas Regulation mandates refrigerant-handling protocol upgrades across cold-chain fabricators in Bavaria and Baden-Württemberg. Industrial corridors around Munich are retrofitting automated guided vehicle fleets to synchronize multi-tier supplier networks.
United States
Aerospace fabrication sites in Seattle and Charleston require time-definite logistics services aligned with long-lead composite component flows. EPA emissions regulations tighten operating parameters for logistics fleets serving manufacturing zones in Michigan and Ohio. Kentucky automotive corridors deploy synchronized sequencing systems feeding Toyota-derived assembly methodologies.
China
Shenzhen electronics manufacturers balance high-mix assembly operations with automated storage and retrieval systems for component proliferation management. MIIT industrial standards and dual carbon goals accelerate warehouse electrification mandates across Yangtze River Delta facilities. Pearl River Delta clusters retrofit conveyor networks to satisfy GB hygiene protocols for food-grade material handling.
Japan
Aichi Prefecture automotive producers maintain compressed tolerance windows for inbound supplier shipments. METI energy efficiency standards drive lithium-ion fleet adoption in Osaka-Kobe logistics corridors. Nagoya industrial clusters integrate RFID tracking layers with manufacturing execution systems for batch-level traceability.
India
Penang and Monterrey electronics assemblers prioritize rapid changeover capabilities through automated component positioning. PLI scheme incentives accelerate capital expenditure in Gujarat and Tamil Nadu logistics infrastructure. Maharashtra industrial zones deploy cloud-native inventory platforms to avoid capital-heavy balance sheet commitments.
Manufacturing Logistics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure where scale economies separate tier-one orchestrators from mid-scale equipment vendors. The vendor base concentrates around freight-forwarding networks with integrated contract logistics capabilities and software-native visibility platforms displacing static ERP modules. Two archetypes dominate: asset-heavy integrated carriers anchoring multi-year manufacturing contracts, and asset-light technology vendors leasing automated infrastructure to mid-scale producers. Competitive moves center on strategic partnerships bridging hardware procurement with subscription-based software layers, plus geographic expansion into industrial clusters with tightening tolerance windows.
Among integrated freight-forwarding networks, Deutsche Post DHL anchors contract logistics relationships across European automotive corridors, while FedEx exemplifies time-definite manufacturing support services synchronizing inbound material flows with production windows. DSV occupies a position within the asset-light transformation tier, representing mid-scale entrants deploying enterprise-grade infrastructure without capital-heavy balance sheets. These three collectively illustrate how competitive positioning fragments between system-scale orchestration and specialized synchronization services.
| Leading Market Players |
|---|
| Deutsche Post DHL |
| United Parcel Service |
| FedEx |
| A.P. Moller - Maersk |
| DSV |
| Kuehne + Nagel |
| DB Schenker |
| CEVA Logistics |
| Expeditors International of Washington |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's conveyor equipment manufacturing base is forcing European suppliers to abandon premium positioning and absorb margin compression to defend share against subsidized imports. This utilization imbalance cascades through procurement decisions, pushing automotive OEMs toward asset-light leasing models that transfer capital risk to logistics providers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around uptime guarantees rather than equipment ownership, compressing upfront margins while expanding recurring service revenue pools. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified pharmaceutical fabricators from food-grade assemblers and general industrial users. Cost compression in standard-grade conveyor systems is intensifying because Chinese manufacturers are flooding European distribution channels with undifferentiated hardware. Mid-scale electronics manufacturers exhibit highest price sensitivity, while pharmaceutical fabricators accept premium tiers for contamination-controlled robotics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates strategic sourcing decisions for automated guided vehicle fleets and lithium-ion battery systems. Component manufacturing concentrates in Germany, China, and South Korea, with final assembly gravitating toward industrial clusters in Stuttgart, Wolfsburg, and Munich. Supply chains draw from cathode materials, rare-earth magnets, and precision-machined aluminum frames. Single-source vulnerability in semiconductor motor controllers threatens production continuity. Distribution runs through integrated freight-forwarding networks with embedded contract logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by automotive production restocking across European corridors. Capital expenditure normalization in Stuttgart and Wolfsburg clusters signals the upswing phase.
For Market Incumbents: Entrench contract logistics relationships through multi-year uptime guarantees that lock out asset-light competitors. Deepen backward integration into automated guided vehicle battery systems to capture margin pools currently leaking to Korean suppliers. The threat of software-native visibility platforms displacing static ERP modules demands defensive certification investment in FDA and EMA traceability standards. For New Entrants and Emerging Players: Build out cloud-native inventory positioning platforms targeting mid-scale electronics manufacturers in Vietnam and Malaysia seeking to avoid capital-heavy balance sheet commitments. The most penetrable segment comprises food processing plants retrofitting stainless steel conveyor networks for EU hygiene mandates. A subscription-based go-to-market angle bypasses incumbent advantages in equipment financing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-native orchestration platforms displacing legacy ERP scheduling modules. Long-term viability favors vendors with embedded regulatory compliance capabilities spanning REACH substance tracking and EU F-Gas refrigerant protocols. The acquisition target archetype combines robotics deployment expertise with pharmaceutical cleanroom certification. Watch lithium-ion raw material price stabilization as the inflection signal for fleet expansion capex.| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Leasing Model | Mid-scale electronics manufacturers in Vietnam deploy enterprise-grade infrastructure without balance sheet strain. |
| Cloud Platform Integration | Real-time data analytics displace static ERP scheduling in Stuttgart automotive corridors. |
| Regulatory Certification Investment | FDA and EMA traceability standards lock in pharmaceutical fabricator relationships. |
| Backward Integration into Battery Systems | Cathode supply chain control defends margins against Korean supplier pricing pressure. |
| Geographic Expansion into Industrial Clusters | Wolfsburg and Munich corridors offer concentrated just-in-sequence demand. |
Research Methodology
The analysis maps automated guided vehicle fleets, conveyor systems, inventory management software, and cloud-based orchestration platforms, each validated through plant engineers at automotive OEMs, logistics procurement leads at electronics manufacturers, aftermarket service heads at warehousing equipment vendors, and regulatory compliance officers at pharmaceutical fabricators. Primary interview data triangulates against customs trade flows, SEC filings from integrated carriers, EU F-Gas regulatory databases, and automotive production cluster reports. Bottom-up equipment deployment counts and top-down contract logistics revenue estimates converge through iterative reconciliation.
Fixed assumptions across the projection horizon hold EU regulatory stringency constant and assume no discontinuity in lithium-ion supply chain geography. Segmentation dimensions modeled span product type, technology layer, application intensity, and end-use vertical regulatory burden. CAGRs emerge from logistic curve fitting to adoption saturation levels, with inputs including automotive takt time compression rates and pharmaceutical batch traceability mandate timelines.
Stress conditions across cathode material price volatility, REACH substance restriction expansion, and carbon-border adjustment mechanism implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed documented assumptions about regulatory stability and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Peru Cold Chain Logistics Market