
 North America Shipping Agency Market | 2026-2036
North America Shipping Agency Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shipping Agency Market Analytics
Digital documentation platforms are rebalancing traditional paper-based customs clearance economics, compressing processing margins while expanding throughput capacity. GAC North America leverages its port management infrastructure across U.S. Atlantic and Gulf terminals to sustain premium pricing on project-based energy contracts. Moran Shipping Agency anchors its competitive position through specialized pilotage and tug coordination services in the Northeast harbor complex. Neptune Shipping Agency differentiates via integrated logistics support for pharmaceutical cold-chain importers operating under strict temperature-compliance protocols.
North America shipping agencies coordinate vessel arrivals, cargo documentation, customs facilitation, and terminal logistics on behalf of maritime freight principals, typically operating through networks of licensed port captains and bonded customs brokers who manage compliance with destination-country trade regulations. Freight forwarding commands the largest revenue pool within service type segmentation due to its direct linkage with cross-border manufacturing supply chains, while customs clearance is gaining share fastest as post-pandemic trade enforcement intensifies document scrutiny. Among industry verticals, energy and pharmaceuticals represent the most defensible margin pools because both sectors require specialized handling certifications and project-based delivery models that resist commoditization.
The U.S. Federal Maritime Commission enforces ocean shipping reform provisions that limit detention and demurrage billing practices, directly constraining how port management providers structure contractual terms with beneficial cargo owners. Health Canada and the U.S. FDA jointly regulate pharmaceutical import documentation standards, creating compliance barriers that favor agencies with established cold-chain validation capabilities. Stakeholders must monitor evolving customs automation mandates from both the Canada Border Services Agency and U.S. Customs and Border Protection, as machine-readable filing requirements will determine which agencies retain bonded status and client access.
Market Dynamics
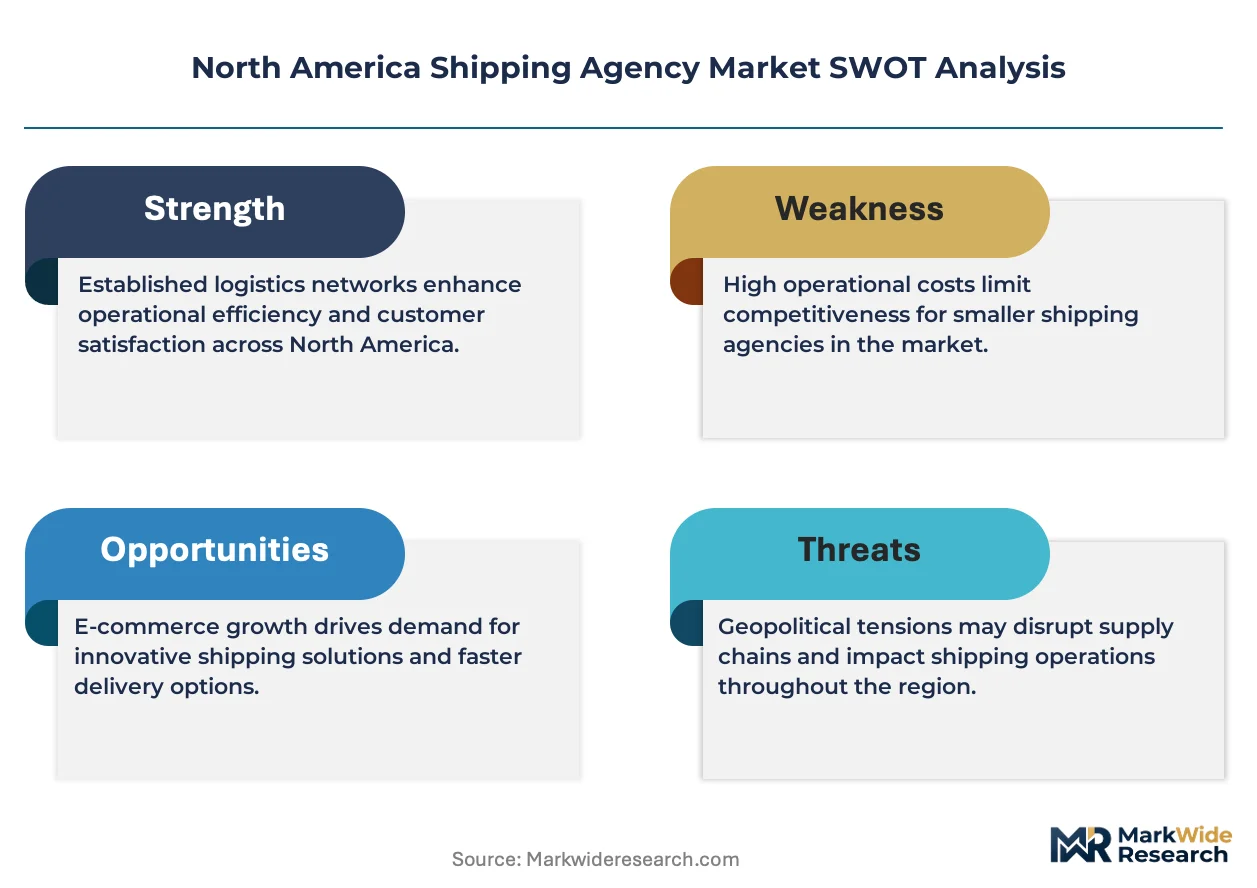
The U.S. Federal Maritime Commission's updated detention and demurrage billing rules are compressing margin structures for port management providers while simultaneously accelerating the shift toward integrated digital documentation platforms across customs clearance workflows.
Growth Catalysts
- Energy export corridors:The Gulf Coast concentration spanning Texas and Louisiana is generating sustained contract volumes for specialized vessel coordination and project cargo handling services tied to liquefied natural gas and petroleum product movements.
- E-commerce logistics integration:Online retail fulfillment networks are consolidating freight forwarding with bonded customs brokerage, creating bundled service demand that reduces principal coordination costs across cross-border supply chains.
- Digital customs automation:The Canada Border Services Agency and U.S. Customs and Border Protection machine-readable filing mandates are favoring agencies with established electronic data interchange infrastructure and bonded status maintenance capabilities.
Market Restraints
- Regulatory cost compression:The U.S. Federal Maritime Commission's ocean shipping reform provisions directly constrain how port management providers structure detention and demurrage terms with beneficial cargo owners, limiting pricing flexibility on terminal storage services.
- Specialized certification scarcity:Cold-chain validation credentials required by Health Canada and the U.S. FDA for pharmaceutical imports create capacity bottlenecks that restrict agency expansion into high-margin temperature-controlled logistics segments.
- Pilotage coordination fragmentation:Harbor complex tug and pilot services remain geographically siloed, preventing scale economies in vessel traffic management across the Northeast Atlantic and Gulf Coast terminal networks.
Strategic Opportunities
- Mexican nearshoring corridors:Manufacturing relocation from Asia to Mexico is expanding cross-border freight forwarding demand through Laredo and Brownsville gateway ports, requiring agencies to establish licensed customs broker presence on both sides of the U.S.-Mexico border.
- Pharmaceutical cold-chain convergence:Integration of Internet-of-Things temperature monitoring with blockchain documentation creates service differentiation opportunities for agencies serving FDA-regulated biologics importers requiring end-to-end chain-of-custody verification.
- Project cargo energy specialization:Offshore wind component logistics and carbon capture equipment movements represent emerging vessel charter coordination needs that command premium pricing outside commoditized container handling markets.
Industry Challenges
- Licensed customs broker talent scarcity:The technical complexity of harmonized tariff schedule classification and rules-of-origin determination under the USMCA is outpacing training pipeline capacity, constraining service expansion for mid-tier agencies.
- Legacy system integration friction:Port community systems and customs automation platforms require costly middleware development to connect agency proprietary databases with government filing portals, delaying digital transformation timelines for established operators.
- Intermodal coordination complexity:Synchronization between vessel schedules, rail ramp availability, and chassis pool positioning demands real-time data feeds that many agencies lack the capital intensity to deploy across multiple port ranges simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shipping Agency Market |
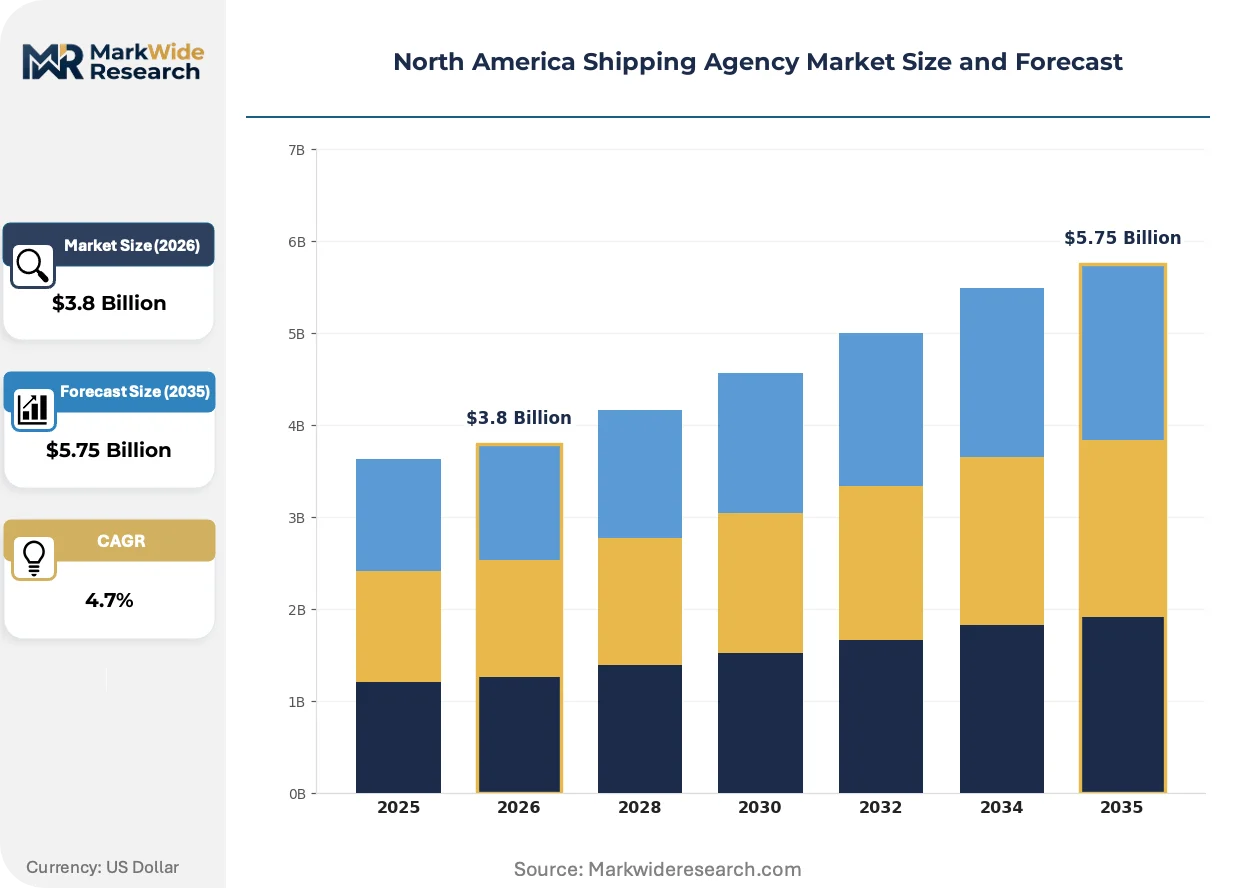
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port Management, Freight Forwarding, Logistics Support, Customs Clearance Client Type: Importers, Exporters, E-commerce Companies, Manufacturers Industry Vertical: Retail, Automotive, Pharmaceuticals, Energy Delivery Model: On-demand, Contractual, Project-based, Subscription |
| Companies Covered | United Shipping, Asiana USA, GAC North America, TransOcean Shipping, Lighthouse Shipping Agency Inc, Moran Shipping Agency, North American Shipping Agencies (NASA), Neptune Shipping Agency, Evergreen Shipping Agency, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shipping Agency Market Evolving Landscape
Digital documentation platforms and regulatory automation mandates are fundamentally restructuring how shipping agencies capture value, shifting competitive advantage from relationship-based port access to technology-enabled compliance throughput and specialized vertical expertise.
Machine-readable customs filing systems are rewriting the economics of document preparation services. U.S. Customs and Border Protection's Automated Commercial Environment and the Canada Border Services Agency's Single Window Initiative are compressing processing margins for traditional paper-based brokers while expanding revenue potential for agencies that embed validation algorithms directly into client enterprise resource planning systems. Pharmaceutical and automotive manufacturers are adopting these integrated platforms fastest, accepting per-transaction pricing in exchange for reduced examination rates and faster cargo release.
The U.S. Federal Maritime Commission's interpretive rule on detention and demurrage billing practices is forcing contractual term renegotiations across port management agreements. Beneficial cargo owners now demand invoice transparency and dispute resolution timelines that legacy billing systems cannot accommodate, compelling agencies to invest in time-stamped container tracking data feeds. Container lines and terminal operators in the Los Angeles-Long Beach and Savannah corridors are most exposed to these compliance costs.
Consolidation of buying power among large e-commerce fulfillment networks is compressing agency commission structures while expanding volume commitments. Amazon, Walmart, and Target are unbundling traditional freight forwarding packages, purchasing vessel space allocation and customs clearance as separate line items through competitive bidding platforms. This procurement fragmentation is most advanced in the Pacific Northwest and Southern California gateway markets, where direct carrier contracting has displaced intermediary agency roles on trans-Pacific routes.
North America Shipping Agency Market Segmentation
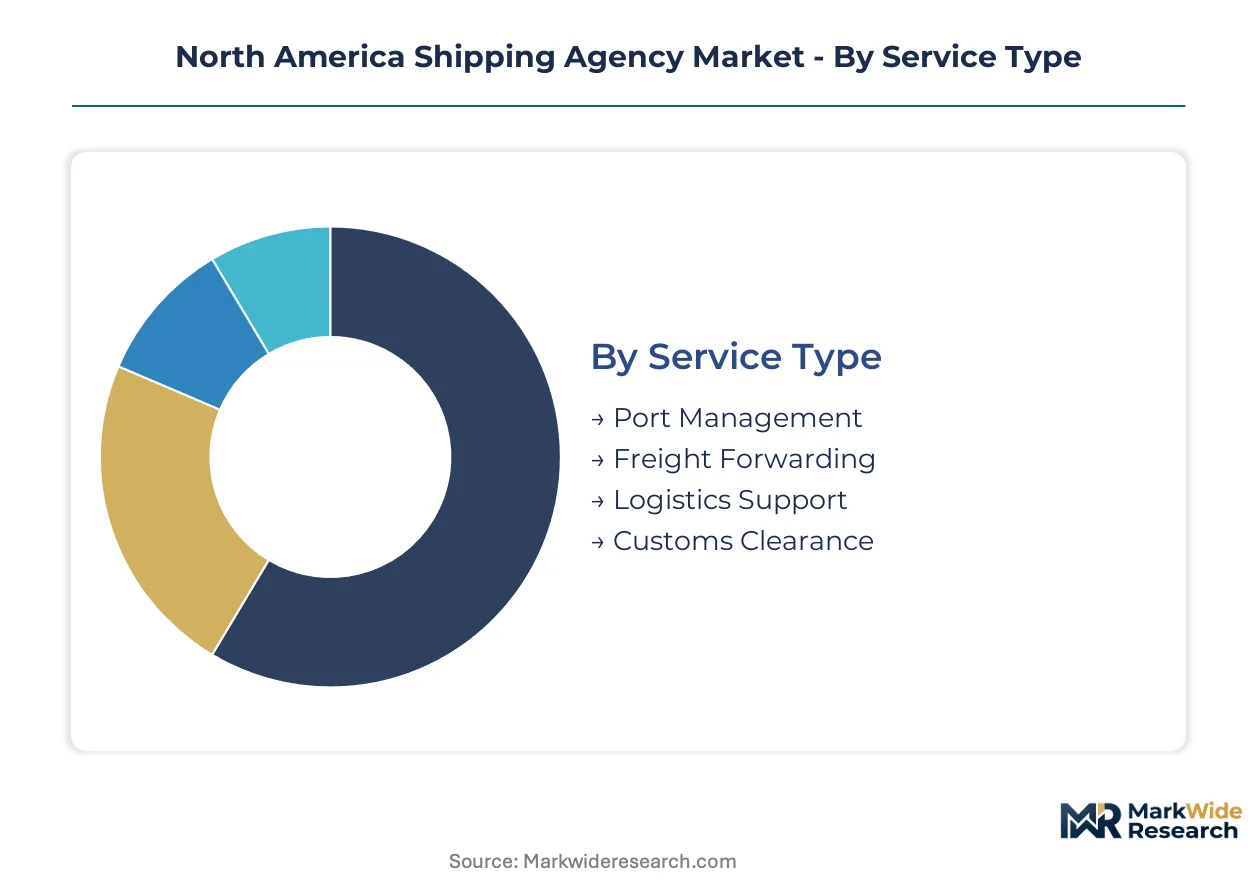
Shipping agencies in North America configure service portfolios around distinct operational rhythms—continuous vessel traffic versus discrete project mobilizations, transactional customs filings versus embedded supply chain partnerships. Segment boundaries determine capital deployment patterns, from bonded warehouse networks to licensed customs broker staffing ratios.
Service Type:
Upgrade cycles in documentation technology and regulatory compliance infrastructure are redistributing revenue across service lines as agencies retire paper-based workflows.
- Freight Forwarding:Core service coordinating carrier selection, cargo consolidation, and multimodal routing decisions on behalf of cargo principals. Demand clusters around cross-border manufacturing supply chains linking Mexican maquiladoras to U.S. distribution centers, driven by nearshoring acceleration and USMCA rules-of-origin complexity.
- Customs Clearance:Document preparation, tariff classification, and regulatory submission services required for lawful cargo release. U.S. Customs and Border Protection's machine-readable filing mandates and Canada Border Services Agency automation requirements are concentrating demand with agencies maintaining electronic data interchange infrastructure and continuous bonded status.
- Port Management:Vessel arrival coordination, berth scheduling, and terminal interface management. Gulf Coast energy export terminals and Savannah container gateways generate sustained contract volumes.
- Logistics Support:Ancillary services including warehousing, inventory management, and last-mile coordination. E-commerce fulfillment networks are absorbing this function into integrated platform offerings.
Volume placements concentrate in Freight Forwarding; the faster expansion belongs to Customs Clearance.
Client Type:
Cost tier differentiation separates transactional shippers seeking spot-market rates from principals requiring embedded agency relationships.
- Manufacturers:Industrial cargo owners with continuous production schedules demanding predictable vessel space allocation and just-in-time customs release. Automotive and aerospace supply chains in Michigan and South Carolina represent concentrated demand pools.
- E-commerce Companies:Online retail fulfillment networks with high-velocity, small-parcel import flows and stringent delivery window requirements. Amazon, Walmart, and Target procurement teams are unbundling traditional service packages into competitively bid line items.
- Importers:Discrete cargo principals with periodic shipment needs, typically lacking in-house trade compliance expertise. Pharmaceutical and medical device importers under FDA jurisdiction require specialized handling protocols.
- Exporters:Domestic producers seeking foreign market access, particularly energy sector principals moving liquefied natural gas and petroleum products through Texas and Louisiana terminals.
Revenue concentration sits with Manufacturers; E-commerce Companies are climbing the fastest as procurement platforms fragment traditional agency relationships.
Industry Vertical:
Application-specific certification requirements create defendable margin pools that resist commoditization pressures affecting general cargo segments.
- Energy:Project cargo and bulk commodity movements requiring specialized vessel charter coordination, heavy-lift equipment, and port infrastructure access. Offshore wind component logistics and carbon capture equipment transport represent emerging demand categories.
- Pharmaceuticals:Temperature-controlled supply chains governed by FDA and Health Canada validation protocols, with Internet-of-Things monitoring and blockchain documentation increasingly standard. Cold-chain certification scarcity restricts agency participation.
- Automotive:Just-in-sequence production support with precise delivery windows and customs deferral programs. Mexican assembly plant supply chains drive cross-border service integration.
- Retail:High-volume, low-margin container movements with seasonal demand spikes and compressed margin structures. Pacific Northwest and Southern California gateways handle dominant share.
Margin protection is strongest in Energy; Pharmaceuticals is gaining share fastest on compliance barrier expansion.
Delivery Model:
Maturity gradients separate established contractual relationships from emerging subscription and on-demand platforms.
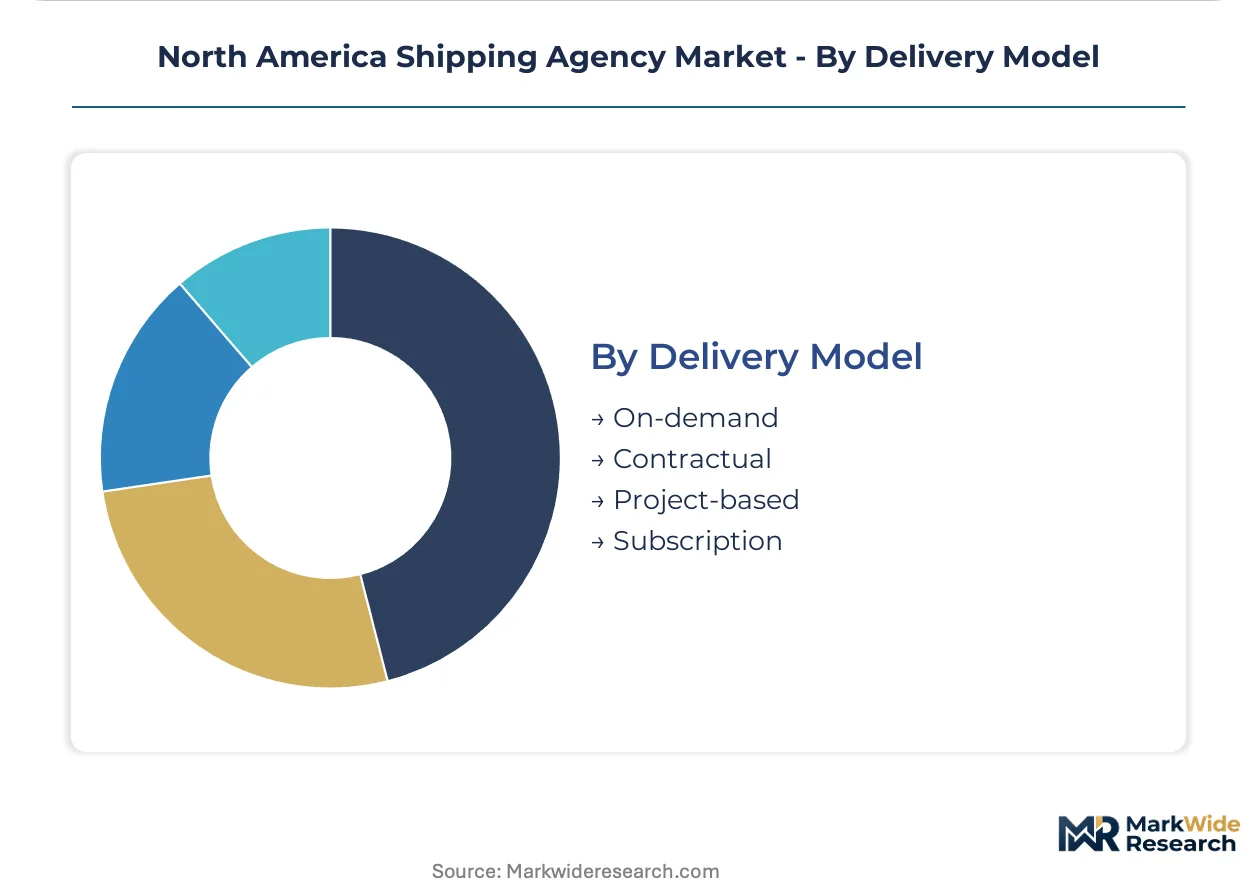
- Contractual:Multi-year agreements with defined service levels, volume commitments, and pricing mechanisms. Energy sector exporters and major manufacturers prefer this structure for budget predictability.
- Project-based:Discrete engagements tied to specific vessel calls, construction mobilizations, or facility startups. Offshore wind installation campaigns and LNG facility expansions generate premium pricing.
- Subscription:Fixed-fee arrangements covering unlimited customs filings or port calls within defined parameters. Mid-market importers are testing this model for cost control.
- On-demand:Spot-market service procurement through digital platforms with transparent pricing and immediate availability. E-commerce logistics teams are driving adoption in gateway markets.
Revenue stability favors Contractual arrangements; On-demand platforms are expanding most quickly as digital procurement penetrates agency selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone designations along the Gulf Coast and Pacific gateway corridors are concentrating shipping agency infrastructure investment, with bonded warehouse networks and licensed customs broker capacity clustering around energy export terminals and e-commerce fulfillment hubs.
United States
The U.S. Federal Maritime Commission's detention and demurrage billing reforms are reshaping port management economics across California and Georgia gateway terminals. U.S. Customs and Border Protection's Automated Commercial Environment mandates favor agencies with electronic data interchange infrastructure. The Los Angeles-Long Beach corridor handles dominant trans-Pacific container volumes while Savannah anchors Southeast Atlantic expansion.
Canada
Health Canada and the Canada Border Services Agency jointly regulate pharmaceutical import documentation standards, creating compliance barriers for temperature-controlled logistics providers. The Single Window Initiative accelerates machine-readable filing adoption. Vancouver and Prince Rupert terminals concentrate Pacific Rim trade flows while Montreal anchors St. Lawrence Seaway access.
Mexico
Manufacturing relocation from Asia to Mexican maquiladoras is expanding cross-border freight forwarding demand through Laredo and Brownsville gateway ports. The USMCA rules-of-origin complexity requires licensed customs broker presence on both sides of the U.S.-Mexico border. Nuevo León and Baja California industrial corridors generate sustained contract volumes for integrated logistics providers.
Texas Gulf Coast
Liquefied natural gas and petroleum product exports through Texas terminals are driving specialized vessel coordination and project cargo handling demand. The U.S. Department of Energy's export authorization frameworks structure terminal access priorities. The Houston Ship Channel and Corpus Christi anchor energy sector agency relationships with premium pricing power.
Louisiana Gulf Coast
Offshore wind component logistics and carbon capture equipment movements represent emerging vessel charter coordination needs commanding premium rates outside commoditized container markets. The Bureau of Ocean Energy Management's lease auctions structure offshore development timelines. Lake Charles and Port Fourchon concentrate heavy-lift infrastructure for energy project mobilizations.
North America Shipping Agency Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with energy sector project cargo resisting commoditization while e-commerce forwarding faces procurement fragmentation. The vendor base organizes around three strategic archetypes: integrated port management operators with terminal infrastructure control, specialized customs brokerage firms with bonded status maintenance, and project logistics coordinators with heavy-lift certifications. M&A activity concentrates on digital documentation platform acquisitions and cross-border customs broker licensing expansions.
Within the integrated port management tier, GAC North America and Moran Shipping Agency exemplify contrasting geographic specializations—GAC leveraging Atlantic and Gulf terminal networks for energy contracts, Moran anchoring Northeast harbor pilotage coordination. Neptune Shipping Agency occupies a position within the specialized vertical tier, representing agencies that differentiate through cold-chain validation capabilities for pharmaceutical compliance. These three structures illustrate how certification scarcity and infrastructure control determine margin protection across service archetypes.
| Leading Market Players |
|---|
| United Shipping |
| Asiana USA |
| GAC North America |
| TransOcean Shipping |
| Lighthouse Shipping Agency Inc |
| Moran Shipping Agency |
| North American Shipping Agencies (NASA) |
| Neptune Shipping Agency |
| Evergreen Shipping Agency |
| Others |
Value Network & Pricing Analysis
The U.S. Federal Maritime Commission's detention and demurrage billing reforms gate qualified supply access for port management providers while simultaneously compressing margin structures that previously supported premium-tier service pricing. Agencies maintaining bonded customs broker status and electronic data interchange infrastructure capture pricing power as regulatory compliance costs disqualify mid-tier competitors from high-value contract participation.
Pricing Analysis
Short lead-time vessel coordination commands premium pricing in energy export corridors, while spot-market customs clearance transactions face downward pressure from digital platform transparency. Three-tier pricing structure across premium, standard, and economy levels separates project-based energy contracts from subscription customs filings and on-demand spot services. Price differentiation rests on cold-chain certification grade and USMCA rules-of-origin expertise. Cost compression in standard-tier freight forwarding is intensifying because e-commerce procurement teams unbundle service packages into competitively bid line items. E-commerce fulfillment networks exhibit highest price sensitivity; pharmaceutical biologics importers show lowest sensitivity due to compliance failure costs.
Supply Chain Analysis
Cold-chain validation credentials and licensed customs broker certifications gate supplier participation in pharmaceutical and energy verticals, restricting service expansion to agencies with established training pipelines. Qualified supply concentrates in the United States, Canada, and Mexico, with cross-border USMCA corridor infrastructure drawing from specialized pilotage coordination, bonded warehouse networks, and heavy-lift terminal equipment. Raw material dependencies include vessel charter capacity, chassis pool positioning, and rail ramp availability. Single-source vulnerability in licensed customs broker talent creates structural risk as harmonized tariff schedule complexity outpaces training capacity. Distribution runs through port community systems linking terminal operators, customs automation platforms, and principal enterprise resource planning systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed customs broker scarcity props pricing power for qualified agencies across North American shipping corridors. Energy sector project cargo and pharmaceutical cold-chain segments remain supply-constrained due to certification bottlenecks that resist rapid capacity expansion.
For Market Incumbents: Acquire digital documentation platform capabilities to defend against procurement fragmentation from e-commerce fulfillment networks. Incumbents should embed validation algorithms directly into client enterprise resource planning systems to lock in subscription revenue. Backward integration into bonded warehouse networks at Gulf Coast energy terminals secures terminal access priority against emerging port management competitors. For New Entrants and Emerging Players: Mid-market importers seeking subscription-based customs clearance cost control represent an underserved buyer archetype with limited incumbent penetration. New entrants should establish licensed customs broker presence on both sides of the U.S.-Mexico border to capture nearshoring corridor expansion through Laredo and Brownsville. A direct-to-principal digital platform with transparent per-transaction pricing offers the most penetrable go-to-market angle against relationship-dependent incumbents. For Investors and Strategic Acquirers: U.S. Federal Maritime Commission interpretive rule implementation is the leading indicator that detention and demurrage billing system investments will separate acquisition targets from stranded legacy operators. Long-term viability favors agencies with integrated port management infrastructure and specialized vertical certifications rather than pure-play freight forwarders facing procurement commoditization. The signal to monitor is Canada Border Services Agency and U.S. Customs and Border Protection machine-readable filing mandate acceleration, which will determine bonded status retention and client access preservation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Documentation Platform Acquisition | Embedded validation algorithms in client ERP systems reduce examination rates at U.S. Customs and Border Protection. |
| Bonded Warehouse Network Expansion | Gulf Coast terminal infrastructure control secures premium pricing on liquefied natural gas export contracts. |
| Cold-Chain Certification Investment | FDA and Health Canada validation credentials unlock pharmaceutical biologics importer relationships with defensible margins. |
| Cross-Border Customs Broker Licensing | USMCA corridor presence on both U.S. and Mexico sides captures nearshoring manufacturing relocation demand. |
| Internet-of-Things Integration Partnership | Blockchain documentation with temperature monitoring creates service differentiation for temperature-controlled logistics. |
Research Methodology
Multi-period observation of vessel call volumes, customs filing automation adoption rates, and energy export terminal utilization anchored the trend analysis, supplemented by interviews with port captains, licensed customs brokers, freight forwarding operations directors, and pharmaceutical supply chain managers. Secondary validation drew from U.S. Federal Maritime Commission enforcement actions, U.S. Customs and Border Protection Automated Commercial Environment disclosure data, Canada Border Services Agency Single Window Initiative progress reports, and Bureau of Ocean Energy Management lease auction records. Bottom-up service line revenue estimates triangulated against top-down regional trade flow data.
Segment-weighting approaches distributed value projections across freight forwarding, customs clearance, port management, and logistics support service types, with additional weighting for energy, pharmaceutical, automotive, and retail industry verticals. Modeled dimensions included service type, client category, industry vertical, and delivery model structure across the analysis window. CAGRs derived from historical trajectory fitting adjusted for regulatory intervention impacts and technology adoption S-curves. Forecast inputs incorporated USMCA rules-of-origin complexity indices and offshore wind project development pipeline data.
Revisions become necessary when U.S. Federal Maritime Commission enforcement priorities shift, Canada Border Services Agency automation timelines accelerate, or licensed customs broker training pipeline capacity materially expands. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology platform adoption rates. A model refresh is warranted upon material change in cross-border manufacturing relocation patterns or pharmaceutical cold-chain validation protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
GCC Air Freight and Logistics Market