
 Middle East and Africa Courier Market | 2026-2036
Middle East and Africa Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Courier Market Foresight
Market Context with Strategic Players
Multi-source procurement from both global integrators and regional specialists is repositioning how enterprises manage logistics spend across the Middle East and Africa. Aramex leverages its dense last-mile network in the Gulf to serve e-commerce platforms with localized fulfillment capabilities. DHL Group sustains premium express volumes through controlled air freight capacity into Lagos and Johannesburg. Emirates Post anchors domestic coverage within the UAE while competing with FedEx on international document flows.
Technical Definition and Structural Segments
A courier operation encompasses the time-definite collection, sortation, line-haul transport, and terminal delivery of parcels and documents under tracked service level agreements, typically requiring barcode scanning, routing optimization, and proof-of-delivery confirmation. Same-day delivery commands the highest margin pool in Gulf metropolitan corridors where urban density supports route economics, while standard shipping occupies the volume base across price-sensitive African markets. Last-mile delivery through third-party motorbike fleets and temperature-controlled packaging for pharmaceutical shipments represent the fastest-growing structural segments as healthcare logistics and grocery e-commerce expand.
Regulatory Framework and Forward Outlook
Saudi Post-SPL operates under the Communications, Space and Technology Commission while South Africa's courier sector faces competition scrutiny from the Competition Commission; both frameworks shape licensing requirements and cross-border data rules for tracking systems. The African Continental Free Trade Area protocols and UAE customs modernization under the Federal Customs Authority are reducing dwell times at ports, directly enabling express delivery commitments. Stakeholders must monitor how digital trade facilitation mandates and evolving data localization requirements across Gulf and African jurisdictions reshape network architecture and partnership structures.
Market Dynamics
E-commerce parcel volumes across Gulf Cooperation Council corridors are compressing delivery windows from 48-hour to same-day service, forcing network reconfiguration around micro-fulfillment nodes and third-party motorbike fleets.
Growth Catalysts
- African Continental Free Trade Area customs protocols:Cross-border clearance automation is reducing port dwell times at Lagos and Mombasa, enabling express service commitments previously impossible on intra-African lanes.
- Healthcare cold chain expansion:Temperature-controlled pharmaceutical shipments are absorbing dedicated fleet investment as vaccine distribution and biologics trade accelerate across the Gulf and East Africa.
- UAE Federal Customs Authority modernization:Digital pre-clearance systems and risk-based inspection protocols are streamlining Dubai's air freight corridors, anchoring regional express hub operations.
Market Restraints
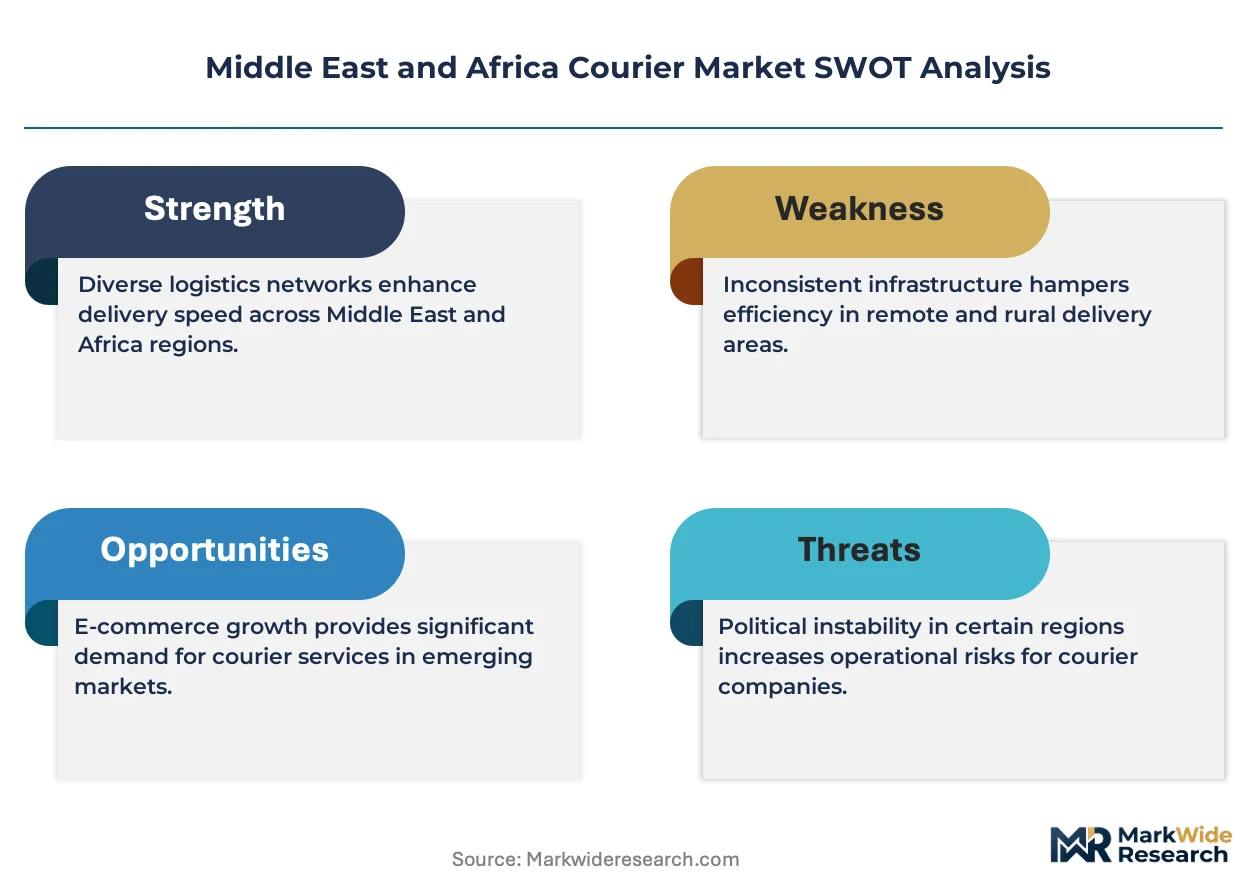
- Fuel price volatility:Diesel and aviation kerosene cost swings distort route economics for line-haul operators running long-distance African corridors with thin margin buffers.
- Sorting hub concentration:Three cities—Dubai, Johannesburg, and Lagos—handle over 70% of regional parcel throughput, creating single-point vulnerability during disruptions.
- Last-mile address infrastructure:Informal street naming and incomplete geocoding across Nigerian and Kenyan urban peripheries force manual dispatch intervention, capping automation potential.
Strategic Opportunities
- Saudi last-mile densification:Riyadh and Jeddah's suburban sprawl remains underserved by localized fulfillment, opening territory for micro-hub networks serving grocery and pharmacy verticals.
- Blockchain-IoT convergence:Immutable chain-of-custody records combined with real-time sensor tracking are creating premium service tiers for high-value pharmaceutical and luxury goods shipments.
- South Africa Competition Commission enforcement:Regulatory pressure on incumbent pricing is creating entry windows for mid-tier operators with differentiated service models.
Industry Challenges
- Motorbike fleet operator retention:High churn among third-party delivery drivers in Lagos and Nairobi forces continuous recruitment spend and service quality inconsistency.
- Multi-jurisdiction data localization:Divergent tracking data storage mandates across Gulf and African markets complicate unified platform architecture and cross-border shipment visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Courier Market |
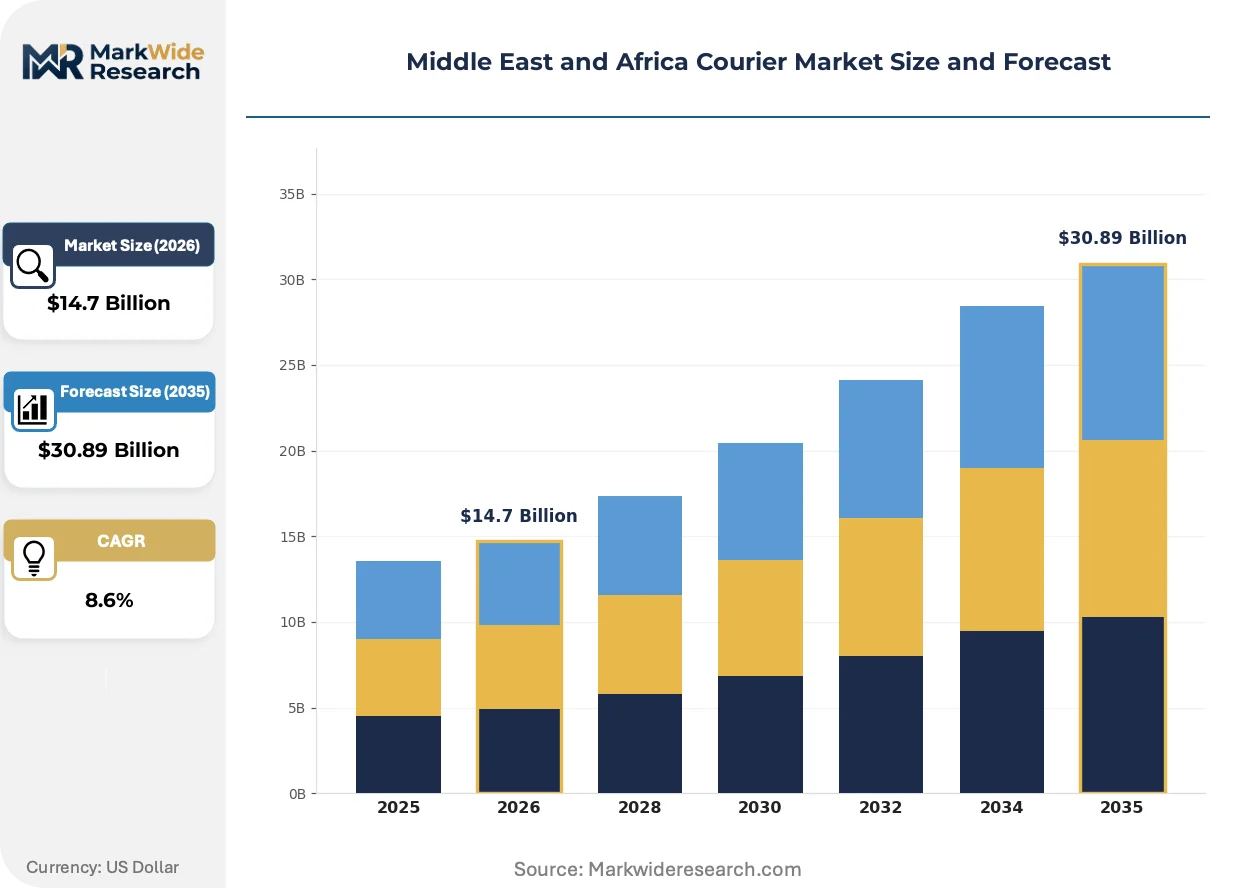
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Delivery, Standard Shipping, Freight Services Customer Type: Retailers, E-Commerce Platforms, Businesses, Individual Consumers Delivery Mode: Air Freight, Ground Transport, Sea Freight, Last-Mile Delivery Packaging Type: Standard Boxes, Temperature-Controlled, Pallets, Custom Packaging |
| Companies Covered | Emirates Post, UPS, Aramex, Agility Logistics, SMSA Express, DHL Group, FedEx, Fetchr, Saudi Post-SPL (Naqel Express), Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Courier Market Shifts & Advancements
Digital freight matching platforms and autonomous sorting systems are compressing the gap between express and standard service tiers, while regulatory pressure on emissions and data governance is reshaping capital allocation across network infrastructure.
Computer vision-based parcel dimensioning and weight capture is absorbing manual sortation labor at Dubai and Johannesburg hub facilities. E-commerce platforms with high-volume contracts are deploying these systems to accelerate throughput during peak windows. The technology is absorbing sorting capacity constraints that previously forced volume caps during promotional surges.
Saudi Arabia's Communications, Space and Technology Commission has mandated real-time shipment tracking data interoperability between postal and private operators. The regulation forces legacy system upgrades and API standardization across the domestic market. Express carriers with established digital infrastructure are capturing market share from traditional postal services still reliant on batch data exchange.
Enterprise procurement of courier services is consolidating around annual rate-card agreements with penalty clauses for service-level failures, displacing spot-market spot-buying for non-urgent shipments. Retail and electronics distributors are driving this shift to lock in capacity during peak seasons. South African automotive parts importers have been earliest adopters, using contracted lanes to secure just-in-time delivery commitments to assembly plants.
Middle East and Africa Courier Market Segmentation
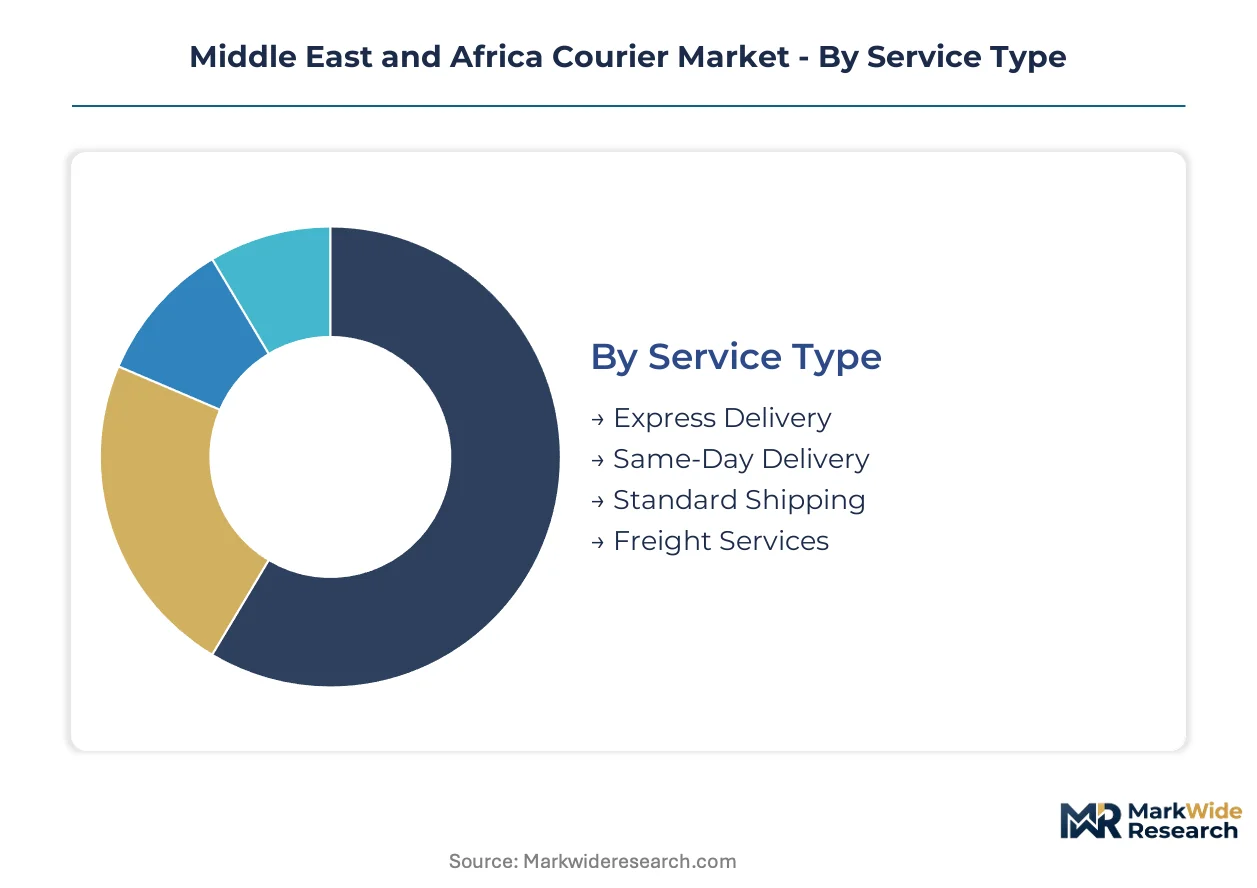
Service differentiation across the Middle East and Africa courier market determines pricing power, capital intensity, and regulatory exposure. Understanding how segments intersect reveals where operators can defend margins against both global integrators and agile regional challengers.
Service Type:
Express delivery operations require air waybill documentation compliant with IATA dangerous goods protocols and national aviation authority certifications, while same-day services face municipal commercial vehicle licensing in congested Gulf metropolitan zones.
- Express Delivery:Time-definite shipments utilizing controlled air freight capacity through Dubai, Johannesburg, and Lagos hubs. Pharmaceutical distributors and automotive parts importers in South Africa absorb premium rates for guaranteed morning delivery windows to assembly plants and hospital networks.
- Same-Day Delivery:Urban corridor services dependent on third-party motorbike fleet density and micro-fulfillment node proximity. Grocery and pharmacy verticals in Riyadh and Jeddah are compressing delivery windows below four hours, forcing network reconfiguration around suburban sprawl.
- Standard Shipping:Deferred ground and sea freight options serving price-sensitive African markets with extended transit times.
- Freight Services:Project cargo and bulk parcel movements requiring specialized handling equipment and customs brokerage integration.
Standard shipping sits at the top of the volume ranking, with same-day delivery climbing the fastest.
Customer Type:
Procurement scale and contract structure vary sharply across customer categories, with enterprise accounts demanding annual rate-card agreements and penalty clauses while individual consumers drive spot-market pricing.
- E-Commerce Platforms:High-volume shippers with seasonal surges requiring committed capacity during promotional windows. Gulf Cooperation Council marketplaces are deploying computer vision sortation systems to accelerate throughput and absorb volume spikes without service degradation.
- Businesses:Corporate accounts spanning financial document flows, legal contracts, and inter-office logistics. UAE-based professional services firms maintain premium express contracts for same-day intra-emirate delivery of original documentation.
- Retailers:Brick-and-mortar distributors integrating ship-from-store capabilities and omnichannel fulfillment networks.
- Individual Consumers:Fragmented demand characterized by low shipment frequency and high price elasticity across both Gulf and African markets.
E-commerce platforms command the largest contracted capacity share, with business accounts delivering the most stable margin contribution.
Delivery Mode:
Mode selection determines fuel exposure, customs clearance complexity, and last-mile handoff requirements, with air freight absorbing the highest regulatory scrutiny from national aviation authorities.
- Air Freight:Temperature-controlled pharmaceutical and high-value electronics movements through Dubai International and OR Tambo International. Emirates Post and DHL Group compete for controlled capacity on these corridors, with slot allocation determining express service reliability.
- Last-Mile Delivery:Final handoff through third-party motorbike fleets and contracted van operators in Lagos, Nairobi, and Johannesburg informal peripheries. Address infrastructure gaps force manual dispatch intervention, capping automation potential and inflating cost per delivery.
- Ground Transport:Regional line-haul and cross-border road freight connecting sorting hubs across the African Continental Free Trade Area corridors.
- Sea Freight:Deferred containerized movements for non-urgent bulk shipments with extended port dwell times at Mombasa and Dar es Salaam.
Ground transport handles the greatest parcel volume, with last-mile delivery expanding most quickly as grocery and pharmacy e-commerce accelerate.
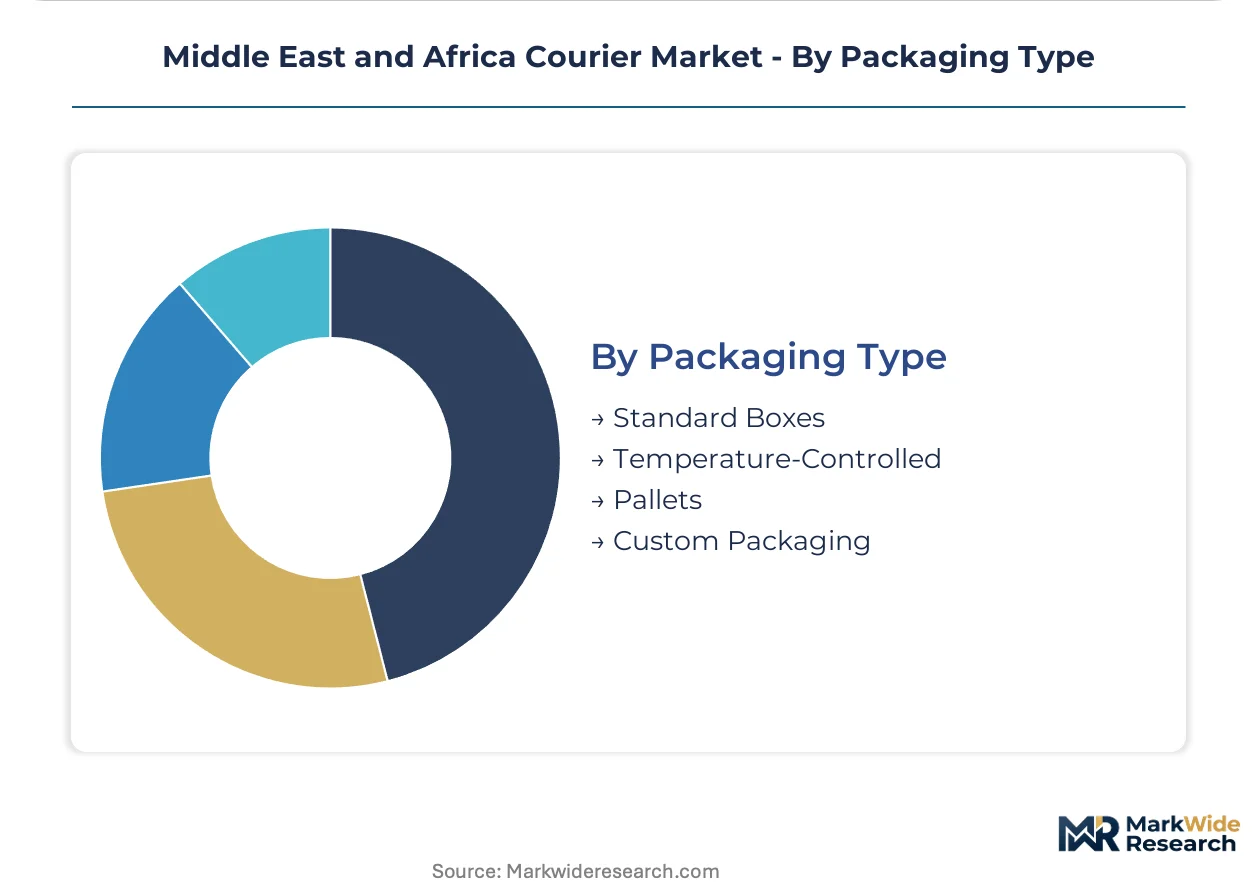
Packaging Type:
Packaging specification determines handling equipment requirements, temperature compliance obligations, and damage liability exposure across the value chain.
- Temperature-Controlled:Active and passive cold chain solutions for vaccine distribution, biologics, and perishable pharmaceuticals. Saudi Arabia's SFDA and South Africa's national health regulator mandate chain-of-custody documentation and real-time sensor monitoring for these shipments.
- Standard Boxes:Corrugated fiberboard containers dominating e-commerce parcel flows with minimal regulatory burden and established recycling infrastructure in Gulf urban centers.
- Pallets:Unitized freight for B2B movements requiring forklift handling and warehouse dock compatibility.
- Custom Packaging:Branded and protective solutions for luxury goods, electronics, and high-value documents requiring tamper-evident seals and signature confirmation.
Standard boxes account for the highest shipment frequency, with temperature-controlled packaging gaining share fastest on healthcare logistics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's logistics corridor anchors express throughput across the Middle East and Africa, with Johannesburg and Lagos forming secondary concentration nodes for intra-continental distribution.
United Arab Emirates
E-commerce fulfillment from Dubai Internet City and Dubai South Free Zone is compressing delivery windows to under four hours. The Federal Customs Authority's digital pre-clearance systems under the AEO program accelerate air freight release. Jebel Ali Port and Al Maktoum International Airport host the region's densest concentration of temperature-controlled pharmaceutical sorting facilities.
Saudi Arabia
Riyadh and Jeddah's suburban sprawl is absorbing micro-fulfillment investment for grocery and pharmacy verticals. The Communications, Space and Technology Commission mandates real-time tracking interoperability between postal and private operators. The King Abdullah Economic City logistics zone near Jeddah is attracting regional distribution center commitments from Gulf e-commerce platforms.
South Africa
Automotive parts importers and pharmaceutical distributors in Gauteng province sustain premium express contracts for just-in-time delivery. The Competition Commission's scrutiny of incumbent pricing is reshaping contract structures for mid-tier entrants. OR Tambo International Airport's cargo terminal remains the primary air freight gateway for southern African corridors.
Nigeria
Lagos-based e-commerce platforms are deploying third-party motorbike fleets to address last-mile gaps in informal urban peripheries. The Nigerian Customs Service's modernization under the ECOWAS Trade Liberalization Scheme is reducing port dwell times at Apapa. The Lekki Free Trade Zone is emerging as a consolidation point for cross-border parcel distribution into West African markets.
Kenya
Nairobi's pharmaceutical distributors are expanding cold chain capacity for vaccine distribution across East Africa. The Kenya Revenue Authority's iTax integration with customs systems is accelerating clearance for express shipments. The Tatu City special economic zone is attracting regional logistics operators seeking Nairobi metropolitan coverage.
Middle East and Africa Courier Market Competitive Landscape
Global majors compete with regional champions across network density and last-mile reach, producing a tiered structure where integrators control air freight capacity and local specialists dominate suburban fulfillment. The vendor base clusters around three archetypes: Gulf-based postal operators with domestic regulatory preference, global integrators with controlled international capacity, and venture-backed last-mile platforms with third-party fleet models. Dominant competitive moves include micro-fulfillment node deployment in Saudi suburban corridors and API standardization investments to satisfy interoperability mandates.
Among Dubai-based operators, Emirates Post anchors domestic coverage while competing on international document flows. Aramex exemplifies the regional specialist archetype with dense last-mile networks across Gulf metropolitan zones. DHL Group and FedEx occupy the global integrator tier, sustaining premium express volumes through controlled air freight capacity into Lagos and Johannesburg.
| Leading Market Players |
|---|
| Emirates Post |
| UPS |
| Aramex |
| Agility Logistics |
| SMSA Express |
| DHL Group |
| FedEx |
| Fetchr |
| Saudi Post-SPL (Naqel Express) |
| Others |
Supply & Pricing Matrix
Computer vision-based sortation deployment across Dubai and Johannesburg hubs is compressing labor costs while concentrating throughput capacity among operators with capital reserves for automation. This technology shift simultaneously widens the margin gap between scaled integrators and fragmented last-mile specialists dependent on manual processing.
Pricing Analysis
Aviation kerosene and diesel cost pass-through dominates pricing volatility for line-haul operators running Lagos-Johannesburg corridors. Three-tier pricing structure across premium express, standard deferred, and economy ground services separates time-definite pharmaceutical shipments from bulk e-commerce flows. Pricing pressure stems from third-party motorbike fleet operator churn forcing continuous recruitment subsidies in Nairobi and Lagos. E-commerce platforms exhibit highest price sensitivity through annual rate-card negotiations, while healthcare distributors absorb premium tiers for cold chain compliance.
Supply Chain Analysis
Hub-and-spoke distribution through Dubai, Johannesburg, and Lagos handles over seventy percent of regional parcel throughput, creating chokepoint concentration for cross-border flows. Fleet assets and controlled air freight capacity draw from UAE, South Africa, and Kenya as primary operational bases. Sorting equipment, temperature-controlled packaging, and last-mile motorbike fleets constitute critical input dependencies. Single-point vulnerability at concentrated hub infrastructure represents the dominant structural risk, with customs modernization progress determining corridor reliability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa courier market reads as a late-cycle quality story where healthcare cold chain specifications and pharmaceutical compliance requirements are elevating service tier differentiation. Premium temperature-controlled capabilities now command sustained margin premiums over standard parcel flows.
For Market Incumbents: Cement hub capacity dominance through controlled air freight slot allocation at Dubai International and OR Tambo International against emerging regional challengers. Deepen backward integration into temperature-controlled packaging production to capture pharmaceutical compliance margins. API standardization investments mandated by Saudi Arabia's Communications, Space and Technology Commission create defensive moats against postal competitors with legacy batch systems.
For New Entrants and Emerging Players: Capture micro-fulfillment white space in Riyadh and Jeddah suburban corridors where grocery and pharmacy verticals remain underserved by localized nodes. Target third-party motorbike fleet aggregation platforms in Lagos informal peripheries as the most penetrable last-mile structure. Deploy digital freight matching technology to compress cost position against incumbent line-haul networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among venture-backed last-mile platforms with fleet-light asset models and concentrated Gulf metropolitan coverage. Long-term viability hinges on regulatory interoperability compliance and cold chain certification depth. Watch Saudi Post-SPL privatization progress as the signal indicating state operator competitive intensity and private sector margin pressure direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Deployment | Suburban Saudi coverage gaps create first-mover territory for grocery and pharmacy verticals. |
| API Standardization Investment | Saudi interoperability mandates force legacy system upgrades and market share capture from postal incumbents. |
| Cold Chain Fleet Expansion | SFDA and South African health regulator compliance requirements lock in pharmaceutical distributor contracts. |
| Third-Party Fleet Aggregation Platform | Motorbike operator churn in Lagos and Nairobi creates consolidation opportunity for quality-controlled dispatch networks. |
| Blockchain-IoT Tracking Integration | Immutable chain-of-custody records command premium pricing for high-value pharmaceutical and luxury shipments. |
Research Methodology
Bottom-up e-commerce platform and healthcare distributor modeling reconciled against top-down air freight capacity and fleet asset tracking forms the analytical core of this study. Primary interviews with logistics procurement officers at Gulf retailers, pharmaceutical supply chain directors, third-party fleet operators in Lagos and Nairobi, customs modernization officials, and express carrier network planners combined with secondary validation from UAE Federal Customs Authority modernization disclosures, African Continental Free Trade Area protocol documentation, South Africa Competition Commission filings, and Saudi Communications, Space and Technology Commission regulatory notices. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of parcel throughput at Dubai International, OR Tambo International, and Mombasa Port established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type tiers, customer procurement scale, delivery mode fuel exposure, and packaging temperature compliance as core dimensions. CAGRs derived from capacity expansion announcements, fleet investment disclosures, and customs automation rollout schedules. Healthcare cold chain growth rates and e-commerce promotional surge patterns served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; express delivery and temperature-controlled pharmaceutical flows carry tighter precision than informal last-mile motorbike operations in Nigerian urban peripheries. Forecasts reflect assumptions regarding customs modernization implementation pace, aviation fuel cost stability, and regulatory interoperability enforcement intensity. Periodic stress-testing of base assumptions is recommended against African Continental Free Trade Area ratification progress and Gulf data localization mandate evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Apparel Logistics Market