
 Dust Extractors Market | 2026-2036
Dust Extractors Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Extractors Market Analysis
Equipment leasing and project-based financing is reshaping competitive dynamics in the dust extractors sector, lowering capital barriers for mid-sized contractors. Donaldson Company leverages its vertically integrated filter media production to sustain margin control across aftermarket channels. Nederman Holding anchors its position through captive service networks in Northern Europe. Parker Hannifin competes on hydraulic and pneumatic integration, bundling extraction with factory automation systems.
Dust extractors are industrial air filtration systems designed to capture and separate particulate matter from process air streams, typically achieving capture velocities of 3,500–4,500 feet per minute at the source hood. These systems employ baghouse filters, cartridge media, or wet scrubbing chambers to protect worker respiratory health and maintain ambient air quality below permissible exposure limits. Portable units lead volume shipments in construction and renovation workflows where site mobility dominates purchasing criteria. HEPA technology commands premium positioning in pharmaceutical cleanrooms and laboratory environments where containment integrity is non-negotiable. Wet scrubbing systems occupy a mature niche in metalworking applications handling combustible aluminum or magnesium fines.
OSHA enforces permissible exposure limits for respirable crystalline silica, compelling construction firms to upgrade from passive ventilation to source-capture extraction. The EPA National Emission Standards for Hazardous Air Pollutants governs metal finishing and mineral processing facilities, mandating continuous monitoring tied to extraction system performance. ISO 15012-1 provides welding fume capture efficiency benchmarks that equipment manufacturers must document for CE marking access into European markets. Stakeholders should monitor evolving MEE enforcement protocols in China, where dual carbon goals are tightening industrial air discharge permits and reshaping import equipment certification requirements.
Market Dynamics
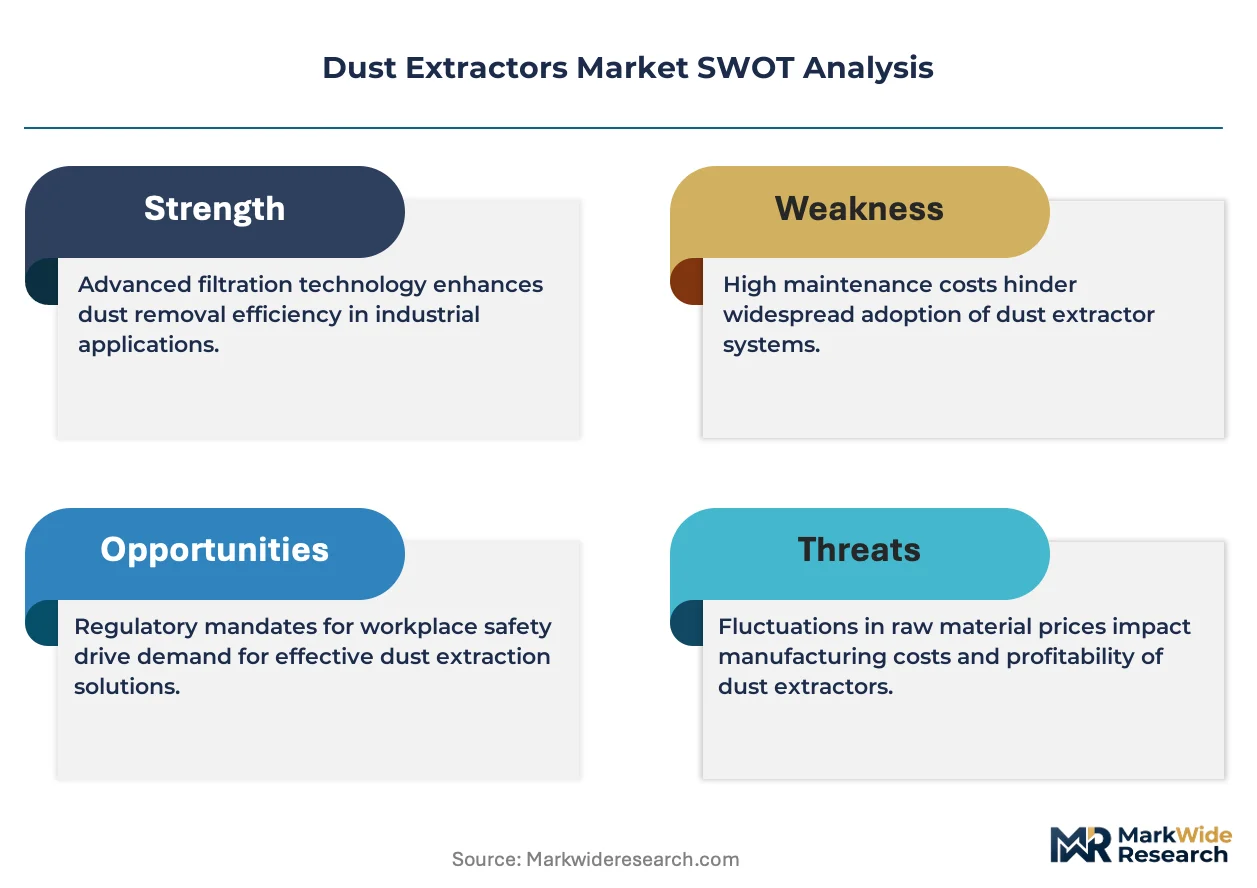
OSHA's tightened silica exposure limits are forcing construction contractors to retire passive ventilation in favor of source-capture systems, compressing replacement cycles and reshaping equipment procurement priorities across the industrial base.
Growth Catalysts
- Regulatory Enforcement Intensification:OSHA's respirable crystalline silica PEL compels construction firms to upgrade extraction infrastructure, particularly in concrete cutting and demolition workflows.
- Metalworking Automation:Robotic welding cells in automotive fabrication require integrated fume capture systems, driving centralized dust extraction installations in manufacturing corridors.
- Pharmaceutical Containment Standards:HEPA-grade extraction systems are becoming mandatory in sterile manufacturing environments where cross-contamination risks carry severe regulatory penalties.
Market Restraints
- Filter Media Cost Volatility:Synthetic fiber and nanofiber membrane prices fluctuate with petrochemical feedstock markets, squeezing margin stability for system manufacturers.
- Supply Concentration in Filter Manufacturing:High-efficiency media production concentrates among a limited set of specialized suppliers, creating bottleneck risks for premium system tiers.
- Technical Limitation in Wet Scrubbing:Water-based systems face deployment constraints in cold-climate operations where freeze protection adds operational complexity and energy burden.
Strategic Opportunities
- Underpenetrated Indian Manufacturing:PLI scheme incentives for domestic electronics and automotive production are creating first-mover openings for extraction system vendors in industrializing states.
- Battery Cell Manufacturing:Lithium-ion electrode production generates combustible metal fines, opening demand for specialized wet scrubbing and inert gas extraction configurations.
- Equipment-as-a-Service Models:Subscription-based maintenance and filter replacement programs are penetrating mid-sized contractor segments previously priced out of premium system ownership.
Industry Challenges
- Certification Timeline Compression:CE marking documentation under ISO 15012-1 welding fume standards requires extensive third-party validation, delaying product launches for modular system variants.
- Integration Complexity with Legacy Ductwork:Retrofitting source-capture hoods into existing ventilation infrastructure demands custom engineering that extends project timelines and erodes contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Extractors Market |
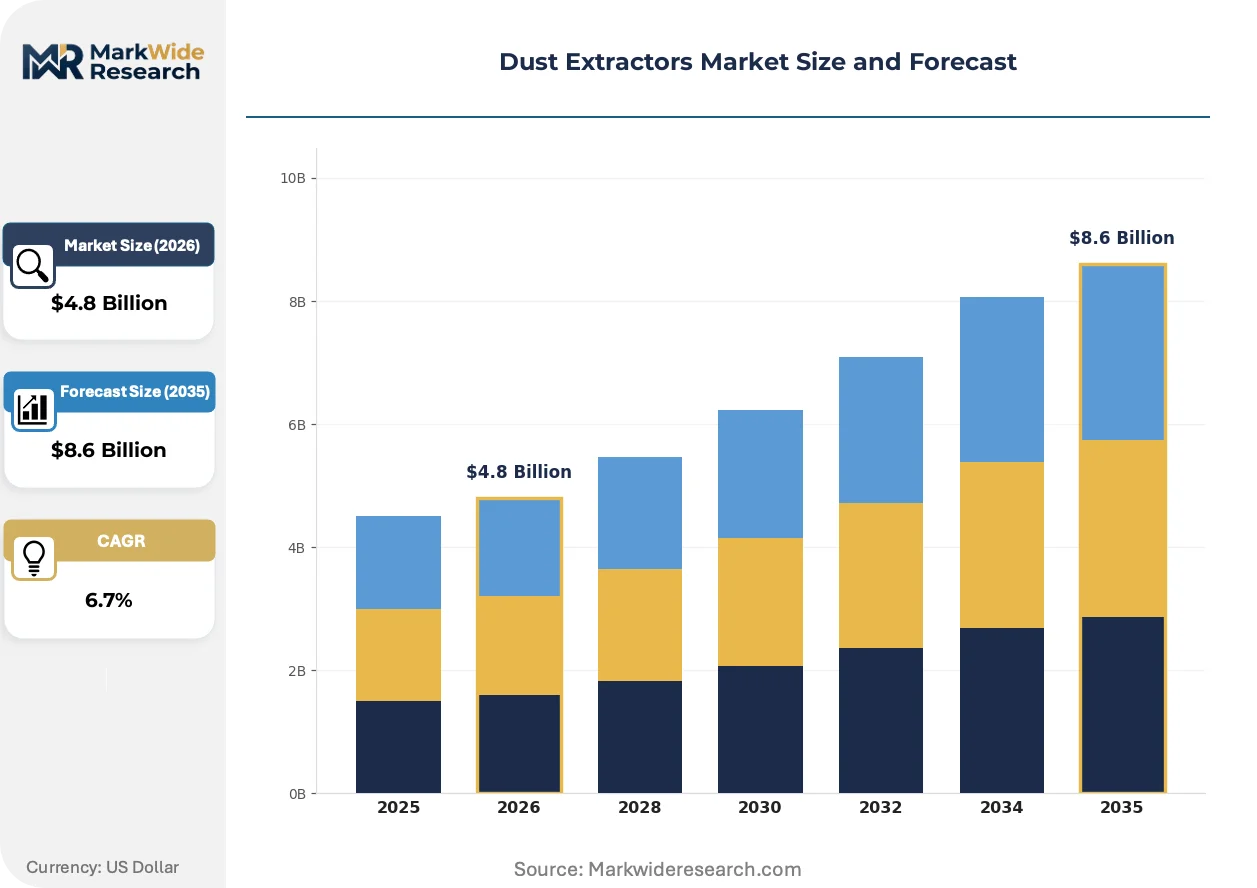
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-Mounted, Stationary, Centralized Technology: Wet, Dry, Cyclonic, HEPA Application: Construction, Woodworking, Metalworking, Pharmaceuticals End User: Contractors, Manufacturers, DIY Enthusiasts, Laboratories |
| Companies Covered | Donaldson Company, Inc., Nederman Holding AB, Camfil AB, Parker Hannifin Corporation, Robert Bosch Tool Corporation, Makita Corporation, CECO Environmental Corp., RoboVent, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Extractors Market Emerging Trajectories
Intelligent filtration systems are displacing static pressure-drop monitoring, embedding sensors that enable predictive maintenance and real-time compliance documentation. This shift is compressing the service interval economy and redefining aftermarket revenue pools.
Pulse-jet cleaning technology with differential pressure sensors is rendering obsolete manual filter replacement scheduling in high-duty-cycle metalworking operations. Tier-one automotive suppliers are adopting these self-cleaning baghouse configurations to sustain capture efficiency across 24-hour production regimes. The technology is compressing labor allocation to filtration maintenance and shifting buyer value assessment toward total cost of ownership metrics.
REACH chemical registration requirements are tightening filter media composition disclosures across European supply chains. Manufacturers must now document full material substance inventories to maintain CE marking eligibility, raising compliance costs for imported components. German metalworking clusters are responding by qualifying domestic media suppliers with pre-certified substance portfolios.
Equipment leasing structures are displacing outright purchase in mid-cap construction segments, with project-based financing lowering capital barriers for silica-compliant extraction. Rental fleet operators are capturing market share from traditional distributors by bundling maintenance and filter logistics. This shift is most visible in United States metropolitan construction markets where contractor liquidity constraints intersect with aggressive OSHA enforcement timelines.
Dust Extractors Market Segmentation
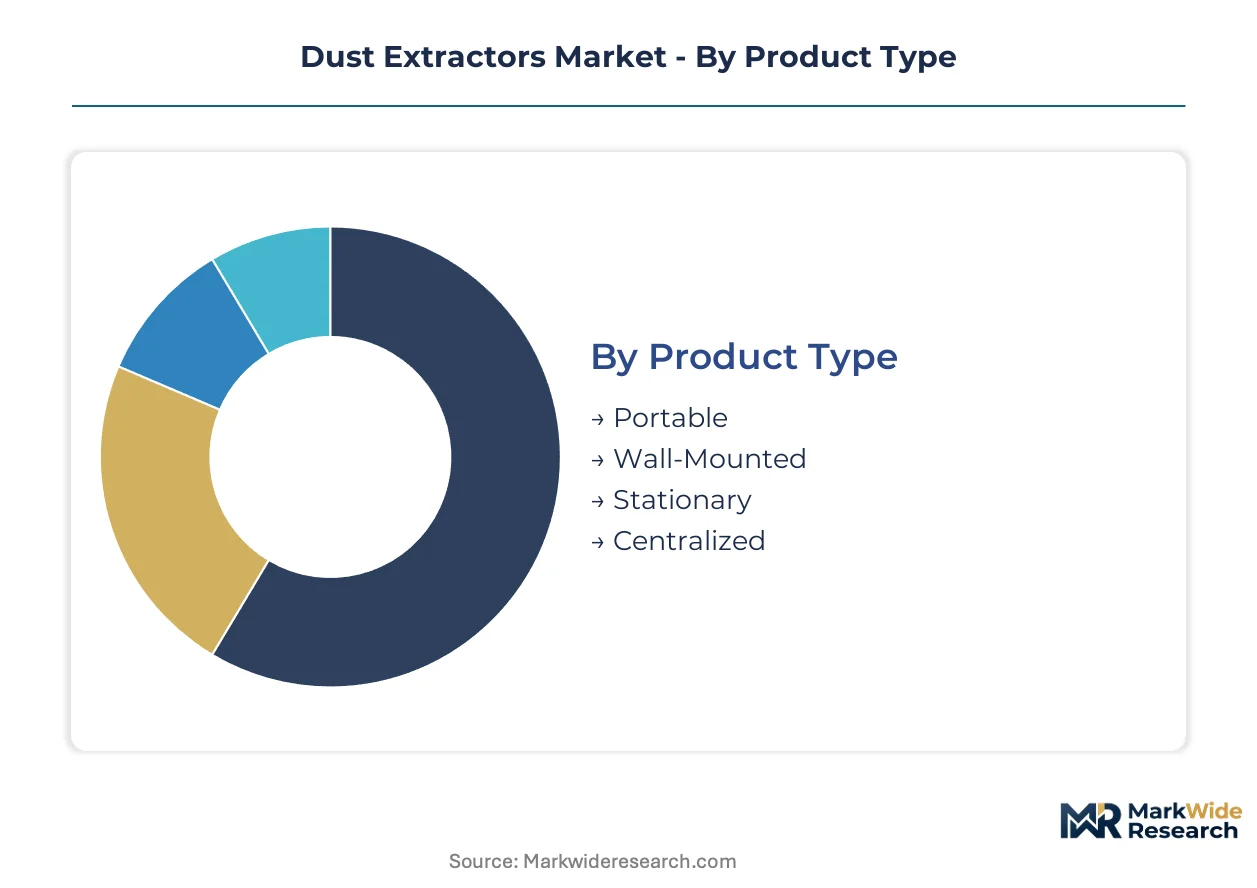
Dust extractor segmentation reveals distinct procurement patterns across mobility requirements, contamination severity, and regulatory exposure. Equipment specifications diverge sharply between construction site portability and pharmaceutical containment integrity.
Product Type:
Mobility requirements span from single-operator portability to facility-wide centralized infrastructure, with capital intensity and installation permanence defining buyer segments.
- Portable:Self-contained units with internal power and collection bins serve renovation contractors and demolition crews. OSHA silica enforcement in United States metropolitan construction markets accelerates fleet turnover toward HEPA-compliant portable configurations.
- Centralized:Ducted systems with multiple extraction points anchor automotive fabrication facilities and large-scale woodworking operations. Germany's industrial manufacturing corridor concentrates demand for these high-capacity installations serving robotic welding cells.
- Wall-Mounted:Fixed-position units optimize floor space in compact workshops and training facilities.
- Stationary:Floor-standing systems balance capacity against relocation flexibility for mid-sized manufacturers.
The dominant share belongs to Portable units, while Centralized systems are closing the gap fastest.
Technology:
Filtration mechanisms align with particle physics and combustibility profiles across industrial processes.
- HEPA:99.97% efficiency at 0.3-micron capture serves pharmaceutical sterile suites and nanomaterial handling. Cleanroom validation protocols in United States FDA-regulated facilities mandate continuous integrity testing.
- Wet:Water-based suppression neutralizes combustible aluminum and magnesium fines in metalworking. Cold-climate deployment constraints limit adoption in northern-tier United States fabrication shops.
- Dry:Baghouse and cartridge media dominate general industrial applications with standard particulate loads.
- Cyclonic:Pre-separation chambers extend primary filter life in high-volume woodworking and grain processing.
HEPA commands premium positioning, though Wet systems are expanding most quickly into battery cell manufacturing safety applications.
Application:
Industry-specific contamination risks drive divergent equipment specifications and certification requirements.
- Construction:Silica-generating activities dominate equipment deployment. United States OSHA enforcement compresses replacement cycles for non-compliant passive ventilation.
- Metalworking:Robotic welding fume capture integrates with factory automation. German automotive tier-one suppliers standardize on self-cleaning pulse-jet configurations.
- Woodworking:Combustible dust hazards trigger NFPA compliance requirements in United States cabinet and furniture manufacturing.
- Pharmaceuticals:Cross-contamination prevention mandates HEPA-grade containment with documented filter integrity.
Construction maintains volume leadership, while Pharmaceuticals demonstrates the steepest expansion trajectory on regulatory tightening.
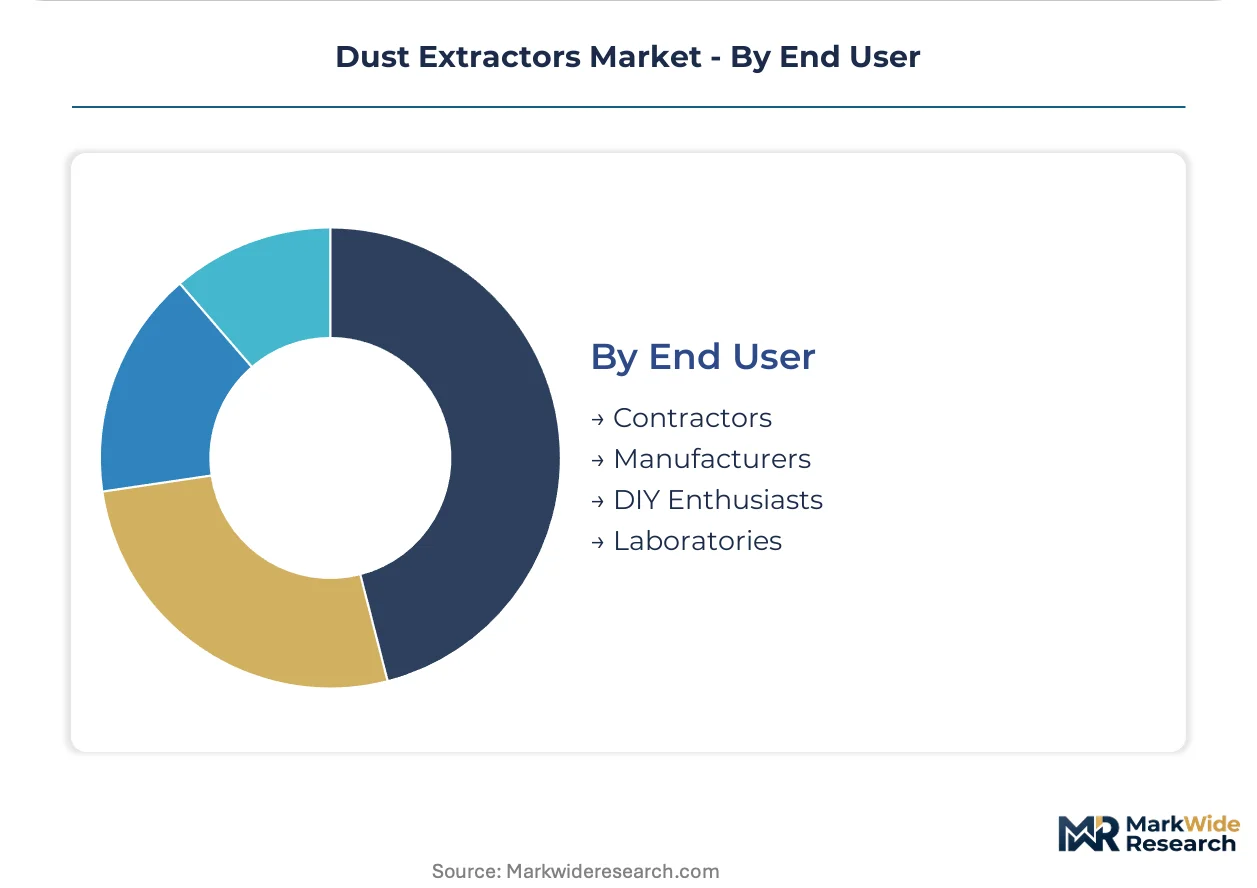
End User:
Buyer sophistication and capital access stratify across professional and non-commercial segments.
- Contractors:Project-based procurement favors leasing and rental fleet access. United States equipment-as-a-service providers capture mid-cap contractors facing liquidity constraints.
- Manufacturers:In-house engineering teams specify integrated extraction for process automation. German metalworking clusters prioritize captive service networks for maintenance continuity.
- DIY Enthusiasts:Consumer-grade portable units serve residential workshop applications with minimal regulatory exposure.
- Laboratories:Research facilities demand certified containment for hazardous material protocols.
Manufacturers anchor revenue concentration, though Contractors are gaining share fastest via financing innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA's respirable crystalline silica enforcement is compressing equipment replacement cycles across United States construction markets. National emission discharge permits are tightening industrial air quality standards in China under dual carbon mandates. Germany's automotive manufacturing corridor sustains concentrated demand for centralized extraction infrastructure.
United States
Metropolitan construction markets drive portable HEPA unit procurement as contractors face aggressive OSHA compliance timelines. The EPA National Emission Standards for Hazardous Air Pollutants governs metal finishing facilities with continuous monitoring requirements. Texas and California fabrication clusters anchor demand for wet scrubbing systems handling combustible aluminum fines.
Germany
Automotive tier-one suppliers standardize on self-cleaning pulse-jet baghouse configurations for 24-hour robotic welding operations. REACH chemical registration mandates full filter media substance disclosure for CE marking eligibility. Baden-Württemberg and Bavaria industrial corridors concentrate captive service network deployments for maintenance continuity.
China
Battery cell manufacturing expansion generates specialized demand for inert gas extraction handling lithium-ion electrode combustible fines. MEE enforcement protocols are tightening industrial air discharge permits under dual carbon policy frameworks. Yangtze River Delta electronics manufacturing clusters drive first-mover adoption of intelligent filtration with predictive maintenance sensors.
India
PLI scheme incentives for domestic electronics and automotive production create equipment vendor openings in industrializing states. BIS certification requirements are evolving for imported extraction system components. Maharashtra and Gujarat manufacturing zones concentrate initial centralized system installations serving contract electronics assembly.
Japan
Pharmaceutical sterile manufacturing mandates HEPA-grade containment with documented filter integrity protocols. METI industrial efficiency guidelines encourage predictive maintenance adoption in precision metalworking. Kansai region automotive suppliers integrate extraction with factory automation systems for robotic welding cell deployments.
Dust Extractors Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers. Vertically integrated filter media producers compete against specialized system fabricators and rental fleet operators. Equipment-as-a-service providers are capturing mid-cap contractor segments through project-based financing structures. Strategic moves concentrate on captive service network expansion and backward integration into high-efficiency media production.
Among North American industrial filtration specialists, Donaldson Company, Inc. exemplifies the vertically integrated archetype with in-house filter media production. Nederman Holding AB anchors the European captive service network model through maintenance continuity offerings. Parker Hannifin Corporation occupies the factory automation integration position, bundling extraction with pneumatic and hydraulic system deployments. These three represent divergent competitive vectors rather than direct substitution.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Nederman Holding AB |
| Camfil AB |
| Parker Hannifin Corporation |
| Robert Bosch Tool Corporation |
| Makita Corporation |
| CECO Environmental Corp. |
| RoboVent |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's filter media production corridors is compressing margin structures for mid-tier cartridge suppliers while forcing premium German and US manufacturers toward service bundling to defend pricing power. This utilization asymmetry between geographies is reshaping procurement negotiations for construction contractors and automotive fabricators alike.
Pricing Analysis
Certification level creates the primary spread between portable dust extraction tiers, with ISO 15012-1 welding fume documentation and CE marking eligibility commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates the contractor segment, though equipment-as-a-service subscriptions are displacing outright purchase for mid-cap buyers facing OSHA compliance deadlines. Cost compression in synthetic fiber media is intensifying because petrochemical feedstock volatility squeezes filter replacement economics. DIY enthusiasts exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize containment integrity over unit cost.
Supply Chain Analysis
Contract manufacturing for HEPA-grade filter media concentrates among specialized Taiwanese and South Korean membrane producers, with German captive facilities retaining premium cartridge production. Synthetic fiber supply draws from China, Germany, and the United States, while nanofiber membrane technology rests on Japanese and South Korean specialty chemical inputs. Single-source vulnerability in high-efficiency media creates bottleneck exposure for premium system tiers awaiting CE marking documentation. Distribution runs through captive service networks in Northern Europe and rental fleet operators in United States metropolitan construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dust extractor penetration remains early-cycle across industrializing manufacturing corridors, with battery cell fabrication and Indian electronics assembly creating fresh installation demand before regulatory mandates harden.
For Market Incumbents: Harden aftermarket revenue streams through predictive maintenance sensor deployment and filter subscription logistics, as rental fleet operators threaten traditional distributor margins. Deepen backward integration into nanofiber media production to offset synthetic fiber cost volatility. Prioritize CE marking pre-certification for modular system variants to compress launch timelines against ISO 15012-1 validation requirements. For New Entrants and Emerging Players: Pursue equipment-as-a-service positioning in United States metropolitan construction markets, where contractor liquidity constraints intersect with aggressive OSHA enforcement timelines. Maharashtra and Gujarat manufacturing zones in India offer first-mover openings for centralized system installations serving PLI-scheme electronics assembly. Anchor go-to-market through project-based financing partnerships rather than capital equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable HEPA configurations as sensor commoditization reduces hardware differentiation. Long-term viability favors vertically integrated filter media producers with captive service network density over pure-play system fabricators. Monitor MEE enforcement protocol tightening in China as inflection signal for import equipment certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Donaldson's captive nanofiber production sustains margin control against petrochemical volatility. |
| Equipment-as-a-Service Launch | Rental fleet operators capture mid-cap contractors facing OSHA silica compliance deadlines. |
| Predictive Maintenance Sensor Deployment | Intelligent filtration systems compress service intervals and redefine aftermarket revenue pools. |
| CE Marking Pre-Certification Investment | ISO 15012-1 documentation delays favor early movers in modular welding fume capture. |
| Battery Cell Manufacturing Partnership | Wet scrubbing configurations for lithium-ion electrode production open specialized safety demand. |
Methodological Framework
Desk research of regulatory filing databases, customs trade records, and equipment certification registries preceded structured interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and rental fleet operators. Primary fieldwork with construction contractors and automotive tier-one suppliers was validated against EPA enforcement data, OSHA inspection records, and SEC 10-K disclosures from listed filtration specialists. Bottom-up unit shipment estimates triangulated with top-down capital expenditure analysis across manufacturing corridors.
Assumptions held fixed include OSHA silica PEL enforcement intensity, REACH chemical registration scope, and dual carbon policy trajectory in China; variables tested spanned petrochemical feedstock price bands and battery cell manufacturing capacity expansion rates. Segmentation modeling spanned mobility tier, filtration technology, application vertical, and end-user sophistication across the projection horizon. CAGRs were derived from regression analysis of historical equipment replacement cycles against regulatory enforcement phase-ins, with robotic welding automation intensity and pharmaceutical containment standard tightening as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, industrial capital expenditure sentiment, or central bank rate policy would shift the trajectory. Forecasts embed assumptions regarding filter media cost normalization and certification timeline standardization. Quarterly review of OSHA enforcement action rates, MEE discharge permit issuances, and battery cell manufacturing capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Freight Elevators Market